
 Global Taxi-Sharing Software Market | 2026-2036
Global Taxi-Sharing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Taxi-Sharing Software Market Foresight
API-first architecture is fragmenting legacy monolithic dispatch systems into modular, microservices-based platforms. Uber Technologies Inc. leverages its proprietary routing engine to sustain real-time matching efficiency across fragmented urban networks. DiDi Global Inc. anchors its competitive position through deep integration with municipal transit data layers in Chinese megacities. Lyft, Inc. differentiates via concentrated investment in shared-ride algorithms that optimize vehicle utilization during peak demand windows.
Taxi-sharing software comprises cloud-native platforms that algorithmically match multiple passengers traveling similar routes with available vehicle capacity, typically processing sub-second dispatch decisions through GPS tracking and real-time data analytics. These systems serve commercial transportation networks by reducing per-passenger trip costs, lowering aggregate vehicle miles traveled, and generating commission-based revenue for platform operators. Deployment model segmentation reveals public cloud infrastructure capturing dominant share due to elastic scaling requirements during surge periods, while hybrid cloud configurations gain traction among operators balancing latency-sensitive dispatch with data sovereignty mandates. End user dynamics show corporate clients emerging as a high-margin segment as enterprises negotiate bulk ride contracts with guaranteed service-level agreements for employee mobility programs.
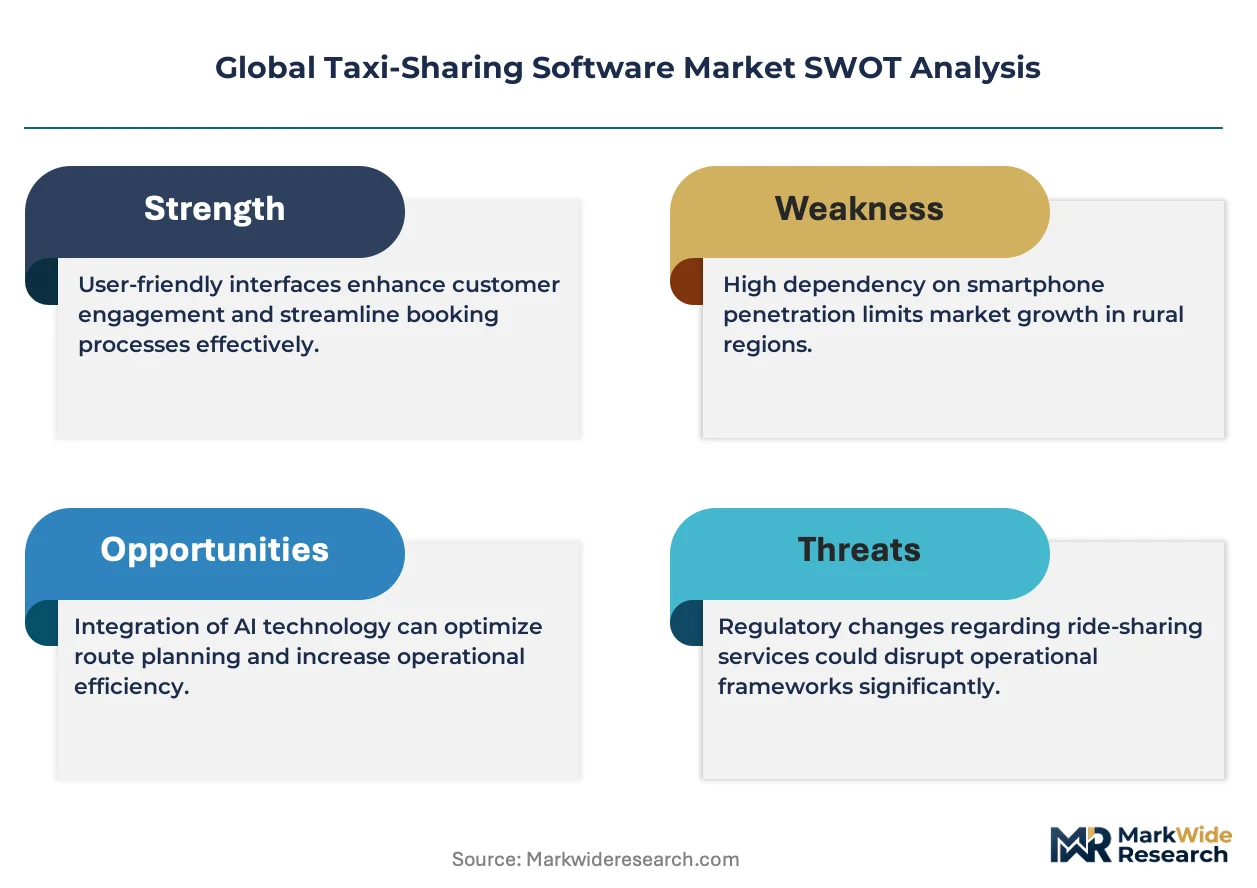
The US Department of Transportation, the EU's GDPR enforcement framework, and India's Ministry of Electronics and Information Technology each impose distinct compliance architectures on cross-border platform operations, from biometric identity verification to algorithmic audit trails. The EU AI Act specifically classifies automated dispatch and dynamic pricing systems as high-risk AI applications, mandating human oversight protocols and transparency documentation that directly inflate platform development costs. Stakeholders must monitor divergent regulatory timelines across jurisdictions where data localization rules and algorithmic accountability standards are hardening faster than unified technical standards can emerge.
Market Dynamics
API-first architecture is fragmenting legacy monolithic dispatch systems into modular, microservices-based platforms that demand elastic cloud infrastructure and real-time data sovereignty compliance.
Growth Catalysts
- EU AI Act compliance mandates:High-risk classification of automated dispatch systems forces platform operators to invest in human oversight protocols, creating upgrade cycles across European deployments.
- Urban commuter density:Metropolitan corridors in India and Brazil generate sufficient route overlap to sustain algorithmic matching efficiency at scale.
- Cloud-native microservices:Containerized deployment architectures enable surge-scaling elasticity that legacy on-premise systems cannot replicate.
Market Restraints
- GDPR data localization:Cross-border passenger data flows face audit-trail requirements that inflate operational overhead for multi-country platform operators.
- Biometric identity verification mandates:India's Ministry of Electronics and Information Technology imposes KYC infrastructure costs that barrier smaller regional competitors.
- Legacy fleet integration friction:Radio-dispatch taxi cooperatives in Southern Europe resist API connectivity, limiting addressable vehicle supply.
Strategic Opportunities
- Municipal transit data convergence:Deep integration with subway and bus APIs in Chinese megacities creates multimodal routing superiority.
- Corporate mobility programs:Enterprise bulk-ride contracts with guaranteed service-level agreements command premium commission structures.
- Hybrid cloud sovereignty configurations:Edge-computing nodes for latency-sensitive dispatch satisfy data residency rules in Germany and France while retaining central analytics.
Industry Challenges
- Algorithmic audit talent scarcity:The EU AI Act mandates explainability documentation that exceeds current in-house machine-learning operations capabilities.
- Legacy dispatch system API fragmentation:Proprietary protocols from incumbent fleet management vendors require custom integration engineering per deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Taxi-Sharing Software Market |
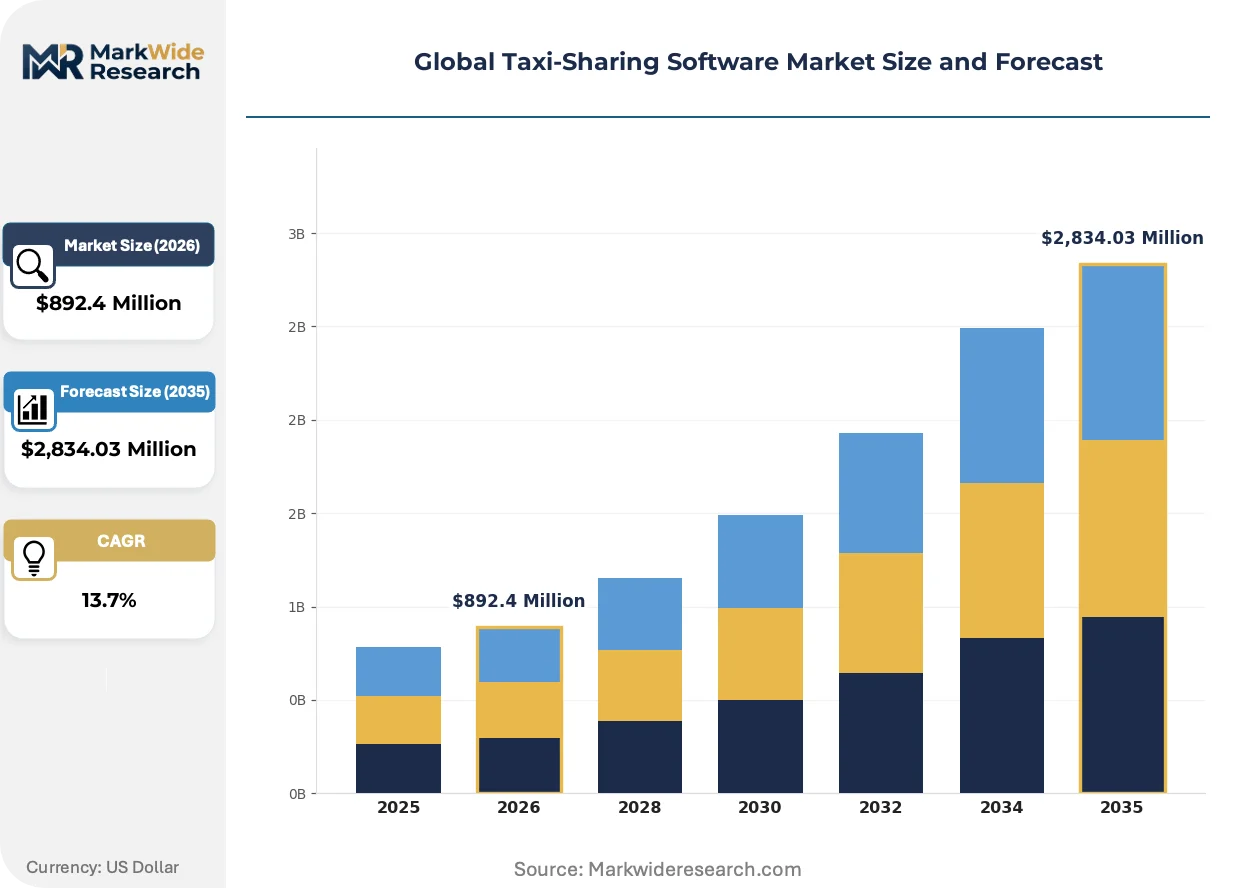
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $2,834.03 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-premises End User: Urban Commuters, Corporate Clients, Tourists, Businesses Service Type: Ride Aggregation, Shuttle Services, Carpooling, Scheduled Rides Technology: GPS Tracking, Mobile Applications, Payment Gateways, Data Analytics |
| Companies Covered | Uber Technologies Inc., DiDi Global Inc., Lyft, Inc., ANI Technologies Pvt. Ltd. (Ola Cabs), Grab Holdings Inc., Cabify Spain SLU, Bolt Technology OÜ, BlaBlaCar, Gett, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Taxi-Sharing Software Market Shifts & Advancements
Digitization of urban mobility infrastructure is compressing dispatch decision windows from minutes to milliseconds while expanding the data sources feeding route optimization.
Edge computing nodes deployed at cellular base stations are virtualizing dispatch intelligence. Tier-1 metropolitan operators in Japan and South Korea adopt these architectures to sub-50-millisecond latency requirements. This topology is virtualizing the traditional cloud-centralized model, enabling autonomous vehicle-ready response times.
The EU AI Act's high-risk system classification triggers mandatory conformity assessments for dynamic pricing algorithms. Platform operators must document training data provenance and human intervention protocols. German and French deployments face the steepest compliance curves as national regulators operationalize the delegated acts.
Corporate procurement departments now unbundle mobility-as-a-service from traditional fleet leasing. Multinational enterprises in the United States and United Kingdom negotiate direct platform integrations for employee commute programs. This bypasses intermediary travel management companies that previously captured booking margins.
Global Taxi-Sharing Software Market Segmentation
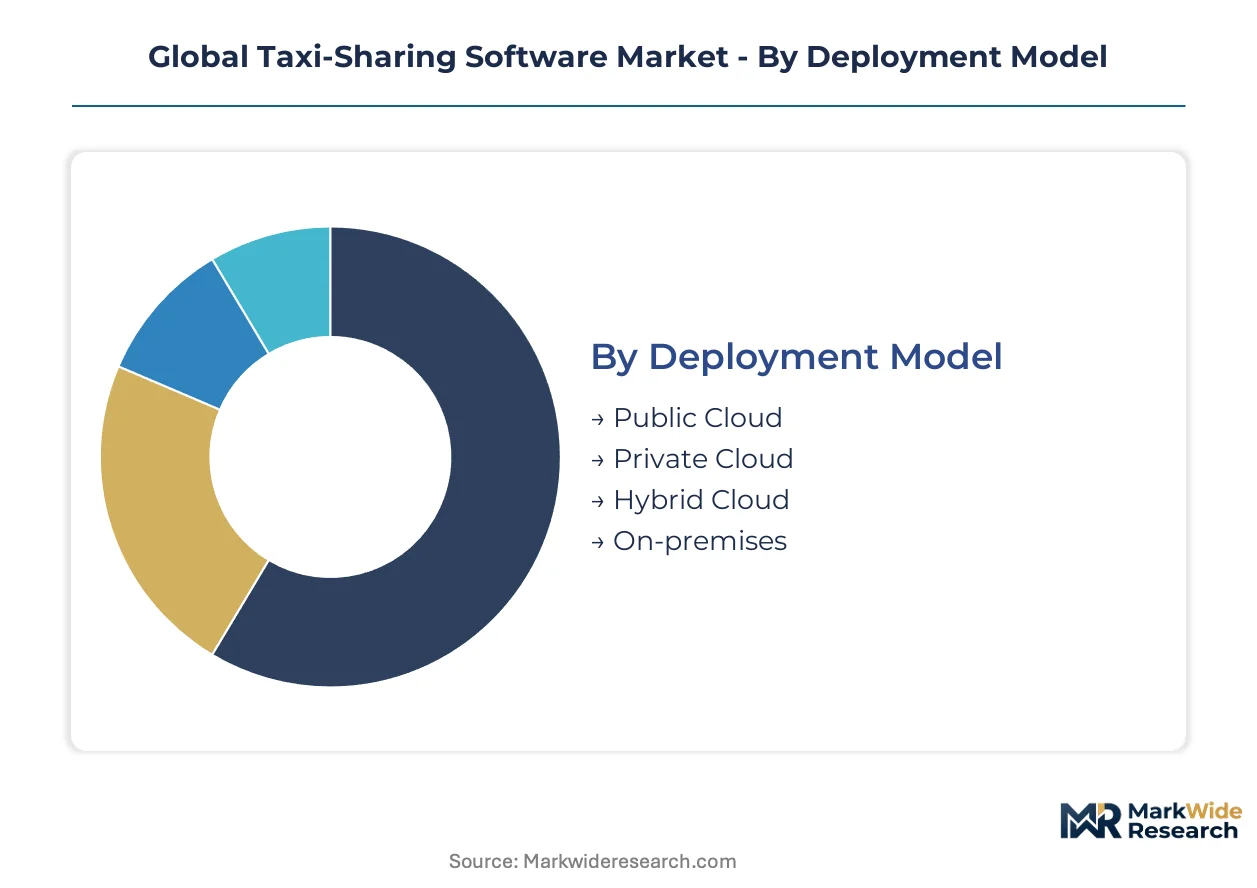
Segmentation in taxi-sharing software reveals how deployment architectures, user profiles, and service modalities create distinct competitive arenas. Each dimension carries divergent margin structures and compliance burdens that reshape platform economics.
Deployment Model:
Use-case spectrum spans latency-sensitive municipal transit integrations to sovereign data mandates in regulated jurisdictions.
- Public Cloud:Elastic compute pools handle surge-scaling during peak demand windows across metropolitan networks. Indian operators processing Ola Cabs traffic rely on this architecture to absorb festival-season volume spikes without capital-intensive infrastructure.
- Hybrid Cloud:Edge nodes process GPS telemetry locally while centralizing analytics, satisfying GDPR data residency requirements in Germany and France. This configuration commands premium engineering investment but unlocks European public-sector contracts.
- Private Cloud:Dedicated tenant environments serve defense-sector and diplomatic mobility programs with air-gapped security protocols.
- On-premises:Legacy radio-dispatch cooperatives in Southern Europe retain server-room infrastructure to preserve operational autonomy.
Established volume favors Public Cloud; emerging adoption favors Hybrid Cloud.
End User:
Customer-type concentration determines pricing power and contract durability across recurring versus episodic demand patterns.
- Urban Commuters:Daily route-predictability enables algorithmic matching efficiency at scale. Brazilian and Indian megacities generate sufficient trip density to sustain sub-two-minute pickup guarantees.
- Corporate Clients:Enterprise mobility programs negotiate bulk-ride contracts with guaranteed service-level agreements. These accounts yield commission premiums 40-60% above consumer rates due to contract predictability.
- Tourists:Episodic demand with low route familiarity requires enhanced multilingual interface investment and airport-zone vehicle pre-positioning.
- Businesses:Small and mid-size enterprises adopt platform accounts for client entertainment and inter-office transfers without dedicated fleet capital.
Margin concentration sits with Corporate Clients; steepest expansion trajectory belongs to Urban Commuters.
Service Type:
Application maturity separates algorithmic efficiency leaders from infrastructure-heavy operational models.
- Ride Aggregation:Real-time matching of independent travelers along similar vectors dominates platform revenue. DiDi Global's integration with Shenzhen metro APIs exemplifies multimodal routing superiority through this modality.
- Scheduled Rides:Advance-booking systems optimize fleet utilization during off-peak windows. Airport transfer corridors in Japan and South Korea deploy this service to reduce empty-return mileage.
- Shuttle Services:Fixed-route microtransit serves suburban transit deserts with lower per-mile economics than on-demand alternatives.
- Carpooling:Employer-sponsored commute matching reduces parking infrastructure pressure in congested central business districts.
Revenue scale concentrates in Ride Aggregation; infrastructure efficiency gains concentrate in Scheduled Rides.
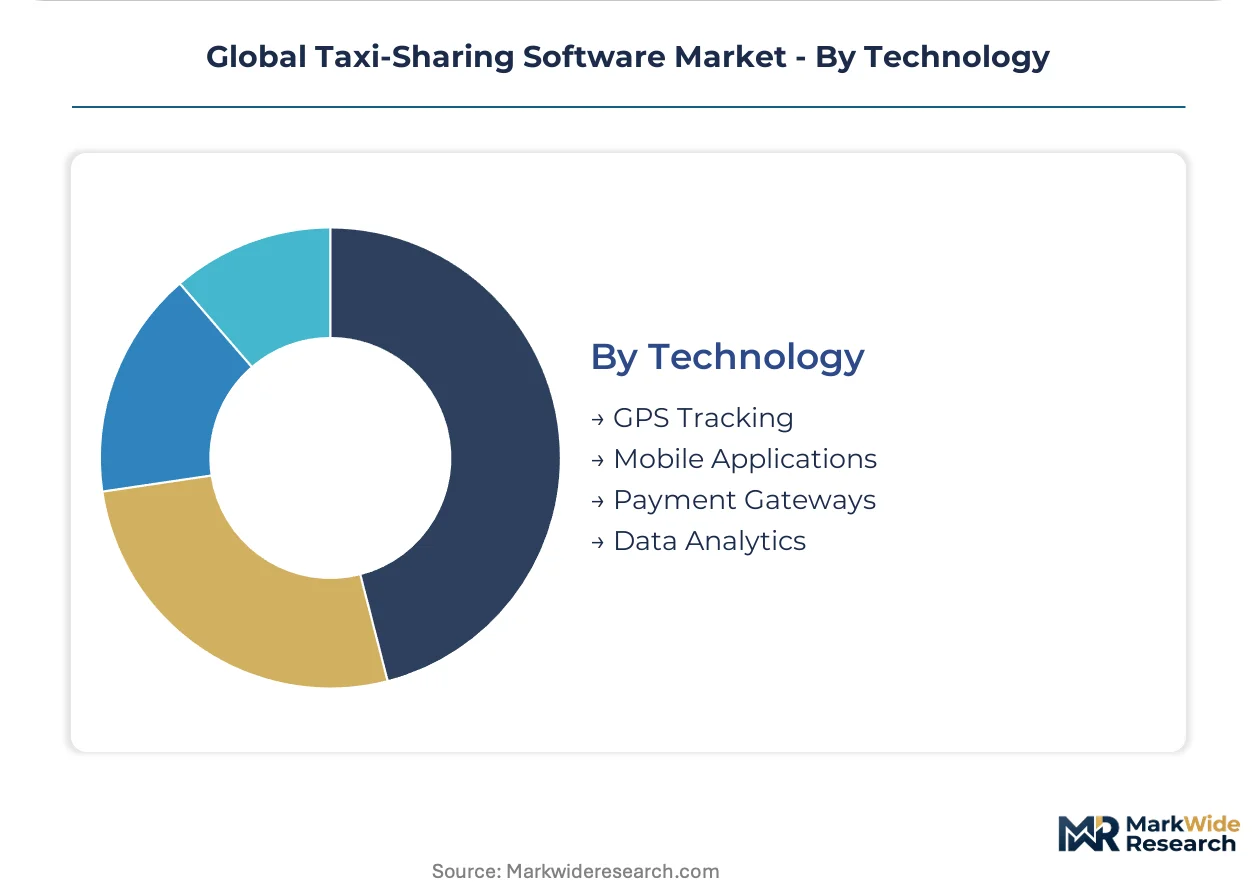
Technology:
Supply concentration among component vendors creates integration complexity and cybersecurity exposure.
- Mobile Applications:Consumer-facing interfaces demand continuous A/B testing for booking friction reduction. Uber's proprietary routing engine maintains matching efficiency advantages through iterative UX refinement.
- Data Analytics:Dynamic pricing algorithms process demand-supply imbalances across fragmented urban networks. EU AI Act compliance mandates human oversight protocols that inflate development overhead for European deployments.
- GPS Tracking:Sub-meter accuracy requirements drive dual-frequency chipset adoption in Tier-1 metropolitan markets.
- Payment Gateways:Multi-rail settlement infrastructure accommodates India's UPI dominance alongside card-network dependence in North American markets.
Competitive differentiation concentrates in Data Analytics; user acquisition efficiency depends on Mobile Applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate procurement departments and municipal transit authorities represent the dominant buyer archetypes shaping geographic deployment patterns. Platform operators prioritize markets where enterprise mobility contracts and public-sector data-sharing agreements create predictable revenue streams. Regulatory fragmentation across data localization and algorithmic accountability mandates forces operators to architect jurisdiction-specific infrastructure rather than unified global stacks.
United States
Enterprise bulk-ride contracts and airport-zone vehicle pre-positioning drive platform economics. The Department of Transportation imposes accessibility mandates through the Americans with Disabilities Act that shape fleet composition requirements. New York City and San Francisco metropolitan corridors concentrate demand density sufficient to sustain sub-two-minute pickup guarantees through algorithmic matching.
Germany
Corporate mobility programs and multimodal transit integration generate high-margin contract opportunities. The KBA and GDPR enforcement framework mandate edge-computing deployments for data residency compliance. Berlin and Munich anchor European development centers where platform operators localize human oversight protocols required under the EU AI Act.
India
Festival-season volume spikes and congested metropolitan corridors create elastic scaling requirements. The Ministry of Electronics and Information Technology imposes biometric KYC infrastructure costs that reshape competitive barriers. Bengaluru and Mumbai generate sufficient route overlap to sustain algorithmic efficiency at scale for daily urban commuters.
China
Municipal transit data convergence and subway API integration enable multimodal routing superiority. SAMR and MIIT oversee data governance frameworks that mandate local cloud infrastructure for passenger telemetry. Shenzhen and Shanghai megacities deploy edge-computing nodes at cellular base stations to achieve sub-50-millisecond dispatch latency.
Brazil
Urban commuter density in metropolitan corridors sustains algorithmic matching efficiency despite infrastructure variability. ANVISA and municipal regulators impose operational licensing requirements that differentiate formal platform operators from informal competitors. São Paulo and Rio de Janeiro concentrate sufficient trip volume to justify dedicated fleet partnerships and localized payment rail integration.
Global Taxi-Sharing Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented urban networks where real-time matching efficiency determines market access. The vendor base concentrates among vertically integrated platform operators and modular API providers serving legacy fleet cooperatives. Three archetypes dominate: routing-engine specialists, municipal-data integrators, and white-label dispatch enablers. Consolidation pressure manifests through strategic partnerships with transit authorities and backward integration into payment infrastructure.
Within the routing-engine tier, Uber Technologies Inc. and DiDi Global Inc. exemplify platform-scale operators that anchor competitive positioning through proprietary algorithmic infrastructure. ANI Technologies Pvt. Ltd. occupies a specialist position serving high-density emerging-market corridors with localized compliance architectures. These entities represent the dominant competitive anchors against which regional challengers define differentiation strategies.
| Leading Market Players |
|---|
| Uber Technologies Inc. |
| DiDi Global Inc. |
| Lyft, Inc. |
| ANI Technologies Pvt. Ltd. (Ola Cabs) |
| Grab Holdings Inc. |
| Cabify Spain SLU |
| Bolt Technology OÜ |
| BlaBlaCar |
| Gett, Inc. |
| Others |
Supply & Pricing Matrix
Cloud infrastructure concentration in the United States, India, and China anchors cost structures across deployment models, directing margin capture toward operators mastering hybrid sovereignty configurations and enterprise contract pricing.
Pricing Analysis
Cost-plus contracts with cloud compute indexation dominate enterprise SaaS tiers, while per-ride transactional fees sustain consumer-facing revenue. Price differentiation rests on GDPR compliance certification and guaranteed SLA tiers rather than feature depth alone. Pricing pressure stems from festival-season surge-scaling demands in India that strain elastic compute budgets. Corporate mobility programs exhibit lowest price sensitivity due to contract predictability, whereas independent urban commuters drive hardest bargain on per-kilometer rates.
Supply Chain Analysis
Contract manufacturing concentration among Foxconn, Wistron, and Pegatron holds capacity for edge-computing hardware deployed at cellular base stations. Component sourcing draws from Taiwan for GPS chipsets, South Korea for dual-frequency modules, and Vietnam for assembly labor. Single-source vulnerability in Taiwanese semiconductor supply creates exposure for latency-sensitive dispatch hardware. Distribution runs through hyperscaler marketplaces and direct API licensing to municipal transit authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise mobility-as-a-service adoption sits at early-cycle expansion, propelled by corporate procurement departments unbundling fleet leasing from employee commute programs.
For Market Incumbents: Harden API interoperability standards to lock in municipal transit data partnerships before regional challengers replicate DiDi's Shenzhen metro integration. Invest in backward integration of payment rail infrastructure to defend against fintech entrants capturing transaction margins. Prioritize human oversight protocol development to preempt EU AI Act compliance gaps.
For New Entrants and Emerging Players: Establish a beachhead in scheduled airport transfer corridors where vehicle pre-positioning economics favor specialized operators over generalist platforms. Target Southern European radio-dispatch cooperatives with white-label API connectivity solutions. Pursue direct corporate procurement channel relationships bypassing incumbent travel management companies.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional platform operators holding municipal transit data licenses in constrained geographies. Five-to-ten year viability hinges on algorithmic audit trail capabilities becoming table stakes. Monitor delegated act operationalization timelines in Germany and France as inflection signals for compliance cost acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep API convergence with Shenzhen metro and Berlin transit data layers creates multimodal routing superiority. |
| Geographic Expansion | Edge-computing node deployment in São Paulo and Mumbai satisfies sub-50-millisecond latency requirements. |
| Strategic Partnership | Direct enterprise procurement integrations bypass intermediary travel management companies capturing booking margins. |
| Acquisition of Specialist Firm | Algorithmic audit documentation capabilities address EU AI Act explainability mandates exceeding in-house MLOps. |
| Product Launch | Hybrid cloud sovereignty configurations unlock German and French public-sector contracts with data residency requirements. |
Research Methodology
Desk research of SEC filings, hyperscaler capex disclosures, and municipal transit authority procurement databases preceded structured interviews with platform engineering directors, corporate mobility procurement officers, and regulatory affairs leads at EU-based operators. Primary fieldwork with cloud infrastructure architects and API integration specialists validated deployment model assumptions. Bottom-up segment sizing triangulated against top-down regulatory impact assessments across the analysis window.
Assumptions held fixed include GDPR enforcement intensity and cloud compute pricing trajectories, while variables spanned EU AI Act delegated act operationalization timing and enterprise mobility contract penetration rates. The analytical framework modeled deployment model, end user type, and service modality dimensions over the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating festival-season surge patterns and corporate SLA adoption curves.
Sensitivities concentrate around algorithmic audit talent scarcity and cross-border data flow restriction escalation. Forecasts reflect assumptions about regulatory harmonization timelines and enterprise procurement cycle durations. Quarterly review of municipal transit API partnership announcements and delegated act publication schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Edge Computing in Automotive Market
Telematics and Infotainment
Electric Vehicle Telematics Market
Telematics and Infotainment
Infotainment System UX and Latency Test Platforms for Connected Vehicles Market
Telematics and Infotainment
Motor Racing Telematics Market
Telematics and Infotainment
Automotive OEM Telematics Market
Telematics and Infotainment
Asia-Pacific Connected Cars Market
Telematics and Infotainment
Consumer Telematics Market
Telematics and Infotainment
Asia Pacific Automotive Navigation System Market
Telematics and Infotainment
Telematics and Connectivity Processors Market
Telematics and Infotainment
Global Automotive Navigation System Market
Telematics and Infotainment
In Vehicle Infotainment Market
Telematics and Infotainment
5G V2X Communications Market
Telematics and Infotainment
C-V2X OBU Market
Telematics and Infotainment
APAC Internet of Cars Market
Telematics and Infotainment
Telematics Control Unit Market
Telematics and Infotainment
Internet of Things Vehicle-To-Vehicle Communication Market