
 India Fleet Management Software Market | 2026-2036
India Fleet Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
India Fleet Management Software Market Foresight
Market Context with Strategic Players
Cloud-native telematics architecture is tilting fleet software away from legacy on-premise installations toward API-first platforms with real-time data streaming. Samsara Networks India Private Limited leverages its IoT sensor ecosystem to anchor premium positioning in enterprise accounts. Trimble Mobility Solutions India Private Limited sustains dominance through deep integration with geospatial mapping and precision routing engines.
Technical Definition and Structural Segments
India fleet management software comprises integrated digital platforms that combine GPS tracking, engine diagnostics, fuel consumption analytics, and driver behavior monitoring to optimize commercial vehicle operations. These systems process telemetry data at sub-minute intervals to enable dynamic route recalculation, predictive maintenance scheduling, and regulatory compliance automation for fleet operators. Cloud-based deployment leads adoption due to lower capital barriers and faster scaling across distributed vehicle networks, while telematics solutions capture the deepest margin pools through recurring hardware-software bundles. Tracking software maintains volume leadership as the foundational module, though route optimization is accelerating fastest as fuel cost volatility pressures operating margins.
Regulatory Frame and Forward-Looking Close
The Ministry of Road Transport and Highways mandates AIS-140 compliant GPS devices on all commercial vehicles, while the Central Pollution Control Board enforces emission monitoring linkages that fleet software must integrate. BIS certification requirements for automotive electronics shape product standards and create compliance barriers for unqualified entrants. Stakeholders must monitor how FASTag integration with fleet platforms and impending carbon accounting rules for logistics will reshape software specifications and vendor qualification criteria.
Market Dynamics
Cloud-native telematics architecture is compressing deployment cycles from months to weeks, forcing legacy on-premise vendors to re-platform or exit. The Ministry of Road Transport and Highways mandate on AIS-140 compliant GPS tracking has created compliance-driven procurement urgency across commercial fleet operators.
Growth Catalysts
- AIS-140 Mandate:The Ministry of Road Transport and Highways requires GPS-based vehicle tracking on all commercial vehicles, creating mandatory replacement demand for non-compliant hardware and software stacks.
- Fuel Cost Volatility:Route optimization modules are accelerating adoption as logistics operators seek real-time recalculation capabilities to hedge diesel price swings.
- Port-Linked Freight Corridors:Dense fleet deployment concentrates in Maharashtra, Gujarat, and Karnataka where manufacturing clusters and maritime gateways generate sustained platform demand.
Market Restraints
- Hardware-Software Bundle Economics:Telematics solutions require upfront IoT sensor deployment, creating working capital intensity that constrains small fleet adoption below fifty vehicles.
- BIS Certification Barriers:Bureau of Indian Standards requirements for automotive electronics create six-to-twelve month product qualification timelines that filter unqualified entrants.
- Cellular Connectivity Fragmentation:Patchy 4G coverage on national highways and state road networks degrades real-time data streaming reliability in rural freight corridors.
Strategic Opportunities
- FASTag Integration:Toll plaza data streams merging with fleet platforms enable automated expense reconciliation and route cost optimization for long-haul operators.
- Predictive Maintenance Convergence:Engine diagnostics married with machine learning models compress vehicle downtime and extend asset life cycles for high-utilization fleets.
- Carbon Accounting Rules:Impending emission monitoring linkages from the Central Pollution Control Board will force software specification upgrades and vendor requalification.
Industry Challenges
- Embedded Systems Talent Scarcity:Shortage of firmware engineers with automotive telematics experience slows product development cycles and inflates compensation costs.
- Legacy Fleet Integration:Retrofitting older commercial vehicles with OBD-II compatible hardware requires custom harness development and field calibration protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Fleet Management Software Market |
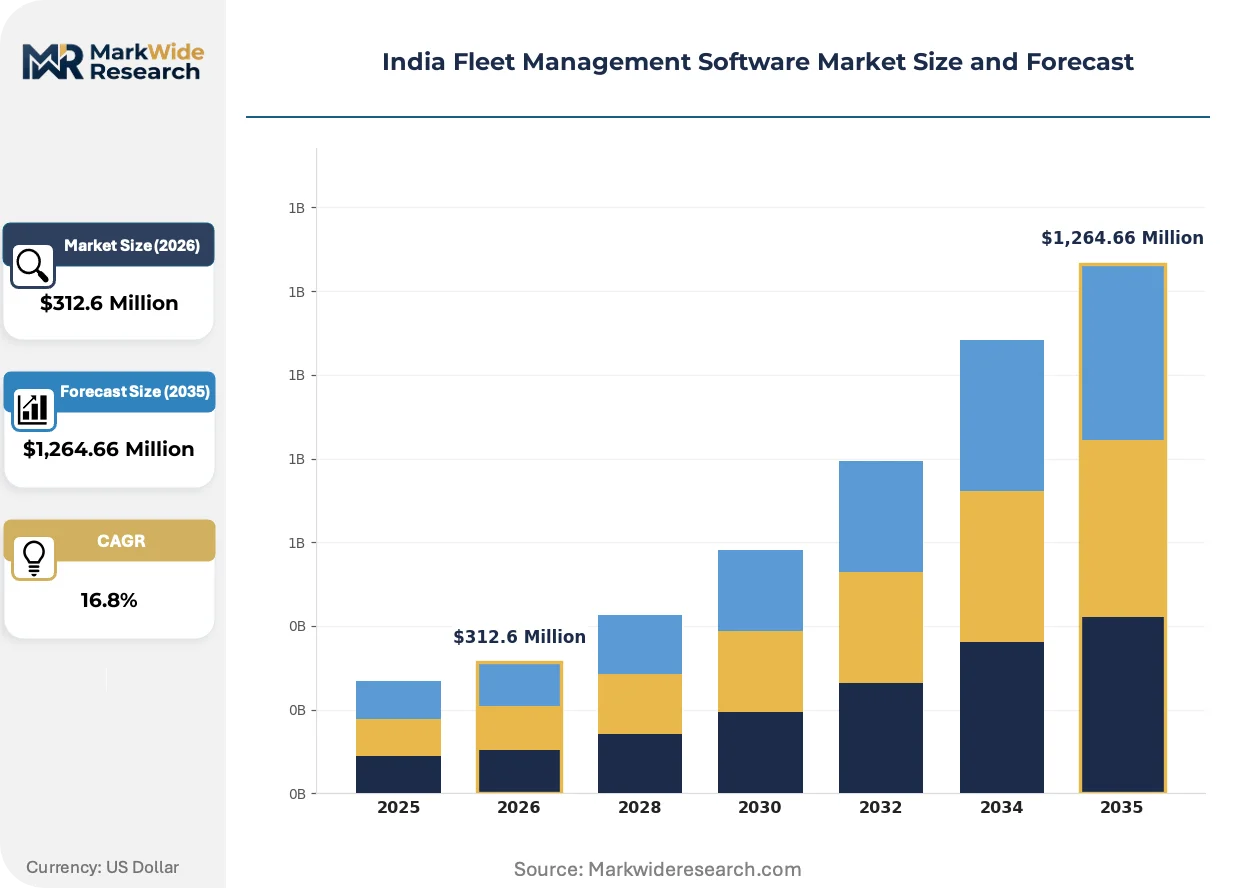
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $1,264.66 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tracking Software, Route Optimization, Fuel Management, Maintenance Management Deployment: On-Premise, Cloud-Based, Hybrid, Web-Based End User: Logistics Providers, Transportation Companies, Enterprises, Government Agencies Solution: Telematics, Driver Management, Compliance Management, Inventory Control |
| Companies Covered | Samsara Networks India Private Limited, Uffizio India Software Consultants Private Limited, Trimble Mobility Solutions India Private Limited, VAMOSYS, Cygnux Softtech Private Limited, BT TechLabs Private Limited (LocoNav), Web World Digital Solutions Private Limited (TrackoBit), Verizon Connect, fleetx Technologies Private Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Fleet Management Software Market Shifts & Advancements
API-first platform architecture is displacing monolithic fleet software, enabling modular procurement where operators subscribe to specific capabilities rather than bundled suites. Real-time data streaming at sub-minute intervals is becoming the baseline expectation.
Edge computing nodes deployed within vehicle cabins are digitizing telemetry processing, reducing latency for critical safety alerts and enabling offline operation during connectivity blackouts. Large fleet operators with over two hundred vehicles are piloting these architectures fastest, compressing their dependence on continuous cloud uplinks for core functionality.
The Central Pollution Control Board's emission monitoring linkages are tightening integration requirements between fleet software and vehicle diagnostic systems. Commercial vehicle categories above 3.5 tonnes gross vehicle weight face the steepest compliance deadlines, with logistics providers in Delhi-NCR and Mumbai-Pune corridors accelerating procurement to meet enforcement windows.
Subscription-based pricing is displacing perpetual license models across mid-sized fleet operators with fifty to two hundred vehicles. Monthly per-vehicle fees reduce capital barriers and align vendor incentives with ongoing platform utilization, a shift most visible among third-party logistics providers in Tamil Nadu and Telangana seeking operational flexibility.
India Fleet Management Software Market Segmentation
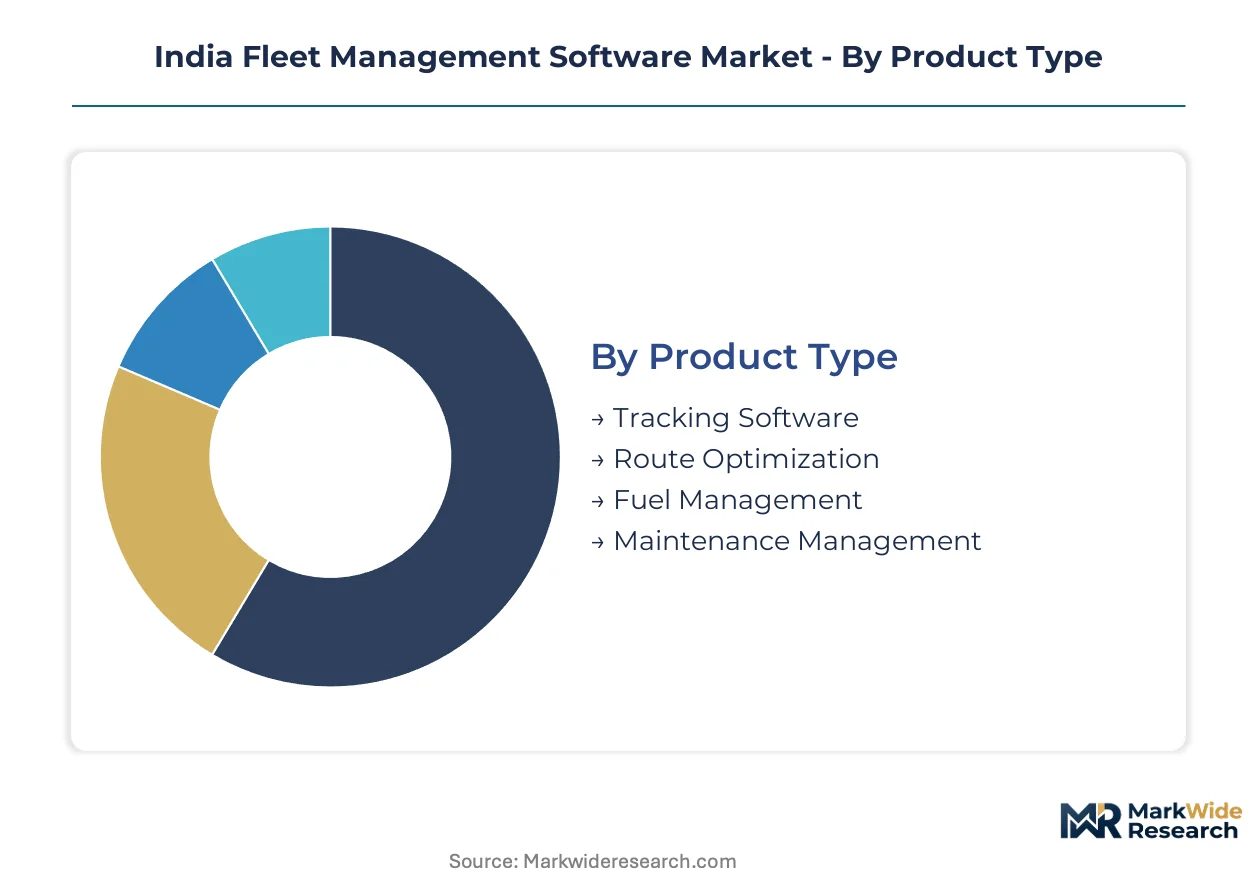
Segmentation reveals how procurement priorities diverge across fleet operator profiles in India. Deployment preferences split sharply between capital-constrained smaller operators and enterprise accounts seeking scalability. Product mix varies with fleet utilization intensity and regulatory exposure.
Product Type:
Application focus determines software architecture requirements and integration depth with vehicle systems.
- Tracking Software:GPS-based location monitoring forms the foundational layer, processing telemetry at sub-minute intervals for real-time visibility. Maharashtra and Gujarat logistics corridors drive concentrated demand as port-linked freight operators prioritize cargo security and regulatory compliance.
- Route Optimization:Dynamic recalculation engines integrate traffic, fuel price, and toll data to minimize operating costs. Fuel cost volatility in long-haul corridors accelerates adoption fastest among third-party logistics providers seeking margin protection.
- Fuel Management:Consumption analytics and theft detection modules address diesel expenditure control.
- Maintenance Management:Predictive scheduling based on engine diagnostics and utilization patterns.
Tracking software commands the established base. The steepest expansion runs through route optimization.
Deployment:
Cost tier and capital structure shape procurement decisions across operator size classes.
- Cloud-Based:Subscription pricing eliminates upfront infrastructure investment, enabling rapid scaling across distributed vehicle networks. Logistics providers in Karnataka and Tamil Nadu favor this model for operational flexibility and reduced IT overhead.
- On-Premise:Legacy installations persist among defense and public sector fleets with stringent data sovereignty requirements. BIS certification complexity and extended procurement cycles constrain new adoption.
- Hybrid:Split architectures balance sensitive data on-premise with analytics in cloud environments.
- Web-Based:Browser-accessible platforms serve small fleet operators below fifty vehicles with minimal technical requirements.
Cloud-based deployment captures volume leadership. Hybrid configurations are gaining share fastest among security-conscious enterprises.
End User:
Customer type dictates feature prioritization, integration complexity, and contract value profiles.
- Logistics Providers:Third-party operators require modular platforms with API connectivity to shipper systems and warehouse management software. Dense deployment concentrates in Delhi-Mumbai industrial corridors where e-commerce fulfillment pressures drive real-time visibility demands.
- Transportation Companies:Asset-heavy operators prioritize predictive maintenance and driver behavior monitoring to maximize vehicle utilization.
- Enterprises:Captive fleet operators in manufacturing and retail seek ERP integration and carbon accounting capabilities.
- Government Agencies:Public transport and municipal fleets emphasize AIS-140 compliance and passenger safety systems.
Logistics providers anchor current revenue. Enterprise accounts are expanding most quickly as supply chain digitization accelerates.
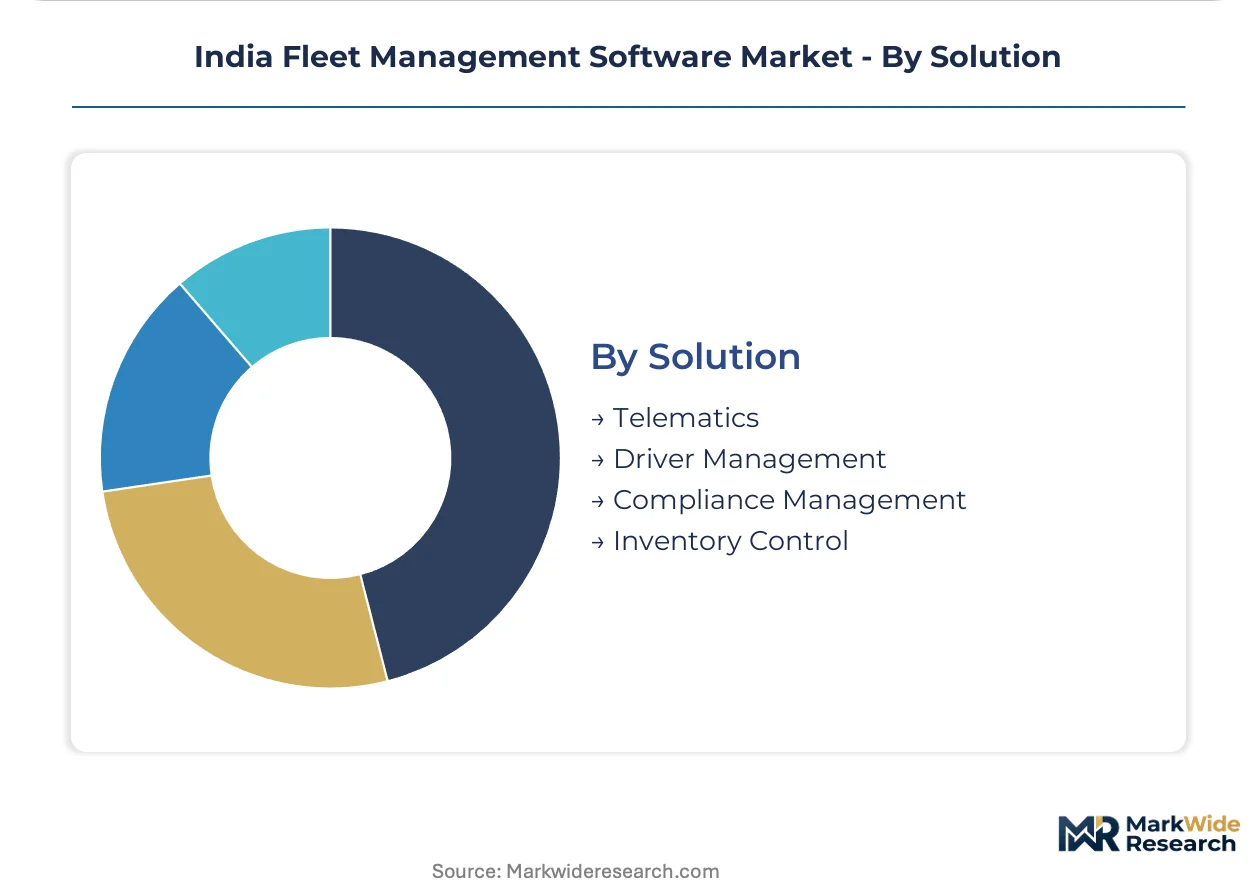
Solution:
Maturity and margin concentration vary across functional modules and their hardware-software bundling requirements.
- Telematics:Integrated sensor-to-cloud platforms combining GPS, OBD-II diagnostics, and cellular connectivity generate recurring revenue through hardware-software bundles. The Central Pollution Control Board's emission monitoring mandates tighten integration requirements for commercial vehicles above 3.5 tonnes.
- Driver Management:Behavior scoring, fatigue detection, and training modules address insurance cost reduction and safety compliance.
- Compliance Management:Automated AIS-140 reporting, FASTag reconciliation, and permit tracking reduce administrative burden.
- Inventory Control:Cargo condition monitoring and proof-of-delivery systems serve temperature-sensitive and high-value freight segments.
Telematics commands the established base. Compliance management is climbing the fastest as regulatory enforcement tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports fleet management software services and embedded systems to Southeast Asian logistics markets and African mining operators. The domestic market concentrates around port-linked freight corridors and manufacturing clusters where commercial vehicle density drives platform deployment. State-level regulatory enforcement varies, creating demand pockets tied to compliance deadlines.
Maharashtra
Mumbai-Pune industrial corridor generates dense fleet deployment from third-party logistics providers serving e-commerce fulfillment. The Ministry of Road Transport and Highways enforces AIS-140 compliance deadlines most aggressively here. JNPT port-linked freight operators in Navi Mumbai accelerate GPS tracking procurement ahead of enforcement windows.
Gujarat
Mundra and Hazira port zones anchor manufacturing supply chains with captive fleet requirements for steel and petrochemicals. The state's industrial promotion schemes subsidize fleet digitization for small operators. Ahmedabad-Surat freight corridors exhibit the highest telematics penetration rates among mid-sized logistics providers.
Karnataka
Bengaluru's technology hub spurs demand for API-first platforms among IT-enabled logistics startups. BIS certification timelines compress as state industrial parks prioritize automotive electronics manufacturing. Whitefield and Electronics City industrial zones host pilot deployments of edge-computing vehicle nodes.
Tamil Nadu
Chennai-Coimbatore manufacturing belt sustains heavy commercial vehicle utilization in automotive component supply chains. The state's pollution control board mandates emission monitoring linkages ahead of national deadlines. Sriperumbudur industrial corridor operators prioritize predictive maintenance modules for just-in-time delivery contracts.
Delhi-NCR
Grim air quality enforcement drives fastest adoption of CPCB-mandated emission tracking for heavy commercial vehicles. The Supreme Court-monitored diesel ban jurisdictions force fleet operators into compliance-driven procurement cycles. Gurugram and Faridabad logistics parks concentrate demand for integrated FASTag and fuel management solutions.
India Fleet Management Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across deployment modes and fleet size segments. The market exhibits moderate consolidation with three distinct tiers: global platform vendors, domestic telematics integrators, and regional software specialists. Strategic archetypes include API-first cloud platforms, hardware-software bundle providers, and compliance-focused solution vendors. Dominant competitive moves center on BIS certification acceleration and FASTag integration partnerships.
Within the global platform tier, Samsara Networks India Private Limited and Trimble Mobility Solutions India Private Limited occupy positions defined by sensor ecosystem breadth and geospatial routing depth. Domestic specialists including Uffizio India Software Consultants Private Limited and fleetx Technologies Private Limited exemplify agile deployment models targeting mid-sized operators. VAMOSYS represents the hardware-centric archetype with embedded systems capabilities.
| Leading Market Players |
|---|
| Samsara Networks India Private Limited |
| Uffizio India Software Consultants Private Limited |
| Trimble Mobility Solutions India Private Limited |
| VAMOSYS |
| Cygnux Softtech Private Limited |
| BT TechLabs Private Limited (LocoNav) |
| Web World Digital Solutions Private Limited (TrackoBit) |
| Verizon Connect |
| fleetx Technologies Private Limited |
| Others |
Supply & Pricing Matrix
Cellular module manufacturing concentrates in China and Taiwan, anchoring hardware cost structures for Indian fleet telematics providers and compressing margins on entry-level GPS trackers. This upstream concentration forces domestic software vendors to capture value through recurring SaaS tiers rather than device markups, shifting margin pools toward cloud-native platforms with sticky subscriber bases.
Pricing Analysis
Legacy on-premise installations command three-to-five year amortization schedules that cloud-native platforms undercut with monthly per-vehicle subscriptions. Three-tier pricing structure across premium, standard, and economy levels segments by integration depth, with API-first platforms capturing premium positioning through real-time data streaming capabilities. Pricing pressure stems from BIS certification delays that extend vendor qualification timelines and inflate compliance costs. Small fleet operators below fifty vehicles exhibit acute price sensitivity, while enterprise accounts with two hundred-plus vehicles prioritize scalability over per-unit economics.
Supply Chain Analysis
Extended payment terms from large logistics providers compress working capital for hardware-software bundle vendors, forcing telematics specialists to secure supply-chain finance facilities. Manufacturing concentrates in China, Taiwan, and South Korea for GPS chipsets, cellular modules, and OBD-II diagnostic hardware. The supply chain draws from semiconductor foundries, lithium-ion battery cell producers, and injection-molded enclosure fabricators. Single-source vulnerability around AIS-140 certified GPS chipsets creates qualification bottlenecks when demand surges ahead of enforcement deadlines. Distribution runs through direct enterprise sales teams for large fleet accounts and regional system integrators for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among third-party logistics providers with two hundred-plus vehicle fleets, compressing vendor margins and forcing platform consolidation around API-first architectures.
For Market Incumbents: Entrench dominance through accelerated BIS certification pipelines that filter unqualified competitors, while deepening FASTag integration partnerships to lock in toll-data monetization. Threat substitution from low-code fleet platforms demands defensive API ecosystem expansion. Vertical integration into edge-computing hardware design preserves margin on high-utilization enterprise accounts. For New Entrants and Emerging Players: Establish a beachhead in Tamil Nadu and Telangana mid-market logistics corridors where cloud-native adoption lags Maharashtra and Karnataka penetration rates. White-space targets include predictive maintenance modules for automotive component supply chains and carbon accounting dashboards for Delhi-NCR compliance-driven procurement. Go-to-market angle should emphasize rapid deployment cycles measured in weeks rather than legacy vendor months. For Investors and Strategic Acquirers: Capital is best deployed toward domestic telematics integrators with embedded systems capabilities and existing BIS certification portfolios. Long-term viability hinges on regulatory compliance automation rather than pure-play tracking functionality. Signal to watch is Central Pollution Control Board acceleration of emission monitoring linkages for commercial vehicles above 3.5 tonnes, which would force vendor requalification and consolidate market share around prepared platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architecture enables modular procurement from third-party logistics providers seeking operational flexibility. |
| Geographic Expansion | State-level AIS-140 enforcement windows in Maharashtra and Delhi-NCR create compliance-driven demand pockets. |
| Acquisition of Specialist Firm | Embedded systems talent scarcity makes firmware engineering teams strategic acquisition targets. |
| Strategic Partnership | FASTag integration partnerships unlock automated toll reconciliation for long-haul operators. |
| Product Launch | Edge-computing vehicle nodes address connectivity fragmentation on rural national highways. |
Research Methodology
Initial hypotheses were tested against primary input from fleet operations managers, telematics platform engineers, logistics procurement directors, and Ministry of Road Transport and Highways compliance officers and refined through secondary validation. Sources included AIS-140 device certification databases, FASTag transaction disclosures, cellular coverage maps from TRAI, and customs import records for GPS hardware. Bottom-up triangulation across vehicle registration data and top-down validation against logistics sector revenue estimates anchored market sizing.
Demand-supply-balance framing modeled fleet operator procurement cycles against vendor certification capacity and hardware import lead times across the analysis window. Segmentation dimensions included deployment model, fleet size tier, solution type, and state-level regulatory enforcement intensity. CAGRs were derived from logistic curve adoption modeling calibrated to AIS-140 mandate phase-in schedules. Industry-specific inputs incorporated diesel price volatility indices and port freight volume correlations.
Stress conditions across cellular connectivity reliability, BIS certification timeline extensions, and emission monitoring linkage acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts assume documented regulatory enforcement schedules and technology adoption curves. Macroeconomic contraction in manufacturing corridors, abrupt cellular tariff restructuring, or technological deviation toward satellite-based tracking would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Global Automotive Navigation System Market
Telematics and Infotainment
Global Intelligent Transportation System (ITS) Market
Telematics and Infotainment
Global Car Digital Cockpit Market
Telematics and Infotainment
Boat and Ship Telematics Market
Telematics and Infotainment
Video Telematics Market
Telematics and Infotainment
Telematics in Automotive Market
Telematics and Infotainment
Europe Commercial Telematics Market
Telematics and Infotainment
5G V2X Communications Market
Telematics and Infotainment
Automotive Wi-Fi Router Market
Telematics and Infotainment
Motor Racing Telematics Market
Telematics and Infotainment
Europe Dashboard Camera Market
Telematics and Infotainment
Asia-Pacific Automotive Telematics Market
Telematics and Infotainment
North America Automotive Infotainment System Market
Telematics and Infotainment
Mobile Resource Management (MRM) Market
Telematics and Infotainment
Advanced Traveller Information System Market
Telematics and Infotainment
Internet of Things Vehicle-To-Vehicle Communication Market