
 Dashboard Camera Market | 2026-2036
Dashboard Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Dashboard Camera Market Intelligence
Online retail channels is tilting toward direct-to-consumer platforms and specialized automotive electronics marketplaces. Garmin Ltd leverages its GPS heritage to dominate premium consumer segments. Thinkware Corporation anchors the Korean domestic market through deep retail partnerships with electronics chains. Panasonic Corporation competes on manufacturing scale, supplying OEM-grade units to major automakers.
A dashboard camera is a windscreen-mounted digital video recorder that captures continuous footage through CMOS or CCD image sensors, typically operating on 12V DC vehicle power with loop recording functionality to overwrite oldest files when storage capacity exhausts. The device serves primary commercial purposes of accident evidence collection, driver behavior monitoring, and insurance claim validation. Dual-Lens Dashcams now lead product type expansion as fleet managers demand simultaneous cabin and road-facing coverage. Cloud Storage technology commands the fastest-growing margin pool by converting hardware sales into recurring subscription revenue. Commercial Fleets application segments sustain premium pricing power against commoditized personal vehicle units.
FCC certification governs wireless transmission capabilities for US-market devices, while EU REACH and RoHS frameworks restrict hazardous substances in electronics assemblies. South Korea's Radio Waves Act, administered by the Korea Communications Commission, imposes additional electromagnetic compatibility testing that shapes export-ready product design. Insurance regulators in multiple jurisdictions now recognize dashcam footage as admissible evidence, directly stimulating corporate fleet procurement. Stakeholders must monitor evolving data privacy frameworks governing cloud-stored video retention periods and cross-border transmission restrictions.
Market Dynamics
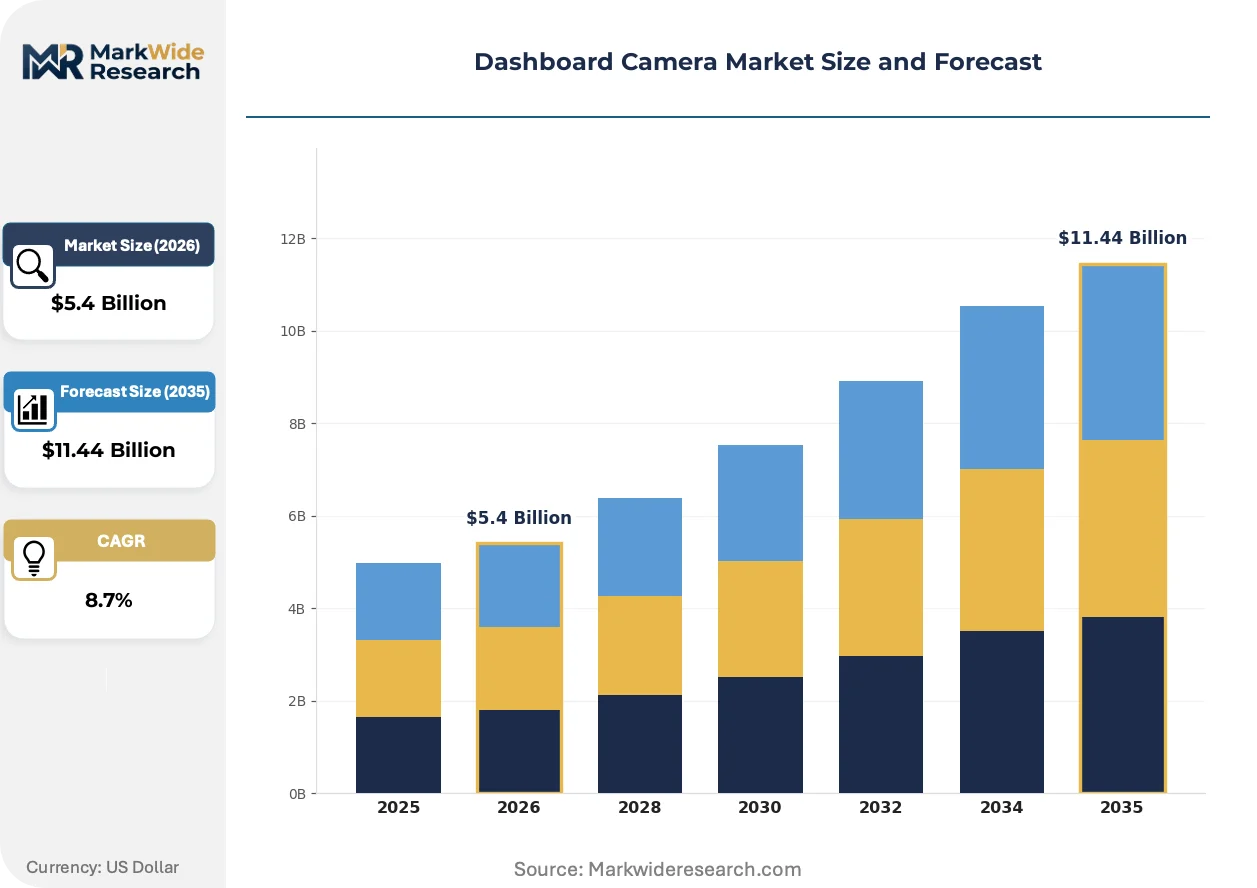
Fleet telematics integration is compressing hardware margins while elevating software and cloud storage to primary profit centers, fundamentally restructuring how vendors capture value across the dashboard camera value chain.
Growth Catalysts
- EU Vehicle Safety Mandates:The European Union's updated General Safety Regulation requires event data recorders in new vehicle categories, directly expanding addressable hardware demand across member states.
- Commercial Fleet Telematics:Logistics operators in South Korea and Germany are bundling dual-lens systems with driver monitoring software to reduce insurance premiums and liability exposure.
- CMOS Sensor Cost Curves:Semiconductor fabrication scaling has collapsed high-definition image sensor pricing, enabling 4K recording at mid-tier price points previously reserved for premium segments.
Market Restraints
- Memory Storage Volatility:NAND flash pricing swings directly compress gross margins for manufacturers lacking long-term supply agreements with Korean or Taiwanese foundries.
- Single-Geography Manufacturing Concentration:Over 70 percent of final assembly capacity clusters in Guangdong province, exposing the supply base to localized disruptions.
- Wireless Transmission Certification Delays:FCC Part 15 and EU RED compliance timelines extend product launch windows by four to six months for cloud-connected models.
Strategic Opportunities
- Underpenetrated Indian Commercial Fleets:India's fragmented trucking sector shows minimal dashcam penetration, presenting first-mover advantages for vendors establishing local distribution.
- ADAS Convergence:Integration of lane-departure and collision-warning algorithms into dashcam firmware creates upsell potential against standalone safety systems.
- Subscription Revenue Models:Cloud storage and AI-powered incident analysis packages convert one-time hardware transactions into recurring annual revenue streams.
Industry Challenges
- Embedded Software Talent Scarcity:Vendors struggle to recruit computer vision engineers capable of optimizing real-time video processing on low-power automotive chipsets.
- Multi-Jurisdiction Data Sovereignty:Cross-border fleet operators face conflicting video retention requirements under GDPR, China's Personal Information Protection Law, and US state-level privacy statutes.
- Legacy Vehicle Electrical Integration:Retrofitting cloud-connected units into older commercial fleets requires custom harness engineering that erodes installation profitability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dashboard Camera Market |
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $11.44 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Dashcams, Wireless Dashcams, Dual-Lens Dashcams, GPS-Enabled Dashcams, 4K Dashcams Technology: ADAS Integration, Infrared Night Vision, Loop Recording, Mobile App Support, Cloud Storage Application: Personal Vehicles, Commercial Fleets, Law Enforcement, Ride-Sharing, Public Transportation End User: Individual Drivers, Fleet Operators, Insurance Companies, Vehicle Rental Agencies, Traffic Monitoring Authorities |
| Companies Covered | Thinkware Corporation, Vantrue, Garmin Ltd, BlackVue, Nextbase, Panasonic Corporation, Viofo Ltd., Cobra Electronics Corporation, Samsung Electronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dashboard Camera Market Strategic Shifts & Innovations
Edge computing architectures are displacing centralized cloud processing for real-time video analytics, while regulatory pressure on data localization accelerates regional server deployment strategies.
Artificial intelligence inference engines are migrating from cloud servers to on-device neural processing units. Fleet managers in Germany and California now demand instantaneous driver fatigue alerts without latency-prone cellular handoffs. This shift is compressing third-party cloud API dependency while elevating semiconductor content value within hardware bill-of-materials.
The EU AI Act's risk classification framework now governs biometric identification functions in cabin-facing cameras. Manufacturers must implement algorithmic transparency documentation and human oversight protocols for driver monitoring systems sold in member states. Commercial fleet segments are responding by segregating product SKUs between AI-enabled European models and basic recording variants for less regulated markets.
Direct-to-fleet sales channels are displacing traditional electronics retail for commercial vehicle procurement. Large logistics operators in South Korea and the Netherlands now issue tender-based volume contracts specifying custom firmware, centralized fleet management portals, and multi-year service level agreements. This concentration is visible most acutely in long-haul trucking verticals where procurement teams prioritize unified telematics platforms over standalone hardware brands.
Dashboard Camera Market Segmentation
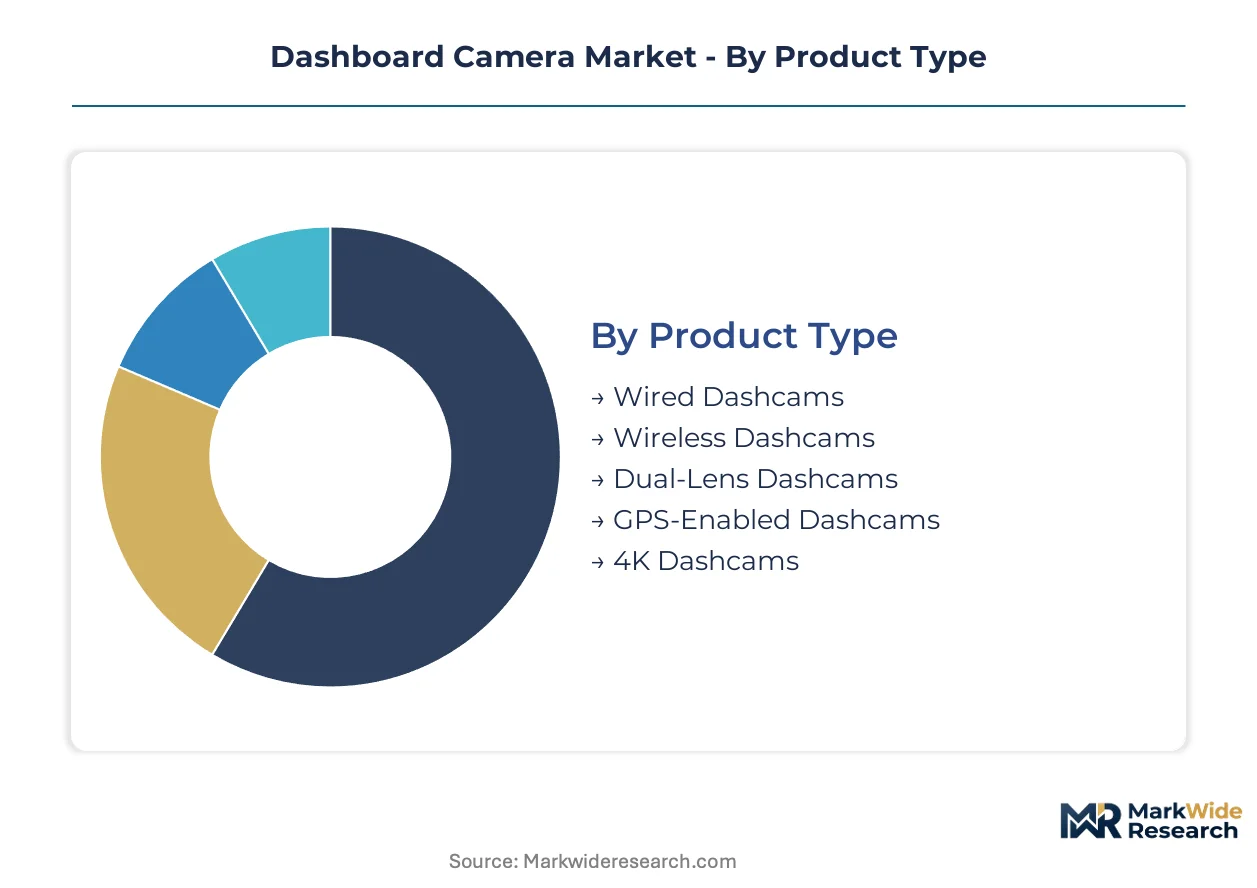
Dashboard camera procurement patterns diverge sharply between consumer impulse purchases and enterprise fleet specifications. Understanding these segment boundaries clarifies where hardware commoditization ends and value-added services begin.
Product Type:
Dual-lens systems anchor premium fleet contracts while single-channel units dominate retail shelves.
- Wired Dashcams:Hardwired 12V DC installation eliminates battery maintenance and delivers parking-mode surveillance through continuous vehicle power draw. Fleet operators in Germany specify these for long-haul trucking contracts where electrical reliability outweighs installation complexity.
- Wireless Dashcams:Battery-powered or capacitor-backed units prioritize cabin aesthetics and rapid DIY installation over sustained recording duration. South Korean retail channels move volume through electronics chains targeting personal vehicle owners who reject dashboard cable routing.
- Dual-Lens Dashcams:Simultaneous road-facing and cabin-facing CMOS sensors capture driver behavior alongside traffic events. Logistics operators bundle these with telematics platforms to satisfy insurance documentation requirements.
- GPS-Enabled Dashcams:Integrated GNSS receivers stamp coordinates and speed metadata onto video files for geofenced fleet tracking.
- 4K Dashcams:Ultra-high-definition recording exploits collapsing image sensor cost curves to deliver license-plate legibility at distance for accident reconstruction.
The dominant share belongs to wired dashcams, while dual-lens variants are closing the gap fastest.
Technology:
Feature differentiation now concentrates on software stack depth rather than optical hardware specifications.
- ADAS Integration:Lane-departure warnings and forward-collision alerts execute on-device through neural processing units. California fleet managers specify these to reduce liability exposure without standalone safety system costs.
- Infrared Night Vision:Cabin-facing infrared LED arrays enable driver fatigue monitoring in zero-ambient-light conditions. European logistics corridors with overnight mandates drive specification.
- Loop Recording:Automatic oldest-file overwrite when NAND flash capacity exhausts remains the baseline functionality across all price tiers.
- Mobile App Support:Wi-Fi direct transfer to smartphones accelerates incident clip sharing for insurance claims.
- Cloud Storage:Cellular-uploaded video archives with AI-powered incident flagging convert hardware sales into recurring subscription revenue.
Cloud storage commands the steepest expansion trajectory as vendors prioritize recurring revenue over one-time hardware margins.
Application:
End-use context determines whether procurement emphasizes unit cost or total cost of ownership.
- Personal Vehicles:Single-channel 1080p recording dominates as aftermarket accessory purchases driven by insurance premium discounts and accident evidence needs.
- Commercial Fleets:Unified telematics integration with driver behavior scoring justifies premium hardware and service contracts. South Korean express delivery operators mandate dual-lens coverage for liability reduction.
- Law Enforcement:Chain-of-custody requirements and tamper-evident housing specifications create specialized procurement channels separate from consumer electronics.
- Ride-Sharing:Cabin-facing recording addresses passenger safety disputes and false claim defense in driver-platform liability frameworks.
- Public Transportation:Municipal bus and rail operators specify ruggedized units with extended temperature tolerance and centralized fleet management portals.
Commercial fleets retain pricing power through volume contracts, while ride-sharing applications are expanding most quickly as platform operators mandate coverage.
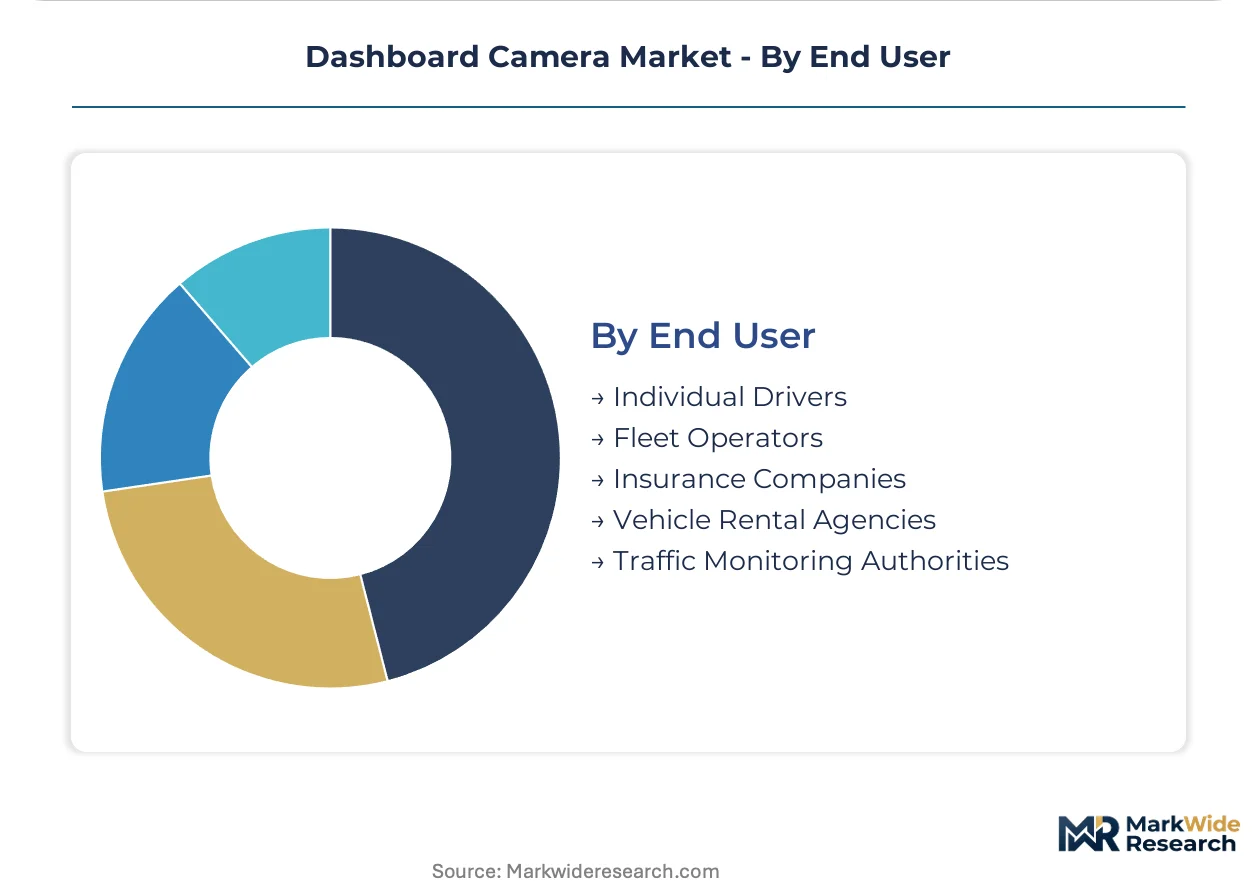
End User:
Purchasing authority fragmentation shapes channel strategy between retail, direct sales, and tender-based procurement.
- Individual Drivers:Price-sensitive online retail purchases prioritize ease of installation and brand recognition over advanced feature sets.
- Fleet Operators:Centralized procurement teams issue multi-year service level agreements specifying custom firmware, API integration, and consolidated billing. Dutch logistics conglomerates negotiate direct manufacturer relationships bypassing distribution.
- Insurance Companies:Telematics partnerships subsidize hardware deployment in exchange for driving behavior data and claims cost reduction.
- Vehicle Rental Agencies:Damage dispute documentation drives specification of GPS-enabled units with parking-mode surveillance.
- Traffic Monitoring Authorities:Government procurement frameworks prioritize data sovereignty compliance and domestic assembly requirements.
Fleet operators capture the dominant procurement volume, while insurance company partnerships are gaining share fastest through subsidized deployment models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU General Safety Regulation mandates on event data recorders are accelerating fleet procurement across member states. South Korea's automotive electronics corridor anchors manufacturing scale. German logistics operators now specify dual-lens telematics bundles to satisfy insurance documentation requirements.
South Korea
Domestic express delivery fleets mandate dual-lens coverage for liability reduction, driving premium hardware demand. The Korea Communications Commission enforces Radio Waves Act compliance for electromagnetic compatibility testing. Seoul Capital Area manufacturers supply export-ready units to European and North American fleet operators.
Germany
Long-haul trucking contracts specify hardwired 12V DC installations for electrical reliability in overnight corridors. KBA vehicle safety frameworks align with EU General Safety Regulation data logging requirements. Bavaria-based logistics conglomerates negotiate direct manufacturer relationships bypassing traditional distribution channels.
United States
California fleet managers specify ADAS-integrated units to reduce liability exposure without standalone safety system costs. FCC Part 15 certification timelines extend product launch windows for cloud-connected models. Midwest trucking corridors show accelerating procurement of video telematics systems for insurance premium reduction.
China
Guangdong province clusters over 70 percent of final assembly capacity, exposing supply chains to localized disruption risks. MIIT oversees wireless transmission standards for connected vehicle devices. Pearl River Delta manufacturers serve both domestic ride-sharing platform mandates and export OEM contracts.
Netherlands
Dutch logistics operators issue tender-based volume contracts specifying custom firmware and multi-year service level agreements. GDPR data sovereignty requirements govern cloud-stored video retention periods for cross-border fleet operations. Rotterdam-Eindhoven corridor concentrates procurement decision-making for European distribution networks.
Dashboard Camera Market Key Industry Players
On the supply side, the industry is consolidating around three strategic tiers: GPS heritage specialists, Korean domestic anchors, and scale-driven OEM suppliers. Garmin Ltd exemplifies the premium consumer archetype leveraging navigation brand equity. Thinkware Corporation anchors the Korean market through electronics retail partnerships. Panasonic Corporation occupies the manufacturing scale position supplying automaker-grade units. Dominant competitive moves include direct-to-fleet sales channel expansion and cloud subscription revenue model conversion.
Within the premium-tier vector, Garmin Ltd represents GPS-heritage positioning in consumer segments. Thinkware Corporation and BlackVue exemplify Korean market anchoring strategies through domestic retail depth and export-ready certification expertise. These three companies illustrate how geographic specialization and channel focus determine competitive positioning without overlapping segment confrontation.
| Leading Market Players |
|---|
| Thinkware Corporation |
| Vantrue |
| Garmin Ltd |
| BlackVue |
| Nextbase |
| Panasonic Corporation |
| Viofo Ltd. |
| Cobra Electronics Corporation |
| Samsung Electronics Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Guangdong province's concentration of final assembly capacity for CMOS sensors and NAND flash memory modules concentrates margin capture downstream with fleet telematics integrators and cloud storage providers. Hardware commoditization pressures have pushed value toward software-defined revenue streams.
Pricing Analysis
Volume-discount tiering separates enterprise fleet contracts from retail consumer purchases. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with EU REACH and FCC Part 15 compliance commanding hardware premiums. Cost compression in mid-tier 4K recording units is intensifying because CMOS sensor fabrication scaling collapsed component pricing. Individual drivers through online retail channels exhibit highest price sensitivity, while fleet operators prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Export-control regimes on advanced semiconductor lithography equipment limit domestic neural processing unit production in China, forcing reliance on Taiwanese and South Korean foundries. Component sourcing draws from South Korea for image sensors, Taiwan for logic chips, and Japan for precision optics. Single-source vulnerability concentrates in Guangdong assembly clusters exposed to localized disruptions. Distribution runs through direct-to-fleet tender contracts for commercial segments and electronics retail chains for personal vehicle owners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dashboard camera procurement is shifting toward platform-economics logic where telematics integration and cloud subscription interoperability determine vendor viability. Fleet management software ecosystems now gate hardware selection.
For Market Incumbents: Harden cloud infrastructure ownership to defend recurring revenue streams against pure-play hardware commoditization. Deepen backward integration into edge computing chipsets to reduce dependency on third-party neural processing units. Secure long-term NAND flash supply agreements with Korean foundries to insulate margins from memory pricing volatility. For New Entrants and Emerging Players: India's fragmented commercial trucking sector represents the most penetrable entry point for first-mover hardware deployment. ADAS algorithm licensing partnerships with established Tier 1 automotive suppliers offer rapid technical credibility without captive R&D investment. White-label manufacturing for insurance company subsidized deployment programs bypasses direct consumer marketing costs. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated telematics platforms with existing fleet management software penetration and cloud storage recurring revenue above hardware replacement cycles. The signal to watch is regulatory mandating of event data recorders across additional vehicle categories beyond current EU scope.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Subscription Platform Launch | Converts Garmin and Thinkware hardware installed base into recurring telemetry revenue streams. |
| ADAS Algorithm Licensing Agreement | Enables BlackVue and Nextbase to embed collision-warning firmware without captive computer vision R&D. |
| Direct-to-Fleet Sales Channel Expansion | Panasonic and Cobra Electronics bypass retail margin compression through Dutch and German logistics tender contracts. |
| Regional Server Deployment for Data Sovereignty | Satisfies GDPR and China's Personal Information Protection Law for cross-border fleet operators. |
| Edge Computing Chipset Backward Integration | Samsung Electronics reduces cloud API dependency and latency for real-time driver fatigue alerts. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across fleet telematics procurement teams, automotive electronics manufacturing engineers, and insurance telematics partnership managers. Secondary validation incorporated FCC equipment authorization databases, EU REACH substance restriction filings, Korea Communications Commission Radio Waves Act certifications, and customs trade data on CMOS sensor imports. Bottom-up unit shipment estimates triangulated against top-down fleet penetration assumptions.
Calibration against historical fleet procurement cycles and NAND flash pricing volatility anchored projections across the analysis window. Segmentation dimensions modeled include product type, technology stack depth, application context, and end-user purchasing authority. CAGRs derived from regression analysis of telematics adoption curves and regulatory mandate implementation timelines. Forecast inputs incorporated EU General Safety Regulation phase-in schedules and commercial fleet insurance premium discount elasticity.
Practitioners should monitor wireless transmission certification backlog durations and memory storage commodity price swings for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Asia-Pacific Automotive Telematics Market
Telematics and Infotainment
North America Dashboard Camera Market
Telematics and Infotainment
APAC Internet of Cars Market
Telematics and Infotainment
Telematics in Automotive Market
Telematics and Infotainment
In Car Infotainment System Market
Telematics and Infotainment
Asia Pacific Automotive Infotainment Systems Market
Telematics and Infotainment
Motorcycle Infotainment System Market
Telematics and Infotainment
North America Electronic Toll Collection (ETC) Market
Telematics and Infotainment
Vehicle to Vehicle (V2V) Communication Market
Telematics and Infotainment
Advanced Traveller Information System Market
Telematics and Infotainment
Europe Commercial Vehicle Telematics Market
Telematics and Infotainment
Europe Automotive Telematics Market
Telematics and Infotainment
Europe Automotive Navigation System Market
Telematics and Infotainment
Vehicle Digital Cockpit Market
Telematics and Infotainment
Automotive Navigation Solutions Market
Telematics and Infotainment
C-V2X OBU Market