
 Global Vehicle Fleet Communication Market | 2026-2036
Global Vehicle Fleet Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vehicle Fleet Communication Market Analytics
The capability gap between cloud-native platforms and legacy hardware-dependent vendors is collapsing as subscription economics displace upfront capital expenditure models. Trimble leverages its precision agriculture heritage to anchor telematics solutions for heavy equipment fleets across North America. Geotab sustains R&D intensity through open API architecture that attracts third-party developers and system integrators. Omnitracs competes on regulatory compliance depth, embedding hours-of-service rules directly into driver workflow tools.
Vehicle fleet communication encompasses the integrated hardware, software, and network infrastructure enabling real-time data exchange between fleet operators, drivers, vehicles, and external systems, typically operating over cellular LTE/5G, satellite, or dedicated short-range communication protocols with sub-30-second location refresh rates. Its primary purpose is optimizing asset utilization, reducing fuel consumption, and ensuring regulatory compliance across distributed transportation networks. Telematics dominates current revenue pools as fleet managers prioritize engine diagnostics and driver behavior monitoring over emerging V2X protocols. Cloud-based deployment leads adoption curves among mid-size logistics providers seeking scalable infrastructure without data center capital. IoT sensor integration represents the fastest-expanding technology segment as predictive maintenance applications reduce unplanned downtime costs.
The European Union's F-Gas Regulation and GDPR compliance frameworks shape product development cycles for vendors serving cross-border operators, while the U.S. Federal Motor Carrier Safety Administration's electronic logging device mandate established baseline connectivity requirements that now extend to video telematics. China's MIIT issues GB standards for connected vehicle data security that foreign suppliers must satisfy for market access. Stakeholders must monitor divergent data sovereignty rules across jurisdictions as fleet data flows trigger multi-regulator oversight regimes.
Market Dynamics
Subscription-based telematics platforms are compressing hardware margins while forcing legacy vendors to abandon perpetual licensing models. Fleet operators now prioritize predictive analytics over basic GPS tracking, reshaping R&D allocation across the vendor base.
Growth Catalysts
- EU Green Deal mandates:Emissions tracking requirements for cross-border logistics fleets are accelerating replacement of first-generation telematics hardware with connected diagnostic systems.
- Cellular IoT module cost curves:Falling LTE-M and NB-IoT chipset prices enable mid-size fleet operators to deploy real-time fuel monitoring without satellite uplink expenses.
- Last-mile delivery densification:E-commerce fulfillment networks in Germany and China are driving demand for sub-30-second location refresh rates and geofenced route optimization.
Market Restraints
- Semiconductor supply concentration:Cellular modem fabrication depends on TSMC and Samsung foundry capacity, creating 16-24 week lead time volatility for telematics control units.
- GPRS network sunsets:2G spectrum reallocation in the United States and Australia forces premature hardware obsolescence for aging fleet installations.
- Data sovereignty fragmentation:China's GB standards for connected vehicle data security impose localization requirements that fragment cloud architecture economics for multinational operators.
Strategic Opportunities
- Video telematics integration:AI-powered driver monitoring systems represent underpenetrated white space in heavy trucking segments where insurance premium reduction justifies hardware investment.
- India's logistics modernization:National highway corridor development and FASTag mandate penetration create first-mover advantages for cellular-connected weighbridge and toll automation vendors.
- V2X protocol convergence:DSRC and C-V2X standardization battles present partnership opportunities for fleet communication providers aligned with NHTSA and 5GAA roadmaps.
Industry Challenges
- Embedded software talent scarcity:Firmware engineering for automotive-grade telematics control units competes with autonomous vehicle development for limited pools of ISO 26262-certified developers.
- Multi-regulator compliance timelines:Simultaneous GDPR data governance, F-Gas refrigerant tracking, and FMCSA hours-of-service rule changes strain product management bandwidth.
- Legacy fleet integration complexity:Pre-CAN-bus vehicles require aftermarket sensor retrofitting that degrades data fidelity and extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vehicle Fleet Communication Market |
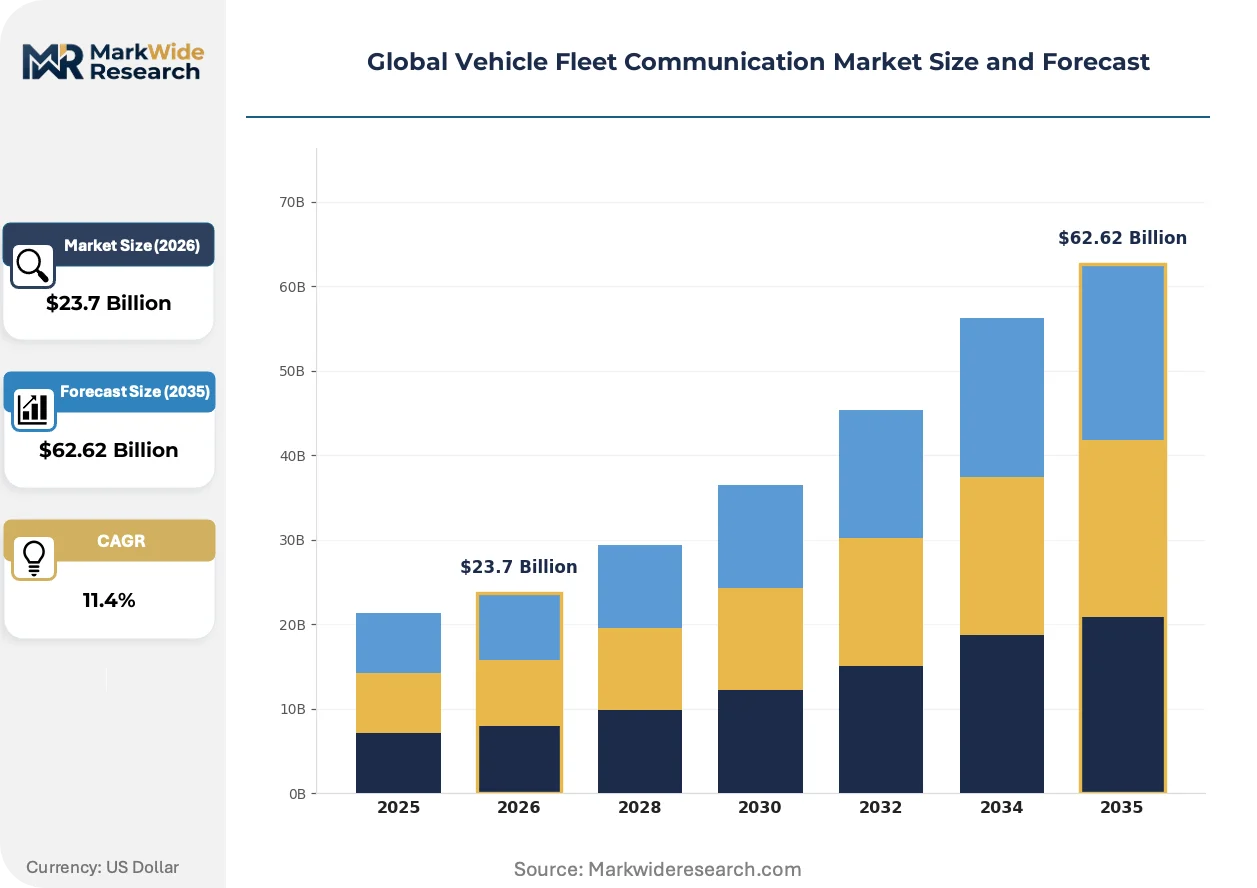
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS, Telematics, V2X, IoT Service Type: Fleet Management, Vehicle Tracking, Data Analytics, Maintenance Services End User: Logistics Providers, Transport Companies, Fleet Owners, Governments Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Solutions |
| Companies Covered | Trimble, TomTom Telematics, Geotab, Powerfleet, Teletrac Navman, Verizon Connect, Omnitracs, MiX Telematics, Samsara, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vehicle Fleet Communication Market Evolving Landscape
Edge computing architectures are relocating data processing from cloud data centers to vehicle-mounted gateways. This shift reduces latency for safety-critical applications while complicating software update orchestration across distributed fleets.
Containerized microservices are supplanting monolithic telematics platforms. Tier-1 logistics providers in the United States are deploying Docker-based applications on edge gateways within 18-month refresh cycles. This architecture enables third-party algorithm integration without hardware swaps, compressing vendor lock-in duration.
California Air Resources Board's Advanced Clean Trucks regulation is mandating zero-emission vehicle reporting infrastructure. Fleet operators must transmit battery state-of-health and charging event data to state databases. Heavy-duty electric truck deployments in California and Oregon are driving demand for combined telematics-charge management platforms.
Outcome-based fleet management contracts are replacing per-vehicle SaaS subscriptions. Third-party logistics providers in Germany now pay telematics vendors against fuel reduction guarantees and on-time delivery metrics. This pricing model concentrates among refrigerated transport segments where temperature excursion liability creates measurable outcome baselines.
Global Vehicle Fleet Communication Market Segmentation
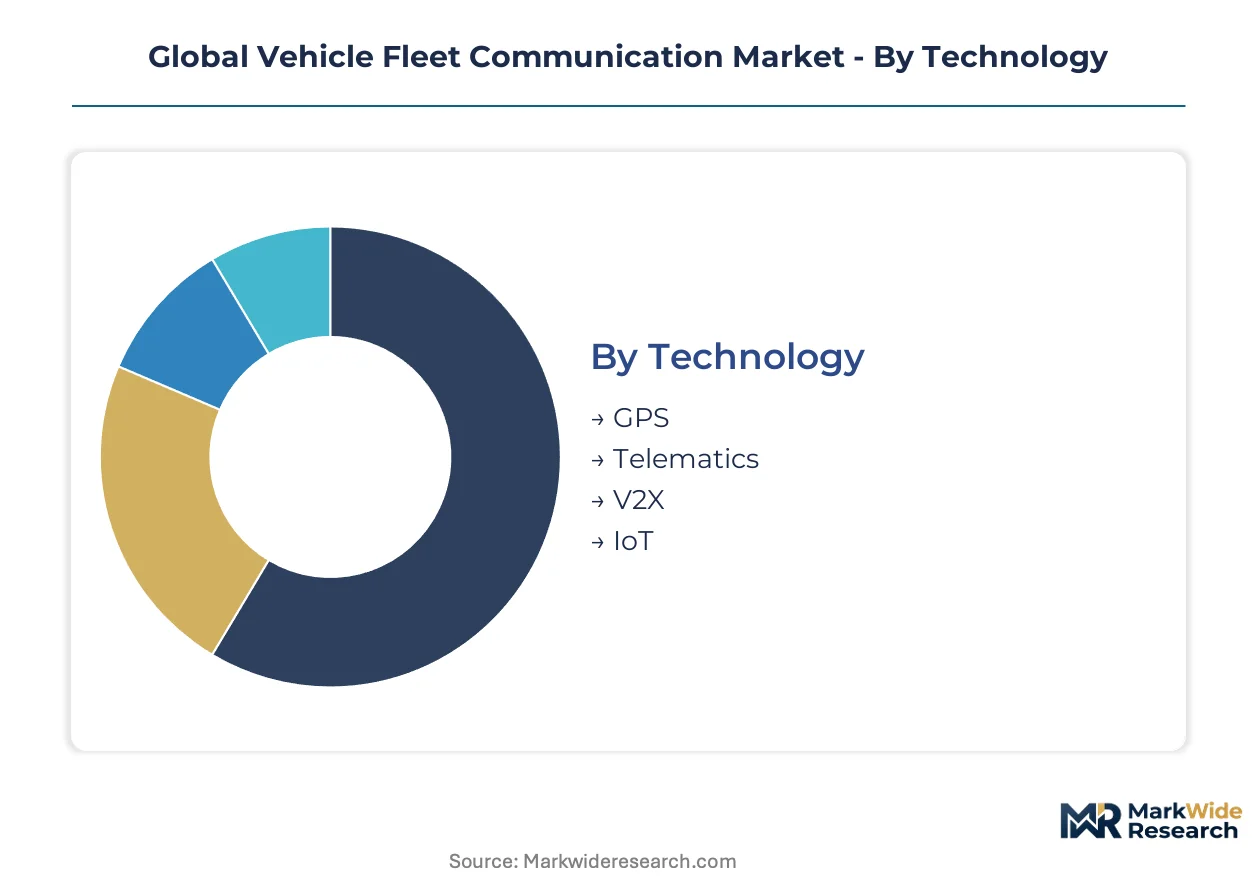
Fleet communication markets fragment across technology maturity curves and regulatory compliance tiers. Understanding segment boundaries reveals where subscription economics displace capital expenditure models and which deployment architectures win across operator scale.
Technology:
GPS and Telematics concentrate demand in domestic fleet operations across Germany and the United States, while V2X and IoT segments track export-led deployment into China's connected vehicle corridors.
- Telematics:Combines cellular modems, CAN-bus integration, and cloud dashboards for real-time engine diagnostics and driver behavior scoring. Demand clusters with heavy trucking fleets in the United States facing FMCSA electronic logging mandates and EU cross-border operators navigating F-Gas refrigerant tracking requirements.
- IoT:Encompasses fuel-level sensors, tire pressure monitors, and cargo condition trackers operating over LTE-M protocols. Logistics providers in Germany and China deploy these for predictive maintenance as cellular module costs fall below satellite uplink thresholds.
- GPS:Satellite-based location systems with 10-30 meter accuracy for basic asset tracking. Mature adoption in small fleet operators across India and Brazil.
- V2X:DSRC and C-V2X protocols enabling vehicle-to-infrastructure and vehicle-to-vehicle communication. Deployment concentrates in Chinese smart highway pilots and NHTSA-aligned corridors in Michigan and Arizona.
Telematics holds the largest share; momentum sits with IoT as predictive maintenance applications expand.
Service Type:
Service tiers stratify by customer technical sophistication, with Fleet Management and Vehicle Tracking dominating mid-market procurement while Data Analytics commands premium pricing from tier-1 logistics providers.
- Fleet Management:Integrated platforms combining dispatch optimization, compliance reporting, and driver workflow tools. Transport companies in California and Texas adopt these to satisfy CARB Advanced Clean Trucks battery state-of-health reporting mandates.
- Data Analytics:Predictive algorithms for fuel consumption modeling, route efficiency scoring, and insurance risk profiling. Third-party logistics providers in Germany negotiate outcome-based contracts tied to measurable delivery metrics.
- Vehicle Tracking:Location-centric services with geofencing and theft recovery features. Standard offering for small fleet owners across India's national highway corridors.
- Maintenance Services:Condition-based scheduling integrating telematics alerts with parts procurement and workshop booking. Emerging traction among refrigerated transport operators managing temperature excursion liability.
Fleet Management captures dominant revenue; Data Analytics climbs fastest as outcome-based pricing models proliferate.
End User:
End-user concentration follows logistics infrastructure investment cycles, with Logistics Providers and Transport Companies driving replacement demand while Government procurement anchors standardization.
- Logistics Providers:Third-party operators managing multi-shipper networks requiring cross-fleet visibility. E-commerce fulfillment densification in Germany and China demands sub-30-second location refresh rates.
- Fleet Owners:Asset-heavy operators with captive maintenance capabilities and long vehicle replacement cycles. Heavy equipment segments in North America prioritize engine diagnostics over emerging V2X protocols.
- Transport Companies:Passenger and freight carriers with regulatory compliance as primary procurement driver. Hours-of-service rule embedding shapes vendor selection.
- Governments:Municipal and national fleet operators standardizing on domestic vendors for data sovereignty compliance. China's MIIT GB standards restrict foreign supplier market access.
Logistics Providers command the largest addressable base; Fleet Owners show steepest expansion trajectory as subscription platforms penetrate mid-market.
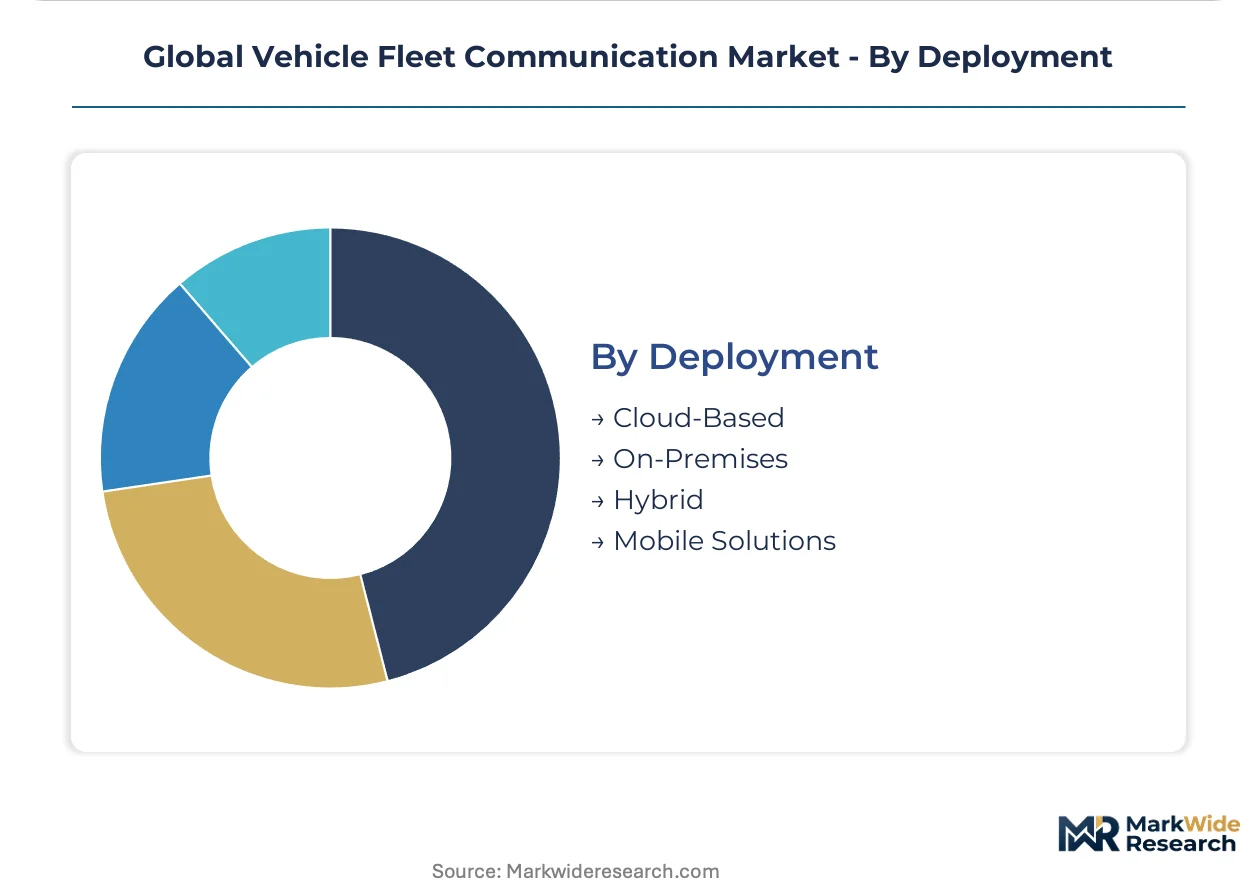
Deployment:
Deployment architecture splits by operator IT maturity, with Cloud-Based solutions capturing mid-market growth and Hybrid configurations serving multinational data sovereignty requirements.
- Cloud-Based:SaaS delivery eliminating data center capital expenditure with API-extensible architectures. Mid-size logistics providers across the United States and Germany prioritize scalable infrastructure without hardware refresh cycles.
- Hybrid:Edge gateways processing safety-critical data locally with cloud aggregation for analytics. Multinational operators navigating China's data localization mandates and GDPR cross-border transfer rules.
- On-Premises:Self-hosted platforms in dedicated facilities. Declining share concentrated in defense and critical infrastructure fleets with air-gapped security requirements.
- Mobile Solutions:Smartphone-dependent tracking without dedicated telematics hardware. Entry-level adoption among owner-operators and last-mile gig economy drivers.
Cloud-Based deployment leads volume; Hybrid configurations gain share fastest as data sovereignty fragmentation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators in Germany and California exhibit low price elasticity as regulatory mandates force hardware refresh cycles, while Brazilian and Indian buyers prioritize cellular module cost curves above predictive analytics capabilities.
United States
FMCSA electronic logging device mandates and CARB Advanced Clean Trucks battery reporting rules drive telematics replacement across heavy trucking fleets. The Federal Motor Carrier Safety Administration hours-of-service enforcement embeds compliance directly into procurement specifications. Fleet modernization concentrates in California's Central Valley freight corridors and Texas interstate highway networks where zero-emission truck deployments require combined charge management platforms.
Germany
Cross-border logistics operators face EU Green Deal emissions tracking and F-Gas refrigerant monitoring requirements that obsolete first-generation hardware. The KBA enforces type-approval standards for connected vehicle systems serving multi-national fleets. Industrial clusters in Bavaria and North Rhine-Westphalia host third-party logistics providers negotiating outcome-based contracts tied to fuel reduction guarantees.
China
MIIT GB standards for connected vehicle data security restrict foreign supplier market access while accelerating domestic platform adoption. National smart highway pilots in the Yangtze River Delta and Pearl River Delta deploy DSRC and C-V2X protocols for vehicle-to-infrastructure communication. E-commerce fulfillment densification in Shanghai and Shenzhen demands sub-30-second location refresh rates for last-mile optimization.
India
FASTag mandate penetration and national highway corridor development create first-mover opportunities for cellular-connected toll automation vendors. The Ministry of Road Transport and Highways mandates commercial vehicle tracking for interstate freight operations. Logistics modernization clusters along the Delhi-Mumbai Industrial Corridor and Chennai-Bengaluru freight routes where weighbridge integration reduces checkpoint delays.
Brazil
GPRS network sunsets force premature hardware obsolescence as carriers reallocate 2G spectrum to LTE services. ANATEL certification requirements shape telematics device approval timelines for aftermarket installations. Fleet communication adoption concentrates in São Paulo state agribusiness corridors and Rio de Janeiro port logistics zones where cargo theft risk justifies real-time tracking investment.
Global Vehicle Fleet Communication Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision hardware vendors competing against cloud-native platform providers for fleet operator procurement budgets. The vendor base organizes around three strategic archetypes: legacy telematics hardware manufacturers pivoting to subscription models, API-first software platforms attracting system integrator ecosystems, and compliance-specialized workflow providers embedding regulatory rules directly into driver interfaces. Dominant competitive moves include strategic partnerships with cellular carriers for IoT connectivity bundling and geographic expansion through localized data center deployments to satisfy data sovereignty mandates.
Within the precision hardware tier, Trimble leverages its positioning technology heritage to anchor heavy equipment fleet solutions across North American markets. Geotab exemplifies the API-first archetype through its open architecture strategy that attracts third-party developer ecosystems. Omnitracs occupies a specialized position embedding hours-of-service compliance rules directly into driver workflow tools for regulated trucking segments.
| Leading Market Players |
|---|
| Trimble |
| TomTom Telematics |
| Geotab |
| Powerfleet |
| Teletrac Navman |
| Verizon Connect |
| Omnitracs |
| MiX Telematics |
| Samsara |
| Others |
Value Network & Pricing Analysis
EU Green Deal emissions tracking mandates and California Air Resources Board battery reporting rules simultaneously gate supplier qualification and stratify price tiers, as compliance-certified platforms command premiums over uncertified alternatives while non-compliant hardware faces accelerated obsolescence.
Pricing Analysis
After-sales service contracts and predictive analytics subscriptions now drive lifetime value beyond initial hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates API-extensible cloud platforms from locked legacy systems and basic GPS-only trackers. Cost compression in economy tiers is intensifying because cellular module commoditization erodes hardware differentiation. Mid-size logistics providers in Germany exhibit lowest price sensitivity as regulatory mandates force replacement cycles regardless of cost.
Supply Chain Analysis
TSMC and Samsung foundry capacity for cellular modem fabrication represents the critical chokepoint determining telematics control unit availability. Component sourcing draws from Taiwanese semiconductor fabrication, Chinese PCB assembly, and Mexican final integration for North American demand. Single-source vulnerability concentrates in advanced node cellular baseband chips. Distribution runs through Tier 1 automotive electronics distributors and direct carrier-IoT bundling partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet communication markets reward service-attach models where predictive maintenance subscriptions and compliance-as-a-service layers expand faster than capital-intensive hardware sales, creating recurring revenue durability.
For Market Incumbents: Compound defensive moats through API ecosystem deepening and localized data center deployments that satisfy China's MIIT GB standards and GDPR cross-border rules. Cloud-native platform entrants threaten legacy hardware-dependent vendors with faster feature velocity. Vertical integration into edge gateway manufacturing restores margin control against commoditized cellular module suppliers. For New Entrants and Emerging Players: Video telematics integration for heavy trucking insurance premium reduction represents the most penetrable white space where incumbents under-serve. India's FASTag-mandated toll automation corridors offer first-mover positioning with lower competitive density. Partner with domestic system integrators in China to bypass MIIT foreign supplier restrictions. For Investors and Strategic Acquirers: California's Advanced Clean Trucks regulation reshapes the acquisition landscape by mandating combined telematics-charge management platforms for zero-emission fleets. Five-to-ten year viability favors API-first software platforms with developer ecosystem network effects over hardware-centric legacy vendors. Monitor NHTSA V2X protocol standardization decisions as inflection signal for DSRC versus C-V2X alignment bets.| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | Open architecture attracts third-party developers and system integrators, reducing customer switching costs. |
| Localized Data Center Deployment | Edge infrastructure in China and EU satisfies MIIT GB standards and GDPR data sovereignty mandates. |
| Video Telematics Integration | AI-powered driver monitoring unlocks insurance premium reduction value in heavy trucking segments. |
| Cellular Carrier Partnership | IoT connectivity bundling with Verizon or Deutsche Telekom compresses customer acquisition costs. |
| Predictive Maintenance Platform | Outcome-based contracts tied to fuel reduction guarantees penetrate refrigerated transport liability segments. |
Research Methodology
Initial hypotheses were tested against primary input from fleet operations directors, telematics procurement managers, cellular carrier IoT specialists, and regulatory compliance officers, then refined through secondary validation across FMCSA enforcement databases, EU F-Gas Regulation filings, MIIT GB standard documentation, and commercial vehicle registration data, with bottom-up unit economics triangulated against top-down market sizing.
Variance decomposition across technology, service type, end user, and deployment architecture segments shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectory modeling incorporating cellular module cost curve elasticity, regulatory mandate implementation timelines, and fleet replacement cycle dynamics.
Forecasts assume regulatory continuity in EU Green Deal enforcement, CARB Advanced Clean Trucks mandates, and MIIT data localization requirements; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as V2X protocol standardization battles and semiconductor supply concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Electronic Rotary Controller Systems for Infotainment Market
Telematics and Infotainment
Europe Commercial Vehicle Telematics Market
Telematics and Infotainment
Global Car GPS Navigation System Market
Telematics and Infotainment
Japan Commercial Telematics Market
Telematics and Infotainment
Automotive Personal Navigation Systems Market
Telematics and Infotainment
Internet of Things Vehicle-To-Vehicle Communication Market
Telematics and Infotainment
Dashboard Camera Market
Telematics and Infotainment
Boat and Ship Telematics Market
Telematics and Infotainment
Europe Automotive Telematics Market
Telematics and Infotainment
Roadside Assistance Software Market
Telematics and Infotainment
GPS Tracker Market
Telematics and Infotainment
United States Commercial Telematics Market
Telematics and Infotainment
C-V2X OBU Market
Telematics and Infotainment
Car Generated Data Market
Telematics and Infotainment
APAC Internet of Cars Market
Telematics and Infotainment
India Fleet Management Software Market