
 Europe Automotive Telematics Market | 2026-2036
Europe Automotive Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Telematics Market Foresight
The EU Green Deal is rebalancing investment priorities across European automotive supply chains. Continental AG leverages its embedded systems division to capture fleet management contracts requiring real-time emissions compliance. Robert Bosch GmbH anchors its competitive position through R&D intensity in vehicle-to-cloud architectures. Vodafone Automotive differentiates via channel control over cellular connectivity modules serving insurance telematics providers.
Europe automotive telematics encompasses GPS, GSM, Wi-Fi, and Bluetooth-enabled data transmission systems integrated into vehicles for remote monitoring, diagnostics, and two-way communication with centralized platforms. These systems typically operate through embedded control units processing CAN bus signals at sub-second intervals to deliver location, performance, and behavioral metrics to fleet operators, insurers, and OEMs. Embedded systems command the largest installed base due to OEM pre-installation mandates, while cloud solutions represent the fastest-expanding segment as edge computing architectures reduce latency for predictive maintenance applications. Insurance telematics concentrates margin pools through usage-based pricing models that monetize driver behavior data.
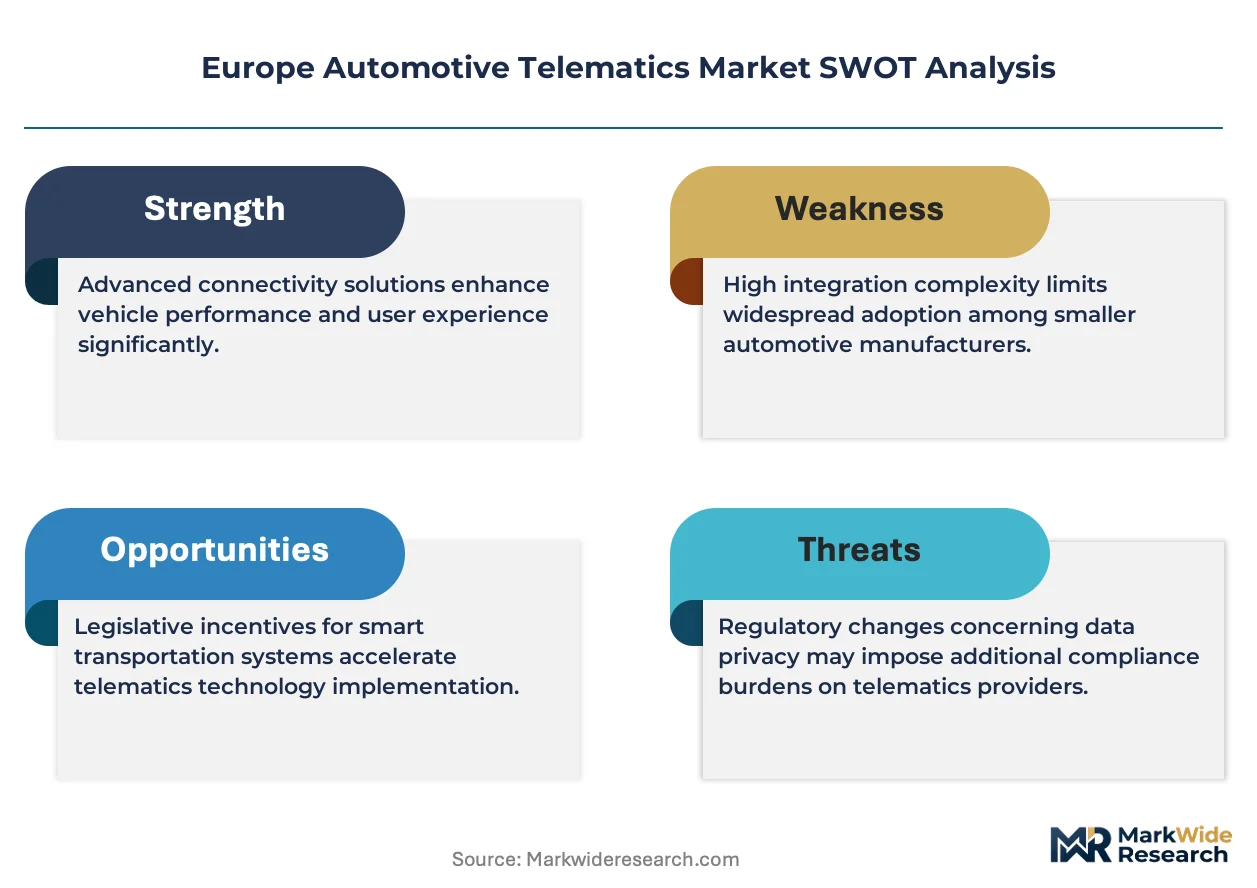
EMA, ECHA, and the EU AI Act collectively shape product standards, data governance, and algorithmic transparency requirements for connected vehicle platforms across Europe. REACH compliance obligations extend to hardware components, while GDPR restricts cross-border data flows and mandates explicit consent for biometric driver monitoring. Fleet operators and technology vendors must monitor evolving cybersecurity certification schemes under the EU Cyber Resilience Act as regulatory scope broadens from vehicle safety to network integrity.
Market Dynamics
The EU Green Deal's emissions monitoring mandates are compressing vehicle data infrastructure timelines across European automotive supply chains. Fleet operators now require real-time CAN bus telemetry to demonstrate compliance with evolving carbon accounting standards.
Growth Catalysts
- EU Green Deal mandates:Emissions monitoring requirements for commercial fleets are mandating embedded connectivity hardware retrofits across Germany, France, and Poland.
- Edge computing architectures:Predictive maintenance platforms are reducing latency for diagnostic data processing, enabling sub-second anomaly detection in powertrain systems.
- Insurance telematics expansion:Usage-based pricing models are monetizing driver behavior data through cellular-connected OBD-II dongles in Italy and Spain.
Market Restraints
- Semiconductor supply concentration:Embedded control unit production depends on Taiwanese foundry capacity, creating vulnerability in automotive-grade chip availability.
- GDPR compliance friction:Cross-border data flow restrictions limit centralized fleet analytics platforms from processing driver biometric data outside originating member states.
- Cellular module cost volatility:5G chipset pricing fluctuations compress margins for aftermarket telematics hardware vendors serving price-sensitive Eastern European markets.
Strategic Opportunities
- Romanian fleet underpenetration:Commercial vehicle connectivity rates lag Western European benchmarks, creating whitespace for embedded OEM partnerships with local logistics operators.
- EU Cyber Resilience Act certification:Early compliance with vehicle network integrity standards opens preferential procurement channels with German municipal fleet tenders.
- V2X convergence with smart city infrastructure:Cellular vehicle-to-everything protocols are integrating with Dutch and Danish urban traffic management systems for priority signaling.
Industry Challenges
- Embedded systems engineering talent scarcity:CAN protocol firmware developers and automotive cybersecurity specialists command premium compensation in Stuttgart and Munich manufacturing corridors.
- Legacy fleet integration complexity:Pre-2018 commercial vehicles require aftermarket retrofit kits that must interface with heterogeneous OBD-II implementations across Scania, Volvo, and DAF platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Telematics Market |
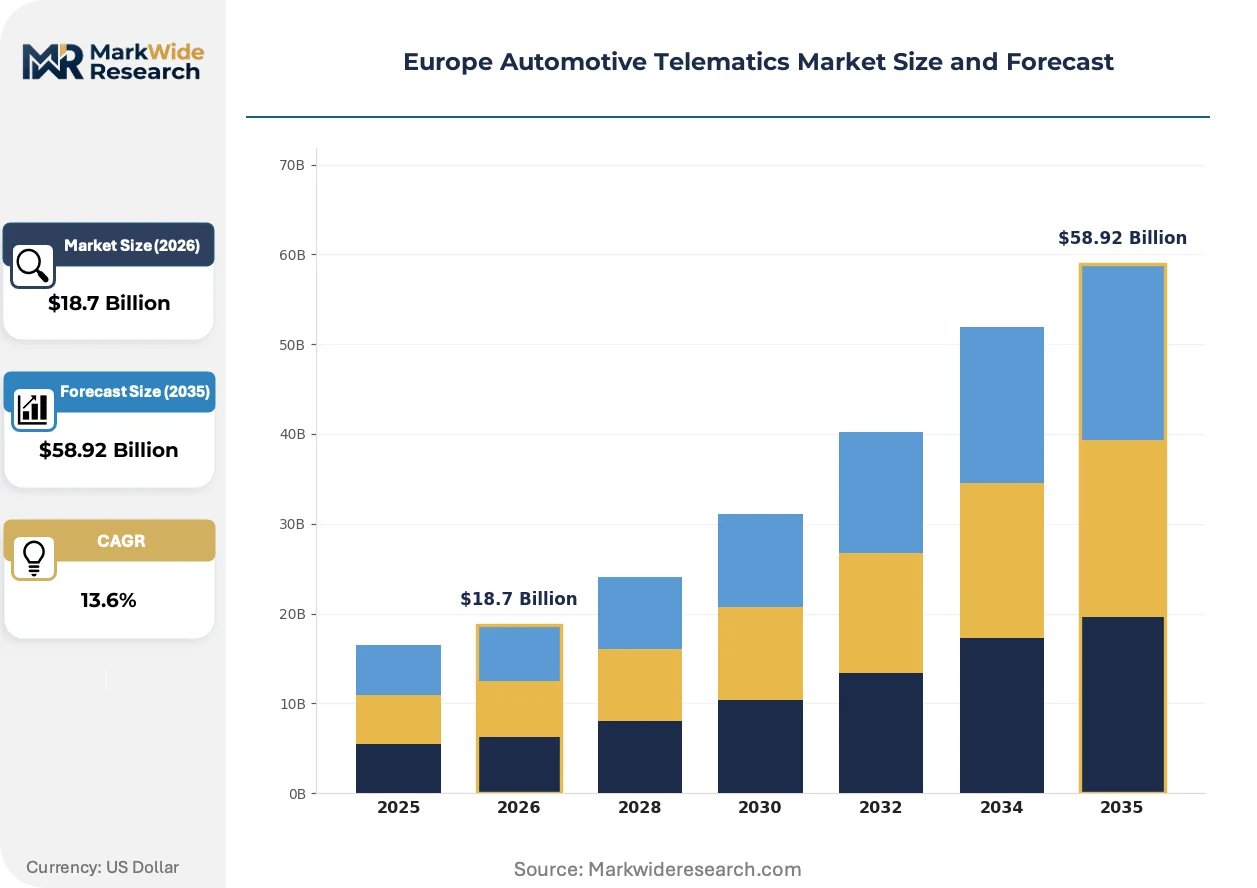
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $58.92 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Systems, Aftermarket Devices, Smartphone Applications, Cloud Solutions Technology: GPS, GSM, Wi-Fi, Bluetooth Application: Fleet Management, Vehicle Tracking, Insurance Telematics, Roadside Assistance End User: OEMs, Fleet Operators, Insurance Companies, Individual Users |
| Companies Covered | Continental AG, Robert Bosch GmbH, TomTom International BV, Octo Group S.p.A, Vodafone Automotive, Geotab, Verizon Connect, Magneti Marelli SpA, Ficosa International SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Telematics Market Shifts & Advancements
Software-defined vehicle architectures are decoupling hardware refresh cycles from feature deployment, compressing telematics platform upgrade timelines. This shift is redistributing value from embedded hardware suppliers to cloud-native platform vendors.
Edge computing nodes deployed within vehicle gateways are absorbing diagnostic processing workloads previously handled by centralized fleet management servers. German commercial vehicle operators are retrofitting these modules at scale to enable predictive maintenance without continuous cellular connectivity. The technology is absorbing latency-sensitive applications and compressing data transmission costs for cross-border logistics operators.
REACH compliance obligations are extending to rare earth elements in telematics hardware supply chains, forcing component suppliers to document material provenance through the EU SCIP database. Automotive electronics manufacturers must now certify tungsten and tantalum sourcing for connectivity modules. The regulation most affects aftermarket hardware vendors sourcing from non-EU smelters, who are accelerating supplier audits to maintain CE marking eligibility.
Fleet procurement departments are consolidating telematics vendor relationships from multi-supplier arrangements to single-platform contracts with integrated insurance and maintenance bundling. Large German logistics operators are displacing point solutions with end-to-end mobility service providers. The pattern is most visible in Rhine-Ruhr corridor freight operators, where total cost of ownership contracting now dominates RFP evaluation criteria.
Europe Automotive Telematics Market Segmentation
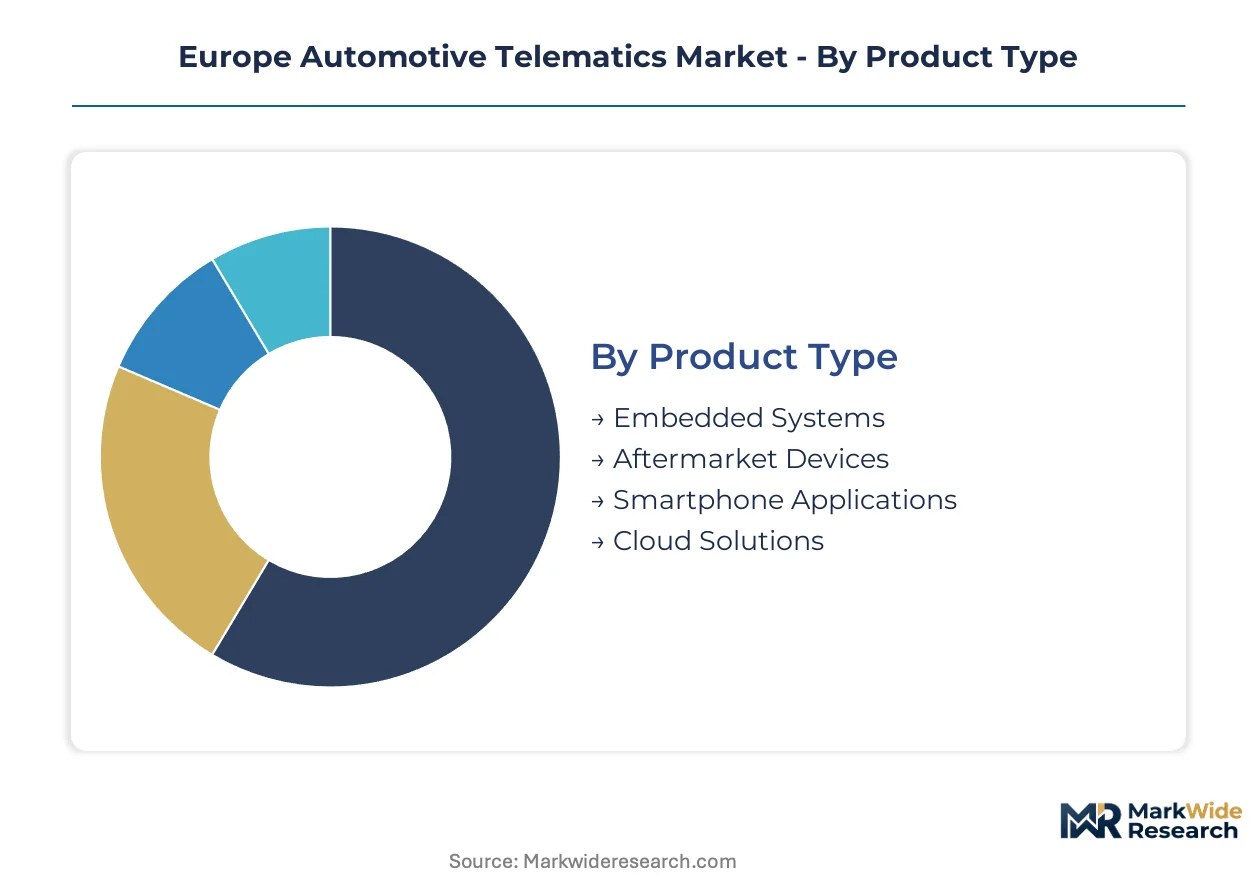
European automotive telematics segments diverge sharply between hardware-anchored revenue pools and software-driven expansion corridors. Fleet procurement patterns and OEM pre-installation mandates determine which segments command margin premiums versus volume scale.
Product Type:
Embedded systems anchor volume shipments while cloud solutions capture the steepest expansion trajectory as edge computing architectures mature.
- Embedded Systems:Factory-integrated control units process CAN bus telemetry through hardened automotive-grade chipsets with 10-year lifecycle guarantees. German commercial vehicle OEMs mandate these modules for EU Green Deal emissions compliance, locking in multi-year procurement contracts with tier-1 suppliers.
- Cloud Solutions:Vehicle-to-cloud platforms aggregate telemetry from heterogeneous fleets into predictive maintenance algorithms with sub-second latency targets. French and Dutch logistics operators are migrating diagnostic workloads from on-premise servers to these architectures, reducing cross-border data transmission costs.
- Aftermarket Devices:Retrofit OBD-II dongles serve pre-2018 commercial vehicle fleets in Poland and Romania where embedded penetration remains incomplete.
- Smartphone Applications:Bring-your-own-device telemetry leverages native sensors for light-duty fleet tracking in Italy's fragmented last-mile delivery sector.
Today's leader: Embedded Systems. Tomorrow's challenger: Cloud Solutions.
Technology:
Cellular protocols dominate commercial fleet deployments while short-range wireless handles in-vehicle device meshing.
- GPS:Multi-constellation receivers combining Galileo, GLONASS, and GPS signals deliver meter-level positioning for geofencing applications across Alpine logistics corridors. German freight operators require redundant satellite coverage for tunnel navigation.
- GSM:LTE-M and NB-IoT cellular modules transmit telemetry through Vodafone and Deutsche Telekom networks serving pan-European fleet operators. The technology commands the largest installed base due to ubiquitous coverage and insurance telematics certification requirements.
- Wi-Fi:802.11p and Wi-Fi 6 enable high-bandwidth firmware updates and media streaming in passenger vehicle cabins.
- Bluetooth:Low-energy beacons authenticate driver identity and synchronize mobile devices with vehicle gateways.
GSM retains volume dominance. GPS gains differentiation through Galileo integration mandates.
Application:
Fleet management concentrates enterprise spending while insurance telematics monetizes behavioral data through usage-based pricing.
- Fleet Management:Real-time vehicle location, fuel consumption analytics, and driver behavior scoring consolidate procurement decisions for Rhine-Ruhr logistics operators. The application absorbs the majority of embedded system shipments due to EU emissions monitoring mandates.
- Insurance Telematics:Cellular-connected dongles capture acceleration, braking, and cornering metrics to price risk dynamically. Italian and Spanish insurers lead European deployment of pay-as-you-drive models for passenger vehicles.
- Vehicle Tracking:Stolen vehicle recovery services leverage GPS-GSM combinations through security operations centers in the UK and Germany.
- Roadside Assistance:Automatic crash notification triggers emergency response protocols through proprietary automotive club networks.
Fleet management commands current investment. Insurance telematics expands most quickly through cellular module cost reductions.
End User:
OEMs control embedded system specifications while fleet operators drive aftermarket and cloud procurement decisions.
- OEMs:Volkswagen Group, Stellantis, and Renault integrate telematics control units during vehicle assembly, specifying firmware architectures that lock competitors out of diagnostic data access. These manufacturers mandate embedded connectivity for warranty compliance and over-the-air update delivery.
- Fleet Operators:DHL, DB Schenker, and mid-size Polish logistics companies select telematics vendors based on total cost of ownership metrics spanning hardware, connectivity, and platform fees. Procurement departments consolidate multi-supplier arrangements into single-platform contracts with insurance bundling.
- Insurance Companies:Allianz, AXA, and Admiral underwrite usage-based policies requiring standardized data formats from connected vehicle platforms.
- Individual Users:Consumer adoption concentrates in stolen vehicle recovery and usage-based insurance enrollment through smartphone-tethered solutions.
OEMs anchor embedded revenue. Fleet operators determine cloud platform winners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive telematics originated in European fleet management corridors during the 1990s, with German commercial vehicle operators pioneering GPS-based cargo tracking across Alpine freight routes. The technology diffused westward through Rhine-Ruhr logistics networks before embedding into OEM production lines.
Germany
Commercial vehicle OEMs mandate embedded connectivity for EU Green Deal emissions compliance, locking in multi-year procurement contracts. The KBA enforces cybersecurity certification under UN R155 for vehicle type approvals. Stuttgart and Munich manufacturing corridors concentrate firmware development talent for CAN protocol systems.
France
Logistics operators in the Île-de-France basin migrate diagnostic workloads to cloud-native platforms to reduce cross-border data transmission costs. The CNIL enforces GDPR consent requirements for biometric driver monitoring systems. Lyon-based fleet operators consolidate multi-supplier telematics arrangements into single-platform contracts.
United Kingdom
Insurance telematics providers deploy cellular-connected dongles for usage-based pricing models in passenger vehicle segments. The Financial Conduct Authority regulates data usage in insurance underwriting algorithms. Security operations centers in Greater London coordinate stolen vehicle recovery services through GPS-GSM combinations.
Italy
Fragmented last-mile delivery operators adopt smartphone-tethered solutions for light-duty fleet tracking. ANSM and CNIL-equivalent data protection frameworks restrict cross-border driver data flows. Milan and Turin automotive clusters anchor embedded system integration for Stellantis production networks.
Netherlands
Urban traffic management systems in Amsterdam and Rotterdam integrate cellular vehicle-to-everything protocols for priority signaling. The Dutch Data Protection Authority enforces algorithmic transparency under the EU AI Act for automated fleet dispatch systems. Randstad logistics operators pilot edge computing nodes for predictive maintenance without continuous connectivity.
Europe Automotive Telematics Market Competitive Landscape
Capital-heavy semiconductor foundries supplying automotive-grade chipsets compete with asset-light platform vendors designing cloud-native fleet management software. The vendor base concentrates around tier-1 automotive suppliers with embedded system integration capabilities and telecommunications operators controlling cellular connectivity modules. Three strategic archetypes dominate: integrated automotive electronics manufacturers, connectivity service providers, and specialized fleet software vendors. Competitive moves center on strategic partnerships between hardware suppliers and cloud platform developers, plus vertical integration into edge computing module production.
Within the integrated automotive electronics tier, Continental AG and Robert Bosch GmbH anchor positions through embedded systems divisions serving OEM pre-installation mandates. Vodafone Automotive occupies a distinct position among connectivity service providers, leveraging channel control over cellular modules for insurance telematics applications. These three exemplify how competitive positioning separates hardware-anchored revenue pools from software-driven expansion corridors.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| TomTom International BV |
| Octo Group S.p.A |
| Vodafone Automotive |
| Geotab |
| Verizon Connect |
| Magneti Marelli SpA |
| Ficosa International SA |
| Others |
Supply & Pricing Matrix
EU Green Deal emissions monitoring mandates gate qualified supply and premium-tier pricing access for embedded telematics hardware, forcing fleet operators to absorb certification-driven cost premiums for automotive-grade chipsets while aftermarket vendors face margin compression from REACH compliance documentation requirements.
Pricing Analysis
Subscription-based SaaS tiering across connectivity platforms separates premium predictive maintenance bundles from standard location-tracking tiers and economy-grade hardware-only procurement. Price differentiation rests on cybersecurity certification under UN R155 and EU Cyber Resilience Act pre-qualification status. Cost compression in economy aftermarket dongles is intensifying because 5G chipset volatility erodes hardware margins. Eastern European fleet operators exhibit highest price sensitivity, while German municipal tenders prioritize certified compliance over unit cost.
Supply Chain Analysis
Firmware engineering talent scarcity in Stuttgart and Munich manufacturing corridors constrains embedded systems production capacity for CAN protocol development. Supply concentrates in Germany for automotive-grade control units, Taiwan for semiconductor foundry output, and China for rare earth element processing in connectivity modules. Raw material dependencies include tantalum capacitors, tungsten contacts, and automotive-grade silicon wafers. Single-source vulnerability in Taiwanese foundry capacity threatens embedded control unit availability. Distribution runs through tier-1 automotive suppliers direct to OEM assembly lines and cellular carriers serving insurance telematics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe automotive telematics functions as a stable compounder, with regulatory compliance mandates generating recurring revenue streams through embedded hardware refresh cycles and platform subscription renewals.
For Market Incumbents: To counter cloud-native platform vendors displacing on-premise fleet management systems, Continental AG and Robert Bosch GmbH should deepen backward integration into edge computing module production while securing exclusive channel control over Vodafone Automotive cellular connectivity for insurance telematics certification.
For New Entrants and Emerging Players: Direct-to-fleet SaaS platforms offer the lowest competitive density for new market entry, with Romanian commercial vehicle operators presenting the most penetrable geography due to embedded connectivity underpenetration versus Western European benchmarks. A usage-based pricing model bundled with cross-border logistics optimization software provides viable go-to-market positioning.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized fleet software vendors lacking embedded hardware integration capabilities, reflecting acquisition opportunity before EU Cyber Resilience Act certification requirements consolidate vendor relationships. Long-term viability favors platforms with dual revenue streams from hardware and recurring software. The signal to watch is German municipal fleet tender awards favoring certified end-to-end providers over point solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| EU Cyber Resilience Act Certification | Early compliance unlocks preferential procurement from KBA-regulated German municipal fleets. |
| Edge Computing Module Production | In-house manufacturing of vehicle gateways reduces latency for predictive maintenance platforms. |
| Cellular Connectivity Partnership | Channel control over Vodafone or Deutsche Telekom modules secures insurance telematics positioning. |
| Romanian Fleet Operator Alliance | Embedded OEM partnerships with underpenetrated logistics operators capture whitespace expansion. |
| Cloud-Native Platform Migration | French and Dutch operators migrating diagnostic workloads reduces cross-border data transmission costs. |
Research Methodology
Direct dialogue with OEM platform engineers, tier-1 supplier procurement leads, fleet operations directors at Rhine-Ruhr logistics operators, and insurance telematics product managers grounded qualitative findings. Secondary validation drew from KBA type approval databases, EU SCIP material provenance filings, vehicle production statistics, and SEC disclosures from automotive electronics manufacturers. Bottom-up segment sizing triangulated against top-down regulatory mandate impact assessments.
Segment-level revenue trajectories across the analysis window reflect modeled deployment of embedded systems, cloud solutions, aftermarket devices, and smartphone applications by fleet management, insurance telematics, vehicle tracking, and roadside assistance applications. CAGRs derived from regression analysis against EU Green Deal compliance timelines, 5G module cost curves, and edge computing adoption rates in German commercial vehicle corridors.
The model assumes a particular technology adoption path; alternative pathways for software-defined vehicle architectures would alter the outlook if OEMs accelerate decoupling of hardware refresh cycles from feature deployment. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and semiconductor supply normalization. Material deviation in Taiwanese foundry capacity allocation or GDPR cross-border data flow rulings warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
India Connected Car Market
Telematics and Infotainment
Telematics-Linked Fleet Battery Health Management Systems Market
Telematics and Infotainment
Automotive Wi-Fi Router Market
Telematics and Infotainment
V2X Communication Module Market
Telematics and Infotainment
Commercial Telematics Market
Telematics and Infotainment
Global 5G in Automotives Market
Telematics and Infotainment
In-Taxi Digital Signage Market
Telematics and Infotainment
Europe Commercial Telematics Market
Telematics and Infotainment
Vehicle Digital Cockpit Market
Telematics and Infotainment
In-Car Infotainment Market
Telematics and Infotainment
Smart Telematics Gateway Market
Telematics and Infotainment
Automotive OEM Telematics Market
Telematics and Infotainment
North America Electronic Toll Collection (ETC) Market
Telematics and Infotainment
Mobility on Demand (Mod) Market
Telematics and Infotainment
GCC Commercial Telematics Market
Telematics and Infotainment
Intelligent Transport Systems (ITS) Market