
 Electric Vehicle Telematics Market | 2026-2036
Electric Vehicle Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Telematics Market Analysis
The EU Green Deal is repositioning automotive OEM sourcing priorities toward embedded telematics with real-time emissions verification. Continental AG leverages its integrated hardware-software stack to anchor European supply relationships for battery management systems. Robert Bosch GmbH competes through manufacturing scale in connectivity modules, while Geotab Inc. specializes in cloud-based fleet analytics for commercial vehicle operators.
Electric vehicle telematics encompasses the integrated systems of sensors, communication modules, and software platforms that collect, transmit, and analyze vehicle performance data over cellular or satellite networks, typically operating through CAN bus interfaces with sub-second latency for critical safety parameters. These systems enable remote battery state monitoring, predictive maintenance scheduling, and usage-based insurance underwriting across passenger and commercial fleets. Hardware components dominate current revenue pools due to module costs and installation complexity, though data analytics represents the fastest-expanding margin segment as fleet managers prioritize predictive insights over raw connectivity. Cloud-based deployment leads adoption among fleet managers seeking centralized oversight, while edge computing gains traction in autonomous vehicle applications demanding millisecond-level response times.
The EPA enforces emissions data transparency requirements that mandate OBD-II telematics integration for compliance verification in the United States, while EMA guidelines across Europe standardize battery health reporting formats for secondary-market valuation. China's MIIT imposes GB standards for connected vehicle data security that shape product architecture for any supplier accessing domestic OEM channels. Stakeholders must monitor regulatory divergence between data localization mandates and cross-border fleet management needs when architecting platform roadmaps.
Market Dynamics
Fleet operators in Germany, China, and the United States are consolidating procurement around embedded connectivity platforms that unify battery management with emissions compliance verification, compressing vendor selection timelines and elevating systems integrators over component suppliers.
Growth Catalysts
- EU Green Deal mandates:The EU Green Deal's emissions tracking requirements are repositioning OEM sourcing toward real-time telematics with verified carbon reporting, accelerating platform deployment across European commercial fleets.
- Battery state monitoring:Predictive algorithms for lithium-ion degradation are reducing warranty exposure for fleet operators, pulling demand toward integrated hardware-software stacks with CAN bus interfaces.
- China:Domestic EV production scaling under MIIT's GB standards for connected vehicle data security is concentrating platform demand within domestic OEM channels and their captive suppliers.
Market Restraints
- Semiconductor input volatility:Cellular module chipsets and CAN bus controllers face allocation constraints from concentrated foundry capacity in East Asia, elevating hardware costs and extending lead times.
- Data localization mandates:China's MIIT requirements for domestic data storage create architectural friction for cross-border fleet management platforms serving multinational operators.
- Edge-to-cloud latency tradeoffs:Millisecond-level autonomous vehicle response requirements strain pure cloud architectures, forcing redundant infrastructure investments that compress margins.
Strategic Opportunities
- Secondary battery valuation:Standardized battery health reporting formats under EMA guidelines are creating white space for analytics platforms serving residual-value underwriting and second-life energy storage applications.
- Edge computing convergence:The intersection of 5G low-latency networks with onboard AI inference engines enables real-time predictive maintenance without persistent cellular connectivity, opening rural and mining fleet segments.
- Usage-based insurance channels:Direct partnerships between telematics providers and commercial insurers bypass traditional fleet management middlemen, capturing premium data monetization in North American long-haul trucking.
Industry Challenges
- Embedded systems engineering talent:Shortages in CAN protocol firmware development and automotive cybersecurity certification are extending platform development cycles and elevating compensation costs.
- Multi-standard compliance timelines:Simultaneous EPA OBD-II integration, EMA battery reporting, and MIIT data security audits create overlapping certification requirements that delay market entry.
- Legacy fleet integration complexity:Retrofit installations in pre-2020 commercial vehicles require custom hardware adapters and protocol translation layers that fragment engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Telematics Market |
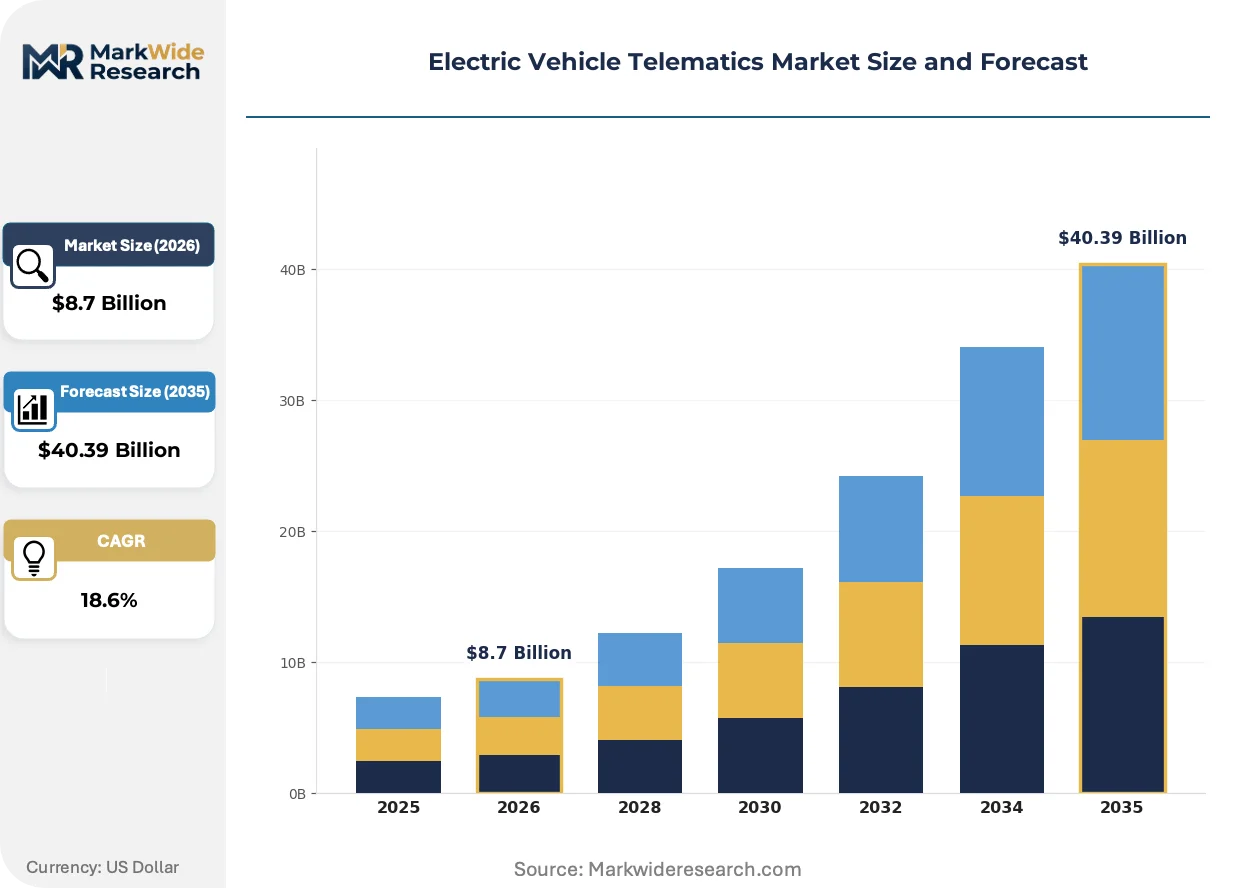
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $40.39 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Connectivity Solutions, Data Analytics Deployment: Cloud-based, On-premise, Hybrid, Edge Computing End User: OEMs, Fleet Managers, Insurance Companies, Consumers Feature: Navigation, Battery Management, Remote Diagnostics, Usage-based Insurance |
| Companies Covered | TomTom International, Robert Bosch GmbH, Continental AG, Geotab Inc., Trimble, Inc., Aptiv PLC, Harman International, NXP Semiconductors, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Telematics Market Emerging Trajectories
Telematics architectures are bifurcating between centralized cloud platforms for fleet oversight and distributed edge systems for safety-critical autonomy, with regulatory pressure and latency requirements driving divergent technical roadmaps.
Edge computing is converging with 5G network slicing to enable millisecond-level battery thermal runaway detection without persistent backhaul dependency. Autonomous shuttle operators in controlled campus environments are piloting these architectures ahead of highway deployment. The structural consequence is compressing the addressable market for pure cloud analytics vendors while elevating hardware-integrated platform providers.
The EU AI Act's risk classification framework is reclassifying predictive maintenance algorithms as high-risk AI systems requiring conformity assessments and audit trails. Industrial consequence includes mandatory documentation burdens for training data provenance and model drift monitoring. Battery management system vendors serving European OEMs are rearchitecting software stacks to embed explainability modules ahead of enforcement timelines.
Commercial fleet managers are unbundling telematics procurement from vehicle acquisition, selecting specialized analytics providers through competitive tender rather than accepting captive OEM subscriptions. This behavior shift disrupts traditional distribution through dealer networks and captive finance arms. The pattern is most visible in German and US long-haul trucking where operating cost transparency outweighs integration convenience.
Electric Vehicle Telematics Market Segmentation
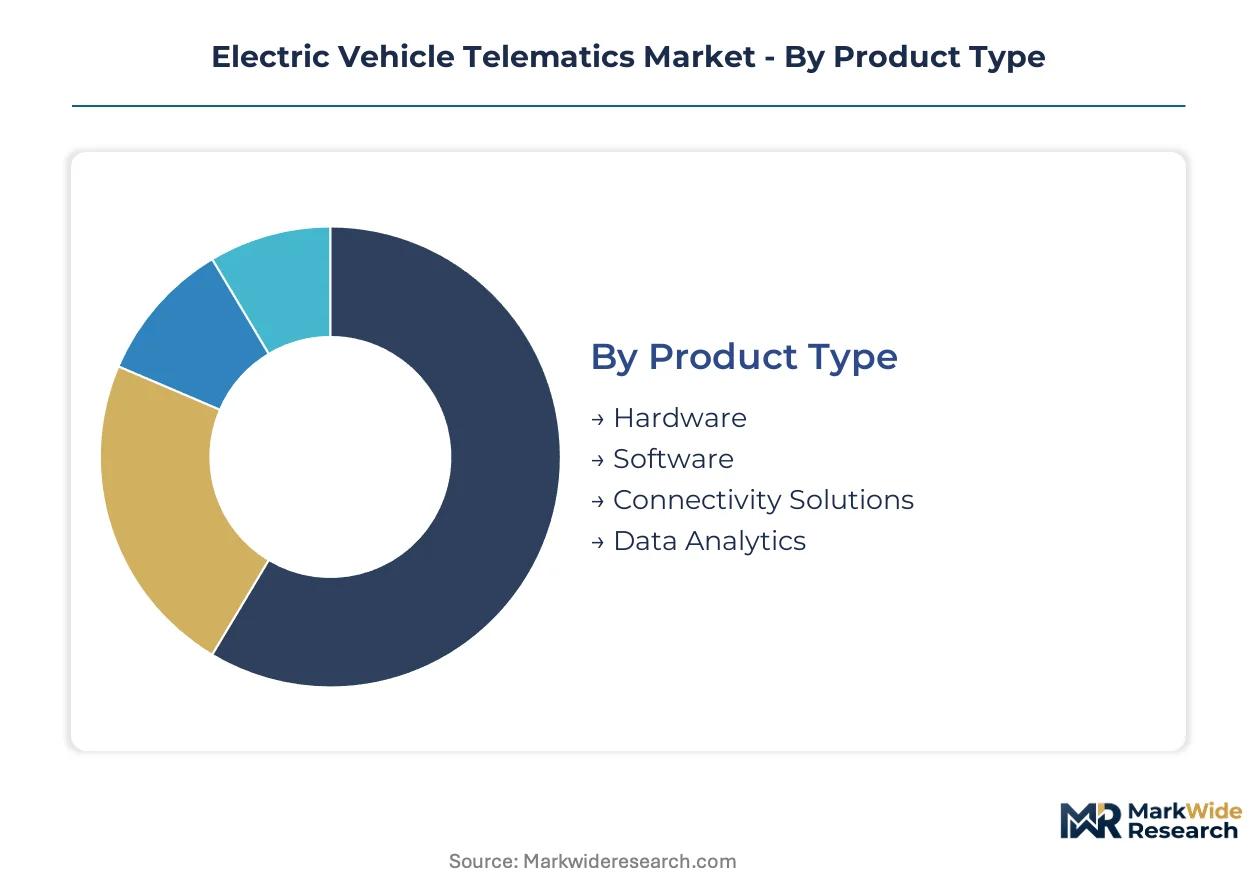
Segmentation in electric vehicle telematics reveals how procurement priorities diverge between hardware-intensive legacy fleets and software-forward next-generation platforms. Upgrade cycles vary dramatically across deployment architectures and end-user categories, compressing vendor roadmaps into incompatible technical specifications.
Product Type:
Replacement cycles for telematics hardware compress as cellular module standards evolve from 4G LTE toward 5G NR, forcing parallel software stack migrations.
- Hardware:CAN bus interfaces, cellular modems, and GPS receivers constitute the physical layer for data acquisition. Fleet operators in Germany prioritize integrated hardware-software stacks from Continental AG and Robert Bosch GmbH to minimize interoperability failures during warranty periods.
- Software:Firmware layers managing protocol translation, over-the-air updates, and security certificates determine platform extensibility. Cloud-native architectures are displacing embedded legacy codebases in North American commercial fleets seeking API interoperability with third-party analytics tools.
- Connectivity Solutions:Cellular, satellite, and DSRC modules enable data transmission.
- Data Analytics:Predictive algorithms for battery degradation and route optimization.
Volume placements concentrate in Hardware; the faster expansion belongs to Data Analytics.
Deployment:
Cost tiering separates centralized cloud platforms accessible via subscription from capital-intensive edge installations demanding onboard GPU acceleration.
- Cloud-based:Centralized data lakes with web dashboards dominate fleet management procurement due to minimal upfront capital requirements. Geotab Inc. anchors this segment through multi-tenant architectures serving North American long-haul operators with standardized API access.
- Edge Computing:Onboard inference engines process safety-critical battery thermal events without cellular backhaul dependency. Autonomous shuttle pilots in controlled campus environments across China and Germany validate millisecond-latency architectures ahead of highway deployment.
- On-premise:Private server installations for data-sovereign operators.
- Hybrid:Architectures splitting processing between edge and cloud tiers.
Customer procurement gravitates toward Cloud-based deployments for fleet oversight; Edge Computing gains share fastest in safety-critical autonomy applications.
End User:
Application-specific requirements fragment procurement specifications between regulatory compliance mandates and operational efficiency priorities.
- Fleet Managers:Commercial operators demand unified dashboards consolidating battery state, emissions verification, and predictive maintenance across mixed-vehicle portfolios. Unbundling from captive OEM subscriptions accelerates competitive tender processes in German and US long-haul trucking.
- OEMs:Vehicle manufacturers embed telematics at factory to control service revenue streams and warranty exposure. EU Green Deal emissions tracking mandates reposition sourcing criteria toward real-time carbon verification capabilities.
- Insurance Companies:Underwriters leverage driving behavior data for risk-adjusted premium pricing.
- Consumers:Individual EV owners access smartphone-integrated features.
Revenue concentration sits with Fleet Managers; Insurance Companies represent the steepest expansion trajectory through usage-based underwriting partnerships.
Feature:
Maturity curves separate commoditized navigation services from emerging battery health monetization pathways.
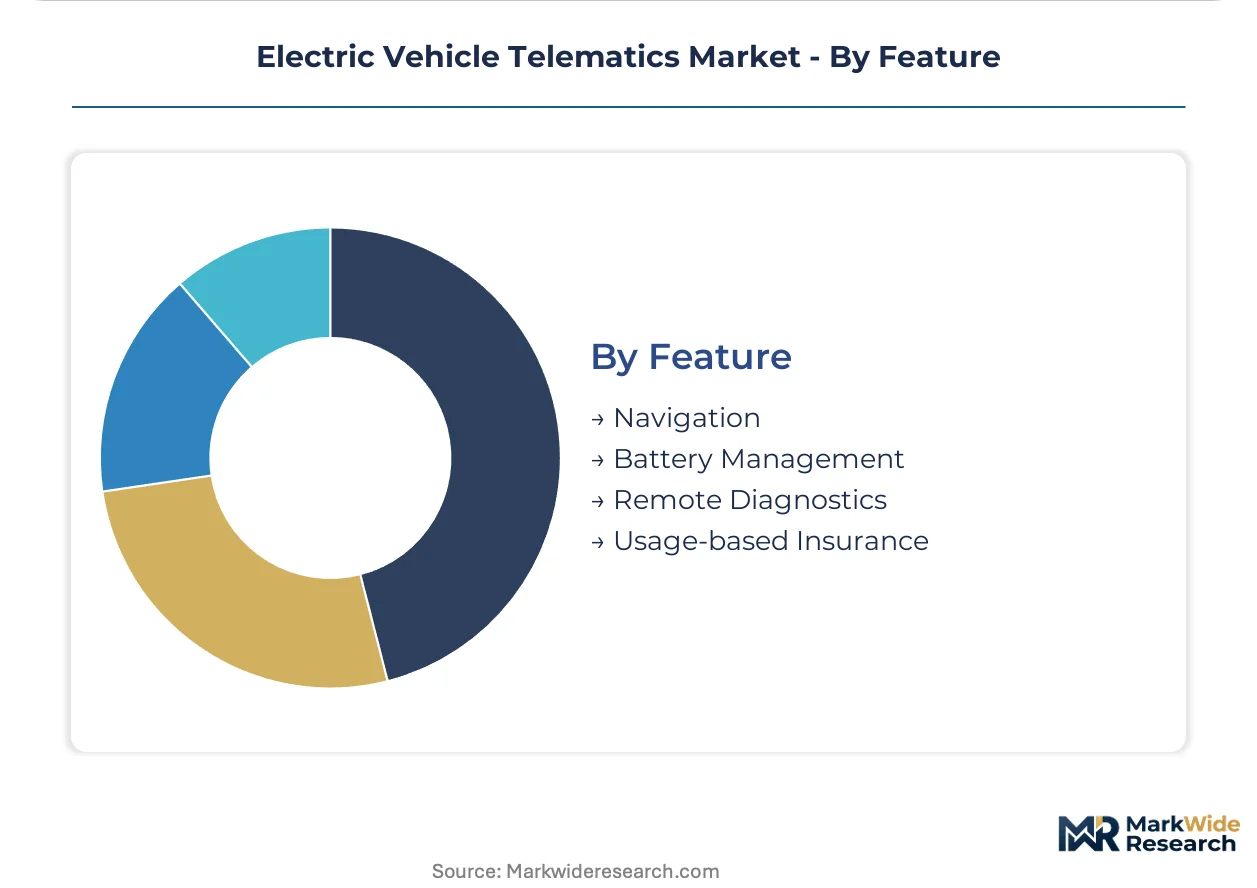
- Battery Management:State-of-charge monitoring, thermal runaway detection, and degradation forecasting anchor platform value propositions. EMA guidelines standardizing health reporting formats create residual-value underwriting opportunities for second-life energy storage applications.
- Usage-based Insurance:Pay-per-mile and behavior-adjusted premium models bypass traditional fleet management intermediaries. Direct partnerships between telematics providers and commercial insurers capture data monetization in North American trucking corridors.
- Navigation:Route optimization with charging station integration.
- Remote Diagnostics:Over-the-air fault code reading and predictive maintenance scheduling.
Deployment scale favors Navigation; Usage-based Insurance climbs the fastest as regulatory frameworks mature for data-driven underwriting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European telematics engineering density through Continental AG and Robert Bosch GmbH headquarters clustering. The city's embedded systems talent pool feeds directly into OEM procurement pipelines for battery management platforms.
United States
Long-haul fleet operators in Texas and the Midwest consolidate procurement around cloud-based analytics platforms with EPA OBD-II compliance verification. The EPA mandates real-time emissions data transparency for commercial vehicle certification. Detroit's automotive corridor drives embedded connectivity integration into domestic EV production lines.
Germany
Commercial fleet managers unbundle telematics from OEM subscriptions through competitive tender processes in Bavaria and North Rhine-Westphalia. The EU Green Deal's carbon tracking requirements reposition sourcing criteria toward verified emissions reporting. Munich's technology cluster concentrates battery management system development for European OEM supply relationships.
China
Domestic EV manufacturers scale connected vehicle platforms under MIIT's GB standards for data security and localization. The MIIT imposes strict domestic data storage requirements that shape product architecture for captive suppliers. Shenzhen's electronics corridor concentrates cellular module and CAN controller manufacturing capacity.
Japan
Automotive suppliers integrate edge computing architectures for battery thermal runaway detection in Kansai and Chubu manufacturing belts. METI guidelines shape connected vehicle data governance frameworks for export markets. Nagoya's industrial corridor hosts precision sensor development for next-generation telematics hardware.
South Korea
Battery manufacturers and semiconductor fabricators in the Seoul Capital Area co-develop telematics platforms for integrated cell monitoring. The country's national automotive regulator enforces cybersecurity certification for connected vehicle systems. Busan-Ulsan's logistics hub drives commercial fleet deployment of predictive maintenance analytics.
Electric Vehicle Telematics Market Vendor Landscape
The competitive structure tilts toward diversified automotive suppliers with captive OEM relationships. Hardware-software integration capabilities separate tier-one systems integrators from component specialists. Two archetypes dominate: embedded platform providers with factory-fit contracts, and cloud-native fleet analytics vendors winning post-sale procurement. Consolidation pressure elevates M&A activity around connectivity module manufacturers and strategic partnerships between telematics providers and commercial insurers.
Within the diversified automotive supplier tier, Continental AG and Robert Bosch GmbH anchor European OEM supply relationships through integrated hardware-software stacks. Geotab Inc. occupies a position exemplifying the cloud-native fleet analytics archetype, serving commercial operators through multi-tenant subscription models. These three companies represent the structural bifurcation between factory-embedded and aftermarket procurement channels reshaping vendor selection timelines.
| Leading Market Players |
|---|
| TomTom International |
| Robert Bosch GmbH |
| Continental AG |
| Geotab Inc. |
| Trimble, Inc. |
| Aptiv PLC |
| Harman International |
| NXP Semiconductors |
| Denso Corporation |
| Others |
Supply Flow & Price Mechanics
Lithium carbonate price indices cascading from Chilean and Australian extraction operations compress hardware margins for cellular modem and CAN bus controller suppliers, forcing three-tier pricing stratification across premium certified, standard compliant, and economy unbranded tiers in fleet procurement channels.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for predictive battery analytics platforms, with premium tiers commanding multiples over standard connectivity subscriptions due to ISO 26262 functional safety certification and real-time thermal runaway liability coverage. Price differentiation separates OEM-embedded factory fits from aftermarket retrofit installations, with the latter facing acute cost compression from semiconductor allocation constraints in East Asian foundries. Fleet operators in North American long-haul trucking exhibit highest price sensitivity, while autonomous shuttle pilots in controlled campus environments absorb premium edge-computing hardware costs without volume negotiation.
Supply Chain Analysis
Ocean freight rate volatility from Shanghai to Rotterdam strains landed costs for cellular module assemblies, with containerized electronics facing extended transit uncertainty. Hardware production concentrates in China, South Korea, and Germany, drawing from concentrated semiconductor wafer output in Taiwan and memory fabrication in South Korea. Single-source vulnerability in 5G NR chipset supply creates architectural risk for vendors locked into Qualcomm or MediaTek reference designs. Distribution runs through captive OEM supply agreements for factory-embedded platforms, while aftermarket channels fragment across specialized fleet management integrators and direct-to-operator SaaS subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk algorithm classification erects compliance moats around battery management system vendors with documented training data provenance and model drift monitoring capabilities, elevating cost-of-entry for undercapitalized entrants.
For Market Incumbents: Anticipate margin compression from cloud-native fleet analytics vendors unbundling telematics procurement from OEM subscriptions by accelerating vertical integration into edge computing hardware with onboard GPU acceleration. Prioritize certification investment for EU AI Act conformity assessments ahead of enforcement timelines to defend installed base against compliant challengers.
For New Entrants and Emerging Players: The mid-market pricing gap between Continental AG's integrated stacks and economy retrofit adapters creates white-space opportunity for standardized battery health reporting platforms serving secondary-market valuation and second-life energy storage applications. Target German commercial fleet operators through competitive tender processes unbundled from captive OEM relationships, leveraging API interoperability as the primary go-to-market wedge.
For Investors and Strategic Acquirers: Distressed-cycle entries favor connectivity module manufacturers with captive foundry relationships in South Korea and Taiwan during semiconductor allocation crunches. Long-term viability centers on 5G NR and edge-AI convergence plays with automotive cybersecurity certification; monitor EPA OBD-II mandate expansion timelines as inflection signal for compliance-tech valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Hardware Integration | Millisecond-latency battery thermal detection enables autonomous shuttle deployment without persistent cellular dependency. |
| EU AI Act Compliance Certification | Documented training data provenance and explainability modules secure European OEM supply relationships against regulatory exclusion. |
| 5G NR Module Supply Agreement | Locked allocation with MediaTek or Qualcomm insulates production schedules from foundry capacity crunches in Taiwan. |
| Usage-Based Insurance Partnership | Direct data monetization with commercial underwriters bypasses fleet management intermediaries in North American trucking corridors. |
| Secondary Battery Valuation Platform | EMA-standardized health reporting formats enable residual-value underwriting for second-life energy storage applications. |
Methodological Framework
Multi-period observation of cellular module shipment volumes, battery management system installation rates, and fleet operator procurement patterns anchored the trend analysis, supplemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, commercial fleet operations directors, and automotive cybersecurity certification specialists. Secondary validation drew from EPA OBD-II regulatory filings, MIIT GB standard publications, EMA battery reporting guidelines, vehicle production databases, and SEC disclosures from diversified automotive suppliers. Bottom-up unit economics triangulated against top-down market sizing across deployment architectures and end-user categories.
The input-output matrix framed volume and value projections across the analysis window, modeling segmentation dimensions including hardware-software-deployment configurations, fleet size tiers, propulsion architectures, and regional regulatory clusters. CAGRs derived from fitted growth curves applied to installed base penetration rates, with forecast inputs incorporating cellular module cost trajectories, edge computing adoption curves in autonomous applications, and emissions compliance mandate expansion schedules.
Inputs from regulatory agency publications and supplier financial disclosures were available through the study window; gaps in real-time fleet operator procurement data introduce uncertainty bands around aftermarket adoption assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
North America Electronic Toll Collection (ETC) Market
Telematics and Infotainment
Global 5G in Automotives Market
Telematics and Infotainment
Roadside Assistance Software Market
Telematics and Infotainment
Global Carpool-As-A-Service Market
Telematics and Infotainment
India Fleet Management Software Market
Telematics and Infotainment
APAC Telematics Market
Telematics and Infotainment
Europe Automotive Telematics Market
Telematics and Infotainment
Asia Pacific Automotive Infotainment Systems Market
Telematics and Infotainment
Europe Dashboard Camera Market
Telematics and Infotainment
V2X Communication Module Market
Telematics and Infotainment
Global Intelligent Transportation System (ITS) Market
Telematics and Infotainment
Mobile Resource Management (MRM) Market
Telematics and Infotainment
North America Dashboard Camera Market
Telematics and Infotainment
Automotive Embedded Telematics Market
Telematics and Infotainment
In Vehicle Infotainment Market
Telematics and Infotainment
Intelligent Transport Systems (ITS) Market