
 Europe Automotive Navigation System Market | 2026-2036
Europe Automotive Navigation System Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Navigation System Market Foresight
Software-defined navigation feature subscriptions is broadening what European automakers monetize beyond hardware sales. Continental AG leverages its embedded systems expertise to anchor factory-installed contracts with German OEMs. Garmin differentiates through specialized aftermarket units for commercial vehicle operators across Nordic markets.
An automotive navigation system integrates multi-constellation GNSS receivers, digital map databases, and real-time traffic processing algorithms to compute optimal vehicle routing. These systems process sensor fusion inputs at sub-meter accuracy to guide drivers through complex road networks. Embedded Systems dominate European OEM supply chains due to tighter vehicle integration requirements, while Cloud Solutions represent the fastest-expanding segment as over-the-air map updates replace physical media. Smartphone Integration occupies a mature position among budget passenger vehicle tiers where factory-installed options remain limited.
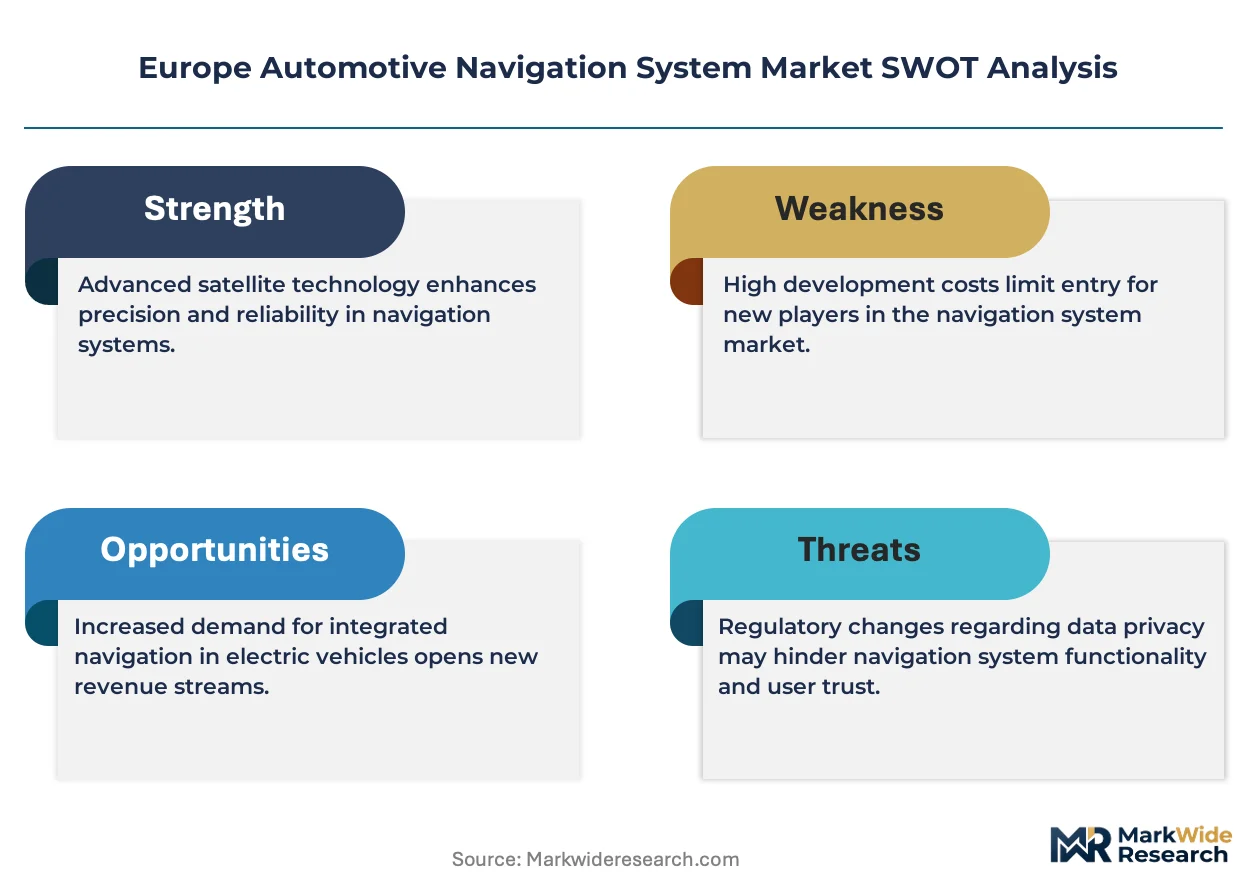
EU GDPR mandates constrain how navigation providers collect and retain location telemetry, forcing architecture redesigns for cloud-connected platforms. ECE R10 electromagnetic compatibility standards and CE marking requirements shape hardware certification pathways for devices sold across EU member states. The EU AI Act introduces algorithmic transparency obligations for AI-assisted routing features. Stakeholders must evaluate whether to build compliant data infrastructures in-house or outsource to regionally certified platform operators.
Market Dynamics
GDPR and the EU AI Act are forcing European navigation providers to re-architect cloud data pipelines, converting compliance from cost center to competitive differentiator as automakers select suppliers with pre-certified governance stacks.
Growth Catalysts
- Fleet electrification mandates:Commercial vehicle operators across Germany and France require dynamic routing that accounts for charging infrastructure, pulling real-time navigation into fleet management contracts.
- Multi-constellation GNSS deployment:Galileo signal authentication is hardening against spoofing, enabling liability-sensitive applications like autonomous lane-keeping that demand certified positioning.
- ECE R10 electromagnetic compatibility:Harmonized certification pathways reduce retesting costs for suppliers selling across EU member states, accelerating hardware refresh cycles.
Market Restraints
- Semiconductor supply concentration:Advanced GNSS receiver fabrication concentrates in East Asian foundries, exposing European module assemblers to allocation risk during demand spikes.
- GDPR data localization costs:Telemetry storage restrictions force redundant cloud infrastructure across multiple EU jurisdictions, inflating operational overhead versus single-region architectures.
- Smartphone navigation substitution:Free consumer-grade routing applications cap willingness-to-pay for entry-level embedded systems in budget vehicle segments.
Strategic Opportunities
- Nordic commercial vehicle aftermarket:Long-haul trucking corridors across Sweden and Finland lack factory-installed coverage, creating white space for specialized fleet navigation units.
- AI-assisted predictive routing:Machine learning models processing historical congestion patterns are unifying navigation with energy management systems in electric vehicle platforms.
- CE marking digitalization:Streamlined conformity assessment pathways for software-defined features enable faster feature rollouts through over-the-air updates.
Industry Challenges
- Embedded-to-cloud integration complexity:Legacy vehicle electrical architectures constrain bandwidth for real-time map streaming, forcing expensive gateway redesigns.
- Algorithmic transparency documentation:EU AI Act requirements for explainable routing decisions demand new technical documentation workflows that extend development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Navigation System Market |
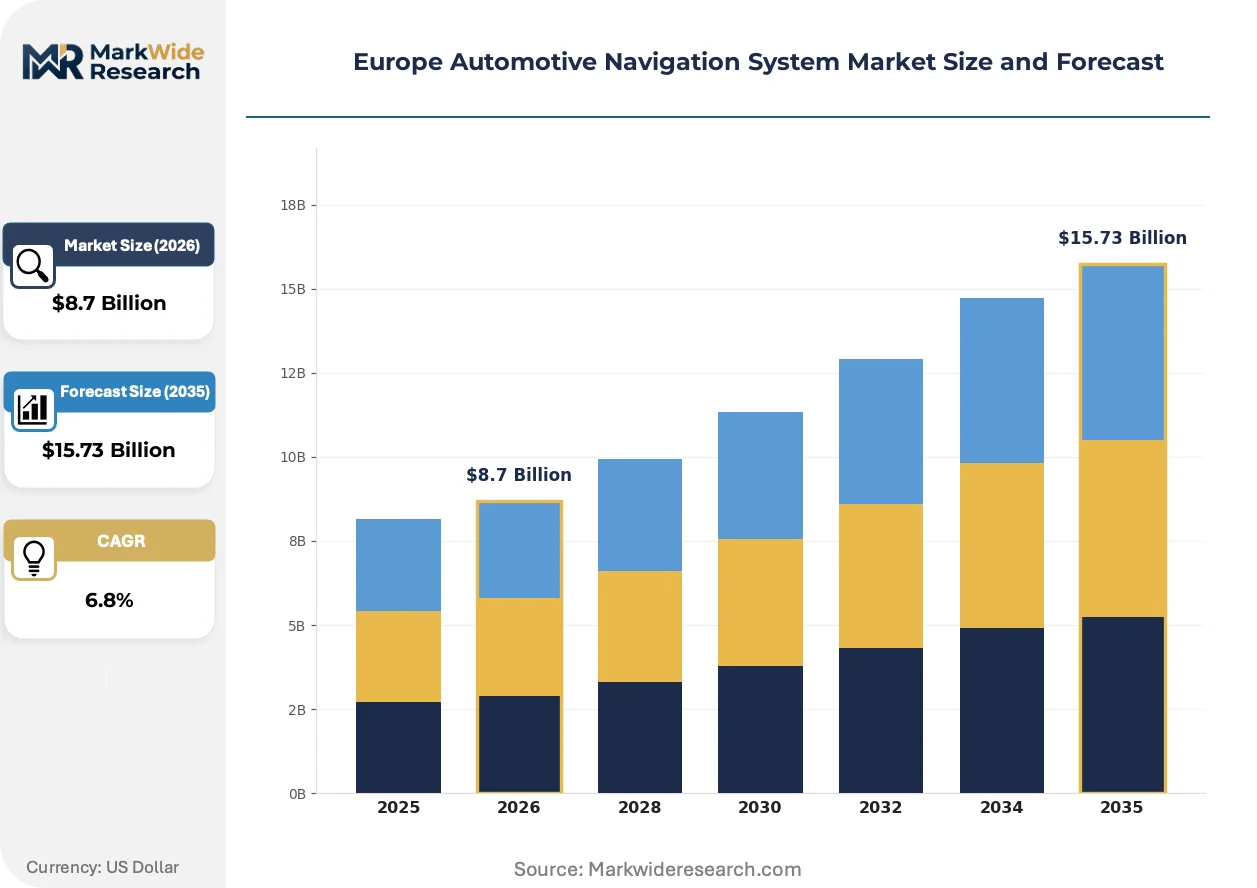
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Devices, Embedded Systems, Smartphone Integration, Cloud Solutions Technology: GPS, GLONASS, Galileo, GNSS End User: Passenger Vehicles, Commercial Vehicles, Fleet Operators, Ride-sharing Services Installation: Factory-installed, Aftermarket, Integrated Systems, Independent Units |
| Companies Covered | Denso Corporation, Mitsubishi Electric Corporation, Continental AG, Pioneer, Clarion, Alpine Electronics, Garmin, Panasonic Corporation, Aisin Aw Co.Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Navigation System Market Shifts & Advancements
Navigation systems are pivoting from static map repositories to continuously updated software platforms, with data governance and edge computing architectures determining supplier selection criteria.
Sensor fusion is unifying camera, radar, and GNSS inputs into single positioning pipelines that enable lane-level accuracy without high-cost RTK infrastructure. German premium OEMs are adopting these stacks for highway pilot functions. The convergence is compressing hardware bill-of-materials while raising software certification burdens.
GDPR's data minimization principles are reshaping how cloud-connected platforms retain trip history, forcing anonymization layers that degrade personalization features. Navigation providers serving French and Italian markets are responding with edge-processing architectures that limit telemetry transmission. The regulatory friction is advantaging suppliers with pre-built privacy-by-design stacks.
Fleet procurement teams are consolidating vendor relationships around platforms that combine navigation with telematics and compliance reporting. Long-haul operators across the Benelux corridor are displacing standalone routing contracts with integrated mobility subscriptions. The bundling is compressing supplier margins while locking in multi-year service agreements.
Europe Automotive Navigation System Market Segmentation
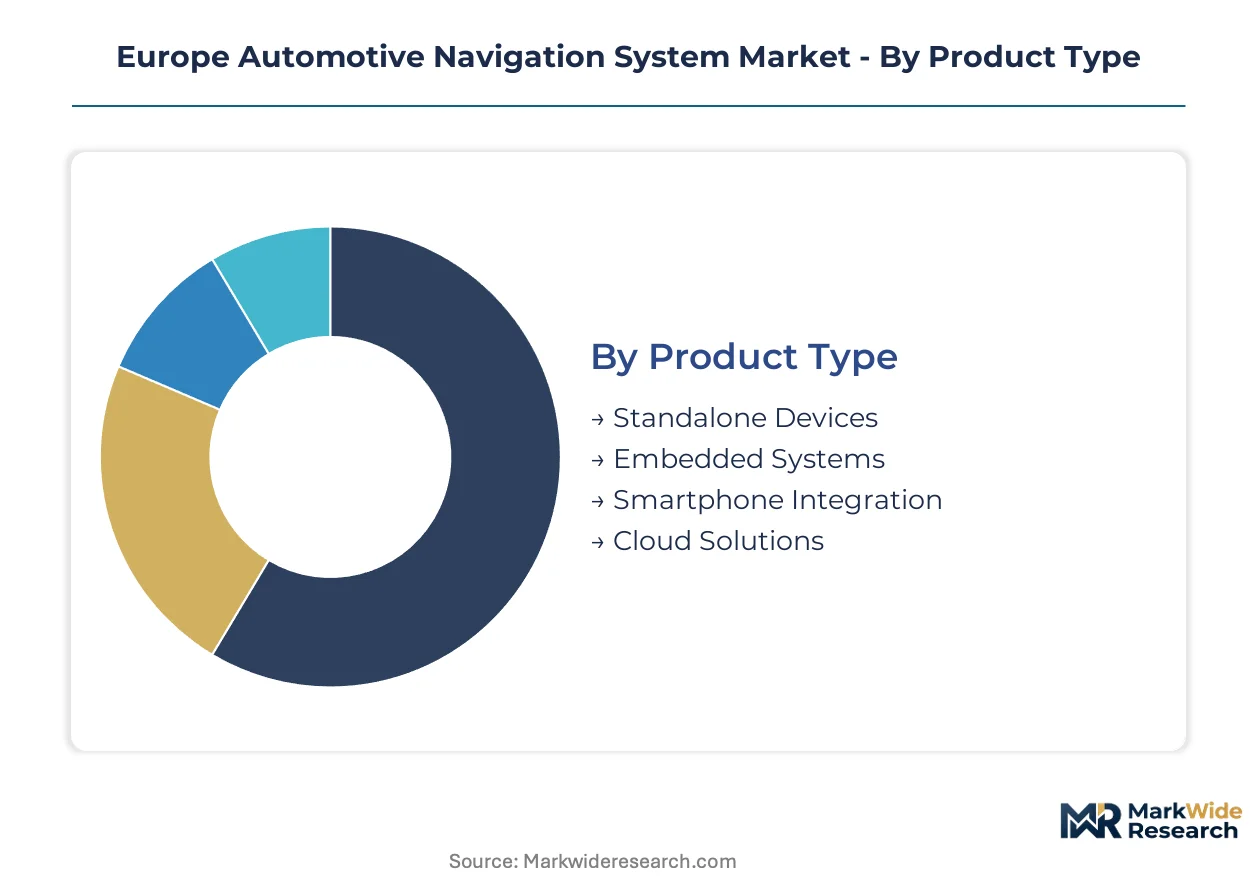
Segmentation in the European automotive navigation market reveals how supplier capabilities align with diverging customer requirements across OEM factory contracts and aftermarket channels. Understanding these divides exposes where procurement power concentrates and which technology stacks command premium positioning.
Product Type:
Supply concentration among German tier-1 suppliers favors embedded architectures that lock in multi-year OEM contracts through vehicle integration complexity.
- Embedded Systems:Tight integration with vehicle electrical architectures enables real-time sensor fusion and over-the-air map updates. German premium OEMs anchor demand here, driven by ECE R10 certification requirements that favor pre-certified supplier relationships.
- Cloud Solutions:Software-defined platforms stream navigation data through cellular modems, eliminating local storage constraints. Fleet operators across France and the Netherlands are pulling adoption fastest as they consolidate telematics and routing into single subscriptions.
- Standalone Devices:Portable units with self-contained GNSS receivers and display screens serve budget-conscious consumers in Eastern European markets where factory-installed penetration remains limited.
- Smartphone Integration:Mirroring protocols leverage driver handsets for navigation, occupying entry-level vehicle tiers where hardware cost minimization dominates procurement decisions.
Embedded Systems absorb the bulk of installed capacity; Cloud Solutions are expanding most quickly.
Technology:
Cost tier separation follows signal authentication capabilities, with certified positioning commanding hardware premiums in liability-sensitive applications.
- GNSS:Multi-constellation receivers processing GPS, GLONASS, and Galileo signals simultaneously deliver sub-meter accuracy through sensor fusion. German highway pilot programs are concentrating demand here, compelled by EU AI Act liability frameworks that require traceable positioning confidence.
- Galileo:Europe's indigenous constellation offers authenticated signals resistant to spoofing, enabling certified applications where GNSS vulnerability creates legal exposure. Italian and Spanish fleet operators are adopting fastest where cross-border cargo security mandates apply.
- GPS:The legacy US constellation remains baseline for cost-optimized receivers in budget vehicle segments across Poland and Romania.
- GLONASS:Russian constellation signals augment availability in urban canyon environments, though geopolitical friction is compressing new design-ins across EU supply chains.
GNSS multi-constellation stacks dominate current procurement volumes; Galileo authentication is climbing the fastest as regulatory liability frameworks harden.
End User:
Customer type determines whether procurement flows through centralized fleet contracts or fragmented retail channels, reshaping margin structures.
- Fleet Operators:Centralized procurement of integrated navigation-telematics platforms across thousands of vehicles. Long-haul operators along the Benelux-Germany corridor are driving specifications, compelled by electrification mandates requiring dynamic charging-aware routing.
- Commercial Vehicles:Specialized units with truck-specific routing algorithms that account for vehicle dimensions and hazardous cargo restrictions. Nordic markets concentrate demand where factory-installed coverage gaps persist.
- Passenger Vehicles:Individual ownership models dominate volume but fragment across premium embedded and economy smartphone-mirrored tiers.
- Ride-sharing Services:Platform-mediated driver supply creates demand for low-friction navigation that minimizes driver cognitive load during high-frequency trip execution.
Fleet Operators concentrate procurement volume; Commercial Vehicles are gaining share fastest as electrification mandates penetrate heavy-duty segments.
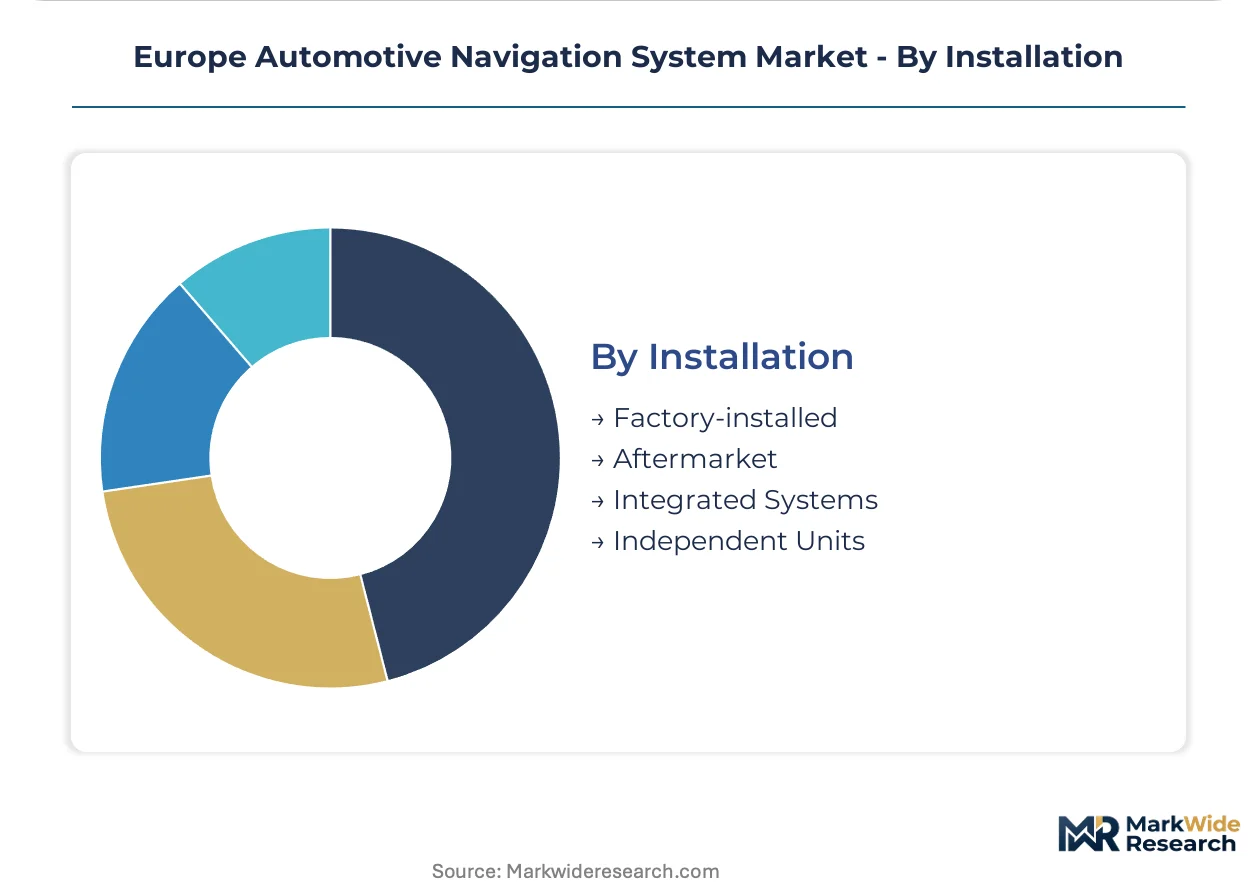
Installation:
Maturity differentials separate established factory channels from aftermarket opportunities where vehicle parc coverage creates service revenue pools.
- Factory-installed:OEM-controlled integration from vehicle design phase enables optimized antenna placement and electrical architecture co-design. German and French OEMs anchor supply here, locking in tier-1 suppliers through platform-sharing agreements.
- Aftermarket:Post-purchase installation addresses vehicle parc gaps where embedded coverage never penetrated. Nordic commercial vehicle corridors concentrate opportunity, particularly for specialized fleet units absent from factory option lists.
- Integrated Systems:Navigation bundled with infotainment and instrument cluster displays through unified domain controllers.
- Independent Units:Standalone hardware installations preserving legacy electrical architectures in older vehicle fleets.
Factory-installed channels dominate new vehicle uptake; Aftermarket is expanding fastest where electrification retrofits and fleet refresh cycles create hardware replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany produces the majority of embedded navigation hardware for European OEMs, while consumption spreads across fleet operators in France, the United Kingdom, and the Nordic corridor. This production-consumption divide shapes supplier location decisions and regulatory compliance investments.
Germany
Premium OEMs in Bavaria and Baden-Württemberg anchor embedded system demand through factory-installed contracts with tier-1 suppliers. The KBA enforces ECE R10 electromagnetic compatibility certification, accelerating hardware refresh cycles. Stuttgart's automotive cluster concentrates sensor fusion R&D for highway pilot functions.
France
Commercial fleet operators in Île-de-France require dynamic routing platforms that integrate charging infrastructure data for electrification mandates. The CNIL enforces GDPR data minimization principles on cloud-connected navigation services. Lyon hosts specialized telematics providers serving cross-border logistics corridors.
United Kingdom
London-based ride-sharing platforms drive demand for low-friction navigation that minimizes driver cognitive load during high-frequency trip execution. The Information Commissioner's Office mandates algorithmic transparency for AI-assisted routing under the EU AI Act framework. The Midlands manufacturing belt assembles aftermarket units for Eastern European export.
Sweden
Long-haul trucking fleets across the Stockholm-Gothenburg corridor lack factory-installed navigation coverage, creating aftermarket opportunity for specialized commercial vehicle units. The Swedish Transport Agency enforces hazardous cargo routing compliance that requires certified positioning systems. Scania's Södertälje headquarters influences regional supplier specifications for heavy-duty applications.
Italy
Cross-border cargo operators in Lombardy and Emilia-Romagna adopt Galileo-authenticated signals for liability-sensitive fleet applications. The Italian Data Protection Authority enforces GDPR localization requirements on telemetry storage. Turin's automotive cluster supports aftermarket integration services for aging commercial vehicle parc.
Europe Automotive Navigation System Market Competitive Landscape
Top-tier vendors anchor factory-installed OEM supply chains, while mid-tier specialists and aftermarket distributors occupy fragmented positions below. The vendor base stratifies across embedded system integrators, cloud platform operators, and portable device manufacturers. Three archetypes dominate: German tier-1 automotive suppliers, Japanese electronics conglomerates with navigation divisions, and specialized fleet-focused aftermarket providers. Competitive moves concentrate on strategic partnerships with OEM platform teams and geographic expansion into Nordic commercial vehicle corridors.
Among German-based automotive suppliers, Continental AG anchors the embedded systems tier through factory-installed contracts with domestic OEMs. Garmin represents the specialized aftermarket archetype, occupying position in Nordic commercial vehicle markets where factory coverage gaps persist. Japanese electronics conglomerates including Denso Corporation and Panasonic Corporation exemplify diversified technology portfolios that span navigation hardware across multiple automotive programs. These three company types illustrate how supplier capabilities align with diverging procurement channels from premium OEM integration to fleet operator direct purchasing.
| Leading Market Players |
|---|
| Denso Corporation |
| Mitsubishi Electric Corporation |
| Continental AG |
| Pioneer |
| Clarion |
| Alpine Electronics |
| Garmin |
| Panasonic Corporation |
| Aisin Aw Co.Ltd |
| Others |
Supply & Pricing Matrix
Multi-constellation GNSS receiver migration to authenticated Galileo signals is compressing hardware bill-of-materials while concentrating premium pricing power among certified suppliers. This technology shift simultaneously reduces silicon costs and elevates compliance investment barriers that reshape supplier economics across German and French OEM channels.
Pricing Analysis
Margin tightening in embedded systems reflects ECE R10 certification costs that tier-1 suppliers amortize across multi-year OEM contracts. Three-tier pricing structure across premium, standard, and economy levels separates factory-installed highway pilot stacks from aftermarket portable units and smartphone-mirrored tiers. Price differentiation hinges on Galileo authentication grade and sensor fusion integration depth. Fleet operators in the Benelux corridor show lowest price sensitivity due to electrification mandate compliance requirements, while Eastern European budget vehicle buyers face smartphone substitution pressure.
Supply Chain Analysis
Refurbishment flows for legacy embedded units extend service revenue for aftermarket distributors addressing aging commercial vehicle parc in Nordic corridors. Advanced GNSS receiver fabrication concentrates in Taiwan, South Korea, and Japan, drawing from specialized semiconductor foundries and MEMS sensor suppliers. Supply chain risk centers on single-source vulnerability for authenticated positioning chipsets subject to allocation constraints. Distribution runs through tier-1 automotive supplier networks into OEM assembly plants, with direct fleet procurement bypassing traditional dealer channels fastest in France and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GDPR data localization mandates and EU AI Act compliance requirements are forcing consolidation as smaller cloud platform operators lack capital for redundant EU infrastructure. Weaker players without pre-certified governance stacks face exit pressure from OEM procurement shortlists.
For Market Incumbents: Anchor factory-installed relationships through exclusive sensor fusion co-development with Stuttgart and Munich OEM platform teams. Deepen backward integration into multi-constellation receiver design to capture silicon margin compression. Defend against cloud-native entrants by accelerating over-the-air map update roadmaps that leverage embedded antenna placement advantages.
For New Entrants and Emerging Players: The EU AI Act in Germany and France opens a window for specialized compliance-as-a-service platforms serving mid-tier suppliers lacking in-house governance expertise. Target Nordic commercial vehicle aftermarket corridors where factory-installed coverage gaps persist for long-haul electrification fleets. Lead with edge-processing architectures that limit telemetry transmission and satisfy CNIL data minimization mandates.
For Investors and Strategic Acquirers: Re-rating potential sits with tier-2 embedded system specialists possessing ECE R10 pre-certification and dormant OEM relationships given accelerating hardware refresh cycles. Long-term viability favors suppliers with Galileo authentication IP and regional cloud infrastructure already deployed. Monitor KBA enforcement patterns for electromagnetic compatibility certification as inflection indicator for supplier consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Constellation GNSS Integration | Galileo authentication hardens positioning liability for German highway pilot deployments. |
| Edge-Processing Architecture Deployment | GDPR-compliant telemetry minimization opens French and Italian fleet procurement channels. |
| Over-the-Air Map Update Platform | Software-defined revenue streams displace physical media in premium OEM contracts. |
| Charging Infrastructure Data Partnership | Dynamic routing integration captures Benelux electrification mandate compliance spending. |
| Aftermarket Fleet Unit Specialization | Nordic commercial vehicle corridors lack factory coverage for heavy-duty applications. |
Research Methodology
Document review covered EU regulatory filings, ECE R10 certification databases, and OEM platform engineering disclosures, complemented by interviews with tier-1 supplier procurement directors, fleet telematics managers, and embedded systems engineers. Secondary validation drew from KBA type-approval records, CNIL enforcement actions, and Galileo service deployment reports. Bottom-up unit economics triangulated against top-down OEM production planning data.
Cross-referencing historical adoption curves with expert panel input shaped the analytical framework across vehicle class, propulsion architecture, and installation channel dimensions throughout the forecast period. CAGRs derived from segment-level demand elasticity modeling and technology substitution rates. Industry-specific inputs included GNSS receiver cost curves and cloud infrastructure deployment timelines.
The model assumes a particular technology adoption path; alternative pathways for sensor fusion consolidation would alter the outlook if camera-radar integration leapfrogs standalone positioning stacks. Forecasts reflect documented assumptions about regulatory enforcement intensity and semiconductor allocation stability. Practitioners should monitor KBA certification queue lengths and Galileo commercial service activation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Vehicle to Vehicle (V2V) Communication Market
Telematics and Infotainment
India Fleet Management Software Market
Telematics and Infotainment
Global in Dash Navigation System Market
Telematics and Infotainment
Europe Automotive Infotainment Systems Market
Telematics and Infotainment
Automotive Navigation Solutions Market
Telematics and Infotainment
Global Automotive Infotainment System Market
Telematics and Infotainment
Global Car GPS Navigation System Market
Telematics and Infotainment
Telematics in Automotive Market
Telematics and Infotainment
Asia Pacific Automotive Navigation System Market
Telematics and Infotainment
In Vehicle Infotainment Market
Telematics and Infotainment
Automotive Human Machine Interface (HMI) Market
Telematics and Infotainment
Mobility on Demand (Mod) Market
Telematics and Infotainment
In Car Infotainment System Market
Telematics and Infotainment
Europe Automotive Telematics Market
Telematics and Infotainment
Vehicle Digital Cockpit Market
Telematics and Infotainment
Asia-Pacific Automotive Telematics Market