
 Connected Car Market | 2026-2036
Connected Car Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Car Market Intelligence
Subscription-based vehicle data monetization is narrowing the competitive field to capitalized technology platforms and established OEMs with captive customer bases. Tesla Inc. leverages over-the-air software architecture to sustain recurring revenue streams independent of hardware cycles. Continental AG anchors its position through embedded systems integration that spans telematics modules to edge computing controllers. Qualcomm Technologies competes by supplying cellular connectivity chipsets that power vehicle-to-everything communication stacks.
A connected car integrates onboard sensors, wireless communication modules, and cloud-based software platforms to enable real-time data exchange between vehicles, infrastructure, and external services, typically operating through 4G/5G cellular, dedicated short-range communication, or satellite links with latency requirements under 100 milliseconds for safety-critical applications. The primary commercial purpose is to generate actionable intelligence for predictive maintenance, autonomous navigation, and usage-based insurance while creating recurring service revenue beyond the initial vehicle sale. Embedded systems dominate the integration level segment due to their direct hardware coupling and guaranteed performance for advanced driver-assistance functions. Telematics leads the product type category as fleet operators and insurers mandate location tracking, driver behavior scoring, and remote diagnostics. Vehicle-to-everything represents the fastest-expanding product category as municipalities and highway authorities deploy roadside units requiring interoperable communication standards.
The National Highway Traffic Safety Administration in the United States enforces crashworthiness standards that increasingly incorporate connected safety warnings, while the European Union's Cyber Resilience Act mandates software update transparency across the vehicle lifecycle. The United Nations Economic Commission for Europe WP.29 regulation establishes binding cybersecurity and software management requirements that determine market access for vehicles sold across signatory countries. Stakeholders must monitor how divergent data localization rules between jurisdictions fragment cloud architecture strategies and compliance costs.
Market Dynamics
The connected car market is undergoing fundamental restructuring as embedded 5G architectures replace aftermarket telematics hardware, forcing tier-one suppliers to abandon module-only business models in favor of integrated software-hardware stacks that lock in multi-year OEM contracts.
Growth Catalysts
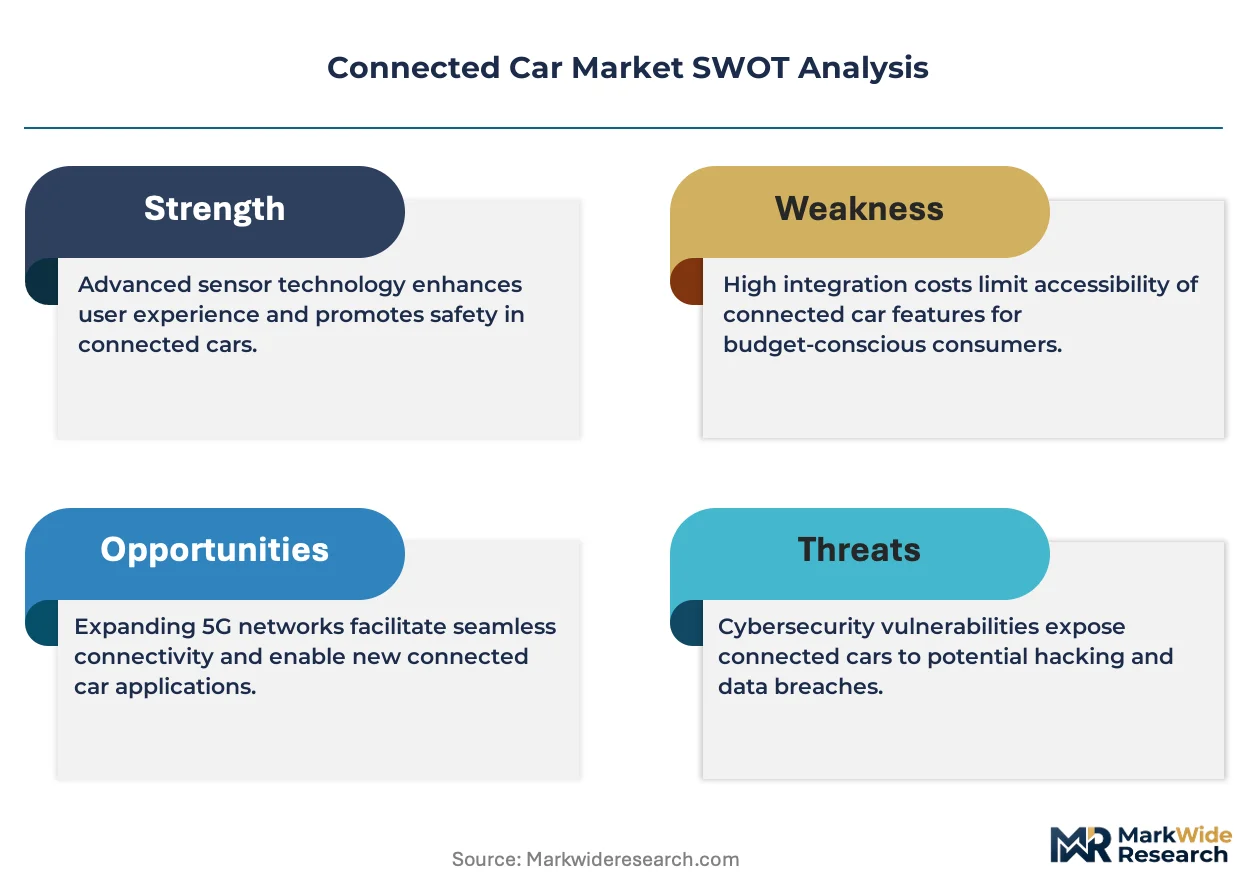
- UNECE WP.29 cybersecurity mandates:Binding software update and intrusion detection requirements across signatory markets are accelerating hardware refresh cycles as OEMs retrofit existing fleets to maintain type approval.
- Fleet telematics adoption:Commercial vehicle operators in Germany and the United States are mandating real-time fuel consumption monitoring and predictive maintenance alerts to reduce total cost of ownership.
- Edge computing integration:Onboard processing units capable of sub-50-millisecond latency are enabling autonomous emergency braking and cooperative adaptive cruise control without cloud dependency.
Market Restraints
- Semiconductor supply concentration:Advanced cellular modems and automotive-grade system-on-chips depend on fabrication capacity concentrated in Taiwan and South Korea, creating vulnerability to geopolitical disruption.
- Cellular module cost structure:5G NR chipsets remain priced at multiples of 4G LTE equivalents, compressing margins for mass-market vehicle segments below premium tiers.
- Data localization fragmentation:Divergent sovereignty requirements between China's MIIT, the European Union's GDPR, and United States state-level privacy laws force redundant cloud infrastructure investments.
Strategic Opportunities
- Vehicle-to-infrastructure deployment:United States Department of Transportation grants for roadside unit installation along interstate corridors are creating captive demand for DSRC-C-V2X hybrid communication stacks.
- Usage-based insurance expansion:Telematics data monetization through driver behavior scoring represents underpenetrated revenue in markets where traditional actuarial models still dominate premium calculation.
- Software-defined vehicle architectures:Centralized compute platforms that decouple hardware from application layers enable aftermarket feature activation, extending revenue capture across vehicle lifecycles.
Industry Challenges
- Functional safety certification timelines:ISO 26262 ASIL-D validation for safety-critical connected systems extends development cycles by 18-24 months versus non-automotive electronics.
- Cross-domain integration complexity:Harmonizing infotainment, advanced driver-assistance, and powertrain control networks requires rare systems engineering expertise spanning multiple silicon vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Car Market |
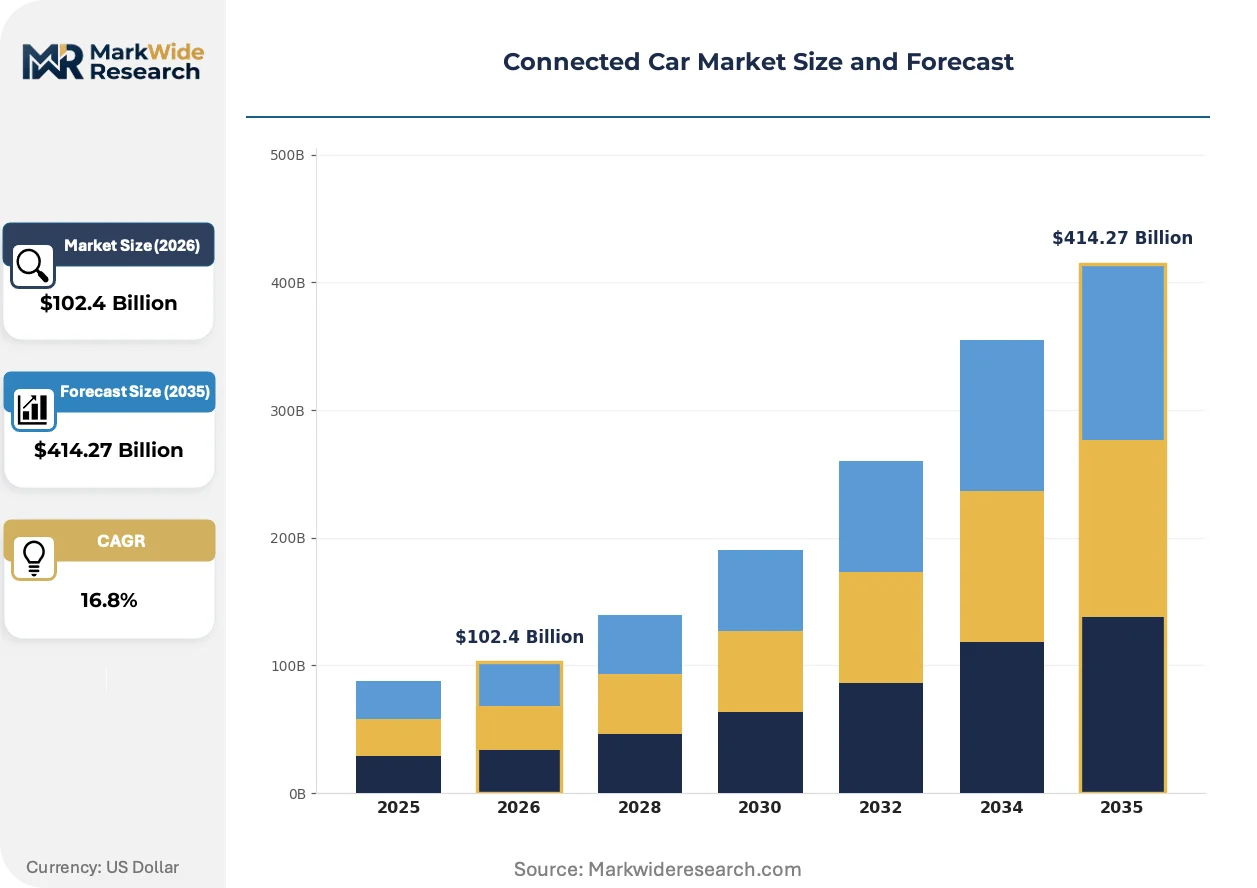
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $414.27 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telematics, Infotainment Systems, Advanced Driver-Assistance Systems, Vehicle-to-Everything End User: OEMs, Fleet Operators, Consumers, Ride-Sharing Services Technology: Cellular Connectivity, Bluetooth, Wi-Fi, Satellite Communication Integration Level: Embedded Systems, Tethered Solutions, Cloud-Based Solutions, Hybrid Systems |
| Companies Covered | Continental AG, Robert Bosch GmbH, Harman International, BMW AG, General Motors, Ford Motor Company, Tesla Inc., Qualcomm Technologies, Audi AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Car Market Strategic Shifts & Innovations
Automotive connectivity is pivoting from hardware-centric installation models toward software-native architectures that enable continuous feature deployment. This shift is compressing traditional tier-one supplier influence while elevating semiconductor and cloud platform vendors.
Automotive-grade cellular modems is migrating from discrete add-on modules toward system-on-chip integration within domain controllers. Continental and Bosch are phasing out standalone telematics control units in favor of consolidated zonal compute nodes. This migration from modular to integrated architectures is collapsing the addressable market for pure-play modem suppliers while expanding silicon content per vehicle for semiconductor foundries.
The European Union's Cyber Resilience Act imposes mandatory vulnerability disclosure and patch transparency obligations across the vehicle lifecycle. OEMs must now maintain software bills of materials and document end-of-life support commitments to retain CE marking. European premium manufacturers are responding by extending security operations center staffing and contracting specialized automotive cybersecurity firms for continuous monitoring.
Fleet procurement patterns are fragmenting from national leasing aggregators toward direct manufacturer relationships with embedded connectivity subscriptions. Logistics operators in the United States are bypassing traditional fleet management companies to negotiate directly with OEMs for factory-installed telematics with API-accessible data streams. This disintermediation is most visible in long-haul trucking, where real-time freight matching platforms require direct vehicle data feeds that legacy intermediaries cannot provide.
Connected Car Market Segmentation
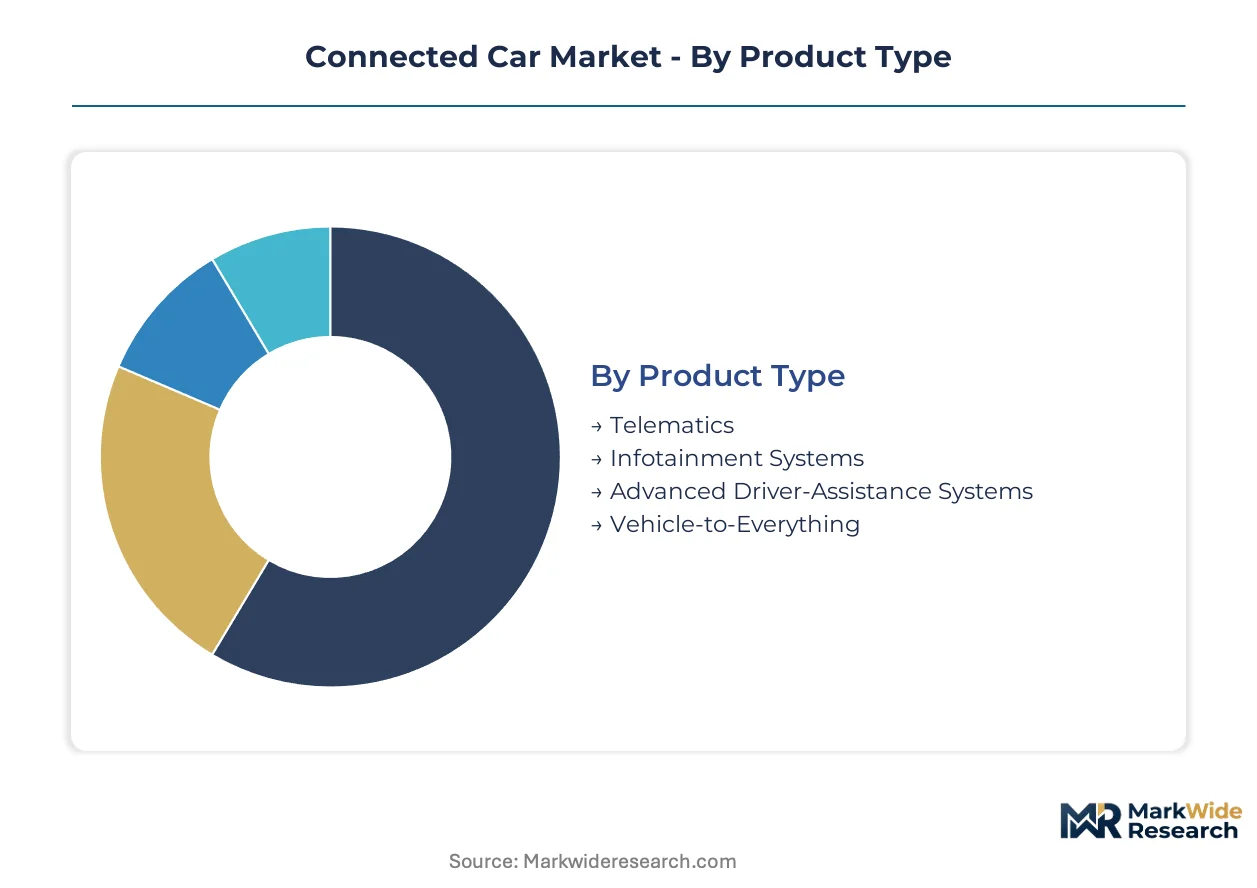
Connected car segmentation reveals how value pools distribute across hardware-software boundaries and customer procurement models. Technology choices determine regulatory compliance paths and recurring revenue potential for stakeholders.
Product Type:
Application focus separates safety-critical systems from convenience features in OEM platform strategies.
- Telematics:Combines GPS positioning, cellular modems, and onboard diagnostics to transmit vehicle health and location data. Fleet operators in Germany and the United States mandate factory-installed units for fuel monitoring and predictive maintenance compliance.
- Vehicle-to-Everything:Enables direct communication between vehicles, infrastructure, and pedestrians through DSRC or C-V2X protocols. United States Department of Transportation grants for interstate roadside units are accelerating deployment timelines.
- Infotainment Systems:Integrates navigation, media streaming, and voice interfaces through centralized touch displays.
- Advanced Driver-Assistance Systems:Processes sensor fusion data for lane keeping, adaptive cruise control, and collision avoidance.
Telematics commands the established base. The steepest expansion runs through Vehicle-to-Everything.
End User:
Customer type dictates contract structures, from multi-year OEM supply agreements to per-ride data licensing.
- Fleet Operators:Procure embedded connectivity platforms with API-accessible data streams for route optimization and driver scoring. Logistics providers in the United States increasingly negotiate direct manufacturer relationships, bypassing traditional fleet management intermediaries.
- OEMs:Integrate connectivity modules during vehicle assembly to enable over-the-air software updates and subscription services. Type approval requirements under UNECE WP.29 mandate standardized cybersecurity architectures.
- Consumers:Access connected features through retail vehicle purchases and aftermarket service subscriptions.
- Ride-Sharing Services:Deploy telematics for real-time vehicle tracking and automated fare calculation.
Fleet operators anchor current volume. The fastest share gains are occurring among ride-sharing services.
Technology:
Connectivity protocol selection determines latency performance, coverage reliability, and hardware cost structures.
- Cellular Connectivity:Dominates through 4G LTE and 5G NR modems enabling cloud-based services and over-the-air updates. 5G NR chipsets remain priced at multiples of 4G equivalents, compressing margins for mass-market vehicle segments.
- Satellite Communication:Provides coverage in remote corridors where cellular infrastructure is absent. Mining and long-haul trucking operators in Australia and Canada specify dual-mode cellular-satellite terminals for uninterrupted fleet visibility.
- Bluetooth:Enables short-range device pairing for smartphone integration and keyless entry.
- Wi-Fi:Supports high-bandwidth in-vehicle hotspot services and local device networking.
Cellular connectivity holds the dominant installed base. Satellite communication is climbing the fastest as coverage gaps persist.
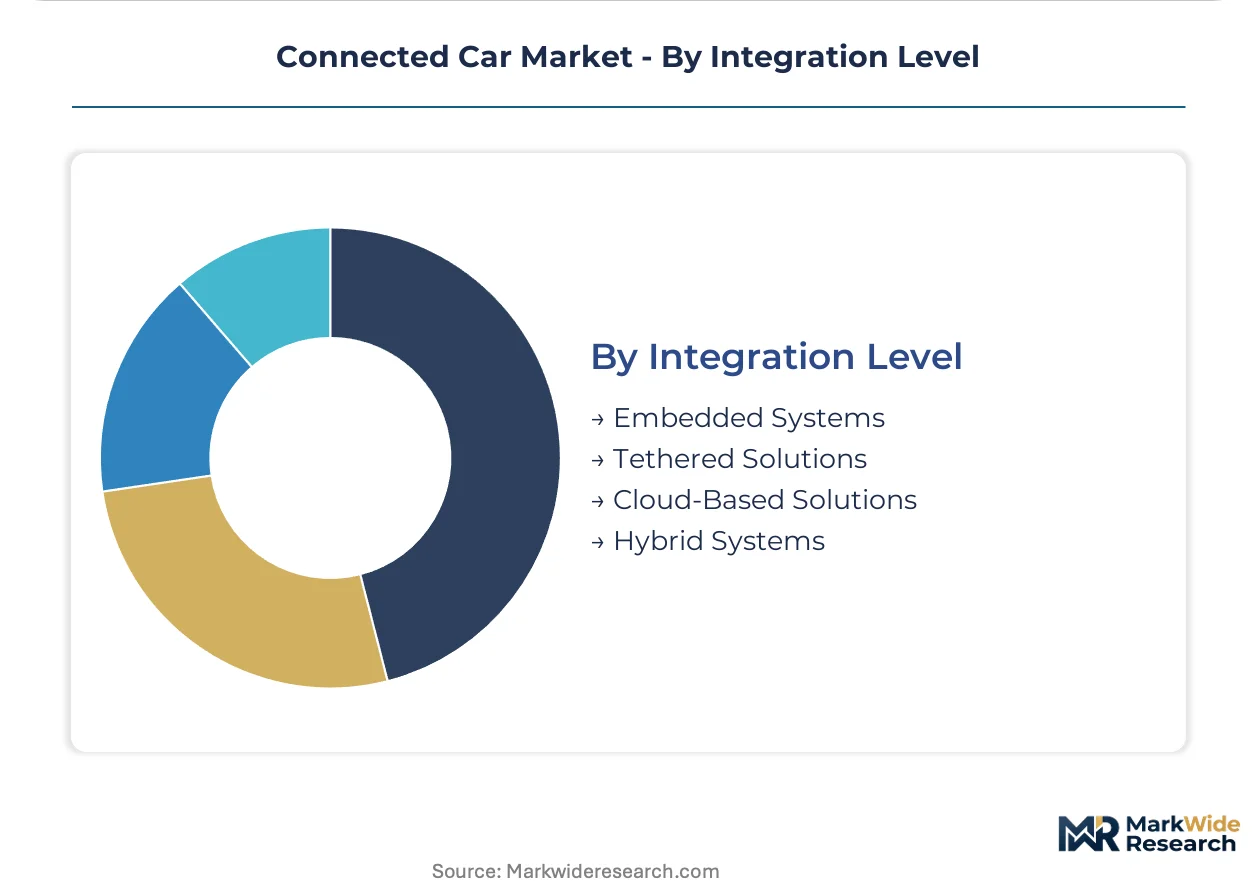
Integration Level:
System architecture depth determines performance guarantees and supplier lock-in duration for OEM programs.
- Embedded Systems:Direct hardware coupling through dedicated control units guarantees deterministic performance for safety-critical functions. Continental AG and Bosch are consolidating standalone telematics modules into zonal compute nodes.
- Hybrid Systems:Combines onboard processing with cloud offloading to balance latency requirements against compute costs. Municipal vehicle-to-infrastructure deployments in the United States favor hybrid architectures for cooperative intersection management.
- Tethered Solutions:Relies on driver smartphone connectivity for navigation and media services.
- Cloud-Based Solutions:Offloads processing entirely to remote data centers, minimizing onboard hardware.
Embedded systems retain the largest footprint. Hybrid systems are gaining share fastest as edge computing requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and premium OEMs concentrate procurement power in Germany, the United States, and China, with regulatory divergence across these jurisdictions fragmenting cloud architecture strategies and compliance investments.
Germany
Domestic OEMs and tier-one suppliers anchor embedded systems demand for advanced driver-assistance functions. The KBA enforces UNECE WP.29 cybersecurity type approval requirements that determine market access across signatory countries. Stuttgart and Munich host dense clusters where Bosch and Continental consolidate telematics modules into zonal compute nodes.
United States
Long-haul trucking fleets and ride-sharing platforms drive factory-installed telematics with API-accessible data streams. The NHTSA incorporates connected safety warnings into crashworthiness standards while DOT grants accelerate roadside unit deployment along interstate corridors. Michigan and California concentrate development activity where OEMs negotiate direct fleet relationships bypassing traditional intermediaries.
China
Domestic EV manufacturers and technology platforms scale vehicle-to-everything deployment for smart city integration. MIIT mandates data localization requirements that force redundant cloud infrastructure investments separate from Western architectures. Shanghai and Shenzhen anchor supplier ecosystems where cellular modem integration accelerates within domain controllers.
Japan
Premium manufacturers and semiconductor fabricators concentrate on edge computing integration for sub-50-millisecond latency applications. METI coordinates standards alignment for cooperative adaptive cruise control and autonomous emergency braking systems. Nagoya and Tokyo metropolitan areas host development clusters where system-on-chip integration migrates from discrete modules.
South Korea
Domestic OEMs and cellular chipset suppliers anchor 5G NR modem adoption for vehicle-to-everything communication stacks. National regulators align with UNECE frameworks while maintaining distinct data sovereignty requirements for connected vehicle services. Seoul and Busan concentrate manufacturing capacity where foundries supply automotive-grade silicon to tier-one integrators.
Connected Car Market Key Industry Players
Channel-controlling players compete with product-specialist players across hardware-software boundaries, with consolidated influence concentrated among semiconductor foundries and integrated tier-one suppliers. The vendor base separates into three strategic archetypes: captive OEM technology divisions, modular component suppliers, and cloud platform operators. Dominant competitive moves include backward integration into silicon design and strategic partnerships for zonal compute architecture consolidation.
Within the integrated tier-one archetype, Continental AG and Robert Bosch GmbH occupy positions exemplifying embedded systems consolidation. Tesla Inc. represents the captive OEM technology division model, sustaining recurring revenue through over-the-air software architecture independent of hardware refresh cycles.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Harman International |
| BMW AG |
| General Motors |
| Ford Motor Company |
| Tesla Inc. |
| Qualcomm Technologies |
| Audi AG |
| Others |
Cost & Logistics Intelligence
Taiwanese semiconductor foundries and South Korean memory fabricators anchor upstream supply for automotive-grade cellular modems and system-on-chips, concentrating margin capture with silicon vendors while compressing tier-one module suppliers into assembly-only roles. This concentration forces OEMs to absorb 5G NR chipset premiums or sacrifice feature content in mass-market vehicle segments.
Pricing Analysis
Certification level under UNECE WP.29 and ISO 26262 ASIL-D grades creates the primary spread between premium embedded systems and standard tethered solutions. Three-tier pricing structure across premium, standard, and economy levels reflects cybersecurity validation depth and functional safety rigor. Cost compression in mass-market segments is intensifying because 5G NR silicon multiples over 4G LTE equivalents force feature trade-offs below luxury tiers. Fleet operators exhibit lowest price sensitivity due to total cost of ownership calculations, while consumer retail buyers drive hardest bargaining on subscription service bundling.
Supply Chain Analysis
Geopolitical exposure across the Taiwan Strait dominates supply chain risk assessment for advanced cellular modems and automotive-grade system-on-chips. Manufacturing concentrates in Taiwan, South Korea, and Japan for leading-edge silicon nodes. Raw material dependencies span gallium arsenide substrates, high-purity silicon wafers, and rare earth elements for magnetics. Single-source vulnerability persists for 5G NR baseband processors. Distribution runs through tier-one integrators like Continental and Bosch, who consolidate discrete modules into zonal compute nodes for OEM direct supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator procurement consolidation toward direct OEM relationships is shifting buyer power away from traditional fleet management intermediaries, fragmenting legacy channel control and forcing suppliers to choose between volume scale and margin preservation.
For Market Incumbents: Pre-empt disintermediation by embedding API-accessible data architectures that lock fleet operators into multi-year software subscriptions independent of hardware refresh cycles. Backward integration into silicon design secures allocation priority at Taiwanese foundries. Invest in cybersecurity operations center staffing to satisfy EU Cyber Resilience Act transparency mandates before compliance deadlines tighten. For New Entrants and Emerging Players: Establish a beachhead in satellite-cellular hybrid terminals for mining and long-haul trucking operators across Australia and Canada, where coverage gaps persist and incumbent tethering solutions fail. Target municipal vehicle-to-infrastructure deployments in United States interstate corridors receiving DOT grant funding. Lead with DSRC-C-V2X protocol expertise to capture roadside unit integration contracts ahead of standardization maturation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive cybersecurity specialists holding continuous monitoring contracts with European premium manufacturers. Long-term viability hinges on software-defined vehicle architecture adoption extending revenue capture across fifteen-year vehicle lifecycles. Watch for inflection when OEMs begin reporting recurring connectivity revenue per vehicle exceeding hardware content margin contribution.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Centralized compute platforms enable aftermarket feature activation extending revenue across vehicle lifecycles for Tesla and legacy OEMs alike. |
| Battery Supply Agreement | Cellular modem power budgets constrain electric vehicle range calculations, forcing silicon vendors to prioritize energy-efficient 5G NR architectures. |
| Platform Standardization | Zonal compute node consolidation collapses standalone telematics module addressable market while expanding semiconductor content per vehicle. |
| Charging Infrastructure Partnership | Vehicle-to-grid communication protocols require interoperable connectivity stacks that bridge automotive and utility cybersecurity frameworks. |
| Geographic Manufacturing Footprint | Regional data localization mandates in China and Europe force redundant cloud infrastructure investments separate from unified global architectures. |
Research Approach
Desk research of automotive production databases, regulatory filing repositories, and semiconductor supply disclosures preceded structured interviews with OEM platform engineers, tier-one supplier procurement directors, fleet operator technology officers, and cellular chipset product managers. Primary fieldwork combined telephone discussions and written questionnaire responses with secondary validation against UNECE WP.29 implementation timelines and vehicle registration statistics. Bottom-up triangulation across component-level bill-of-materials analysis and top-down reconciliation against OEM reported connectivity revenue informed segmentation-level estimates.
Assumptions held fixed include UNECE WP.29 signatory adoption rates, 5G NR network coverage expansion curves, and automotive semiconductor foundry capacity allocation ratios across end-markets. Variables tested across sensitivity scenarios encompassed fleet telematics penetration rates, usage-based insurance regulatory approval timelines, and data localization enforcement intensity across jurisdictions. Segmentation modeling spanned product type, end user archetype, connectivity protocol, and integration level dimensions. CAGRs derived from logistic curve fitting against technology adoption benchmarks and replacement cycle analysis. Forecast inputs incorporated vehicle production schedules, cellular module pricing trajectories, and cybersecurity compliance cost estimates.
Sensitivities concentrate around semiconductor supply disruption severity, divergent data sovereignty enforcement between China's MIIT and European GDPR frameworks, and fleet operator subscription renewal rates through economic cycles. Forecasts reflect assumptions regarding regulatory harmonization progress and technology substitution thresholds that could accelerate or delay embedded system displacement of tethered alternatives. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Global Carpool-As-A-Service Market
Telematics and Infotainment
Telematics Market
Telematics and Infotainment
Commercial Vehicle Telematics Market
Telematics and Infotainment
In Car Infotainment System Market
Telematics and Infotainment
In Vehicle Infotainment Market
Telematics and Infotainment
V2X Communication Module Market
Telematics and Infotainment
APAC Telematics Market
Telematics and Infotainment
Automotive Human Machine Interface (HMI) Market
Telematics and Infotainment
Transport Data Logger Market
Telematics and Infotainment
Global Car GPS Navigation System Market
Telematics and Infotainment
Park Assist Camera Market
Telematics and Infotainment
Global Car Sharing Telematics Market
Telematics and Infotainment
Automotive Navigation & Infotainment Systems Market
Telematics and Infotainment
North America Commercial Vehicle Telematics Market
Telematics and Infotainment
Europe Dashboard Camera Market
Telematics and Infotainment
Europe Vehicle Remote Diagnostic Market