
 Motor Racing Telematics Market | 2026-2036
Motor Racing Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
Motor Racing Telematics Market Outlook
The gap between factory-backed race programs and privateer operations is repositioning how telematics capabilities distribute across the competitive grid. Robert Bosch GmbH leverages its sensor integration heritage to anchor high-frequency data capture systems for premier motorsport categories. Continental AG competes through specialized telemetry hardware designed for extreme thermal and vibrational environments. OCTO Telematics S.p.A differentiates via cloud-native architectures that serve both professional race teams and enthusiast segments.
Motor racing telematics encompasses the real-time acquisition, transmission, and analysis of vehicle performance parameters including suspension travel, tire temperature differentials, fuel consumption rates, and aerodynamic load distributions to inform competitive decision-making during events. The technology layer clusters around GPS tracking and sensor integration as foundational capabilities, with data analytics representing the fastest-expanding margin pool as teams invest in predictive modeling. Application demand concentrates in race strategy and performance monitoring where split-second data interpretation directly influences podium outcomes, while safety analysis matures as regulatory bodies mandate standardized incident reconstruction protocols.
FIA technical regulations, EU GDPR biometric data protections, and ISO 26262 functional safety standards collectively shape product development priorities and cross-border data governance for telematics providers serving European motorsport. The US Federal Communications Commission governs radio frequency allocations for real-time telemetry transmission at domestic circuits including Indianapolis Motor Speedway and Circuit of the Americas. Stakeholders must monitor evolving data sovereignty requirements as cloud-based telemetry architectures span multiple national jurisdictions during international race calendars.
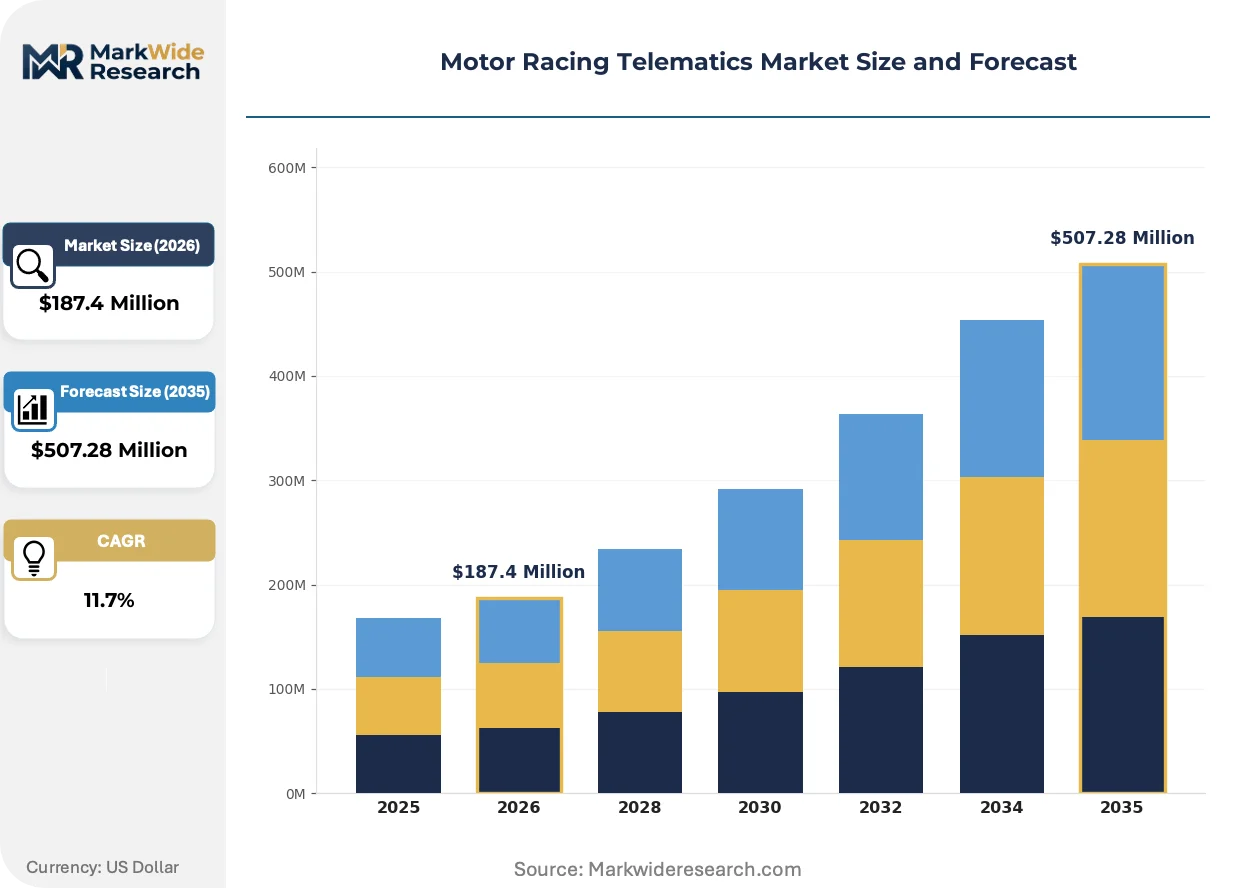
Market Dynamics
The divergence between factory-backed race programs and privateer operations is redistributing telematics capabilities across the competitive grid, with cloud-native architectures compressing deployment timelines for mid-tier teams while elite programs pursue proprietary sensor fusion stacks.
Growth Catalysts
- EU AI Act compliance mandates:European motorsport entities must implement auditable data governance frameworks for driver biometric processing, accelerating investment in compliant telemetry infrastructure.
- Real-time race strategy optimization:Formula One and IndyCar teams deploy high-frequency data capture to inform split-second pit wall decisions, creating sustained demand for low-latency transmission systems.
- Historic circuit clustering in Germany, Italy, and the United Kingdom:Manufacturer-backed teams anchor advanced telematics investment where technical heritage and regulatory sophistication converge.
Market Restraints
- GDPR biometric data friction:Cross-border race calendars trigger complex data sovereignty requirements that fragment cloud architecture standardization across European jurisdictions.
- Radio frequency allocation constraints:The US Federal Communications Commission governs spectrum access at domestic circuits, creating transmission bottlenecks during high-density event weekends.
- ISO 26262 functional safety certification:Hardware validation timelines extend product development cycles for sensor-integrated systems destined for premier motorsport categories.
Strategic Opportunities
- Enthusiast segment cloud migration:Amateur racing series and track day operators represent underpenetrated demand for subscription-based telemetry analytics previously reserved for professional teams.
- FIA standardized incident reconstruction:Mandatory safety analysis protocols create recurring revenue streams for telemetry providers serving regulatory compliance functions.
- Edge-to-cloud convergence:On-vehicle processing combined with centralized analytics architectures enables new service tiers between factory and privateer programs.
Industry Challenges
- Embedded systems engineering scarcity:Race-grade telemetry development requires rare expertise in extreme thermal and vibrational environment hardware design.
- Legacy chassis integration complexity:Older race car platforms lack standardized data buses, forcing costly custom sensor retrofitting for competitive parity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motor Racing Telematics Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Data Type: Vehicle Dynamics, Telemetry Data, Driver Performance, Environmental Conditions Application: Race Strategy, Performance Monitoring, Safety Analysis, Data Compression Technology: GPS Tracking, Sensor Integration, Data Analytics, Cloud Computing End User: Race Teams, Event Organizers, Automotive Manufacturers, Enthusiasts |
| Companies Covered | OCTO Telematics S.p.A, Robert Bosch GmbH, Agero Inc., Geotab, Verizon Communications Inc., Airbiquity Inc., Continental AG, Verizon Connect, Aptiv Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motor Racing Telematics Market Strategic Shifts
Predictive modeling capabilities are migrating from post-race analysis to real-time decision support, compressing the feedback loop between data acquisition and competitive action. This shift is restructuring how teams allocate technical resources across hardware, software, and human interpretation layers.
Edge computing architectures are rewriting how race teams process sensor streams. On-vehicle GPU clusters now execute machine learning inference for tire degradation prediction and fuel strategy optimization milliseconds after data capture. Factory-backed programs deploy these systems at every event, while privateer teams access equivalent capability through managed service arrangements that eliminate capital intensity.
The EU AI Act's risk classification framework for biometric data processing is forcing telemetry providers to reengineer data pipelines serving European motorsport. Systems must now maintain audit trails for algorithmic decisions affecting driver safety assessments. German and Italian race teams face the steepest compliance burden, driving consolidation toward providers with established regulatory documentation capabilities.
Subscription-based telemetry access is displacing perpetual license models among mid-tier race operations. Teams now procure analytics capability as a race-weekend service rather than capital investment, with cloud-native platforms capturing this demand shift. The United Kingdom's vibrant club racing scene exhibits the fastest adoption of this consumption pattern, where budget-constrained programs prioritize operational flexibility over asset ownership.
Motor Racing Telematics Market Segmentation
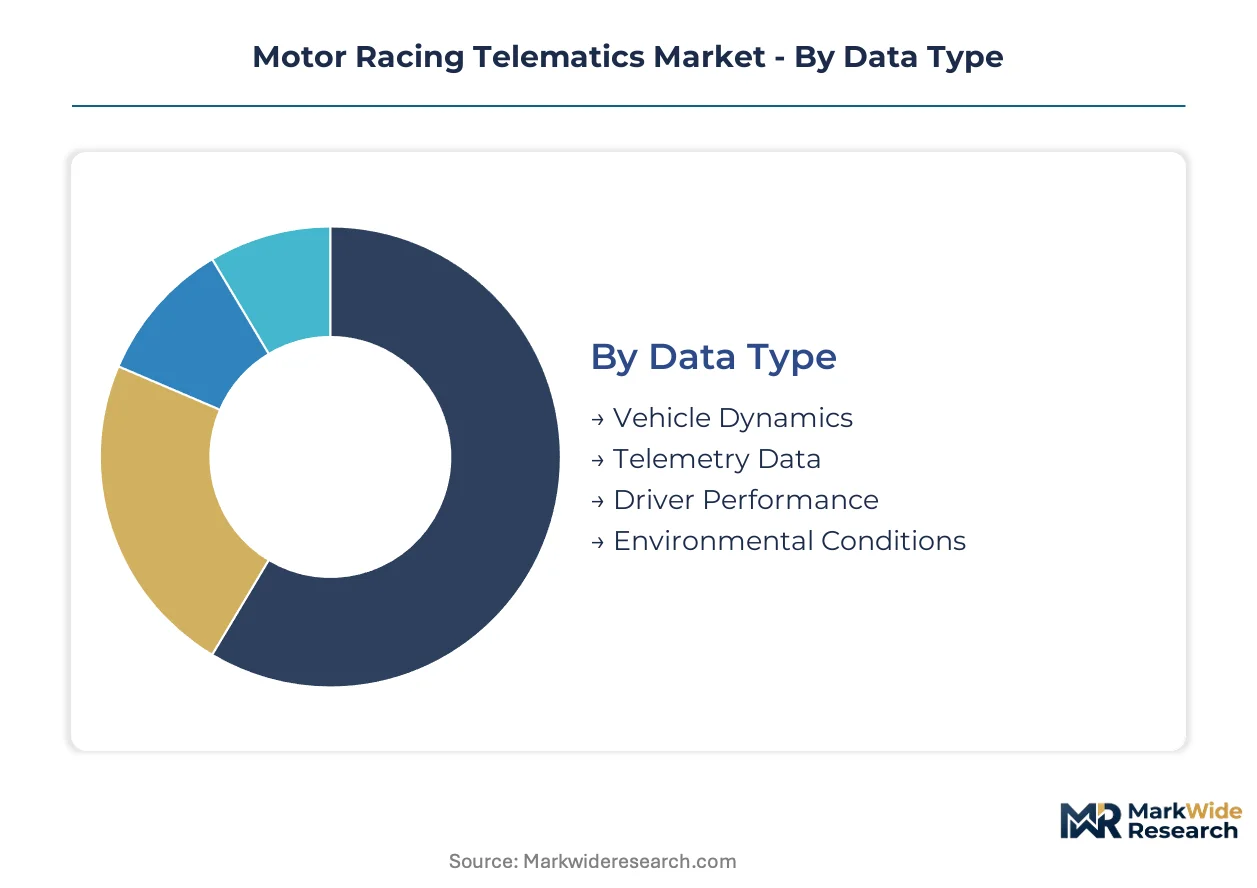
Motor racing telematics segmentation reveals how compliance burdens and technical specifications concentrate investment across hardware, software, and service layers. Teams allocate budgets differentially based on which segments trigger mandatory certification pathways versus discretionary capability upgrades.
Data Type:
ISO 26262 functional safety certification governs Vehicle Dynamics and Telemetry Data segments, while GDPR biometric protections apply specifically to Driver Performance processing across European circuits.
- Vehicle Dynamics:Captures suspension travel, aerodynamic load distribution, and chassis flex parameters through high-frequency accelerometer arrays. Demand clusters with Formula One and IndyCar factory programs at Silverstone Circuit and Indianapolis Motor Speedway where millisecond-resolution data shapes competitive outcomes. ISO 26262 validation extends hardware development timelines for race-grade sensor integration.
- Telemetry Data:Encompasses real-time transmission of fuel consumption rates, tire temperature differentials, and engine performance metrics via radio frequency bands. The US Federal Communications Commission governs spectrum allocation at domestic events, creating transmission bottlenecks during high-density race weekends. Teams invest in redundant transmission pathways to mitigate regulatory constraints.
- Driver Performance:Biometric monitoring including heart rate variability, hydration indicators, and cognitive load assessments. EU AI Act compliance mandates auditable data governance frameworks for European motorsport entities processing this category.
- Environmental Conditions:Track surface temperature, ambient humidity, and wind vector measurements. Sensors deploy at fixed circuit positions and mobile weather stations.
Leading the category by volume: Telemetry Data. Growing fastest: Driver Performance.
Application:
Cost tiers separate factory-backed programs from privateer operations across application segments, with premium deployments concentrating in race strategy optimization while safety analysis serves regulatory compliance functions.
- Race Strategy:Real-time pit wall decision support systems integrating predictive tire degradation models and fuel consumption algorithms. Edge computing architectures execute machine learning inference milliseconds after data capture at premier motorsport categories. Factory programs deploy proprietary stacks; privateer teams access equivalent capability through managed service arrangements.
- Performance Monitoring:Continuous vehicle health assessment during practice, qualifying, and race sessions. Post-session analysis identifies setup optimization opportunities for subsequent events. Demand concentrates in Germany, Italy, and the United Kingdom where manufacturer-backed teams anchor technical investment.
- Safety Analysis:FIA-mandated incident reconstruction protocols requiring standardized telemetry data formats. Regulatory compliance creates recurring revenue streams for providers serving this function.
- Data Compression:Algorithmic reduction of transmission bandwidth requirements without analytical fidelity loss. Critical for radio frequency-constrained environments.
Highest margin concentration: Race Strategy. Fastest volume expansion: Safety Analysis.
Technology:
Supply concentration favors established sensor manufacturers for GPS Tracking and Sensor Integration, while Data Analytics and Cloud Computing segments attract software-native entrants with lower capital barriers.
- GPS Tracking:High-precision positioning systems delivering centimeter-level accuracy for trajectory analysis and sector timing. Hardware integrates with inertial measurement units to maintain precision during satellite signal interruption. Robert Bosch GmbH leverages sensor integration heritage in this segment.
- Sensor Integration:Multi-parameter data acquisition modules engineered for extreme thermal and vibrational environments. Continental AG competes through specialized hardware validation for premier motorsport categories. ISO 26262 certification requirements extend development cycles.
- Data Analytics:Predictive modeling platforms migrating from post-race analysis to real-time decision support. Cloud-native architectures compress deployment timelines for mid-tier teams.
- Cloud Computing:Centralized data storage and processing infrastructure spanning multiple national jurisdictions during international race calendars. EU GDPR data sovereignty requirements fragment architecture standardization.
Steepest expansion trajectory: Data Analytics. Highest certification burden: Sensor Integration.
End User:
Customer maturity separates professional motorsport programs with dedicated engineering staff from enthusiast segments seeking subscription-based access to previously proprietary capabilities.
- Race Teams:Factory-backed and privateer operations deploying telematics for competitive advantage. Formula One and IndyCar programs pursue proprietary sensor fusion stacks while mid-tier teams adopt cloud-native managed services. Budget allocation prioritizes real-time race strategy optimization.
- Event Organizers:Circuit operators and series promoters implementing standardized safety analysis protocols. FIA regulatory mandates drive telemetry infrastructure investment at historic European circuits.
- Automotive Manufacturers:OEMs leveraging motorsport telemetry for production vehicle development feedback loops. Technical heritage in Germany and Italy anchors advanced investment.
- Enthusiasts:Amateur racing series and track day operators representing underpenetrated demand for subscription-based analytics. The United Kingdom's club racing scene exhibits fastest adoption of consumption-based models.
Dominant revenue share: Race Teams. Gaining share fastest: Enthusiasts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silverstone Circuit anchors European telematics investment through its proximity to Oxfordshire-based Formula One engineering clusters and the UK's dense concentration of motorsport technology suppliers.
Germany
Hockenheimring and Nürburgring host manufacturer-backed programs from Porsche, Mercedes-AMG, and BMW that demand millisecond-resolution vehicle dynamics data. The KBA enforces ISO 26262 functional safety standards for race-grade sensor systems. Baden-Württemberg's Stuttgart region concentrates embedded systems engineering talent for extreme environment hardware validation.
United Kingdom
Formula One teams at Milton Keynes and Brackley drive premium-tier telemetry procurement for real-time race strategy optimization. The Information Commissioner's Office applies GDPR biometric protections to driver performance data processing. Silverstone's surrounding Oxfordshire corridor houses specialist firms serving both factory programs and the country's vibrant club racing subscription market.
Italy
Ferrari's Maranello operations and the Monza Circuit anchor investment in high-frequency data capture for aerodynamic load analysis. The EU AI Act's risk classification framework imposes auditable governance requirements on biometric data pipelines. Emilia-Romagna's Motor Valley cluster integrates telemetry development with production vehicle feedback loops.
United States
Indianapolis Motor Speedway and Circuit of the Americas host IndyCar and Formula One events requiring redundant radio frequency transmission pathways. The FCC governs spectrum allocation at domestic circuits, creating bottlenecks during high-density race weekends. Austin's emerging technology corridor attracts cloud-native telemetry providers serving North American privateer operations.
Japan
Suzuka Circuit and Fuji Speedway support Toyota and Honda motorsport programs with heritage in production-vehicle sensor integration. METI standards influence automotive data governance approaches adopted by Japanese race teams. The Kanto region's Tokyo-Yokohama corridor supplies precision manufacturing capabilities for accelerometer and inertial measurement unit production.
Motor Racing Telematics Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification burden and thermal environment specialization. The vendor base stratifies between sensor-integrated hardware manufacturers with ISO 26262 validation capabilities and cloud-native software platforms serving subscription-based demand. Three archetypes dominate: heritage automotive suppliers with motorsport divisions, specialized telemetry hardware fabricators, and software-native platforms with managed service architectures. Competitive moves concentrate on strategic partnerships between sensor manufacturers and cloud infrastructure providers, plus portfolio diversification into enthusiast segment subscriptions.
Among European heritage automotive suppliers, Robert Bosch GmbH and Continental AG exemplify the premium-tier hardware archetype through their sensor integration specialization for extreme thermal and vibrational environments. OCTO Telematics S.p.A occupies a distinct position within the cloud-native tier, representing the managed service architecture approach that compresses deployment timelines for mid-tier race operations. These three entities collectively illustrate how compliance documentation capabilities and regulatory sophistication separate market positions across the European motorsport landscape.
| Leading Market Players |
|---|
| OCTO Telematics S.p.A |
| Robert Bosch GmbH |
| Agero Inc. |
| Geotab |
| Verizon Communications Inc. |
| Airbiquity Inc. |
| Continental AG |
| Verizon Connect |
| Aptiv Plc |
| Others |
Value Chain & Pricing Dynamics
Rare earth magnet price indices cascade through motor racing telematics supply chains, compressing margins for high-frequency sensor manufacturers while amplifying pricing power for cloud-native platform providers with software-heavy cost structures. Teams purchasing race-grade telemetry hardware face cost pass-through from German and Japanese component suppliers, whereas subscription-based analytics vendors absorb commodity volatility through recurring revenue models.
Pricing Analysis
Value-based pricing anchored to race outcome improvement commands premium tiers, with factory-backed Formula One programs paying for millisecond-latency data transmission that directly influences podium results. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262-certified sensor systems from club-grade enthusiast packages. Cost compression in mid-tier hardware is intensifying because privateer teams migrate toward managed service arrangements. Amateur racing series in the United Kingdom exhibit highest price sensitivity, while manufacturer-backed programs in Germany and Italy demonstrate lowest elasticity for compliance-validated systems.
Supply Chain Analysis
Dual-sourcing requirements from FIA technical regulations and OEM procurement policies mandate multi-supplier qualification for critical telemetry components, fragmenting concentration across Germany, Japan, and the United States. Supply chains draw from Taiwanese semiconductor foundries for GPU clusters, Baden-Württemberg precision manufacturers for accelerometer arrays, and Kanto-region producers for inertial measurement units. Single-source vulnerability persists in specialized thermal-vibration-hardened enclosures validated to ISO 26262. Distribution runs through direct OEM relationships for factory programs and regional motorsport distributors for privateer and enthusiast segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Motor racing telematics represents a vertical-integration race where cloud-native providers pursue backward integration into edge hardware, and heritage sensor manufacturers acquire software analytics capabilities to defend margin pools.
For Market Incumbents: Lock in regulatory documentation capabilities as the EU AI Act and GDPR biometric frameworks harden compliance barriers. Acquire cloud-native telemetry platforms serving the United Kingdom's club racing subscription market to capture demand migration from capital expenditure to operational expenditure models. ISO 26262 certification investment creates defensive moats against software-native entrants lacking hardware validation heritage.
For New Entrants and Emerging Players: Enter via the enthusiast segment's unmet demand for race-weekend telemetry analytics previously reserved for professional teams. Target amateur series operators in the United Kingdom and regional club circuits across Italy seeking consumption-based service models. Partner with established sensor distributors to bypass capital-intensive hardware development while building brand recognition through subscription platforms.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap telemetry hardware specialists with established FIA regulatory relationships in Germany and Italy. Long-term viability hinges on capability to serve both factory-backed programs requiring proprietary stacks and privateer operations demanding managed services. Monitor FCC spectrum allocation decisions as inflection indicators for transmission infrastructure investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Hardware Backward Integration | Cloud-native providers acquire sensor validation capabilities to capture factory program margins. |
| EU AI Act Compliance Certification | Audit trail documentation for biometric data processing opens regulatory-mandated revenue streams. |
| Enthusiast Segment Platform Launch | Subscription models targeting United Kingdom club racing compress deployment timelines for mid-tier teams. |
| Spectrum Redundancy Partnership | Dual-pathway transmission agreements with FCC-licensed operators mitigate high-density event bottlenecks. |
| Predictive Analytics Acquisition | Machine learning tire degradation capabilities differentiate real-time race strategy offerings. |
Study Parameters
FIA technical regulations, EU GDPR implementation guidance, and ISO 26262 certification databases formed the secondary backbone, cross-referenced against SEC filings from listed automotive suppliers and telecommunications spectrum allocation records. Primary interviews with race strategy engineers at Formula One and IndyCar programs, telemetry platform product managers, and regulatory compliance officers at European motorsport governing bodies validated demand assumptions. Bottom-up segment sizing across data type, application, technology, and end-user dimensions triangulated against top-down market value estimates.
Historical trendline analysis of telematics deployment patterns across premier motorsport categories established baseline growth trajectories. The analytical framework modeled segmentation across vehicle dynamics, telemetry data, driver performance, and environmental conditions data types; race strategy, performance monitoring, safety analysis, and data compression applications; GPS tracking, sensor integration, data analytics, and cloud computing technologies; and race teams, event organizers, automotive manufacturers, and enthusiasts end users. CAGRs were derived from elasticity modeling against regulatory mandate timelines and cloud infrastructure cost curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FCC spectrum reallocation scenarios or accelerated EU AI Act enforcement timelines. Forecasts reflect assumptions regarding cloud migration rates among privateer operations and ISO 26262 validation timeline stability. Deviation in rare earth magnet supply constraints or FIA technical regulation revisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
In-Car Apps Market
Telematics and Infotainment
North America Dashboard Camera Market
Telematics and Infotainment
Automotive Telematics System Market
Telematics and Infotainment
Europe Telematics Market
Telematics and Infotainment
Vehicle Digital Cockpit Market
Telematics and Infotainment
Telematics in Automotive Market
Telematics and Infotainment
Europe Automotive Infotainment Systems Market
Telematics and Infotainment
Global Car Sharing Telematics Market
Telematics and Infotainment
United States Commercial Telematics Market
Telematics and Infotainment
Global Carpool-As-A-Service Market
Telematics and Infotainment
Europe Automotive Navigation System Market
Telematics and Infotainment
India Fleet Management Software Market
Telematics and Infotainment
Europe Commercial Telematics Market
Telematics and Infotainment
Motorcycle Infotainment System Market
Telematics and Infotainment
Telematics and Connectivity Processors Market
Telematics and Infotainment
Global Automotive Navigation System Market