
 Europe Citric Acid Market | 2026-2036
Europe Citric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Citric Acid Market Intelligence
Specialty chemical distribution networks across Europe are tilting toward direct manufacturer-to-formulator relationships as buyers seek supply security. Jungbunzlauer leverages its Swiss fermentation heritage to dominate pharmaceutical-grade citric acid supply. Cargill anchors North European food processing demand through integrated glucose-to-citric acid pathways. Tate & Lyle competes on acidulant blends that combine citric with malic and tartaric variants for beverage clients.
Citric acid is a tricarboxylic acid produced industrially via submerged fermentation of Aspergillus niger on sucrose or glucose substrates, typically yielding purity grades between 99.5% and 99.9% for food and pharmaceutical applications; its primary function spans pH reduction, metal ion chelation, and microbial growth inhibition across processed goods. Citric acid anhydrous commands the largest volume share due to shelf stability and ease of powder handling in dry mixes, while citrate salts represent the fastest-expanding product category as pharmaceutical formulators seek buffered excipient systems. The preservative application segment carries the deepest margin pool because food safety regulations mandate its inclusion in acidified shelf-stable products.
EMA pharmaceutical guidelines, REACH chemical registration requirements, and EU Green Deal sustainability targets collectively reshape product specifications and sourcing transparency for European citric acid suppliers. EFSA purity standards for food-grade acidulants create compliance barriers that favor established fermentation producers over import-dependent traders. Stakeholders must monitor bio-based feedstock certification schemes and carbon border adjustment mechanisms as these frameworks increasingly determine competitive access to European formulation markets.
Market Dynamics
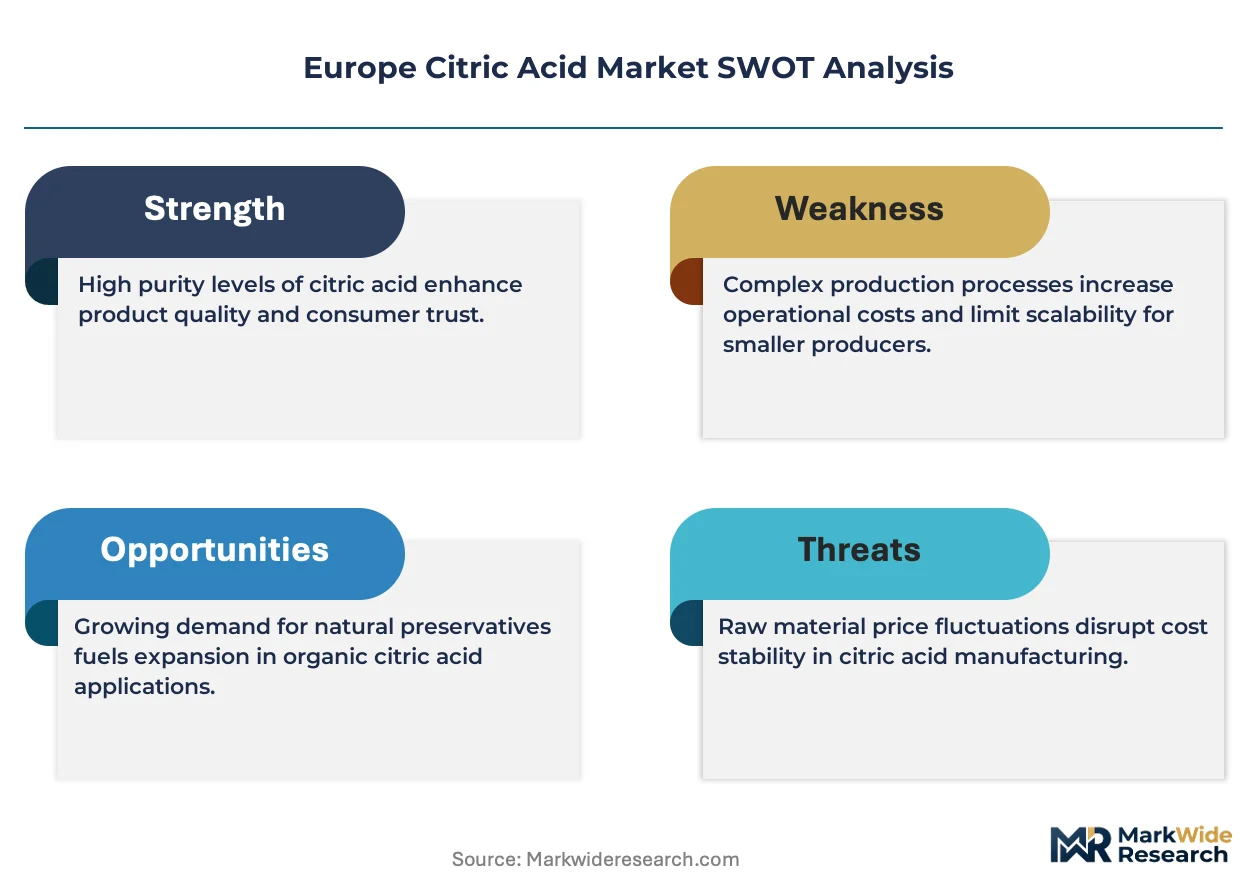
The EU Green Deal's carbon border adjustment mechanism is forcing fermentation-based citric acid producers to reconfigure feedstock sourcing and energy inputs, compressing margins for operators dependent on fossil-derived glucose.
Growth Catalysts
- Clean-label preservation mandates:EFSA purity standards for acidulants in shelf-stable foods compel manufacturers to source pharmaceutical-grade citric acid, expanding the addressable premium tier.
- Benelux pharmaceutical clustering:Injectable drug formulators in Belgium and the Netherlands are expanding citrate buffer purchases for biologic stabilization, creating concentrated demand pull.
- Fermentation yield improvements:Continuous processing of Aspergillus niger cultures on beet molasses substrates is reducing batch cycle times and improving titers for established European producers.
Market Restraints
- Glucose price volatility:Wheat and corn feedstock costs fluctuate with Black Sea grain flows, destabilizing input economics for glucose-dependent fermentation.
- Import concentration risk:Chinese anhydrous citric acid volumes dominate spot market availability, exposing European compounders to tariff and logistics disruption.
- REACH registration friction:ECHA substance evaluation timelines for citrate salts extend commercialization cycles for novel excipient grades.
Strategic Opportunities
- Italian pharmaceutical expansion:Lombardy-based injectable manufacturers are localizing citrate buffer supply chains, creating captive offtake for regional fermentation investments.
- CSRD sustainability disclosure:Corporate sustainability reporting requirements are rewarding bio-based feedstock certification with preferential procurement positioning.
- Chelation chemistry convergence:Metal sequestration applications in industrial water treatment are absorbing citric acid volumes previously directed to commodity food channels.
Industry Challenges
- Pharmaceutical GMP certification timelines:EMA inspection backlogs delay qualification of new fermentation facilities for injectable-grade output.
- Legacy batch-to-continuous retrofit costs:Converting submerged fermentation trains to perfusion culture systems demands capital deployment that mid-scale operators struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Citric Acid Market |
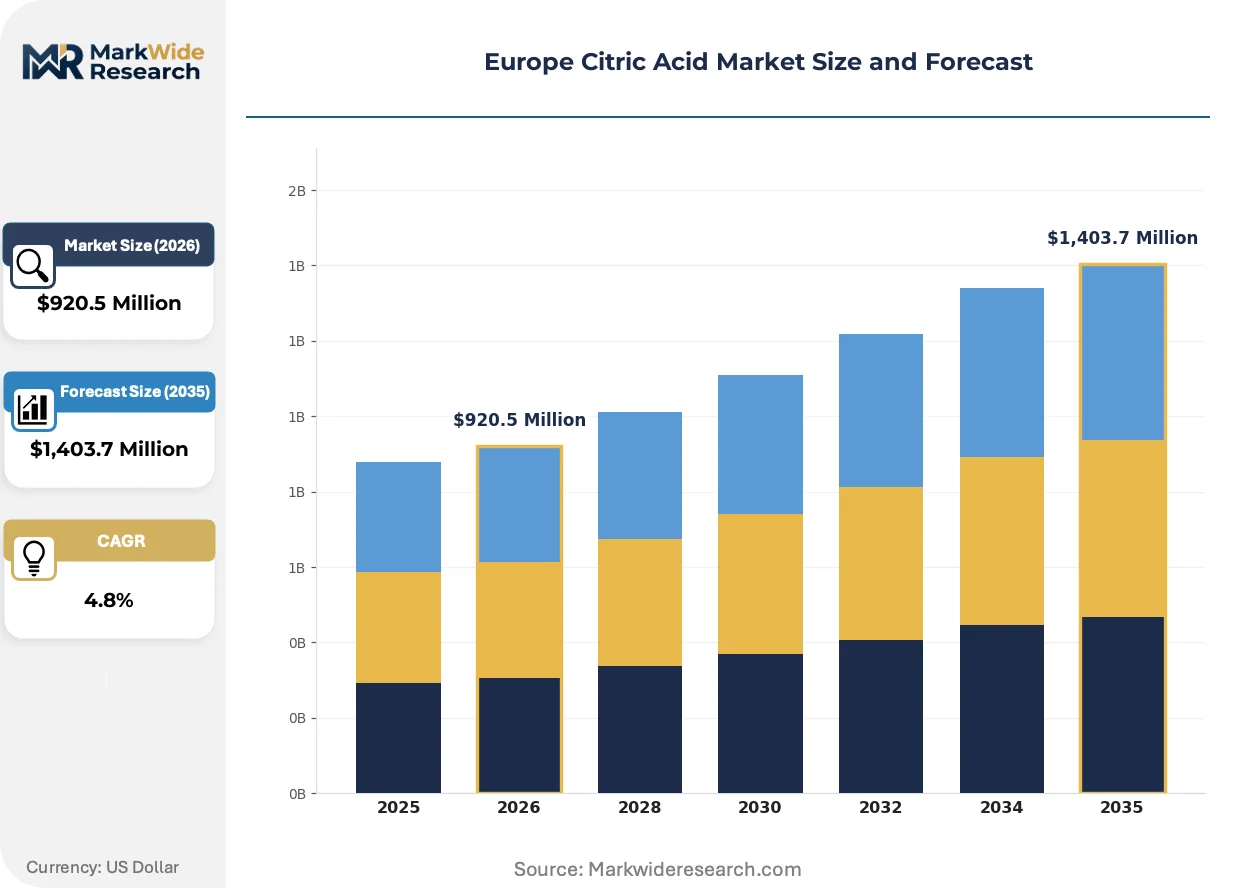
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,403.7 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citrate Salts, Citric Acid Anhydrous, Citric Acid Monohydrate, Liquid Citric Acid End User: Food & Beverage, Pharmaceuticals, Personal Care, Agriculture Application: Preservative, Flavoring Agent, pH Regulator, Chelating Agent Distribution Channel: Online Sales, Direct Sales, Distributors, Retail Stores |
| Companies Covered | Jungbunzlauer, Cargill, Tate & Lyle, Archer Daniels Midland (ADM), COFCO Biochemical, Brenntag, Corbion, Kenko Corporation, Danisco, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Citric Acid Market Strategic Shifts & Innovations
Fermentation process control, regulatory disclosure requirements, and buyer consolidation are restructuring how citric acid moves from bioreactor to formulation plant across European supply chains.
Inline Raman spectroscopy coupled with machine learning algorithms is digitizing real-time titer monitoring in Aspergillus niger bioreactors. German and Swiss producers are deploying these sensor arrays to reduce offline sampling frequency and compress batch release timelines. The technology is digitizing quality assurance workflows, enabling predictive release of pharmaceutical-grade lots before traditional lab confirmation completes.
REACH authorization requirements for Substances of Very High Concern are tightening impurity thresholds for citric acid derivatives used in medical devices. ECHA's 2024 update to restriction entries affects citrate plasticizers in PVC blood bags, forcing formulators to document alternative plasticizer migration profiles. Medical device manufacturers in Ireland and Germany are responding by qualifying citrate-buffered biocompatible polymers ahead of sunset date enforcement.
Food and beverage compounders are consolidating acidulant procurement through direct manufacturer contracts rather than distributor intermediaries. Large German processed meat and ready-meal producers are negotiating multi-year citric acid supply agreements with fixed volume tiers and indexed glucose pass-throughs. This concentration is most visible in the Ruhr industrial corridor, where three buyers now contract directly for over half of regional anhydrous acidulant offtake.
Europe Citric Acid Market Segmentation
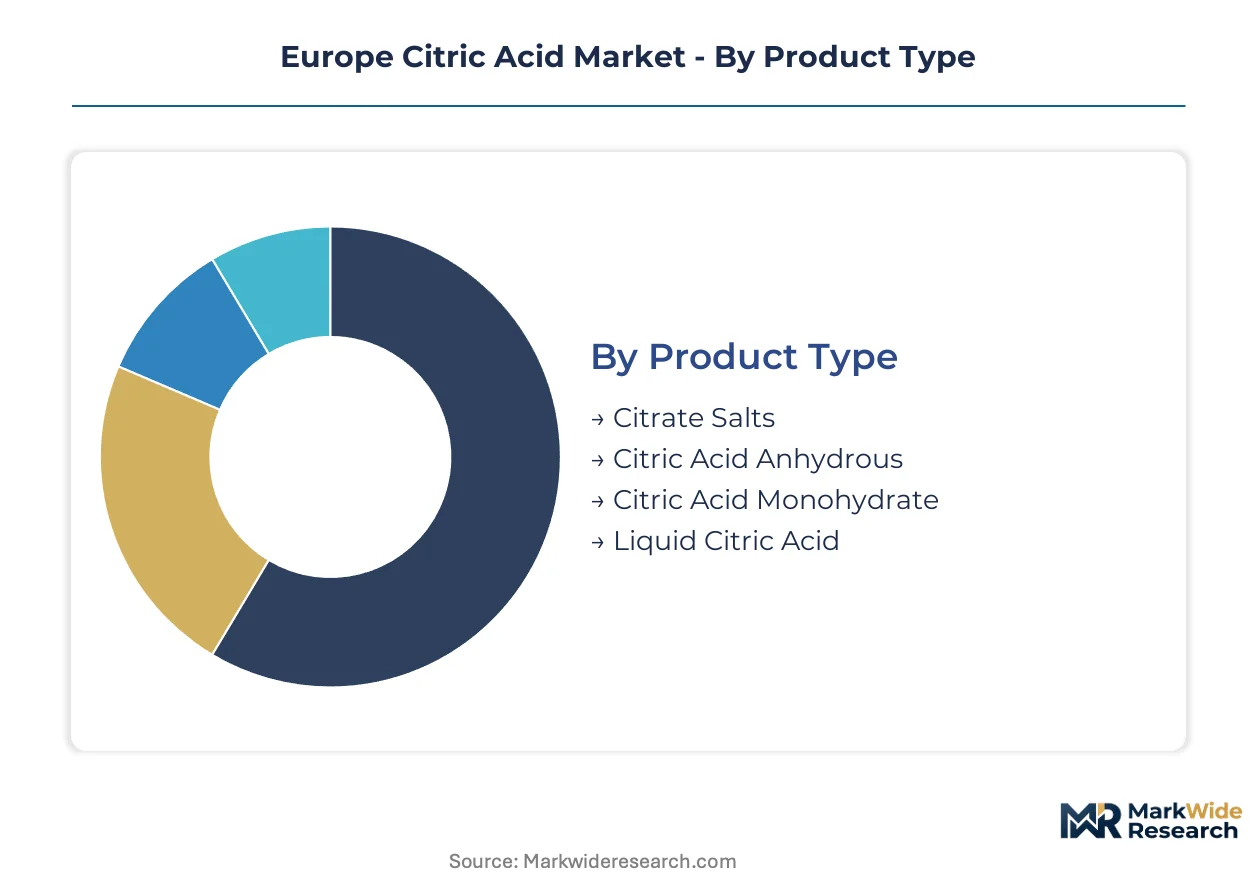
Segmentation in the Europe Citric Acid Market reveals how purity grades, formulation requirements, and regulatory pathways fragment demand across distinct commercial channels. Each dimension carries different margin structures, certification burdens, and buyer consolidation patterns that reshape supplier strategy.
Product Type:
After-sales service intensity varies sharply across product types, with pharmaceutical-grade anhydrous variants demanding batch-specific certificates of analysis and technical support that commodity liquid grades rarely require.
- Citric Acid Anhydrous:The powder form achieves 99.5-99.9% purity through controlled crystallization, eliminating water content for shelf-stable dry mixes. German processed meat manufacturers and Benelux pharmaceutical formulators dominate offtake, driven by EFSA and EMA purity mandates that disqualify lower-grade alternatives.
- Citrate Salts:Sodium, potassium, and calcium citrate derivatives function as buffered excipient systems with tunable pH and ionic strength. Injectable drug manufacturers in Belgium and the Netherlands are expanding purchases fastest, responding to biologic stabilization protocols that favor citrate-buffered formulations over phosphate alternatives.
- Citric Acid Monohydrate:The single-water-molecule form offers easier dissolution kinetics for beverage applications. French soft drink compounders prefer this grade for liquid acidulant systems.
- Liquid Citric Acid:Aqueous solutions at 50% concentration eliminate powder handling for large-volume food processors. Italian tomato paste canneries represent concentrated demand.
By volume, Citric Acid Anhydrous leads. By growth pace, Citrate Salts are climbing the fastest.
End User:
Cost tier stratification separates pharmaceutical buyers, who absorb premium pricing for GMP-certified material, from agricultural applicators, who source technical-grade citric acid through commodity channels.
- Food & Beverage:Acidification, preservation, and flavor modulation across processed meats, soft drinks, and convenience foods. German ready-meal producers in the Ruhr corridor anchor regional demand, responding to clean-label mandates that replace synthetic preservatives with citric acid.
- Pharmaceuticals:Active pharmaceutical ingredient buffering, anticoagulant stabilization, and excipient functionality. Lombardy-based injectable manufacturers are localizing supply chains, creating captive offtake for fermentation investments serving EMA-inspected facilities.
- Personal Care:pH adjustment and chelation in cosmetics and toiletries. French formulators leverage citric acid for natural-positioned skincare lines.
- Agriculture:Micronutrient chelation and feed acidification. Polish livestock operations represent expanding demand for acidified feed formulations.
Food & Beverage commands the largest volume share. Pharmaceuticals generate the steepest margin expansion.
Application:
Application selection dictates regulatory exposure, with preservative uses triggering EFSA food additive evaluations that chelating agents in industrial water treatment rarely face.
- Preservative:Microbial growth inhibition through pH reduction and metal ion sequestration. Shelf-stable acidified foods across Germany, France, and Italy mandate inclusion, creating compliance-driven demand that resists substitution.
- Chelating Agent:Metal ion complexation for stabilization and detoxification. Industrial water treatment facilities in the Netherlands are absorbing volumes previously directed to commodity food channels, responding to stricter discharge regulations.
- pH Regulator:Acid-base balance control across formulations. Beverage compounders in Spain deploy citric acid for precise titratable acidity targets.
- Flavoring Agent:Tartness contribution and taste enhancement. Confectionery manufacturers in Belgium favor citric acid for sour candy profiles.
Preservative applications dominate current volumes. Chelating Agent uses are gaining share fastest as industrial water treatment expands.
Distribution Channel:
Customer type fragmentation separates large formulators, who negotiate direct manufacturer contracts with indexed glucose pass-throughs, from smaller compounders dependent on distributor inventory buffers.
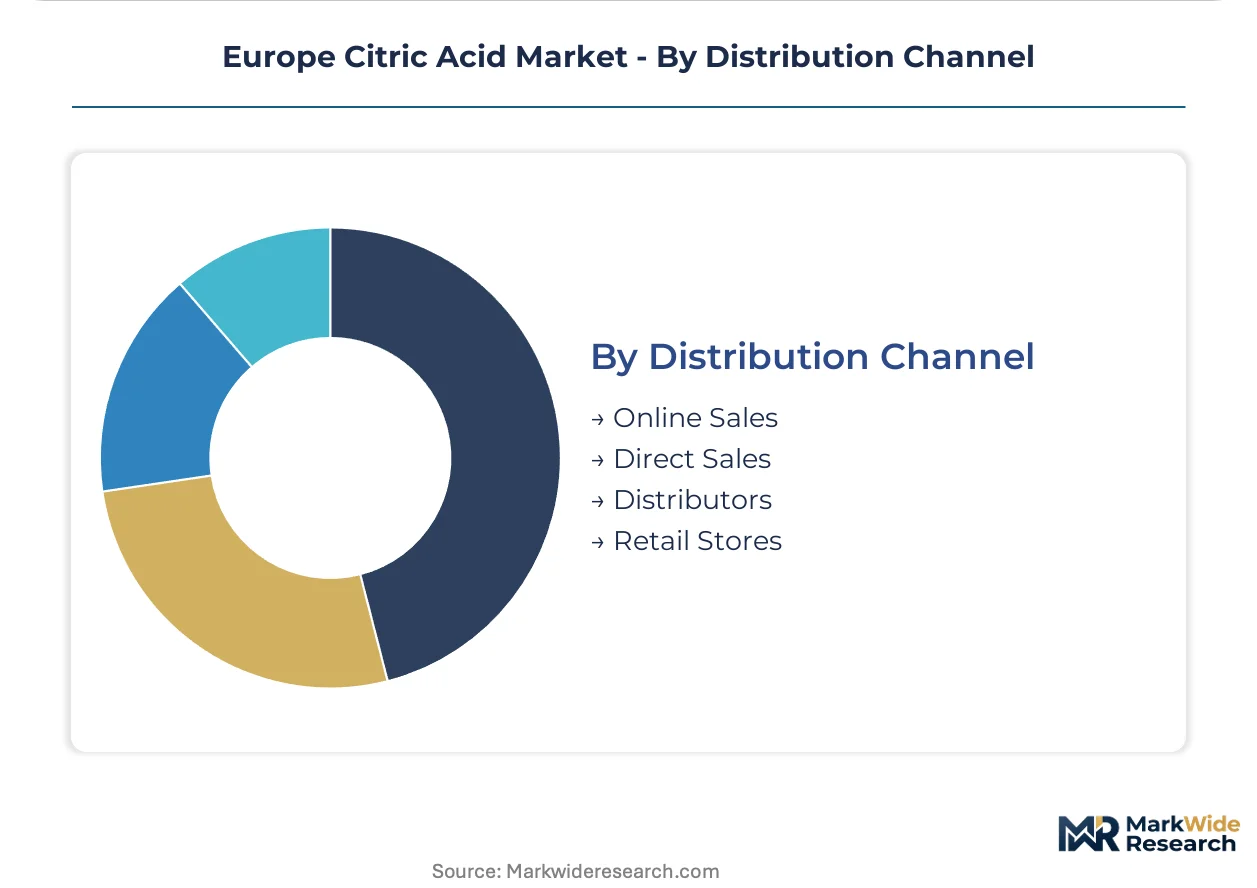
- Direct Sales:Manufacturer-to-formulator contracts with fixed volume tiers and technical support attachments. Three German processed meat producers now contract directly for over half of Ruhr corridor anhydrous offtake, consolidating procurement through multi-year agreements.
- Distributors:Specialty chemical wholesalers providing inventory management and just-in-time delivery. Mid-scale pharmaceutical compounders across Switzerland and Austria rely on distributor networks for smaller lot sizes.
- Online Sales:E-commerce platforms serving small-batch buyers and research institutions. Technical-grade purchases for agricultural trials increasingly route through digital channels.
- Retail Stores:Consumer-packaged goods for home preservation and cleaning applications. Limited penetration in professional citric acid markets.
Direct Sales channels capture the largest volume flows. Online Sales are expanding most quickly for small-lot technical grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Benelux pharmaceutical buyers command premium pricing leverage over Mediterranean food processors, creating a north-south value gradient that fermentation producers exploit through tiered certification strategies.
Germany
Ruhr corridor processed meat manufacturers anchor anhydrous citric acid offtake for clean-label preservation, while EFSA purity standards compel pharmaceutical-grade sourcing. The EU Green Deal carbon border adjustment mechanism pressures glucose feedstock economics for domestic fermentation operators. North Rhine-Westphalia's chemical parks host integrated glucose-to-citric acid pathways serving both food and pharmaceutical channels.
Netherlands
Injectable drug formulators in Rotterdam and Utrecht pharmaceutical clusters drive fastest-expanding citrate buffer demand for biologic stabilization. REACH registration requirements for novel excipient grades extend commercialization timelines. The Randstad region concentrates biopharma manufacturing requiring EMA-inspected citrate supply chains.
Belgium
Flemish pharmaceutical compounders localize citrate buffer procurement to reduce import dependency for injectable-grade material. EMA GMP certification backlogs delay qualification of new fermentation facilities. Antwerp's chemical distribution hub channels pharmaceutical-grade volumes toward Lombardy-based manufacturers.
Italy
Lombardy-based injectable manufacturers build captive citrate supply chains through direct fermentation investments. CSRD sustainability disclosure requirements reward bio-based feedstock certification with preferential procurement positioning. Emilia-Romagna tomato paste canneries absorb liquid citric acid volumes for acidification.
France
Paris Basin soft drink compounders favor citric acid monohydrate for liquid acidulant systems with precise titratable acidity targets. ECHA substance evaluation timelines for citrate salts create friction for novel excipient commercialization. Île-de-France cosmetics formulators leverage citric acid for natural-positioned skincare pH adjustment.
Europe Citric Acid Market Key Industry Players
Fermentation heritage specialists and integrated agribusiness conglomerates split the market into distinct capability tiers. Jungbunzlauer anchors pharmaceutical-grade supply through Swiss fermentation expertise, while Cargill leverages North American glucose integration for food acidulant scale. Tate & Lyle competes on acidulant blend formulation. Capacity expansion and direct manufacturer-to-formulator contracting represent the dominant competitive vectors reshaping distribution economics.
Within the fermentation heritage tier, Jungbunzlauer Suisse AG exemplifies Swiss-based pharmaceutical-grade specialization, occupying a position defined by EMA-inspected facility networks and batch-specific certificate of analysis protocols. Cargill Incorporated represents North American agribusiness integration into European food acidulant channels, anchoring the scale-driven segment through captive glucose supply. Tate & Lyle PLC sits within the formulation specialist archetype, emphasizing acidulant blend portfolios that combine citric with malic and tartaric variants for beverage clients.
| Leading Market Players |
|---|
| Jungbunzlauer |
| Cargill |
| Tate & Lyle |
| Archer Daniels Midland (ADM) |
| COFCO Biochemical |
| Brenntag |
| Corbion |
| Kenko Corporation |
| Danisco |
| Others |
Cost & Logistics Intelligence
Chinese import concentration risk determines both pricing tier spreads and supply chain shape across European citric acid markets, compressing margins for glucose-dependent fermentation operators while elevating premiums for EMA-certified domestic production. Buyers respond by bifurcating procurement between spot-exposed commodity volumes and contracted pharmaceutical-grade supply with indexed feedstock pass-throughs.
Pricing Analysis
The customization-premium spread separates pharmaceutical-grade anhydrous citric acid with batch-specific certificates of analysis from standard food-grade powder and liquid formats. Pricing stratifies across premium, standard, and economy tiers according to EMA GMP certification status and glucose feedstock origin. Cost compression in the standard tier intensifies because Chinese spot volumes dominate commodity availability. Agricultural compounders in Poland exhibit the highest price sensitivity, while Benelux injectable drug formulators absorb premium positioning for supply security.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk assessment for European compounders dependent on spot market anhydrous volumes. Manufacturing concentrates in China, Germany, and Switzerland, with fermentation capacity drawing from wheat and corn glucose streams anchored in Black Sea grain corridors. Single-source vulnerability persists for citrate salts serving pharmaceutical excipient applications. Distribution runs through direct manufacturer-to-formulator contracts for large German processed meat producers and specialty chemical distributors for mid-scale pharmaceutical compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidation as three German processed meat producers now contract directly for over half of Ruhr corridor anhydrous offtake, fragmenting distributor intermediaries and compressing their margin capture.
For Market Incumbents: Pre-empt Chinese spot market encroachment by securing long-term glucose supply agreements with indexed pass-throughs and accelerating EMA GMP certification for injectable-grade capacity. Backward integration into beet molasses fermentation feedstocks reduces exposure to Black Sea grain volatility. For New Entrants and Emerging Players: Establish a beachhead in Italian pharmaceutical citrate buffer supply by qualifying Lombardy-based injectable manufacturers seeking localized sourcing. Target technical-grade agricultural applications in Poland where distributor fragmentation creates entry pathways. Lead with bio-based feedstock certification to exploit CSRD sustainability disclosure requirements. For Investors and Strategic Acquirers: EU Green Deal carbon border adjustment mechanism implementation reshapes the acquisition landscape toward fermentation assets with verified bio-based glucose pathways. Five-to-ten year viability favors Swiss and German pharmaceutical-grade specialists with EMA-inspected facility networks. Monitor REACH authorization timelines for citrate salt derivatives as the inflection signal for excipient-grade margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Beet Molasses Feedstocks | Reduces glucose price volatility exposure for fermentation operators serving EFSA-mandated food preservation demand. |
| EMA GMP Certification Investment | Unlocks injectable-grade citrate buffer supply contracts with Benelux biologic stabilization formulators. |
| Long-term Direct Supply Agreement | Secures captive offtake from German processed meat producers consolidating Ruhr corridor procurement. |
| CSRD-Aligned Bio-based Certification | Positions fermentation output for preferential procurement under corporate sustainability reporting requirements. |
| Continuous Fermentation Retrofit | Compresses batch cycle times for Aspergillus niger cultures through perfusion culture system deployment. |
Research Approach
A standing panel of fermentation plant managers, pharmaceutical procurement leads at Benelux injectable manufacturers, food acidulant buyers at German processed meat producers, and specialty chemical distribution channel partners provided ongoing calibration. This primary intelligence combined with secondary validation from ECHA substance evaluation databases, EU customs trade flows, SEC filings of listed agribusiness conglomerates, and Cefic chemical industry reports. Bottom-up volume triangulation across grade tiers and top-down value reconciliation anchored the analytical framework.
Scenario-bracketing framed projections across the modeling period, with segmentation dimensions spanning purity grade, end-use industry channel, application function, and regional production hub. CAGRs derived from historical trajectory analysis modified by feedstock cost elasticity and regulatory compliance burden shifts. Forecast inputs incorporated EMA inspection backlog timelines and REACH authorization sunset dates for citrate plasticizer alternatives.
Stress conditions across Black Sea grain flow disruptions, Chinese export tariff impositions, and EMA GMP certification delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about fermentation yield improvements and buyer consolidation trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Sodium Citrate Anhydrous Market
Additives
Global Matting Agents Market
Additives
North America Potassium Nitrate Market
Additives
Surface Modifiers Market
Additives
Tackifier Market
Additives
Monocalcium Phosphate Market
Additives
Canada Water Enhancer Market
Additives
Global Rheology Modification Coating Additives Market
Additives
Driveline Additives Market
Additives
Choline Chloride Market
Additives
Acrylamide Reducing Ingredients Market
Additives
Global Calcium Formate Market
Additives
Cement Grinding Aid and Performance Enhancers Market
Additives
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market
Additives
Powder Induction and Dispersion Systems Market
Additives
Deodorant and Antiperspirant Ingredients Market