
 Choline Chloride Market | 2026-2036
Choline Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Choline Chloride Market Analysis
Trimethylamine hydrochloride chemistry is pivoting toward bio-based feedstock routes as corn-derived ethanol co-products replace petrochemical precursors in cost-sensitive formulations. Balchem Corporation leverages captive trimethylamine capacity to anchor North American supply security for feed-grade output. BASF SE competes through integrated methanol-to-chloride synthesis at Ludwigshafen, sustaining margin control across intermediate stages. Kemin Industries Inc. differentiates via microencapsulated choline delivery systems for rumen-protected applications, positioning against commodity price cycles.
Choline chloride functions as a quaternary ammonium salt with the molecular formula C5H14ClNO, typically manufactured through the reaction of trimethylamine with hydrochloric acid or ethylene oxide with trimethylamine hydrochloride to yield crystalline or aqueous products with 50-98% active content; its primary purpose centers on methyl group donation for phosphatidylcholine synthesis in animal metabolism and as a lipotropic agent in human nutrition. Feed Grade output dominates volume economics given inclusion rates of 200-500 grams per ton in poultry and swine rations, while Pharmaceutical Grade commands premium positioning due to USP-grade purity requirements and injectable formulation standards. Powder form leads in shipping efficiency for bulk feed mill integration, though liquid variants are gaining traction in automated dosing systems at integrated livestock operations.
The US FDA regulates choline chloride as a GRAS substance for food fortification under 21 CFR 182.8252, while China's SAMR enforces GB standards for feed additive quality and labeling disclosure. REACH registration requirements in Europe mandate full toxicological dossiers for trimethylamine intermediates, elevating compliance costs for non-integrated importers. Stakeholders must monitor evolving EFSA opinions on maximum choline levels in infant formula and specialty nutrition, as these will redirect formulation R&D investment toward precision-delivery platforms.
Market Dynamics
Feed-grade choline chloride supply chains are consolidating around integrated trimethylamine-to-chloride manufacturing corridors in eastern China, compressing margin structures for non-integrated Western producers facing escalating REACH compliance burdens.
Growth Catalysts
- Poultry Feed Intensification:Layer and broiler operations in Vietnam and Indonesia are standardizing 400g/ton inclusion rates to optimize feed conversion ratios and reduce fatty liver incidence.
- REACH Registration Completion:Full toxicological dossier acceptance for trimethylamine intermediates in the European Union has cleared import pathways for compliant Asian manufacturers.
- Bio-Based Feedstock Pivot:Corn ethanol co-product streams in the US Midwest are displacing petrochemical trimethylamine precursors in cost-sensitive aqueous formulations.
Market Restraints
- Input Cost Volatility:Methanol and ethylene oxide pricing swings directly compress margins for non-integrated chloride producers lacking captive precursor supply.
- Supply Concentration Risk:Shandong and Jiangsu provinces in China control over 60% of global crystalline powder capacity, creating single-geography vulnerability.
- Substitution Pressure:Choline bitartrate and choline citrate alternatives are capturing pharmaceutical-grade applications requiring lower chloride content.
Strategic Opportunities
- Rumen-Protected Delivery Systems:Microencapsulated choline formats for dairy cattle represent underdeveloped white space against standard feed-grade commoditization.
- SAMR Labeling Harmonization:China's 2024 feed additive disclosure mandates are redirecting formulation investment toward precision-delivery platforms with verified bioavailability claims.
- Automated Dosing Integration:Liquid choline chloride variants are penetrating integrated livestock operations in Brazil and Thailand with centralized nutrient injection systems.
Industry Challenges
- Specialized Process Engineering Talent:Quaternary ammonium salt synthesis expertise concentrates among aging technical workforces in Ludwigshafen and Rotterdam chemical clusters.
- Multi-Jurisdiction Certification Timelines:Parallel USP-grade, FAMI-QS, and GB standard approvals extend product launch cycles by 18-24 months for multi-market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Choline Chloride Market |
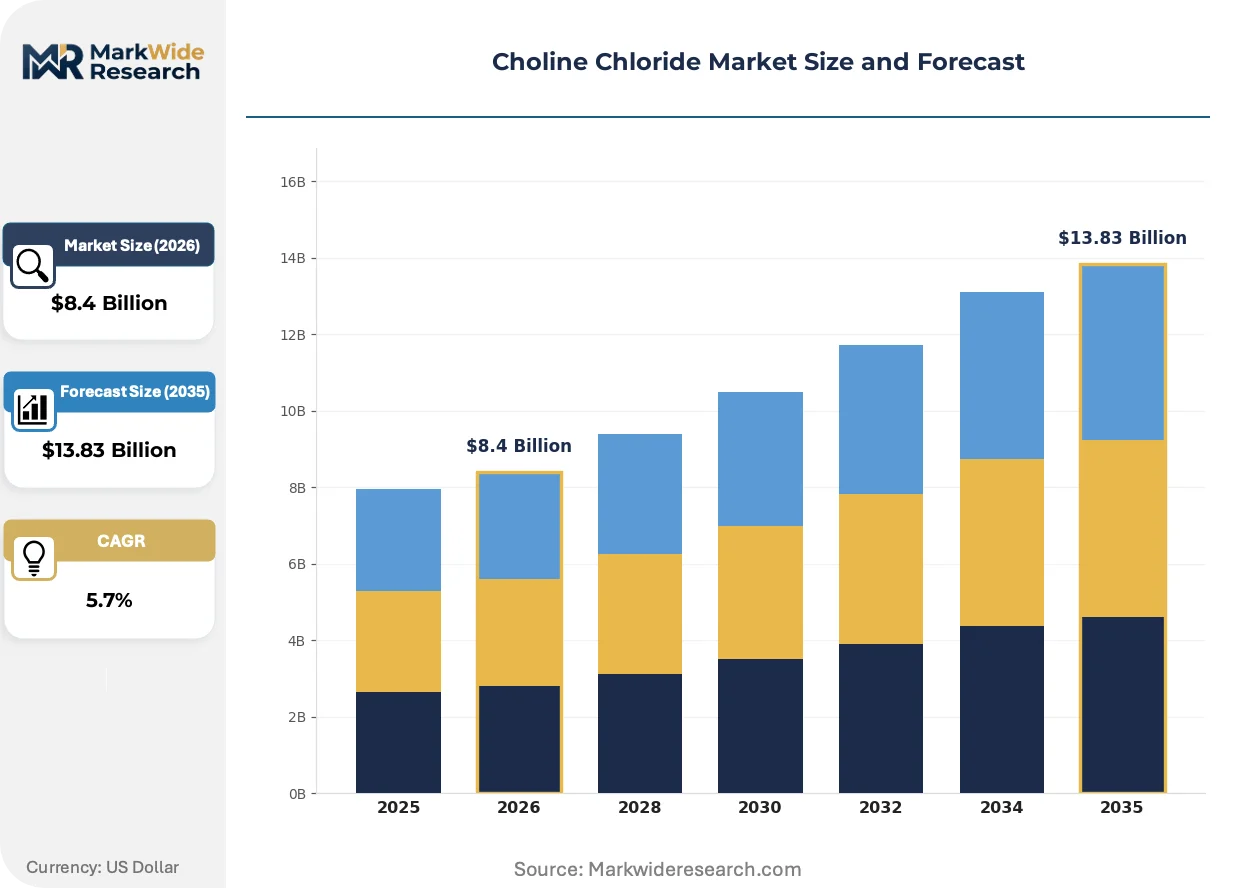
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feed Grade, Food Grade, Technical Grade, Pharmaceutical Grade Application: Animal Nutrition, Human Nutrition, Pharmaceuticals, Food Additives End User: Agriculture, Dietary Supplements, Animal Feed Manufacturers, Food Industry Form: Granules, Liquid, Powder, Tablets |
| Companies Covered | Balchem Corporation, Eastman Chemical Company, BASF SE, GHW International, Imperial Group Limited, Liaoning Biochem Co. Ltd., Kemin Industries Inc., NB Group Co. Ltd., Jubilant Ingrevia Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Choline Chloride Market Emerging Trajectories
Manufacturing technology and regulatory disclosure requirements are converging to favor integrated producers with captive feedstock control and automated quality verification systems.
Continuous flow reactor technology for trimethylamine hydrochloride synthesis is rewriting capital efficiency benchmarks in chloride production. Mid-scale European manufacturers are retrofitting batch plants to capture yield improvements and reduce solvent waste volumes. The technology is compressing the minimum viable scale for cost-competitive operation below 10,000 metric tons annually.
EFSA's evolving opinions on maximum choline levels in infant formula are tightening purity documentation requirements for pharmaceutical-grade output. Manufacturers must now maintain batch-level traceability from trimethylamine source through crystallization. Specialty nutrition compounders in the Netherlands and Switzerland are qualifying suppliers exclusively against these emerging standards.
Long-term offtake contracting is displacing spot-market purchasing among North American integrators seeking supply security. Tyson Foods and Pilgrim's Pride are negotiating 36-month chloride supply agreements with fixed-price escalators tied to methanol indices. The shift is most visible in the US Southeast where new mega-broiler complexes require guaranteed additive continuity.
Choline Chloride Market Segmentation
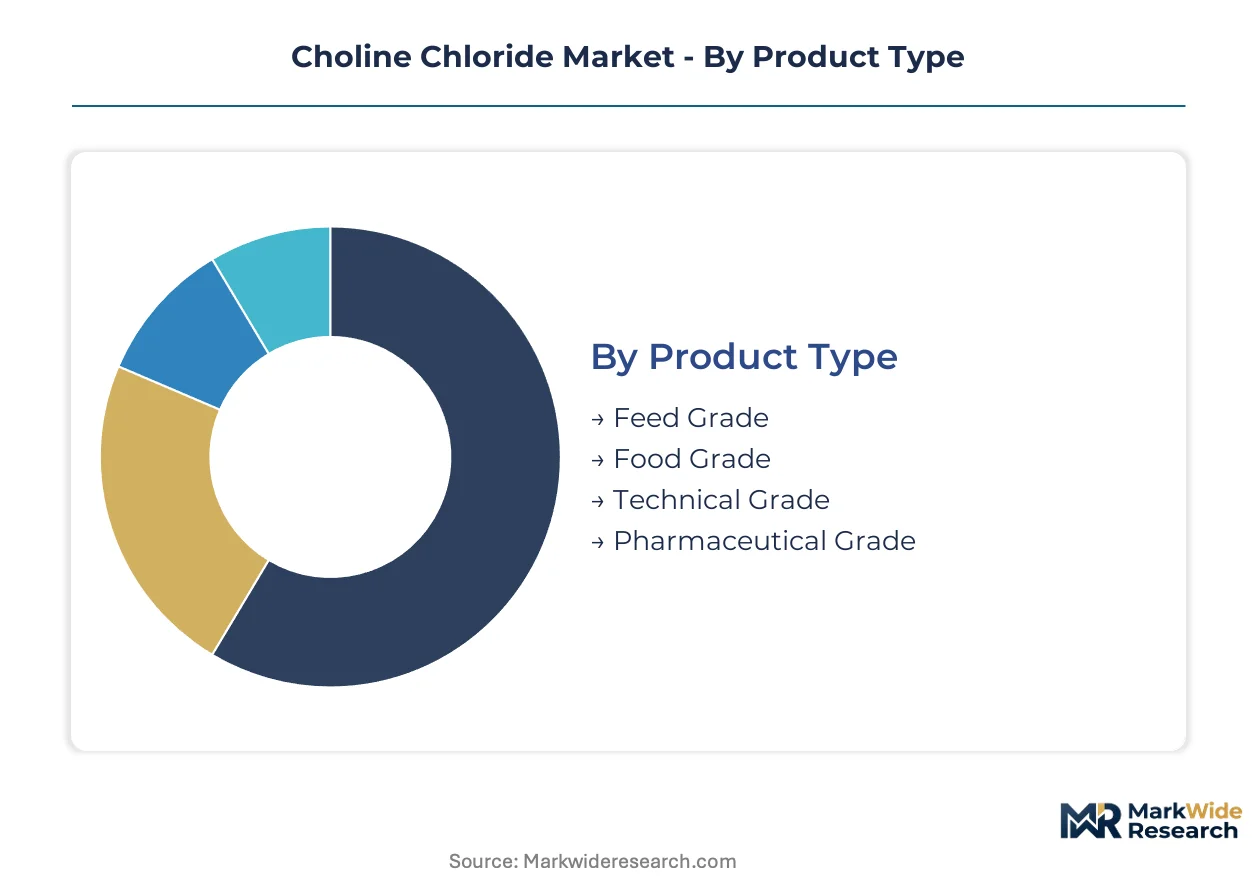
Choline chloride production economics and regulatory pathways diverge sharply across purity tiers and delivery formats. Manufacturers must align capacity investments with specific end-use certification requirements rather than pursuing undifferentiated scale.
Product Type:
Supply concentration in eastern China favors high-volume aqueous and crystalline output, while Western producers defend niches through integrated precursor control and quality documentation systems.
- Feed Grade:Aqueous solutions and crystalline powders with 50-75% active content dominate volume flows. Poultry integrators in Vietnam and Indonesia standardize 400g/ton inclusion rates, compressing margin structures for non-integrated producers lacking captive trimethylamine supply.
- Pharmaceutical Grade:USP-grade crystalline material meets injectable formulation standards with batch-level traceability from trimethylamine source. EFSA's evolving purity documentation requirements for infant formula applications are redirecting supplier qualification toward integrated manufacturers with automated quality verification.
- Food Grade:GRAS-compliant crystalline products for food fortification under FDA 21 CFR 182.8252.
- Technical Grade:Industrial quaternary ammonium salt applications in oilfield chemicals and clay stabilization.
Feed Grade absorbs the bulk of installed capacity; Pharmaceutical Grade is expanding most quickly.
Application:
Cost tier differentiation separates commodity methyl group donation from premium lipotropic and cognitive health positioning.
- Animal Nutrition:Methyl group donation for phosphatidylcholine synthesis drives inclusion across poultry, swine, and ruminant rations. Tyson Foods and Pilgrim's Pride negotiate 36-month supply agreements with methanol-indexed escalators, displacing spot purchasing in the US Southeast.
- Human Nutrition:Lipotropic agent positioning in dietary supplements commands formulation flexibility against choline bitartrate alternatives. SAMR labeling harmonization in China redirects investment toward precision-delivery platforms with verified bioavailability claims.
- Pharmaceuticals:Injectable and parenteral formulations requiring maximum chloride content documentation.
- Food Additives:Fortification in infant formula and functional foods subject to EFSA maximum level opinions.
Animal Nutrition commands the deepest volume commitments; Human Nutrition climbs the fastest on premium positioning.
End User:
Customer type determines procurement structure, with integrated livestock operations favoring long-term contracting and compounders prioritizing formulation flexibility.
- Animal Feed Manufacturers:Bulk compounders in Brazil and Thailand integrate automated liquid dosing systems for centralized nutrient injection. Continuous flow reactor retrofits compress minimum viable scale below 10,000 metric tons annually, opening entry paths for mid-scale European producers.
- Agriculture:Direct livestock operation procurement concentrates in North American integrators seeking supply security through multi-year offtake structures.
- Dietary Supplements:Specialty nutrition compounders in the Netherlands and Switzerland qualify suppliers exclusively against emerging EFSA batch-traceability standards.
- Food Industry:Infant formula manufacturers face tightening purity documentation timelines extending product launch cycles.
Animal Feed Manufacturers anchor procurement volume; Dietary Supplements gain share fastest on premium-grade qualification requirements.
Form:
Shipping efficiency and dosing automation trade off against solubility and stability requirements across delivery formats.
- Powder:Crystalline and spray-dried variants optimize shipping economics for bulk feed mill integration. Shandong and Jiangsu provinces control crystalline powder capacity, creating single-geography vulnerability for non-diversified purchasers.
- Liquid:Aqueous solutions penetrate automated dosing systems at integrated operations in Brazil and Thailand. Corn ethanol co-product streams in the US Midwest displace petrochemical precursors in cost-sensitive aqueous formulations.
- Granules:Flow-enhanced crystalline products for high-speed feed mill handling.
- Tablets:Direct-compression formats for human supplement and pharmaceutical applications.
Powder retains the largest installed base; Liquid steepest expansion trajectory follows automated dosing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China where integrated production clusters serve both domestic feed compounders and export markets. Shandong and Jiangsu provinces control crystalline powder capacity. Regulatory divergence across major consuming regions is fragmenting procurement strategies.
China
Poultry and swine feed intensification drives 400g/ton standardization among domestic integrators. SAMR enforces GB standards for feed additive quality and labeling disclosure. Shandong and Jiangsu provinces host over 60 percent of global crystalline powder capacity, creating single-geography supply vulnerability for international purchasers.
United States
Tyson Foods and Pilgrim's Pride negotiate 36-month supply agreements with methanol-indexed price escalators for Southeast mega-broiler complexes. FDA regulates choline chloride as GRAS under 21 CFR 182.8252 for food fortification. Corn ethanol co-product streams in the Midwest displace petrochemical trimethylamine precursors in cost-sensitive aqueous formulations.
Germany
Specialty nutrition compounders in Ludwigshafen qualify suppliers against emerging EFSA batch-traceability standards for infant formula applications. REACH registration requirements mandate full toxicological dossiers for trimethylamine intermediates. The Ludwigshafen chemical cluster sustains integrated methanol-to-chloride synthesis operations with captive precursor supply.
Vietnam
Layer and broiler operations standardize 400g/ton inclusion rates to optimize feed conversion ratios and reduce fatty liver incidence. The country's national feed safety regulator tightens additive import documentation requirements. Ho Chi Minh City and Mekong Delta feed mill corridors integrate automated liquid dosing systems for centralized nutrient injection.
Brazil
Integrated livestock operations in São Paulo and Paraná states adopt automated liquid choline chloride dosing for centralized nutrient management. ANVISA aligns with international feed additive safety benchmarks for import clearance. São Paulo feed manufacturing corridors retrofit batch plants to capture yield improvements from continuous flow reactor technology.
Choline Chloride Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated chemical conglomerates defending feed-grade volume and pharmaceutical-grade purity specialists capturing premium tiers. The vendor base organizes around three strategic archetypes: captive trimethylamine producers with backward integration into precursor supply, microencapsulation technology licensors serving rumen-protected applications, and regional compounders leveraging distributed formulation flexibility. Consolidation pressure concentrates in Asian manufacturing corridors where scale economics dominate, while European and North American positions depend on quality documentation and regulatory compliance capabilities. Dominant competitive moves include multi-year offtake contracting with price escalators and continuous flow reactor retrofits to compress minimum viable operating scale.
Among North American integrated producers, Balchem Corporation exemplifies the captive precursor archetype with dedicated trimethylamine capacity anchoring regional supply security. BASF SE occupies a position within the European integrated chemical complex, representing the Ludwigshafen-centered methanol-to-chloride synthesis model. Kemin Industries Inc. sits within the specialty delivery tier, embodying microencapsulated choline technology positioning against commodity price cycles.
| Leading Market Players |
|---|
| Balchem Corporation |
| Eastman Chemical Company |
| BASF SE |
| GHW International |
| Imperial Group Limited |
| Liaoning Biochem Co. Ltd. |
| Kemin Industries Inc. |
| NB Group Co. Ltd. |
| Jubilant Ingrevia Limited |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap producers in eastern China anchor feed-grade supply, disciplining spot-market volatility through captive trimethylamine capacity while compressing margins for Western importers facing REACH compliance burdens.
Pricing Analysis
Volume-mass feed-grade crystalline powder trades on thin spreads indexed to methanol feedstock costs, while pharmaceutical-grade USP material commands substantial premia through batch-traceability documentation and EFSA-aligned purity certification. Three-tier pricing structure across pharmaceutical-grade, feed-grade, and technical-grade levels separates quality-assured supply from commodity spot transactions. Pricing pressure stems from Shandong-Jiangsu production concentration enabling Chinese exporters to undercut non-integrated Western manufacturers on landed cost. Poultry integrators in Vietnam and Indonesia exhibit highest price sensitivity, standardizing 400g/ton inclusion rates and negotiating volume commitments; pharmaceutical compounders in the Netherlands and Switzerland show lowest sensitivity, prioritizing documentation reliability over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from Tyson Foods and Pilgrim's Pride are fragmenting procurement structures, compelling qualified suppliers to maintain redundant manufacturing footprints across North America and Asia despite scale penalties. Supply concentrates in China, Germany, and the United States, with Shandong and Jiangsu provinces hosting crystalline powder capacity while Ludwigshafen and Rotterdam clusters retain pharmaceutical-grade synthesis expertise. Raw material flows draw from methanol, ethylene oxide, and corn ethanol co-product streams, with bio-based trimethylamine precursors displacing petrochemical routes in cost-sensitive aqueous formulations. Single-geography concentration risk concentrates in eastern China, where over 60 percent of global crystalline capacity resides within two provinces. Distribution runs through long-term offtake contracts with methanol-indexed escalators, displacing spot-market purchasing among North American integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as REACH registration costs and continuous flow reactor capital requirements force sub-scale European and North American producers toward exit or acquisition.
For Market Incumbents: Deploy captive trimethylamine capacity to anchor regional supply security against Chinese import penetration, while retrofitting batch plants to continuous flow reactor technology to capture yield improvements and defend margin structures against integrated competitors. BASF SE's Ludwigshafen methanol-to-chloride synthesis model exemplifies the backward integration lever, sustaining cost control across intermediate stages. Incumbents must simultaneously invest in batch-level traceability systems to meet evolving EFSA purity documentation requirements for infant formula applications, as non-compliant suppliers face disqualification from pharmaceutical-grade qualification. For New Entrants and Emerging Players: Enter via microencapsulated choline delivery systems for rumen-protected dairy cattle applications, an underdeveloped white space where Kemin Industries Inc. has established proof-of-concept against commodity price cycles. The penetrable segment centers on automated liquid dosing integration at integrated livestock operations in Brazil and Thailand, where centralized nutrient injection systems are displacing powder handling. Go-to-market positioning should emphasize precision-delivery platforms with verified bioavailability claims aligned to SAMR labeling harmonization requirements, enabling premium pricing against standard feed-grade commoditization. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European manufacturers with REACH-registered trimethylamine intermediates and retrofit-capable batch plants in the Netherlands and Germany, where aging technical workforces and compliance burdens are forcing generational ownership transitions. Long-term viability over a 5-10 year window rests on securing captive precursor supply or exclusive offtake relationships with corn ethanol co-product streams in the US Midwest. The signal to watch is EFSA opinion finalization on maximum choline levels in infant formula, which would redirect formulation R&D investment and reshape supplier qualification criteria across pharmaceutical-grade tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Trimethylamine | Balchem Corporation's captive precursor capacity anchors North American supply security against import volatility. |
| Continuous Flow Reactor Retrofit | Mid-scale European manufacturers compress minimum viable scale below 10,000 metric tons annually through yield improvements. |
| Microencapsulation Technology Licensing | Kemin Industries Inc. differentiates against commodity cycles via rumen-protected delivery systems for dairy applications. |
| Long-term Supply Agreement | Tyson Foods and Pilgrim's Pride negotiate 36-month contracts with methanol-indexed escalators for Southeast mega-broiler complexes. |
| SAMR Labeling Harmonization Compliance | Precision-delivery platforms with verified bioavailability claims capture premium positioning in China's redirected formulation investment. |
Methodological Framework
Multi-period observation of methanol price indices, REACH registration timelines, and poultry feed inclusion rate standardization anchored the trend analysis, supplemented by interviews with plant managers at integrated chemical facilities, procurement leads at North American poultry integrators, distribution channel partners in Southeast Asian feed corridors, and technical R&D directors specializing in quaternary ammonium salt synthesis. Secondary validation drew from customs and trade data, SEC 10-K filings of listed chemical producers, ECHA registration dossiers, and FAMI-QS certification records. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic indicators to ensure cross-verification of volume and value outputs.
Input-output matrices structured the analytical framework across the projection horizon, modeling choline chloride demand through segmentation dimensions including grade tier (pharmaceutical, feed, food, technical), end-use industry (animal nutrition, human nutrition, pharmaceuticals, oilfield chemicals), delivery format (powder, liquid, granules, tablets), and regional production hub concentration. CAGRs were derived through regression analysis of historical price-volume relationships and forward projection of feed intensification trends in emerging poultry markets. Industry-specific forecast inputs included corn ethanol co-product availability in the US Midwest and EFSA opinion evolution timelines for infant formula maximum levels.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme methanol price volatility or sudden REACH restriction tightening on trimethylamine intermediates. Forecasts reflect documented assumptions regarding poultry feed standardization rates, bio-based feedstock substitution velocity, and regulatory disclosure mandate implementation schedules. Deviation in Chinese environmental enforcement intensity or Shandong-Jiangsu production corridor disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Russia Sodium Reduction Ingredient Market
Additives
Automotive Additives Market
Additives
Biosaccharide Gum Market
Additives
Sorbitan Laurate Market
Additives
Anti-Wear Additives Market
Additives
Global Isononanoic Acid Market
Additives
Antiscalants/Scale Inhibitors Market
Additives
Green Polymer Additive Market
Additives
Global Pearlizing Agent Market
Additives
Europe Anti-Caking Market
Additives
Microcrystalline Cellulose (MCC) Market
Additives
Electrolyte Additives for Lithium Ion Battery Market
Additives
PVC Plasticizers and Stabilizers Market
Additives
Weighing Agents Market
Additives
Chitosan Powder Market
Additives
Zinc Dialkyldithiophosphates Additive Market