
 Global Calcium Formate Market | 2026-2036
Global Calcium Formate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Calcium Formate Market Foresight
Direct supply relationships between Chinese manufacturers and European distributors is narrowing as logistics costs and certification requirements harden. Zibo Ruibao Chemical leverages captive feedstock access to sustain cost leadership in powder-grade output. LANXESS anchors premium positioning through REACH-certified supply chains serving Western European construction chemical formulators. Perstorp Holding AB differentiates via controlled crystallization technology that yields low-dust granular grades for automated dosing systems.
Calcium formate (Ca(HCOO)2) is the calcium salt of formic acid, typically manufactured through the reaction of calcium hydroxide with carbon monoxide under pressure or via calcium carbonate neutralization of formic acid, yielding a white crystalline solid with minimum 98% purity in commercial grades. The compound functions primarily as an accelerating admixture in Portland cement systems, reducing setting time at low temperatures while enhancing early compressive strength development. Construction applications dominate volume absorption, with powder formulations leading due to blending compatibility with dry mortar systems and grouts. Feed additive demand is accelerating fastest among end-user segments as poultry and swine producers substitute antibiotic growth promoters with organic acid salts. Granular product types command margin premiums in automated feed mills where dust control determines dosing accuracy and worker safety compliance.
EPA guidelines under the Toxic Substances Control Act shape import thresholds for chemical purity documentation in the United States, while China's SAMR enforces GB standards governing heavy metal limits in feed-grade calcium formate. The EU Green Deal's embodied carbon tracking requirements are pressuring construction chemical suppliers to document manufacturing emissions across their calcium formate supply chains. Stakeholders must monitor evolving feed safety regulations in Brazil and Saudi Arabia where import substitution policies are redirecting procurement toward certified regional producers.
Market Dynamics
REACH compliance tightening across the European Union is forcing construction-grade calcium formate producers to requalify supply chains or exit Western European markets entirely. This regulatory pressure is compressing the supplier base while elevating certified producers to preferred-partner status with major formulators.
Growth Catalysts
- EU Green Deal embodied carbon tracking:Construction chemical suppliers must document manufacturing emissions, creating competitive advantage for producers with verified low-carbon production routes.
- Feed additive substitution wave:Poultry and swine producers across Brazil and Saudi Arabia are replacing antibiotic growth promoters with organic acid salts, accelerating feed-grade calcium formate absorption.
- Cold-weather construction demand:Accelerating admixture functionality enables year-round cement work in temperate climates, driving specification by infrastructure contractors in Germany and Poland.
Market Restraints
- Formic acid feedstock volatility:Pricing swings in the primary raw material compress margins for non-integrated producers lacking captive carbon monoxide supply.
- Chinese supply concentration:Domestic producers control approximately two-thirds of global powder-grade output, creating single-source vulnerability for European distributors.
- Sodium formate substitution threat:Lower-cost sodium salt alternatives displace calcium formate in certain de-icing and leather tanning applications where calcium cation functionality is non-critical.
Strategic Opportunities
- Saudi Arabia import substitution policy:The SFDA is redirecting feed additive procurement toward certified regional producers, opening white space for compliant local manufacturing investments.
- Automated dosing system convergence:Integration of dust-controlled granular grades with precision feed mill equipment creates premium positioning in industrial-scale livestock operations.
- Southeast Asia infrastructure buildout:Cement consumption expansion in Vietnam and Indonesia generates unmet demand for construction-grade accelerating admixtures.
Industry Challenges
- REACH re-registration timeline compression:The ECHA dossier preparation and substance evaluation process demands specialized regulatory affairs expertise that mid-tier producers struggle to staff.
- Legacy dry-mix equipment incompatibility:Automated blending systems in European construction chemical plants require flowability specifications that standard powder grades fail to meet without process re-engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Calcium Formate Market |
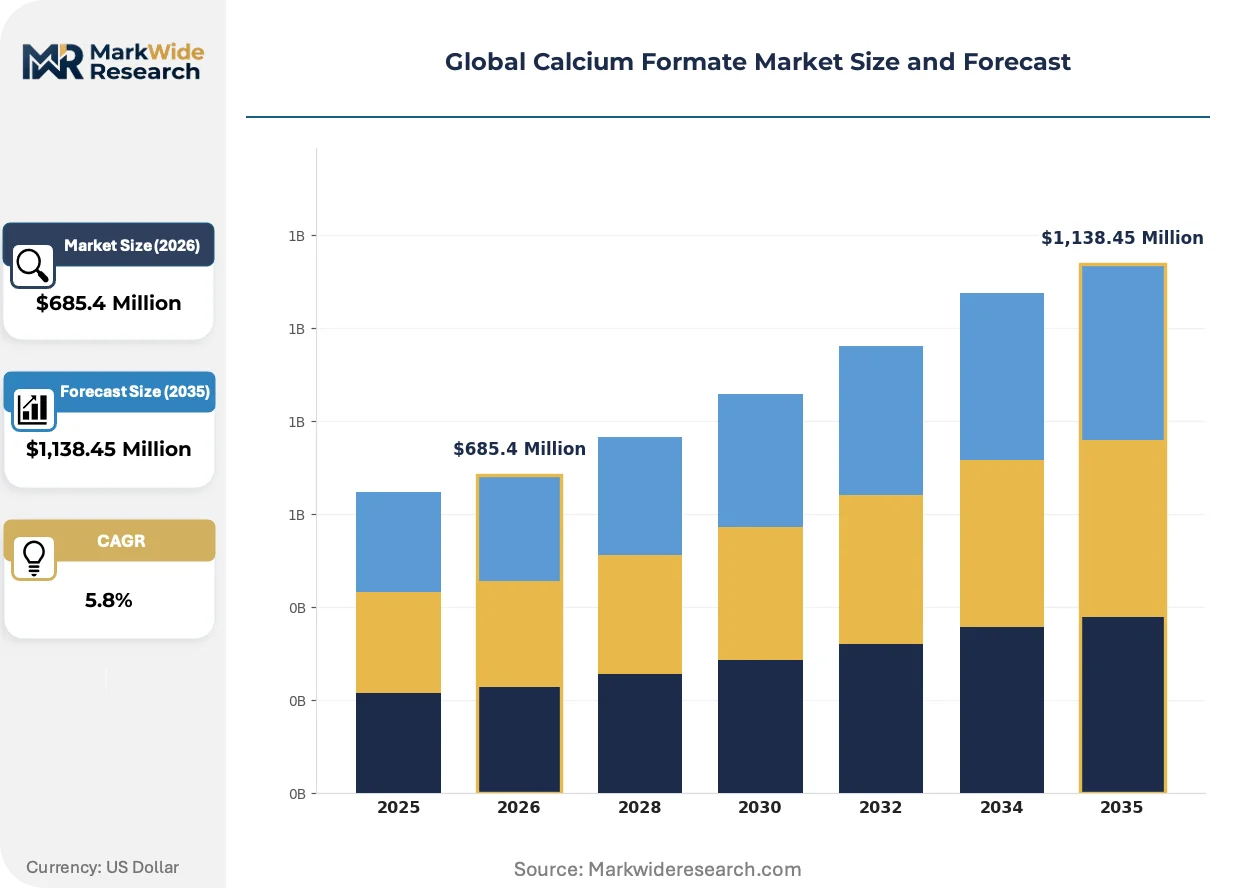
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Construction, Agriculture, Oil & Gas, Feed Additives Product Type: Granular, Powder, Liquid, Tablet End User: Construction Companies, Farmers, Chemical Manufacturers, Animal Feed Producers Packaging Type: Bags, Drums, Bulk, Boxes |
| Companies Covered | Zibo Ruibao Chemical Co. Ltd., Shandong Baoyuan Chemical Co. Ltd., LANXESS, American Elements, SIDLEY CHEMICAL CO. LTD., Perstorp Holding AB, Henan Botai Chemical Building Material Co. Ltd., Minerals Technologies Inc., Chongqing Chuandong Chemical (Group) Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Calcium Formate Market Shifts & Advancements
Controlled crystallization processes and digital supply chain verification are redefining product differentiation in calcium formate manufacturing. These innovations separate commodity producers from premium-positioned suppliers capable of serving automated industrial systems.
Continuous crystallization technology with real-time particle size monitoring is virtualizing quality control in calcium formate production. Major feed mill operators in Germany and the Netherlands are specifying granular grades with sub-2% dust fraction for automated dosing lines. This precision is compressing the addressable market for standard powder grades while expanding margin pools for engineered particle morphology.
The EU Green Deal's carbon border adjustment mechanism is reshaping import economics for construction-grade additives. Suppliers must now document Scope 1 and Scope 2 emissions through certified third-party verification to maintain market access. Western European construction chemical formulators are responding by consolidating procurement around REACH-certified producers with verified low-carbon manufacturing routes.
Direct manufacturer-to-feed-mill relationships are displacing traditional distributor intermediaries in the feed additive channel. Large integrated livestock operations in Brazil and Saudi Arabia are negotiating volume contracts with certified producers to secure supply continuity and price transparency. This disintermediation is most advanced in poultry production clusters where automated dosing systems require technical support that distributors no longer provide.
Global Calcium Formate Market Segmentation
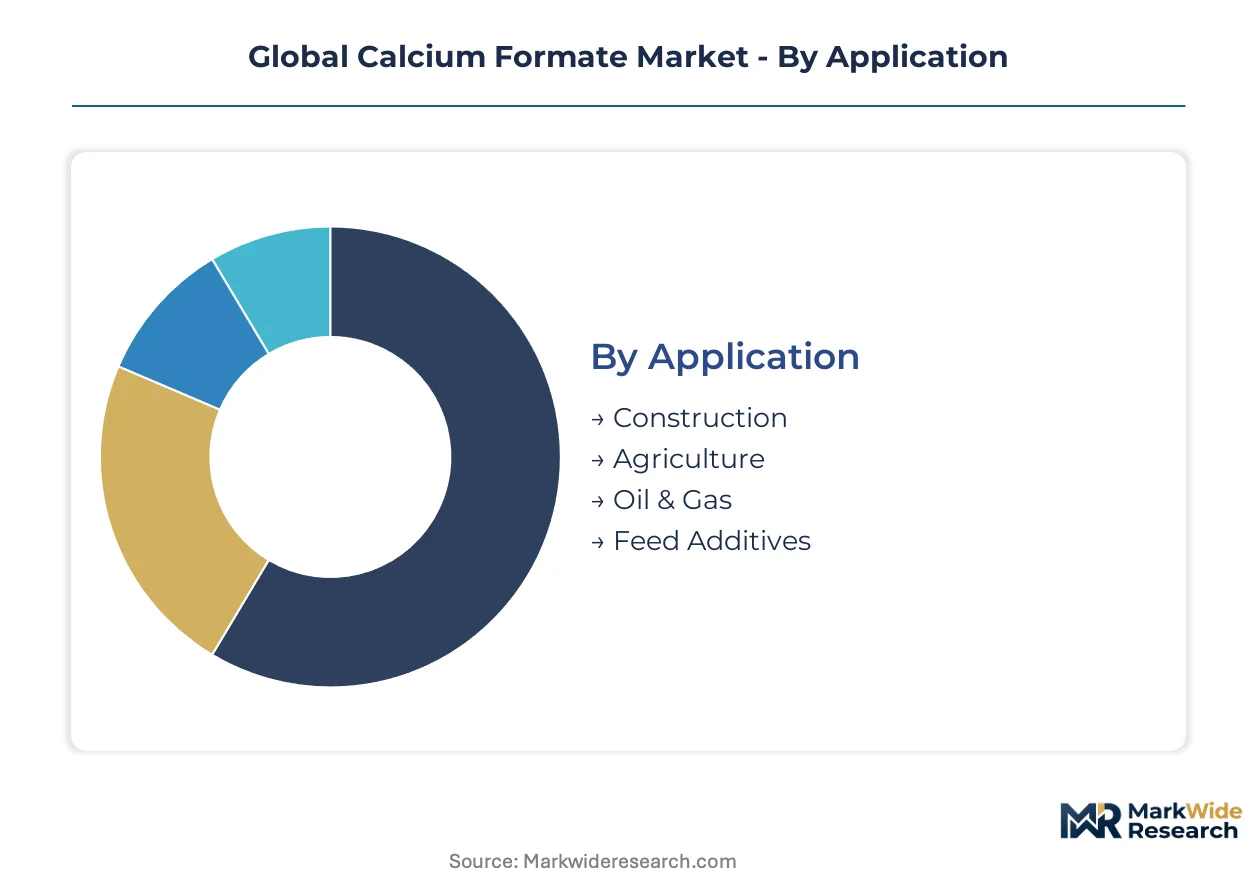
Segmentation in calcium formate markets separates commodity-grade suppliers from technical specialists capable of meeting automated dosing specifications and regulatory documentation requirements. Understanding these divides enables procurement strategies that align product form with end-use performance demands.
Application:
After-sales technical support intensity varies sharply across applications, with feed additive customers demanding formulation guidance and construction buyers prioritizing batch certification documentation.
- Construction:Calcium formate serves as an accelerating admixture in Portland cement systems, reducing setting times at low temperatures while enhancing early compressive strength development. Demand concentrates in Germany and Poland where infrastructure contractors specify cold-weather admixtures for year-round cement work. The EU Green Deal's embodied carbon tracking requirements pressure suppliers to document manufacturing emissions.
- Feed Additives:Poultry and swine producers substitute antibiotic growth promoters with organic acid salts, creating specification demand for low-dust granular grades compatible with automated dosing systems. Brazil and Saudi Arabia drive absorption as national regulators redirect procurement toward certified regional producers.
- Agriculture:Silage preservation and soil amendment applications absorb standard powder grades where dust tolerance permits manual handling protocols.
- Oil & Gas:Drilling fluid formulations utilize calcium formate as a shale stabilizer in high-temperature wellbore environments.
Construction holds the largest share; momentum sits with feed additives.
Product Type:
Cost tier differentiation separates engineered particle morphology from commodity powder output, with premium granular grades commanding margin multiples due to crystallization technology investments.
- Powder:Standard crystalline output with minimum 98% purity dominates volume absorption in dry mortar blending and manual feed supplementation. Chinese producers control approximately two-thirds of global powder-grade output, creating single-source vulnerability for European distributors lacking backward integration into carbon monoxide feedstock.
- Granular:Controlled crystallization yields low-dust particles with sub-2% fines fraction, enabling automated dosing accuracy in industrial-scale feed mills and construction chemical plants. REACH-certified supply chains anchor premium positioning for Western European formulators.
- Liquid:Aqueous solutions serve specialized leather tanning and textile processing applications where rapid dispersion outweighs solids handling economics.
- Tablet:Compressed forms target precision livestock supplementation in smaller-scale operations lacking automated equipment infrastructure.
Powder commands volume leadership; granular climbs the fastest as automation penetration deepens.
End User:
Customer type determines procurement channel structure, with integrated livestock operations disintermediating distributors through direct manufacturer contracts.
- Construction Companies:Infrastructure contractors in Vietnam and Indonesia generate unmet demand for accelerating admixtures as cement consumption expands across Southeast Asia buildout projects.
- Animal Feed Producers:Large integrated poultry operations in Brazil and Saudi Arabia negotiate volume contracts with certified producers to secure supply continuity and price transparency, bypassing traditional distributor intermediaries.
- Farmers:Smallholder silage preservation drives seasonal powder demand with minimal technical service requirements.
- Chemical Manufacturers:Downstream formulators source technical-grade material for leather tanning and textile auxiliary production.
Construction companies anchor current procurement volumes; animal feed producers gain share fastest through disintermediation.
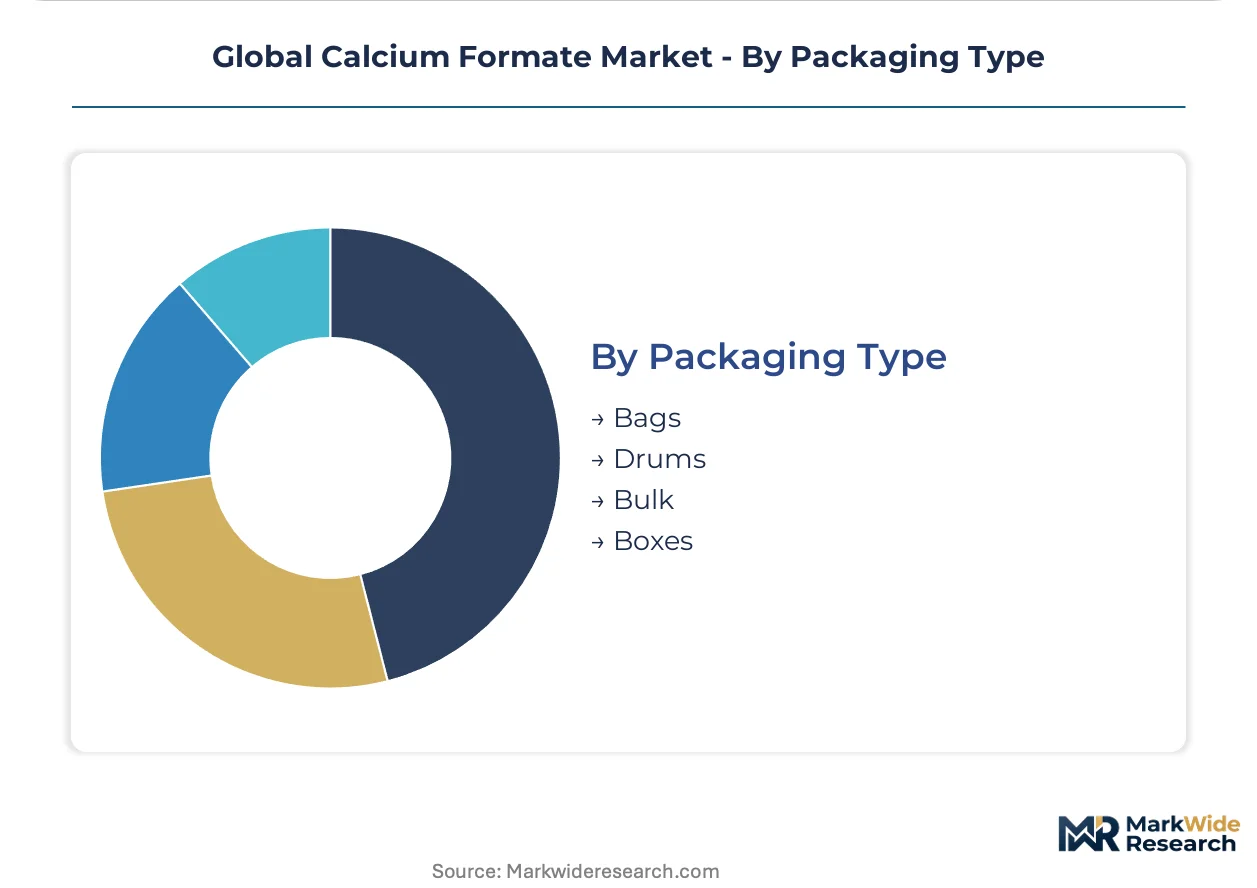
Packaging Type:
Supply chain configuration determines packaging economics, with bulk delivery systems penetrating highest-volume construction chemical plants while bagged formats retain flexibility for distributed feed mill networks.
- Bulk:Tanker and silo delivery systems minimize handling costs for major construction chemical formulators in Germany and the Netherlands operating continuous dry-mix production lines.
- Bags:Multi-wall paper and woven polypropylene formats dominate feed additive distribution where batch-scale flexibility and warehouse stacking stability prove critical.
- Drums:Steel and fiber containers serve liquid formulations and high-purity technical grades requiring contamination protection.
- Boxes:Corrugated retail formats target small-scale agricultural and specialty chemical applications with limited volume requirements.
Bags retain the largest installed base; bulk formats expand most quickly as construction chemical consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure anchors European calcium formate distribution, while China's Yangtze River Delta manufacturing belt concentrates global powder-grade output. Rail links connecting Zhengzhou to Hamburg via the New Eurasian Land Bridge are compressing transit times for construction-grade shipments.
China
Feed additive and construction chemical segments absorb domestic powder-grade production from Shandong and Jiangsu provinces. SAMR enforces GB standards governing heavy metal limits in feed-grade material. Zibo's chemical industrial park hosts integrated producers leveraging captive carbon monoxide feedstock for cost-competitive output.
Germany
Infrastructure contractors in Bavaria and North Rhine-Westphalia specify cold-weather accelerating admixtures for year-round cement work. ECHA dossier preparation and REACH re-registration compress the qualified supplier base. Construction chemical formulators in the Cologne-Düsseldorf corridor consolidate procurement around certified low-carbon supply chains.
United States
EPA guidelines under the Toxic Substances Control Act shape import thresholds for chemical purity documentation. The Houston Ship Channel handles bulk construction-grade arrivals for Gulf Coast dry-mix plants. Midwest feed mill operators are specifying dust-controlled granular grades for automated dosing lines.
Brazil
Poultry producers in São Paulo and Paraná states substitute antibiotic growth promoters with organic acid salts. ANVISA feed safety regulations redirect procurement toward certified regional producers. Integrated livestock operations in the southern agricultural belt negotiate direct volume contracts with qualified suppliers.
Saudi Arabia
SFDA import substitution policies are redirecting feed additive procurement toward certified regional producers. The King Abdullah Port on the Red Sea handles construction chemical imports for GCC infrastructure projects. Riyadh-based formulators are qualifying local manufacturing investments to serve domestic livestock operations.
Global Calcium Formate Market Competitive Landscape
On the supply side, the industry is bifurcated between commodity powder-grade suppliers and premium-positioned granular specialists. Chinese producers control approximately two-thirds of global powder output through integrated carbon monoxide feedstock access. Three archetypes dominate: integrated chemical conglomerates with captive raw material supply, specialty crystallization technology firms serving automated dosing systems, and regional construction chemical blenders sourcing technical-grade material. Competitive moves concentrate on REACH certification investments and controlled crystallization capacity expansion.
Within the integrated chemical tier, Zibo Ruibao Chemical Co. Ltd. and Shandong Baoyuan Chemical Co. Ltd. represent scale-driven Chinese producers with provincial industrial base positioning. LANXESS occupies a position exemplifying premium-tier Western European supply chain certification. Perstorp Holding AB sits within the specialty technology segment, representing granular-grade precision manufacturing archetypes.
| Leading Market Players |
|---|
| Zibo Ruibao Chemical Co. Ltd. |
| Shandong Baoyuan Chemical Co. Ltd. |
| LANXESS |
| American Elements |
| SIDLEY CHEMICAL CO. LTD. |
| Perstorp Holding AB |
| Henan Botai Chemical Building Material Co. Ltd. |
| Minerals Technologies Inc. |
| Chongqing Chuandong Chemical (Group) Co. Ltd. |
| Others |
Supply & Pricing Matrix
Zibo's chemical industrial park in Shandong Province anchors global powder-grade capacity, with captive carbon monoxide feedstock access translating directly into pricing power over European distributors lacking backward integration. This supply concentration enables Chinese producers to undercut non-integrated competitors while granular-grade specialists in Western Europe defend margin pools through REACH-certified positioning.
Pricing Analysis
Volume-discount tiering separates three distinct pricing levels across the market. Premium granular grades with sub-2% dust fractions command significant markups from automated feed mills in Germany and the Netherlands, while standard powder output competes on cost in dry mortar blending. Price differentiation rests on certification grade and crystallization technology investment. Cost compression in commodity powder tiers is intensifying as Brazilian and Saudi Arabian buyers consolidate procurement around certified regional producers. Smallholder agricultural operations show highest price sensitivity, whereas integrated livestock operations prioritize dosing accuracy over unit economics.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk assessment for construction-grade distributors. Production gravity centers on China, Germany, and Saudi Arabia, with the Yangtze River Delta and Shandong Province feeding global powder demand. Raw material dependencies include formic acid feedstock, carbon monoxide supply, and calcium carbonate sources. Single-source vulnerability pervades European markets where two-thirds of powder-grade output originates from Chinese producers. Distribution runs through Rotterdam's chemical handling infrastructure for Western European construction chemical formulators, while direct manufacturer contracts are displacing traditional distributor intermediaries in Brazil and Saudi Arabia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feed additive substitution represents an early-cycle expansion opportunity as poultry and swine producers across Brazil and Saudi Arabia accelerate organic acid salt adoption. Regulatory redirection toward certified regional producers creates white space for compliant manufacturing investments.
For Market Incumbents: Insulate margin position by deepening captive feedstock control over carbon monoxide supply and accelerating REACH re-registration investments before ECHA timeline compression eliminates mid-tier competitors. Sodium formate substitution in de-icing applications threatens calcium cation-dependent segments, requiring granular-grade capacity expansion to defend premium positioning in automated dosing systems. For New Entrants and Emerging Players: Build out certified production capacity in Saudi Arabia to capture SFDA import substitution policy benefits, targeting Riyadh-based formulators serving domestic livestock operations. Southeast Asia infrastructure buildout in Vietnam and Indonesia offers penetrable construction-grade demand as cement consumption expands. A technical service-led go-to-market approach differentiates against commodity powder traders lacking formulation support capabilities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors controlled crystallization specialists with proven automated dosing system integration. Long-term viability over a multi-year horizon rests on carbon border adjustment compliance and verified low-carbon manufacturing routes. Acquisition targets should demonstrate REACH-certified supply chains and granular-grade production capabilities. The signal to watch is ECHA substance evaluation outcomes that could disqualify non-compliant producers and consolidate the supplier base.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Monoxide Feedstock | Captive supply eliminates formic acid price volatility exposure for Shandong-based producers. |
| REACH Certification Investment | ECHA compliance secures preferred-partner status with Cologne-Düsseldorf construction chemical formulators. |
| Controlled Crystallization Capacity Expansion | Sub-2% dust fraction granular output commands premium positioning in Dutch automated feed mills. |
| Direct Manufacturer-to-Feed-Mill Contracts | Disintermediation captures margin pools previously allocated to Brazilian and Saudi Arabian distributors. |
| Regional Manufacturing Investment in Saudi Arabia | SFDA procurement redirection opens white space for King Abdullah Port-adjacent production facilities. |
Research Methodology
Operator-level perspectives from plant managers at Shandong and Jiangsu production facilities, procurement leads at German construction chemical formulators, distribution channel partners in Rotterdam's chemical handling infrastructure, and technical R&D directors specializing in crystallization technology anchored the qualitative base. Secondary validation drew from customs and trade data, Cefic construction chemical reports, SEC 10-K filings from listed chemical producers, and SAMR GB standards documentation. Bottom-up capacity assessments and top-down demand modeling were triangulated to reconcile volume estimates.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning grade tier, end-use industry, packaging format, and regional production hub. CAGRs were derived from production capacity trajectories, feed additive substitution elasticity estimates, and cement consumption forecasts. Industry-specific inputs included ECHA registration timelines, EU Green Deal embodied carbon tracking requirements, and SFDA import substitution policy implementation pace.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated Chinese producers expanding granular-grade capacity or European specialty chemical firms acquiring crystallization technology would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Chelating Agents Market
Additives
Metal Deactivators Market
Additives
Sodium Citrate Anhydrous Market
Additives
Global Lubricating Oil Additives Market
Additives
United States Citric Acid Market
Additives
Drilling Fluid Additives Market
Additives
Global Inorganic Corrosion Inhibitors Market
Additives
Grinding Aids Market
Additives
Sorbitan Esters Market
Additives
Propyl Gallate Market
Additives
Fluoropolymer Additives Market
Additives
Amino Acids Premixes Market
Additives
Texture Modifier Market
Additives
Refining Additives Market
Additives
Plastic Fillers Market
Additives
Volatile Corrosion Inhibitors Market