
 Global Matting Agents Market | 2026-2036
Global Matting Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Matting Agents Market Foresight
Waterborne coating formulation is fragmenting the legacy solvent-borne matting agent supply chain as automotive OEMs enforce stricter volatile organic compound limits. Evonik Industries AG leverages its synthetic silica R&D pipeline to anchor premium dispersion grades for European automotive refinish. PPG Industries Inc. competes through backward integration into specialty silica sourcing for its captive coating operations. Imerys SA dominates natural clay matting agent supply to construction coating manufacturers across Southern Europe.
Matting agents are finely divided particulate additives, typically 2-15 microns in median particle diameter, that induce controlled surface roughness to reduce gloss values from 90+ GU to below 10 GU at 60° incidence. Manufacturers disperse these additives into liquid coating systems where light scattering at the film surface produces the desired matte aesthetic. Synthetic silica commands the largest value share among product types due to its superior transparency and scratch resistance in wood and industrial coatings. Powder deployment formats lead volume consumption because of easier handling and longer shelf stability, though dispersion formats gain traction in just-in-time automotive coating lines. Polymer beads represent the fastest-expanding product category as regulatory pressure on silica dust exposure intensifies across multiple jurisdictions.
REACH in Europe restricts crystalline silica content in workplace formulations, while EPA oversight in the United States governs hazardous air pollutant thresholds in coating manufacturing facilities. China's MEE enforces emission standards that favor waterborne systems incorporating compatible matting agents. Stakeholders must monitor evolving dust exposure limits and substitution mandates that will determine which particulate technologies retain market access across major manufacturing regions.
Market Dynamics
Waterborne coating formulation mandates are compressing legacy solvent-borne matting agent architectures as automotive OEMs enforce stricter volatile organic compound limits across manufacturing footprints.
Growth Catalysts
- REACH crystalline silica limits:German paint producers accelerate silica-based matting agent procurement under ECHA workplace exposure mandates, pulling premium dispersion grades into automotive refinish.
- China's MEE emission standards:Coastal manufacturing provinces in Guangdong and Jiangsu favor waterborne systems incorporating compatible matting agents for automotive coating output scaling.
- Synthetic silica R&D pipelines:European coating formulators invest in transparency-optimized particulate technologies for wood and industrial coating segments demanding sub-10 GU gloss values.
Market Restraints
- Silica dust exposure regulation:OSHA and REACH workplace limits on crystalline silica content force reformulation investments, elevating compliance costs for legacy powder deployment formats.
- Natural clay supply concentration:Imerys SA dominates Southern European construction coating supply, creating single-source vulnerability for regional manufacturers.
- Polymer bead performance ceiling:Scratch resistance and transparency gaps versus synthetic silica limit adoption in premium wood coating segments despite regulatory tailwinds.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Domestic manufacturing incentives create white space for local silica-based matting agent production serving Asian coating formulators.
- Just-in-time automotive lines:Dispersion format matting agents gain traction as Tier-1 suppliers eliminate powder handling complexity from high-throughput coating operations.
- EU Green Deal circularity mandates:Bio-based polymer bead technologies align with sustainable procurement frameworks emerging across European industrial coating buyers.
Industry Challenges
- Formulation chemist scarcity:Waterborne dispersion stability expertise sits concentrated with senior technologists at major coating houses, constraining mid-tier competitor R&D velocity.
- REACH registration timelines:New silica-based additive chemistries face 18-24 month ECHA evaluation windows, delaying product commercialization against fast-moving automotive specification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Matting Agents Market |
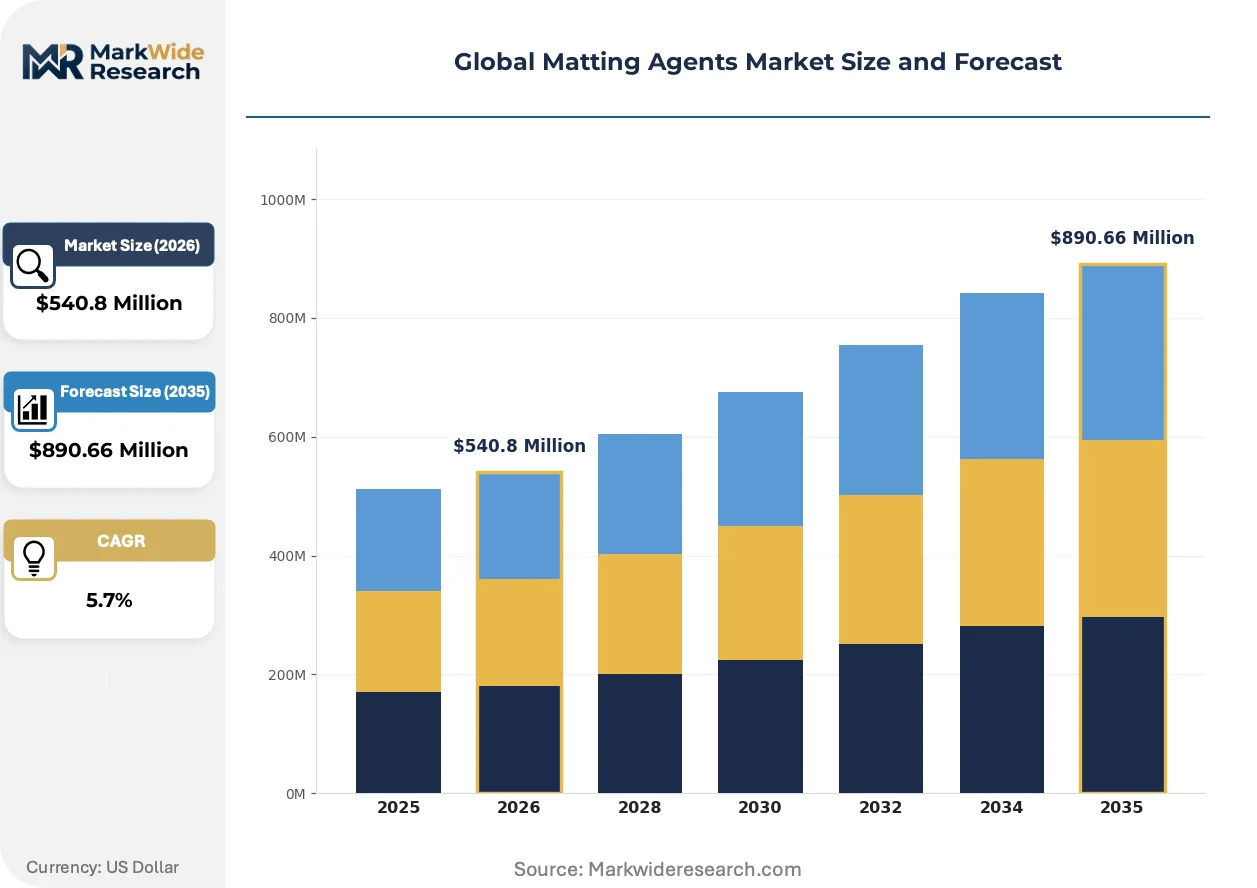
| Market Size in 2026 | $540.8 Million |
| Market Size in 2035 | $890.66 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Silica, Natural Clay, Talc, Calcium Carbonate, Polymer Beads, Hollow Glass Microspheres Application: Coatings, Printing Inks, Plastic Films, Adhesives, Construction Materials, Paper Products End User Industry: Packaging Manufacturers, Paint Producers, Textile Producers, Electronics Fabricators, Automotive Component Makers, Consumer Goods Producers Deployment Format: Powder, Dispersion, Paste, Granules, Emulsion |
| Companies Covered | Evonik Industries AG, PPG Industries Inc., Imerys SA, Huntsman International LLC, W. R. Grace & Co.-Conn., BYK Additives & Instruments, Lubrizol Corporation, J.M. Huber Corporation, allnex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Matting Agents Market Shifts & Advancements
Particulate matting technology is fragmenting across three vectors: synthetic silica transparency optimization, polymer bead dust-exposure substitution, and dispersion format logistics integration.
Synthetic silica with engineered pore structures is migrating from premium wood coating segments into mass-market industrial applications as Chinese automotive OEMs specify 60° gloss values below 5 GU for interior trim. Tier-2 coating formulators in Hebei and Shandong provinces adopt these grades at compressed implementation cycles, collapsing the traditional 36-month specification lag.
REACH crystalline silica workplace exposure limits are forcing powder-to-dispersion format conversion across European coating manufacturing facilities. ECHA's 2023 revised occupational exposure threshold compresses permissible crystalline silica content in workplace formulations, pushing automotive refinish operations toward liquid dispersion matting agents with pre-stabilized particle distributions.
Automotive OEM procurement teams are consolidating qualified supplier lists from twelve to four vendors per coating category, privileging backward-integrated matting agent producers with captive silica sourcing. This concentration is most visible in Germany's Baden-Württemberg automotive cluster, where PPG Industries Inc. and BASF SE coating operations enforce single-source dispersion supply agreements for just-in-sequence paint shop operations.
Global Matting Agents Market Segmentation
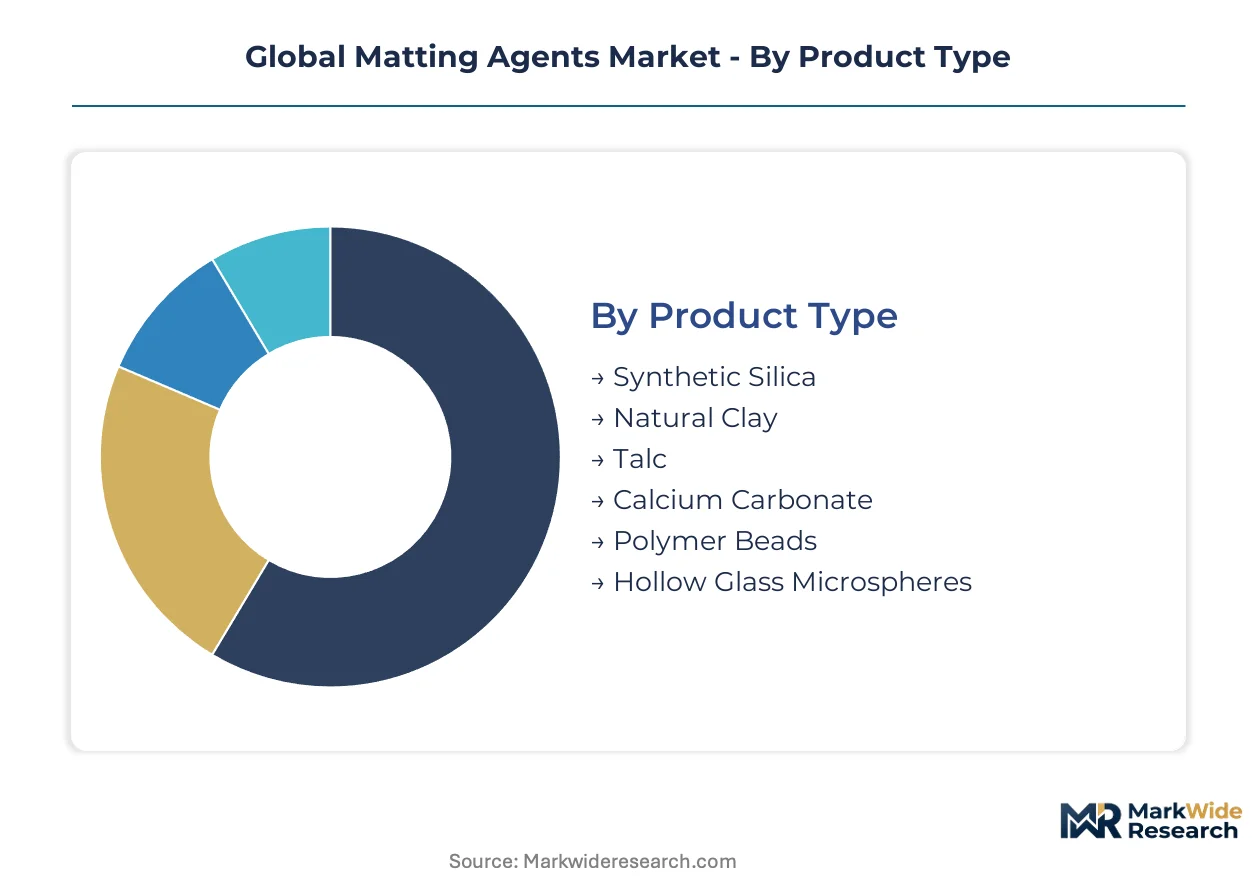
Matting agent procurement cycles vary dramatically by product chemistry and deployment format, with powder formats turning inventory in weeks while dispersion grades lock in annual supply agreements. Automotive coating specifications now compress these cycles further as OEMs consolidate qualified supplier lists.
Product Type:
Synthetic silica and natural clay command the longest procurement lead times due to mining and synthesis complexity, while polymer beads and hollow glass microspheres turn faster through toll manufacturing networks.
- Synthetic Silica:Engineered precipitated silica with controlled pore structures delivers superior transparency and scratch resistance for sub-10 GU gloss specifications. Demand concentrates in Germany's automotive refinish sector where REACH crystalline silica limits force premium dispersion grade adoption.
- Polymer Beads:Cross-linked organic particulates eliminate respirable silica dust exposure in workplace formulations. Expansion concentrates in European industrial coating operations facing ECHA occupational threshold compression.
- Natural Clay:Hydrous aluminum silicate matting agents serve construction coating cost tiers in Southern Europe.
- Talc:Magnesium silicate particulates anchor economy-grade industrial coatings in Asian manufacturing provinces.
- Calcium Carbonate:Ground mineral fillers provide basic matting functionality in paper and construction applications.
- Hollow Glass Microspheres:Low-density spherical additives enable weight-sensitive applications in automotive plastics.
Synthetic silica dominates installed base. Polymer beads are where expansion concentrates.
Application:
Coatings applications absorb the highest absolute volume, though printing inks and plastic films turn inventory faster through just-in-time delivery contracts.
- Coatings:Liquid and powder coating systems incorporate matting agents to control 60° gloss values across wood, metal, and plastic substrates. Waterborne architectural coatings in China's Guangdong province drive silica dispersion consumption as MEE emission standards tighten.
- Printing Inks:Gravure and flexographic ink formulations deploy micronized particulates for matte paper and film finishes. Packaging converters in India's Maharashtra state favor polymer bead dispersions for food-contact compliance.
- Plastic Films:Extruded and cast films integrate matting masterbatches for consumer electronics and automotive interior applications.
- Adhesives:Pressure-sensitive and structural adhesives use controlled surface roughness for bonding optimization.
- Construction Materials:Cementitious systems and decorative concrete employ talc and calcium carbonate for aesthetic control.
- Paper Products:Coated and uncoated papers achieve matte finishes through mineral filler selection.
Coatings applications anchor volume share. Printing inks and plastic films are climbing the fastest.
End User Industry:
Paint producers and packaging manufacturers operate on opposing procurement rhythms, with coating houses locking annual silica contracts while packaging converters spot-buy dispersion grades.
- Paint Producers:Industrial and automotive coating formulators specify matting agent particle size distributions to achieve target gloss values. Germany's Baden-Württemberg automotive cluster demands REACH-compliant dispersion formats with pre-stabilized distributions.
- Packaging Manufacturers:Flexible packaging and label converters prioritize food-contact safe polymer bead technologies. European flexible packaging operations facing EU Green Deal circularity mandates evaluate bio-based particulate alternatives.
- Automotive Component Makers:Interior trim and exterior body panel coatings specify ultra-low gloss finishes below 5 GU.
- Electronics Fabricators:Consumer device housings and displays require fingerprint-resistant matte surfaces.
- Textile Producers:Synthetic leather and technical fabrics incorporate matting agents for tactile and visual effects.
- Consumer Goods Producers:Appliances and furniture manufacturers specify consistent matte aesthetics across product lines.
Paint producers dominate technical specification influence. Packaging manufacturers are gaining share fastest.
Deployment Format:
Powder formats maintain the broadest geographic reach through stable shelf life, while dispersion and emulsion formats capture premium pricing in automated coating lines.
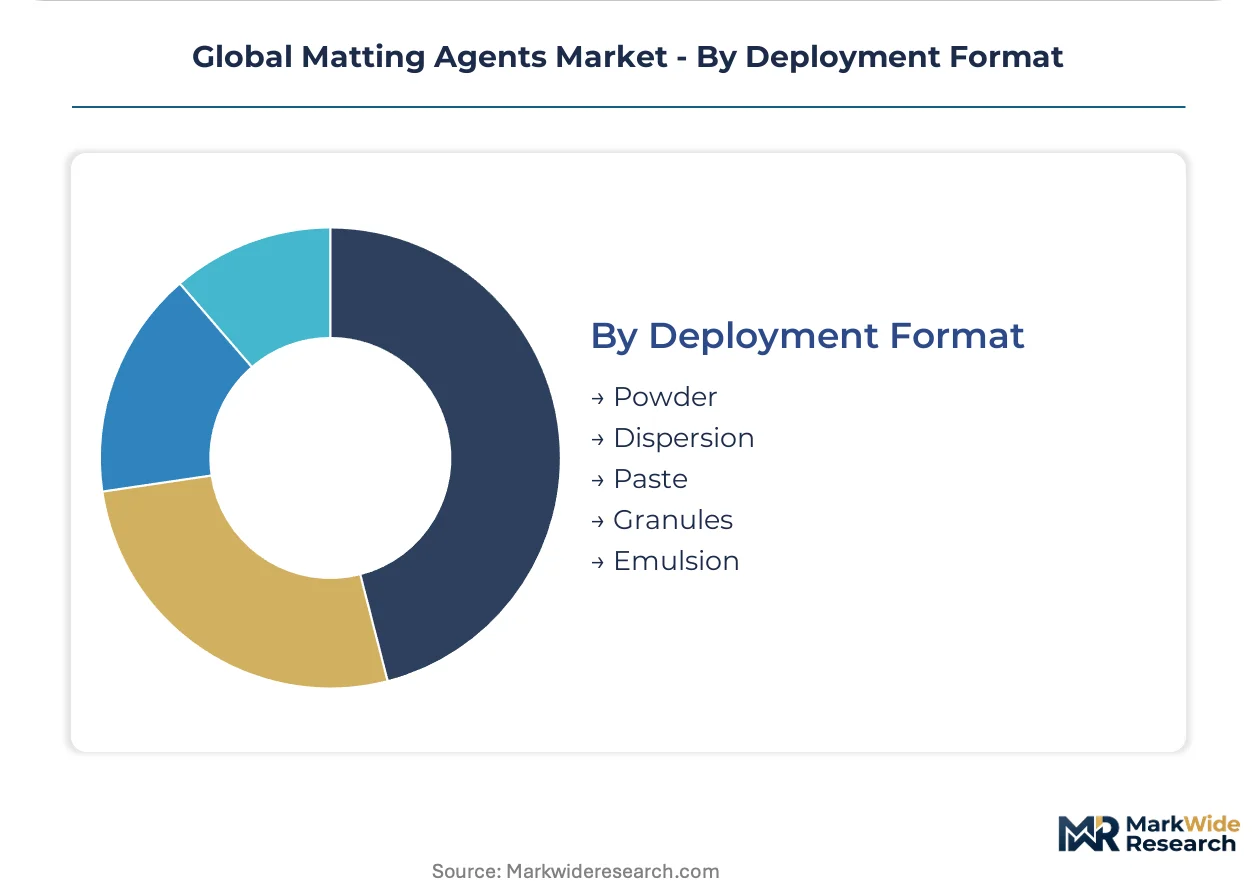
- Powder:Dry particulate formats enable long-distance logistics and extended warehouse storage without settling or agglomeration. Powder handling infrastructure in legacy European coating facilities faces OSHA and REACH dust exposure compliance investments.
- Dispersion:Pre-dispersed liquid concentrates eliminate on-site powder handling and ensure batch-to-batch consistency. Automotive Tier-1 suppliers in Germany's just-in-sequence paint shops mandate dispersion formats to eliminate powder contamination risks.
- Paste:High-solids concentrates serve small-batch custom coating operations.
- Granules:Dust-free handling formats bridge powder convenience with dispersion performance.
- Emulsion:Water-based liquid carriers align with waterborne coating system compatibility requirements.
Powder formats dominate installed base. Dispersion formats are where specification migration concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German matting agent exports flow predominantly into automotive coating operations across China's coastal manufacturing provinces, establishing the primary trade-flow corridor for premium silica dispersion grades.
China
Automotive coating output in Guangdong and Jiangsu provinces scales rapidly as domestic OEMs specify ultra-low gloss finishes below 5 GU for interior trim applications. MEE emission standards tighten waterborne system mandates, pulling compatible silica dispersions into high-volume procurement cycles. Tier-2 formulators in Hebei and Shandong provinces collapse traditional 36-month specification lags through accelerated adoption of engineered pore-structure silica.
Germany
Paint producers in Baden-Württemberg expand silica-based matting agent procurement under REACH crystalline silica workplace exposure mandates from ECHA. Automotive refinish operations enforce single-source dispersion supply agreements for just-in-sequence paint shop operations. Evonik Industries AG anchors premium dispersion grade supply from its synthetic silica R&D pipeline serving the regional automotive cluster.
United States
OSHA workplace limits on crystalline silica content force reformulation investments across legacy powder handling infrastructure in Midwest coating facilities. EPA hazardous air pollutant thresholds govern coating manufacturing operations, elevating compliance costs for solvent-borne matting agent architectures. Automotive OEM procurement teams in Michigan and Ohio consolidate qualified supplier lists from twelve to four vendors per coating category.
India
Domestic manufacturing incentives under the PLI scheme for specialty chemicals create white space for local silica-based matting agent production serving Asian coating formulators. Packaging converters in Maharashtra state favor polymer bead dispersions for food-contact compliance in flexible packaging operations. Maharashtra and Gujarat industrial corridors attract toll manufacturing networks for faster-turn polymer bead and hollow glass microsphere production.
France
Construction coating manufacturers across Southern Europe rely on natural clay matting agent supply from Imerys SA operations with significant French production footprint. EU Green Deal circularity mandates push bio-based polymer bead technologies into sustainable procurement frameworks across industrial coating buyers. Auvergne-Rhône-Alpes and Hauts-de-France regions concentrate formulation expertise for waterborne architectural coating segments.
Global Matting Agents Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered market structure where backward-integrated coating houses and independent additive suppliers occupy distinct strategic positions. The vendor base concentrates around three archetypes: synthetic silica technology leaders, natural mineral suppliers with mining assets, and polymer bead specialists addressing dust-exposure substitution demand. Dominant competitive moves include capacity expansion in dispersion format production and geographic licensing agreements for regional toll manufacturing networks.
Among Germany-based chemical conglomerates, Evonik Industries AG and BASF SE exemplify the backward-integrated archetype with captive silica sourcing and coating operations. PPG Industries Inc. represents the multinational coating house model with in-house matting agent production serving proprietary formulation requirements. Imerys SA anchors the natural mineral supplier tier with mining-integrated clay matting agent production for construction coating segments across Southern Europe.
| Leading Market Players |
|---|
| Evonik Industries AG |
| PPG Industries Inc. |
| Imerys SA |
| Huntsman International LLC |
| W. R. Grace & Co.-Conn. |
| BYK Additives & Instruments |
| Lubrizol Corporation |
| J.M. Huber Corporation |
| allnex |
| Others |
Supply & Pricing Matrix
Guangdong province's silica dispersion capacity expansion directly compresses premium-grade pricing power for European automotive coating suppliers. REACH compliance investments at German manufacturing facilities elevate cost bases, while Chinese waterborne system mandates pull procurement toward lower-cost dispersion formats.
Pricing Analysis
Synthetic silica with engineered pore structures commands substantial premiums over legacy precipitated grades, while polymer bead technologies price at mid-tier levels despite regulatory tailwinds. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant dispersions from powder formats and basic mineral fillers. Price differentiation centers on certification grade and volume scale, with automotive OEM procurement teams extracting concessions through consolidated supplier lists. Cost compression in powder formats is intensifying because OSHA and ECHA dust exposure limits force handling infrastructure investments. Mid-tier coating formulators exhibit highest price sensitivity, while automotive refinish operations absorb premiums for just-in-sequence supply assurance.
Supply Chain Analysis
REACH crystalline silica workplace exposure limits function as de facto export controls on legacy powder formats, restricting cross-border flows of non-compliant particulate technologies. Manufacturing concentrates in Germany, China, and India, with synthetic silica synthesis anchored in German chemical clusters and dispersion toll manufacturing expanding through Indian industrial corridors. Raw material dependencies rest on sodium silicate feedstocks, specialized precipitation reactor equipment, and surface treatment chemistries. Single-source vulnerability concentrates around Imerys SA's Southern European clay mining operations. Distribution runs through qualified supplier agreements with automotive OEM procurement teams and annual contracts with coating formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment protects incumbent positions. ECHA evaluation timelines and REACH registration requirements create structural barriers that compound over successive specification cycles.
For Market Incumbents: Harden dispersion format capacity in Baden-Württemberg and Guangdong to capture specification migration away from powder handling. Deepen backward integration into specialty silica sourcing to defend margin position against polymer bead substitution threats. Prioritize certification investment for bio-based polymer bead technologies ahead of EU Green Deal circularity mandates tightening.
For New Entrants and Emerging Players: India's Maharashtra and Gujarat industrial corridors present underpenetration white space for local silica-based matting agent production under PLI scheme incentives. Target toll manufacturing partnerships with polymer bead specialists to bypass ECHA registration timelines. Pursue food-contact compliance positioning with packaging converters seeking polymer bead dispersions for flexible film applications.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because REACH and OSHA exposure limits continuously elevate compliance costs that favor scaled incumbents with dedicated regulatory affairs capabilities. Acquisition targets should display captive silica sourcing and established automotive OEM qualification status. Monitor ECHA crystalline silica threshold revisions as the critical inflection signal for dispersion format adoption acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Silica Sourcing | PPG Industries Inc. secures captive supply for automotive refinish operations against Imerys SA clay concentration. |
| Capacity Expansion in Dispersion Format Production | Evonik Industries AG anchors premium grades for German automotive cluster just-in-sequence paint shop requirements. |
| Green Manufacturing Transition to Bio-based Polymer Beads | European industrial coating buyers align procurement with EU Green Deal circularity mandates emerging across member states. |
| Long-term Supply Agreement with Automotive OEMs | Consolidated supplier lists from twelve to four vendors per coating category privilege backward-integrated producers. |
| Joint Venture for Regional Toll Manufacturing Networks | India's PLI scheme incentives attract faster-turn polymer bead and hollow glass microsphere production partnerships. |
Research Methodology
Initial hypotheses were tested against primary input from coating formulator R&D directors, automotive OEM procurement managers, specialty chemical plant managers, and regulatory affairs leads at ECHA-registered entities, then refined through secondary validation. Sources included customs and trade flow databases, Cefic sector reports, SEC 10-K filings from listed chemical conglomerates, and REACH registration dossiers. Bottom-up volume estimates from application-level consumption patterns were triangulated against top-down market sizing from producer revenue disclosures.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by product chemistry, deployment format, end-use industry, and regional production hub. CAGRs were derived from trend extrapolation of specification cycle compression and regulatory adoption curves. Forecast inputs incorporated automotive coating output scaling in China's coastal provinces and REACH crystalline silica workplace exposure threshold enforcement timelines.
Practitioners should monitor ECHA occupational exposure limit revisions, MEE emission standard tightening, and automotive OEM gloss specification shifts for early signals requiring forecast recalibration. Material shifts in silica dust exposure regulation stringency or waterborne coating mandate acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Chelating Agents Market
Additives
North America Paints and Coatings Additives Market
Additives
Ammonium Acetate Market
Additives
Refining Additives Market
Additives
Global Low-Profile Additive Market
Additives
Polymeric Plasticizer Market
Additives
Asia-Pacific Fuel Additives Market
Additives
Asia Pacific Plastic Additives Market
Additives
Citric Acid Market
Additives
Global Anti-Fog Additives Market
Additives
Grease Additives Market
Additives
Antimicrobial Ingredients Market
Additives
Citrate Ester Market
Additives
Antiknock Agents Market
Additives
Octane Improver Fuel Additives Market
Additives
Fluoropolymer Additives Market