
 Anti-Redeposition Polymer Additives for Short-Wash Cycles Market | 2026-2036
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market Insights
Polymer formulation expertise is redrawing competitive boundaries in this specialty chemicals niche. BASF leverages its integrated acrylic acid chain to control raw material quality for polycarboxylate production. Dow anchors its position through polyethylene glycol platforms optimized for cold-water solubility. Nouryon competes with amphoteric polymer architectures that perform across pH extremes in commercial wash tunnels.
Anti-redeposition polymer additives for short-wash cycles are water-soluble macromolecules, typically 2,000–50,000 Daltons in molecular weight, that adsorb onto fabric surfaces and suspended soils to prevent graying during abbreviated rinse phases. Polycarboxylates dominate volume due to cost-performance balance in liquid detergent matrices, while polyvinylpyrrolidone variants capture premium positioning in healthcare textile cleaning where thermal stability and biocompatibility command higher formulation spend. Powder and liquid forms split demand along regional supply chain conventions, with concentrated liquids gaining share in European commercial laundries equipped for automated dosing systems.
EPA Safer Choice criteria and EU REACH restrictions on phosphonate builders are redirecting formulator procurement toward polymeric alternatives with favorable ecotoxicological profiles. Germany's Federal Environment Agency evaluates biodegradability thresholds for laundry chemicals discharged into municipal wastewater streams. Stakeholders must monitor pending revisions to ISO 14034 environmental technology verification protocols, as these will determine which polymer chemistries qualify for preferential procurement by institutional buyers.
Market Dynamics
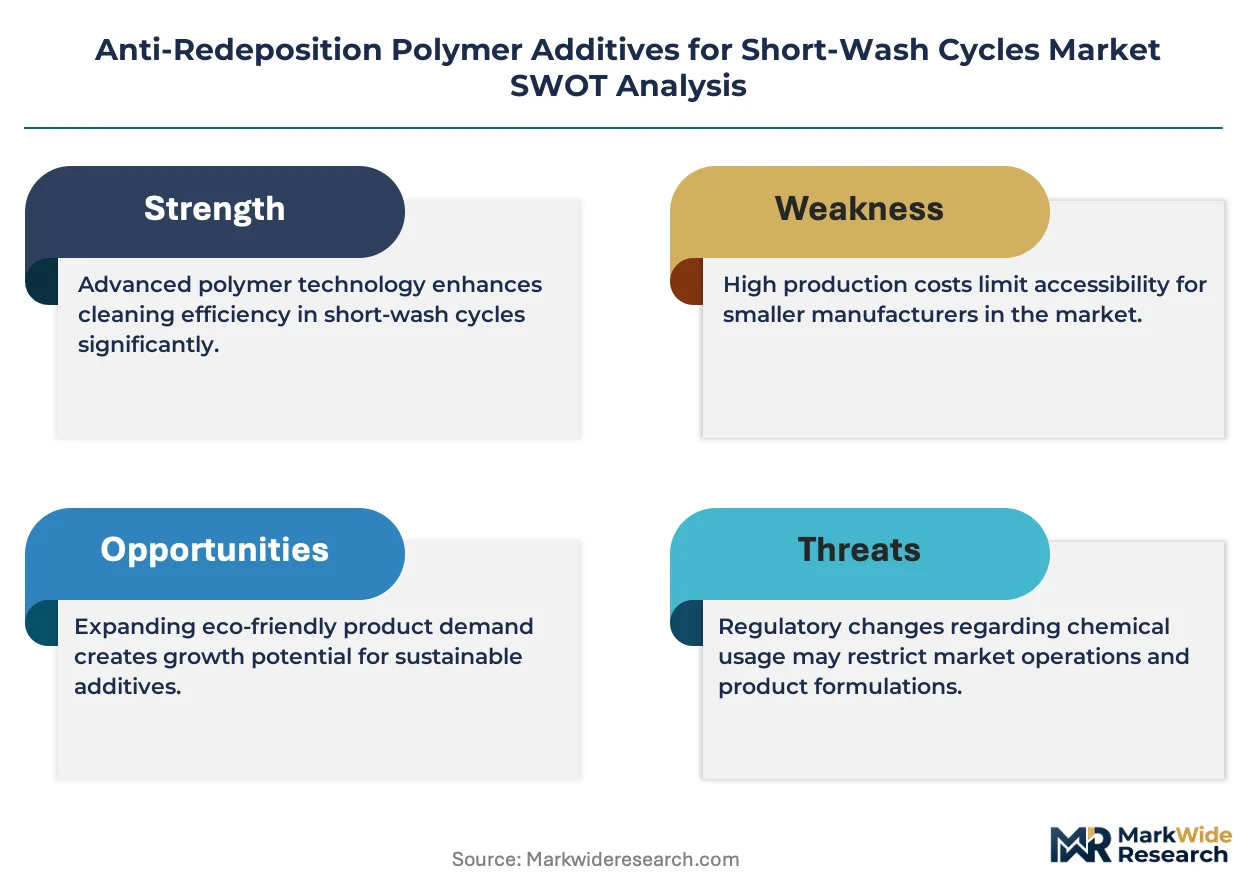
Water-efficiency mandates across industrial laundry operations are compressing wash cycle durations, forcing formulators to engineer polymer additives that maintain soil suspension performance in abbreviated rinse phases where traditional chemistry fails.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Tightening formulation requirements for home-care chemicals are redirecting procurement toward polymeric alternatives with verified ecotoxicological profiles, expanding addressable demand for polycarboxylate and amphoteric architectures.
- Commercial laundry automation:Automated dosing systems in European industrial laundries are concentrating demand for concentrated liquid polymer formulations compatible with precision-metering infrastructure.
- Healthcare textile cleaning:Thermal stability and biocompatibility requirements in hospital and pharmaceutical laundering operations are pulling premium polyvinylpyrrolidone variants into specialized formulations.
Market Restraints
- Acrylic acid feedstock volatility:Polycarboxylate production depends on petrochemical-derived monomers exposed to crude oil price swings, compressing margin predictability for integrated and non-integrated producers alike.
- REACH authorization complexity:Polymer registration dossiers for novel molecular architectures face extended evaluation timelines at ECHA, delaying commercialization of next-generation biodegradable variants.
- Phosphonate builder residual demand:Legacy formulations in price-sensitive institutional segments retain incumbent chelating agents despite regulatory pressure, slowing polymer substitution rates in municipal and correctional facility laundries.
Strategic Opportunities
- ISO 14034 environmental technology verification:Pending protocol revisions will create preferential procurement pathways for polymer chemistries achieving third-party biodegradability certification, opening institutional buyer segments in Germany and the Netherlands.
- Cold-water solubility platforms:Polyethylene glycol-optimized architectures enable performance in energy-reduced wash programs, aligning with utility rebate programs for commercial laundries in California and Texas.
- Automotive sector industrial laundries:Underpenetrated demand from precision-cleaning operations for reusable shop towels and uniforms in Stuttgart and Wolfsburg manufacturing clusters offers specialized formulation contracts.
Industry Challenges
- Polymer characterization expertise scarcity:Formulation chemists with molecular weight distribution optimization skills for 2,000–50,000 Dalton architectures are concentrated among legacy surfactant specialists, constraining R&D velocity for mid-tier additive suppliers.
- pH-performance validation:Amphoteric polymer architectures require extensive testing across commercial wash tunnel conditions, extending certification timelines for commercial laundry equipment compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Redeposition Polymer Additives for Short-Wash Cycles Market |
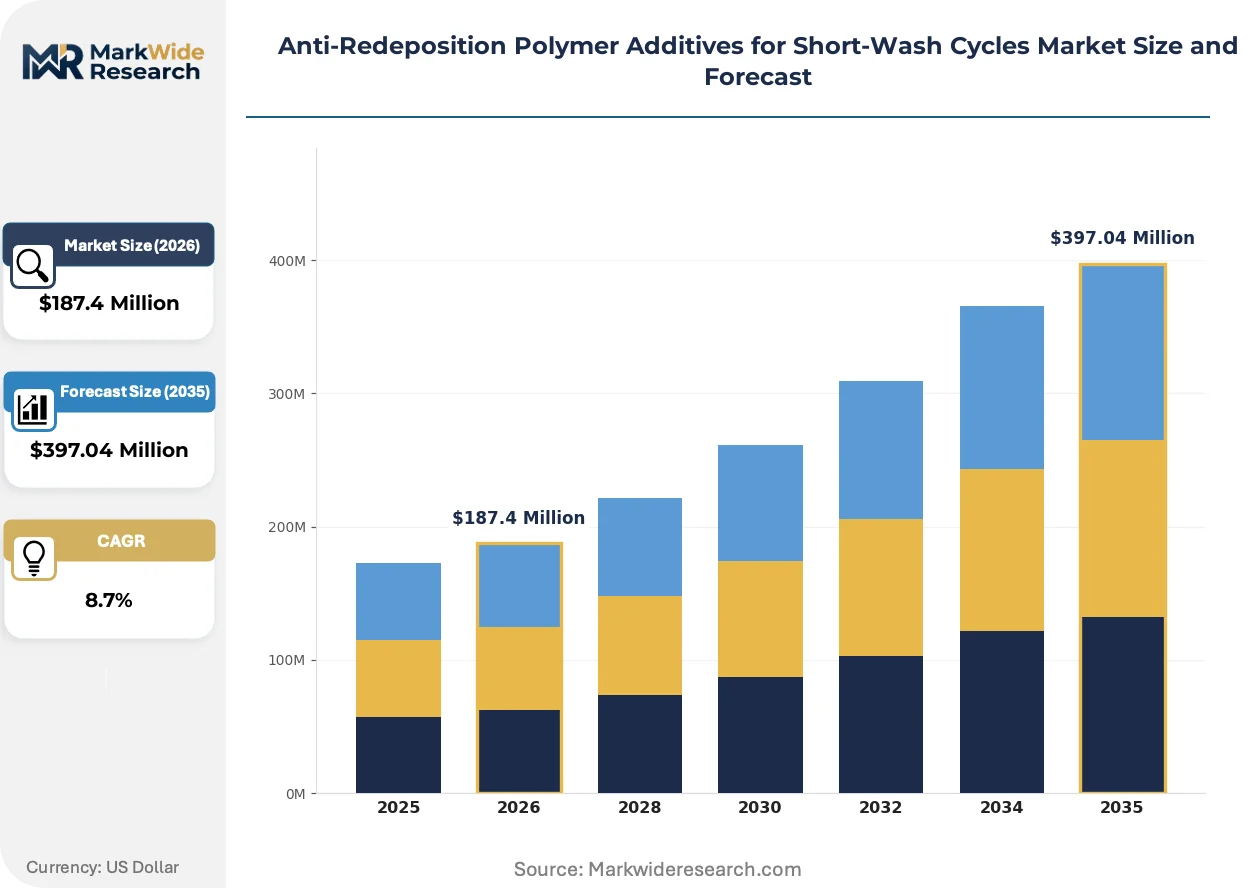
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarboxylates, Polyvinylpyrrolidones, Polyethylene Glycols, Sodium Citrates, Carboxymethyl Cellulose Application: Commercial Laundries, Residential Laundry Machines, Hospitality Laundry Services, Healthcare Textile Cleaning, Institutional Laundry End User: Laundry Service Providers, Textile Manufacturers, Hospitality Facilities, Medical Laboratories, Educational Institutions Form: Liquid, Powder, Granules, Tablets, Concentrate |
| Companies Covered | BASF, Dow, Nouryon, Solvay, Clariant, SNF, Ashland, Lubrizol, Kemira, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market Trends and Innovations
Formulation chemistry is fragmenting into performance-specialized architectures as regulatory pressure and end-use diversification outpace the capabilities of legacy universal polymer platforms.
Biodegradable polycarboxylate alternatives synthesized from bio-based acrylic acid feedstocks are decomposing the historical cost-performance advantage of petroleum-derived standards. Industrial laundries in Germany and the Netherlands are piloting these architectures under Federal Environment Agency discharge monitoring protocols. The structural consequence is decomposing volume concentration among incumbent suppliers lacking fermentation-derived monomer integration.
EPA Safer Choice criteria revisions are tightening allowable ecotoxicological thresholds for laundry chemicals discharged into municipal wastewater. Formulators serving North American commercial laundries are reformulating to eliminate phosphonate builder residuals entirely. Liquid detergent matrices optimized for automated dosing systems are capturing disproportionate qualification effort from institutional procurement teams.
Consolidated buying by multi-site hospitality and healthcare chains is compressing supplier negotiation cycles from annual to quarterly terms. Distributor relationships are being displaced by direct specification contracts between polymer additive producers and national laundry service operators. This concentration is most visible in the United States, where Aramark and Sodexo procurement teams are centralizing detergent formulation approvals across property portfolios.
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market Segmentation
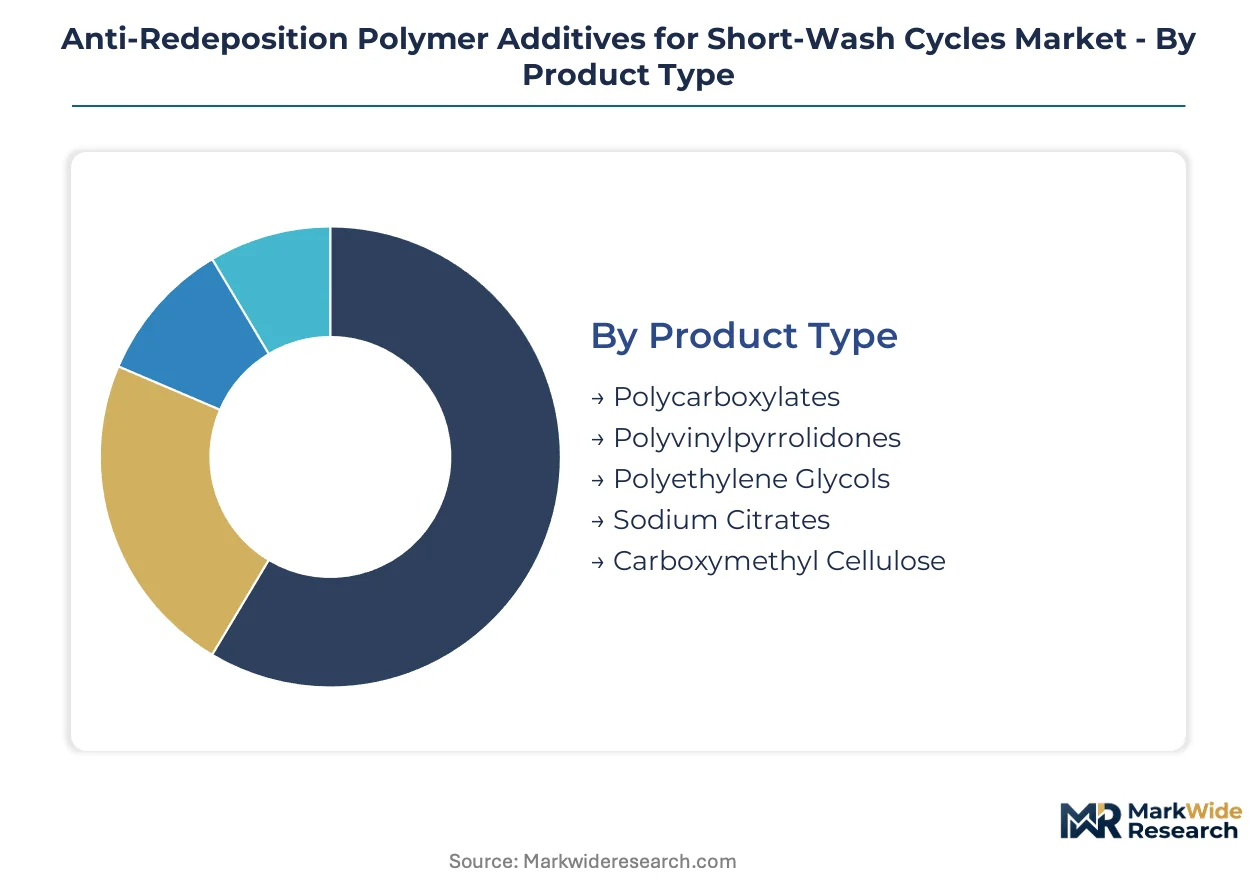
Polymer additive performance requirements diverge sharply across wash cycle configurations and end-use compliance standards. Channel dynamics in this market are dictated by dosing infrastructure compatibility and regulatory discharge protocols rather than conventional distribution economics.
Product Type:
Polycarboxylates and polyvinylpyrrolidones flow predominantly through liquid concentrate channels serving automated commercial laundries, while powder-form sodium citrates and carboxymethyl cellulose retain legacy distribution through institutional procurement cooperatives.
- Polycarboxylates:Acrylic acid-derived architectures with molecular weights spanning 2,000–50,000 Daltons deliver cost-optimized soil suspension in liquid detergent matrices. Demand concentrates in German industrial laundries serving automotive manufacturing clusters, where Federal Environment Agency discharge monitoring favors biodegradable polycarboxylate variants over phosphonate builders.
- Polyvinylpyrrolidones:Amide-functionalized polymers exhibit thermal stability above 150°C and biocompatibility profiles required for healthcare textile protocols. Expansion concentrates in hospital and pharmaceutical laundering operations across Stuttgart and Wolfsburg, where sterilization cycle compatibility commands premium formulation spend.
- Polyethylene Glycols:Cold-water solubility platforms align with utility rebate programs for energy-reduced wash programs.
- Sodium Citrates:Chelating functionality derived from fermentation processes serves price-sensitive municipal facility segments.
- Carboxymethyl Cellulose:Cellulose-derived thickeners stabilize powder detergent matrices in legacy institutional supply chains.
Polycarboxylates dominate installed base. Polyvinylpyrrolidones are where expansion concentrates.
Application:
Cost tier stratification separates premium healthcare and hospitality specifications from economy-grade institutional contracts, with automation readiness determining polymer formulation selection.
- Commercial Laundries:High-volume tunnel washing operations in North America deploy precision-metering infrastructure requiring concentrated liquid polycarboxylate formulations. Water-efficiency mandates from EPA regional offices compress cycle durations, forcing polymer architectures that maintain soil suspension in abbreviated rinse phases.
- Healthcare Textile Cleaning:Thermal stability requirements for hospital linen sterilization cycles pull premium polyvinylpyrrolidone variants into specialized formulations. German pharmaceutical manufacturing clusters around Ludwigshafen and Leverkusen enforce biocompatibility certification exceeding standard commercial laundry protocols.
- Residential Laundry Machines:Home-care detergent formulations prioritize cost-performance balance in powder and liquid matrices.
- Hospitality Laundry Services:Multi-site hotel chains consolidate procurement through direct specification contracts with polymer producers.
- Institutional Laundry:Correctional and municipal facilities retain legacy phosphonate-containing formulations despite REACH regulatory pressure.
Commercial laundries anchor volume concentration. Healthcare textile cleaning is climbing the fastest.
End User:
Customer type fragmentation reflects divergent technical specification capabilities, with textile manufacturers and medical laboratories demanding molecular-weight-certified architectures unavailable to hospitality generalists.
- Laundry Service Providers:National operators like Aramark and Sodexo centralize formulation approvals across property portfolios, displacing distributor relationships with direct polymer producer contracts. Automated dosing system compatibility determines procurement qualification in United States multi-site hospitality chains.
- Textile Manufacturers:Pre-treatment of reusable technical textiles for automotive and aerospace applications requires polymer additives with validated molecular weight distributions. Stuttgart manufacturing clusters specify polycarboxylate architectures for precision-cleaning of reusable shop towels.
- Hospitality Facilities:Individual property procurement teams lack technical resources for polymer specification, deferring to service provider detergent selections.
- Medical Laboratories:Contamination control protocols mandate biocompatibility documentation exceeding standard laundry chemical requirements.
- Educational Institutions:University and school district laundries operate on municipal procurement cycles with extended vendor qualification timelines.
Laundry service providers concentrate volume leverage. Textile manufacturers represent the steepest expansion trajectory.
Form:
Supply concentration in liquid concentrate production reflects capital requirements for automated dosing compatibility, while powder and granule forms retain geographic pockets of demand tied to legacy infrastructure.
- Liquid:Concentrated aqueous solutions enable precision-metering compatibility with European commercial laundry automation. German industrial laundries equipped with automated dosing systems drive disproportionate qualification effort for liquid polycarboxylate formulations.
- Concentrate:Ultra-high solids formulations reduce transportation cost burden for national laundry service operators with centralized distribution networks. California and Texas utility rebate programs for energy-reduced wash programs favor concentrate platforms enabling cold-water solubility.
- Powder:Legacy spray-dried matrices retain installed base in price-sensitive institutional segments.
- Granules:Free-flowing agglomerated forms serve regional supply chain conventions in Southern European markets.
- Tablets:Unit-dose formats capture limited demand in residential and small commercial segments.
Liquid dominates installed base. Concentrate is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes polycarboxylate architectures for Federal Environment Agency compliance, while the United States deploys cold-water solubility platforms for utility rebate capture. This consumption-mix differential separates European regulatory-driven procurement from North American energy-efficiency optimization.
United States
Commercial laundries in California and Texas deploy polyethylene glycol-optimized formulations to capture utility rebate programs for energy-reduced wash programs. EPA Safer Choice criteria revisions tighten allowable ecotoxicological thresholds for laundry chemicals discharged into municipal wastewater. Aramark and Sodexo procurement teams centralize detergent formulation approvals across multi-site hospitality portfolios, displacing distributor relationships with direct polymer producer contracts.
Germany
Industrial laundries serving automotive manufacturing clusters specify biodegradable polycarboxylate variants under Federal Environment Agency discharge monitoring protocols. EU REACH restrictions on phosphonate builders redirect formulator procurement toward polymeric alternatives with favorable ecotoxicological profiles. Stuttgart and Wolfsburg manufacturing clusters generate underpenetrated demand from precision-cleaning operations for reusable shop towels and uniforms.
Netherlands
Automated dosing systems in commercial laundries concentrate demand for concentrated liquid polycarboxylate formulations compatible with precision-metering infrastructure. Pending ISO 14034 protocol revisions will create preferential procurement pathways for polymer chemistries achieving third-party biodegradability certification. Industrial laundries pilot bio-based acrylic acid feedstock architectures under Federal Environment Agency-aligned discharge monitoring frameworks.
China
Dual carbon goals and MIIT industrial efficiency mandates compress wash cycle durations in textile manufacturing operations, forcing polymer architectures that maintain soil suspension in abbreviated rinse phases. GB standards for industrial laundry chemicals tighten formulation requirements for wastewater discharge. Yangtze River Delta manufacturing clusters concentrate demand for cost-optimized polycarboxylate production serving export-oriented textile operations.
Japan
METI energy efficiency standards for commercial laundry operations accelerate adoption of cold-water solubility platforms in hospitality and healthcare textile cleaning. JIS standards for laundry chemical biodegradability align with OECD environmental technology verification frameworks. Kansai region industrial laundries serving pharmaceutical manufacturing enforce thermal stability requirements that pull premium polymer variants into specialized formulations.
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with polymer formulation expertise redrawing competitive boundaries in this specialty chemicals niche. BASF leverages integrated acrylic acid chains to control raw material quality for polycarboxylate production. Dow anchors position through polyethylene glycol platforms optimized for cold-water solubility. Nouryon competes with amphoteric polymer architectures that perform across pH extremes in commercial wash tunnels. Dominant competitive moves include backward integration into fermentation-derived monomer supply and direct specification contracts with national laundry service operators displacing traditional distribution channels.
Among integrated chemical conglomerates, BASF, Dow, and Nouryon occupy positions that exemplify three distinct competitive archetypes. BASF represents the captive raw material model with upstream control over acrylic acid chains. Dow anchors the platform chemistry approach with polyethylene glycol expertise transferable across detergent matrices. Nouryon sits within the performance specialization tier, with amphoteric architectures addressing pH-variable commercial tunnel conditions. These three companies illustrate how polymer formulation capabilities concentrate competitive advantage in a market where molecular weight distribution optimization and biodegradability certification determine procurement qualification.
| Leading Market Players |
|---|
| BASF |
| Dow |
| Nouryon |
| Solvay |
| Clariant |
| SNF |
| Ashland |
| Lubrizol |
| Kemira |
| Others |
Pricing and Supply Chain Analysis
Acrylic acid substitution for phosphonate builders in German industrial laundries simultaneously redistributes supply gravity toward petrochemical corridors in Ludwigshafen and compresses pricing premiums for biodegradable polycarboxylate variants. This dual transformation rewards integrated producers with captive monomer supply while squeezing margin buffers for formulators dependent on spot acrylic acid procurement.
Pricing Analysis
Long-term offtake contracts between polycarboxylate producers and national laundry service operators anchor pricing stability, while spot transactions for bio-based acrylic acid feedstocks introduce volatility into premium tier quotations. Three-tier pricing structure across premium, standard, and economy levels separates polyvinylpyrrolidone healthcare formulations from commodity polycarboxylate volumes and phosphonate-legacy institutional contracts. Cost compression in standard-grade polycarboxylates is intensifying because acrylic acid feedstock volatility transmits directly through non-integrated supply chains. Municipal and correctional facility laundries exhibit highest price sensitivity, while pharmaceutical manufacturing clusters in Stuttgart tolerate premium positioning for thermal-stable architectures.
Supply Chain Analysis
Strait of Hormuz transit vulnerability for petroleum-derived acrylic acid monomers exposes European polycarboxylate production to energy price shocks, even as fermentation-derived bio-based alternatives pilot in Netherlands industrial laundries. Supply concentration rests on Germany, China, and the United States for acrylic acid and polyethylene glycol platform chemicals. Raw material dependencies draw from crude oil derivatives, bio-based fermentation feedstocks, and ethylene oxide supply chains. Single-source vulnerability concentrates in acrylic acid monomer supply for non-integrated formulators. Distribution runs through direct specification contracts with national laundry service operators, displacing legacy distributor networks in North American and European commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment around REACH authorization timelines and ECHA evaluation protocols creates structural barriers against rapid competitive displacement. Incumbents with established polymer registration dossiers command procurement qualification advantages that compound over multi-year commercialization cycles.
For Market Incumbents: Shield market position by accelerating backward integration into fermentation-derived acrylic acid supply chains before bio-based feedstock certification becomes mandatory under Federal Environment Agency protocols. Secure direct specification contracts with Aramark and Sodexo procurement teams to lock out distributor-dependent challengers. Prioritize capacity addition in Netherlands pilot facilities aligned with pending ISO 14034 biodegradability verification pathways. For New Entrants and Emerging Players: Differentiate on cold-water solubility performance metrics to capture utility rebate program qualifications in California and Texas commercial laundries. Target automotive sector precision-cleaning operations in Stuttgart and Wolfsburg manufacturing clusters as the most penetrable white-space segment. Pursue joint formulation development contracts with regional industrial laundry equipment manufacturers as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated chemical conglomerates with captive monomer supply and established regulatory dossiers. Long-term viability hinges on biodegradability certification entrenchment rather than transient formulation performance advantages. Acquisition target archetype: mid-tier polymer specialists with ECHA-registered architectures and underutilized production capacity in Germany or the Netherlands. Watch Federal Environment Agency discharge threshold revisions as the critical inflection signal for bio-based feedstock substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Acrylic Acid | Fermentation-derived monomer supply secures preferential qualification under Federal Environment Agency protocols. |
| Long-term Supply Agreement with National Laundry Operators | Direct contracts with Aramark and Sodexo displace distributor intermediaries and stabilize volume commitments. |
| ISO 14034 Biodegradability Certification Investment | Third-party verification opens institutional procurement pathways in Germany and the Netherlands. |
| Cold-Water Solubility Platform Development | Polyethylene glycol optimization captures utility rebate programs in California and Texas energy-reduced wash programs. |
| Joint Venture with Automotive Textile Cleaners | Precision-cleaning partnerships in Stuttgart manufacturing clusters address underpenetrated reusable shop towel demand. |
Research Methodology
Initial hypotheses were tested against primary input from polymer formulation chemists, commercial laundry procurement directors, detergent manufacturing R&D heads, and ECHA regulatory affairs specialists and refined through secondary validation against REACH registration dossiers, Federal Environment Agency discharge monitoring reports, SEC 10-K filings from integrated chemical producers, and customs trade data for acrylic acid derivatives. Bottom-up volume modeling across product type, application, end user, and form segments was cross-checked against top-down demand aggregation from regional industrial laundry capacity assessments.
Variance decomposition across the projection horizon isolates volume drivers by segmentation dimension including polymer chemistry architecture, wash cycle configuration compliance tier, automated dosing infrastructure penetration, and regional regulatory stringency cluster. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs incorporated EPA Safer Choice criteria revision timelines and EU Ecodesign implementation phase schedules.
The analysis sits within stated boundaries; outcomes outside current REACH authorization trajectories and Federal Environment Agency discharge threshold stability would require recalibration. Forecasts assume continuation of existing regulatory enforcement intensity and acrylic acid feedstock availability patterns. Practitioners should keep alternative scenarios live as phosphonate builder substitution velocity and bio-based acrylic acid scale-up economics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Feed Acidulants Market
Additives
Diamino Stilbene Disulfonic Acid (DASDA) Market
Additives
1,4 Butanediol Derivatives Market
Additives
Lactic Acid Ester Market
Additives
Friction Modifier Additives Market
Additives
Texture Modifier Market
Additives
South America Concrete Admixtures Market
Additives
Iso-Butyric Acid Market
Additives
Europe Anti-Caking Market
Additives
Pearlizers Market
Additives
Coating Additives Market
Additives
Thallium Acetate Market
Additives
Anti Crystallizing Agents Market
Additives
Biosaccharide Gum Market
Additives
Pectin Market
Additives
Dispersing Agents Market