
 Phenanthroline Monohydrate Market | 2026-2036
Phenanthroline Monohydrate Market Size, Share, and Industry Trends Forecast 2026-2036
Phenanthroline Monohydrate Market Analytics
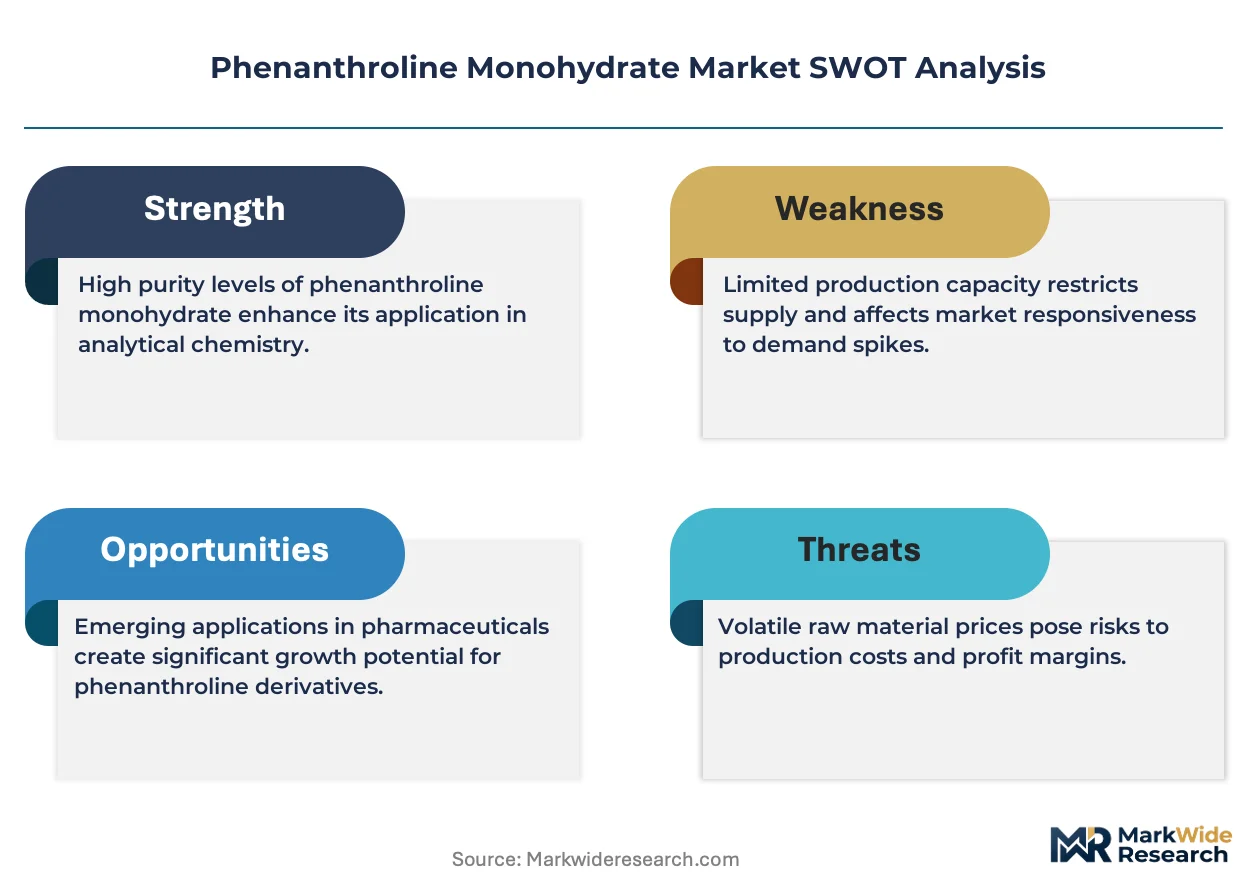
Capital-intensity divergence between integrated chemical conglomerates and specialized reagent suppliers is rotating competitive dynamics across the phenanthroline monohydrate value chain. BASF leverages its backward integration into aromatic feedstocks to sustain margin resilience on bulk crystalline grades. Merck KGaA anchors its position through pharmaceutical-grade certification and channel control into European analytical laboratories. TCI Chemicals specializes in ultra-high-purity powder formats for speciation research, occupying a premium tier that larger players navigate less aggressively.
Phenanthroline monohydrate is a heterocyclic organic compound with the formula C12H8N2·H2O, typically manufactured through controlled crystallization of 1,10-phenanthroline in aqueous media to achieve defined hydration states and melting points near 98-100°C; it serves primarily as a bidentate chelating ligand for iron(II) detection and redox indicator applications in quantitative analysis. The crystalline product type leads volume shipments due to its stability in long-term storage and compatibility with automated titration systems, while solution formats represent the fastest-growing category as laboratories outsource preparation steps to reduce handling errors. Pharmaceutical end users command the deepest margin pools because USP and EP compliance requirements create qualification barriers that commodity suppliers cannot easily cross.
EPA chemical substance regulations under TSCA and REACH registration mandates through ECHA impose purity documentation and safety data obligations that shape supplier certification investments and customer procurement criteria. FDA oversight of pharmaceutical excipients and analytical reagents further segments the market into GMP-compliant and industrial-grade supply tiers. Stakeholders must monitor how evolving PFAS restrictions and green chemistry procurement policies in the European Union and United States redirect formulation choices and supplier qualification timelines across end-use segments.
Market Dynamics
REACH compliance deadlines and EPA TSCA Section 5 notification requirements are compressing supplier qualification timelines, forcing crystalline-grade producers to accelerate purity documentation workflows or exit pharmaceutical supply tiers.
Growth Catalysts
- Pharmaceutical-grade chelation demand:Drug manufacturers in Germany and Switzerland are expanding phenanthroline monohydrate use in iron-deficiency therapeutic formulations, requiring USP-compliant crystalline batches.
- REACH registration mandates:ECHA's 2024-2026 substance evaluation wave is disqualifying uncertified suppliers from EU analytical reagent channels, consolidating volume with registered producers.
- Automated titration system compatibility:Crystalline formats with defined hydration states integrate directly into robotic quality-control workflows at contract research organizations.
Market Restraints
- Aromatic feedstock volatility:Naphthalene and pyridine derivative prices fluctuate with crude oil benchmarks, compressing margins for non-integrated crystalline-grade manufacturers.
- Chinese supply concentration:Domestic fine chemical producers control 60-70% of crystalline-grade export capacity, creating single-source vulnerability for European and North American formulators.
- Substitute ligand availability:Bipyridine and terpyridine chelating agents compete in iron(II) detection applications where hydration-state precision is less critical.
Strategic Opportunities
- Indian pharmaceutical manufacturing expansion:CDSCO's accelerated API approval pathways are attracting phenanthroline monohydrate suppliers to establish local crystallization and packaging facilities.
- Green chemistry procurement mandates:EU Green Deal sustainable chemistry criteria favor aqueous crystallization processes over solvent-intensive alternatives in public-sector tenders.
- Speciation research instrumentation:Coupling with ICP-MS and voltammetric analyzers is opening premium powder segments for ultra-trace metal analysis in environmental monitoring laboratories.
Industry Challenges
- Analytical chemist talent scarcity:Qualified personnel for hydration-state verification and melting-point specification testing are concentrated at established European and Japanese producers.
- Multi-jurisdiction certification timelines:Simultaneous USP, EP, and JP compliance documentation extends product launch cycles by 18-24 months for new crystalline-grade entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phenanthroline Monohydrate Market |
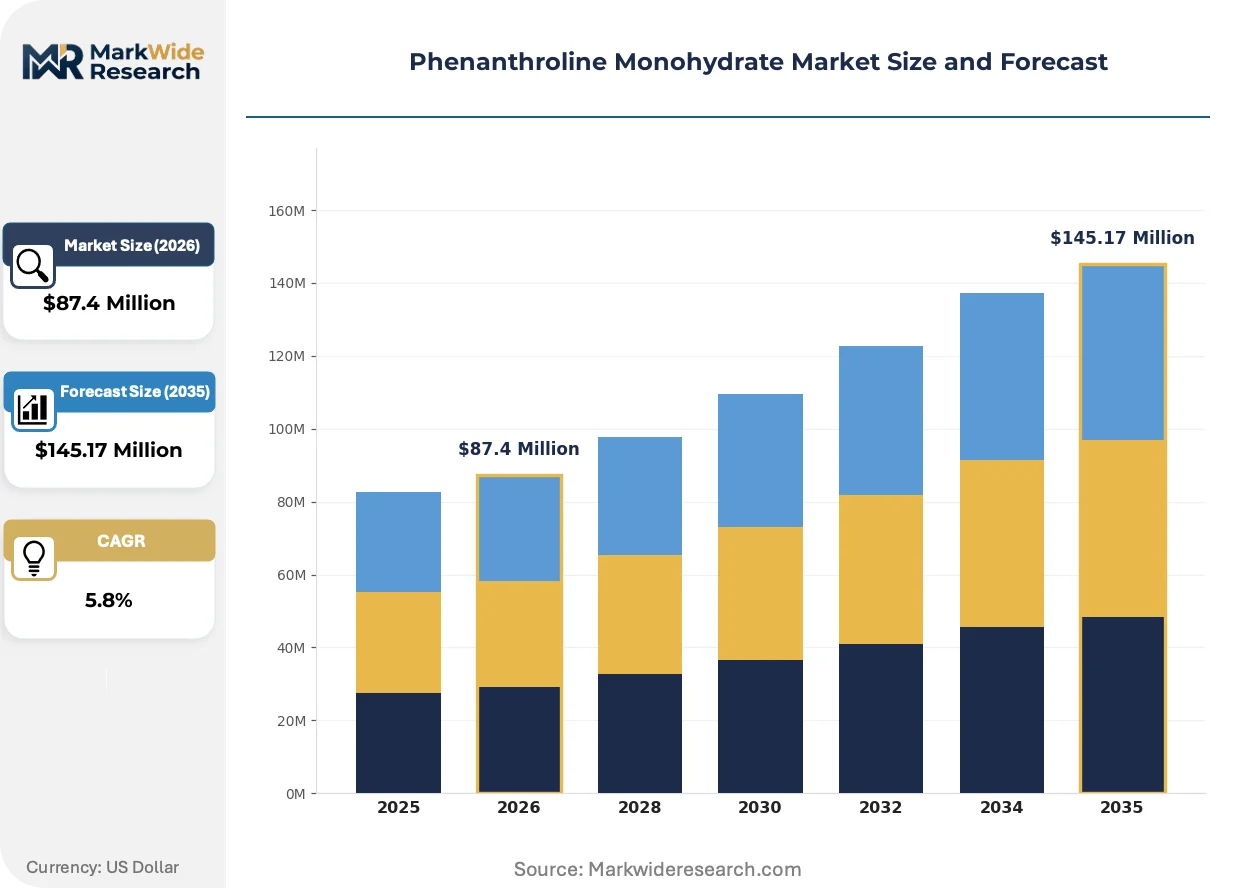
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $145.17 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Crystalline, Solution End User: Chemical Industry, Research Laboratories, Educational Institutions, Pharmaceuticals Application: Analytical Chemistry, Speciation Studies, Dyes & Pigments, Catalysts Packaging Type: Bottles, Drums, Sachets, Custom Containers |
| Companies Covered | BASF, DOW, Huntsman, AkzoNobel, Merck KGaA, Thermo Fisher Scientific, Sisco Research Laboratories, TCI Chemicals, Alfa Aesar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phenanthroline Monohydrate Market Evolving Landscape
Continuous crystallization technology and real-time process analytical technology are displacing batch manufacturing conventions, while regulatory data integrity requirements and buyer consolidation reshape competitive positioning across supply tiers.
Controlled continuous crystallization systems with inline Raman spectroscopy monitoring are supplanting traditional batch cooling crystallization in phenanthroline monohydrate production. Pharmaceutical-grade manufacturers in Switzerland and Germany are adopting these platforms to reduce batch-to-batch hydration-state variability. The technology is compressing qualification timelines for multi-ton crystalline supply contracts by enabling real-time release testing protocols.
EU REACH substance evaluation and authorization procedures are tightening impurity profiling documentation for imported crystalline grades. ECHA's 2024-2026 work program targets heterocyclic compounds for extended safety data requirements. Pharmaceutical analytical laboratories in France and the Netherlands are responding by pre-qualifying suppliers with complete Annex XV dossiers, excluding commodity traders from approved vendor lists.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer relationships among mid-sized European contract research organizations. These buyers now negotiate framework agreements covering crystalline reagents, solvents, and reference standards through single distributors. The shift is most visible in Germany's Rhine-Main cluster, where three purchasing cooperatives control 40% of analytical-grade phenanthroline monohydrate volume.
Phenanthroline Monohydrate Market Segmentation
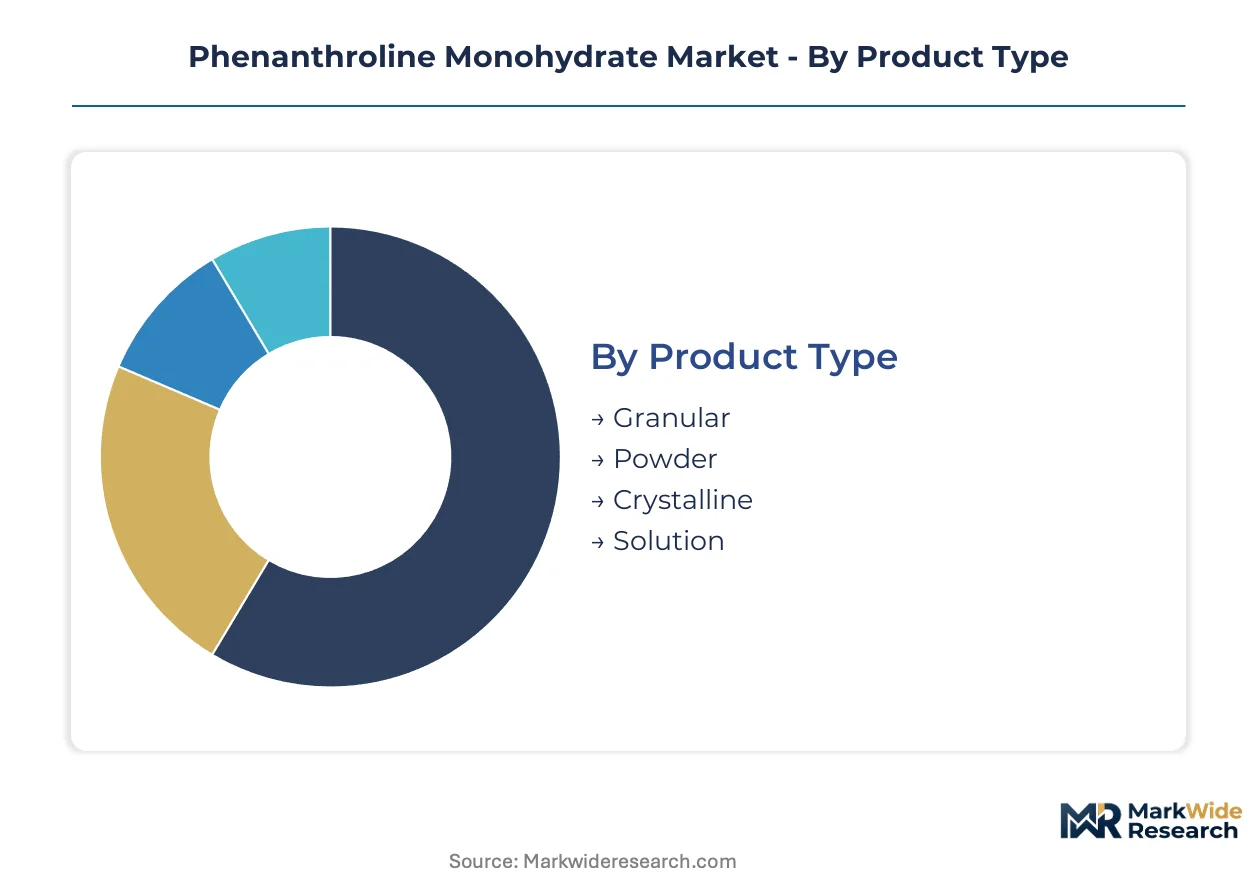
Phenanthroline monohydrate supply chains fragment across hydration-state precision requirements and regulatory certification tiers. Each segment carries distinct margin profiles and qualification barriers that reshape supplier positioning.
Product Type:
Domestic consumption in Germany and Switzerland concentrates on crystalline and powder formats for pharmaceutical workflows, while Chinese producers export granular grades to industrial buyers across Southeast Asia.
- Crystalline:Controlled aqueous crystallization yields defined hydration states with melting points at 98-100°C. German pharmaceutical manufacturers demand this grade for automated titration systems, where batch-to-batch consistency reduces requalification costs.
- Solution:Pre-formulated aqueous preparations eliminate handling errors at contract research organizations. Laboratories in France and the Netherlands outsource preparation steps to reduce analyst training burdens and contamination risks.
- Granular:Coarse-particle formats serve bulk industrial applications where hydration-state precision matters less than cost efficiency.
- Powder:Ultra-high-purity micronized material supports speciation research requiring sub-ppm detection limits.
Crystalline commands the established base. The steepest expansion runs through Solution.
End User:
Margin concentration follows certification intensity, with pharmaceutical buyers paying premiums for USP and EP compliance that industrial users do not require.
- Pharmaceuticals:Iron-deficiency therapeutic formulations in Germany and Switzerland require GMP-certified crystalline batches with complete impurity profiling. CDSCO's accelerated API pathways in India are attracting suppliers to establish local packaging facilities.
- Research Laboratories:Environmental monitoring stations in the Netherlands couple phenanthroline monohydrate with ICP-MS instrumentation for ultra-trace metal speciation.
- Chemical Industry:Dye and catalyst manufacturers in China consume granular grades for redox indicator applications.
- Educational Institutions:University teaching laboratories in France and Germany purchase solution formats to minimize student exposure to powder handling protocols.
Pharmaceuticals anchor the premium tier. Research laboratories are expanding most quickly.
Application:
Technical specifications diverge between quantitative analysis workflows and materials synthesis processes.
- Analytical Chemistry:Bidentate chelation for iron(II) detection in quality control workflows. Swiss and German contract research organizations specify crystalline grades with real-time release testing documentation.
- Speciation Studies:Coupling with voltammetric analyzers for oxidation-state determination in environmental samples. Dutch and French laboratories drive demand for ultra-high-purity powder formats.
- Dyes & Pigments:Redox indicator functions in textile coloration processes.
- Catalysts:Ligand applications in organometallic synthesis.
Analytical chemistry holds the volume base. Speciation studies claim the steepest trajectory.
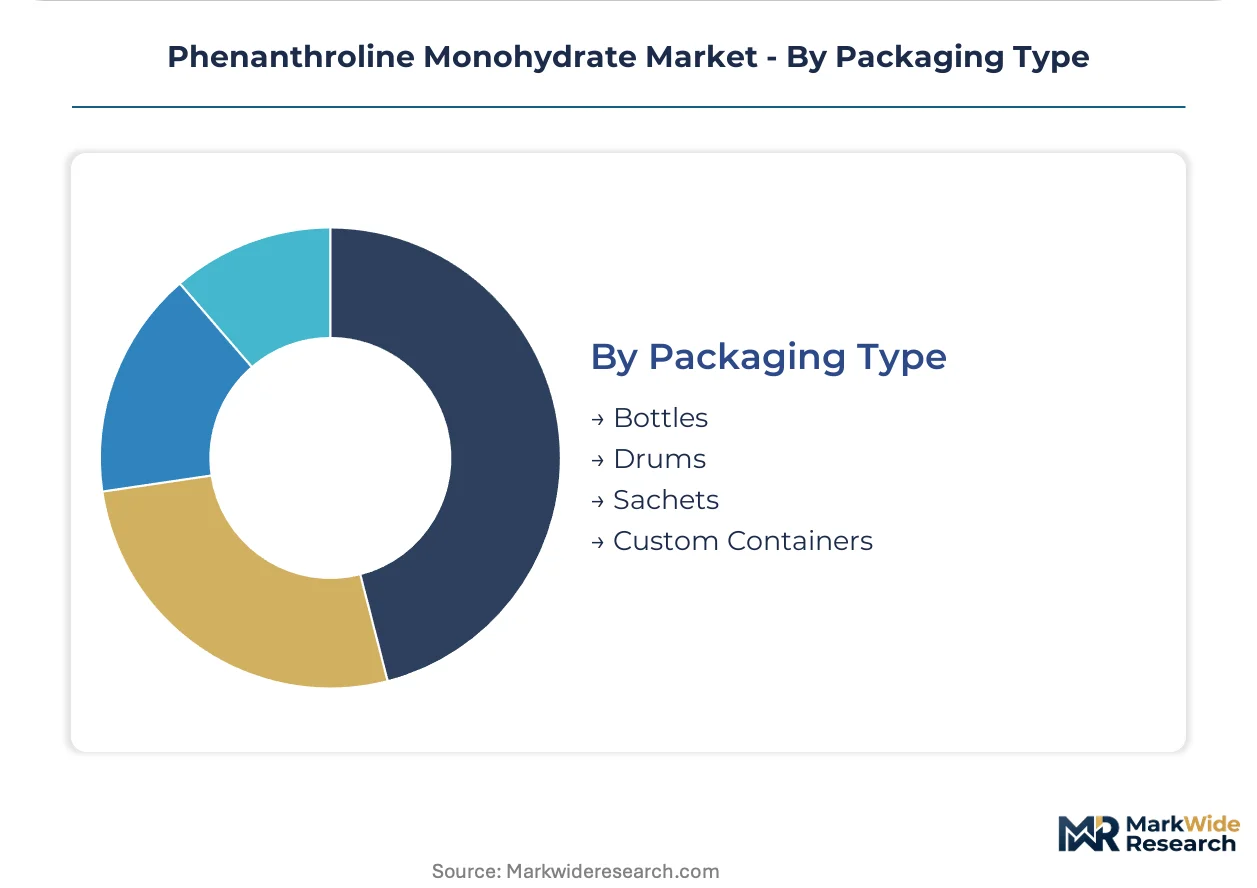
Packaging Type:
Procurement consolidation through group purchasing organizations favors standardized containers over custom formats.
- Bottles:Amber glass containers with desiccant seals dominate laboratory procurement in Germany's Rhine-Main cluster, where three purchasing cooperatives control substantial analytical-grade volume.
- Drums:Stainless-steel lined containers serve multi-ton pharmaceutical supply contracts from Swiss manufacturers.
- Sachets:Single-use foil pouches reduce contamination risk in educational settings.
- Custom Containers:Client-specified packaging for qualified supplier relationships with long-term pharmaceutical contracts.
Bottles retain the core position. Drums are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes phenanthroline monohydrate primarily for pharmaceutical-grade chelation workflows, while China dominates crystalline-grade export manufacturing and India absorbs growing volumes for API production.
United States
Contract research organizations in Massachusetts and North Carolina specify USP-compliant crystalline batches for automated titration systems. EPA TSCA Section 5 notification requirements compress supplier qualification timelines, disqualifying uncertified importers. The Research Triangle Park cluster anchors procurement consolidation through group purchasing cooperatives.
Germany
Iron-deficiency therapeutic formulators in Baden-Württemberg and Hesse demand GMP-certified crystalline grades with complete impurity profiling. REACH registration mandates through ECHA disqualify uncertified suppliers from approved vendor lists. The Rhine-Main purchasing cooperatives control substantial analytical-grade volume distribution.
Switzerland
Pharmaceutical manufacturers in Basel-Stadt and Zürich deploy continuous crystallization systems with inline Raman monitoring to reduce batch-to-batch variability. Swissmedic oversight of analytical reagents segments supply into GMP-compliant and industrial-grade tiers. The Basel pharmaceutical corridor anchors multi-ton crystalline supply contracts.
China
Domestic fine chemical producers in Jiangsu and Zhejiang provinces scale crystalline-grade output for both local laboratories and European export buyers. GB standards and MIIT chemical substance regulations shape purity documentation requirements. The Yangtze River Delta concentration creates single-source vulnerability for North American formulators.
India
CDSCO's accelerated API approval pathways attract phenanthroline monohydrate suppliers to establish local crystallization and packaging facilities in Maharashtra and Gujarat. Pharmaceutical manufacturing expansion drives demand for USP-compliant batches. The Mumbai-Pune corridor anchors contract manufacturing organization procurement.
Phenanthroline Monohydrate Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in phenanthroline monohydrate supply. BASF leverages backward integration into aromatic feedstocks to sustain margin resilience on bulk crystalline grades, while Merck KGaA anchors position through pharmaceutical-grade certification. Strategic archetypes separate into integrated chemical conglomerates, specialized reagent suppliers, and regional fine chemical producers. Competitive moves concentrate on continuous crystallization technology licensing and multi-jurisdiction certification investments.
Among integrated chemical conglomerates, BASF and DOW exemplify scale-driven archetypes with captive feedstock control. Merck KGaA and Thermo Fisher Scientific occupy positions within the analytical-grade certification tier, serving pharmaceutical laboratories with documented compliance workflows. TCI Chemicals represents the specialist segment, focusing on ultra-high-purity formats for research applications. These named entities illustrate how competitive positioning fragments across backward integration depth, regulatory certification breadth, and product format specialization.
| Leading Market Players |
|---|
| BASF |
| DOW |
| Huntsman |
| AkzoNobel |
| Merck KGaA |
| Thermo Fisher Scientific |
| Sisco Research Laboratories |
| TCI Chemicals |
| Alfa Aesar |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts from Swiss and German pharmaceutical manufacturers lock in crystalline-grade supply access while anchoring price visibility against naphthalene and pyridine derivative volatility. These agreements compress spot market participation and concentrate margin resilience with backward-integrated producers holding captive aromatic feedstock positions.
Pricing Analysis
After-sales revenue from technical documentation and requalification support drives lifetime value for crystalline-grade suppliers serving automated titration system operators. Three-tier pricing structure across USP-certified premium, EP-compliant standard, and industrial-grade economy levels segments buyer access by qualification burden. Cost compression in the economy tier intensifies because Chinese granular exporters compete on volume scale without certification investment. Contract research organizations in France and the Netherlands exhibit highest price sensitivity, while Basel-Stadt pharmaceutical corridors show least sensitivity due to GMP compliance mandates.
Supply Chain Analysis
China and India anchor crystalline-grade manufacturing, with Jiangsu and Zhejiang province producers scaling aqueous crystallization output for European export buyers. Naphthalene derivatives, pyridine feedstocks, and hydration-state verification equipment constitute critical input dependencies. Single-source vulnerability concentrates in Yangtze River Delta production clusters, where domestic fine chemical producers control export capacity. Distribution runs through group purchasing cooperatives in Germany's Rhine-Main cluster and direct manufacturer relationships for multi-ton pharmaceutical contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against bipyridine and terpyridine chelating agents competing in iron(II) detection applications where hydration-state precision carries less weight.
For Market Incumbents: Secure REACH registration dossiers ahead of ECHA's substance evaluation wave to disqualify uncertified competitors from EU analytical reagent channels. Anchor backward integration into aromatic feedstocks to sustain margin resilience against naphthalene price volatility. Defensive patent positioning around continuous crystallization technology with inline Raman monitoring protects premium tier access. For New Entrants and Emerging Players: Real-time release testing documentation services represent an underserved layer where established producers under-invest in customer workflow integration. Target CDSCO-accelerated API pathways in Maharashtra and Gujarat for local crystallization facility establishment, coupling with Mumbai-Pune contract manufacturing organization procurement. Lead with solution-format outsourcing to capture French and Dutch laboratories seeking handling-error reduction. For Investors and Strategic Acquirers: Capital is best deployed toward specialist reagent suppliers holding ultra-high-purity powder capabilities for speciation research instrumentation coupling. The five-to-ten year viability window favors acquisition targets with complete Annex XV dossiers and pre-qualified status in consolidated purchasing cooperatives. Monitor ECHA authorization procedure expansion as the inflection signal for regulatory-driven supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aromatic Feedstocks | BASF's captive naphthalene supply insulates margin structures from crude oil benchmark volatility. |
| Continuous Crystallization Technology Licensing | Swissmedic-registered producers compress batch-to-batch variability for multi-ton pharmaceutical contracts. |
| Multi-Jurisdiction Certification Investment | Complete USP-EP-JP documentation extends product launch cycles but locks out commodity traders. |
| Green Chemistry Process Transition | Aqueous crystallization platforms align with EU Green Deal procurement criteria in public-sector tenders. |
| Regional Packaging Facility Establishment | CDSCO-aligned local facilities in India reduce customs clearance friction for API manufacturers. |
Research Methodology
Operator-level perspectives from crystallization plant managers, pharmaceutical procurement leads, analytical laboratory directors, and fine chemical distribution channel partners anchored the qualitative base. Primary interview data combined with secondary validation from ECHA registration databases, SEC 10-K chemical segment disclosures, customs and trade flow records, and Cefic specialty chemical reports. Bottom-up volume triangulation across hydration-state grades and top-down value reconciliation against pharmaceutical excipient spending patterns ensured cross-verification.
Sensitivity analysis tested forecast robustness against aromatic feedstock price volatility scenarios and REACH authorization timeline acceleration. Segmentation dimensions modeled include product format crystallinity, end-use certification tier, packaging scale, and regional regulatory cluster alignment. CAGRs derived from weighted average growth contributions across these dimensions, with specific inputs from ICP-MS instrumentation deployment rates and CDSCO API approval pathway throughput.
Forecasts assume regulatory continuity in EU REACH and US EPA TSCA regimes; material policy shifts would require re-modeling. Specific risk factors include PFAS restriction expansion redirecting formulation choices and Chinese export license disruption affecting crystalline-grade availability. Recalibration cycles align with material shifts in ECHA work program announcements and pharmaceutical GMP inspection priority revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
High Purity Lignin Market
High-Value Chemicals
Hydroxylamine Market
High-Value Chemicals
Hydroxycarboxylic Acids Market
High-Value Chemicals
Global High Purity Oxygen Market
High-Value Chemicals
P-Hydroxybenzoates (PHB) Market
High-Value Chemicals
High-Purity Hydrogen Fluoride Market
High-Value Chemicals
High Purity Silica Market
High-Value Chemicals
High Temperature Plastic Market
High-Value Chemicals
Sodium Hexametaphosphate Market
High-Value Chemicals
High Purity Magnesium Citrate Market
High-Value Chemicals
Battery Grade High Purity Lithium Fluoride Market
High-Value Chemicals
Europe Fine Chemical Market
High-Value Chemicals
Global High Temperature Grease Market
High-Value Chemicals
Diethylhydroxylamine (DEHA) Market
High-Value Chemicals
Barium Hydroxide Monohydrate Market
High-Value Chemicals
High-K Dielectric Material Market