
 Surface Modifiers Market | 2026-2036
Surface Modifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Modifiers Market Analytics
China is tilting toward expanded silane and fluoropolymer modifier capacity to serve domestic electronics and automotive tiers. BASF SE leverages integrated precursor supply chains across Ludwigshafen and Nanjing to sustain cost-competitive silicone modifier output. Evonik Industries AG anchors its position through specialized polyacrylic dispersants for high-solids coatings. Dow Inc. competes on silane chemistry breadth, extending formulation support to adhesive producers in Asia.
Surface modifiers are chemical additives that alter interfacial properties—wetting, adhesion, slip, or chemical resistance—through molecular restructuring at substrate boundaries, typically applied at loadings between 0.1% and 5% by weight in liquid or powder form. Their primary industrial purpose is to resolve coating defects, enhance laminate bonding, or impart functional performance without altering bulk material properties. Polyacrylics dominate volume in architectural and industrial coatings where waterborne systems require rheology control and substrate wetting. Fluoropolymers command premium positioning in electronics and aerospace applications demanding oleophobic and hydrophobic surface energy reduction. Silicones occupy the broadest cross-sector footprint, bridging automotive sealants, textile softening, and ink defoaming with versatile siloxane backbone architectures.
REACH registration requirements and EU Green Deal decarbonization mandates are forcing reformulation away from solvent-borne systems toward waterborne and powder surface modifier delivery forms. FDA 21 CFR compliance for medical device coatings and EPA TSCA Section 5 premanufacture notification requirements constrain new chemical introductions in North American healthcare and consumer product channels. Stakeholders must monitor regulatory divergence between EU hazard-based classification and US risk assessment frameworks when planning cross-border product registrations and manufacturing investments.
Market Dynamics
REACH registration deadlines and EU Green Deal decarbonization mandates are forcing manufacturers to abandon solvent-borne surface modifier formulations. This regulatory compression is restructuring raw material sourcing and accelerating capital deployment into waterborne and powder delivery systems.
Growth Catalysts
- Automotive lightweighting mandates:OEM procurement of surface modifiers for carbon fiber and glass-reinforced polymer substrates is expanding as CAFE standards and EU CO2 fleet targets tighten.
- REACH Annex XVII VOC restrictions:The European Chemicals Agency's tightening permissible emission thresholds in coating formulations is pulling demand toward compliant silicone and polyacrylic modifiers.
- Electronics captive coating expansion:Domestic manufacturers in China are scaling in-house surface treatment operations for printed circuit boards and display panels, concentrating modifier procurement within the country's eastern manufacturing clusters.
Market Restraints
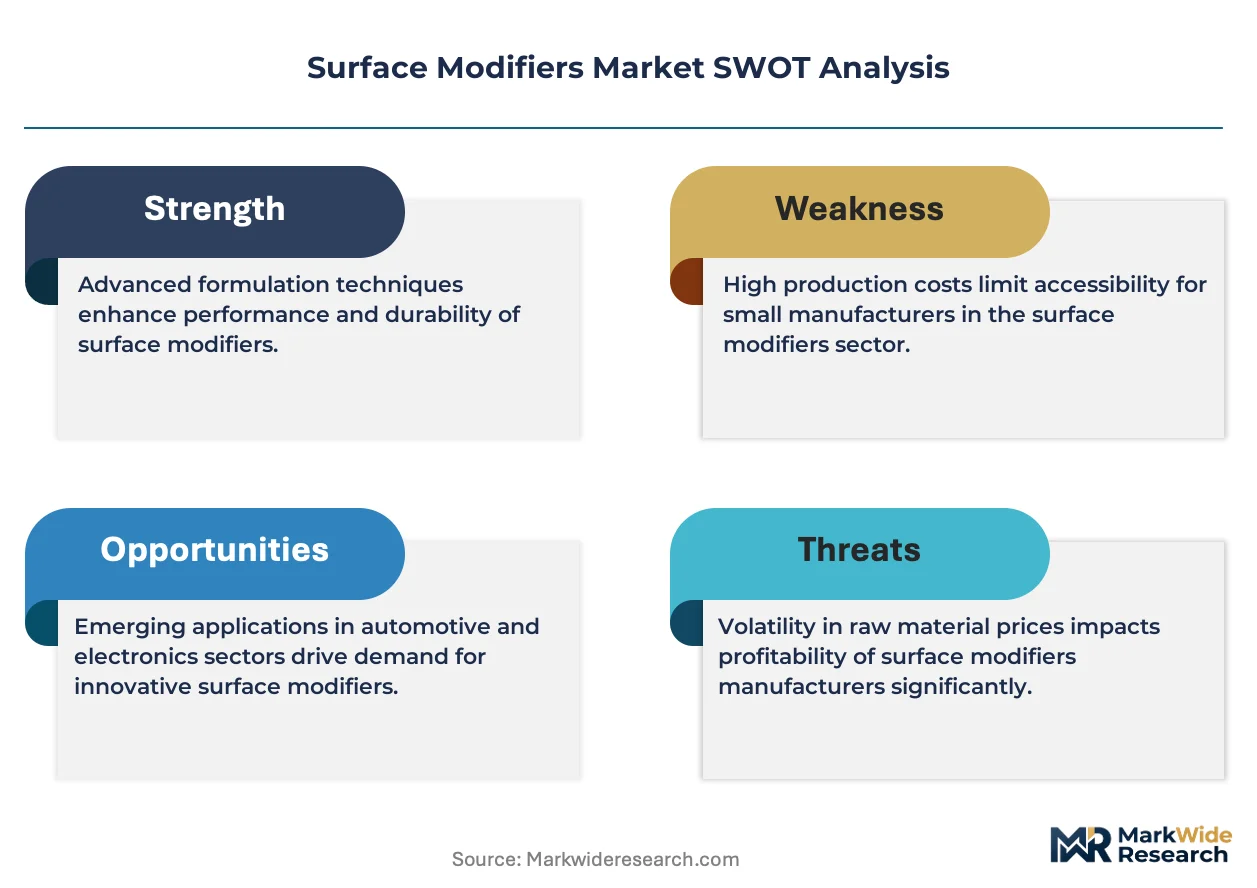
- Fluoropolymer feedstock concentration:Key fluorinated precursor supply is concentrated among a limited set of chemical producers, exposing modifier formulators to input cost volatility and allocation risk.
- Technical performance gaps in waterborne systems:Waterborne surface modifiers still exhibit inferior substrate wetting and corrosion resistance compared to solvent-borne alternatives in heavy-duty industrial applications.
- FDA 21 CFR compliance timelines:Medical device coating applications face extended premarket notification pathways that delay revenue realization for new modifier chemistries in North American healthcare channels.
Strategic Opportunities
- India specialty chemicals manufacturing:The country's PLI scheme for chemical sector investment is creating greenfield capacity opportunities for silane and polyacrylic modifier production serving domestic automotive and textile tiers.
- Bio-based dispersant convergence:Integration of enzymatic synthesis with conventional polyacrylic modifier production is opening formulation space for USDA BioPreferred-eligible coatings.
- Direct-to-formulator digital channels:Specialty chemical distributors are deploying technical specification platforms that bypass traditional multi-tier distribution for mid-volume coating producers in Southeast Asia.
Industry Challenges
- Formulation chemist scarcity:The specialized skill set spanning surface chemistry, rheology, and regulatory compliance is concentrated among aging technical workforces in Germany and Japan.
- Legacy equipment retrofit requirements:Transitioning coating lines from solvent-borne to waterborne or powder surface modifier application demands capital-intensive spray booth and curing oven modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Modifiers Market |
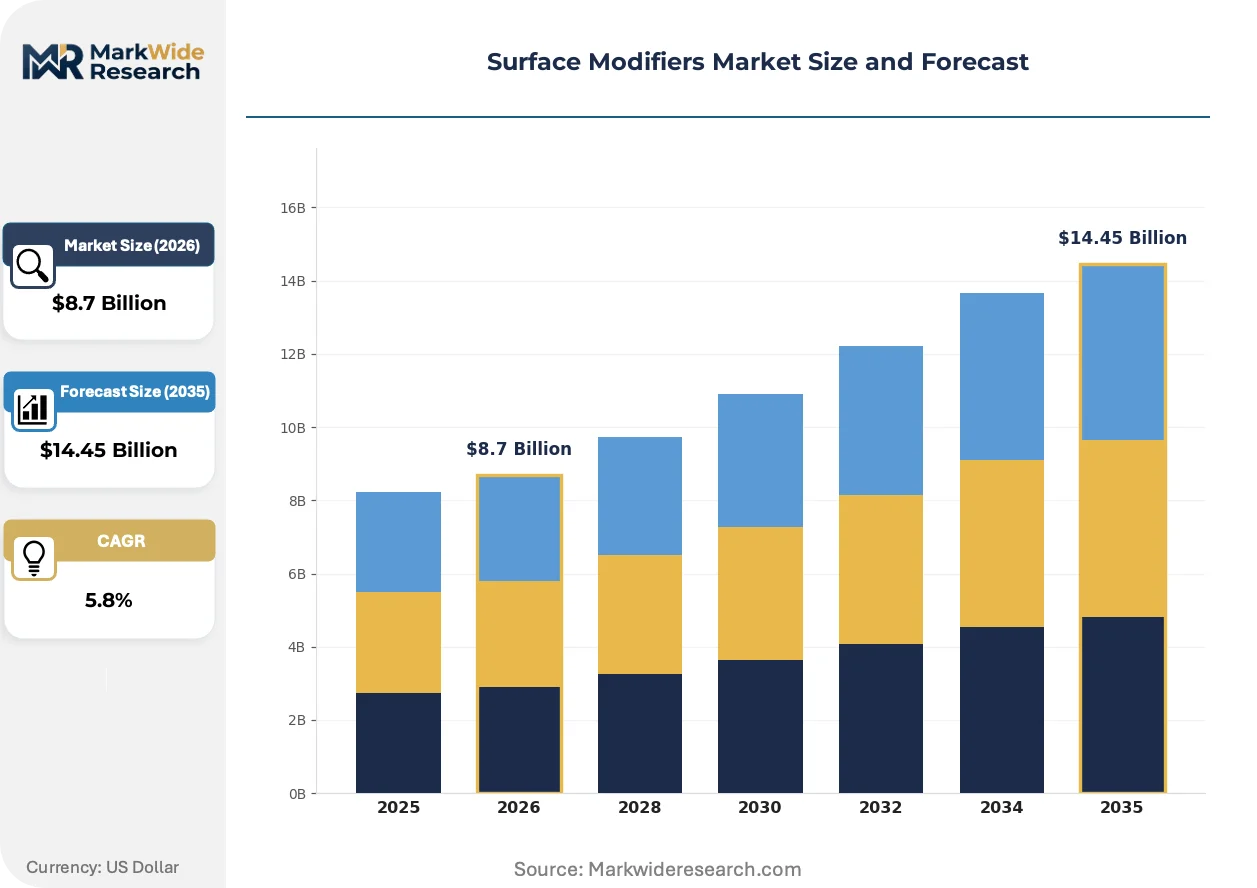
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicones, Polyurethanes, Polyacrylics, Fluoropolymers End Use Industry: Aerospace, Automotive, Medical Devices, Electronics Application: Adhesives, Coatings, Inks, Textiles Form: Liquid, Powder, Granules, Emulsions |
| Companies Covered | BASF SE, Evonik Industries AG, BYK (ALTANA), Dow Inc., Arkema, Elementis, Eastman Chemical Company, Air Products, Lubrizol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Modifiers Market Evolving Landscape
Formulation science is converging with digital specification tools and bio-based feedstock development. These intersecting currents are compressing product development cycles and reconfiguring how technical performance is validated and commercialized.
Hybrid organic-inorganic silane systems are collapsing the traditional separation between primer and topcoat functionalities in automotive and aerospace applications. Tier 1 suppliers to Boeing and Airbus are qualifying these materials for single-step application protocols that reduce shop floor cycle time. The technology is collapsing capital requirements for coating line expansion by eliminating dedicated primer stations.
EU F-Gas Regulation phase-down schedules are accelerating fluoropolymer modifier reformulation toward lower-GWP alternatives. The industrial consequence is a supply squeeze for conventional PTFE-based surface energy modifiers in electronics and medical device channels. German and French coating formulators are responding by accelerating qualification of short-chain fluorotelomer-based alternatives ahead of 2030 reduction milestones.
Specification-driven procurement platforms are displacing relationship-based distributor relationships among mid-sized industrial coating buyers. Technical data sheet comparison tools and automated sample fulfillment are consolidating purchasing power with formulators in China's Yangtze River Delta and Pearl River Delta manufacturing belts. The shift is most visible in automotive component coating operations where just-in-time inventory mandates favor rapid technical validation cycles.
Surface Modifiers Market Segmentation
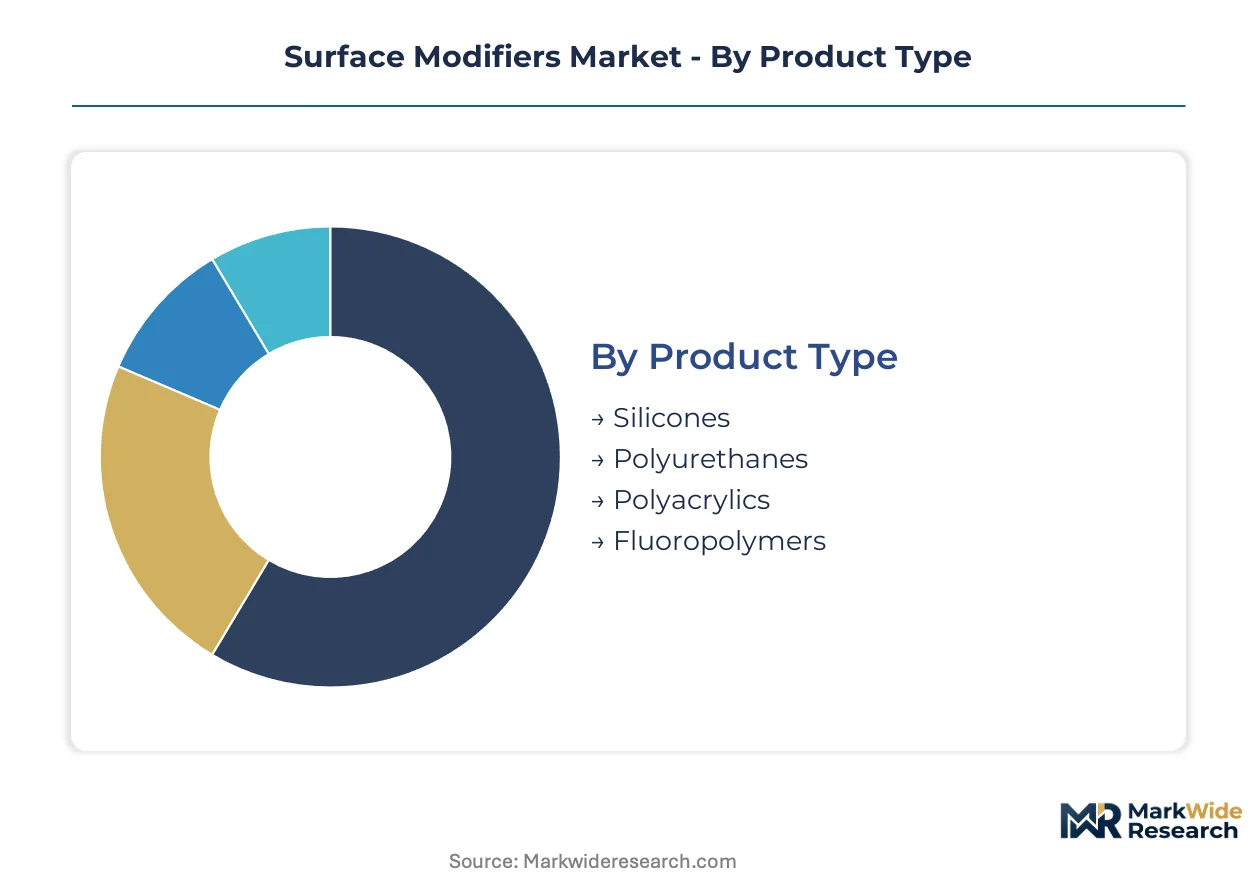
Surface modifiers serve distinct performance requirements across substrate chemistries and application methods. Segment boundaries reflect formulation compatibility constraints and regulatory compliance pathways rather than interchangeable commodity positioning.
Product Type:
After-sales technical service intensity varies sharply by chemistry family, with fluoropolymer and silicone modifiers demanding sustained formulation support while polyacrylics require minimal ongoing intervention.
- Silicones:Organosiloxane backbones deliver versatile wetting, defoaming, and slip control through adjustable molecular architecture. Automotive sealant producers in Stuttgart and Nagoya specify silicone modifiers for dual-cure systems requiring precise viscosity windows. REACH Annex XVII VOC thresholds are pulling European coating formulators toward waterborne silicone dispersions.
- Polyacrylics:Acrylic acid-derived dispersants anchor rheology control in waterborne architectural and industrial coatings. Chinese state-owned construction chemical manufacturers are scaling captive polyacrylic modifier capacity to serve domestic infrastructure coatings procurement. Technical performance gaps in corrosion resistance persist versus solvent-borne alternatives in heavy-duty marine applications.
- Polyurethanes:Isocyanate-terminated prepolymers enhance abrasion resistance and flexibility in textile and leather finishing operations.
- Fluoropolymers:Perfluorinated chains achieve ultra-low surface energy reduction for electronics oleophobic barriers and medical device lubricity.
Polyacrylics hold the largest share; momentum sits with fluoropolymers as EU F-Gas Regulation phase-down accelerates qualification of short-chain fluorotelomer alternatives.
End Use Industry:
Cost tier stratification separates aerospace and medical device specifications commanding premium modifier pricing from automotive and electronics procurement driven by volume efficiency targets.
- Automotive:OEM lightweighting mandates for carbon fiber and glass-reinforced polymer substrates are expanding procurement of adhesion-promoting modifiers. Tier 1 suppliers to BMW and Toyota specify silane-based primers for composite bonding in electric vehicle battery enclosures. CAFE standards and EU CO2 fleet targets tighten specification windows annually.
- Electronics:Domestic manufacturers in China's Yangtze River Delta are scaling captive surface treatment operations for printed circuit boards and display panels. Display panel producers in Suzhou and Hefei concentrate modifier procurement within eastern manufacturing clusters. Just-in-time inventory mandates favor rapid technical validation cycles.
- Aerospace:Boeing and Airbus qualification protocols demand extensive substrate-specific testing for single-step hybrid organic-inorganic systems.
- Medical Devices:FDA 21 CFR compliance timelines extend premarket notification pathways for new chemistries in North American healthcare channels.
Automotive commands the largest volume position; electronics is expanding most quickly as domestic Chinese coating operations displace imported modifier formulations.
Application:
Application method determines delivery form selection and curing protocol compatibility, with coatings demanding the broadest modifier portfolio breadth.
- Coatings:Architectural, automotive, and industrial coating systems consume modifiers for substrate wetting, leveling, and defect elimination. Waterborne system penetration in Germany and France accelerates silicone and polyacrylic dispersant demand. REACH registration deadlines force reformulation away from solvent-borne delivery.
- Adhesives:Structural bonding applications in automotive and electronics assembly rely on silane coupling agents for substrate-interface molecular bridging. Asian adhesive producers in South Korea and Japan specify organofunctional silanes for display lamination and semiconductor packaging operations.
- Inks:Printing ink defoaming and substrate adhesion control utilize silicone and polyacrylic modifier chemistries.
- Textiles:Fabric softening and water-repellent finishing operations deploy silicone emulsions and fluoropolymer dispersions.
Coatings represents the dominant application; adhesives is gaining share fastest as electronics assembly complexity intensifies bonding specification requirements.
Form:
Supply concentration in powder modifier production centers on German and Japanese specialty chemical infrastructure serving automotive and aerospace coating lines.
- Liquid:Solvent-borne and waterborne liquid dispersions remain the default delivery form for spray-applied coatings and dip-coating operations. European coating formulators are accelerating waterborne liquid modifier adoption ahead of EU Green Deal decarbonization milestones.
- Powder:Solid particulate modifiers enable electrostatic spray application in automotive and architectural coating lines requiring zero VOC emissions. Powder coating producers in Germany and Japan specify tailored particle size distributions for film-thickness uniformity.
- Emulsions:Aqueous silicone and fluoropolymer emulsions serve textile finishing and architectural coating applications.
- Granules:Solid pellet forms facilitate metered addition in extrusion compounding and masterbatch production.
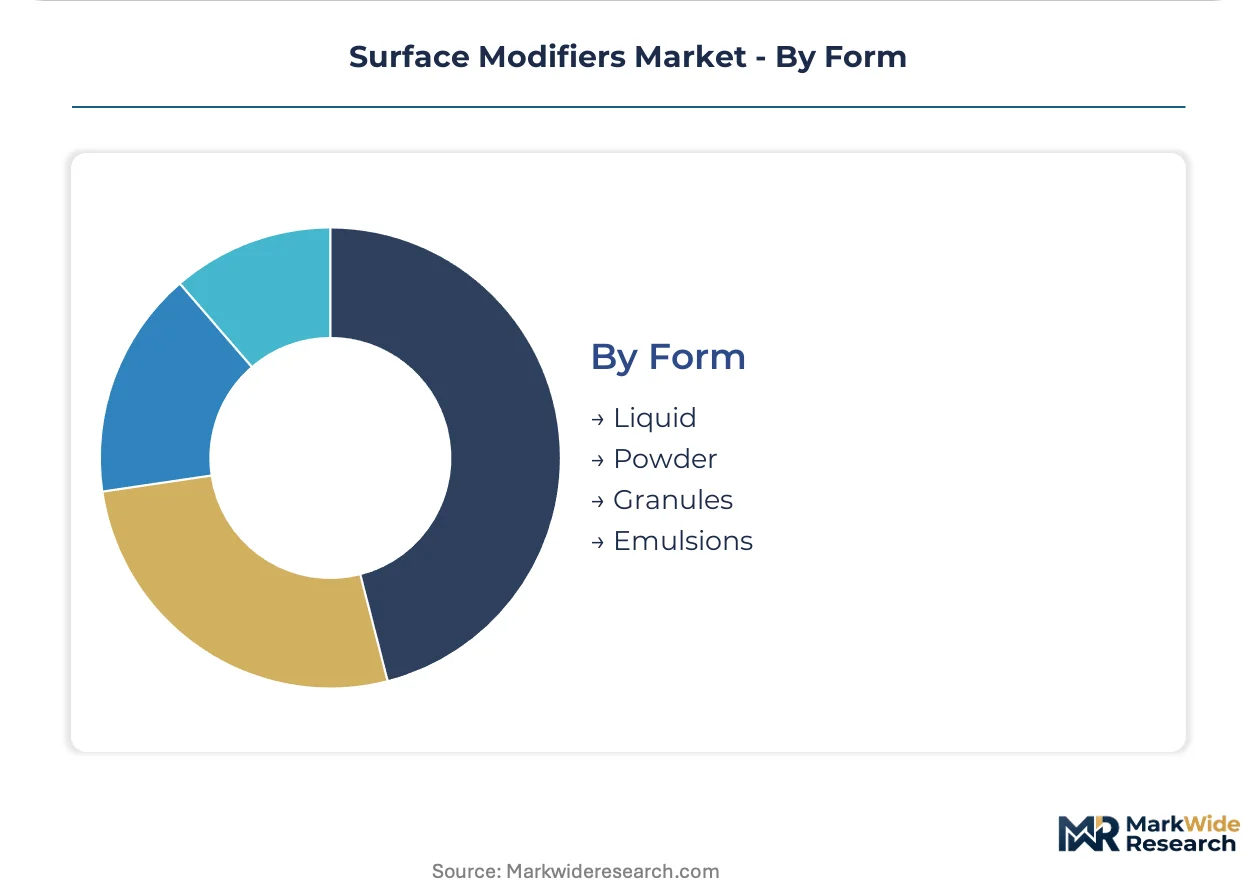
Liquid holds the largest share; powder is climbing the fastest as coating line retrofits eliminate solvent recovery infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surface modifier consumption patterns diverge sharply by geography: European formulators prioritize REACH-compliant waterborne silicone and polyacrylic systems, while Chinese electronics manufacturers concentrate procurement around captive fluoropolymer and silane operations for display and semiconductor applications.
Germany
Automotive OEMs in Stuttgart and Munich specify silane-based primers for carbon fiber composite bonding in electric vehicle battery enclosures. ECHA REACH Annex XVII enforcement tightens permissible VOC thresholds in coating formulations annually. The Ludwigshafen chemical cluster anchors integrated silicone modifier precursor supply serving domestic automotive sealant producers.
China
Domestic electronics manufacturers scale captive surface treatment operations for printed circuit boards and display panels in the Yangtze River Delta. MIIT dual carbon goals accelerate waterborne modifier adoption in state-owned construction chemical operations. Suzhou and Hefei display panel producers concentrate modifier procurement within eastern manufacturing clusters with just-in-time inventory mandates.
United States
Medical device coating applications face extended FDA 21 CFR premarket notification pathways that constrain new modifier chemistry introduction. EPA TSCA Section 5 requirements govern premanufacture notification for novel surface treatment chemistries. Automotive lightweighting procurement for carbon fiber substrates expands among Tier 1 suppliers serving Detroit-area OEM electrification programs.
Japan
Adhesive producers in Nagoya and Osaka specify organofunctional silanes for display lamination and semiconductor packaging operations. METI industrial decarbonization roadmaps push coating formulators toward powder and waterborne modifier delivery systems. The Chubu region concentration of automotive sealant manufacturers sustains demand for precise viscosity window silicone modifiers.
India
The PLI scheme for chemical sector investment creates greenfield capacity opportunities for silane and polyacrylic modifier production serving domestic automotive tiers. BIS standards compliance requirements shape import substitution strategies among Mumbai and Ahmedabad coating formulators. Maharashtra and Gujarat textile finishing operations expand silicone emulsion consumption for fabric softening applications.
Surface Modifiers Market Competitive Landscape
Capability concentration sits with specialized dispersant and fluoropolymer formulators; scale advantage sits with diversified chemical conglomerates with integrated precursor supply. The vendor base organizes around three archetypes: integrated petrochemical majors with backward silane precursor control, mid-cap specialty additive houses with formulation technical service intensity, and regional distributors with specification platform digital reach. Competitive moves center on waterborne system qualification partnerships with automotive OEMs and powder coating line retrofit alliances with industrial applicators.
Among German-based chemical conglomerates, BASF SE and Evonik Industries AG occupy positions reflecting divergent strategic postures: Ludwigshafen-headquartered BASF SE exemplifies integrated supply chain architecture spanning precursor through formulated modifier, while Essen-based Evonik Industries AG represents specialized dispersant technical service intensity. US-based Dow Inc. anchors the silane chemistry breadth archetype with formulation support extension to Asian adhesive producers. These three entities collectively illustrate the capability-scale tension structuring competitive positioning.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| BYK (ALTANA) |
| Dow Inc. |
| Arkema |
| Elementis |
| Eastman Chemical Company |
| Air Products |
| Lubrizol Corporation |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor shapes cost dynamics across fluoropolymer modifier shipments, concentrating pricing power with German and Japanese precursor producers while downstream formulators absorb freight volatility through differentiated contract structures. This logistics tension amplifies margin pressure on mid-tier polyacrylic suppliers competing against integrated silicone majors with captive silane supply.
Pricing Analysis
Long-term offtake agreements dominate fluoropolymer procurement from German precursor producers, while spot markets govern silicone modifier transactions among Asian adhesive formulators. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-qualified fluoropolymers from automotive-grade silicones and commodity polyacrylics. Cost compression in waterborne polyacrylic tiers is intensifying because Chinese state-owned construction chemical manufacturers scale captive capacity. Electronics OEMs in Suzhou exhibit highest price sensitivity; medical device coating specialists in Massachusetts accept premium positioning for FDA 21 CFR compliance pathways.
Supply Chain Analysis
Contract manufacturing concentration for fluoropolymer modifier finishing sits with German specialty chemical houses in Ludwigshafen and Japanese producers in the Chubu region. Raw material supply draws from Chinese silane precursor operations, German organosiloxane feedstock, and French fluorotelomer intermediates. Single-source vulnerability runs through PTFE precursor allocation ahead of EU F-Gas Regulation phase-down milestones. Distribution runs through technical specification platforms displacing traditional multi-tier chemical distributors in China's Yangtze River Delta manufacturing belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is tilting toward consolidated automotive OEM procurement functions and captive electronics coating operations, fragmenting modifier demand across fewer volume accounts with tighter specification windows.
For Market Incumbents: Insulate formulation technical service relationships from price-only competition by embedding chemists at BMW and Toyota Tier 1 supplier facilities. Deepen backward integration into silane precursor production in Nanjing to match BASF's integrated cost position. The priority threat is specification-driven procurement platforms consolidating purchasing power among mid-volume coating producers. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized silane modifier capacity serving domestic automotive tiers. Target textile finishing operations in Maharashtra and Gujarat with silicone emulsion formulations bypassing established distributor relationships. A direct-to-formulator digital channel with automated sample fulfillment offers the cleanest go-to-market angle against legacy chemical distributors. For Investors and Strategic Acquirers: Specialized dispersant houses with USDA BioPreferred qualification capabilities represent the most defensible acquisition archetype as coating formulators reformulate for sustainability credentials. Long-term viability hinges on waterborne system performance parity with solvent-borne alternatives across heavy-duty industrial applications. The signal to watch is qualification velocity for short-chain fluorotelomer alternatives among German and French electronics coating specialists ahead of 2030 reduction milestones.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Precursors | Ludwigshafen and Nanjing integrated supply chains sustain cost-competitive silicone modifier output against Asian competitors. |
| Waterborne System Qualification Partnership | Collaborative testing with Stuttgart automotive OEMs accelerates REACH-compliant coating formulation adoption ahead of regulatory deadlines. |
| Direct-to-Formulator Digital Channel Launch | Technical specification platforms in China's Yangtze River Delta consolidate purchasing power with mid-volume industrial coating buyers. |
| Bio-Based Dispersant Convergence Investment | Enzymatic synthesis integration opens USDA BioPreferred-eligible formulation space for sustainable coatings procurement. |
| Powder Coating Line Retrofit Alliance | Electrostatic spray application partnerships with German automotive producers eliminate solvent recovery infrastructure capital requirements. |
Research Methodology
Initial hypotheses were tested against primary input from coating formulators, automotive OEM procurement leads, adhesive R&D directors, and specialty chemical distribution channel partners and refined through secondary validation against customs trade data, SEC 10-K filings, ECHA REACH registration databases, and Cefic sector reports. Bottom-up volume modeling triangulated against top-down value estimates across chemistry family, end-use industry, delivery form, and regional production hub segmentation dimensions.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with CAGR derivation reflecting segment-specific volume trajectories and value-per-ton adjustments for fluoropolymer premium positioning. Modeled dimensions included chemistry family, end-use industry tier, delivery form compatibility, and regional regulatory cluster. Forecast inputs incorporated automotive lightweighting procurement timelines and electronics captive coating expansion rates without year-specific milestone assumptions.
Stress conditions across fluoropolymer precursor allocation, REACH Annex XVII enforcement velocity, and waterborne performance gap closure were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory phase-down schedules and OEM qualification protocols. Cross-checking against ECHA substance volume tracking data and automotive production database benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Wax Additives Market
Additives
Viscosity Reducing Agents Market
Additives
North America Pectin Market
Additives
Middle East Lubricant Additives Market
Additives
Refining Additives Market
Additives
Sodium Stearyl Fumarate Market
Additives
Rheological Additives Market
Additives
Lauroyl Methyl Glucamide Market
Additives
Inorganic Rheology Modifiers Market
Additives
Supplemental Coolant Additives Market
Additives
2-Ethylhexyl Nitrate (2EHN) Market
Additives
Global Sodium Acetate Market
Additives
Global Anti-Fog Additives Market
Additives
Conditioning Agent Market
Additives
Global Flame Retardant Masterbatches Market
Additives
Global Coalescing Agent Market