
 Driveline Additives Market | 2026-2036
Driveline Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Driveline Additives Market Intelligence
Expanded production of polyalkylene glycol in Germany is narrowing the performance gap between synthetic and conventional axle fluids. The Lubrizol Corporation leverages its extensive R&D to develop specialized packages for electric vehicle transmissions. Afton Chemical Corporation sustains a strong position in friction modifiers for automatic transmissions. BASF SE competes with a broad portfolio of chemical precursors essential for additive synthesis.
Driveline additives are chemical compounds blended into lubricants like gear oils and transmission fluids to enhance specific performance characteristics. These agents are critical for improving properties such as thermal stability and shear resistance under high-torque conditions. Viscosity improvers and friction modifiers command the largest share by product type. Formulations for complex all-wheel drive systems represent a high-growth application, with OEM manufacturers increasingly specifying synthetic ester-based technologies.
Product formulation and market access are shaped by regulations like the EU's REACH framework and the US EPA's fuel economy standards. In China, GB standards for lubricants dictate minimum performance levels for additives. The central strategic decision for formulators is balancing the cost of advanced synthetic components against the performance demands of next-generation vehicle hardware.
Market Dynamics
The driveline additives market is defined by the technical and economic divergence between lubricants for legacy internal combustion engine vehicles and specialized fluids for electric and hybrid drivetrains. This bifurcation pressures formulators to manage parallel R&D streams while navigating disparate regulatory pressures and cost sensitivities across vehicle platforms.
Growth Catalysts
- Advanced Transmissions:The proliferation of automatic transmissions with a higher number of gear ratios and dual-clutch systems in passenger cars requires more sophisticated additive packages to manage heat, friction, and shear stability, directly increasing additive content per vehicle.
- Chinese Emission Standards:China's GB standards and its dual carbon goals are compelling commercial vehicle fleets to adopt higher-performance lubricants. This transition necessitates advanced additives that enable extended drain intervals and improved fuel efficiency in heavy-duty applications.
- Synthetic Base Stock Penetration:Growing OEM preference for factory-fill synthetic lubricants, particularly in Europe and North America, creates a corresponding demand for high-performance additive technologies designed to function optimally with polyalphaolefin (PAO) and ester base oils.
Market Restraints
- Base Oil Price Volatility:The cost and availability of key synthetic base stocks like polyalkylene glycols and esters, which are essential for high-performance formulations, are subject to significant price fluctuations tied to petrochemical feedstock markets, impacting formulator margins.
- Regulatory Compliance Costs:The European Union's REACH framework imposes extensive data submission and testing requirements for new chemical substances. This creates a significant cost and time-to-market barrier for novel additive chemistries, favoring established incumbent products.
- EV Fluid Consolidation:The trend towards single, multi-functional fluids in electric vehicles for cooling, lubrication, and power electronics management threatens to reduce the total volume of specialized driveline fluids required, potentially consolidating demand into fewer, more complex additive packages.
Strategic Opportunities
- EV-Specific Formulations:The nascent market for dedicated electric vehicle fluids presents a significant opportunity. Additives that address specific EV challenges like copper corrosion from motor windings, electrical conductivity control, and compatibility with new polymer materials represent a high-value growth area.
- Bio-based Lubricants:Increasing sustainability mandates create an opening for additives derived from renewable feedstocks. Developing high-performance, biodegradable friction modifiers or viscosity improvers can provide a competitive advantage, particularly in environmentally sensitive markets or applications.
- Emerging Market Vehicle Parcs:The expanding and modernizing vehicle parc in regions like Southeast Asia and Latin America offers growth potential. Formulators can target these markets with cost-effective additive packages that help local blenders meet more stringent, modern OEM performance standards.
Industry Challenges
- OEM Specification Complexity:A proliferation of unique, proprietary OEM specifications for transmission and axle fluids, especially for EVs, requires additive suppliers to engage in costly and duplicative testing and validation programs, increasing R&D overhead.
- Formulation Expertise Scarcity:A critical challenge is the shortage of tribologists and formulation chemists who possess dual expertise in traditional lubricant chemistry and the specific electrical and material science demands of electrified drivetrains.
- Testing and Standardization Lag:The absence of globally accepted testing protocols and performance standards for EV driveline fluids forces a fragmented, OEM-by-OEM approach to development, hindering economies of scale and slowing market-wide innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Driveline Additives Market |
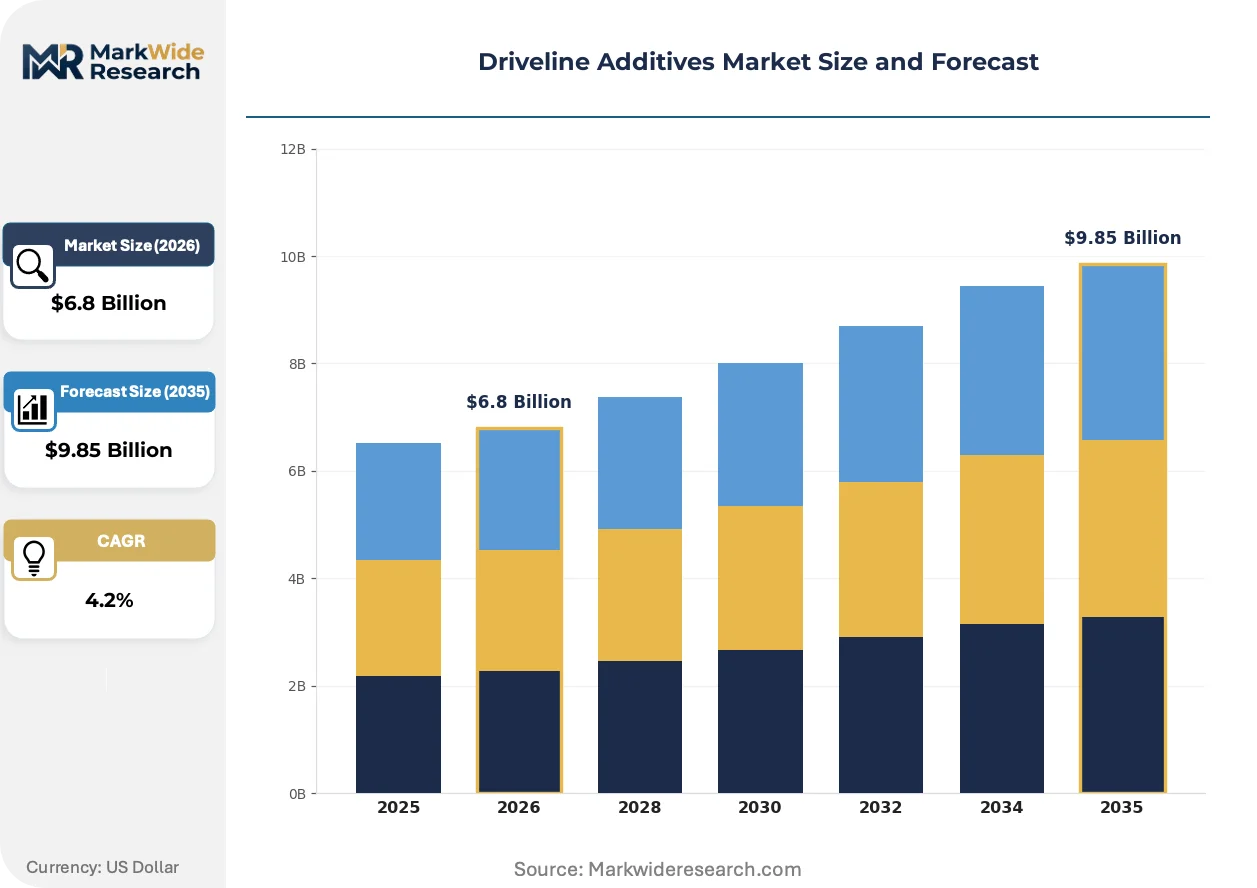
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Friction Modifiers, Viscosity Improvers, Anti-Wear Agents, Corrosion Inhibitors, Seal Conditioners Technology: Synthetic Ester, Polyalkylene Glycol, Zinc Dialkyldithiophosphate, Molybdenum Compounds, Sulfurized Olefins Application: Manual Transmissions, All-Wheel Drive Systems, Transfer Cases, Axle Systems, Differential Systems End User: OEM Manufacturers, Aftermarket Suppliers, Tier-1 Component Makers, Vehicle Refurbishers |
| Companies Covered | Afton Chemical Corporation, Vanderbilt Chemicals, LLC, The Lubrizol Corporation, Evonik Industries, BRB International B.V., Infineum International Ltd., BASF SE, Tianhe Chemicals Group, Chevron Oronite Company, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Driveline Additives Market Strategic Shifts & Innovations
The industry's innovation trajectory is increasingly tied to enabling hardware efficiency and sustainability. Development efforts are concentrating on creating additives that solve specific challenges posed by next-generation transmissions, electrified axles, and stricter environmental regulations, moving away from general-purpose solutions.
Low-viscosity formulations are a primary focus for additive development. These formulations, enabled by advanced viscosity improvers and friction modifiers, are critical for reducing energy losses within the drivetrain. Automakers are rapidly adopting these fluids to meet stringent fuel economy and emissions targets, creating strong demand. The market is migrating from reliance on broadly applicable viscosity grades to precisely engineered profiles for specific hardware like continuously variable transmissions.
United States EPA fuel economy regulations and associated state-level mandates from bodies like the California Air Resources Board exert significant influence on additive design. These rules directly incentivize the development of lubricants that can demonstrate a measurable reduction in parasitic driveline losses. Consequently, the performance of friction modifiers and viscosity index improvers in automatic and continuously variable transmission fluids is under intense scrutiny from OEMs seeking to gain compliance credits.
Original Equipment Manufacturers (OEMs) are specifying proprietary, factory-fill lubricant standards with increasing frequency. This practice displaces the reliance on generic industry specifications, such as those from the American Petroleum Institute, and shifts power to the additive companies capable of co-developing bespoke solutions. This demand for custom formulation is most advanced among European automotive brands but is quickly becoming standard practice for North American and Asian manufacturers of electric vehicles and advanced transmissions.
Driveline Additives Market Segmentation
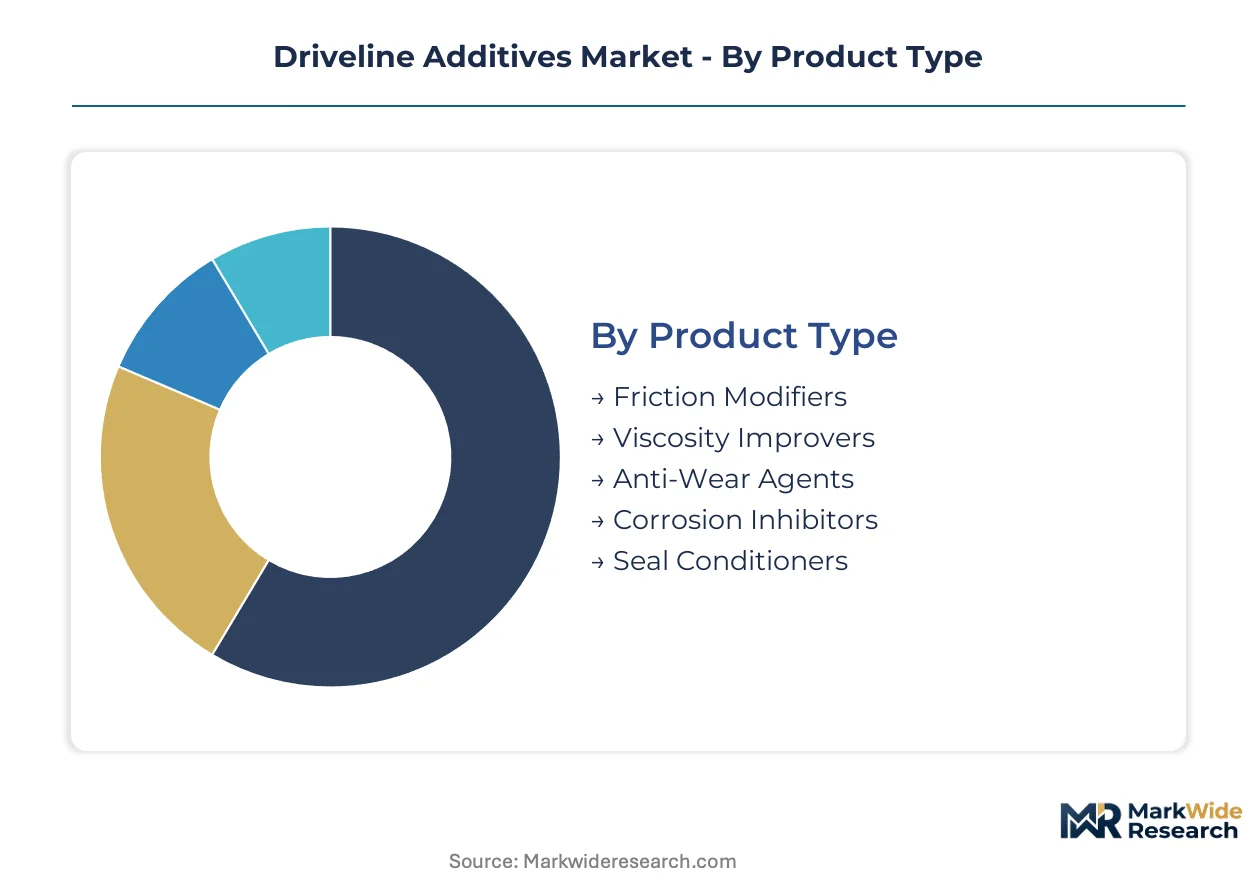
The driveline additives market segments by the intrinsic chemical properties of the additives, their technological basis, specific vehicle applications, and the end-user types. Understanding these distinctions is critical for formulators to align product development with evolving performance demands across the automotive industry.
Product Type:
The functional characteristics of driveline fluids are primarily defined by their additive compositions.
- Friction Modifiers:These compounds reduce friction between moving parts, optimizing energy transfer and preventing wear. Demand is concentrating in advanced automatic transmissions and continuously variable transmissions, where precise friction control is essential for smooth operation and fuel efficiency.
- Viscosity Improvers:Polymeric additives that modify the viscosity-temperature relationship of lubricants, ensuring stable fluid performance across varying operating conditions. These are critical for low-viscosity formulations adopted by OEMs in Europe and North America to meet fuel economy targets.
- Anti-Wear Agents:Chemical compounds that form a protective film on metal surfaces, preventing direct metal-to-metal contact and reducing abrasive wear under high-load conditions.
- Corrosion Inhibitors:Additives that protect metallic components within the driveline system from chemical degradation caused by moisture, acids, or other contaminants.
- Seal Conditioners:Agents designed to maintain the elasticity and integrity of elastomer seals, preventing leaks and extending component lifespan in various driveline systems.
Viscosity improvers hold installed capacity within the market. Friction modifiers are rotating up the share rankings.
Technology:
The chemical backbone of advanced driveline additives varies significantly across different technological approaches.
- Synthetic Ester:These synthetic base oils and additive components offer superior thermal stability, oxidation resistance, and lubricity compared to mineral oils. OEM manufacturers increasingly specify synthetic ester-based technologies for complex all-wheel drive systems.
- Polyalkylene Glycol:PAGs are synthetic base stocks with excellent thermal stability and lubricity, particularly in high-temperature applications. Expanded production in Germany is narrowing the performance gap between synthetic and conventional axle fluids.
- Zinc Dialkyldithiophosphate:ZDDP compounds function as anti-wear and antioxidant additives, widely used in various lubricant formulations.
- Molybdenum Compounds:Molybdenum-based additives, such as molybdenum disulfide, provide extreme pressure and friction modifying properties, especially in heavy-duty applications.
- Sulfurized Olefins:These compounds serve as extreme pressure additives, forming protective layers on metal surfaces to prevent seizure under high loads and temperatures.
Synthetic ester formulations are gaining traction for high-performance applications, while polyalkylene glycol technologies are broadening their market penetration.
Application:
Specific vehicular applications dictate the precise performance requirements for driveline fluids.
- All-Wheel Drive Systems:These complex drivetrains require specialized lubricants with high shear stability and specific friction characteristics to manage power distribution effectively. Formulations for these systems represent a high-growth application segment.
- Axle Systems:Lubricants for axle systems must withstand high loads and temperatures, requiring robust anti-wear and extreme pressure additives. Germany's focus on polyalkylene glycol production supports advanced axle fluid development.
- Manual Transmissions:Fluids for manual transmissions require good gear protection, synchronizer performance, and thermal stability.
- Transfer Cases:These components, often found in 4x4 vehicles, require fluids capable of handling torque transfer and maintaining performance under varying conditions.
- Differential Systems:Lubricants for differentials must manage high contact pressures and sliding friction, necessitating effective extreme pressure additives.
All-wheel drive systems represent the fastest-growing trajectory for specialized additive demand.
End User:
The distribution channels and purchasing power for driveline additives differ considerably among end-user segments.
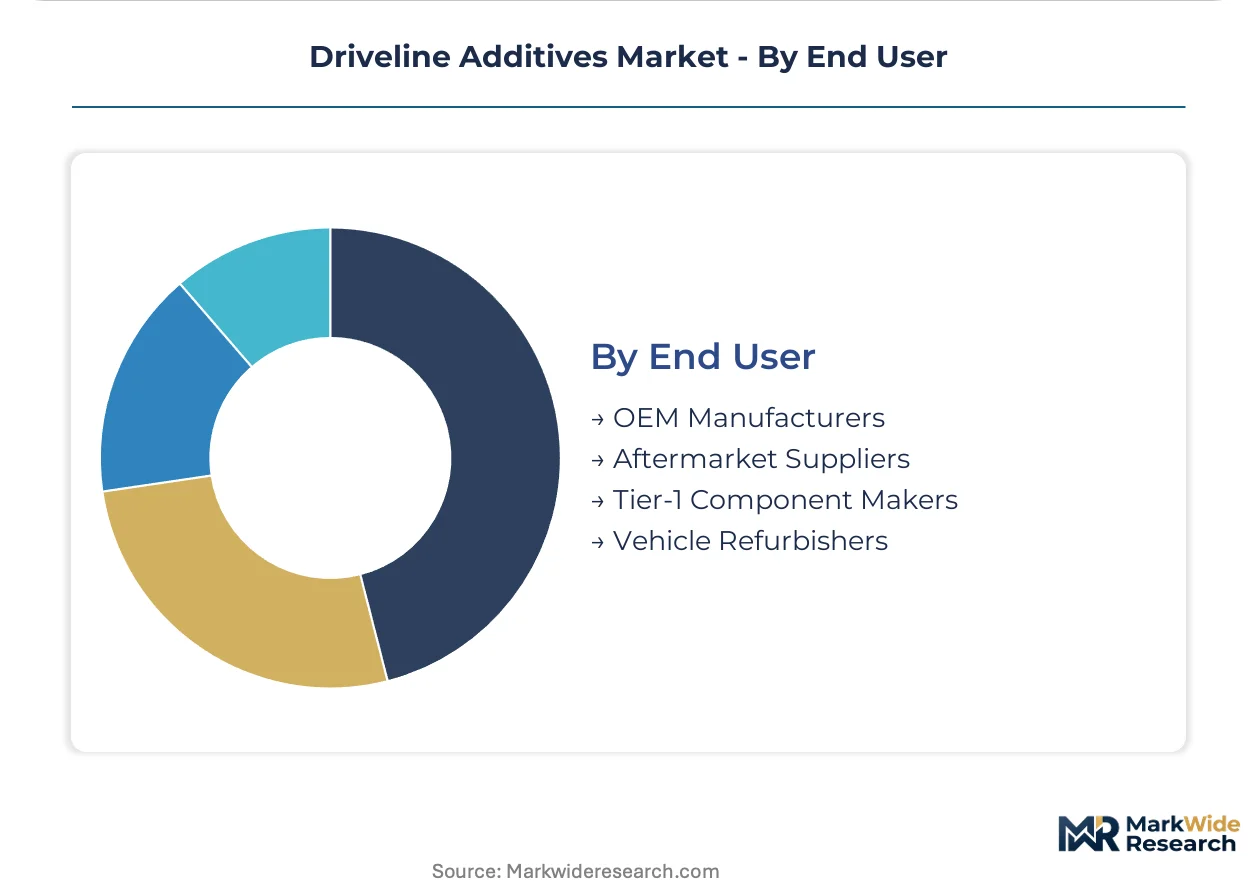
- OEM Manufacturers:These entities specify proprietary, factory-fill lubricant standards for new vehicles, driving demand for custom additive packages. European automotive brands lead in specifying bespoke solutions for their advanced transmissions and electric vehicles.
- Aftermarket Suppliers:Companies providing replacement fluids and service components to the repair and maintenance sector. These suppliers require additive packages that meet broad industry specifications for a diverse range of vehicles.
- Tier-1 Component Makers:Suppliers to OEMs who may require specialized lubricants for initial fill in components like transmissions or axles before vehicle assembly.
- Vehicle Refurbishers:Businesses that restore or rebuild vehicles, requiring driveline fluids that meet original equipment specifications or equivalent performance standards.
OEM manufacturers command a significant portion of new fluid development, with aftermarket suppliers driving volume for service fills.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals significantly influence the global driveline additives market. These ambitious targets drive demand for advanced, fuel-efficient lubricant formulations, especially within the heavy-duty commercial vehicle sector. The shift towards lower-viscosity fluids to reduce energy losses is a direct consequence of these environmental directives.
China
Demand for advanced lubricants in China stems from stringent GB standards for commercial vehicle fleets. The dual carbon goals push for extended drain intervals and improved fuel efficiency, necessitating specialized additives. Major automotive manufacturing clusters, such as those in the Yangtze River Delta, concentrate this demand for high-performance fluids.
Germany
Germany's automotive industry drives demand for high-performance driveline additives, particularly for advanced transmissions. The EU's REACH framework regulates the introduction of new chemical substances, influencing formulation strategies. Expanded polyalkylene glycol production in chemical hubs like Ludwigshafen supports advanced axle fluid development.
United States
US EPA fuel economy regulations incentivize the development of low-viscosity driveline fluids to reduce parasitic losses. OEMs in North America increasingly specify factory-fill synthetic lubricants, requiring high-performance additive technologies. Automotive manufacturing centers in Michigan are a focal point for advanced fluid development and testing.
Japan
Japanese automakers seek specialized driveline additives to enhance the efficiency of their advanced transmissions and hybrid vehicles. METI policies encourage innovation in sustainable automotive technologies, including bio-based lubricants. The automotive R&D centers around Nagoya drive the development of bespoke fluid solutions.
India
India's expanding vehicle parc and evolving emission norms are increasing the need for modern driveline additives. BIS standards for lubricants are becoming more stringent, requiring improved performance and longer drain intervals. Automotive manufacturing clusters in Tamil Nadu and Maharashtra generate substantial demand for these advanced formulations.
Driveline Additives Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a multifaceted competitive landscape in driveline additives. The market exhibits a tiered structure, with a few large integrated chemical companies alongside specialized additive formulators. Strategic archetypes include global chemical conglomerates offering broad portfolios, niche specialists focusing on high-performance applications, and regional suppliers adapting to local standards. Dominant competitive moves involve strategic partnerships for co-development and continuous portfolio diversification to address new vehicle technologies and evolving regulatory requirements.
Specialized additive formulators like Afton Chemical Corporation exemplify the focus on friction modifiers for automatic transmissions, catering to evolving OEM demands for fuel efficiency. The Lubrizol Corporation represents a major player leveraging extensive R&D to develop specialized packages for electric vehicle transmissions, addressing challenges like copper corrosion. Global chemical entities such as BASF SE occupy a position supplying essential chemical precursors for additive synthesis across various segments, from conventional to electric vehicle fluids. These companies anchor different aspects of innovation and supply within the driveline additives ecosystem, reflecting the market's technical complexity.
| Leading Market Players |
|---|
| Afton Chemical Corporation |
| Vanderbilt Chemicals, LLC |
| The Lubrizol Corporation |
| Evonik Industries |
| BRB International B.V. |
| Infineum International Ltd. |
| BASF SE |
| Tianhe Chemicals Group |
| Chevron Oronite Company, LLC |
| Others |
Cost & Logistics Intelligence
The Suez Canal's cost dynamics, influenced by geopolitical events and shipping capacity, directly impact the global supply of chemical precursors for driveline additives. This volatility in freight costs exacerbates supply concentration, ultimately shaping downstream price differentiation for specialized fluid formulations.
Pricing Analysis
Geographic price spreads for driveline additives vary significantly, with premium formulations commanding higher prices in regulated markets like Europe. The dominant pricing model is contract-based long-term offtake, often differentiated by quality grade and the level of customization required for specific OEM specifications. Pricing softness stems from intense competition among regional blenders in emerging markets. OEM manufacturers exhibit low price sensitivity for factory-fill fluids, while aftermarket suppliers are highly sensitive to cost fluctuations.
Supply Chain Analysis
Export-control regimes, particularly those governing advanced chemical technologies, limit the free flow of certain high-performance additive components. Supply concentrates in key chemical manufacturing hubs across China, Germany, and the United States, which source petrochemical feedstocks and specialized synthetic base stocks like polyalkylene glycols and esters. Commodity price volatility for these raw materials represents a significant supply chain risk, impacting formulator margins. Distribution runs primarily through direct sales to lubricant blenders and OEM manufacturers globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The driveline additives market presents a fragmentation opportunity driven by the bifurcation of lubricant demand between legacy internal combustion engines and specialized electric vehicle fluids. This divergence creates distinct niches for highly tailored additive packages.
For Market Incumbents: Harden core positions in conventional driveline additive segments by optimizing cost structures and supply chain resilience. Invest heavily in electric vehicle fluid R&D to counter the threat of EV fluid consolidation, which could reduce total specialized fluid volumes. Secure long-term raw material contracts for essential synthetic base stocks to mitigate price volatility. Focus R&D on EV-specific formulations addressing copper corrosion and electrical conductivity.
For New Entrants and Emerging Players: Bio-based lubricants for driveline systems represent a penetrable entry point, particularly in environmentally sensitive markets like Europe. Target cost-effective additive packages for modernizing vehicle parcs in Southeast Asia and Latin America, where local blenders need to meet evolving performance standards. A go-to-market angle focusing on sustainability certifications and localized technical support can differentiate offerings. Specialize in high-performance friction modifiers for advanced automatic transmissions in these regions.
For Investors and Strategic Acquirers: Carve-out targets emerge from large integrated chemical companies divesting non-core additive portfolios. The long-term viability of the driveline additives market remains strong over the next five to ten years, driven by electrification and advanced transmission needs. Seek out specialized additive formulators with deep expertise in EV fluid chemistry or sustainable bio-based solutions. A signal to watch is the acceleration of global EV fluid standardization initiatives, which could consolidate market demand.
| Strategic Initiative | Industry Significance |
|---|---|
| EV Fluid R&D Acceleration | Develop specialized packages for electric vehicles, addressing copper corrosion and electrical conductivity challenges. |
| Bio-based Additive Development | Capture demand for sustainable solutions, aligning with EU Green Deal mandates and OEM sustainability goals. |
| Global Supply Chain Optimization | Mitigate petrochemical feedstock price volatility and ensure reliable delivery of essential synthetic components. |
| OEM Co-Development Partnerships | Secure factory-fill specifications for next-generation transmissions and EV drivetrains with leading automotive brands. |
| Regional Market Penetration | Expand presence in Southeast Asia with cost-effective additive solutions meeting local BIS and GB standards. |
Research Approach
A spread of perspectives from technical R&D directors, OEM platform engineers, lubricant blenders, and regulatory affairs leads converged on the working assumptions for this analysis. Primary interviews were combined with rigorous secondary validation using customs/trade data, SEC 10-K filings, and industry association reports. Vehicle production databases provided critical market context. This approach employed both bottom-up market sizing and top-down validation through triangulation.
Demand-supply balance formed the core analytical framework over the projection horizon, integrating market dynamics and technological shifts. Segmentation dimensions modeled included product type, technology, application, end-user, and regional production clusters. Compound annual growth rates were derived from historical trends and forward-looking projections of key market drivers. Vehicle parc electrification rates and OEM specification evolution served as critical industry-specific forecast inputs.
Stress conditions across petrochemical feedstock prices and regulatory policy shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technological adoption and market maturation. Material shifts in geopolitical stability or raw material supply would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Sodium Caprylate Market
Additives
Global Corrosion Inhibitor Market
Additives
Caprylyl Glycol Market
Additives
Defoaming Coating Additives Market
Additives
Plasticizer Alcohols Market
Additives
Tartaric Acid Market
Additives
Cetane Improver Additives Market
Additives
Mycotoxin Binders Market
Additives
Zinc Dialkyldithiophosphates Additive Market
Additives
Weighing Agents Market
Additives
Plastics Modifiers Market
Additives
Sodium Benzoate Market
Additives
Polysaccharides and Oligosaccharides Market
Additives
Alginic Acid Market
Additives
Sodium Diacetate Market
Additives
Extruded Inclusions Market