
 Global Rheology Modification Coating Additives Market | 2026-2036
Global Rheology Modification Coating Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rheology Modification Coating Additives Market Analysis
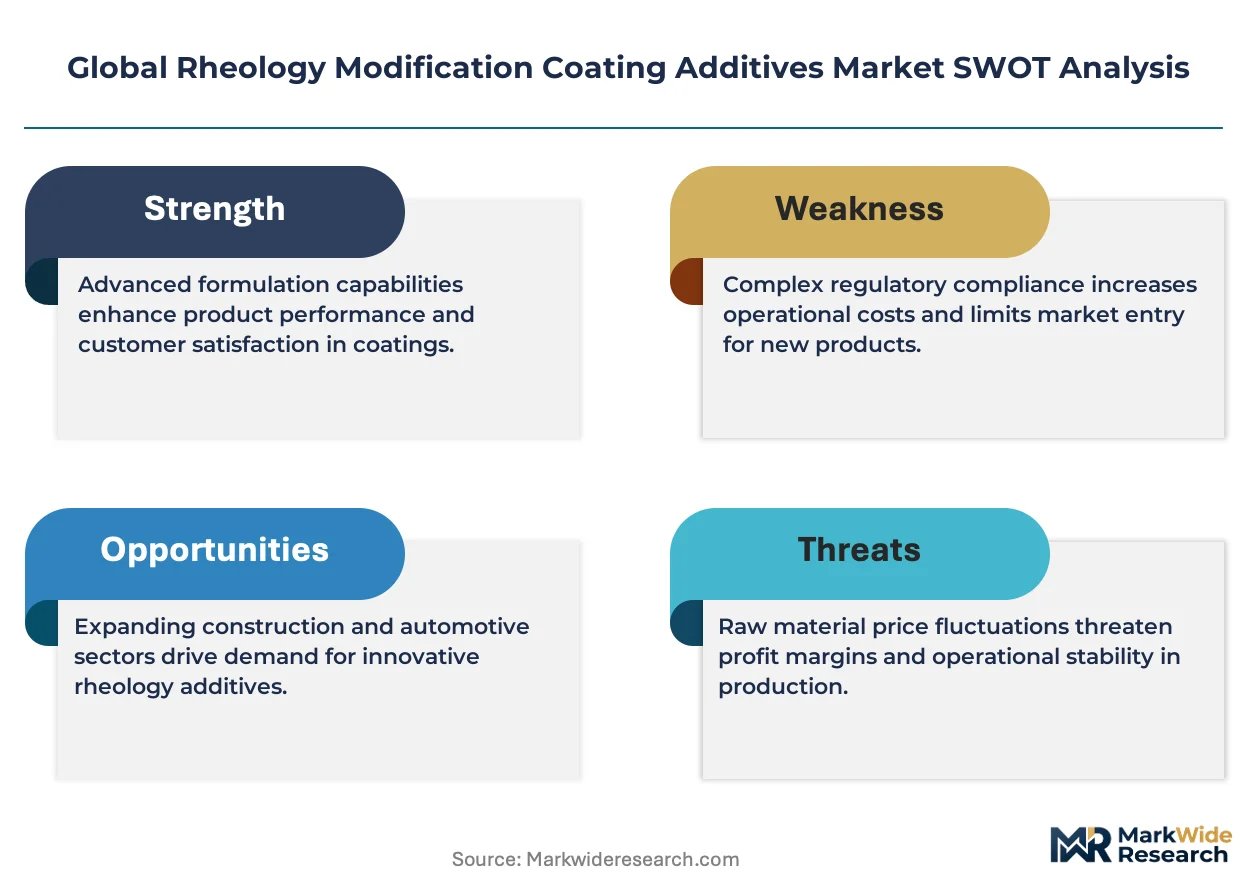
REACH is restructuring compliance costs for European additive suppliers and their downstream coating customers. BASF SE leverages its integrated acrylic monomer-to-additive chain to absorb regulatory testing burdens that strain smaller competitors. Dow Inc. anchors North American supply through water-based rheology modifier production scaled for architectural coatings. Arkema differentiates via high-solids organoclay technologies that reduce solvent dependency without sacrificing sag resistance.
Rheology modification coating additives are chemical agents that control viscosity, thixotropy, and flow behavior in liquid coating systems, typically functioning at loadings of 0.5–5.0 wt% to prevent pigment settling and application defects. They operate by building structured networks within the fluid phase through hydrogen bonding, electrostatic interactions, or particle association, enabling precise control over sprayability, brush drag, and film build in industrial finishing operations. Acrylic additives dominate volume in architectural and automotive OEM coatings where predictable shear-thinning profiles support automated application equipment. Water-based formulations represent the fastest-expanding formulation type segment as regulatory pressure and consumer preference displace solvent-borne systems across construction and automotive refinishing end uses.
EPA VOC regulations in the United States, EU REACH restrictions on hazardous substance authorization, and China's MEE emission standards collectively tighten permissible chemistries and push reformulation cycles. These frameworks elevate demand for low-VOC cellulosic and associative thickeners that maintain performance while satisfying multi-jurisdiction compliance. Stakeholders must monitor divergence between regional chemical restriction schedules to avoid stranded inventory and misaligned R&D commitments.
Market Dynamics
Water-based formulation mandates across automotive OEM and architectural coatings are compressing reformulation cycles and elevating procurement of associative thickeners and cellulosic alternatives that maintain sag resistance without solvent dependency.
Growth Catalysts
- EU F-Gas Regulation:German automotive OEMs are expanding water-based coating lines to comply with tightening VOC limits, driving specialized additive procurement for precision film build control.
- Semiconductor packaging clusters:East Asian electronics manufacturing hubs demand rheology modifiers with ultra-low ionic content for wafer-level packaging applications.
- Acrylic additive platforms:Predictable shear-thinning profiles from associative acrylic thickeners support automated spray equipment deployment in high-volume automotive finishing operations.
Market Restraints
- Organoclay supply concentration:High-grade bentonite feedstock for thixotropic additives concentrates in specific mining districts, exposing formulators to geological and logistics disruptions.
- REACH authorization costs:ECHA's Substances of Very High Concern list expansion forces additive suppliers to absorb six-figure testing burdens or abandon chemistries.
- Cellulosic ether substitution ceiling:HEC and HPMC thickeners face performance boundaries in high-solids industrial coatings where solvent-borne alkyd systems still dominate.
Strategic Opportunities
- India's PLI scheme for electronics:Domestic semiconductor and PCB manufacturing incentives create localized demand for precision coating additives with import-substitution potential.
- UV-curable hybrid systems:Convergence of photoinitiator technology with rheology control enables single-coat processes that eliminate flash-off stages in furniture coatings.
- Direct-to-contractor digital channels:Architectural coatings brands are bypassing distributor tiers to capture specification data and accelerate reformulation feedback loops.
Industry Challenges
- Formulation chemist scarcity:Expertise in water-borne rheology network design—balancing hydrogen bonding, electrostatic stabilization, and particle association—commands premium compensation and extends hiring timelines.
- Multi-jurisdiction compliance synchronization:Divergence between EPA VOC rules, REACH authorization schedules, and China's MEE emission standards strains inventory planning and R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rheology Modification Coating Additives Market |
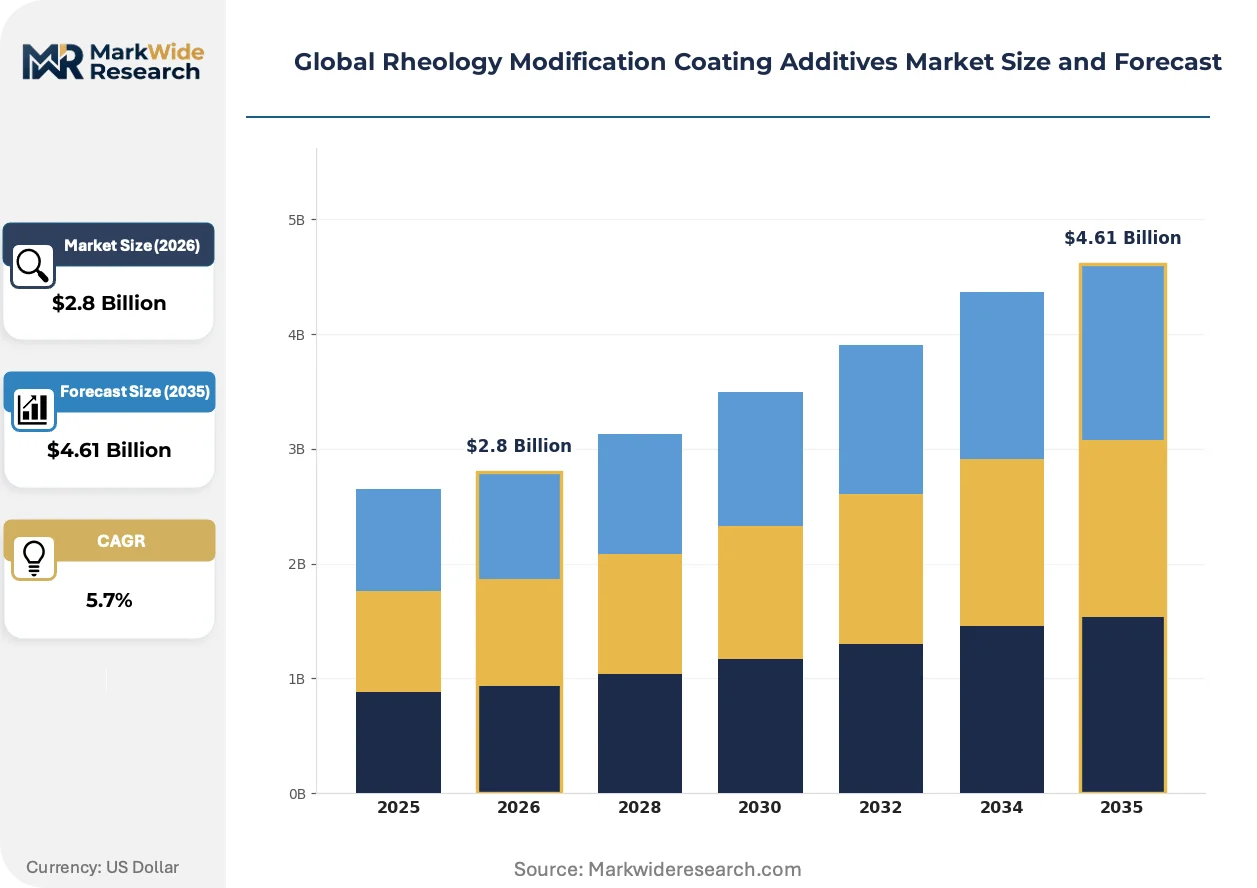
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Cellulosic, Organic, Inorganic Application: Coatings, Adhesives, Sealants, Inks End User: Construction, Automotive, Aerospace, Electronics Formulation Type: Water-Based, Solvent-Based, Powder, Paste |
| Companies Covered | BASF SE, Dow Inc., Arkema, ALTANA AG, Ashland Inc., Evonik Industries AG, Nouryon, Eastman Chemical Company, Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rheology Modification Coating Additives Market Emerging Trajectories
Formulation chemistry is pivoting toward bio-based and hybrid architectures that reconcile performance thresholds with chemical hazard reduction mandates across automotive, electronics, and construction end uses.
Nano-structured silica rheology modifiers are integrating into high-solids industrial coatings to provide thixotropic control at loadings below traditional organoclay thresholds. Japanese automotive refinishing shops are adopting these platforms to meet METI chemical management protocols while maintaining sag resistance on vertical surfaces. The technology is integrating spray application windows previously reserved for solvent-borne systems, compressing the performance gap between regulatory-compliant and legacy formulations.
REACH authorization timelines are compressing available chemistries for European coating formulators, with ECHA's SVHC candidate list expansion accelerating substitution programs for phthalate-based and certain organotin catalyst systems. Industrial maintenance coatings in Germany and France face the tightest substitution deadlines, driving joint development agreements between additive suppliers and OEM technical centers to validate alternative network-building mechanisms.
Specification authority is migrating from distributor technical representatives to centralized procurement functions at multinational coatings manufacturers, consolidating volume commitments and demanding standardized performance data packages. This concentration compresses switching costs for qualified suppliers while raising barriers for niche additive developers lacking global compliance documentation. The shift is most visible in North American architectural coatings, where national account structures now dominate specification decisions previously fragmented across regional distributor networks.
Global Rheology Modification Coating Additives Market Segmentation
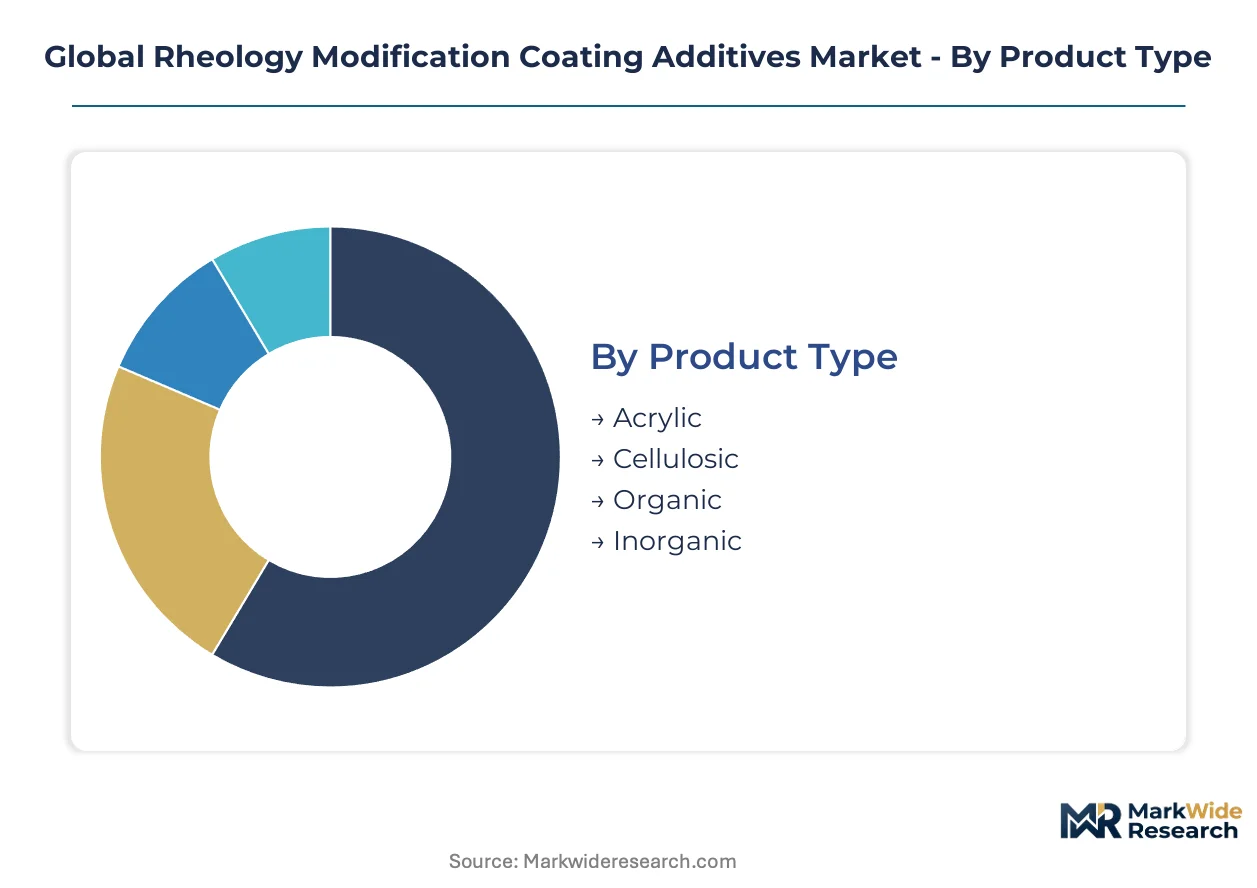
Rheology modification coating additives serve divergent performance requirements across formulation chemistries and end-use specifications. Segmentation reveals where volume concentration clashes with premium pricing power, guiding supplier resource allocation and R&D prioritization.
Product Type:
Acrylic platforms dominate tonnage in commodity architectural coatings while cellulosic alternatives command premium positioning in regulated industrial applications.
- Acrylic:Associative thickeners built from hydrophobically modified alkali-swellable emulsions deliver predictable shear-thinning profiles. Demand concentrates in German and Japanese automotive OEM water-based lines where automated spray equipment requires consistent viscosity recovery rates under EU F-Gas and METI protocols.
- Cellulosic:Hydroxyethyl cellulose and hydroxypropyl methylcellulose derivatives build viscosity through hydrogen-bonded gel networks. Procurement from French and German industrial maintenance coatings accelerates as REACH SVHC deadlines force substitution away from phthalate-based alternatives.
- Organic:Polyurethane associative thickeners and castor oil derivatives serve niche high-solids formulations.
- Inorganic:Fumed silica and precipitated calcium carbonate provide thixotropic control in powder coatings and high-temperature industrial systems.
Today's leader: Acrylic. Tomorrow's challenger: Cellulosic.
Application:
Coatings absorb the majority of rheology modifier volume while adhesives and sealants represent higher-margin specialty opportunities with tighter specification requirements.
- Coatings:Architectural and industrial finishing operations require sag resistance, leveling, and pigment suspension across spray, brush, and roll application methods. Water-based architectural coatings in the United States drive cellulosic and associative acrylic procurement under EPA VOC compliance timelines.
- Adhesives:Structural bonding applications demand precise viscosity control for bead consistency and open time management. Japanese electronics manufacturers specify ultra-low ionic content rheology modifiers for semiconductor packaging adhesives under METI chemical management protocols.
- Sealants:Polyurethane and silicone formulations require thixotropic behavior for gun-grade application without slump.
- Inks:Screen and inkjet printing systems depend on shear-thinning recovery for dot gain control and substrate adhesion.
Coatings anchor current volume. Adhesives are climbing the fastest as electronics packaging specifications tighten.
End User:
Construction generates the highest additive consumption by tonnage while electronics and aerospace concentrate the most stringent purity and performance specifications.
- Construction:Interior and exterior architectural coatings account for the largest absolute volume of cellulosic and acrylic thickeners. China's MEE emission standards and urbanization patterns in India drive water-based formulation conversion across residential and commercial building stock.
- Automotive:OEM clearcoats and basecoats demand sag resistance on vertical surfaces combined with excellent leveling for appearance. German manufacturers expanding water-based lines under EU F-Gas Regulation procure specialized additives for precision film build.
- Aerospace:High-solids and chrome-free primers require rheology control under extreme temperature and chemical exposure conditions.
- Electronics:Wafer-level packaging and PCB conformal coatings specify ultra-low sodium and chloride ion content to prevent corrosion. East Asian manufacturing clusters in Taiwan, South Korea, and Japan drive specialized procurement with import-substitution potential under India's PLI scheme.
Construction owns today's tonnage. Electronics commands tomorrow's margin expansion.
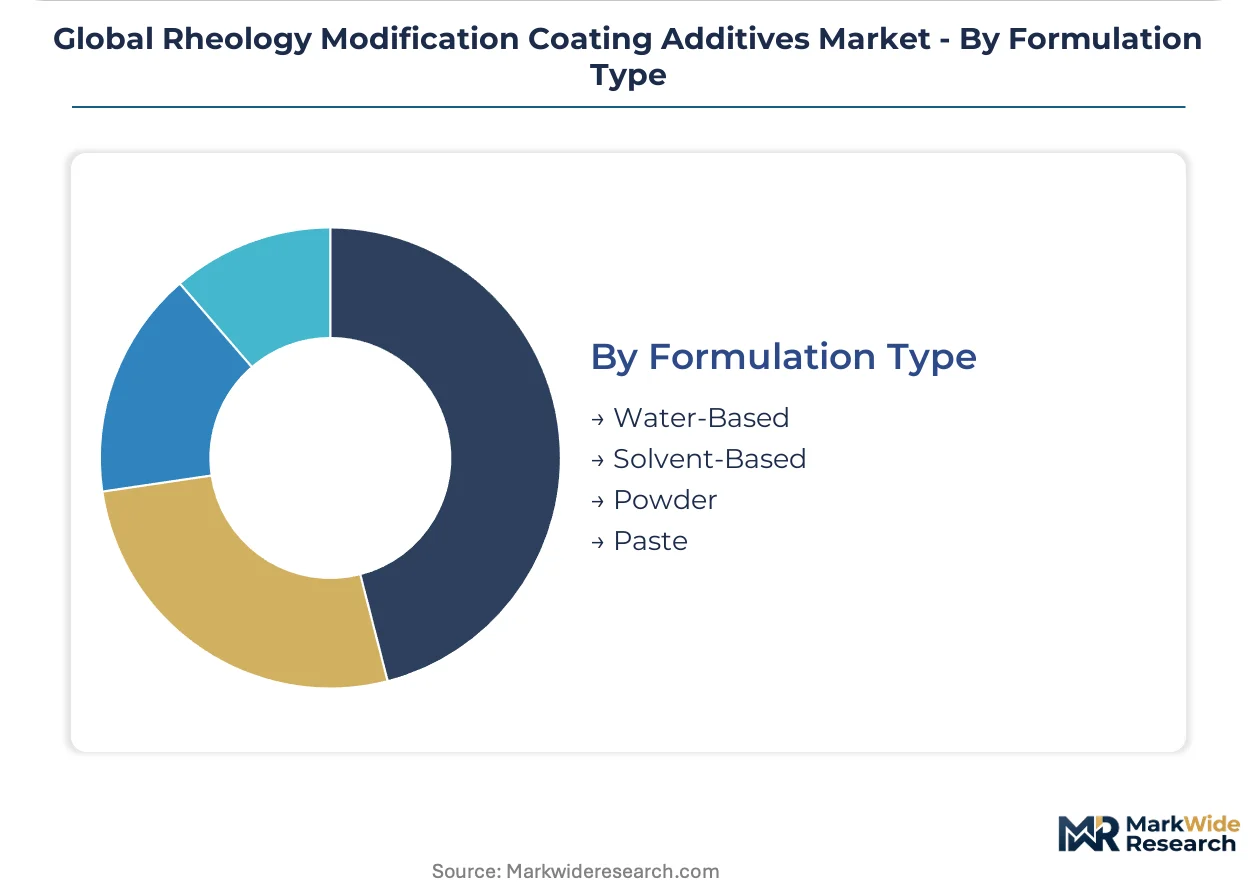
Formulation Type:
Water-based systems are displacing solvent-borne alternatives across regulatory jurisdictions while powder coatings offer zero-VOC solutions with distinct rheology control challenges.
- Water-Based:Associative thickeners and cellulosic ethers build structure through hydrophobic association and hydrogen bonding in aqueous continuous phases. German automotive OEMs and US architectural coatings manufacturers lead procurement as EPA, REACH, and MEE frameworks compress reformulation cycles.
- Solvent-Based:Organoclay and fumed silica technologies dominate high-solids industrial maintenance coatings where solvent-borne alkyds retain performance advantages. Supply concentrates in specific bentonite mining districts, exposing formulators to geological disruption risks.
- Powder:Flow control additives manage melt viscosity and edge coverage during thermal cure without liquid-phase rheology mechanisms.
- Paste:Concentrated additive dispersions simplify incorporation into high-throughput manufacturing lines.
Water-based formulations hold expanding share. Powder systems represent the steepest expansion trajectory in heavy industrial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists with expertise in water-borne rheology network design concentrate in Germany, Japan, and the United States, anchoring regional innovation capacity for automotive OEM and electronics applications.
United States
Architectural coatings manufacturers in the Midwest and Southeast drive cellulosic and associative acrylic procurement under EPA VOC compliance timelines. The country's emission standards compress reformulation cycles for residential and commercial building stock. Manufacturing clusters in Ohio and Texas specialize in high-throughput water-based production lines serving national distribution networks.
Germany
Automotive OEM clearcoat and basecoat operations in Bavaria and Baden-Württemberg demand sag resistance combined with precision leveling for appearance quality. EU F-Gas Regulation mandates are accelerating water-based line expansions at technical centers near Stuttgart and Munich. Industrial maintenance coatings in the Ruhr region face REACH SVHC substitution deadlines for phthalate-based network-building chemistries.
Japan
Semiconductor packaging and PCB conformal coating specifications in the Kanto and Kansai regions require ultra-low sodium and chloride ion content to prevent corrosion. METI chemical management protocols govern additive procurement for wafer-level applications. Electronics manufacturing clusters in Tokyo, Osaka, and Nagoya drive specialized demand for precision rheology control.
China
Construction sector water-based formulation conversion in the Yangtze River Delta and Pearl River Delta absorbs tonnage of cellulosic thickeners for interior and exterior architectural coatings. MEE emission standards tighten permissible chemistries across residential and commercial building applications. Manufacturing scale in Jiangsu and Guangdong provinces supports cost-optimized production for domestic and export markets.
India
Domestic semiconductor and PCB manufacturing incentives under the PLI scheme create localized demand for precision coating additives with import-substitution potential. BIS standards and DGFT regulations shape chemical compliance frameworks for emerging electronics clusters. Karnataka and Tamil Nadu manufacturing zones are attracting technical talent for water-borne formulation development.
Global Rheology Modification Coating Additives Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation technology tiers, creating a bifurcated structure where scale advantages clash with customization agility. The vendor base organizes around three strategic archetypes: integrated chemical majors with captive monomer supply, additive-focused mid-caps with application technical service, and regional compounders with rapid formulation turnaround. Consolidation pressure intensifies as REACH authorization costs and multi-jurisdiction compliance documentation requirements raise barriers for smaller participants. Competitive moves center on backward integration into acrylic monomer production and strategic partnerships with automotive OEM technical centers for qualification protocols.
Among European-based integrated chemical majors, BASF SE exemplifies the archetype of monomer-to-additive chain control that absorbs regulatory testing burdens. Dow Inc. anchors North American supply positioning through water-based rheology modifier production scaled for architectural coatings. Arkema occupies a specialist position within the high-solids organoclay technology tier, representing differentiation through reduced solvent dependency without performance sacrifice.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Arkema |
| ALTANA AG |
| Ashland Inc. |
| Evonik Industries AG |
| Nouryon |
| Eastman Chemical Company |
| Clariant AG |
| Others |
Supply Flow & Price Mechanics
Bentonite feedstock price indices from Wyoming and Turkey mining districts cascade through organoclay additive tiers, compressing margins at the standard-grade level while premium associative thickeners built on captive acrylic monomer supply retain pricing power. German automotive OEMs and Japanese electronics manufacturers absorb higher per-kilogram costs for REACH- and METI-compliant specialty grades, whereas Chinese architectural coatings producers drive volume procurement of cellulosic alternatives at contract-indexed rates.
Pricing Analysis
Service bundling separates formulation technical support from base product supply, with integrated suppliers like BASF SE and Dow Inc. commanding premium positioning through embedded regulatory documentation and application testing. Price differentiation hinges on certification tier—ECHA SVHC compliance and METI chemical management protocols—and volume scale, with national account structures consolidating procurement at multinational coatings manufacturers. Pricing pressure stems from REACH authorization cost absorption straining smaller additive suppliers, forcing price erosion in the standard-grade tier. Regional compounders exhibit highest price sensitivity due to limited compliance documentation budgets, while German automotive OEMs demonstrate lowest sensitivity given qualification switching costs.
Supply Chain Analysis
Dual-sourcing mandates from German and Japanese automotive OEMs require qualification of at least two additive suppliers per formulation platform, compressing single-source dependency risks. Geographic supply concentration centers on the United States for high-purity bentonite feedstock, Germany for acrylic monomer-to-additive integration, and China for cellulosic ether production scale. Raw material dependencies include Wyoming-mined bentonite for organoclay thixotropes, bio-based cellulose pulp for HEC and HPMC derivatives, and propylene oxide for polyurethane associative thickeners. Supply chain risk concentrates in tariff exposure on Chinese-sourced cellulosic ethers under evolving trade frameworks. Distribution runs through national account structures at multinational coatings manufacturers, bypassing traditional distributor tiers in North American architectural coatings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through water-based formulation conversion compressing reformulation cycle frequency and elevating premium-tier procurement for regulatory-compliant specialty additives.
For Market Incumbents: Deepen backward integration into acrylic monomer production to absorb REACH testing burdens that strain smaller competitors, while expanding technical service capacity at automotive OEM technical centers in Stuttgart and Munich to defend against emerging pure-play specialists with rapid formulation turnaround capabilities. For New Entrants and Emerging Players: Launch via direct-to-contractor digital channels in Indian architectural coatings, targeting Karnataka and Tamil Nadu manufacturing zones where BIS standards create qualification barriers for established suppliers but local formulation expertise remains scarce. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH authorization costs and multi-jurisdiction compliance documentation requirements exceed six-figure thresholds, favoring acquisition of regional compounders with captive customer relationships and rapid reformulation capabilities as the signal to watch for inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Production | BASF SE's captive supply chain absorbs ECHA testing burdens that strain additive-only competitors. |
| Joint Development Agreement with Automotive OEM Technical Centers | Qualification protocols at Stuttgart and Munich facilities lock in specification authority for water-based clearcoats. |
| Direct-to-Contractor Digital Channel Launch | Architectural coatings brands bypass distributor tiers to capture reformulation feedback loops in North America. |
| Ultra-Low Ionic Content Additive Platform Development | East Asian semiconductor packaging clusters in Taiwan and South Korea drive specialized procurement premiums. |
| Regional Compounder Acquisition in India | PLI scheme incentives for domestic semiconductor manufacturing create import-substitution demand for precision additives. |
Methodological Framework
Direct dialogue with formulation chemists at German automotive OEMs, procurement leads at Japanese electronics manufacturers, distribution channel partners in North American architectural coatings, and technical R&D directors at integrated chemical majors grounded qualitative findings. Secondary validation drew from ECHA SVHC candidate list publications, EPA VOC regulation dockets, METI chemical management protocol updates, SEC 10-K filings from diversified chemical conglomerates, and customs trade data on bentonite and cellulosic ether imports. Bottom-up segment sizing triangulated against top-down market reconstruction across product type, application, end user, and formulation type dimensions.
Segment-level projections across the analysis window integrated water-based formulation conversion rates by end-use industry, REACH authorization timeline impacts on available chemistries, and regional regulatory divergence patterns. Modeled dimensions spanned acrylic, cellulosic, organic, and inorganic product types; coatings, adhesives, sealants, and inks applications; construction, automotive, aerospace, and electronics end users; and water-based, solvent-based, powder, and paste formulation types. CAGRs derived from regression analysis against historical formulation shift elasticities and regulatory mandate implementation schedules, with semiconductor packaging content-per-unit and automotive OEM water-based line expansion serving as industry-specific demand drivers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH SVHC list expansion or sustained bentonite supply disruption from Wyoming mining districts. Projections reflect assumptions on regulatory implementation timelines, substitution technology performance convergence, and raw material price trajectory stability. Deviation in EU F-Gas Regulation enforcement intensity or China's MEE emission standard acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Pour Point Depressant Market
Additives
United Kingdom Feed Additives Market
Additives
Antiscalants/Scale Inhibitors Market
Additives
Tamarind Gum Derivatives Market
Additives
Green Chelates/Natural Chelating Agents Market
Additives
Tris Nonylphenyl Phosphite Market
Additives
Anti-Creasing Agent Market
Additives
Global Metal Scavenging Agents Market
Additives
Trioctyldodecyl Citrate Market
Additives
Calcium Acetate Market
Additives
Global Ester Gum Market
Additives
Global Butylated Hydroxytoluene Market
Additives
Butyrate Additives Market
Additives
Coating Additives Market
Additives
Oilfield Drilling Fluid Additive Market
Additives
Global Hindered Amine Light Stabilizers Market