
 Cement Grinding Aid and Performance Enhancers Market | 2026-2036
Cement Grinding Aid and Performance Enhancers Market Size, Share, and Industry Trends Forecast 2026-2036
Cement Grinding Aid and Performance Enhancers Market Analysis
The premium-commodity split in cement grinding aids is rebalancing as energy-intensive clinker substitution drives specification divergence. BASF SE leverages its polymer chemistry depth to serve high-performance precast segments. Sika AG anchors European supply through backward integration into raw material sourcing. GCP Applied Technologies competes on formulation flexibility across North American ready-mix channels.
Cement grinding aids and performance enhancers are chemical additives, typically comprising glycols, amines, and specialty polymers dosed at 0.01–0.05% by weight of cement, that reduce particle agglomeration during grinding and improve cement flowability while lowering specific energy consumption per ton. Their primary purpose is to enable cement producers to achieve target fineness at reduced clinker factor or lower mill operating temperatures. Organic additives occupy the fastest-expanding margin pool as producers seek biodegradable alternatives to conventional glycols. Strength Enhancement functionality commands premium positioning where supplementary cementitious material substitution rates exceed regional norms. Water Reduction formulations retain volume dominance in mature markets with established ready-mix infrastructure.
The EPA enforces National Emission Standards for Hazardous Air Pollutants at US cement kilns, indirectly mandating additive performance that enables lower-temperature grinding. REACH registration requirements in Europe restrict certain amine-based chemistries, pushing reformulation toward compliant molecular architectures. China's MEE enforces dual carbon goals that tighten energy-intensity benchmarks for cement producers, expanding addressable demand for efficiency-enhancing additives. Stakeholders must monitor how carbon border adjustment mechanisms redefine competitive access across major cement export corridors.
Market Dynamics
Clinker factor reduction mandates across major cement-producing jurisdictions are compressing the addressable chemistry space for conventional grinding aids while expanding specification divergence between efficiency and strength-enhancement formulations.
Growth Catalysts
- EU Green Deal carbon border adjustments:European cement imports face embedded carbon tariffs, compelling producers to source additives that enable lower-clinker formulations without sacrificing compressive strength targets.
- India's domestic capacity expansion:Chloride-free grinding aid specifications from major cement producers are accelerating as coastal infrastructure projects demand sulfate-resistant cement grades.
- Biodegradable glycol alternatives:Organic additive chemistries derived from agricultural waste streams are displacing petroleum-based feedstocks in markets with stringent wastewater discharge protocols.
Market Restraints
- Diethanolamine supply concentration:REACH registration restrictions on specific amine architectures have consolidated European supply among three specialized chemical manufacturers, creating input bottlenecks.
- Technical performance ceilings:Conventional glycols hit diminishing returns at fineness targets below 3000 Blaine, forcing producers toward higher-cost polymer systems for ultra-fine cement grades.
- Limestone calcined clay cement substitution:LC3 formulations with 50% clinker replacement reduce absolute additive volume requirements per ton of finished cement.
Strategic Opportunities
- Southeast Asian infrastructure buildout:Vietnam, Indonesia, and the Philippines are concentrating demand for grinding aids compatible with pozzolanic cement blends used in marine exposure conditions.
- China's dual carbon goals:MEE energy-intensity benchmarks are expanding addressable demand for mill temperature reduction additives that enable waste heat recovery optimization.
- Digital dosing systems:Real-time particle size analyzers integrated with automated additive injection are creating precision-application service contracts distinct from commodity chemical supply.
Industry Challenges
- Formulation chemist scarcity:The specialized knowledge bridge between polymer synthesis and cement mineralogy is concentrated among retiring specialists at European additive houses.
- Multi-standard compliance complexity:Simultaneous GB standard certification for China, ASTM C465 for North America, and EN 197 for Europe extends product development timelines by 18-24 months.
- Legacy mill infrastructure retrofit costs:Older vertical roller mill installations lack the temperature monitoring precision required for optimized performance enhancer dosing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cement Grinding Aid and Performance Enhancers Market |
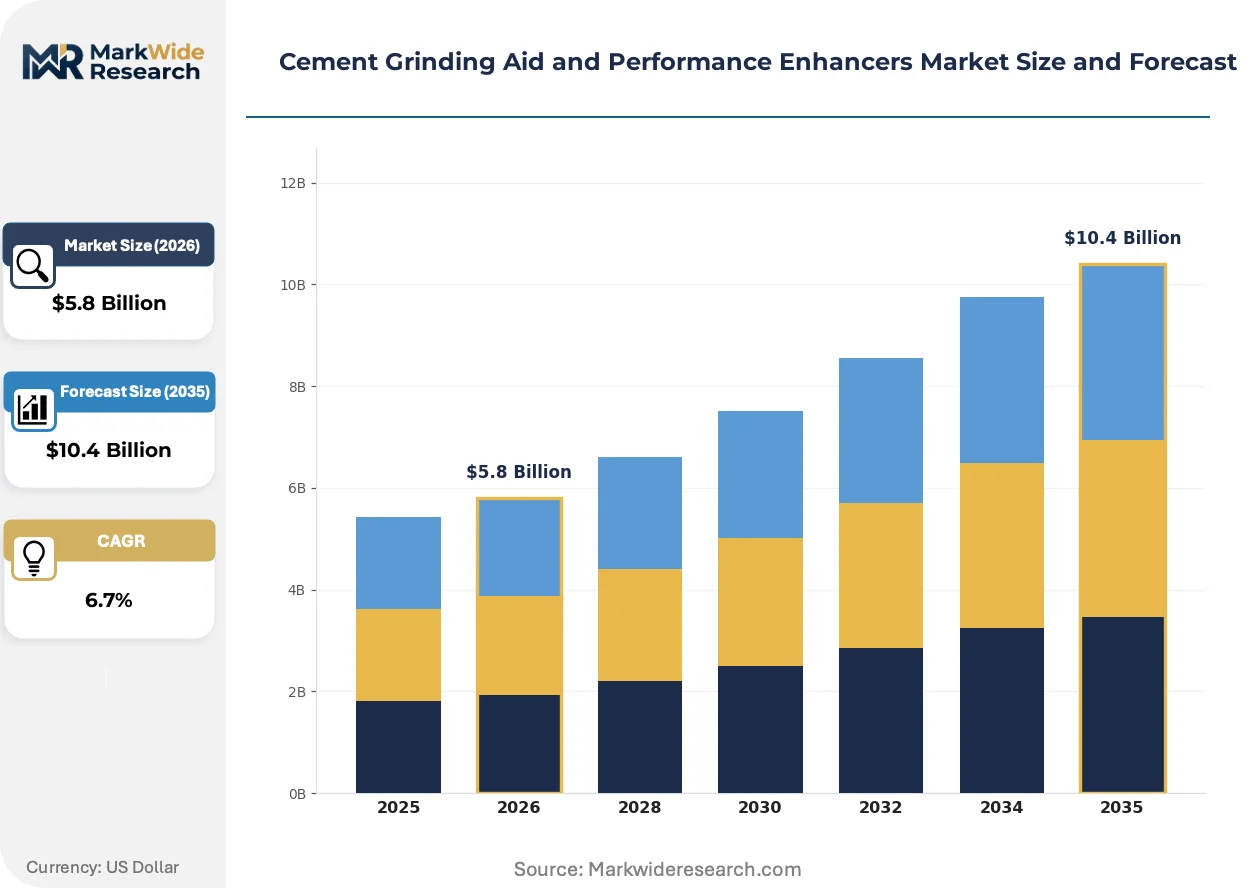
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.4 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cationic, Anionic, Non-ionic, Organic Functionality: Water Reduction, Flowability, Strength Enhancement, Set Time Adjustment Application: Ready-Mix Concrete, Precast Concrete, Mortar, Grout End User: Construction Companies, Manufacturers, Civil Engineers, Contractors |
| Companies Covered | GCP Applied Technologies, Evonik Industries AG, BASF SE, Fosroc Inc., Clariant AG, Sika AG, MBCC Group, Mapei S.p.A., W. R. Grace and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cement Grinding Aid and Performance Enhancers Market Emerging Trajectories
Electrochemical grinding processes and molecular architecture redesign are compressing the boundary between energy efficiency and mechanical performance in cement additive systems. Three developments are restructuring competitive advantage.
Polycarboxylate ether-based grinding aids are electrifying the premium segment by enabling simultaneous water reduction and extended slump retention in ready-mix applications. Precast concrete producers in Germany and Japan are adopting these systems at twice the rate of commodity glycol users. The technology is electrifying margin pools away from basic amine formulations toward specialty polymer supply contracts with technical service attachments.
China's GB 16780-2021 energy consumption limits for cement are forcing additive reformulation toward lower exotherm chemistries that reduce mill outlet temperatures. Domestic cement groups are qualifying new amine-glycol hybrid architectures ahead of scheduled standard updates. The regulation is compressing lead times for foreign suppliers while accelerating local raw material backward integration.
Integrated procurement platforms connecting cement plant laboratories directly with additive formulators are displacing traditional distributor intermediaries in North American markets. Ready-mix producers with centralized quality control functions are consolidating purchase decisions at regional headquarters rather than individual mill sites. The shift is most visible in the US Southwest, where multi-plant operators are negotiating enterprise additive contracts with performance guarantees tied to kWh/ton reduction metrics.
Cement Grinding Aid and Performance Enhancers Market Segmentation
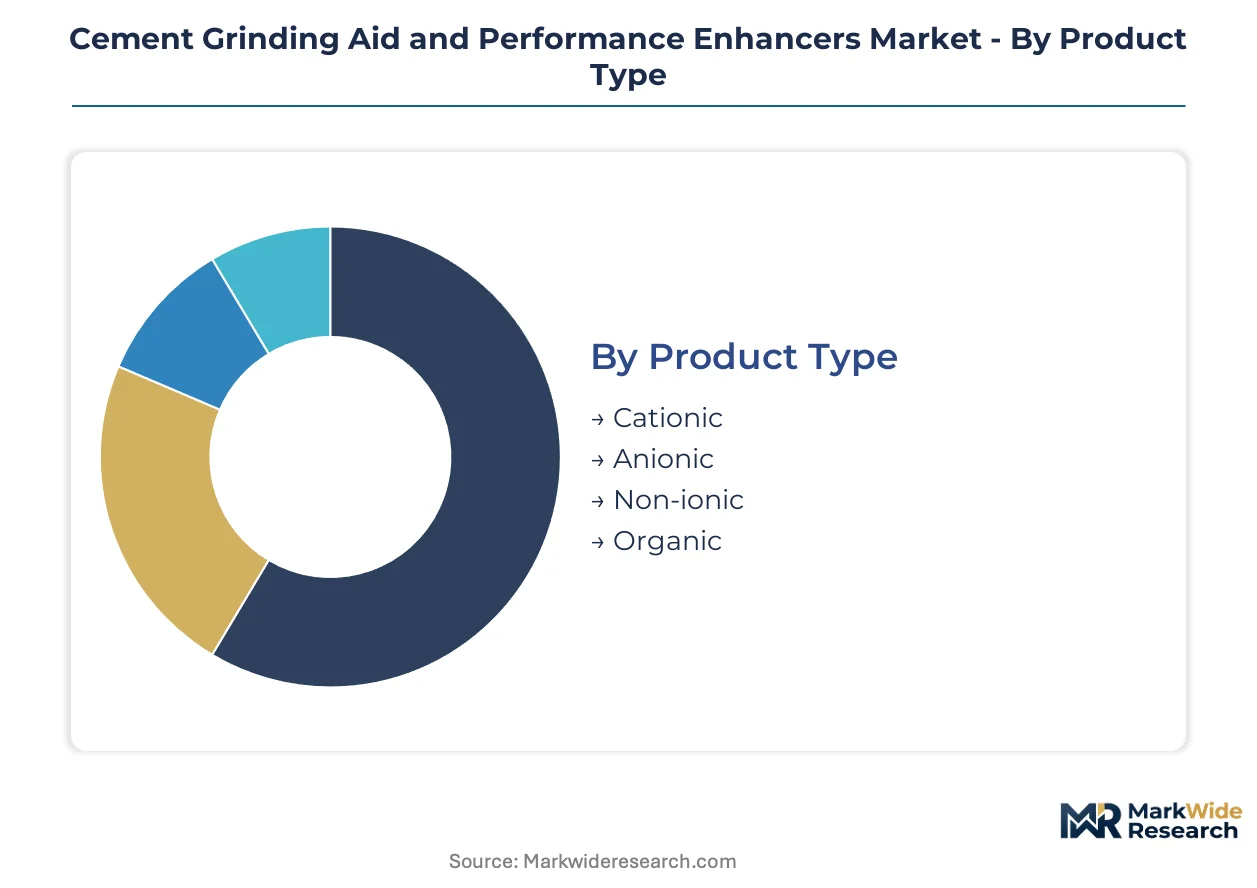
Cement grinding aid segmentation tracks how formulation chemistry, functional performance, and construction workflow requirements diverge across capital deployment cycles. Producers allocate R&D budgets toward segments where mill retrofit costs and technical service intensity align with contract value.
Product Type:
Capital intensity concentrates in ionic chemistries requiring dedicated synthesis infrastructure and REACH-compliant manufacturing assets.
- Cationic:Amine-based architectures carry positive surface charges that aggressively disperse cement particle agglomeration. Demand clusters in Germany and Japan where precast producers specify ultra-fine cement below 3000 Blaine for high-early-strength applications.
- Anionic:Sulfonate and carboxylate functional groups deliver grinding efficiency at lower dosage rates than conventional glycols. Southeast Asian pozzolanic cement mills are qualifying these systems for marine exposure conditions requiring sulfate resistance.
- Non-ionic:Polyglycol ethers operate independently of cement mineralogy variations, simplifying multi-plant procurement for diversified producers.
- Organic:Biodegradable feedstocks derived from agricultural waste streams command premium positioning in markets with stringent wastewater discharge protocols.
Most installed capacity flows through non-ionic formulations. Expansion is steepest in organic alternatives.
Functionality:
Application cost tiers separate commodity efficiency additives from premium strength-enhancement systems commanding technical service attachments.
- Water Reduction:Polycarboxylate ether superplasticizers enable 25-40% water reduction while maintaining workability. Ready-mix concrete producers in the US Southwest negotiate enterprise contracts tied to kWh/ton reduction metrics.
- Flowability:Rheology modifiers extend slump retention for long-haul delivery without retempering. Indian infrastructure projects specify these additives for high-temperature casting conditions.
- Strength Enhancement:Amine-glycol hybrids accelerate early compressive strength development to offset clinker substitution rates exceeding 50% in LC3 formulations.
- Set Time Adjustment:Retarder and accelerator chemistries synchronize cement hydration kinetics with ambient temperature variations and formwork removal schedules.
Volume leadership sits with water reduction. The steepest expansion trajectory belongs to strength enhancement.
Application:
Customer procurement patterns distinguish centralized quality control at regional headquarters from individual mill site purchasing.
- Ready-Mix Concrete:Centralized batching operations demand consistent additive performance across variable aggregate sources and delivery distances. North American multi-plant operators are consolidating purchase decisions at regional headquarters.
- Precast Concrete:Factory-controlled curing environments enable precise additive dosing for high-early-strength specifications. German and Japanese producers adopt polycarboxylate ether systems at twice the rate of commodity glycol users.
- Mortar:Masonry cement applications prioritize extended board life and water retention for trowelability.
- Grout:Pumpability and bleed resistance dominate specification requirements for structural repair and soil stabilization applications.
Most additive volume channels through ready-mix concrete. Precast concrete is gaining share fastest.
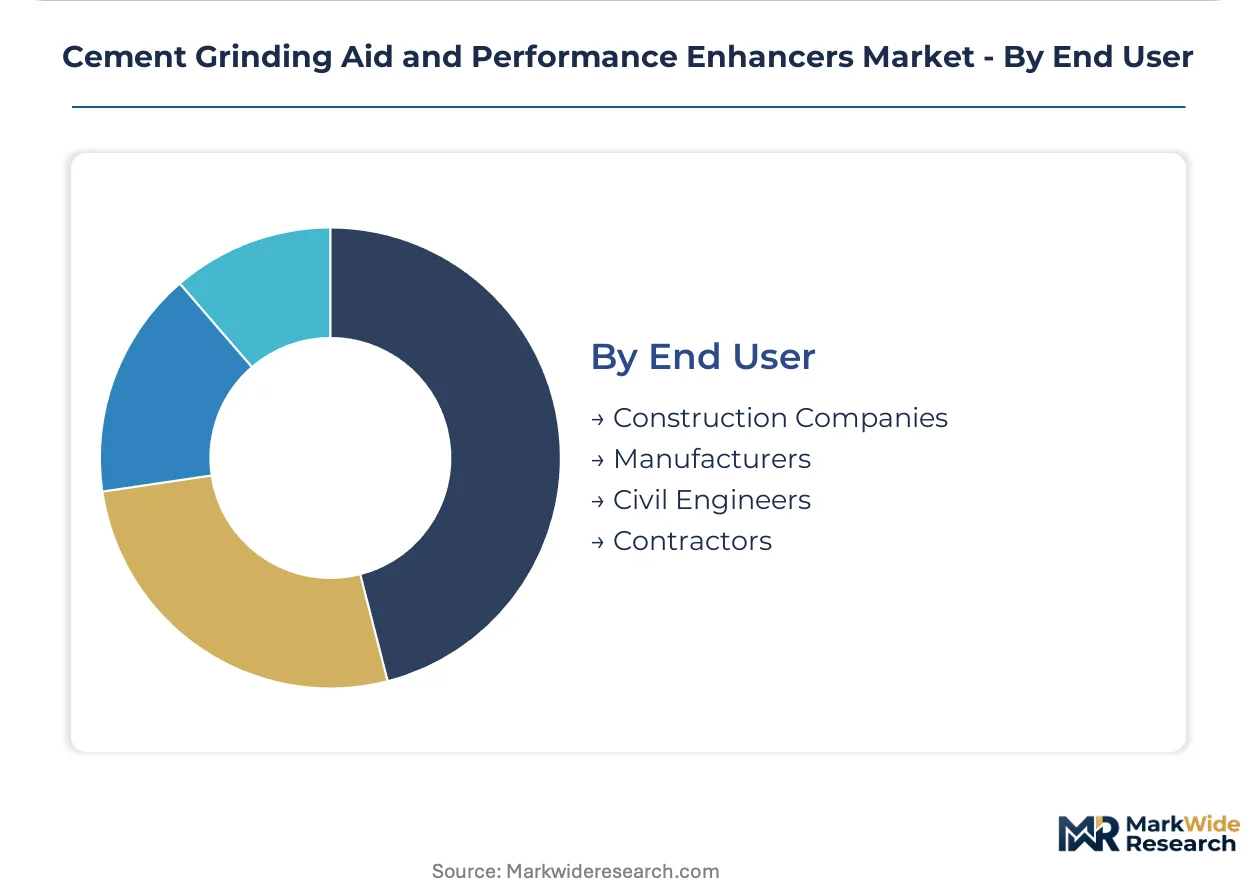
End User:
Technical sophistication and specification authority determine margin capture across contractor, engineer, and manufacturer segments.
- Construction Companies:Large-scale infrastructure developers specify performance guarantees tied to compressive strength targets and carbon intensity benchmarks. China's dual carbon goals are expanding addressable demand for efficiency-enhancing additives among state-owned construction groups.
- Manufacturers:Cement producers with captive grinding aid formulation capabilities optimize mill-specific dosing protocols. Domestic Chinese cement groups are qualifying new amine-glycol hybrid architectures ahead of scheduled GB standard updates.
- Civil Engineers:Design specifications for sulfate-resistant and low-alkali cement grades dictate additive selection for coastal and industrial exposure conditions.
- Contractors:Field-level procurement prioritizes immediate availability and compatibility with existing batching equipment over formulation optimization.
Most formulation development resources target manufacturers. Construction companies are climbing the fastest as enterprise contracting expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands roughly one-third of global cement grinding aid consumption while India trails at roughly half that volume, yet both markets are diverging sharply in formulation requirements as domestic regulations tighten.
China
Domestic cement groups are qualifying new amine-glycol hybrid architectures ahead of scheduled GB standard updates. The MEE enforces dual carbon goals that tighten energy-intensity benchmarks, expanding addressable demand for mill temperature reduction additives. Shandong Province hosts the densest concentration of local additive manufacturers retrofitting synthesis lines for lower-exotherm chemistries.
India
Chloride-free grinding aid specifications from major cement producers are accelerating as coastal infrastructure projects demand sulfate-resistant cement grades. The Bureau of Indian Standards is revising cement additive protocols to align with marine exposure durability targets. Gujarat and Maharashtra cement clusters are piloting organic glycol alternatives derived from agricultural waste streams.
Germany
Precast concrete producers adopt polycarboxylate ether systems at twice the rate of commodity glycol users, electrifying margin pools toward specialty polymer supply. REACH registration restrictions on specific amine architectures have consolidated European supply among specialized chemical manufacturers. The Rhine-Ruhr industrial corridor anchors backward integration into raw material sourcing for grinding aid synthesis.
United States
Ready-mix producers with centralized quality control functions are consolidating purchase decisions at regional headquarters rather than individual mill sites. The EPA enforces National Emission Standards for Hazardous Air Pollutants at cement kilns, indirectly mandating additive performance that enables lower-temperature grinding. The US Southwest concentrates enterprise additive contracts with performance guarantees tied to kWh/ton reduction metrics.
Vietnam
Infrastructure buildout is concentrating demand for grinding aids compatible with pozzolanic cement blends used in marine exposure conditions. Domestic cement capacity expansions are sourcing formulation expertise from regional additive distributors rather than captive chemistry labs. The Red River Delta cement corridor is qualifying anionic sulfonate systems for sulfate resistance in coastal construction.
Cement Grinding Aid and Performance Enhancers Market Vendor Landscape
Top-tier vendors anchor premium polymer chemistry, while mid-tier commodity glycol suppliers compete on formulation flexibility and regional distribution density. The market structure reflects a bifurcation between multinational chemical conglomerates with REACH-compliant manufacturing assets and specialized regional formulators serving single-country procurement patterns. Two strategic archetypes dominate: polymer synthesis specialists leveraging backward integration into raw material sourcing, and application-technology providers bundling digital dosing systems with chemical supply. Competitive moves center on M&A to secure amine feedstock security and strategic partnerships with cement producers for mill-specific performance guarantees.
Among European-headquartered chemical conglomerates, BASF SE and Sika AG exemplify divergent positioning archetypes within the premium tier. BASF SE occupies a position tied to polymer chemistry depth for high-performance precast segments, while Sika AG anchors supply through upstream control over raw material sourcing. GCP Applied Technologies represents the North American formulation-flexibility archetype, competing across ready-mix channels with adaptable dosing protocols. Evonik Industries AG sits within the specialty amine chemistry tier, reflecting German industrial heritage in surface-active agent synthesis.
| Leading Market Players |
|---|
| GCP Applied Technologies |
| Evonik Industries AG |
| BASF SE |
| Fosroc Inc. |
| Clariant AG |
| Sika AG |
| MBCC Group |
| Mapei S.p.A. |
| W. R. Grace and Company |
| Others |
Supply Flow & Price Mechanics
Backward integration into amine feedstock production anchors both supply security and pricing power for European additive houses facing REACH registration bottlenecks. This upstream control enables premium positioning for polycarboxylate ether systems while commodity glycol suppliers compete on regional distribution density.
Pricing Analysis
Capacity additions in China's Shandong Province are reshaping price floors for conventional glycols as domestic synthesis lines retrofit for lower-exotherm chemistries. Three-tier pricing structure across premium polymer, standard amine-glycol hybrid, and economy glycol tiers separates formulation performance guarantees. Price differentiation hinges on mill-specific technical service attachments and GB standard certification status. Cost compression in the commodity tier is intensifying as LC3 cement substitution reduces absolute additive volume per ton. Ready-mix concrete producers with enterprise contracts show lowest price sensitivity; individual mill site procurement shows highest.
Supply Chain Analysis
Formulation chemist scarcity in Germany's Rhine-Ruhr corridor and retiring specialists at European additive houses constrain synthesis capacity expansion. Supply concentrates in China, Germany, and India for amine-based architectures; diethanolamine feedstock draws from consolidated European chemical manufacturers. Raw material dependencies include petroleum-derived glycols, agricultural waste streams for organic alternatives, and specialty amine intermediates. Single-source vulnerability runs through REACH-registered amine architectures limited to three specialized suppliers. Distribution runs through integrated procurement platforms displacing traditional distributor intermediaries in North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through premium polymer chemistry displacement of commodity glycols as clinker substitution mandates intensify specification divergence.
For Market Incumbents: Anticipate formulation chemist retirement waves by capturing specialist knowledge through technical documentation systems and accelerated trainee pipelines. Defend against LC3 cement substitution threats by developing strength-enhancement additives calibrated for 50%+ clinker replacement rates. Prioritize GB standard pre-certification for China's scheduled energy-efficiency updates to maintain market access.
For New Entrants and Emerging Players: Enter via biodegradable glycol alternatives targeting Indian and Southeast Asian markets with stringent wastewater discharge protocols. White-space opportunities concentrate in Vietnam's Red River Delta cement corridor and Indonesia's pozzolanic blend mills lacking captive formulation labs. Anchor initial positioning through digital dosing system partnerships that bundle precision-application services with chemical supply.
For Investors and Strategic Acquirers: Roll-up economics work for regional formulators with captive amine-glycol synthesis assets because REACH registration restrictions have consolidated European supply among limited qualified manufacturers. Five-to-ten-year viability favors specialists with backward integration into agricultural waste feedstock streams. Watch China's MEE enforcement intensity on dual carbon goals as the inflection signal for premium additive demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amine Feedstock | REACH registration bottlenecks reward captive supply of restricted chemistries. |
| Digital Dosing System Partnerships | Real-time particle analyzers create precision-application service contracts distinct from commodity supply. |
| GB Standard Pre-Certification | China's MEE energy-intensity benchmarks expand addressable demand for qualified additives. |
| Biodegradable Glycol Development | Agricultural waste-derived alternatives command premium in wastewater-regulated markets. |
| Technical Service Attachment Expansion | Mill-specific performance guarantees tied to kWh/ton metrics electrify margin pools. |
Methodological Framework
Direct dialogue with cement plant managers, additive formulator R&D directors, procurement leads at ready-mix concrete producers, and MEE regulatory affairs specialists grounded qualitative assessment. Secondary validation drew from GB standard update filings, REACH registration databases, Bureau of Indian Standards revision notices, and EPA National Emission Standards enforcement records. Bottom-up mill capacity modeling and top-down chemical consumption estimates were triangulated against trade flow data.
Bottom-up segment modeling tracked product type, functionality, and application dimensions across the projection horizon. CAGRs were derived from installed cement capacity expansion schedules, clinker substitution rate trajectories, and additive dosage intensity assumptions. Forecast inputs incorporated MEE dual carbon goal enforcement timelines and LC3 formulation adoption curves.
Inputs from Chinese domestic cement groups and European additive houses were available through the study window; gaps in real-time mill-specific dosing data introduce uncertainty bands around precision-application service contract valuations. Forecasts reflect assumptions on regulatory enforcement intensity and clinker substitution technical ceilings. Material deviation in China's GB standard implementation timeline or REACH amine registration restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Sizing Agents Market
Additives
Ethoxyquin Market
Additives
Competitive Inhibitors Market
Additives
Refining Additives Market
Additives
Sorbitan Tristearate Market
Additives
Caprylyl Glycol Market
Additives
Glacial Acetic Acid Market
Additives
North America Citric Acid Market
Additives
Anti-Wear Additives Market
Additives
Alginic Acid Market
Additives
Grease Additives Market
Additives
Sorbitan Laurate Market
Additives
Global Low-Profile Additive Market
Additives
Tartaric Acid Market
Additives
China Feed Additives Market
Additives
Global Lubricating Oil Additives Market