
 Monocalcium Phosphate Market | 2026-2036
Monocalcium Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Monocalcium Phosphate Market Outlook
Phosphate processing expertise is reorganizing competitive dynamics as specialized technical labor becomes scarcer in mature mining regions. PhosAgro leverages its integrated apatite-to-acid infrastructure to control raw material flows from Russian deposits. The Mosaic Company anchors North American supply through its Florida phosphate mining and downstream beneficiation network. OCP Group dominates Moroccan phosphate rock extraction, sustaining long-term feedstock security for monocalcium phosphate derivatives.
Monocalcium phosphate is a calcium dihydrogen phosphate salt produced through the controlled reaction of phosphoric acid with calcium carbonate, typically yielding a product with 16-17% phosphorus content on a dry weight basis. The compound functions primarily as a phosphorus and calcium source in animal feed formulations, leavening agent in baked goods, and acidulant in food processing. Feed Grade material occupies the largest volume share as livestock producers prioritize digestible phosphorus sources that reduce environmental phosphorus excretion. Food Grade output commands premium positioning due to stringent purity thresholds and FSSC 22000 compliance requirements in bakery and prepared food channels. Pharmaceutical Grade represents a concentrated margin pool where USP-NF certification creates supply scarcity and pricing power for qualified manufacturers.
FDA feed additive regulations and EPA nutrient management policies shape product formulation requirements and application rates in the United States. REACH registration and EFSA feed material evaluations govern market access across European Union member states, while China's GB standards for feed-grade phosphates establish import quality benchmarks. Stakeholders must monitor phosphorus recovery technologies and circular economy mandates that could restructure raw material sourcing economics.
Market Dynamics
Phosphate rock depletion in mature mining basins is forcing processors to reconfigure beneficiation circuits around lower-grade feedstock, tightening technical labor markets and reshaping regional cost competitiveness.
Growth Catalysts
- Feed conversion efficiency mandates:Livestock producers in the United States face EPA nutrient management policies that penalize environmental phosphorus excretion, accelerating digestible phosphate adoption.
- REACH registration tailwinds:ECHA compliance requirements for feed-grade phosphates create scarcity value for pre-registered suppliers serving European Union compound feed manufacturers.
- Integrated processing clusters:China's expanding captive acid-to-phosphate capacity in Yunnan and Guizhou provinces locks in downstream monocalcium phosphate supply security for domestic agriculture.
Market Restraints
- Phosphoric acid cost volatility:Sulfur and energy inputs for wet-process acid production swing with natural gas and sulfur benchmark pricing, compressing processor margins unpredictably.
- Moroccan rock concentration:OCP Group's dominance over high-quality sedimentary phosphate reserves creates single-source dependency risk for non-integrated acid producers.
- Dicalcium phosphate substitution:Lower-cost DCP alternatives capture price-sensitive feed formulations where phosphorus digestibility requirements permit mineral source flexibility.
Strategic Opportunities
- Pharmaceutical-grade white space:USP-NF certified production capacity remains concentrated among European and North American specialists, opening margin capture for qualified entrants.
- Circular phosphorus recovery:EU Green Deal nutrient recycling mandates incentivize struvite and sewage sludge ash processing as alternative phosphate feedstock streams.
- Direct-to-mill distribution:Bypassing traditional agrochemical distributors through integrated compounder relationships reduces working capital intensity for large-scale feed operations.
Industry Challenges
- Process engineering talent scarcity:Specialized expertise in apatite beneficiation and acid purification is retiring faster than technical training programs replenish qualified personnel.
- FSSC 22000 certification timelines:Food-grade qualification requires 12-18 month audit cycles that delay revenue recognition for bakery and prepared food channel entry.
- Legacy ERP integration:Batch process control systems at established acid plants resist seamless connectivity with modern supply chain visibility platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monocalcium Phosphate Market |
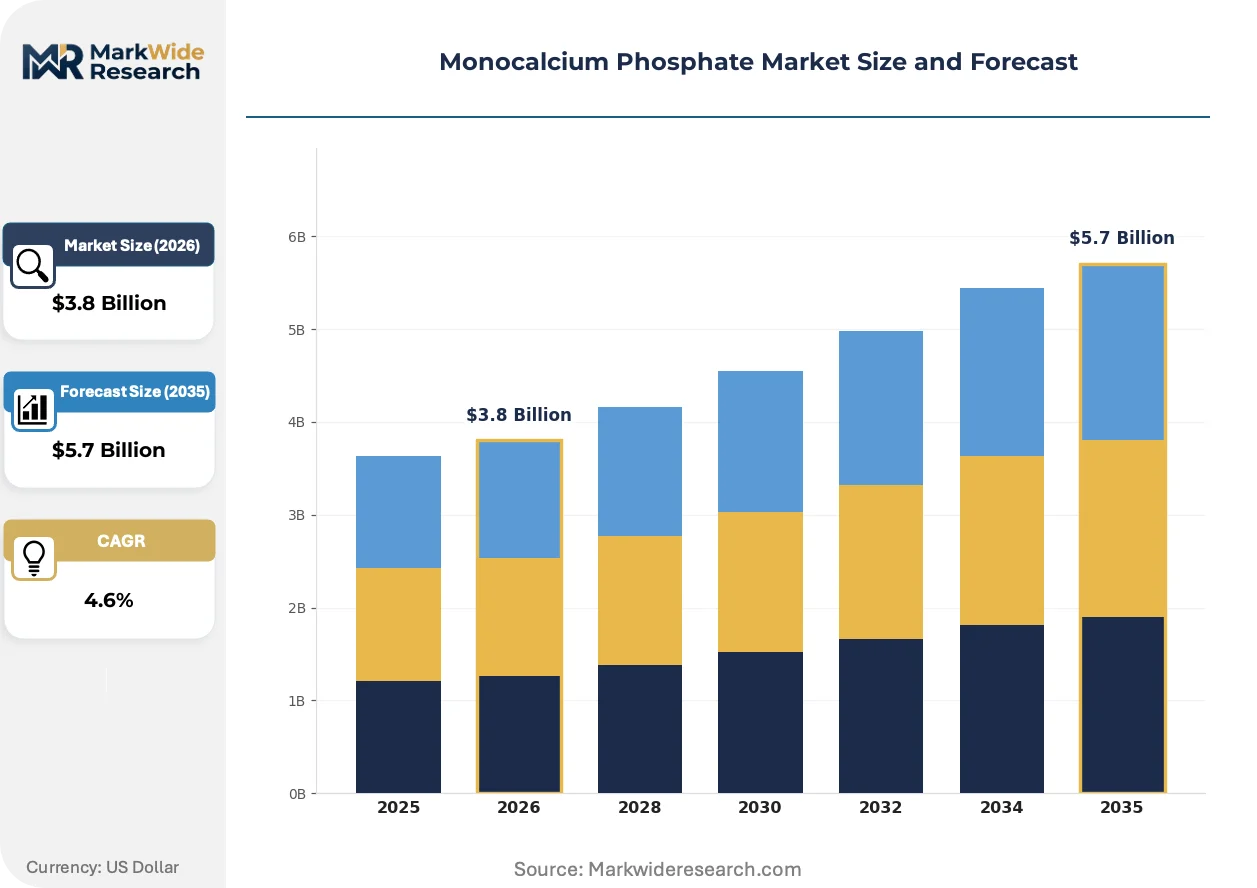
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feed Grade, Food Grade, Technical Grade, Pharmaceutical Grade Application: Animal Nutrition, Fertilizers, Food Additives, Pharmaceutical Applications End User: Agriculture, Food Industry, Pharmaceuticals, Livestock Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Yara International, PhosAgro, The Mosaic Company, Phosphea, Innophos Holdings, Inc., Nutrien Ltd., EuroChem Group, J.R. Simplot Company, OCP Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monocalcium Phosphate Market Strategic Shifts
Granulation and coating technologies are compressing product differentiation cycles, while regulatory pressure on phosphorus runoff accelerates formulation science investment across feed and food channels.
Micro-encapsulated phosphate delivery systems are miniaturizing particle size distribution to enable precision release in ruminant digestive tracts. Dairy and beef operations in the Netherlands and Denmark are piloting these formulations to synchronize phosphorus absorption with metabolic demand curves. The technology is miniaturizing dosage granularity from milligram to microgram scales, enabling nutritionists to program feed matrices with previously unattainable precision.
EFSA's revised feed additive evaluation guidelines now mandate extended environmental fate studies for all new phosphate source approvals. This regulatory tightening extends development timelines by 18-24 months but simultaneously erects competitive moats around incumbent qualified suppliers. Compound feed manufacturers in Germany and France are consolidating procurement around pre-certified legacy suppliers to avoid reformulation risk.
Vertical integration between phosphate miners and compound feed conglomerates is collapsing traditional merchant market layers. Brazilian and Vietnamese livestock operations now source monocalcium phosphate through captive trading arms of integrated protein packers rather than independent distributors. This channel compression concentrates volume among fewer procurement decision-makers and pressures standalone merchant processors to defend position through technical service differentiation.
Monocalcium Phosphate Market Segmentation
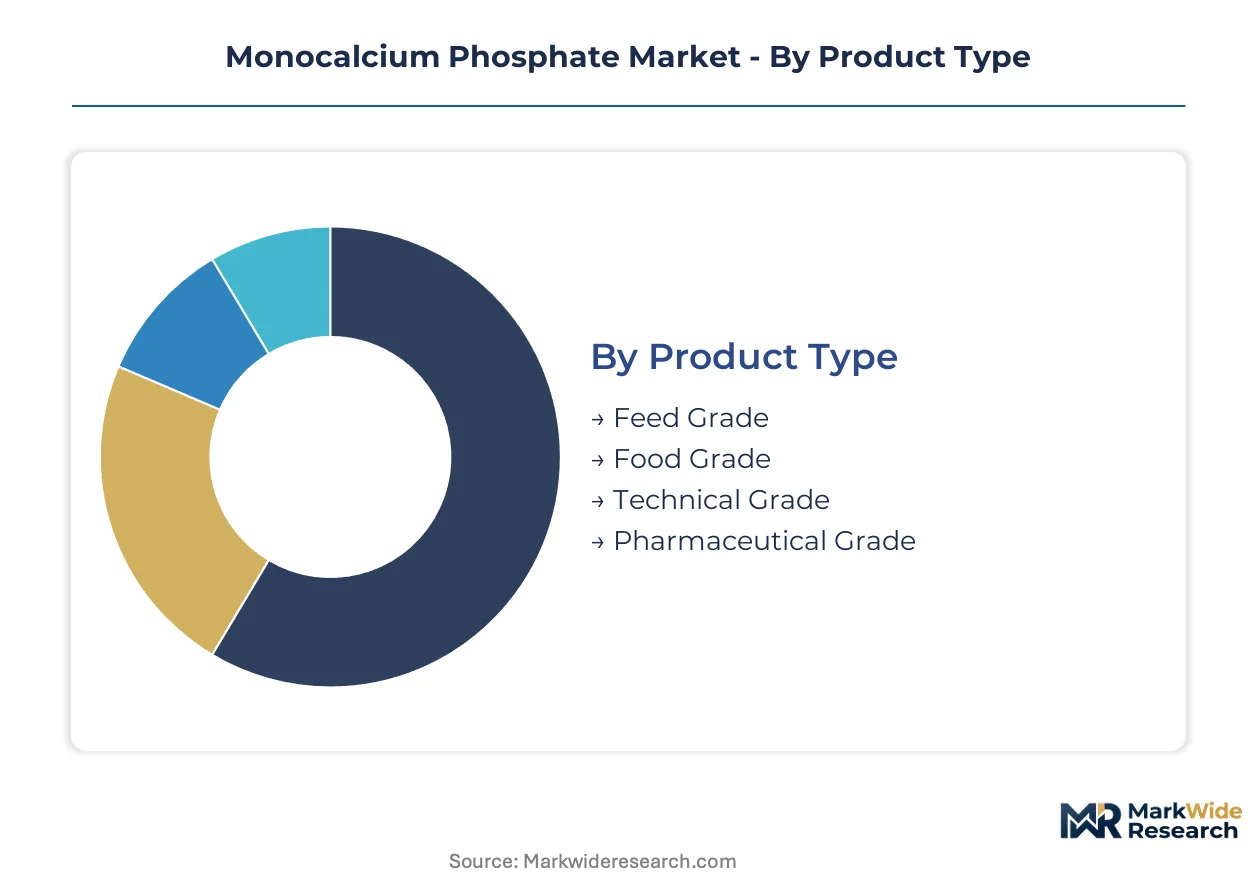
Monocalcium phosphate segmentation reflects divergent purity requirements and regulatory pathways across feed, food, and pharmaceutical channels. Each grade tier commands distinct certification protocols and customer procurement behaviors that reshape competitive positioning.
Product Type:
Substitution pressure from dicalcium phosphate and alternative mineral sources concentrates most intensely on standard feed formulations, while premium grades defend position through certification moats.
- Feed Grade:Contains 16-17% phosphorus on a dry weight basis, optimized for digestibility in poultry, swine, and ruminant formulations. Demand concentrates in integrated livestock operations across Brazil and Vietnam that prioritize phosphorus conversion efficiency to comply with EPA nutrient management policies. Dicalcium phosphate alternatives capture price-sensitive volume where digestibility standards permit flexibility.
- Food Grade:Meets FSSC 22000 and regional food safety standards for bakery leavening and acidulant applications. European Union compound feed manufacturers consolidate procurement around pre-certified suppliers to avoid EFSA-mandated reformulation risk from extended environmental fate study requirements. REACH registration creates scarcity value for incumbent qualified producers.
- Technical Grade:Industrial applications in water treatment and metal surface preparation drive specification requirements. Chinese processors in Yunnan and Guizhou provinces leverage captive acid-to-phosphate capacity to lock in downstream supply security.
- Pharmaceutical Grade:USP-NF certification mandates stringent purity thresholds for excipient and active pharmaceutical ingredient applications. European and North American specialists concentrate qualified production capacity, erecting barriers to new entrants.
Feed Grade retains volume leadership; Pharmaceutical Grade holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity mineral supplementation from precision-formulated pharmaceutical delivery systems.
- Animal Nutrition:Dominates volume throughput as livestock producers optimize feed conversion ratios. Micro-encapsulated delivery systems piloted in Dutch and Danish dairy operations enable precision phosphorus release synchronized with metabolic demand curves.
- Fertilizers:Blends into compound fertilizer formulations for phosphorus-deficient soils. Chinese agricultural expansion drives domestic processing capacity integration.
- Food Additives:Functions as acidulant and leavening agent in baked goods and prepared foods. FDA food additive regulations govern formulation requirements and maximum permitted levels in United States commerce.
- Pharmaceutical Applications:Tablet binder and mineral supplement applications command premium positioning. USP-NF certification timelines extend 12-18 months, delaying revenue recognition for qualified entrants.
Animal Nutrition anchors volume scale; Pharmaceutical Applications deliver the highest margin realization.
End User:
Customer type fragmentation concentrates procurement decision-making among fewer integrated protein packers versus independent distributors.
- Agriculture:Crop nutrition programs in phosphorus-deficient regions specify monocalcium phosphate for starter fertilizer applications. Brazilian soybean operations source through captive trading arms of integrated agricultural conglomerates.
- Food Industry:Bakery and prepared food manufacturers demand FSSC 22000-compliant supply chains with full batch traceability. European channel consolidation favors pre-certified legacy suppliers.
- Pharmaceuticals:Contract manufacturers and innovator drug companies require USP-NF certified excipients with documented stability data. Qualified supplier scarcity sustains pricing power.
- Livestock:Integrated poultry and swine operations prioritize digestible phosphorus sources to reduce environmental excretion penalties. Vietnamese protein packers bypass traditional distributors through direct mill relationships.
Livestock procurement concentrates fastest; Pharmaceuticals maintains the tightest supplier qualification standards.
Distribution Channel:
Supply concentration among integrated processors is compressing traditional merchant market layers and reshaping channel economics.
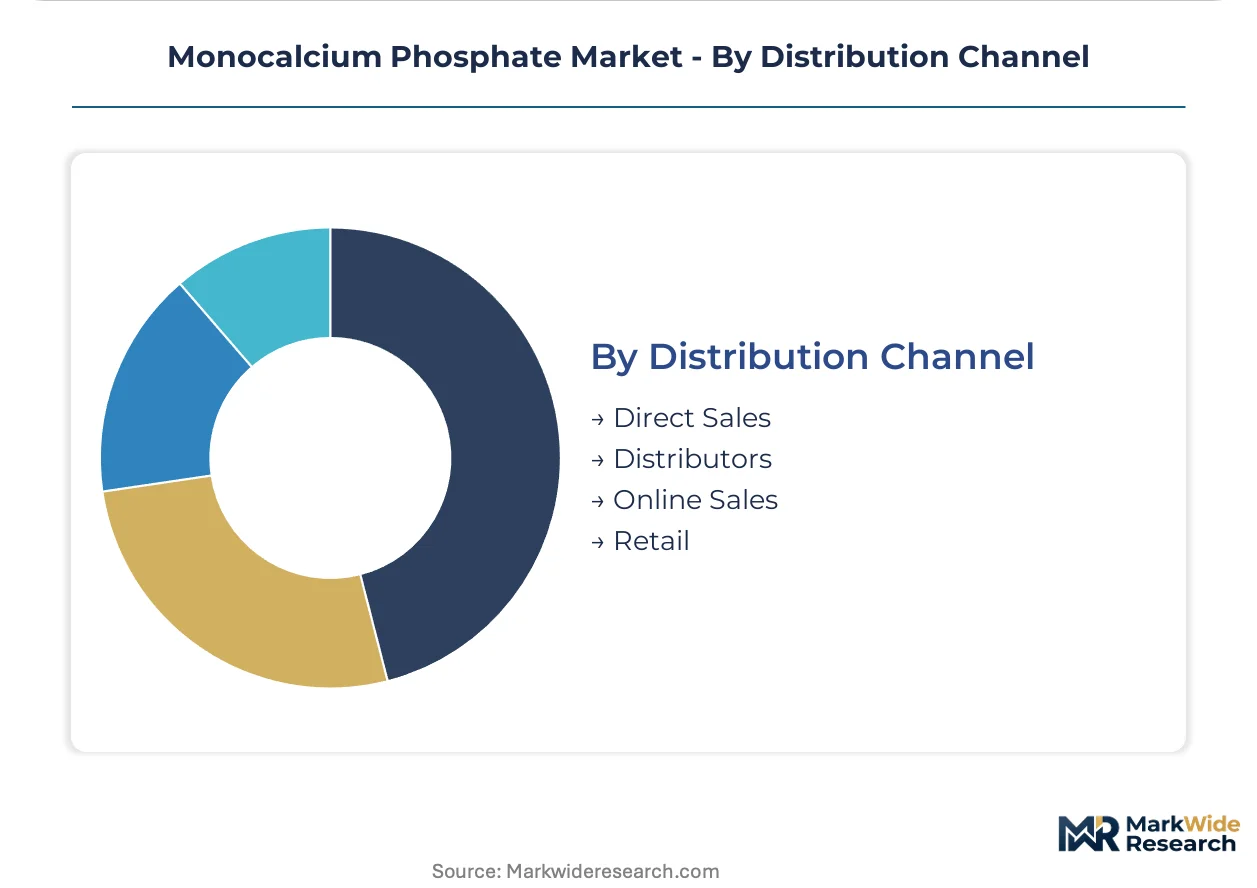
- Direct Sales:Large-scale compound feed operations and integrated protein packers negotiate volume contracts bypassing distributor markups. Working capital intensity reductions attract procurement consolidation.
- Distributors:Traditional agrochemical distributors defend position through technical service differentiation and formulation expertise. Smaller livestock operations without captive sourcing capabilities rely on distributor networks.
- Online Sales:Emerging channel for technical grade and smaller volume food grade purchases. Digital platforms enable price transparency for standardized specifications.
- Retail:Garden and specialty agriculture outlets serve hobbyist and small-scale crop producers. Limited volume contribution relative to industrial channels.
Direct Sales captures share fastest; Distributors retains the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB standards for feed-grade phosphates anchor regulatory gravity for the monocalcium phosphate trade, while processing clusters in Yunnan and Guizhou provinces reshape regional supply security. Integrated acid-to-phosphate capacity expansion across Asia-Pacific and regulatory tightening in Europe and North America are redrawing procurement patterns.
China
Livestock intensification and domestic agricultural self-sufficiency targets drive monocalcium phosphate consumption. GB standards establish import quality benchmarks that filter non-compliant supply. Yunnan and Guizhou provinces host expanding captive acid-to-phosphate processing clusters that lock in downstream supply security for compound feed manufacturers.
United States
EPA nutrient management policies penalize environmental phosphorus excretion, accelerating digestible phosphate adoption in poultry and swine operations. FDA feed additive regulations govern formulation requirements and application rates. Florida's phosphate mining and downstream beneficiation network anchors North American supply through integrated processor infrastructure.
Brazil
Soybean expansion and integrated protein packer consolidation concentrate procurement decision-making among fewer buyers. ANVISA regulates feed additive imports and domestic manufacturing standards. São Paulo and Minas Gerais states host captive trading arms that bypass traditional distributors through direct-to-mill relationships with compound feed operations.
Germany
EFSA feed material evaluations and REACH registration requirements create scarcity value for pre-registered suppliers serving compound feed manufacturers. EU Green Deal nutrient recycling mandates incentivize circular phosphorus recovery technologies. The Rhine-Ruhr industrial corridor maintains technical service differentiation capabilities for distributor-defended market layers.
Morocco
OCP Group's dominance over high-quality sedimentary phosphate reserves sustains long-term feedstock security for acid producers worldwide. The Khouribga and Gantour mining basins supply rock to integrated and non-integrated processors across Atlantic trade routes. Beneficiation expertise concentrates in Casablanca-Settat region for export-oriented derivative production.
Monocalcium Phosphate Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the monocalcium phosphate value chain. The market structure consolidates around integrated miners with captive acid capacity and specialized processors with certification moats. Three archetypes dominate: vertically integrated phosphate rock extractors, regional acid-to-phosphate specialists, and pharmaceutical-grade purity qualifiers. Competitive moves center on backward integration into mining assets and forward integration into compound feed distribution channels.
Among integrated mining conglomerates, PhosAgro and OCP Group exemplify the captive feedstock archetype that controls raw material flows from deposit to derivative. The Mosaic Company anchors North American positioning through Florida-based extraction and beneficiation infrastructure. Specialty chemical qualifiers including Innophos Holdings, Inc. occupy the pharmaceutical-grade tier where USP-NF certification erects supply scarcity barriers.
| Leading Market Players |
|---|
| Yara International |
| PhosAgro |
| The Mosaic Company |
| Phosphea |
| Innophos Holdings, Inc. |
| Nutrien Ltd. |
| EuroChem Group |
| J.R. Simplot Company |
| OCP Group |
| Others |
Value Chain & Pricing Dynamics
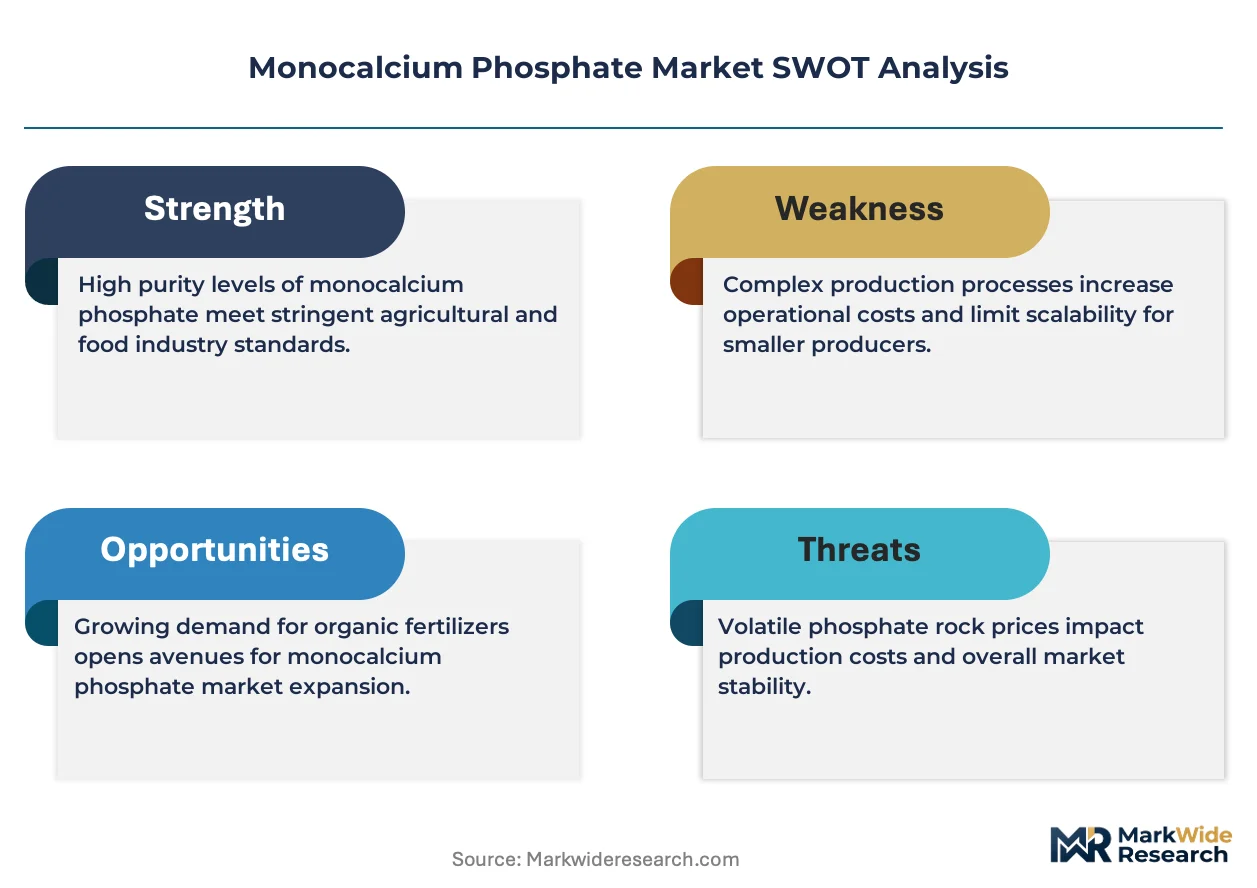
REACH registration and EFSA feed material evaluations simultaneously gate European market access and stratify pricing power across qualified versus non-qualified suppliers, compressing merchant processors into certification-driven margin tiers while rewarding pre-registered incumbents with scarcity premiums.
Pricing Analysis
Chinese-origin feed-grade material trades at structural discounts to European-qualified supply, with three-tier pricing separating USP-NF pharmaceutical certification from FSSC 22000 food-grade and standard feed-grade tiers. Price differentiation hinges on purity thresholds and audit cycle completion, with sulfur and natural gas input volatility pressuring wet-process acid margins unpredictably. Compound feed operations in Brazil and Vietnam exhibit highest price sensitivity, while pharmaceutical contract manufacturers accept premium positioning for documented stability data.
Supply Chain Analysis
Inventory buffers at Moroccan rock export terminals and Florida beneficiation facilities extend lead times for non-integrated acid producers sourcing from OCP Group or The Mosaic Company. Supply concentrates in Morocco, China, and the United States, with Moroccan sedimentary phosphate and Chinese captive acid-to-phosphate clusters anchoring upstream feedstock security. Single-source dependency on OCP's Khouribga and Gantour basins creates vulnerability for Atlantic-route processors. Distribution runs through direct-to-mill contracts for integrated protein packers and technical service-defended distributor networks for smaller livestock operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where EFSA-mandated environmental fate studies and 12-18 month USP-NF certification timelines erect switching costs that defend incumbent positioning against unqualified challengers.
For Market Incumbents: Secure backward integration into Moroccan or Florida phosphate rock assets to insulate margin compression from sulfur and energy input volatility. Expand captive acid-to-phosphate capacity in Yunnan or Guizhou provinces to lock in Chinese agricultural demand. Defend distributor relationships through micro-encapsulation formulation expertise as Brazilian and Vietnamese protein packers consolidate procurement.
For New Entrants and Emerging Players: USP-NF certification fast-tracks offer the most penetrable white space, with European and North American specialist capacity concentrated among legacy qualifiers. Target pharmaceutical-grade excipient supply to contract manufacturers seeking second-source security. Enter through toll manufacturing arrangements with established acid plants to bypass FSSC 22000 audit cycle delays.
For Investors and Strategic Acquirers: Carve-out targets emerge from integrated agricultural conglomerates spinning non-core phosphate derivative units. Long-term viability centers on regulatory moat sustainability and circular phosphorus recovery technology positioning. Watch EU Green Deal nutrient recycling mandate implementation velocity as inflection indicator for struvite and sewage sludge ash processing economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock Assets | Moroccan sedimentary reserves and Florida mining basins anchor feedstock security against OCP concentration risk. |
| USP-NF Certification Investment | Pharmaceutical-grade qualification erects 12-18 month competitive moats with documented stability data requirements. |
| Micro-Encapsulation R&D Partnership | Dutch and Danish dairy pilot programs validate precision phosphorus release synchronized with ruminant metabolic demand. |
| Circular Phosphorus Recovery Buildout | EU Green Deal mandates incentivize struvite processing from municipal wastewater as alternative phosphate feedstock stream. |
| Direct-to-Mill Distribution Expansion | Bypassing agrochemical distributors reduces working capital intensity for Brazilian and Vietnamese integrated protein packers. |
Study Parameters
Operator-level perspectives from phosphate plant managers, compound feed procurement leads, pharmaceutical excipient quality directors, and EFSA regulatory affairs specialists anchored the qualitative base. Primary interview findings triangulated against secondary validation from customs and trade data, SEC 10-K filings of listed processors, Cefic phosphate sector reports, and ANVISA feed additive registration databases. Bottom-up volume modeling across grade tiers and top-down macroeconomic anchoring ensured cross-verification.
Sensitivity analysis tested forecast robustness across sulfur price volatility scenarios and REACH registration timeline variations throughout the projection horizon. The analytical framework modeled segmentation across feed, food, pharmaceutical, and technical grades; animal nutrition, fertilizer, food additive, and pharmaceutical applications; and direct sales versus distributor channel splits. CAGRs derived from regression against livestock intensification indices and agricultural self-sufficiency policy trajectories, with Chinese GB standard enforcement velocity and EPA nutrient management policy adoption as key demand-side inputs.
Decision-makers should treat outputs as directional under stable regulatory enforcement and no disruptive phosphorus recovery technology commercialization; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
United States Betaine Market
Additives
Refinery Fuel Additives Market
Additives
Pectin Market
Additives
Global Coalescing Agent Market
Additives
Alkyl Acetates Market
Additives
North America Paints and Coatings Additives Market
Additives
Low-Carbon Concrete Shrinkage-Reduction Additives Market
Additives
Rosin Ester Market
Additives
Sodium Benzoate Market
Additives
Phthalate and Non-Phthalate Plasticizers Market
Additives
Alkyl Ketene Dimers (AKD) Wax Market
Additives
Glycol Acetate Market
Additives
Anti-Creasing Agent Market
Additives
Amino Acids Premixes Market
Additives
Potassium Nitrate Market
Additives
Volatile Corrosion Inhibitors Market