
 Deodorant and Antiperspirant Ingredients Market | 2026-2036
Deodorant and Antiperspirant Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Deodorant and Antiperspirant Ingredients Market Intelligence
Clean-label certification is unwinding conventional formulation standards across the deodorant and antiperspirant ingredients space. Symrise AG leverages its botanical extraction capabilities to supply natural fragrance compounds to premium personal care brands. BASF SE anchors the aluminum compound segment through its large-scale chemical manufacturing infrastructure. Givaudan competes aggressively in the custom fragrance arena, offering tailored scent profiles that differentiate finished consumer products.
Deodorant and antiperspirant ingredients comprise active compounds, functional additives, and sensory enhancers formulated to inhibit bacterial growth, reduce perspiration, or mask body odor, with aluminum zirconium tetrachlorohydrex glycine typically present at concentrations of 15-20% in clinical-grade antiperspirants. These materials serve primary commercial purposes in personal care manufacturing, where performance claims must balance efficacy against skin tolerability thresholds. The ingredient type dimension shows aluminum compounds still dominating volume shipments while natural oils represent the fastest-expanding margin pool as brands reformulate away from metal salts. Formulation type segmentation reveals spray formats maturing in European markets while stick and gel applications gain shelf space in North American retail channels.
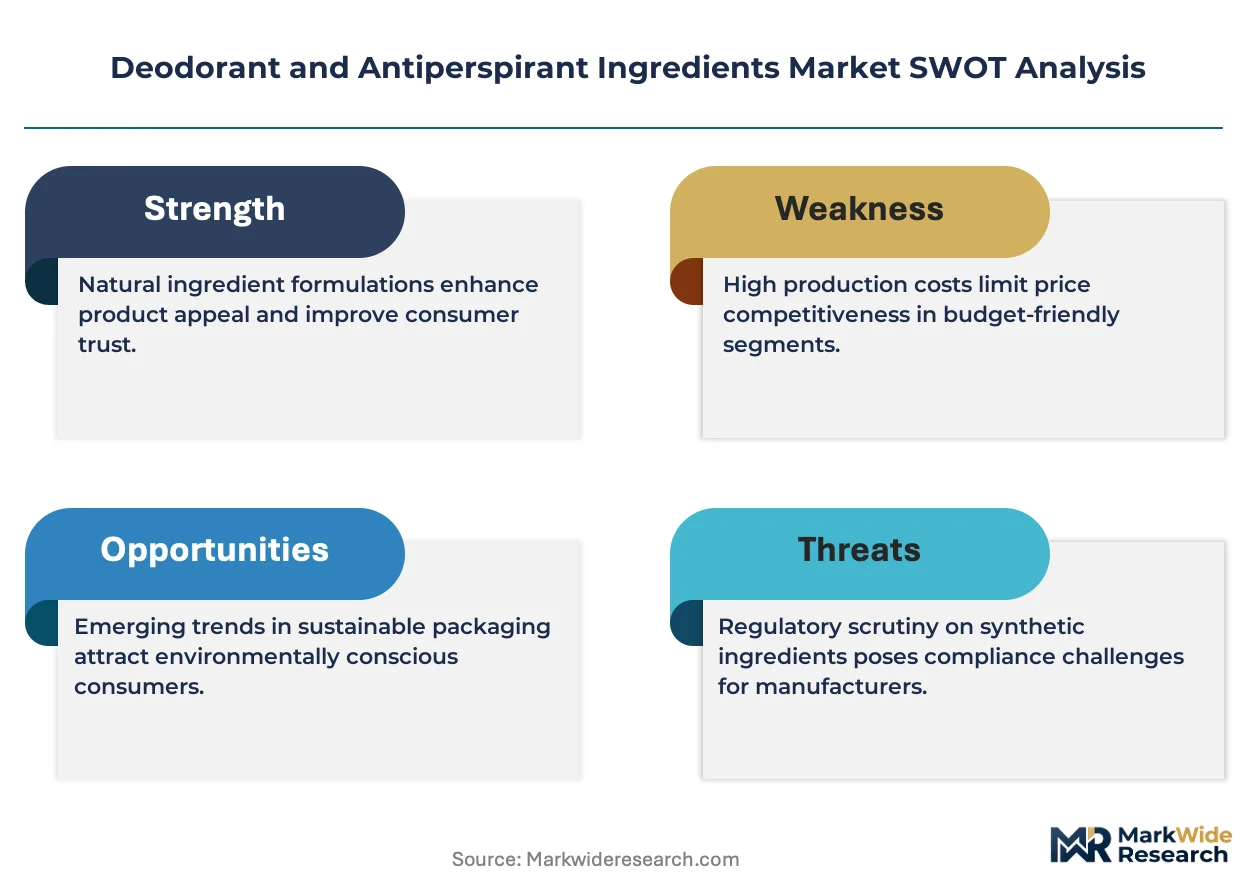
REACH compliance in Europe and FDA oversight in the United States impose strict safety thresholds on aluminum compound concentrations and antimicrobial agent usage, directly constraining permissible ingredient portfolios and reformulation cycles. The EU F-Gas Regulation additionally affects aerosol propellant choices for spray formulations, pushing manufacturers toward hydrocarbon or compressed gas alternatives. Stakeholders must monitor evolving dermatological safety assessments and propellant transition timelines to anticipate ingredient specification shifts before they disrupt supply contracts.
Market Dynamics
The deodorant and antiperspirant ingredients market is undergoing a fundamental reformulation pivot as aluminum-free alternatives displace metal-salt-based actives across premium personal care portfolios. Clean-label certification requirements from major retailers are compressing reformulation cycles and forcing ingredient suppliers to revalidate efficacy claims under stricter dermatological safety thresholds.
Growth Catalysts
- EU F-Gas Regulation:Aerosol propellant restrictions are accelerating hydrocarbon and compressed gas adoption, creating demand for compatible formulation chemistries and propellant-optimized active compounds.
- Clinical-grade antiperspirant demand:Prescription-strength formulations requiring aluminum zirconium tetrachlorohydrex glycine at 15-20% concentrations are sustaining volume in the therapeutic dermatology channel.
- Natural fragrance extraction:Botanical-derived scent compounds from Symrise AG and Givaudan are capturing margin expansion as premium brands reformulate away from synthetic musks and phthalates.
Market Restraints
- Aluminum compound concentration limits:FDA safety thresholds and REACH authorization requirements are constraining permissible active levels, forcing efficacy trade-offs in reformulated products.
- Propylene glycol supply concentration:Hydration base materials for stick and gel formats face input cost volatility from concentrated Asian petrochemical suppliers.
- Natural oil oxidation stability:Coconut-derived and essential oil actives present shorter shelf-life limitations compared to synthetic antimicrobial alternatives, complicating inventory management.
Strategic Opportunities
- India personal care manufacturing:CDSCO regulatory harmonization and PLI scheme incentives are attracting contract formulation investment for export-oriented deodorant production.
- Biotechnology-derived actives:Enzymatic odor-neutralization technologies converging with microbiome-friendly formulation science are opening patent-protected white space beyond metal salts.
- Direct-to-consumer subscription channels:Refillable solid format systems are bypassing traditional retail shelf-space constraints and enabling higher-margin ingredient specification.
Industry Challenges
- Clean-label certification timelines:EWG Verified and ECOCERT approval processes extend new ingredient commercialization by 18-24 months, compressing first-mover advantage windows.
- Legacy aerosol line conversion:Existing spray manufacturing infrastructure requires capital-intensive retooling to accommodate hydrocarbon propellant safety specifications and compressed gas filling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deodorant and Antiperspirant Ingredients Market |
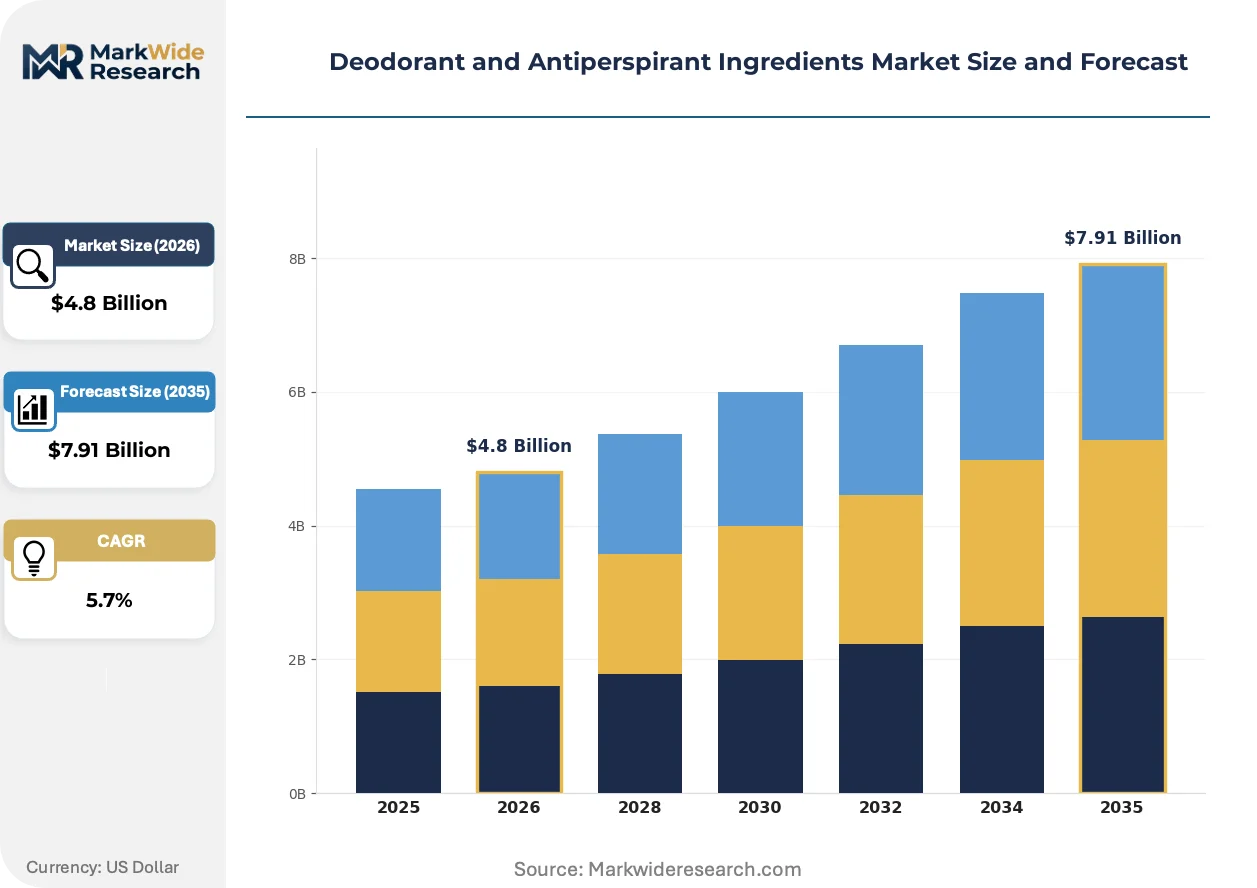
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Aluminum Compounds, Triclosan, Natural Oils, Fragrance Compounds Formulation Type: Roll-on, Spray, Stick, Gel Application Area: Body, Feet, Underarms, Clothing Consumer Segment: Men, Women, Unisex, Teens |
| Companies Covered | Symrise AG, BASF SE, Givaudan, Elementis PLC, Ashland, Arkema, Dow, Croda International, Univar Solutions LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deodorant and Antiperspirant Ingredients Market Strategic Shifts & Innovations
Formulation science is fragmenting along efficacy-versus-sustainability lines as brands navigate divergent consumer expectations and regulatory constraints. Active ingredient portfolios are splitting between clinical-performance metal salts and emerging botanical alternatives.
Prebiotic and postbiotic skin microbiome technologies are bifurcating the antimicrobial active segment. Lactobacillus-derived ferments and enzyme-based odor neutralizers are gaining formulation share among prestige personal care brands in Germany and the United States. This technology is bifurcating supplier relationships as biotechnology firms capture value traditionally held by chemical commodity producers.
REACH authorization requirements for aluminum chlorohydrate are tightening specification windows for European manufacturers. ECHA's ongoing safety assessments are forcing reformulation commitments before definitive hazard classifications conclude. Aerosol antiperspirant producers in Germany and France are accelerating hydrocarbon propellant transitions ahead of F-Gas phase-down deadlines.
Retailer clean-label mandates are compressing supplier qualification cycles. Sephora and Ulta Beauty certification requirements are displacing conventional formulation standards before regulatory mandates take effect. United States premium brands are advancing aluminum-free launches to secure shelf placement, creating demand-pull for natural active suppliers ahead of consumer volume maturation.
Deodorant and Antiperspirant Ingredients Market Segmentation
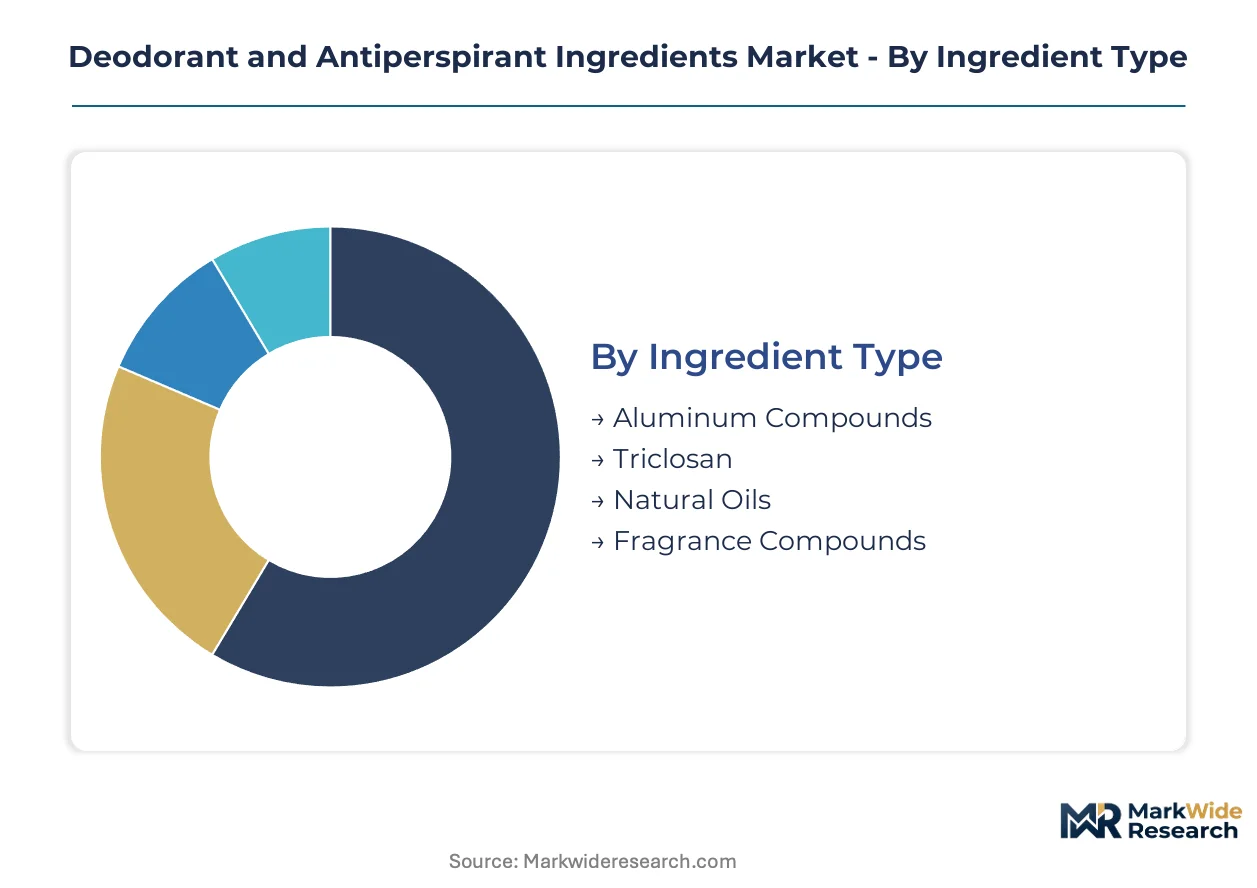
Ingredient portfolios across the deodorant and antiperspirant ingredients market are fragmenting along efficacy-versus-sustainability fault lines. Substitution pressures from clean-label mandates and REACH compliance are reshaping which segments capture formulation investment versus face displacement.
Ingredient Type:
Aluminum compounds face the most acute substitution threat as EU safety assessments and retailer certification requirements accelerate reformulation away from metal-salt actives.
- Aluminum Compounds:Aluminum chlorohydrate and aluminum zirconium tetrachlorohydrex glycine remain the benchmark for clinical antiperspirant efficacy. Concentrations of 15-20% in prescription-grade formulations sustain demand in therapeutic dermatology channels across Germany and the United States, though REACH authorization timelines are compressing permissible specification windows.
- Natural Oils:Coconut-derived antimicrobials and essential oil blends are capturing premium brand reformulation budgets as aluminum-free claims become shelf-placement prerequisites. Oxidation stability challenges and shorter shelf-life profiles complicate inventory management for contract manufacturers.
- Fragrance Compounds:Botanical extractions from specialized suppliers now dominate prestige positioning, displacing synthetic musks and phthalate-based scent carriers.
- Triclosan:Regulatory restrictions from FDA and ECHA have relegated this antimicrobial to niche industrial applications outside mainstream personal care.
Aluminum compounds retain volume leadership; natural oils hold the steepest expansion curve.
Formulation Type:
Format selection increasingly tracks propellant regulation geography and retail channel shelf-space economics rather than pure consumer preference.
- Spray:EU F-Gas Regulation is forcing hydrocarbon and compressed gas propellant transitions, requiring capital-intensive manufacturing retooling. German and French producers face compressed timelines for line conversion ahead of phase-down deadlines.
- Stick:North American retail channels are expanding shelf allocation for solid formats as refillable and plastic-reduced packaging designs gain retailer preference. Propylene glycol supply concentration from Asian petrochemical sources creates input cost volatility.
- Roll-on:Water-based formulations align with clean-label positioning but face slower dry-time complaints versus alternative formats.
- Gel:Transparent aesthetic appeals to younger demographics in United States urban markets, though formulation stability requires more complex polymer systems.
Stick formats are gaining share fastest in North American retail; spray maintains volume concentration in European mass channels.
Application Area:
Clinical positioning and specialty retail distribution determine margin capture across body-zone targeting.
- Underarms:The core volume segment where aluminum-based clinical claims and natural alternatives compete most directly for premium positioning.
- Body:Spray formats dominate this broader application zone, with fragrance-forward positioning driving brand differentiation.
- Feet:Specialized antifungal and high-perspiration formulations command therapeutic pricing tiers through pharmacy channels in Germany and the United States.
- Clothing:Fabric-focused sprays represent an emerging application zone as textile-integrated odor control gains experimental traction.
Underarm applications retain volume leadership; clothing represents the most speculative expansion trajectory.
Consumer Segment:
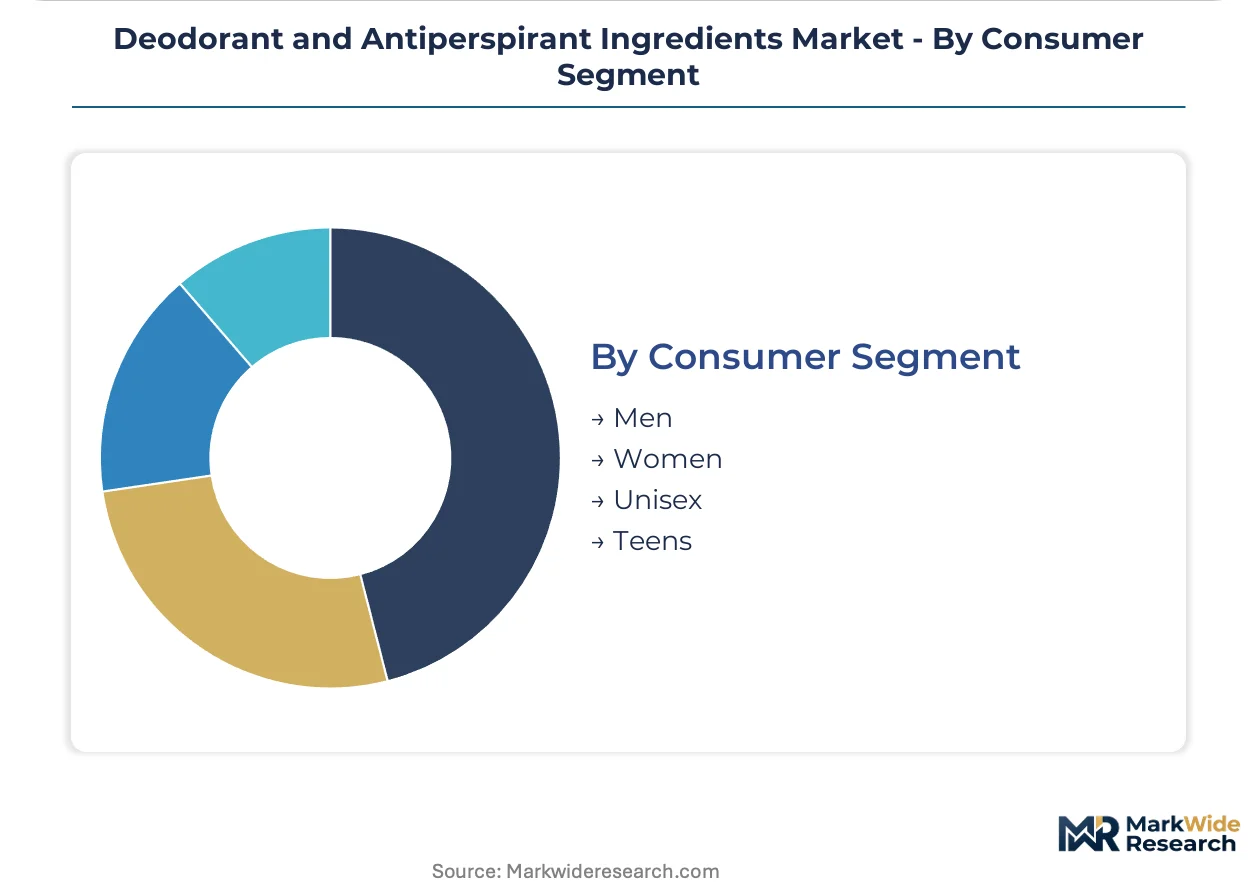
Gendered marketing architectures are dissolving as unisex positioning and teen-specific safety claims reshape product development priorities.
- Unisex:Clean-label brands are aggressively consolidating marketing spend behind gender-neutral positioning, collapsing traditional men-versus-women aisle segmentation in United States specialty retail.
- Women:Clinical-grade aluminum formulations still concentrate in this segment, though natural-alternative switching rates are accelerating fastest here.
- Men:Higher perspiration-volume claims sustain antiperspirant preference, with sport-positioned spray formats maintaining loyalty.
- Teens:Aluminum-free and gentle-formulation claims dominate parental purchase criteria, creating a protected niche for natural active suppliers.
Women's segment retains volume concentration; unisex positioning climbs the fastest as retailer shelf resets accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports aluminum zirconium compounds and natural fragrance actives to premium personal care brands across France and the United States. This trade corridor anchors European formulation science leadership while Asian manufacturing hubs absorb commodity-grade ingredient volumes.
United States
FDA oversight of aluminum compound concentrations and clinical-grade antiperspirant claims sustains demand for high-efficacy actives. The agency's dermatological safety thresholds force reformulation cycles among mass-market manufacturers. New Jersey and Illinois host concentrated contract formulation facilities serving direct-to-consumer subscription brands pivoting to aluminum-free portfolios.
Germany
ECHA's REACH authorization timelines for aluminum chlorohydrate compress specification windows for European manufacturers. The EU F-Gas Regulation accelerates hydrocarbon propellant transitions in aerosol lines. Cologne and Düsseldorf anchor fragrance compound innovation clusters where Givaudan and Symrise AG maintain technical service laboratories for brand co-development.
China
NMPA cosmetic ingredient registration requirements and GB standards for antimicrobial actives reshape import substitution strategies. Domestic brands accelerate natural oil sourcing from Yunnan and Guangxi botanical extraction zones. Shanghai and Guangzhou formulation hubs concentrate contract manufacturing investment for Southeast Asian export markets.
India
CDSCO regulatory harmonization and PLI scheme incentives attract contract formulation investment for export-oriented deodorant production. BIS certification requirements for aluminum compound purity grades constrain local supplier qualification. Maharashtra and Gujarat host emerging personal care manufacturing clusters serving Middle East and African distribution channels.
Brazil
ANVISA cosmetic ingredient safety assessments and tropical climate performance requirements sustain demand for high-efficacy antiperspirant formulations. Import tariffs on aluminum compounds protect domestic chemical producers. São Paulo state concentrates brand headquarters and contract manufacturing infrastructure for Latin American market development.
Deodorant and Antiperspirant Ingredients Market Key Industry Players
Listed leaders compete with private specialists across fragrance extraction and aluminum compound supply. BASF SE and Elementis PLC anchor publicly traded capacity in metal-salt actives, while privately held botanical specialists capture margin in natural alternatives. Three archetypes dominate: diversified chemical conglomerates with captive aluminum production, dedicated fragrance houses with extraction expertise, and distribution intermediaries consolidating formulation ingredient portfolios. Competitive moves concentrate on backward integration into propellant-compatible chemistries and strategic partnerships with microbiome biotechnology firms.
Within the diversified chemical tier, BASF SE and Dow exemplify scale-driven positioning across aluminum compound and functional additive supply. Symrise AG and Givaudan occupy the fragrance-specialist vector, leveraging botanical extraction capabilities for premium brand co-development. Croda International and Ashland sit within the functional ingredients layer, supplying polymer and emollient systems for stick and gel format stability. Arkema and Univar Solutions LLC represent distinct archetypes—specialty chemical manufacturing versus distribution consolidation—each capturing value at different supply chain positions.
| Leading Market Players |
|---|
| Symrise AG |
| BASF SE |
| Givaudan |
| Elementis PLC |
| Ashland |
| Arkema |
| Dow |
| Croda International |
| Univar Solutions LLC |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day lead times for REACH-compliant aluminum chlorohydrate shipments from German chemical producers concentrate pricing power among incumbent suppliers serving European formulation hubs. This inventory band forces North American contract manufacturers into premium spot-market sourcing when reformulation cycles compress specification windows, amplifying cost volatility for aluminum-free alternatives.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the deodorant and antiperspirant ingredients market. Price differentiation stems from EWG Verified certification status and volume scale commitments, with premium botanical actives commanding substantial markups over commodity aluminum compounds. Pricing pressure stems from propylene glycol cost compression as Asian petrochemical supply concentrates, squeezing margins for stick-format contract manufacturers. Mass-market retail buyers exhibit highest price sensitivity, while direct-to-consumer subscription brands absorb premium ingredient costs for clean-label positioning.
Supply Chain Analysis
Ninety-day oxidation-limited shelf lives for coconut-derived natural oils force just-in-time inventory management across North American contract manufacturing facilities. Supply concentrates in Germany for aluminum zirconium compounds, China for propylene glycol hydration bases, and India for emerging botanical extraction capacity. Raw material dependencies include Yunnan-sourced essential oils, Gulf Coast petrochemical feedstocks, and Rhine-Ruhr aluminum salt processing. Single-source vulnerability concentrates in Asian propylene glycol suppliers. Distribution runs through Univar Solutions and regional chemical distributors serving formulation hubs in New Jersey, Illinois, and São Paulo state.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The deodorant and antiperspirant ingredients market functions as a service-attach opportunity where formulation technical support and regulatory compliance consulting expand faster than commodity active compound sales. Subscription-brand co-development services and REACH authorization management represent recurring-revenue layers outpacing hardware ingredient margins.
For Market Incumbents: Compound defensive positioning through backward integration into Yunnan and Guangxi botanical extraction zones, securing captive supply of oxidation-stabilized natural oils before emerging biotechnology entrants scale enzymatic odor-neutralization platforms. Add capacity in Maharashtra and Gujarat to capture PLI scheme incentives and anchor export-oriented contract manufacturing relationships. Certification investment in ECOCERT and EWG Verified approval processes extends first-mover advantage windows as retailer mandates compress qualification timelines. For New Entrants and Emerging Players: Microbiome-friendly formulation technical service gaps offer white-space entry points where incumbents under-serve direct-to-consumer brands lacking in-house R&D infrastructure. Target teen-segment aluminum-free formulations as the most penetrable consumer niche, where parental safety concerns override price sensitivity and brand loyalty remains unformed. Pursue co-development partnerships with German fragrance innovation clusters in Cologne and Düsseldorf to leverage Givaudan and Symrise AG technical service laboratories for credibility transfer. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core personal care active portfolios amid aluminum substitution headwinds. Long-term viability centers on biotechnology-derived active patent estates and microbiome formulation science capabilities. Acquisition archetypes include enzymatic odor-neutralization specialists and prebiotic skin microbiome technology firms. The signal to watch is ECHA's definitive aluminum chlorohydrate hazard classification, which would trigger accelerated reformulation commitments and demand-pull for natural alternative suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Botanical Extraction | Captive supply of Yunnan-sourced essential oils secures margin and oxidation stability control. |
| REACH Authorization Management Service | Regulatory compliance consulting extends supplier relationships beyond commodity transaction cycles. |
| Biotechnology Active Patent Acquisition | Enzymatic odor-neutralization estates provide defensible positioning beyond metal-salt commoditization. |
| Direct-to-Consumer Brand Co-Development | Subscription channel technical partnerships bypass retail shelf-space constraints and enable premium specification. |
| Hydrocarbon Propellant Line Conversion | EU F-Gas Regulation compliance sustains aerosol manufacturing access in German and French markets. |
Research Approach
A standing panel of formulation chemists at contract manufacturing facilities, procurement leads at premium personal care brands, regulatory affairs specialists navigating REACH and FDA oversight, and distribution channel managers provided ongoing calibration throughout this study. Primary interviews combined with secondary validation from customs trade data, SEC filings of listed chemical suppliers, ECHA substance registration databases, and retail audit records from Nielsen and Circana. Bottom-up ingredient demand modeling triangulated against top-down personal care finished goods production estimates.
Consistency checks validated volume and value outputs against external benchmarks including chemical industry association reports and regional production statistics. The analytical framework segmented demand across ingredient type, formulation format, application zone, and consumer demographic dimensions throughout the projection horizon. CAGRs derived from regression analysis of historical shipment data and forward-looking reformulation cycle assumptions. Industry-specific forecast inputs included ECHA authorization timelines, EU F-Gas Regulation phase-down schedules, and retailer clean-label certification adoption curves.
Forecasts assume regulatory continuity in REACH, FDA, and CDSCO regimes; material policy shifts would require re-modeling of aluminum compound permissible concentrations and natural oil antimicrobial claim substantiation requirements. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Driveline Additives Market
Additives
Feed Additive Nosiheptide Premix Market
Additives
Sodium Caprylate Market
Additives
Marine Fuel Additives Market
Additives
Global Butyric Acid Derivatives Market
Additives
Global Dicalcium Phosphate (Feed Grade) Market
Additives
Hexyl Acetate Market
Additives
Tackifier Market
Additives
Russia Sodium Reduction Ingredient Market
Additives
China Citric Acid Market
Additives
Nucleating Agents Market
Additives
Potassium Nitrate Market
Additives
Extruded Inclusions Market
Additives
Europe Anti-Caking Market
Additives
Apocarotenal Market
Additives
Antiknock Agents Market