
 Citric Acid Anhydrous Market | 2026-2036
Citric Acid Anhydrous Market Size, Share, and Industry Trends Forecast 2026-2036
Citric Acid Anhydrous Market Analytics
Pharmaceutical demand is shifting toward higher-purity citric acid anhydrous as drug manufacturers reformulate excipient standards. Jungbunzlauer Suisse AG anchors European supply through specialized fermentation technology. Shandong Ensign Industry Co., Ltd. dominates Chinese output with integrated glucose-to-citric acid processing. Cargill, Incorporated leverages its agricultural feedstock control to sustain North American margin positions.
Citric acid anhydrous consists of anhydrous C6H8O7 crystals with moisture content below 0.5%, produced primarily via submerged fermentation of Aspergillus niger on molasses or sucrose, serving as a pH regulator, chelating agent, and preservative across industrial and consumer applications. Food grade formulations occupy the largest volume pool given entrenched beverage and processed food demand, while pharmaceutical grade commands premium positioning due to USP and EP compliance burdens. Cleaning products applications represent the fastest-growing segment as formulators substitute citric acid for phosphates in automatic dishwasher detergents and surface disinfectants.
The FDA governs citric acid anhydrous under 21 CFR 184.1033 for food use and enforces USP-NF monographs for pharmaceutical grades, while China's NMPA and SAMR administer GB 1886.235 for food additive purity and GB standards for pharmaceutical excipients. REACH and the EU Green Deal are reshaping European sourcing requirements through bio-based content mandates and carbon footprint disclosure rules. Stakeholders must monitor regulatory divergence between FDA, EMA, and NMPA purity specifications when configuring multi-regional supply chains.
Market Dynamics
Fermentation capacity concentration in Shandong Province is reshaping global citric acid anhydrous trade flows, as Chinese producers integrate backward into glucose supply and displace traditional molasses-dependent operations in Europe and North America.
Growth Catalysts
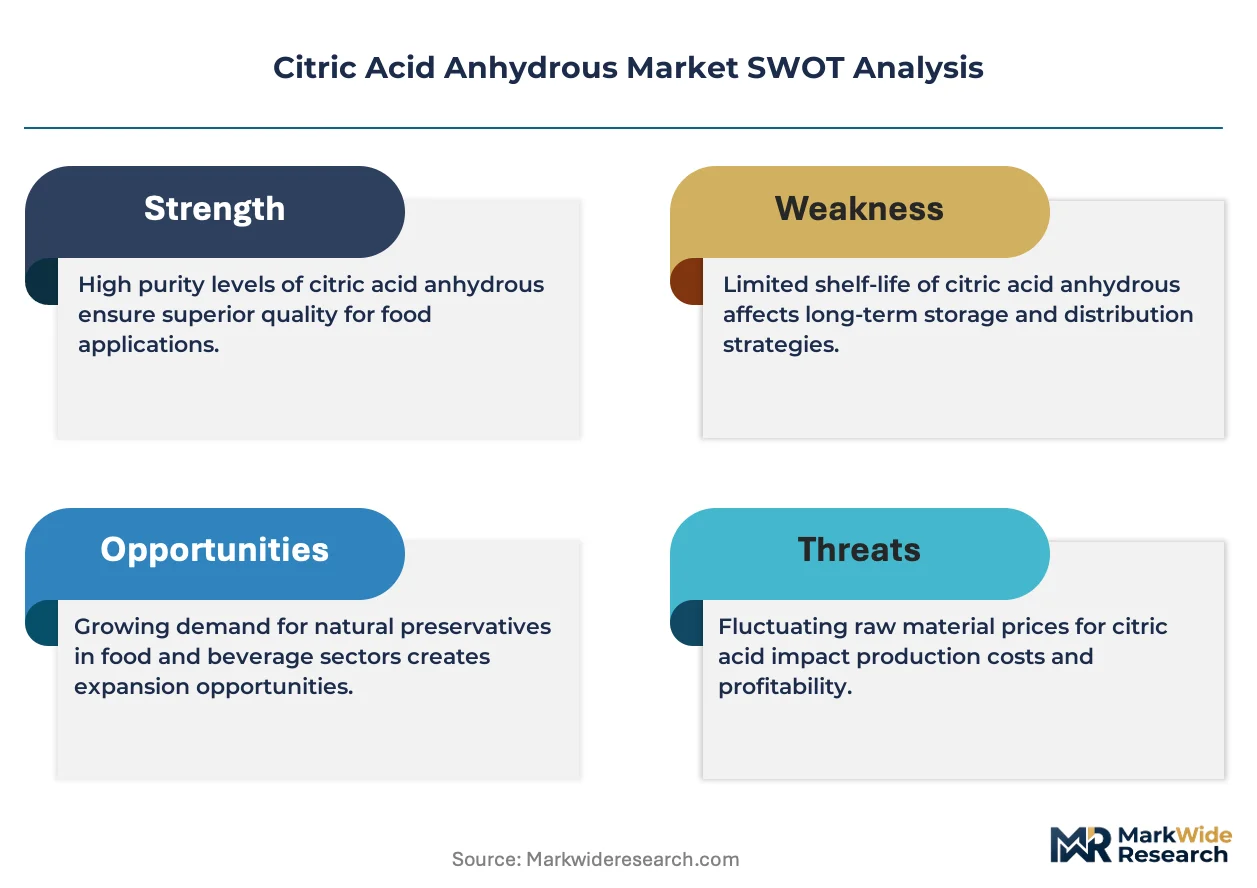
- Pharmaceutical-grade demand pull:USP-NF and EP compliance requirements for excipients are elevating purity specifications across generic drug manufacturing, tightening supplier qualification thresholds.
- EU Green Deal bio-based mandates:REACH carbon footprint disclosure rules and renewable content thresholds are redirecting procurement toward fermentation-based citric acid over petrochemical alternatives.
- Phosphate substitution in cleaning:Automatic dishwasher detergent formulators are accelerating citric acid adoption as phosphates face discharge restrictions under EPA and state-level water quality regulations.
Market Restraints
- Molasses price volatility:Sugar beet and sugarcane harvest fluctuations in Brazil and India transmit directly to fermentation input costs, compressing margins for non-integrated producers.
- Shandong supply concentration:Over sixty percent of global anhydrous capacity resides within 200 kilometers of Weifang, creating single-point vulnerability to environmental enforcement or energy rationing.
- Citrate ester competition:Acetyl tributyl citrate and triethyl citrate plasticizers are capturing share in flexible PVC applications where migration resistance requirements exceed anhydrous acid performance.
Strategic Opportunities
- Southeast Asia beverage expansion:Vietnam and Indonesia's carbonated soft drink bottling capacity additions are outpacing local citric acid supply, opening import substitution windows.
- Pharmaceutical excipient pre-mix integration:Direct compression tablet formulations are creating demand for co-processed citric acid-lactose or citric acid-mannitol blends with specified particle size distributions.
- Carbon capture fermentation coupling:China's dual carbon goals are incentivizing citric acid plants to integrate CO2 capture from off-gas streams, generating compliance credits and process efficiency gains.
Industry Challenges
- USP-NF monograph testing capacity:Pharmaceutical-grade certification requires validated HPLC and heavy metals analysis infrastructure that smaller fermentation operators lack, extending qualification timelines.
- Legacy blackstrap molasses supply contracts:Long-term offtake agreements with sugar refineries lock producers into feedstock specifications that conflict with GB 1886.235 purity benchmarks for food-grade output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citric Acid Anhydrous Market |
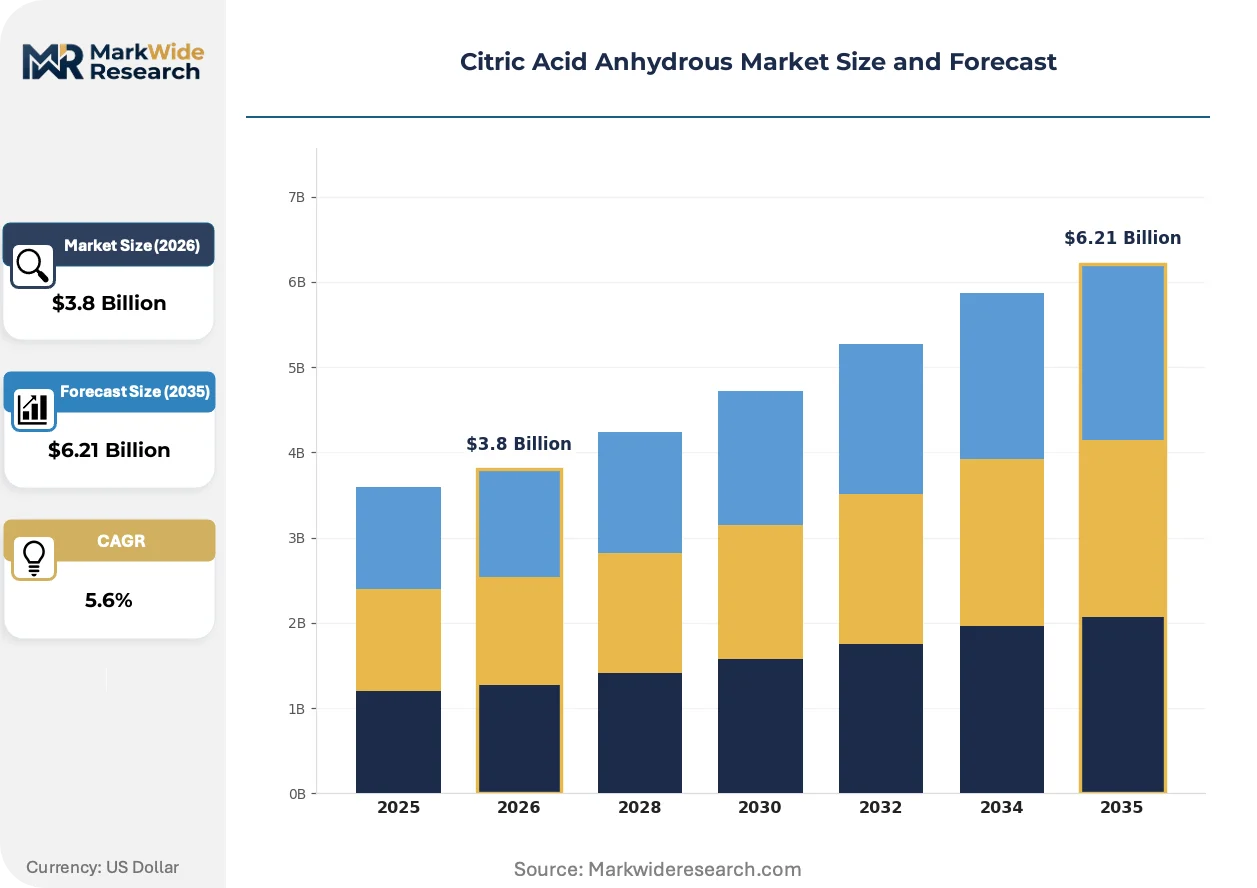
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Feed Grade Application: Food & Beverage, Personal Care, Pharmaceuticals, Cleaning Products Packaging Type: Bags, Drums, Bulk Containers, Custom Packaging End User: Food Manufacturers, Cosmetic Companies, Drug Manufacturers, Agriculture Enterprises |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, Jungbunzlauer Suisse AG, RZBC Group Co., Ltd., Shandong Ensign Industry Co., Ltd., COFCO Biochemical, Tate & Lyle, Weifang Ensign Industry Co., Ltd., TTCA Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citric Acid Anhydrous Market Evolving Landscape
Continuous fermentation monitoring and automated pH control systems are compressing batch-to-batch variability, enabling pharmaceutical-grade production at commercial food-grade scale.
Membrane filtration cell retention technology is unifying upstream fermentation with downstream crystallization efficiency. Jungbunzlauer Suisse AG and Shandong Ensign have deployed ceramic membrane bioreactors that sustain higher cell densities, cutting fermentation cycle times by fifteen to twenty percent. The structural consequence is a compression of the premium-standard price spread as pharmaceutical-grade yields approach food-grade unit economics.
REACH bio-based content verification and the EU Green Deal sustainable product framework are mandating mass-balance chain of custody documentation. Fermentation operators must now certify agricultural feedstock origin through ISCC PLUS or equivalent schemes to access EU pharmaceutical and food additive procurement channels. German and French formulators are most advanced in supplier auditing, with Benelux and Nordic markets following six to twelve months behind.
Long-term toll manufacturing agreements are displacing spot market purchasing among North American beverage concentrate producers. PepsiCo and Coca-Cola system bottlers are consolidating citric acid supply under three to five-year contracts with fixed volume tiers and indexed molasses pass-through mechanisms. This concentration is most visible in the US Midwest and Southeast, where corn-derived glucose feedstock integration offers margin stability unavailable to importers.
Citric Acid Anhydrous Market Segmentation
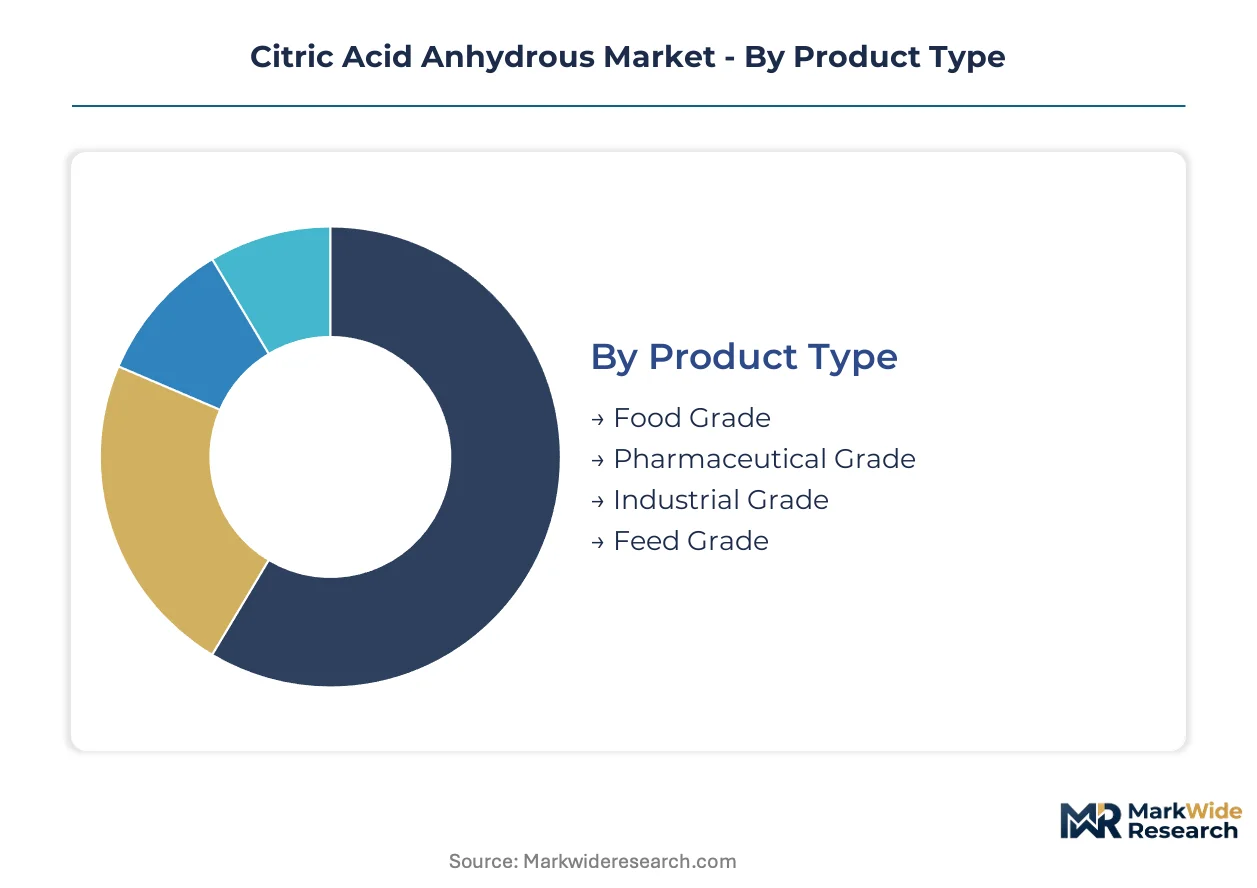
Citric acid anhydrous demand fragments across purity tiers and end-use specifications that dictate fermentation cycle length, crystallization protocols, and certification burdens. Segmentation reveals where margin compression hits hardest and where pharmaceutical compliance creates defensible pricing power.
Product Type:
Standalone acid applications dominate volume, while embedded excipient systems in drug formulations command integration premiums and longer qualification cycles.
- Food Grade:Anhydrous crystals meeting FCC and GB 1886.235 specifications for moisture content below 0.5%. Beverage acidulation in China absorbs the largest share, though Shandong environmental enforcement periodically constrains spot availability.
- Pharmaceutical Grade:USP-NF and EP monograph compliance with validated heavy metals testing and endotoxin limits. Generic drug pre-mix integration in India and Southeast Asia is tightening supplier audit requirements faster than certification capacity can expand.
- Industrial Grade:Technical specifications for metal chelation and pH adjustment without food or pharma certification burdens.
- Feed Grade:Acidifier applications in poultry and swine nutrition with lower purity thresholds than food-grade output.
Food grade leads volumes today; pharmaceutical grade is gaining share fastest.
Application:
Cost tier stratification separates commodity acid substitution from premium formulation integration where performance specifications lock in supplier relationships.
- Food & Beverage:pH regulation and preservation across carbonated drinks, juices, and processed foods. PepsiCo and Coca-Cola system bottlers in the US Midwest have shifted to three-year toll contracts with indexed glucose pass-through mechanisms.
- Pharmaceuticals:Excipient and active pharmaceutical ingredient applications requiring USP-NF or EP certification. Direct compression tablet formulations are driving demand for specified particle size distributions in co-processed blends.
- Personal Care:pH buffering and chelation in cosmetics and toiletries with moderate purity requirements.
- Cleaning Products:Phosphate replacement in automatic dishwasher detergents and surface disinfectants. EPA discharge restrictions are accelerating citric acid adoption faster than alternative sequestrants can achieve cost parity.
Food and beverage applications anchor current revenue; cleaning products show the steepest expansion trajectory.
Packaging Type:
Customer scale and handling infrastructure determine packaging economics, with bulk integration favoring backward-linked producers and custom formats serving specialized compounders.
- Bags:25-50 kg multiwall paper or polyethylene sacks for mid-scale food and pharmaceutical compounders.
- Drums:Fiber or steel drums for liquid and solid acid handling in cosmetic and specialty chemical operations.
- Bulk Containers:Intermediate bulk containers and tanker shipments for high-volume beverage and cleaning product manufacturers. Cargill's corn-derived glucose integration in North America supports dedicated bulk supply chains with margin stability unavailable to importers.
- Custom Packaging:Specified formats for pharmaceutical pre-mix and just-in-time manufacturing requirements.
Bulk containers dominate procurement among integrated manufacturers; custom packaging is climbing fastest as pharmaceutical co-processing expands.
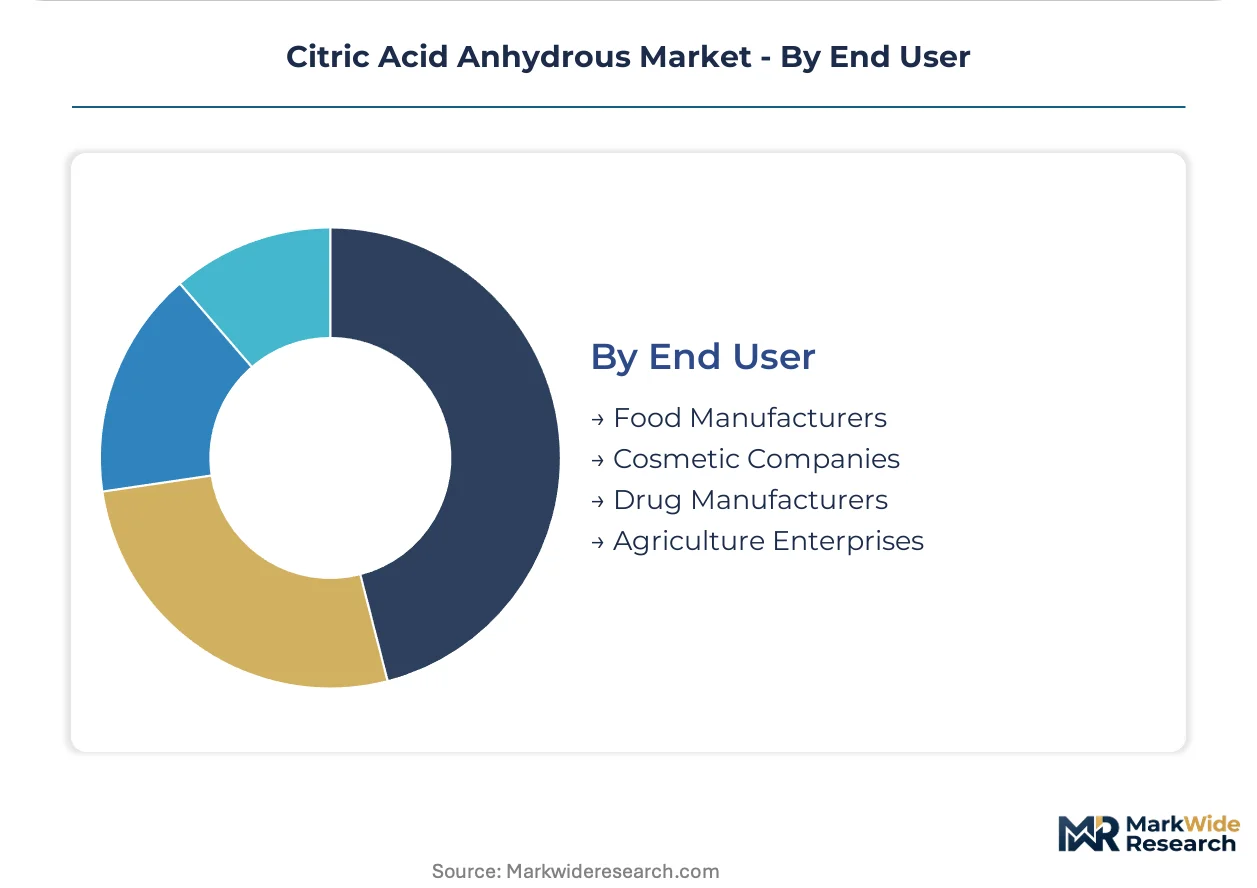
End User:
Supply concentration varies sharply by end-user technical requirements, with pharmaceutical and cosmetic buyers facing narrower qualified supplier bases than agricultural and mainstream food manufacturers.
- Food Manufacturers:Beverage concentrate producers and processed food operations with established GB or FCC certification requirements.
- Cosmetic Companies:Personal care formulators with moderate purity needs and flexible sourcing options.
- Drug Manufacturers:Generic pharmaceutical producers and excipient pre-mix compounders facing USP-NF and EP compliance burdens. Jungbunzlauer Suisse AG anchors European supply through specialized fermentation technology that sustains higher cell densities.
- Agriculture Enterprises:Feed acidifier users with price-sensitive procurement and limited specification constraints.
Food manufacturers lead current offtake; drug manufacturers are expanding procurement fastest as generic formulation volumes rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting citric acid anhydrous capacity toward jurisdictions with lower environmental compliance costs and integrated agricultural feedstock networks. Shandong Province's fermentation cluster exploits China's dual carbon policy implementation gaps while European REACH carbon disclosure rules raise cost barriers for legacy producers.
China
Beverage acidulation and pharmaceutical excipient demand from domestic generic drug manufacturers drive volume. NMPA's GB 1886.235 purity benchmarks and SAMR enforcement of food additive standards are tightening certification requirements. Weifang and surrounding Shandong cities concentrate over sixty percent of global anhydrous capacity, with environmental enforcement periodically constraining spot availability.
United States
PepsiCo and Coca-Cola system bottlers in the Midwest and Southeast are consolidating procurement under long-term toll contracts with indexed glucose pass-through mechanisms. FDA 21 CFR 184.1033 governs food-grade applications while USP-NF monographs regulate pharmaceutical excipients. Cargill's corn-derived glucose integration across Iowa and Illinois supports dedicated bulk supply chains with margin stability unavailable to importers.
Germany
REACH bio-based content verification and EU Green Deal sustainable product frameworks are mandating mass-balance chain of custody documentation for pharmaceutical and food additive procurement. EMA excipient guidelines and ECHA carbon footprint disclosure rules redirect sourcing toward certified fermentation-based supply. Benelux and Nordic markets follow German and French formulators in supplier auditing sophistication with six-to-twelve-month implementation lags.
India
Generic pharmaceutical pre-mix integration and direct compression tablet formulations are tightening supplier audit requirements faster than USP-NF certification capacity can expand. CDSCO pharmaceutical excipient regulations and FSSAI food additive standards govern import and domestic production. Maharashtra and Gujarat pharmaceutical manufacturing clusters are outpacing local citric acid supply, creating import substitution windows for qualified exporters.
Brazil
Sugar beet and sugarcane harvest fluctuations transmit directly to fermentation input costs for molasses-dependent operations. ANVISA pharmaceutical regulations and Ministry of Agriculture food additive standards administer purity benchmarks. São Paulo state's sugar-ethanol complex offers backward integration potential for fermentation operators seeking captive feedstock supply.
Citric Acid Anhydrous Market Competitive Landscape
Capacity expansion dominates the current landscape as Chinese producers integrate backward into glucose supply and displace traditional molasses-dependent operations. The market structure concentrates around fermentation specialists with captive agricultural feedstock networks, creating a tiered competitive environment. Three strategic archetypes define positioning: integrated agribusiness conglomerates with corn and sugarcane control, specialized fermentation technology operators with pharmaceutical-grade certification infrastructure, and regional chemical processors serving technical industrial applications. Dominant competitive moves include multi-year toll manufacturing agreements with beverage concentrate producers and membrane filtration technology licensing for yield optimization.
Among integrated agribusiness operators, Cargill, Incorporated and Archer Daniels Midland Company exemplify the feedstock-control archetype through corn-derived glucose networks in North America. Jungbunzlauer Suisse AG represents the specialized fermentation technology tier with European pharmaceutical-grade certification capabilities. Shandong Ensign Industry Co., Ltd. anchors the Chinese capacity concentration through integrated glucose-to-citric acid processing in Shandong Province.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Jungbunzlauer Suisse AG |
| RZBC Group Co., Ltd. |
| Shandong Ensign Industry Co., Ltd. |
| COFCO Biochemical |
| Tate & Lyle |
| Weifang Ensign Industry Co., Ltd. |
| TTCA Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Membrane filtration cell retention technology is compressing the premium-standard price spread as pharmaceutical-grade yields approach food-grade unit economics, concentrating margin pressure on non-integrated producers while rewarding Shandong-based operators with captive glucose supply.
Pricing Analysis
Distributor margins compress most acutely for spot-market purchases, while direct-to-OEM toll contracts with PepsiCo and Coca-Cola system bottlers secure indexed glucose pass-through mechanisms. Three-tier pricing structure across pharmaceutical, food, and industrial grades reflects certification burden divergence, with USP-NF compliance costs widening spreads. Price erosion runs through food-grade spot markets as Shandong capacity expansion outpaces beverage demand growth. Agricultural feedstock buyers exhibit highest price sensitivity; pharmaceutical excipient procurement prioritizes qualification stability over unit cost.
Supply Chain Analysis
Hub-and-spoke distribution patterns radiate from Weifang regional centers to Southeast Asian beverage bottlers and European pharmaceutical compounders. Supply concentrates in China, with secondary nodes in Germany and the United States. Raw material dependencies center on corn-derived glucose, sugar beet molasses, and ceramic membrane bioreactor components. Single-source vulnerability stems from over sixty percent of global capacity residing within two hundred kilometers of Weifang. Distribution runs through dedicated bulk tanker shipments for integrated manufacturers and multiwall sacks for mid-scale compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as generic drug manufacturers shift procurement toward USP-NF certified excipients with validated heavy metals testing infrastructure.
For Market Incumbents: Hedge against Shandong supply concentration by securing alternative fermentation capacity in Maharashtra or Gujarat pharmaceutical clusters. Invest in membrane filtration licensing to sustain yield advantages as ceramic bioreactor technology diffuses. Defensive certification investments in EP compliance protect European market access against REACH bio-based verification tightening. For New Entrants and Emerging Players: EU Green Deal bio-based mandates in Germany open a window for ISCC PLUS certified operators to capture pharmaceutical procurement from legacy molasses-dependent suppliers. Target Vietnam and Indonesia carbonated soft drink bottling capacity additions where local citric acid supply lags demand expansion. Pursue toll manufacturing agreements with three-year volume commitments to secure offtake before incumbents consolidate relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale fermentation operators lacking pharmaceutical-grade certification infrastructure but possessing glucose supply integration. Long-term viability favors assets with captive agricultural feedstock networks and membrane filtration deployment capability. Watch for NMPA enforcement actions against Shandong environmental compliance gaps as inflection indicators for supply disruption premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glucose Supply | Cargill's corn network demonstrates margin stability unavailable to molasses-dependent importers. |
| Pharmaceutical-Grade Certification Investment | USP-NF monograph compliance creates defensible pricing power against food-grade commoditization. |
| Membrane Filtration Technology Licensing | Jungbunzlauer's ceramic bioreactor deployment cuts fermentation cycle times by fifteen to twenty percent. |
| Long-term Toll Manufacturing Agreements | PepsiCo system bottlers have shifted procurement to three-year contracts with indexed pass-through mechanisms. |
| Carbon Capture Fermentation Coupling | China's dual carbon goals incentivize CO2 capture integration for compliance credit generation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation plant managers, pharmaceutical procurement leads, beverage concentrate formulators, and distribution channel partners with secondary validation through FDA 21 CFR filings, NMPA GB standard publications, customs trade data, and SEC 10-K disclosures from integrated agribusiness operators. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Segment-weighting across the projection horizon applied grade tier, end-use industry, packaging format, and regional production hub dimensions to distribute growth assumptions. CAGRs derived from fermentation capacity expansion schedules, beverage bottling capacity additions, and pharmaceutical excipient demand trajectories. Industry-specific inputs included molasses price volatility indices and environmental enforcement probability assessments for Shandong Province.
Revisions become necessary when NMPA enforcement actions disrupt Shandong supply, REACH bio-based mandates accelerate faster than certification capacity expands, or phosphate substitution demand in cleaning products exceeds fermentation capacity additions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Formulation Additives Market
Additives
Hexyl Acetate Market
Additives
Butyrate Additives Market
Additives
Crosslinking Agents Market
Additives
Global Dicalcium Phosphate (Feed Grade) Market
Additives
Deodorant and Antiperspirant Ingredients Market
Additives
Octane Improver Fuel Additives Market
Additives
Automotive Coolant Additives Market
Additives
Iso-Butyric Acid Market
Additives
Sodium Potassium Tartrate Market
Additives
Low Melt Inclusions Market
Additives
Green Polymer Additive Market
Additives
Carboxymethylcellulose (CMC) Market
Additives
Sorbitan Laurate Market
Additives
North America Paints and Coatings Additives Market
Additives
Global Metal Scavenging Agents Market