
 Sodium Citrate Anhydrous Market | 2026-2036
Sodium Citrate Anhydrous Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Citrate Anhydrous Market Analytics
Citric acid is decoupling from petroleum-derived chelating agents across detergent and industrial cleaning formulations, improving biodegradability profiles while maintaining sequestration performance. Jungbunzlauer Suisse AG leverages its Swiss fermentation infrastructure to sustain pharmaceutical-grade output with backward integration into molasses feedstock. Cargill, Incorporated anchors North American supply through corn-derived citric acid streams that compete on cost with Asian fermentation routes. FUSO CHEMICAL CO., LTD. dominates Japanese technical-grade distribution, occupying positions in food preservative and dialysis buffer supply chains.
Sodium citrate anhydrous is the dehydrated sodium salt of citric acid, typically specified at minimum 99.0% purity with a pH of 7.5–9.0 in solution, manufactured through neutralization of citric acid with sodium carbonate or hydroxide followed by crystallization and thermal drying. Its primary commercial purpose centers on pH buffering, anticoagulation in blood collection tubes, and chelation of metal ions in food preservation and pharmaceutical formulations. Pharmaceutical grade commands the deepest margin pools due to USP and EP certification requirements for injectable and dialysis applications, while food grade sustains the largest volume base across beverage stabilization and emulsified cheese processing. Industrial grade is accelerating in water treatment and concrete retarder segments where phosphate replacement is intensifying.
FDA 21 CFR regulations for direct food substances and USP monograph standards govern pharmaceutical-grade market access in the United States, while the European Pharmacopoeia and REACH compliance frameworks shape specifications across EU manufacturing. India's CDSCO and BIS certification requirements for excipient imports are tightening quality documentation for Chinese and Southeast Asian suppliers. Stakeholders must monitor fermentation feedstock cost volatility and evolving pharmacopoeial harmonization between USP, EP, and JP standards to secure multi-jurisdictional product registrations.
Market Dynamics
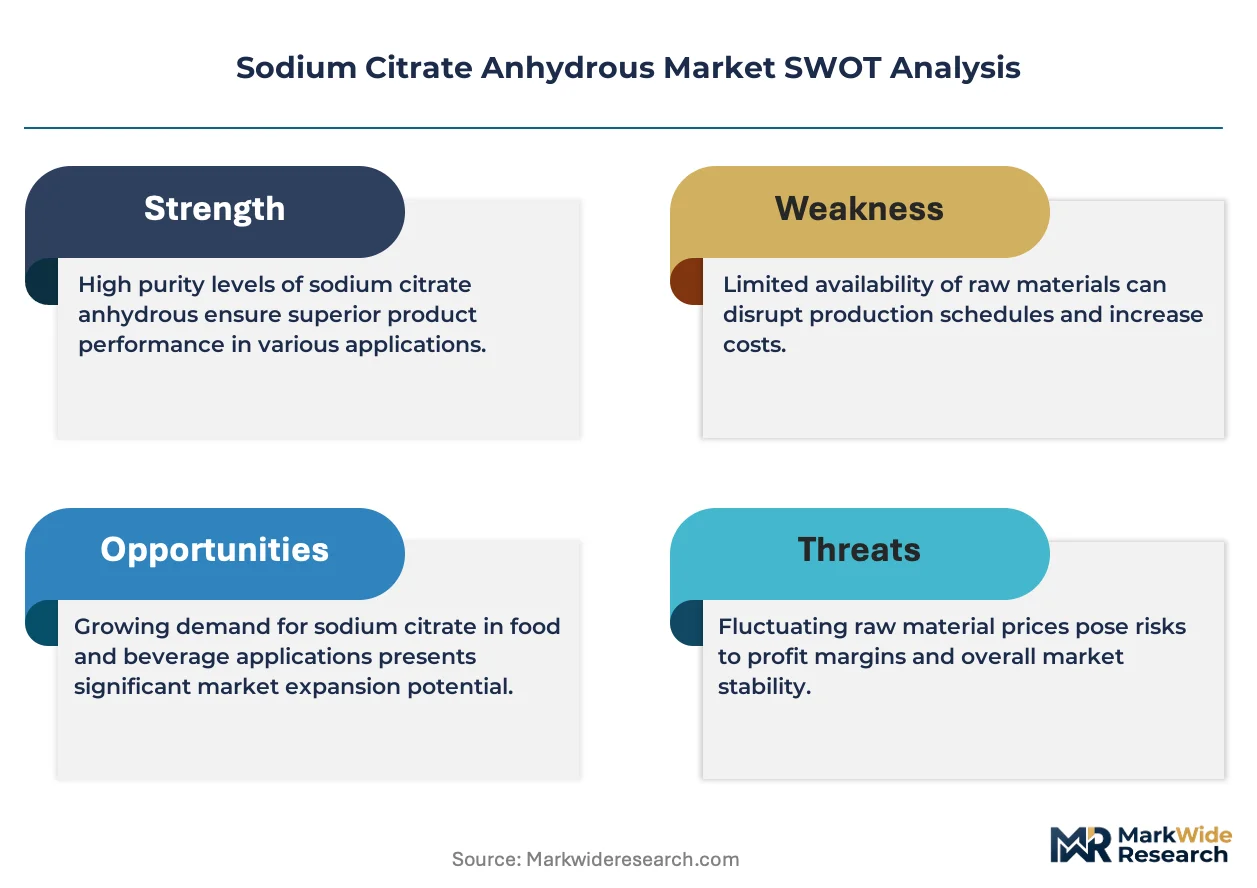
Pharmaceutical-grade certification requirements are compressing supplier margins while concentrating procurement power among dialysis buffer and blood collection tube manufacturers with multi-jurisdictional registration capabilities.
Growth Catalysts
- F-Gas Regulation:The European Union's phasedown of hydrofluorocarbon refrigerants accelerates demand for non-halogenated chemical intermediates in industrial cooling systems, pulling sodium citrate into metal chelation applications.
- Biologic stabilization:German pharmaceutical manufacturers are expanding buffer salt procurement for monoclonal antibody and mRNA vaccine formulation, tightening supply-demand balance for USP-grade material.
- Hyderabad-Visakhapatnam corridor:India's active pharmaceutical ingredient manufacturing cluster is localizing excipient sourcing to reduce import dependency, creating dedicated demand pools for CDSCO-compliant suppliers.
Market Restraints
- Molasses feedstock volatility:Fermentation input costs fluctuate with Brazilian sugarcane harvest cycles and bioethanol diversion, squeezing margin stability for citric acid derivatives.
- Chinese supply concentration:Technical-grade sodium citrate production clusters in Shandong and Jiangsu provinces, exposing buyers to single-origin disruption risks and freight rate spikes.
- Phosphate substitution ceiling:Concrete retarder and water treatment applications face performance limits where sodium citrate cannot match polyphosphate sequestration efficiency in hard water conditions.
Strategic Opportunities
- Cell therapy buffers:Ex vivo cell expansion protocols for CAR-T manufacturing require low-endotoxin sodium citrate formulations, opening premium pricing tiers beyond traditional pharmaceutical grades.
- CDSCO harmonization:India's alignment of excipient master file requirements with ICH Q3D guidelines reduces registration friction for suppliers holding USP and EP certifications simultaneously.
- Direct-to-brewery distribution:Beverage stabilization demand in craft brewing bypasses traditional chemical distributors through specialty ingredient platforms, compressing channel margins.
Industry Challenges
- Pharmacopoeial divergence:USP, EP, and JP monograph variations in heavy metal limits and microbial specifications force redundant testing protocols, extending batch release timelines.
- Anhydrous handling infrastructure:Hygroscopic powder properties require climate-controlled warehousing and pneumatic transfer systems, elevating capital intensity for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Citrate Anhydrous Market |
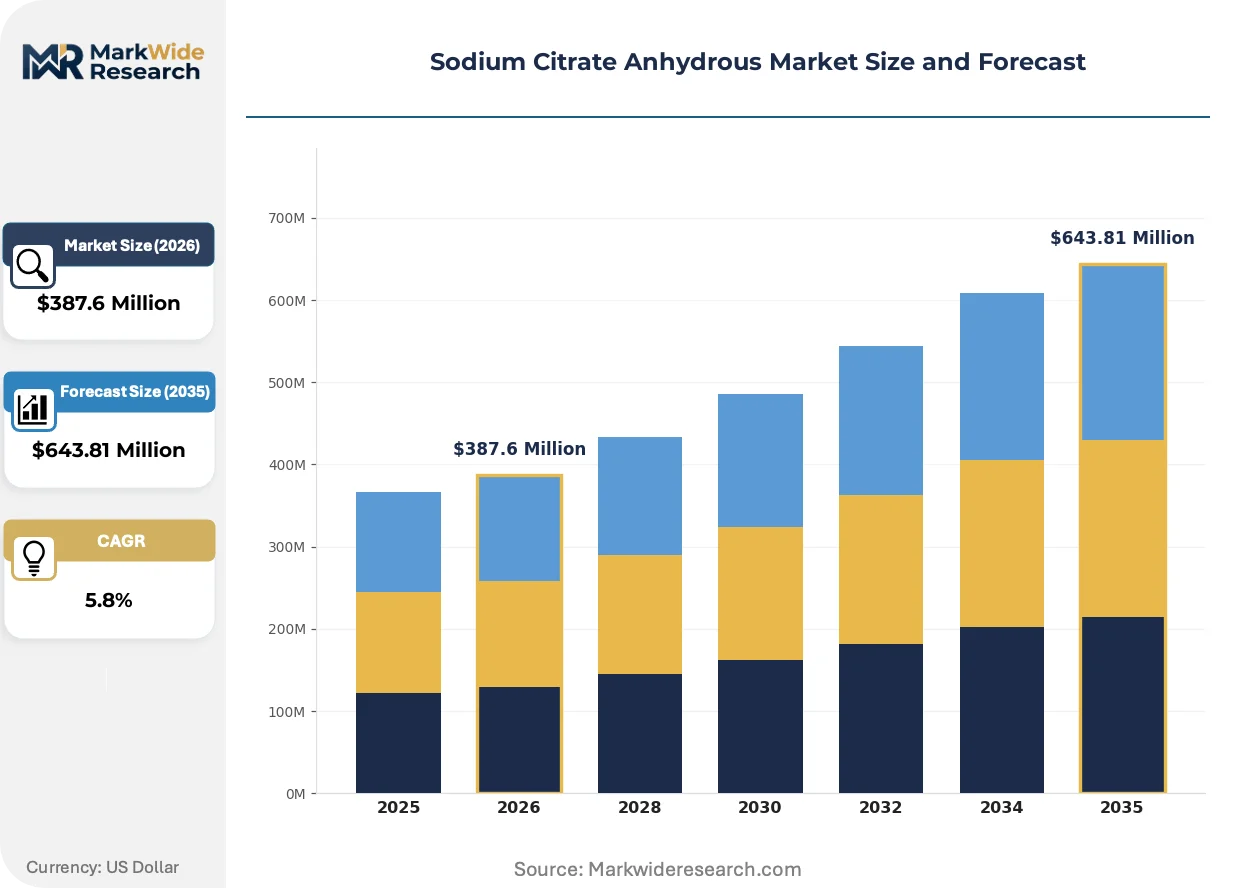
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Laboratory Grade End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Cleaning Agents Packaging Type: Bags, Drums, Cartons, Bulk Packaging Form: Powder, Granules, Crystals, Liquid |
| Companies Covered | Jungbunzlauer Suisse AG, Cargill, Incorporated, ADM, Pan Chem Corporation, ATPGroup, Tate & Lyle PLC, COFCO, Citrique Belge N.V., FUSO CHEMICAL CO., LTD., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Citrate Anhydrous Market Evolving Landscape
Continuous crystallization and inline drying technologies are displacing batch processing in citric acid derivative manufacturing, compressing cycle times while tightening particle size distribution for pharmaceutical applications.
Membrane filtration coupled with simulated moving bed chromatography is automating impurity removal in sodium citrate downstream processing. Dialysis buffer manufacturers in Switzerland and Germany are adopting these systems to reduce endotoxin variability. The technology is automating quality assurance steps that previously required offline laboratory verification, shrinking batch release windows from days to hours.
REACH authorization requirements for trisodium citrate in industrial applications are tightening substance volume tracking and downstream user communication obligations. ECHA's 2024 updates to safety data sheet formats extend compliance burdens to distributors handling technical grades. Food preservative and cleaning compound blenders in the Netherlands and Belgium are consolidating supplier bases to reduce documentation fragmentation.
Long-term offtake agreements with fixed-price escalation clauses are displacing spot market purchases among North American blood collection tube manufacturers. Procurement teams at medical device firms are locking three-year supply contracts to insulate against fermentation feedstock volatility. This contracting pattern concentrates most visibly in Massachusetts and California, where anticoagulant tube production clusters near hospital network distribution hubs.
Sodium Citrate Anhydrous Market Segmentation
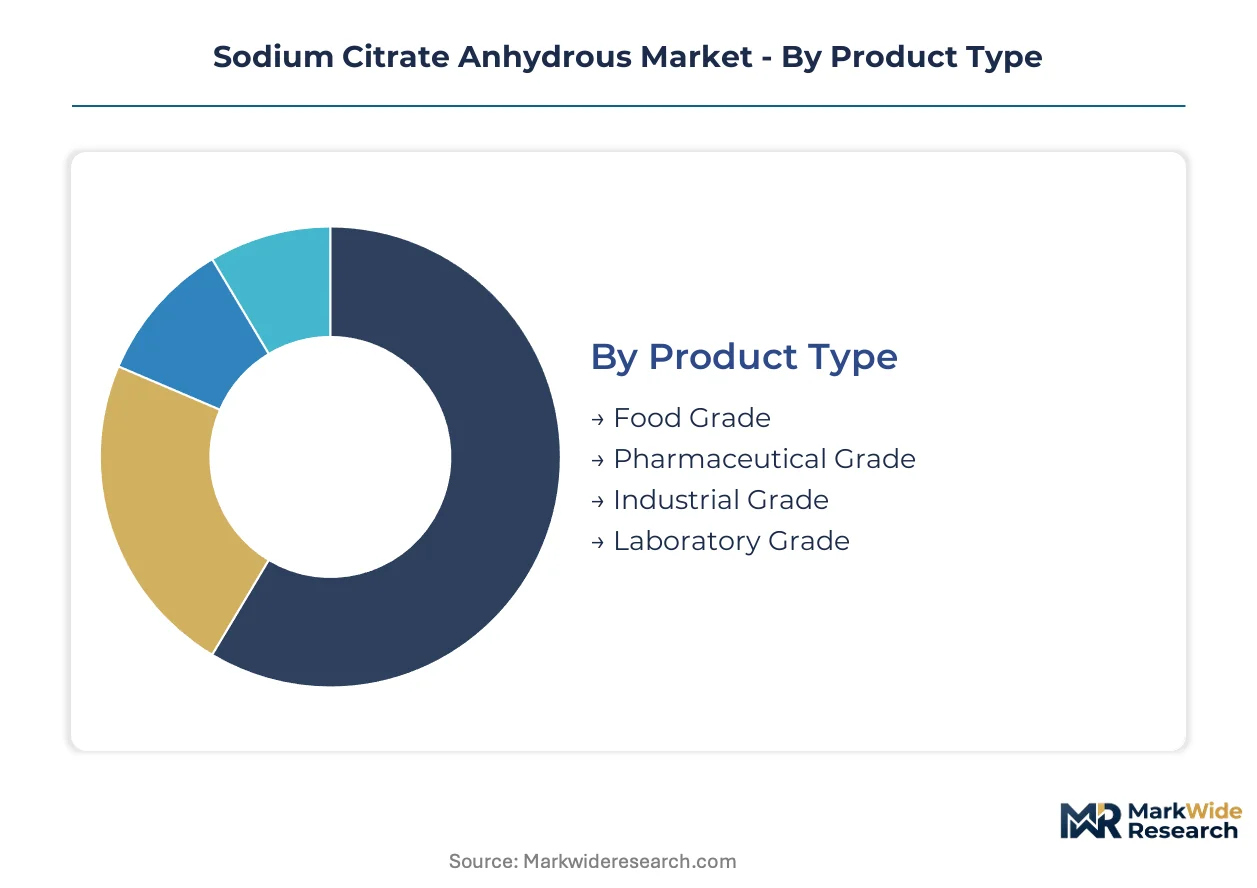
Sodium citrate anhydrous markets stratify sharply around certification burdens, with pharmaceutical and food safety mandates creating divergent margin pools. Understanding these segment boundaries reveals where procurement power concentrates and where new entrants face the steepest compliance barriers.
Product Type:
Certification requirements fragment supplier economics across grades, with USP and EP monographs demanding redundant testing protocols that compress margins for multi-jurisdictional manufacturers.
- Pharmaceutical Grade:Minimum 99.0% purity with endotoxin limits below 2.5 EU/g per USP standards. Dialysis buffer manufacturers in Germany and blood collection tube producers in Massachusetts lock in three-year offtake agreements to secure supply. The grade commands the deepest margin pools but requires climate-controlled warehousing and pneumatic transfer systems.
- Food Grade:FDA 21 CFR direct food substance compliance with pH specifications of 7.5–9.0 in solution. Beverage stabilization demand from craft breweries and emulsified cheese processors sustains the largest volume base, though direct-to-brewery distribution platforms are compressing traditional chemical distributor margins.
- Industrial Grade:Technical specifications for concrete retarders and water treatment phosphate replacement. REACH authorization requirements in the Netherlands and Belgium are tightening substance volume tracking obligations for downstream users.
- Laboratory Grade:Research and analytical applications with less stringent certification than pharmaceutical tiers. Academic procurement and reagent blending operations in Switzerland and Japan absorb modest volumes with spot-market purchasing patterns.
Food grade sits at the top of the volume ranking, with pharmaceutical grade climbing the fastest as biologic stabilization demand tightens supply-demand balance.
End Use Industry:
Customer concentration varies dramatically by application, with medical device manufacturers consolidating procurement while food blenders fragment across thousands of regional accounts.
- Pharmaceuticals:Monoclonal antibody and mRNA vaccine formulation drives buffer salt procurement expansion. The Hyderabad-Visakhapatnam corridor is localizing excipient sourcing to reduce import dependency, creating dedicated demand pools for CDSCO-compliant suppliers.
- Food & Beverage:Emulsified cheese processing and beverage stabilization sustain baseline volume. Craft brewing bypasses traditional distributors through specialty ingredient platforms.
- Cleaning Agents:Detergent and industrial cleaning formulations are decoupling from petroleum-derived chelating agents. The EU F-Gas Regulation accelerates demand for non-halogenated chemical intermediates in metal chelation applications.
- Cosmetics:Personal care preservation and pH buffering for skincare formulations. This segment absorbs technical-grade material with lower certification burdens than pharmaceutical or food applications.
Food and beverage anchors absolute volume, with pharmaceuticals gaining share fastest as cell therapy buffer applications open premium pricing tiers beyond traditional grades.
Packaging Type:
Handling infrastructure requirements scale with volume and hygroscopic sensitivity, elevating capital intensity for climate-controlled warehousing investments.
- Bulk Packaging:Tanker and silo deliveries for large-scale food processors and pharmaceutical manufacturers with captive pneumatic transfer systems. German and Swiss fermentation-based producers favor this format for backward-integrated supply chains.
- Drums:Standard 200-liter steel or fiber containers for mid-volume pharmaceutical and cleaning compound blenders. ECHA's updated safety data sheet formats extend compliance documentation burdens to this packaging tier.
- Bags:25-kilogram multiwall paper sacks for food grade distribution. Hygroscopic powder properties necessitate immediate consumption or climate-controlled storage.
- Cartons:Smallest unit format for laboratory and specialty cosmetic applications. Higher per-kilogram packaging costs are offset by reduced waste for intermittent users.
Bulk packaging dominates tonnage movement, with drum formats expanding most quickly as medium-scale pharmaceutical manufacturers consolidate supplier bases.
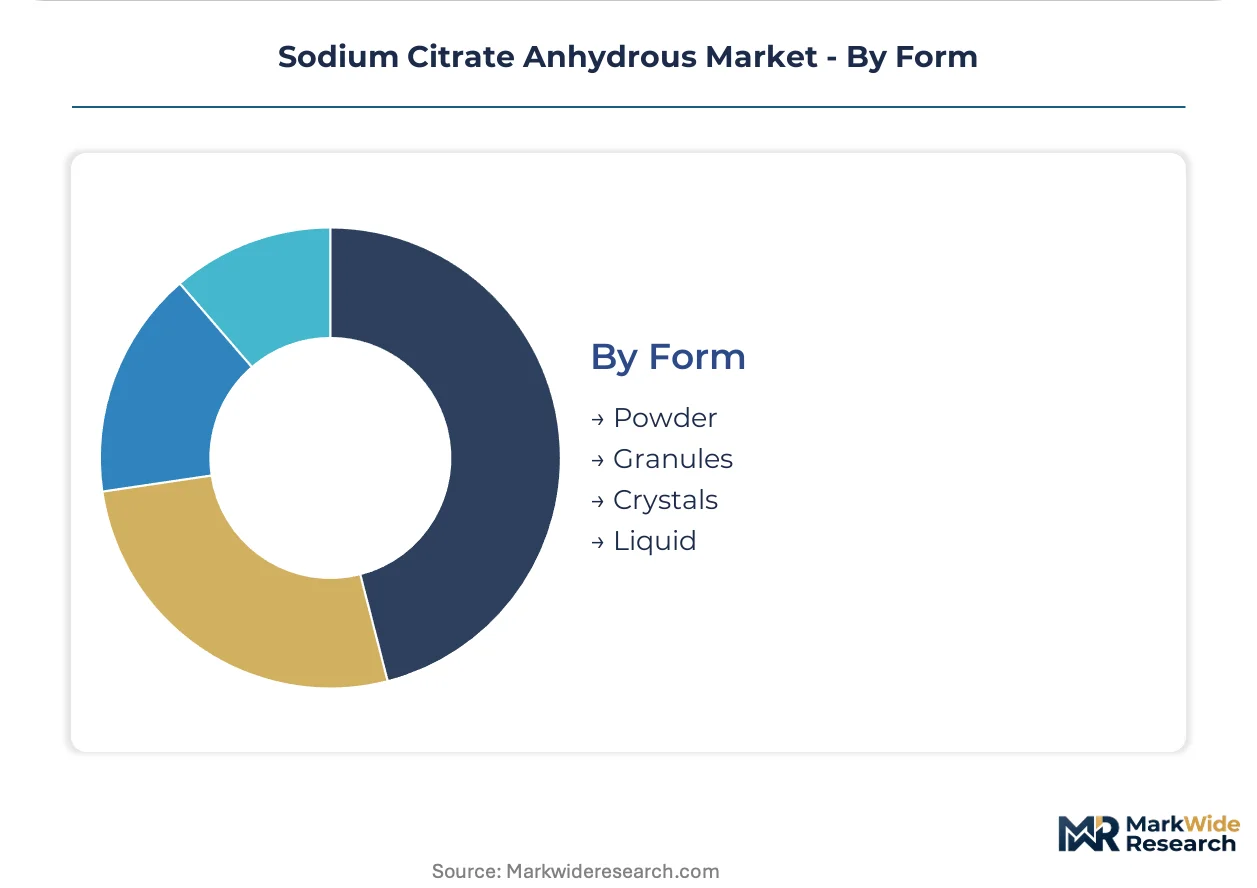
Form:
Particle morphology determines dissolution kinetics and downstream processing compatibility, with crystallization technology investments tightening size distribution specifications.
- Powder:Fine-milled anhydrous material with specified mesh ranges for rapid dissolution in beverage and buffer applications. Continuous crystallization and inline drying technologies are displacing batch processing to tighten particle size distribution.
- Crystals:Defined geometric forms for pharmaceutical tableting and controlled-release formulations. Membrane filtration coupled with simulated moving bed chromatography automates impurity removal for dialysis buffer manufacturers.
- Granules:Intermediate particle size for industrial concrete retarder and water treatment applications where dust generation must be minimized.
- Liquid:Pre-dissolved solutions for direct injection into manufacturing processes. This format eliminates handling of hygroscopic solids but concentrates freight costs and reduces shelf stability.
Powder commands the largest volume position, with crystal forms ascending fastest as cell therapy buffer protocols demand precise dissolution kinetics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hyderabad-Visakhapatnam pharmaceutical corridor anchors regional demand concentration, with active ingredient manufacturers localizing excipient sourcing to reduce import dependency. German biologic drug producers are expanding buffer salt procurement for monoclonal antibody stabilization. Swiss fermentation infrastructure sustains pharmaceutical-grade output with molasses feedstock integration.
United States
Massachusetts and California blood collection tube manufacturers lock three-year offtake agreements to insulate against fermentation feedstock volatility. FDA 21 CFR regulations for direct food substances and USP monograph standards govern pharmaceutical-grade market access. Anticoagulant tube production clusters near hospital network distribution hubs in these states.
Germany
Pharmaceutical manufacturers in Bavaria and North Rhine-Westphalia are expanding buffer salt procurement for mRNA vaccine formulation. The European Union's F-Gas Regulation accelerates demand for non-halogenated chemical intermediates in industrial cooling systems. German dialysis buffer producers adopt membrane filtration and simulated moving bed chromatography to reduce endotoxin variability.
India
CDSCO and BIS certification requirements for excipient imports are tightening quality documentation for Chinese and Southeast Asian suppliers. The country's alignment of excipient master file requirements with ICH Q3D guidelines reduces registration friction for multi-certified suppliers. Active pharmaceutical ingredient manufacturing around Hyderabad and Visakhapatnam is localizing excipient sourcing to reduce import dependency.
Switzerland
Jungbunzlauer Suisse AG leverages Swiss fermentation infrastructure to sustain pharmaceutical-grade output with backward integration into molasses feedstock. Swissmedic certification requirements shape specifications for injectable and dialysis applications. Dialysis buffer manufacturers in Basel and Zurich regions adopt automated quality assurance systems that shrink batch release windows from days to hours.
Japan
FUSO CHEMICAL CO., LTD. dominates technical-grade distribution across food preservative and dialysis buffer supply chains. METI standards and PMDA regulations govern pharmaceutical-grade market access. Japanese technical-grade demand concentrates in industrial cleaning formulations decoupling from petroleum-derived chelating agents.
Sodium Citrate Anhydrous Market Competitive Landscape
Global majors compete with regional champions across certification tiers and feedstock integration depth. The supplier base stratifies sharply around USP, EP, and JP monograph capabilities, with pharmaceutical-grade certification compressing margins for multi-jurisdictional manufacturers. Three archetypes dominate: fermentation-based integrated producers with captive molasses supply, corn-derived bioprocessors competing on cost, and technical-grade distributors occupying regional preservative and buffer niches. Capacity expansion and backward integration into feedstock represent the dominant competitive moves.
Within the fermentation-integrated tier, Jungbunzlauer Suisse AG exemplifies Swiss-based pharmaceutical-grade specialization with molasses feedstock control. Cargill, Incorporated anchors North American supply through corn-derived citric acid streams that compete on cost with Asian fermentation routes. FUSO CHEMICAL CO., LTD. occupies a position in Japanese technical-grade distribution across food preservative and dialysis buffer supply chains.
| Leading Market Players |
|---|
| Jungbunzlauer Suisse AG |
| Cargill, Incorporated |
| ADM |
| Pan Chem Corporation |
| ATPGroup |
| Tate & Lyle PLC |
| COFCO |
| Citrique Belge N.V. |
| FUSO CHEMICAL CO., LTD. |
| Others |
Value Network & Pricing Analysis
Molasses feedstock costs originating from Brazilian sugarcane harvest cycles transmit directly through fermentation-based citric acid production into pharmaceutical-grade sodium citrate pricing tiers, with contract structures absorbing volatility differently across buyer archetypes.
Pricing Analysis
Input-cost pass-through from molasses and corn-derived feedstocks drives contract-based long-term offtake agreements as the dominant pricing model, particularly among dialysis buffer manufacturers and blood collection tube producers seeking insulation from Brazilian harvest volatility. Price differentiation rests on USP/EP certification grade and volume scale, with pharmaceutical-grade material commanding substantial premiums over technical grades. Cost compression in food-grade segments is intensifying because direct-to-brewery distribution platforms bypass traditional chemical distributors. Craft brewing procurement teams exhibit highest price sensitivity, while cell therapy buffer manufacturers show least sensitivity due to low-endotoxin specification requirements.
Supply Chain Analysis
Reverse-logistics flows for pharmaceutical-grade material center on climate-controlled warehousing returns and batch rejection protocols where hygroscopic degradation triggers replacement cycles. Geographic supply concentrates in China, Germany, and Switzerland, with technical-grade production clustering in Shandong and Jiangsu provinces while pharmaceutical-grade output anchors in Swiss and German fermentation facilities. Raw material dependencies include Brazilian sugarcane molasses, North American corn streams, and sodium carbonate from chlor-alkali operations. Single-source vulnerability from Chinese technical-grade concentration exposes buyers to disruption risks. Distribution runs through specialty chemical distributors for industrial grades and direct manufacturer relationships for pharmaceutical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Indian CDSCO registration requirements tightening for Chinese suppliers and German pharmaceutical manufacturers expanding buffer procurement, creating cost and compliance differentials across the Hyderabad-Visakhapatnam corridor versus European sourcing.
For Market Incumbents: To counter fermentation feedstock volatility and margin compression from multi-jurisdictional certification requirements, incumbents should deepen backward integration into captive molasses supply chains and expand climate-controlled warehousing capacity in Basel and Zurich regions to secure Swissmedic-certified distribution advantages. For New Entrants and Emerging Players: Mid-scale cell therapy buffer manufacturers represent an underserved buyer archetype with premium pricing tolerance and limited incumbent penetration. New entrants should prioritize CDSCO-compliant production capacity near the Hyderabad-Visakhapatnam corridor, leveraging India's ICH Q3D alignment to reduce registration friction against established USP/EP-certified suppliers. For Investors and Strategic Acquirers: Consolidation pressure builds where pharmacopoeial divergence forces redundant testing protocols and extends batch release timelines for multi-certified manufacturers. Long-term viability favors acquisition targets with integrated fermentation infrastructure and existing USP/EP dual certifications. Practitioners should monitor ECHA REACH authorization updates and CDSCO master file requirement harmonization progress as inflection indicators for regulatory-driven consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molasses Feedstock | Jungbunzlauer Suisse AG secures pharmaceutical-grade margin stability against Brazilian harvest volatility. |
| CDSCO-Compliant Capacity Expansion | Hyderabad-Visakhapatnam corridor localization reduces import dependency for active pharmaceutical ingredient manufacturers. |
| Continuous Crystallization Technology Deployment | Membrane filtration and simulated moving bed chromatography automate endotoxin removal for dialysis buffer producers. |
| Long-Term Supply Agreement Structuring | Massachusetts and California blood collection tube manufacturers lock three-year offtake terms against feedstock price swings. |
| Climate-Controlled Warehousing Investment | Hygroscopic powder properties necessitate pneumatic transfer systems for pharmaceutical-grade material integrity. |
Research Methodology
Multiple input streams — regulatory filing analysis, customs and trade flow databases, fermentation industry cost structures — were reconciled through bottom-up and top-down triangulation. Primary interviews with pharmaceutical procurement directors, dialysis buffer manufacturing managers, citric acid plant operations heads, and CDSCO regulatory consultants were cross-validated against secondary sources including ECHA substance volume tracking, FDA 21 CFR direct food substance registers, USP monograph documentation, and Indian DGFT excipient import records.
Historical capacity utilization patterns were cross-referenced against panel input from fermentation facility operators to construct projection frameworks across the analysis window. Segmentation dimensions modeled include grade tier, end-use industry, packaging format, and regional production hub. CAGRs were derived through iterative convergence of demand-side pharmaceutical buffer expansion rates and supply-side feedstock cost trajectories. Forecast inputs incorporated EU F-Gas Regulation phasedown timelines and Indian PLI scheme localization incentives.
Underlying measurement precision varies by segment; pharmaceutical-grade volume estimates carry tighter precision than technical-grade industrial applications due to concentrated manufacturer disclosure. Forecasts reflect documented assumptions about molasses-corn feedstock price parity and pharmacopoeial harmonization progress. Practitioners should monitor Brazilian sugarcane harvest reports, ECHA REACH authorization list updates, and CDSCO excipient master file processing timelines for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Antiscalants/Scale Inhibitors Market
Additives
Tackifier Market
Additives
Caprylyl Glycol Market
Additives
Sodium Diacetate Market
Additives
Nucleotide Premix Market
Additives
Lecithin and Phospholipids Market
Additives
Crosslinking Agents Market
Additives
Combustion Clean-Up Additives for High-Mileage Fleets Market
Additives
Inorganic Filler Market
Additives
Global Asphalt Additives Market
Additives
Fluoropolymer Additives Market
Additives
Battery Additives Market
Additives
Global Peptone Market
Additives
Antiblock Agents Market
Additives
Mycotoxin Binders Market
Additives
Caustic Sulphite Caramel Market