
 Meta Tartaric Acid Market | 2026-2036
Meta Tartaric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Meta Tartaric Acid Market Foresight
The beverage industry is pivoting toward natural acid stabilizers as winemakers and soft-drink formulators reduce synthetic additive dependence. Agrovin leverages its Mediterranean supply base to dominate natural-grade sourcing for European vintners. Shaanxi TOP Pharm Chemical Co., Ltd anchors cost-competitive synthetic production, serving Asian and export markets with scaled fermentation-derived output. Tartaros Gonzalo Castello, SL specializes in granulated formats that streamline dosing for mid-sized wineries.
Meta tartaric acid is a stereoisomeric derivative of tartaric acid, typically produced through controlled esterification or racemization processes yielding a crystalline powder with specific optical rotation properties near zero degrees. It functions primarily as a buffering agent, acidulant, and stabilizer in food systems requiring precise pH control without contributing excessive tartness. The natural product type segment leads volume due to clean-label momentum in beverage and cosmetic applications, while modified variants capture margin pools in pharmaceutical formulations demanding enhanced thermal stability. Synthetic grades sustain share in industrial food preservation where cost sensitivity outweighs origin claims, and granulated formats are accelerating as powder-handling efficiency gains priority among mid-scale manufacturers.
EFSA purity standards and REACH chemical registration requirements shape import access and formulation compliance across European food and cosmetic supply chains. FDA GRAS status and EPA chemical substance reporting obligations govern US market entry for both domestic producers and foreign suppliers. ISO 22000 and HACCP certifications increasingly function as baseline qualifiers for distributor relationships rather than differentiators. Stakeholders must monitor evolving EU Green Deal chemical sustainability criteria and assess backward integration into grape-derived feedstock streams to secure supply continuity.
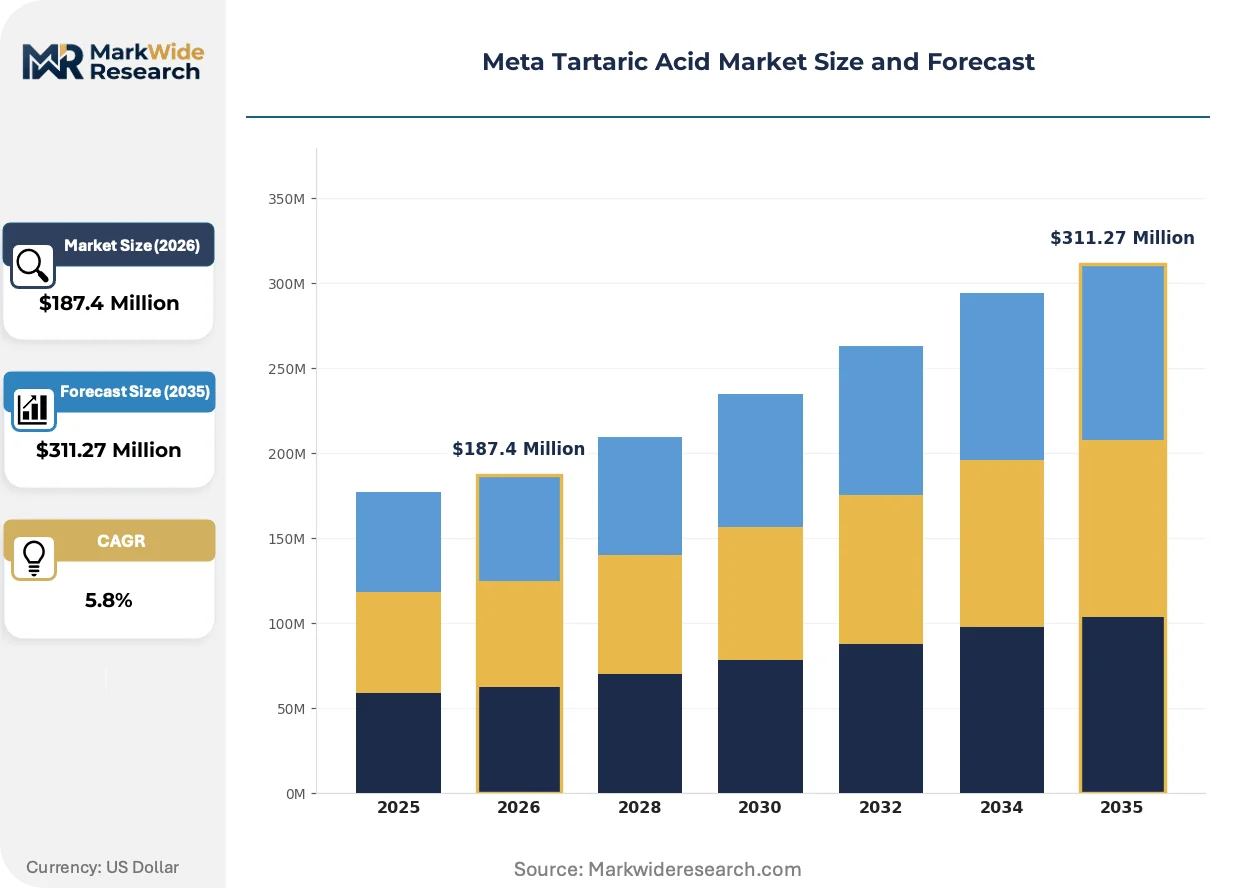
Market Dynamics
Winemakers across France, Italy, and Spain are accelerating acidulation programs, concentrating demand for natural-grade meta tartaric acid in Mediterranean supply chains while REACH compliance tightens purity requirements for imported derivatives.
Growth Catalysts
- Clean-label acid stabilization:Beverage formulators in European wine regions are replacing synthetic additives with natural acid stabilizers to meet EFSA labeling expectations.
- REACH registration momentum:Chemical importers are securing REACH compliance for tartaric acid derivatives ahead of F-Gas Regulation phase-down deadlines, expanding qualified supplier pools.
- Granulated format adoption:Mid-sized wineries are converting from powder to granulated dosing systems, reducing handling waste and improving batch consistency.
Market Restraints
- Grape feedstock concentration:Natural-grade production depends on Mediterranean grape pomace supply, creating geographic single-point vulnerability.
- Synthetic grade price compression:Fermentation-derived synthetic meta tartaric acid from Asian producers caps premium pricing power for natural variants.
- Optical rotation precision limits:Near-zero optical rotation specifications restrict batch-to-batch blending flexibility, increasing quality control costs.
Strategic Opportunities
- Pharmaceutical thermal stability demand:Modified meta tartaric acid variants with enhanced thermal profiles are capturing formulation work for parenteral drug delivery systems.
- EU Green Deal chemical sustainability criteria:Early alignment with evolving EU Green Deal standards positions suppliers for preferred procurement status in cosmetic and food additive supply chains.
- Direct-to-winery distribution channels:Bypassing traditional chemical distributors through vineyard-integrated technical service models reduces margin leakage.
Industry Challenges
- Optical rotation calibration expertise:Polarimetry technicians with meta tartaric acid-specific experience are scarce in contract manufacturing organizations.
- ISO 22000 certification timelines:New market entrants face extended audit cycles to achieve HACCP-integrated food safety certification.
- Legacy dosing equipment incompatibility:Granulated format conversion requires capital replacement of pneumatic powder handling systems at smaller wineries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meta Tartaric Acid Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Modified, Granulated Application: Beverages, Food Preservation, Pharmaceuticals, Cosmetics End User: Beverage Industry, Food Manufacturers, Cosmetic Brands, Pharmaceutical Companies Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Shaanxi TOP Pharm Chemical Co., Ltd, Agrovin, Dal cin, Buon Vino Manufacturing Inc., CLEAN srl, Panteley Toshev Ltd., Sigma-Aldrich Inc., Redox Pty Ltd, Tartaros Gonzalo Castello, SL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meta Tartaric Acid Market Shifts & Advancements
Automation of quality control workflows and tightening chemical registration requirements are compressing supplier qualification timelines while reshaping how buyers evaluate acid stabilizer sourcing.
Inline polarimetry systems integrated with batch processing lines are automating optical rotation verification, eliminating manual sampling delays. Large-scale fermentation facilities in Asian chemical parks are deploying these systems to meet European import documentation requirements. This automation is compressing the gap between synthetic and natural-grade quality assurance costs, eroding the traditional premium justification for natural sourcing.
EFSA is revising purity specifications for food-grade tartaric acid derivatives, mandating tighter heavy metal thresholds and expanded contaminant screening panels. Importers are restructuring supply agreements to require third-party testing at origin rather than destination ports. French and Italian wine additive distributors are absorbing these compliance costs into long-term contracts to lock in qualified supply.
Winery procurement teams are consolidating acid stabilizer purchasing through vineyard management software platforms that integrate inventory tracking with vintage scheduling. Mid-sized cooperatives in Spain are abandoning spot-market purchasing for annual framework agreements with technical service commitments. This channel consolidation favors suppliers with embedded enology expertise over commodity chemical traders.
Meta Tartaric Acid Market Segmentation
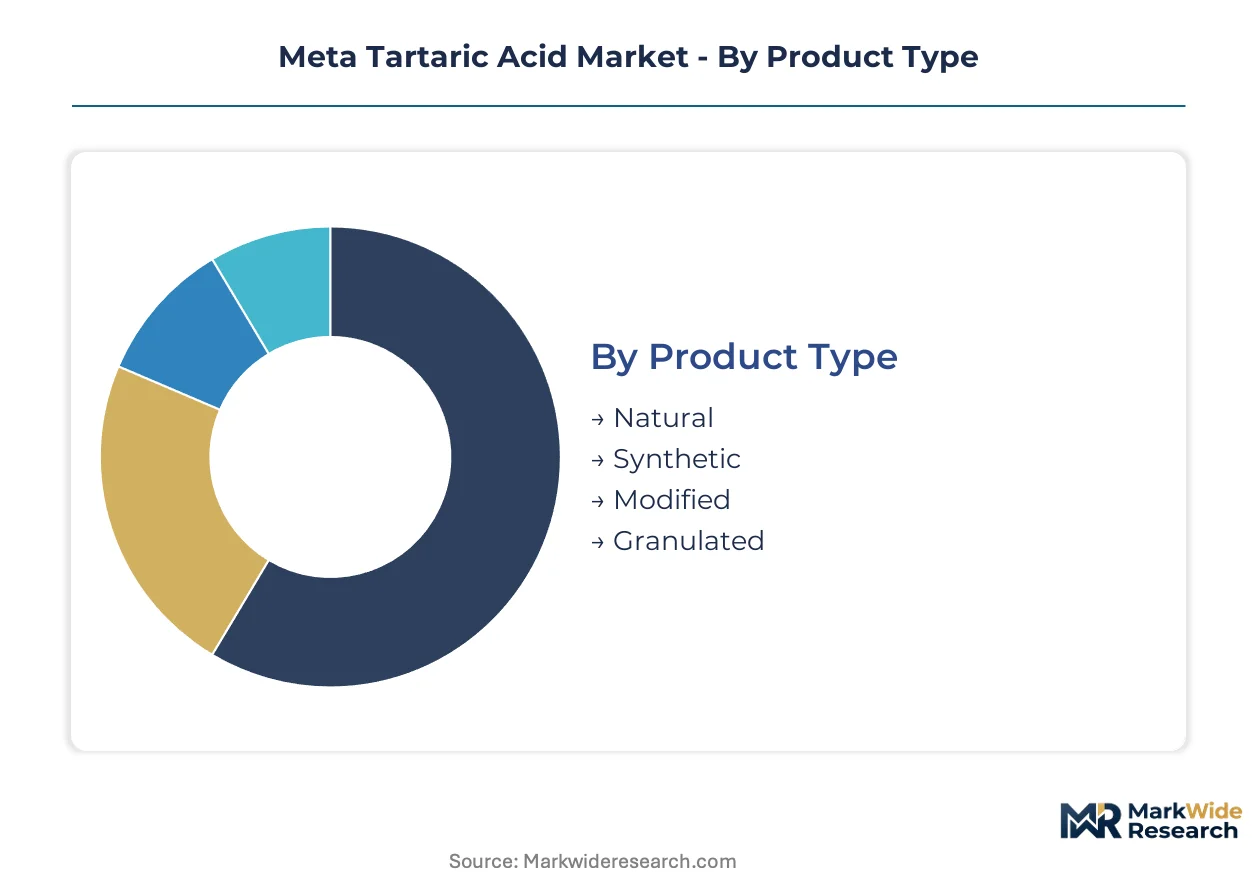
Meta tartaric acid segmentation reflects divergent supply chain economics between grape-derived natural grades and fermentation-based synthetic alternatives. Each dimension—product chemistry, application requirements, and channel structure—creates distinct margin pools and qualification barriers for suppliers.
Product Type:
Natural-grade variants command volume leadership while synthetic production anchors cost-competitive supply tiers across Asian and European markets.
- Natural:Extracted from Mediterranean grape pomace through controlled crystallization processes yielding near-zero optical rotation specifications. French, Italian, and Spanish winemakers concentrate procurement through vineyard-integrated distributors to secure EFSA-compliant acidulation stocks. Clean-label beverage formulations drive preference despite feedstock geographic concentration.
- Synthetic:Fermentation-derived from maleic anhydride or glucose substrates in scaled Asian chemical parks. Cost-sensitive industrial food preservation applications sustain demand while REACH registration requirements compress import documentation gaps. Shaanxi TOP Pharm Chemical Co. anchors regional production capacity.
- Modified:Esterified variants with enhanced thermal stability profiles for pharmaceutical parenteral delivery systems.
- Granulated:Densified crystalline formats reducing pneumatic handling waste at mid-scale winery dosing operations.
Today's leader: Natural. Tomorrow's challenger: Modified.
Application:
Beverage acidulation generates the dominant revenue pool while pharmaceutical thermal stability requirements create premium formulation opportunities.
- Beverages:Wine acidulation programs across Mediterranean cooperatives require precise pH buffering without excessive tartness contribution. Spain's mid-sized wineries are converting framework agreements from spot purchasing to annual technical service contracts. EFSA labeling expectations accelerate synthetic-to-natural substitution timelines.
- Food Preservation:Industrial bakeries and prepared food manufacturers deploy synthetic grades where cost sensitivity outweighs origin claims. Asian export markets sustain scaled fermentation output despite REACH purity threshold tightening.
- Pharmaceuticals:Modified variants with enhanced thermal profiles capture parenteral drug delivery formulation work.
- Cosmetics:Natural-grade buffering agents in clean-label skincare formulations align with EU Green Deal chemical sustainability screening.
Beverages anchor current procurement volume. Pharmaceuticals represent the steepest expansion trajectory.
End User:
Procurement sophistication varies sharply between enology-trained vineyard managers and commodity chemical purchasing at industrial food plants.
- Beverage Industry:Winemakers in France, Italy, and Spain integrate acid stabilizer purchasing through vineyard management software platforms with vintage scheduling. Technical service expectations exceed standard chemical distribution capabilities.
- Food Manufacturers:Industrial bakeries and preservation facilities prioritize synthetic grade cost efficiency over optical rotation precision.
- Cosmetic Brands:Clean-label formulators source natural-grade buffering through specialty chemical distributors with ISO 22000 certification.
- Pharmaceutical Companies:Parenteral drug developers specify modified thermal stability grades with batch documentation exceeding food-grade standards.
Beverage industry procurement consolidation is accelerating. Pharmaceutical qualification timelines extend supplier lock-in effects.
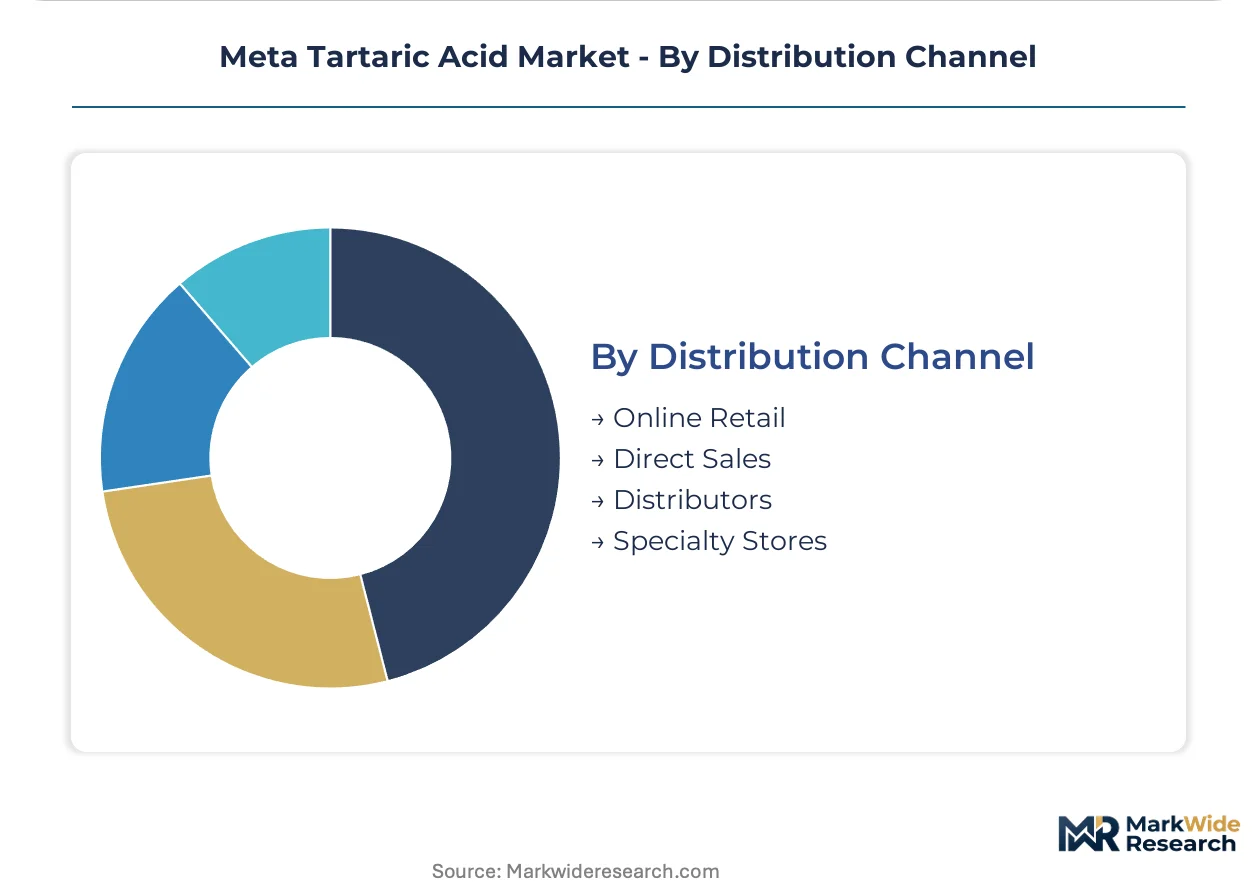
Distribution Channel:
Channel selection reflects customer scale and technical service intensity requirements across European wine regions and Asian manufacturing clusters.
- Direct Sales:Large cooperative wineries in Spain and Italy bypass distributors through embedded enology technical service models. Margin capture and batch customization justify relationship management overhead.
- Distributors:French wine additive specialists absorb EFSA compliance testing costs into long-term supply agreements. Regional chemical distributors serve mid-scale food manufacturers with standardized synthetic grades.
- Online Retail:Small-scale cosmetic formulators and specialty food producers source certified natural grades through B2B platforms with documentation transparency.
- Specialty Stores:Laboratory supply channels serve pharmaceutical R&D procurement with modified grade samples and technical data packages.
Direct sales dominate premium natural-grade volume. Online retail is gaining share fastest among small-batch cosmetic and specialty food entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as REACH compliance costs in Europe widen cost-of-compliance gaps with Asian fermentation hubs. Suppliers are restructuring supply chains to balance EFSA purity requirements against feedstock access and qualified labor pools.
France
Bordeaux and Champagne cooperatives anchor Mediterranean acidulation demand as winemakers convert to natural-grade stabilizers. EFSA labeling expectations and REACH registration deadlines compress supplier qualification timelines. The Languedoc-Roussillon cluster concentrates vineyard-integrated technical service models for direct acid stabilizer procurement.
Italy
Piedmont and Tuscany vintners drive granulated format adoption through cooperative purchasing frameworks. ANSM enforces pharmaceutical-grade purity standards that spill over into food additive documentation requirements. The Veneto region hosts specialty chemical distributors absorbing third-party testing costs into long-term supply agreements.
Spain
Rioja and Ribera del Duero mid-sized wineries are abandoning spot-market purchasing for annual technical service contracts. F-Gas Regulation phase-down deadlines accelerate REACH compliance investments among importers. Catalonia's wine additive distributors are consolidating procurement through vineyard management software platforms.
China
Shaanxi Province fermentation facilities supply cost-competitive synthetic grades to Asian industrial food preservation markets. SAMR food additive standards and GB quality specifications govern domestic circulation while REACH documentation supports European export channels. Yangtze River Delta chemical parks deploy inline polarimetry systems to compress quality assurance cost gaps with natural-grade producers.
United States
California Central Valley wineries represent emerging demand for clean-label acid stabilizers in premium wine segments. FDA GRAS status and EPA chemical substance reporting obligations structure market entry for both domestic and imported suppliers. The Pacific Northwest craft beverage cluster is testing granulated format compatibility with legacy dosing equipment.
Meta Tartaric Acid Market Competitive Landscape
Capacity expansion dominates the current landscape as fermentation facilities in Asian chemical parks scale output to capture REACH-compliant export demand. The vendor base organizes around three strategic archetypes: Mediterranean grape-derived specialists with vineyard-integrated distribution, Asian fermentation-scale producers serving cost-sensitive industrial tiers, and granulated format innovators targeting mid-sized winery efficiency gains. M&A activity concentrates among French and Italian distributors consolidating enology technical service capabilities, while backward integration into grape pomace feedstock streams secures supply continuity for natural-grade producers.
Among Asian fermentation-scale producers, Shaanxi TOP Pharm Chemical Co., Ltd anchors cost-competitive synthetic output for export markets. Agrovin occupies a position within the Mediterranean specialist tier, leveraging proximity to French and Italian vineyard clusters. Tartaros Gonzalo Castello, SL exemplifies the format innovation archetype through granulated product development for winery dosing efficiency. These three company profiles map the competitive terrain without exhausting its full composition.
| Leading Market Players |
|---|
| Shaanxi TOP Pharm Chemical Co., Ltd |
| Agrovin |
| Dal cin |
| Buon Vino Manufacturing Inc. |
| CLEAN srl |
| Panteley Toshev Ltd. |
| Sigma-Aldrich Inc. |
| Redox Pty Ltd |
| Tartaros Gonzalo Castello, SL |
| Others |
Supply & Pricing Matrix
Mediterranean cooperative wineries concentrate procurement volume, anchoring contract-based long-term offtake agreements that compress spot-market pricing power for synthetic-grade suppliers. REACH compliance costs and EFSA purity documentation requirements widen the cost gap between natural-grade grape-derived stocks and Asian fermentation output.
Pricing Analysis
Distributor margins at French and Italian wine additive specialists absorb third-party testing costs into multi-year supply agreements, compressing net prices to regional chemical traders. Three-tier pricing structure across premium natural-grade, standard synthetic-grade, and economy unmodified variants reflects certification grade and optical rotation precision. Pricing pressure stems from Shaanxi fermentation facilities scaling REACH-compliant export capacity. Industrial food manufacturers exhibit highest price sensitivity; pharmaceutical formulators show lowest.
Supply Chain Analysis
Polarimetry technician shortages in Yangtze River Delta chemical parks constrain quality control throughput at synthetic-grade fermentation facilities. Supply concentrates in China, France, and Italy, with raw material dependencies on Mediterranean grape pomace, maleic anhydride feedstocks, and glucose substrates. Single-source vulnerability in grape-derived natural-grade production creates geographic concentration risk. Distribution runs through vineyard-integrated technical service models for premium tiers and regional chemical distributors for industrial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
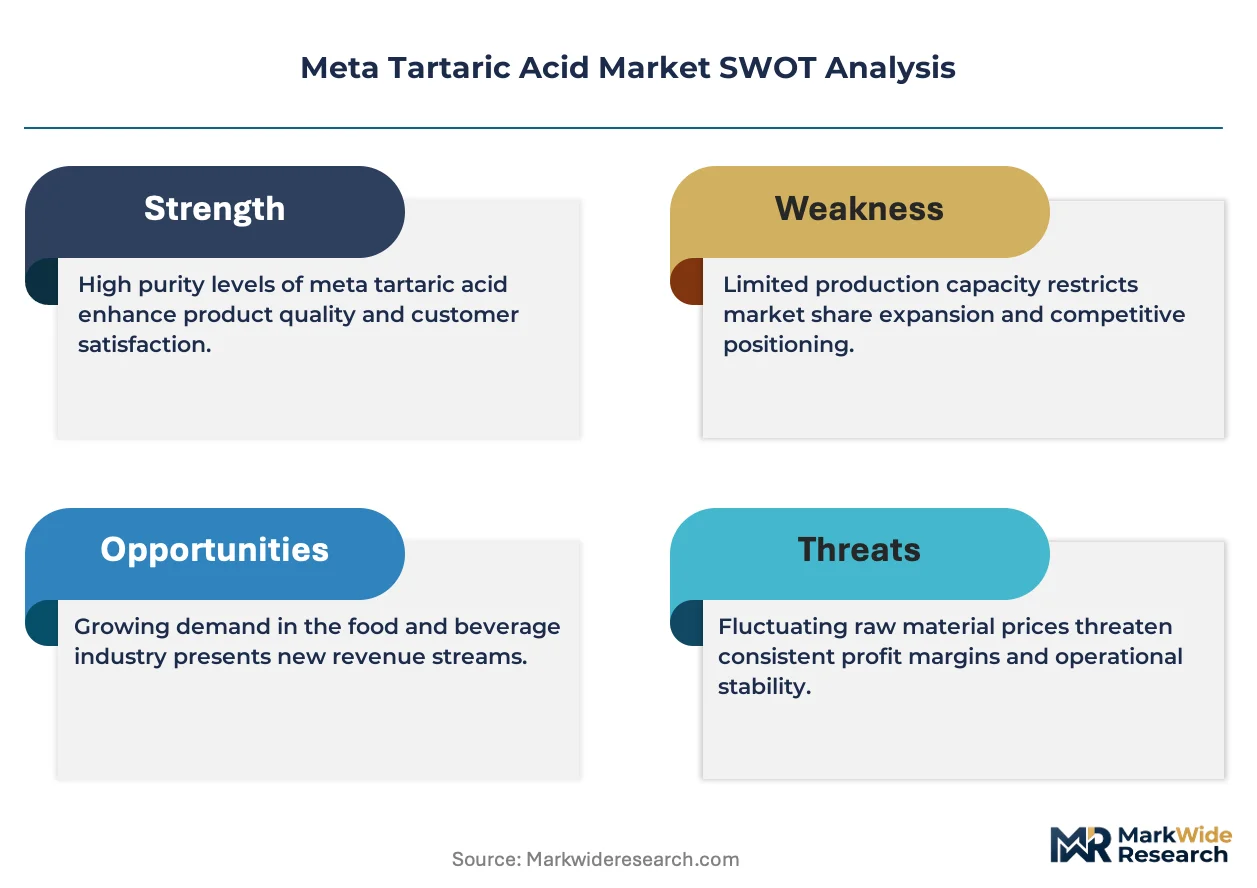
The meta tartaric acid market functions as a stable compounder, with beverage acidulation demand from Mediterranean wine regions providing steady volume foundations across economic cycles.
For Market Incumbents: Extend backward integration into grape pomace feedstock streams to secure natural-grade supply continuity against Asian synthetic-grade price compression. Lock in multi-year technical service contracts with Spanish and Italian cooperatives before vineyard management software platforms consolidate procurement further. Prioritize ISO 22000 certification maintenance as baseline qualification rather than differentiator. For New Entrants and Emerging Players: Inline polarimetry automation systems offer a technology-first wedge to compress quality assurance cost gaps with established natural-grade producers. Target mid-sized Rioja and Ribera del Duero wineries converting legacy powder dosing equipment to granulated format compatibility. Lead with embedded enology expertise rather than commodity chemical trading. For Investors and Strategic Acquirers: Specialty chemical distributors with vineyard-integrated technical service capabilities are the most active acquirer in this space, consolidating enology expertise across French and Italian wine regions. The market supports long-term viability framing around clean-label acid stabilization trends. Watch for EFSA purity specification revisions as inflection indicator for compliance cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grape Pomace | Secures natural-grade feedstock continuity for EFSA-compliant Mediterranean supply. |
| Granulated Format Capacity Expansion | Captures mid-sized winery dosing efficiency demand in Spain and Italy. |
| REACH Registration Acceleration | Unlocks European export channels ahead of F-Gas Regulation phase-down deadlines. |
| Inline Polarimetry Deployment | Compresses quality assurance cost gaps with natural-grade producers in Asian hubs. |
| Vineyard Management Software Integration | Locks in cooperative procurement through vintage scheduling alignment. |
Research Methodology
Direct dialogue with enology technical directors, cooperative procurement managers, fermentation plant engineers, and specialty chemical distribution heads grounded qualitative assessments. Secondary validation drew from EFSA additive specifications, REACH registration databases, customs trade flows, and vineyard management software platform disclosures. Bottom-up volume triangulation across grade tiers and top-down value reconciliation anchored forecast integrity.
Segment-level projections across natural, synthetic, modified, and granulated product chemistry dimensions combined with beverage, pharmaceutical, food preservation, and cosmetic application splits. CAGRs derived from regression against acidulation program expansion rates and REACH compliance investment trajectories. Modeling incorporated grape harvest variability, optical rotation precision requirements, and distributor margin absorption patterns.
The model holds under stable EFSA purity standards and continued Mediterranean wine export demand; deviation in EU Green Deal chemical sustainability criteria or F-Gas Regulation acceleration would shift natural-grade premium justification. Forecasts reflect these base assumptions with acknowledged sensitivity to feedstock geographic concentration and Asian fermentation capacity additions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
North America Sodium Chlorate Market
Bulk Chemicals
Ethylene Dichloride Market
Bulk Chemicals
Methionine Market
Bulk Chemicals
Brazil Magnesium Phosphate Market
Bulk Chemicals
Calcium Bromide Market
Bulk Chemicals
Cobalt Acetate Crystals Market
Bulk Chemicals
Calcined Petcoke Market
Bulk Chemicals
North America Copper Sulphate Market
Bulk Chemicals
North America Potassium Formate Market
Bulk Chemicals
Magnesium Sulfate Market
Bulk Chemicals
North America Methyl Acrylate Market
Bulk Chemicals
Global Linear Alpha Olefins Market
Bulk Chemicals
Asia-Pacific Carbon Black Market
Bulk Chemicals
Global Ammonium Phosphate Market
Bulk Chemicals
Castor Wax Market
Bulk Chemicals
Barium Sulphate Market