
 Anticoagulant Rodenticides Market | 2026-2036
Anticoagulant Rodenticides Market Size, Share, and Industry Trends Forecast 2026-2036
Anticoagulant Rodenticides Market Intelligence
The capital-intensity gap between integrated manufacturers and formulation-only suppliers is collapsing as active ingredient synthesis becomes concentrated among fewer producers. BASF leverages its backward integration into bromadiolone precursors to sustain cost advantages across Latin American agricultural markets. Syngenta anchors its position through proprietary bait matrix technologies that differentiate performance in humid tropical conditions. PelGar International specializes in niche difenacoum formulations for regions with established warfarin resistance.
Anticoagulant rodenticides comprise hydroxycoumarin and indandione derivatives that inhibit vitamin K epoxide reductase, causing fatal hemorrhage in target species through interference with blood clotting factor synthesis; brodifacoum achieves lethality at concentrations below 50 ppm in formulated bait products. The product type landscape shows brodifacoum and bromadiolone commanding premium positioning due to single-feed efficacy, while warfarin persists in price-sensitive municipal contracts where multi-feed protocols remain acceptable. Application demand tilts toward urban areas and commercial establishments as integrated pest management programs in food-processing facilities mandate documented rodent control with anticoagulant rotation requirements.
EPA FIFRA re-registration reviews and ECHA REACH substance evaluations are tightening acceptable residue thresholds and restricting outdoor above-ground placements, forcing reformulation toward lower-concentration, higher-palatability matrices. The EU Biocidal Products Regulation continues to compress the approved active substance list, with bromadiolone and difenacoum facing renewed authorization scrutiny that threatens supply continuity for European pest control operators. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate where product registrations will survive and where portfolio restructuring becomes unavoidable.
Market Dynamics
EPA FIFRA re-registration requirements are compressing permissible active ingredient concentrations while mandating bait station specifications, forcing manufacturers to reformulate around palatability enhancement rather than toxicity escalation. This regulatory compression is redrawing competitive boundaries between integrated synthesis operations and formulation specialists.
Growth Catalysts
- Second-Generation Product Migration:Agricultural storage facilities across Brazil and Argentina are replacing first-generation warfarin protocols with bromadiolone and brodifacoum systems that deliver single-feed lethality, reducing labor costs in grain elevator operations.
- REACH Authorization Continuity:ECHA's phased review timeline for difenacoum and flocoumafen is creating procurement windows where European pest control operators are securing multi-year supply contracts ahead of potential substance restrictions.
- Integrated Pest Management Mandates:Food-processing facilities under FDA Food Safety Modernization Act requirements now document anticoagulant rotation schedules, institutionalizing recurring demand for multiple active ingredient categories.
Market Restraints
- Active Ingredient Supply Concentration:Synthesis of hydroxycoumarin precursors has consolidated among three Chinese manufacturers, exposing formulation specialists to input volatility and qualification delays.
- Secondary Poisoning Liability:Predator exposure to brodifacoum residues in raptor and owl populations has triggered municipal procurement bans in California and New York, restricting application in ecologically sensitive zones.
- Resistance Amplification:Warfarin-resistant rodent populations in parts of the United Kingdom and Denmark are compressing effective product lifecycles and accelerating R&D replacement costs.
Strategic Opportunities
- Humid Tropical Formulation Gaps:Bait matrix degradation in Southeast Asian palm oil plantations creates demand for moisture-resistant encapsulation technologies that maintain palatability above 85% relative humidity.
- Digital Monitoring Convergence:Integration of IoT-enabled bait station sensors with anticoagulant delivery systems allows predictive replenishment models that reduce service frequency for commercial property managers.
- Non-Target Species Mitigation:Weight-triggered bait station designs compatible with EPA risk mitigation measures open municipal contract segments previously restricted due to pet and wildlife exposure concerns.
Industry Challenges
- Toxicology Specialist Scarcity:Registration dossier preparation for EU BPR and EPA FIFRA requires expertise in ecotoxicology study design that outpaces available consultant capacity, extending approval timelines.
- Manufacturing Flexibility Constraints:Campaign production of lower-concentration, higher-volume formulations demands capital investment in blending and extrusion equipment that smaller suppliers cannot justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anticoagulant Rodenticides Market |
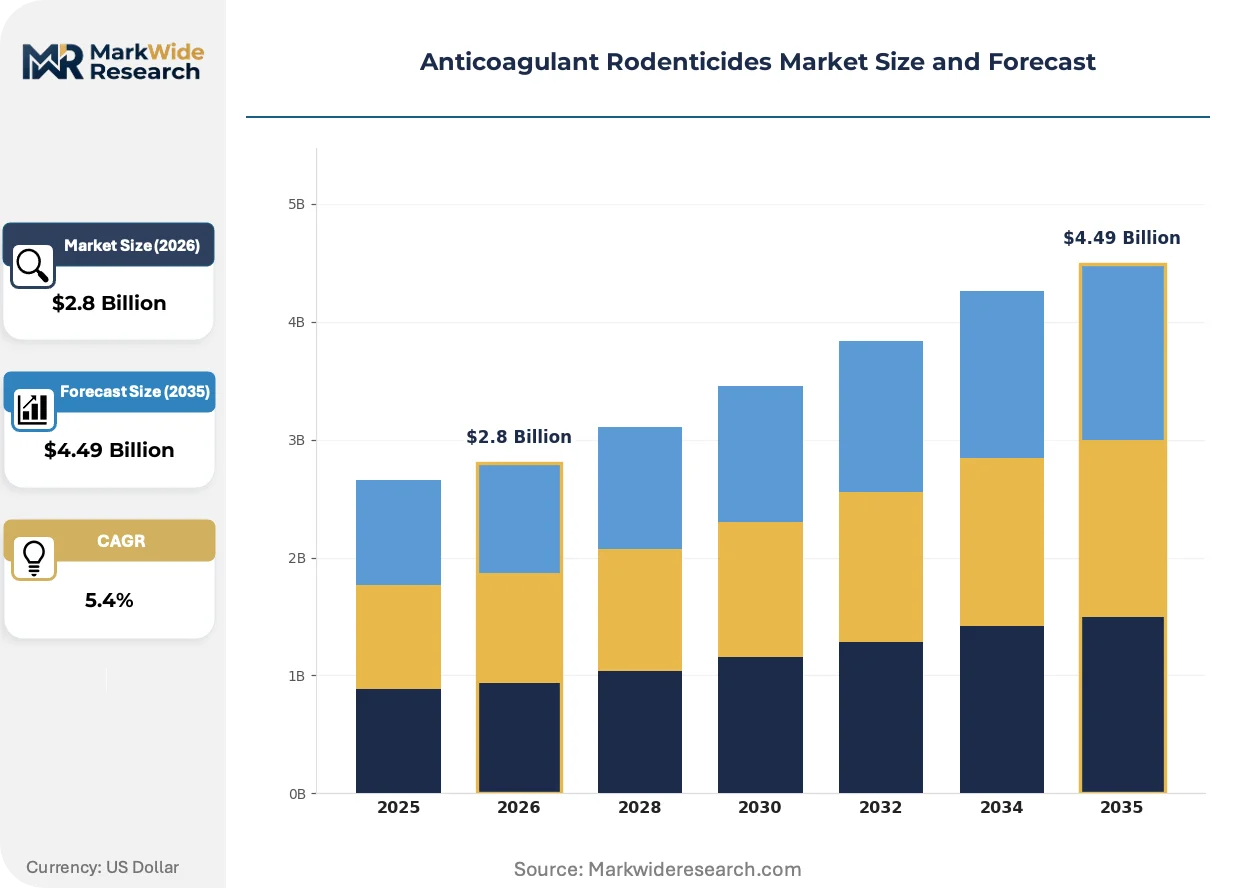
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bromadiolone, Brodifacoum, Difenacoum, Warfarin Application: Agriculture, Urban Areas, Commercial Establishments, Residential Areas End User: Pest Control Operators, Farmers, Household Consumers, Government Agencies Distribution Channel: Online Retail, Specialty Stores, Wholesale Suppliers, Supermarkets |
| Companies Covered | BASF, Bayer AG, Syngenta, PelGar International, Rentokil Initial plc, UPL, Bell Labs, NEOGEN Corporation, Liphatech, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anticoagulant Rodenticides Market Strategic Shifts & Innovations
Formulation chemistry is pivoting toward palatability engineering as regulatory ceilings on active ingredient concentration harden across multiple jurisdictions. This shift favors suppliers with captive flavor-house capabilities and granular understanding of target species feeding behavior.
Paraffin-wax matrix formulations with embedded lipid attractants are supplanting traditional grain-based baits in tropical agricultural applications. Brazilian soybean processors adopted these systems at scale during the 2023-2024 storage season. The technology is compressing market share for conventional pellet formulations that degrade under humidity stress.
EPA FIFRA re-registration reviews are mandating risk mitigation measures that include bait station specifications and distance setbacks from buildings. These requirements are elevating compliance costs for outdoor above-ground applications. Agricultural distributors in the United States are responding by shifting inventory toward professional-grade bait station bundles rather than standalone bait products.
Food safety audit protocols are unbundling rodent control documentation from general pest management contracts. Third-party certification bodies including BRCGS and SQF now require anticoagulant rotation logs with active ingredient specificity. This behavioral shift is most pronounced in North American protein processing facilities where auditor scrutiny has intensified following supply chain contamination incidents.
Anticoagulant Rodenticides Market Segmentation
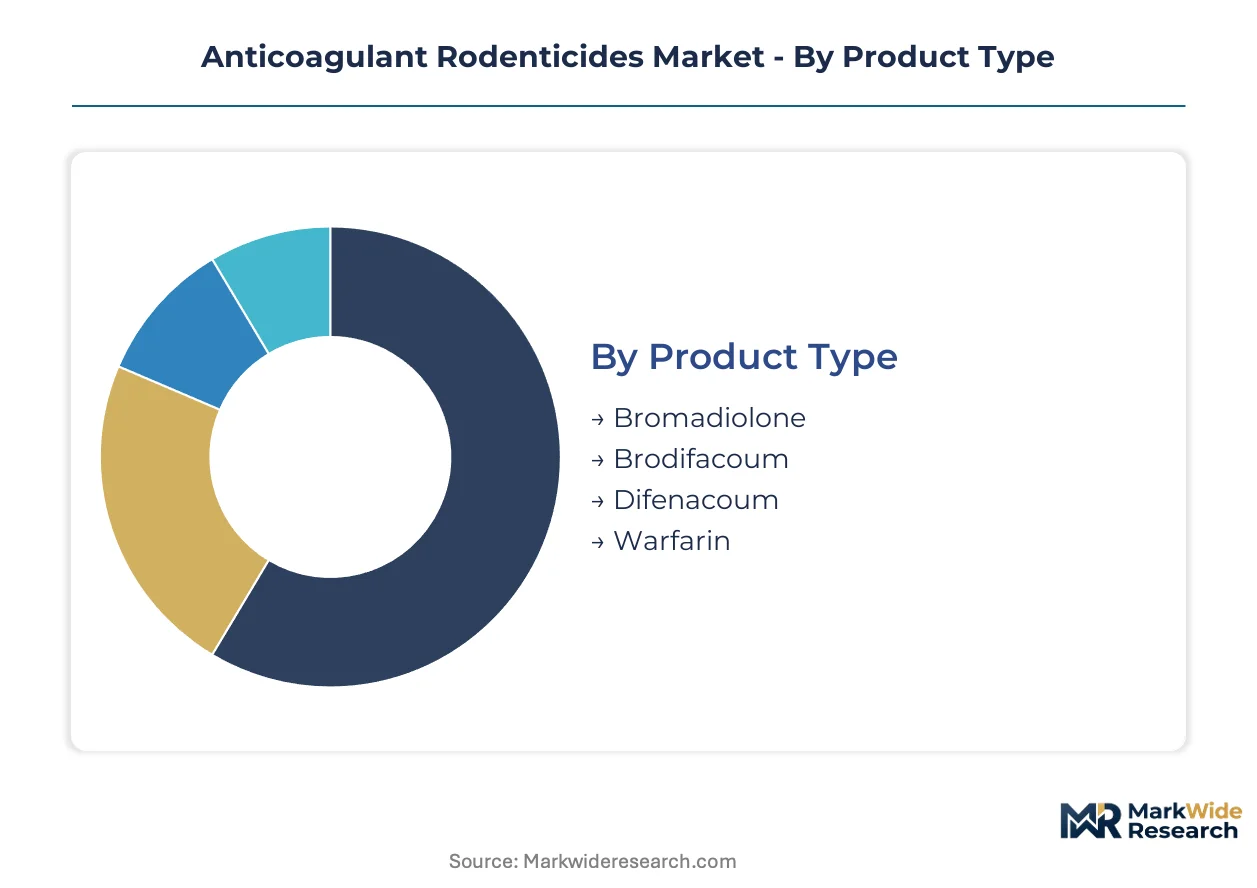
Anticoagulant rodenticides flow through distinct channel architectures that shape formulation priorities and packaging specifications. Product differentiation intensifies as regulatory ceilings on active ingredient concentration harden across EPA FIFRA and ECHA REACH jurisdictions.
Product Type:
Channel mix varies sharply by toxicity tier—professional pest control operators procure second-generation hydroxycoumarin derivatives through wholesale suppliers, while municipal contracts and residential channels favor first-generation indandione products with established handling protocols.
- Bromadiolone:Single-feed hydroxycoumarin derivative synthesized from 4-hydroxycoumarin precursors. Brazilian grain elevator operators and Argentine soybean processors are consolidating procurement around this active ingredient as labor cost reduction becomes paramount in agricultural storage facilities.
- Brodifacoum:High-potency second-generation anticoagulant achieving lethality below 50 ppm in formulated baits. Urban commercial property managers in California and New York face municipal procurement restrictions due to secondary poisoning liability in raptor populations, compressing addressable market scope.
- Difenacoum:Specialized formulation for warfarin-resistant rodent populations in the United Kingdom and Denmark.
- Warfarin:First-generation compound persisting in price-sensitive municipal contracts where multi-feed protocols remain operationally acceptable.
Brodifacoum dominates installed base in premium commercial applications. Bromadiolone is where expansion concentrates as agricultural storage infrastructure scales across Latin America.
Application:
Cost tier stratification separates professional-grade bait station bundles from economy pellet formulations, with humidity-resistant paraffin-wax matrices commanding 40-60% price premiums in tropical deployments.
- Agriculture:Grain elevator and oilseed processing facilities under FDA Food Safety Modernization Act documentation mandates. Brazilian soybean processors adopted paraffin-wax matrix formulations at scale during recent storage seasons, displacing conventional grain-based pellets that degrade above 85% relative humidity.
- Urban Areas:Municipal rodent control programs with EPA-mandated bait station specifications and setback requirements from buildings. Procurement is shifting toward professional-grade bait station bundles rather than standalone bait products as compliance costs escalate.
- Commercial Establishments:Food-processing facilities requiring anticoagulant rotation logs with active ingredient specificity under BRCGS and SQF third-party certification protocols.
- Residential Areas:Household consumers accessing lower-concentration formulations through retail channels with simplified handling instructions.
Agriculture commands the highest volume throughput. Commercial establishments represent the steepest expansion trajectory as food safety audit protocols unbundle rodent control documentation from general pest management contracts.
End User:
Customer type determines formulation concentration access and service frequency requirements, with professional operators maintaining rotation schedules that institutionalize recurring demand across multiple active ingredient categories.
- Pest Control Operators:Professional service providers documenting anticoagulant rotation schedules under integrated pest management protocols. ECHA's phased review timeline for difenacoum and flocoumafen is creating procurement windows where European operators secure multi-year supply contracts ahead of potential substance restrictions.
- Farmers:Agricultural producers investing in rodent control infrastructure for on-farm grain storage. Brazilian and Argentine soybean and corn operations are replacing first-generation warfarin protocols with single-feed systems that reduce labor costs.
- Household Consumers:Residential purchasers accessing pre-formulated bait products through retail channels with EPA-compliant packaging and handling warnings.
- Government Agencies:Municipal procurement bodies imposing secondary poisoning liability restrictions that exclude brodifacoum from ecologically sensitive zones in California and New York.
Pest control operators dominate service revenue. Farmers are where volume expansion concentrates as agricultural storage facility investment accelerates.
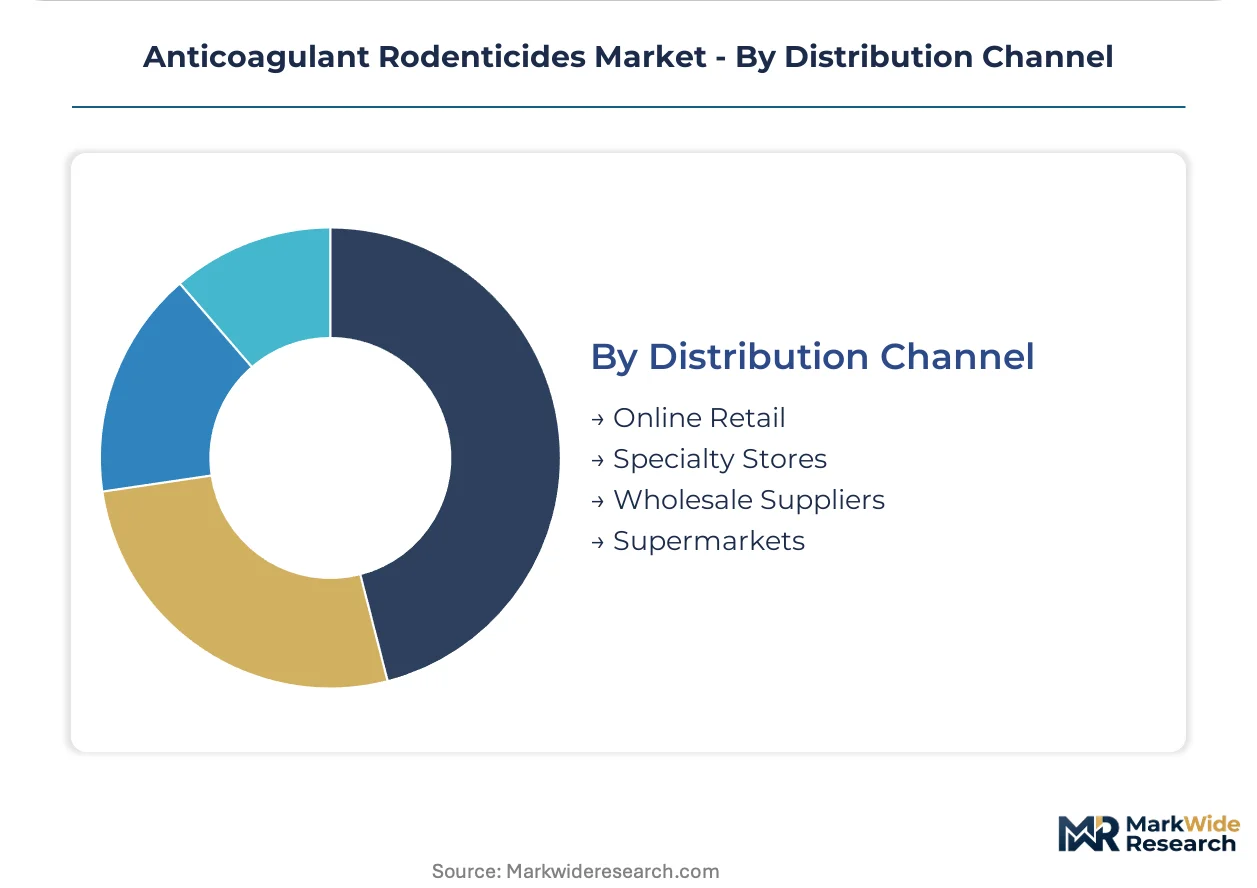
Distribution Channel:
Supply concentration among three Chinese manufacturers of hydroxycoumarin precursors exposes channel intermediaries to input volatility and qualification delays, favoring integrated suppliers with captive synthesis capabilities.
- Online Retail:E-commerce platforms serving household consumers with restricted-access formulations requiring compliance with shipping regulations for hazardous substances.
- Specialty Stores:Agricultural supply outlets and pest control equipment distributors with technical consultation capabilities for professional end users.
- Wholesale Suppliers:Primary procurement channel for pest control operators and government agencies requiring volume pricing and multi-year contract structures.
- Supermarkets:Mass retail access point for residential consumers with lower-concentration, consumer-grade packaging formats.
Wholesale suppliers dominate commercial and agricultural volume. Online retail is where household consumer access is expanding fastest as e-commerce penetration deepens in residential pest control categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian grain elevators consume bromadiolone at intensities unmatched elsewhere, while European operators stockpile difenacoum ahead of regulatory discontinuity risks. This consumption-mix differential separates procurement behavior across jurisdictions.
United States
EPA FIFRA re-registration mandates are compressing permissible brodifacoum concentrations in outdoor applications. California and New York municipalities have enacted procurement bans targeting secondary poisoning liability in raptor populations. Chicago and New York City operate the largest municipal rodent control programs, shifting inventory toward professional-grade bait station bundles.
Brazil
Soybean and corn storage facilities in Mato Grosso and Paraná are replacing warfarin protocols with single-feed bromadiolone systems. ANVISA alignment with international residue standards is accelerating product re-registration timelines. São Paulo-based distributors dominate procurement channels for agricultural pest management programs.
Germany
ECHA REACH substance evaluations are tightening acceptable residue thresholds for anticoagulant formulations. The country's food-processing sector under EFSA oversight mandates documented rotation schedules with active ingredient specificity. Bavarian protein processing facilities represent the steepest compliance-driven demand concentration.
China
Synthesis of hydroxycoumarin precursors has consolidated among three domestic manufacturers, exposing global formulation specialists to input volatility. MEE environmental compliance requirements are reshaping active ingredient production economics. Zhejiang and Jiangsu provinces host the principal manufacturing clusters for export-oriented precursor supply.
United Kingdom
Warfarin-resistant rodent populations in urban centers are compressing effective product lifecycles and accelerating procurement of difenacoum alternatives. HSE stewardship schemes restrict outdoor above-ground placements. London's dense commercial property stock generates concentrated demand for professional pest control operator services.
Anticoagulant Rodenticides Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with backward integration into bromadiolone precursors separating cost-competitive suppliers from formulation-dependent operators. The capital-intensity gap between these tiers is collapsing as active ingredient synthesis concentrates among fewer producers. Three strategic archetypes dominate: integrated chemical conglomerates with captive precursor supply, formulation specialists leveraging proprietary bait matrix technologies, and service-integrated distributors bundling anticoagulants with monitoring hardware. Competitive moves center on regulatory pre-positioning ahead of EPA and ECHA authorization timelines, plus geographic expansion into Brazilian agricultural storage markets.
Among integrated chemical conglomerates, BASF leverages backward integration into bromadiolone precursors to sustain cost advantages across Latin American agricultural markets. Syngenta anchors its position through proprietary bait matrix technologies that differentiate performance in humid tropical conditions. PelGar International occupies a specialist tier position focused on niche difenacoum formulations for regions with established warfarin resistance. These three companies exemplify how divergent integration strategies map onto distinct geographic and application segment priorities.
| Leading Market Players |
|---|
| BASF |
| Bayer AG |
| Syngenta |
| PelGar International |
| Rentokil Initial plc |
| UPL |
| Bell Labs |
| NEOGEN Corporation |
| Liphatech, Inc. |
| Others |
Cost & Logistics Intelligence
EPA FIFRA re-registration requirements and ECHA REACH substance evaluations gate both supplier qualification timelines and price differentiation between professional-grade and economy formulations simultaneously. Regulatory compression on active ingredient concentrations forces manufacturers toward palatability engineering investments that separate premium suppliers from commodity competitors.
Pricing Analysis
Contract-based long-term offtake structures dominate procurement between integrated manufacturers and agricultural distributors in Brazil and Argentina, while spot purchasing persists for municipal buyers in price-sensitive segments. Price differentiation separates brodifacoum-based professional formulations from warfarin economy tiers through certification grade and bait matrix durability under humidity stress. Cost compression in first-generation indandione products is intensifying as Chinese precursor suppliers consolidate, squeezing formulation specialists without backward integration. Government agencies and residential consumers exhibit highest price sensitivity, whereas food-processing facilities under FDA Food Safety Modernization Act mandates accept premium positioning for documented rotation compliance.
Supply Chain Analysis
Strait of Malacca transit underwrites bulk precursor shipments from Zhejiang and Jiangsu provinces to formulation plants across Latin America and Europe. Hydroxycoumarin active ingredient synthesis concentrates in China, with secondary blending operations in Germany and the United States. Raw material dependencies encompass 4-hydroxycoumarin precursors, paraffin-wax matrix substrates, and lipid attractant compounds. Single-source vulnerability in Chinese precursor manufacturing exposes global formulators to environmental compliance disruptions under MEE oversight. Distribution runs through wholesale suppliers serving pest control operators, with agricultural supply outlets capturing growing volume in Brazilian soybean belt expansion zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital monitoring convergence with IoT-enabled bait stations is transforming rodent control from product transaction to subscription-platform economics, creating interoperability standards that reshape competitive boundaries across hardware-software ecosystems.
For Market Incumbents: Secure captive supply of bromadiolone precursors through backward integration or long-term offtake agreements with Zhejiang and Jiangsu manufacturers, insulating against qualification delays that threaten formulation continuity. Anchor platform position by bundling anticoagulant formulations with predictive replenishment software, raising switching costs for commercial property managers before digital-native entrants achieve scale. Defend against secondary poisoning liability restrictions by accelerating weight-triggered bait station certification ahead of EPA risk mitigation mandate expansion. For New Entrants and Emerging Players: Moisture-resistant encapsulation technology gaps in Southeast Asian palm oil plantations represent the most penetrable white-space target, as incumbent paraffin-wax formulations degrade above 85% relative humidity. Target Brazilian agricultural distributors underserved by integrated chemical conglomerates with technical consultation capabilities and flexible volume commitments that match soybean storage seasonality. Pursue go-to-market alignment with ANVISA-registered local partners to compress product re-registration timelines relative to direct foreign entry. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agrochemical parents with under-monetized rodenticide portfolios lacking digital monitoring integration. Five-to-ten-year viability favors specialists with proprietary bait matrix IP and established regulatory dossiers across EPA FIFRA and ECHA REACH jurisdictions. Signal to monitor: ECHA authorization discontinuity for difenacoum and flocoumafen triggering distressed asset availability and consolidation windows among European formulation-dependent operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | BASF's captive 4-hydroxycoumarin supply secures cost position in Latin American agricultural markets. |
| Proprietary Bait Matrix Development | Syngenta's humidity-resistant formulations capture premium positioning in Brazilian soybean storage facilities. |
| Digital Monitoring Platform Integration | IoT-enabled bait station sensors enable predictive replenishment models that reduce service frequency for commercial property managers. |
| Regulatory Pre-Positioning for Authorization Timelines | Early ECHA BPR dossier submission ahead of difenacoum review windows secures supply continuity for European pest control operators. |
| Geographic Expansion into Brazilian Agricultural Storage | Mato Grosso and Paraná grain elevator investments institutionalize recurring demand for single-feed bromadiolone systems. |
Research Approach
Initial hypotheses were tested against primary input from technical R&D directors at formulation specialists, procurement leads at Brazilian grain elevator operators, regulatory affairs managers navigating EPA FIFRA re-registration, and distribution channel partners across agricultural supply outlets. Secondary validation drew from EPA registration databases, ECHA biocidal product submissions, ANVISA regulatory filings, and customs trade data tracking hydroxycoumarin precursor flows. Bottom-up volume estimates from end-use segment interviews were triangulated against top-down market sizing from producer capacity disclosures.
Variance-decomposition across the projection horizon isolates volume drivers by product type tier, application segment, and regional regulatory cluster. Segmentation dimensions modeled encompass active ingredient generation, end-use environment characteristics, distribution channel structure, and jurisdiction-specific compliance requirements. CAGRs were derived from installed base evolution and replacement cycle analysis rather than extrapolation of historical growth rates. Industry-specific forecast inputs include ECHA authorization timeline probabilities and Brazilian agricultural storage infrastructure investment pipelines.
Underlying assumptions cover regulatory continuity for bromadiolone in key agricultural markets, with deviation risk concentrated in ECHA substance discontinuity and secondary poisoning liability expansion in North American municipal procurement. Practitioners should keep alternative scenarios live as EPA risk mitigation measures and REACH authorization outcomes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Scouring Agents Market
Chemicals
Paint Stripper Market
Chemicals
Cetostearyl Alcohol Market
Chemicals
United States Construction Chemicals Market
Chemicals
Global N-Butanol Market
Chemicals
Benzenoid Market
Chemicals
Thioacetic Acid Market
Chemicals
Catechol Market
Chemicals
P-Ethylphenol Market
Chemicals
Gold Plating Chemicals Market
Chemicals
Acetophenone Market
Chemicals
Italy Laboratory Chemicals Market
Chemicals
Global Methyl Cellulose Market
Chemicals
Isooctyl Alcohol Market
Chemicals
Mercuric Chloride Market
Chemicals
Calcium Carbide Market