
 Tackifier Market | 2026-2036
Tackifier Market Size, Share, and Industry Trends Forecast 2026-2036
Tackifier Market Intelligence
Modular tackifier-adhesive bundles tailored to hot-melt application systems are restructuring procurement patterns across packaging converters. Henkel AG & Co. KGaA leverages its adhesive formulation heritage to integrate tackifier selection into turnkey bonding solutions. Eastman Chemical Company anchors North American supply through hydrogenated hydrocarbon resin capacity. Kraton Corporation specializes in styrenic block copolymer-tackifier synergies for pressure-sensitive markets.
A tackifier is a low-molecular-weight resin additive that imparts tack or sticky flow to elastomer-based adhesives, typically exhibiting softening points between 80°C and 150°C and functioning through glass-transition depression of the base polymer matrix. Hydrocarbon resins dominate volume throughput due to petroleum feedstock availability and C5/C9 fractionation economics, while rosin esters command premium positioning in food-contact and skin-adhesive applications where terpene phenolics compete on heat-resistance specifications. Emulsion forms are gaining formulation share in water-based adhesive transitions, though solid flake remains the default for hot-melt compounding.
EPA oversight of volatile organic compound emissions from adhesive operations shapes tackifier selection toward hydrogenated and water-dispersible grades, while REACH registration requirements in Europe restrict certain aromatic-modified hydrocarbon chemistries. FDA indirect food-contact regulations govern rosin ester purity thresholds for packaging adhesives. Stakeholders must monitor bio-based feedstock certification schemes and regional carbon-border adjustments to secure formulation flexibility.
Market Dynamics
Hot-melt adhesive system standardization is compressing tackifier procurement cycles, forcing resin suppliers to bundle formulation support with volume contracts rather than sell commodity grades. Automotive assembly plants in Stuttgart, Wolfsburg, and Detroit now specify tackifier-adhesive packages rather than discrete resin purchases.
Growth Catalysts
- Pressure-sensitive adhesive expansion:Tape and label converters in China's Guangdong province operate continuous coating lines that consume hydrogenated hydrocarbon resins at scale, pulling volume through dedicated supply agreements.
- REACH registration completion:ECHA's full registration requirements for C9 aromatic resins have cleared compliant suppliers to serve European medical and hygiene adhesive formulators without regulatory interruption.
- Bio-based rosin ester innovation:Pine-derived feedstock certification under USDA BioPreferred and comparable EU schemes opens food-contact packaging segments previously closed to petroleum-derived alternatives.
Market Restraints
- Crude oil-C5 fraction correlation:Hydrocarbon resin economics track naphtha and refinery stream volatility, compressing margin predictability for non-integrated compounders.
- East Asian supply concentration:Guangdong and Zhejiang provinces host disproportionate rosin ester distillation capacity, creating geographic risk for buyers dependent on just-in-time flake delivery.
- Hydrogenation capex barriers:Partial and full hydrogenation units require specialized catalyst systems and pressure vessels that smaller resin producers cannot finance internally.
Strategic Opportunities
- India packaging conversion:BIS standards alignment with FDA indirect food-contact rules positions compliant rosin ester suppliers to capture hot-melt demand from Mumbai and Ahmedabad label converters.
- Water-based emulsion transition:EPA VOC enforcement in California and Northeast corridor states is forcing solvent adhesive users toward dispersible tackifier grades compatible with existing coating infrastructure.
- Automotive lightweighting mandate:NHTSA fuel economy standards and comparable EU regulations accelerate pressure-sensitive bonding in interior trim assembly, displacing mechanical fasteners with tackifier-dependent adhesive systems.
Industry Challenges
- Formulation chemistry specialization:Hot-melt compounders require polymer science expertise to balance styrenic block copolymer-tackifier compatibility across temperature and shear specifications, constraining talent pools.
- REACH-SVHC testing timelines:ECHA substance of very high concern candidate list expansion forces resin suppliers to maintain expensive analytical capabilities and extended certification documentation for European customers.
- Legacy equipment retrofit costs:Packaging converters running 1990s-era hot-melt tanks face stainless steel replacement and temperature control upgrades to handle higher-softening-point hydrogenated grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tackifier Market |
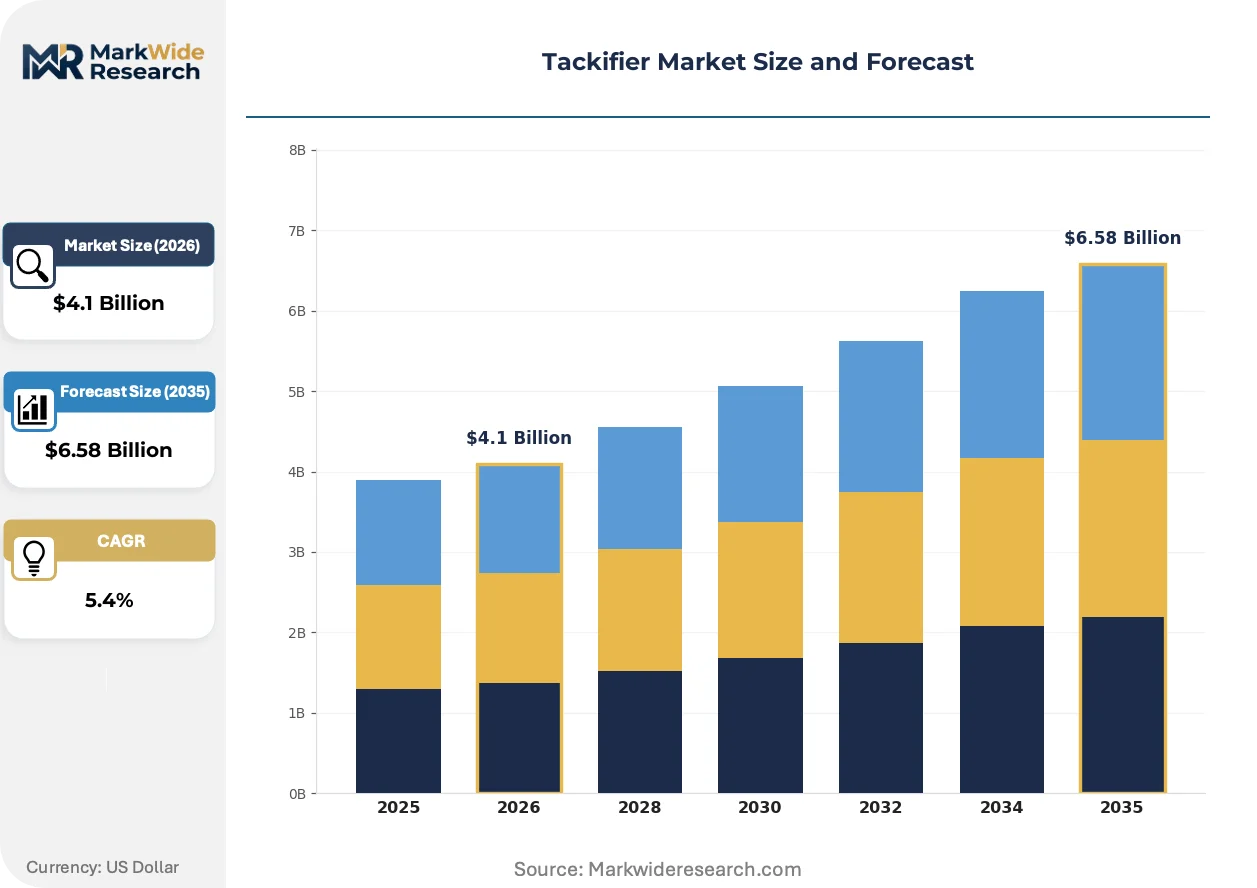
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.58 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rosin Esters, Hydrocarbon Resins, Terpene Phenolics, Polyterpenes, Synthetic Resins Application: Adhesives, Paints & Coatings, Printing Inks, Rubber Compounds, Sealants Form: Solid, Liquid, Powder, Emulsion End User Industry: Packaging, Construction, Footwear, Electronics, Textiles |
| Companies Covered | Henkel AG & Co. KGaA, Kolon Industries, Eastman Chemical Company, Arakawa Chemical Industries, BASF SE, Arkema, Kraton Corporation, Zeon Corporation, ExxonMobil Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tackifier Market Strategic Shifts & Innovations
Digital formulation platforms are collapsing the traditional trial-and-error cycle between tackifier suppliers and adhesive compounders, compressing development timelines from months to weeks. This shift redistributes competitive advantage toward resin producers with integrated technical service capabilities.
Bio-based hydrocarbon resins derived from tall oil and other renewable feedstocks are decentralizing the petroleum-centric supply structure that has dominated tackifier markets since the 1960s. European hygiene product manufacturers in Germany and Sweden have adopted these grades for premium diaper and feminine care adhesive lines, forcing traditional C5/C9 suppliers to develop comparable certification pathways or surrender positioning in sustainability-driven procurement.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants at adhesive manufacturing facilities is accelerating capital deployment toward enclosed hot-melt systems and lower-VOC tackifier alternatives. California's South Coast Air Quality Management District has enacted the most stringent requirements, compelling Los Angeles-area tape producers to validate hydrogenated hydrocarbon and rosin ester replacements for aromatic-modified grades previously standard in construction adhesive formulations.
Consolidated procurement by multinational packaging groups is compressing supplier rosters and extending contract durations, reversing the fragmented multi-source purchasing that characterized converter tackifier buying through 2015. Brazil's flexible packaging sector demonstrates this pattern most acutely, where São Paulo-based converters have reduced qualified resin suppliers from eight to three while demanding integrated formulation support and inventory management services.
Tackifier Market Segmentation
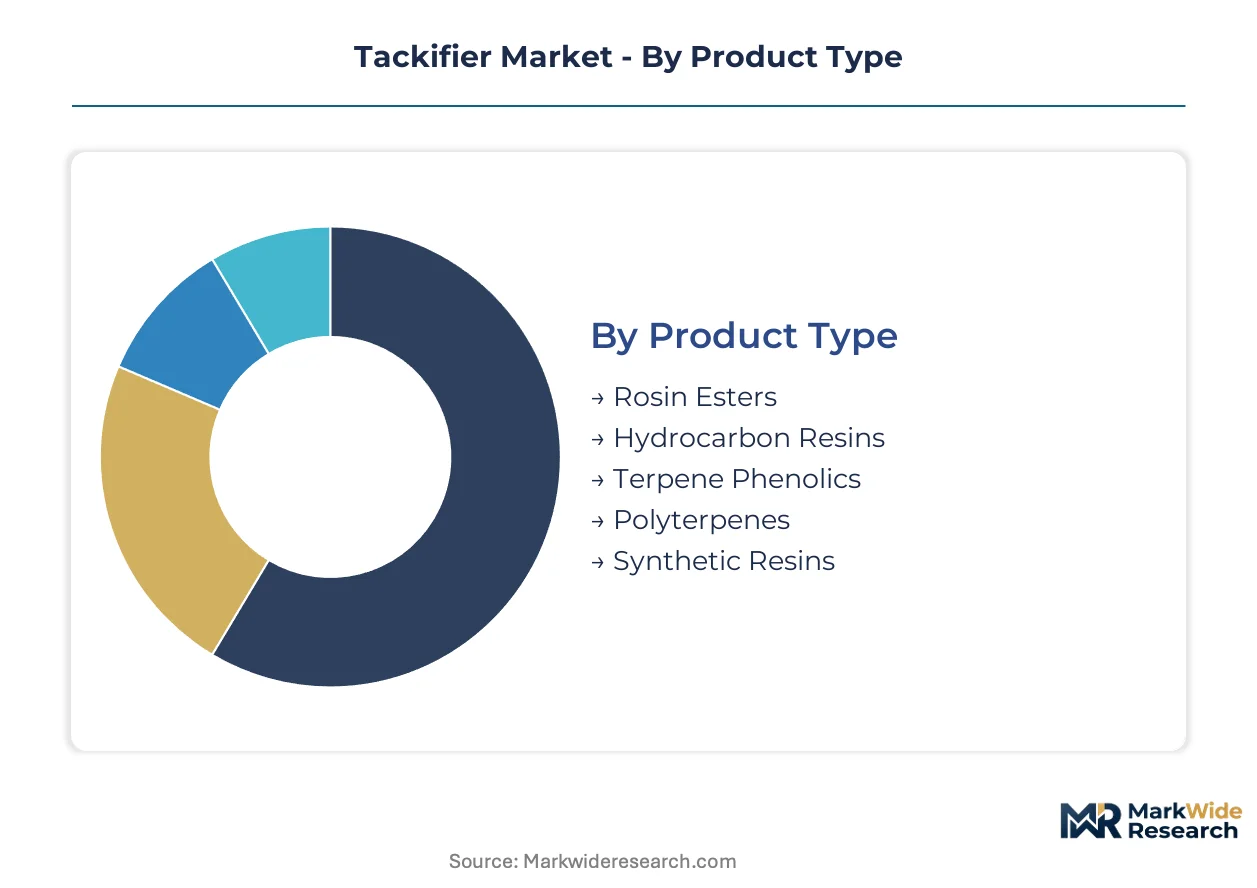
Tackifier segmentation reveals how resin chemistry, physical form, and end-use specifications create distinct supply chain configurations. Each dimension carries procurement implications that shape supplier relationships and formulation strategies across adhesive compounders.
Product Type:
Supply concentration varies sharply by resin chemistry, with hydrogenated hydrocarbon capacity anchored in North American Gulf Coast refineries while rosin ester distillation clusters in China's Guangdong and Zhejiang provinces.
- Rosin Esters:Pine-derived acid esters with softening points between 80°C and 150°C serve FDA-regulated food-contact packaging and medical skin adhesives. Demand concentrates in Guangdong tape manufacturing clusters where converters specify certified grades for export markets. USDA BioPreferred certification opens premium positioning against petroleum alternatives.
- Hydrocarbon Resins:C5 aliphatic and C9 aromatic fractions from petroleum cracking dominate volume throughput through refinery integration economics. Automotive assembly plants in Stuttgart and Detroit specify hydrogenated grades for interior trim bonding to meet VOC regulations. Partial hydrogenation capex barriers protect integrated producers.
- Terpene Phenolics:Beta-pinene-derived resins with elevated softening points compete on heat resistance in industrial tape applications.
- Polyterpenes:Oligomerized terpene structures offer narrow molecular weight distribution for specialty pressure-sensitive formulations.
- Synthetic Resins:Tailored hydrocarbon architectures provide batch-to-batch consistency for medical device adhesives.
Today's leader: Hydrocarbon Resins. Tomorrow's challenger: Rosin Esters.
Application:
Application-driven procurement separates commodity volume buyers from specialty formulators seeking technical partnership.
- Adhesives:Pressure-sensitive, hot-melt, and solvent-based systems consume the majority of tackifier volume. China's Guangdong province operates continuous coating lines pulling hydrogenated hydrocarbon resins through dedicated supply agreements. REACH-compliant C9 aromatic grades serve European medical and hygiene formulators.
- Paints & Coatings:Coalescing aid and film-forming modifier applications in industrial maintenance coatings.
- Printing Inks:Pigment wetting and gloss enhancement in flexographic and gravure systems.
- Rubber Compounds:Tack retention in tire manufacturing and conveyor belt construction.
- Sealants:Green strength development in construction and automotive seam sealing.
Adhesives command formulation attention; sealants represent the steepest expansion trajectory as construction activity accelerates.
Form:
Physical state determines handling infrastructure, with solid flake dominating hot-melt compounding while emulsion forms enable water-based transitions.
- Solid:Flake and pellet forms remain the default for hot-melt adhesive compounding, requiring heated tanks and temperature control systems. Packaging converters in São Paulo reduced qualified suppliers from eight to three while demanding integrated inventory management services.
- Liquid:Low-viscosity grades for solvent-based adhesive systems and inline dosing.
- Powder:Free-flowing micronized products for rubber mixing and powder coating applications.
- Emulsion:Water-dispersible grades gain share as EPA VOC enforcement in California and Northeast corridor states forces solvent adhesive users toward compatible coating infrastructure.
Solid forms anchor current procurement; emulsion grades are climbing the fastest as regulatory pressure intensifies.
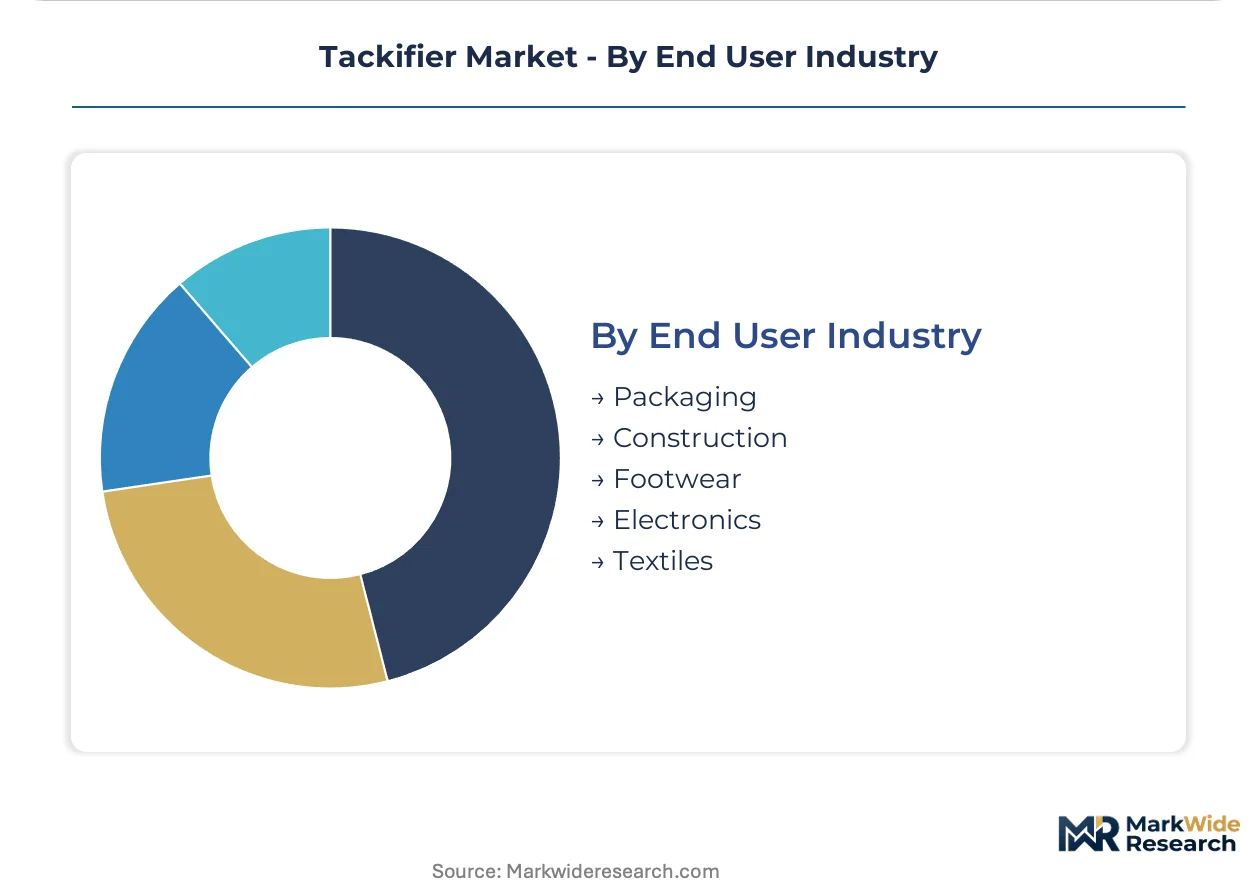
End User Industry:
End-use specifications create divergent margin structures, with medical and electronics applications commanding premium pricing against commodity packaging volumes.
- Packaging:Flexible packaging and label converters in Brazil's São Paulo sector demonstrate consolidated procurement patterns with extended contract durations. BIS standards alignment in India positions compliant rosin ester suppliers to capture hot-melt demand from Mumbai and Ahmedabad converters.
- Construction:Pressure-sensitive bonding in flooring and wall covering applications.
- Footwear:Hot-melt assembly of sole-to-upper bonds in athletic and casual shoe manufacturing.
- Electronics:Low-outgassing grades for display bonding and component fixation.
- Textiles:Fusible interlining and lamination adhesives in garment manufacturing.
Packaging drives volume scale; electronics offers the highest value-add per kilogram.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum cracking and pine distillation established the tackifier industry's geographic footprint across Gulf Coast refineries and southeastern Chinese forestry provinces. These origins continue to shape supply concentration and regulatory exposure today.
United States
Gulf Coast hydrogenation capacity serves automotive assembly plants in Detroit specifying low-VOC grades for interior trim bonding. EPA National Emission Standards enforcement accelerates capital deployment toward enclosed hot-melt systems at adhesive manufacturing facilities. California's South Coast Air Quality Management District maintains the most stringent requirements, compelling Los Angeles-area tape producers to validate hydrogenated hydrocarbon replacements.
China
Guangdong province hosts disproportionate rosin ester distillation capacity feeding continuous coating lines for tape and label export markets. NMPA and GB standards alignment with FDA indirect food-contact rules positions certified suppliers for medical adhesive formulators. Zhejiang province clusters secondary distillation operations, creating geographic risk for buyers dependent on just-in-time flake delivery.
Germany
Stuttgart and Wolfsburg automotive assembly plants specify tackifier-adhesive packages rather than discrete resin purchases for pressure-sensitive interior bonding. ECHA REACH registration requirements for C9 aromatic resins cleared compliant suppliers to serve European medical and hygiene adhesive formulators. Bavaria-based hygiene product manufacturers have adopted tall oil-derived bio-based grades for premium diaper lines.
India
BIS standards alignment with FDA indirect food-contact rules positions compliant rosin ester suppliers to capture hot-melt demand from Mumbai and Ahmedabad label converters. CDSCO medical device regulations govern adhesive purity thresholds for transdermal patch applications. Maharashtra packaging converters demonstrate consolidated procurement patterns with extended contract durations.
Japan
METI industrial standards and JIS certification requirements shape tackifier selection for electronics display bonding applications. Osaka-based tape manufacturers specify low-outgassing grades for component fixation in consumer electronics. Chubu region automotive suppliers source hydrogenated hydrocarbon resins through dedicated supply agreements with integrated petrochemical producers.
Tackifier Market Key Industry Players
Premium-margin players sit above commodity-margin players across hydrogenation capability and formulation integration depth. The market structures around three tiers: integrated petrochemical majors with captive C5/C9 fractionation, specialized rosin ester distillers with pine supply control, and adhesive formulators backward-integrating into resin selection. Strategic moves concentrate on capacity expansion in hydrogenated grades and partnership bundling with packaging converters.
Among German chemical conglomerates, Henkel AG & Co. KGaA exemplifies formulation-integrated positioning through adhesive heritage. Eastman Chemical Company anchors North American supply archetypes through Gulf Coast hydrogenation infrastructure. Kraton Corporation occupies the styrenic block copolymer-tackifier synergy specialist tier.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Kolon Industries |
| Eastman Chemical Company |
| Arakawa Chemical Industries |
| BASF SE |
| Arkema |
| Kraton Corporation |
| Zeon Corporation |
| ExxonMobil Chemical |
| Others |
Cost & Logistics Intelligence
Family-owned rosin ester distillers in China's Guangdong and Zhejiang provinces anchor supply concentration while exercising disciplined pricing power through pine supply control and certified grade premiums. Petroleum-integrated majors on the US Gulf Coast leverage captive C5/C9 fractionation to undercut non-integrated compounders on standard hydrocarbon grades, creating bifurcated margin structures across feedstock ownership models.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs tackifier procurement, with hydrogenated hydrocarbon resins commanding FDA-compliant and low-VOC premiums against commodity C9 aromatic grades. Price differentiation hinges on certification tier—REACH-registered and BioPreferred-certified rosin esters extract 15-25% premiums—and volume scale, where automotive assembly contracts above 500 metric tons secure indexed pricing. Cost compression in standard hydrocarbon grades is intensifying because naphtha volatility compresses non-integrated producer margins. Packaging converters in São Paulo demonstrate highest price sensitivity through consolidated supplier rosters, while medical adhesive formulators in Stuttgart show lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Tackifier supply rests on petroleum cracking economics in the United States, pine distillation infrastructure in China, and tall oil fractionation in Scandinavia. Raw material dependencies include C5/C9 refinery streams, gum rosin and tall oil fatty acids, and hydrogen gas for saturation reactions. Single-source vulnerability concentrates in Guangdong province rosin ester capacity, where just-in-time flake delivery to tape manufacturers creates geographic risk. Distribution runs through direct mill supply agreements for automotive and hygiene OEMs, with packaging converters increasingly demanding bundled formulation support and vendor-managed inventory services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA National Emission Standards for Hazardous Air Pollutants enforcement functions as a regulatory compounder, forcing solvent adhesive users toward water-dispersible and hydrogenated tackifier grades and restructuring procurement patterns across California and Northeast corridor states.
For Market Incumbents: Cement hydrogenation capability advantages through catalyst system upgrades and pressure vessel expansion at Gulf Coast facilities to defend against tall oil-derived bio-based entrants. Prioritize REACH-SVHC testing infrastructure investments to maintain European medical and hygiene adhesive formulator access as ECHA expands candidate list monitoring.
For New Entrants and Emerging Players: Specialty chemical distributors with existing adhesive compounder relationships offer the most penetrable channel for rosin ester market entry without captive pine supply. Target India's Maharashtra and Gujarat packaging corridors where BIS standards alignment with FDA rules creates certification arbitrage opportunities for compliant suppliers. Lead with technical service bundling rather than commodity volume to differentiate from entrenched Guangdong producers.
For Investors and Strategic Acquirers: Valuations sit cheapest among non-integrated hydrocarbon resin producers facing naphtha margin compression without backward integration into refinery streams. Five-to-ten year viability favors tall oil bio-based specialists with USDA BioPreferred certification and European hygiene manufacturer offtake agreements. Watch EPA regional enforcement intensity and South Coast Air Quality Management District rulemaking as demand inflection signals for hydrogenated grade capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pine Supply | Secures rosin ester feedstock certainty for Guangdong distillers facing forestry resource competition. |
| Hydrogenation Capacity Expansion | Enables low-VOC grade supply to Detroit and Stuttgart automotive assembly plants under tightening EPA and EU regulations. |
| BioPreferred Certification Program | Opens premium diaper and feminine care adhesive segments for tall oil-derived alternatives in Bavaria and Sweden. |
| Long-term Supply Agreement | Locks in volume commitments from São Paulo flexible packaging converters consolidating supplier rosters. |
| Joint Venture with Adhesive Formulator | Integrates tackifier selection into turnkey bonding solutions following Henkel's bundled procurement model. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with adhesive R&D directors, procurement leads at packaging converters, plant managers at rosin ester distilleries, and technical service heads at resin suppliers. Secondary validation draws from EPA enforcement records, ECHA REACH registration databases, USDA BioPreferred certified product listings, and customs trade data for C5/C9 hydrocarbon resin flows. Bottom-up volume estimates from end-use consumption patterns triangulate against top-down petrochemical capacity assessments.
Rate-of-change decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include resin chemistry tier, adhesive application type, physical form factor, and end-use industry vertical. CAGRs derive from regression analysis against automotive production forecasts, packaging conversion growth indices, and regulatory phase-in timelines. Industry-specific inputs incorporate hydrogenation capacity expansion announcements and pine harvest yield projections from major forestry regions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to crude oil-naphtha price correlations and EU carbon-border adjustment implementation scope. Assumptions reflect current regulatory enforcement trajectories and disclosed capacity investment plans. A small set of named triggers warrants ongoing watch: EPA regional enforcement intensity, ECHA SVHC list expansion cadence, and Guangdong province environmental compliance inspections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Flux Injection System Market
Additives
Sodium Benzoate Market
Additives
Liquid Silage Additive Market
Additives
Refining Additives Market
Additives
Global Formulation Additives Market
Additives
Glyceryl Caprylate Market
Additives
Calcium Diglutamate Market
Additives
Global Pour Point Depressant Market
Additives
Global Pearlizing Agent Market
Additives
Global Hindered Amine Light Stabilizers Market
Additives
Coating Additives Market
Additives
Binder Excipients Market
Additives
Anti Crystallizing Agents Market
Additives
Automotive Additives Market
Additives
Global Lubricating Oil Additives Market
Additives
Global Peptone Market