
 Canada Water Enhancer Market | 2026-2036
Canada Water Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Water Enhancer Market Outlook
Food scientist and flavor chemist talent scarcity is bifurcating the Canada water enhancer competitive landscape into R&D-intensive innovators and private-label followers. Nestlé S.A. leverages its global beverage science infrastructure to sustain proprietary emulsion stability technology. The Coca-Cola Company anchors its position through dominant shelf-space control in conventional grocery. PepsiCo Inc. differentiates via sports-nutrition cross-branding with its broader hydration portfolio.
Canada water enhancers comprise concentrated liquid, powder, or tablet formulations designed to dissolve in plain water, typically containing natural or artificial flavoring agents, acidulants, sweeteners, vitamins, minerals, and electrolytes at dosages of 1-5 mL per 500 mL serving. These products function as low-calorie alternatives to sugar-sweetened beverages while delivering functional benefits including electrolyte replenishment, energy metabolism support, and palatability improvement for increased water consumption. Flavored drops command the largest volume share due to dosing precision and portability advantages, while tablets represent the fastest-expanding format driven by fitness channel penetration and reduced shipping-weight economics. Powdered mix occupies a mature position in family-oriented bulk purchasing, though single-serve sachets are gaining traction in subscription-based online retail.
Health Canada's Food and Drug Regulations govern permissible sweetener categories, nutrient content claims, and bilingual labeling standards that directly shape product development timelines and reformulation costs. The Canadian Food Inspection Agency enforces compositional standards and allergen declaration protocols that influence manufacturing facility certification requirements and cross-border ingredient sourcing decisions. Environment and Climate Change Canada's single-use plastics restrictions are pressuring packaging format transitions toward recyclable bottles and compostable sachet materials. Stakeholders must monitor evolving natural health product classification thresholds that could reclassify vitamin-fortified enhancers from food to regulated therapeutic goods.
Market Dynamics
Health Canada's evolving natural health product classification thresholds are forcing reformulation cycles across vitamin-fortified enhancers, compressing product development timelines while expanding compliance overhead for functional positioning claims.
Growth Catalysts
- Electrolyte customization demand:Fitness enthusiasts in British Columbia and Ontario are driving precision-dosing adoption for hydration personalization during endurance training protocols.
- Health Canada's bilingual labeling mandate:This regulatory requirement creates barrier-to-entry protection for domestic manufacturers with established compliance infrastructure.
- Single-serve powder sachets:Subscription-based direct-to-consumer channels are capturing urban health-conscious households seeking portion-controlled convenience.
Market Restraints
- Stevia and monk fruit price volatility:Natural high-intensity sweetener supply concentrates in Southeast Asian extraction facilities, exposing margins to climate-driven harvest fluctuations.
- Emulsion stability technical ceiling:Oil-based flavor carriers face shelf-life limitations in temperature-variable retail environments, constraining clean-label formulation options.
- CFIA allergen declaration protocols:Cross-contamination testing requirements extend facility certification timelines, delaying new product market entry.
Strategic Opportunities
- Quebec underpenetration:Specialty retail density remains below Ontario levels in Montreal and Quebec City, presenting whitespace for channel expansion.
- Pediatric functional hydration:Sugar-reduction positioning aligned with Health Canada sodium reduction targets opens school-lunch adjacent occasions.
- Compostable sachet materials:Environment and Climate Change Canada's single-use plastics restrictions are accelerating biodegradable packaging substitution ahead of enforcement deadlines.
Industry Challenges
- Flavor chemist talent scarcity:Food science programs produce insufficient formulation specialists versed in natural masking technologies for bitter functional ingredients.
- Dual facility certification:Manufacturers serving both food and prospective natural health product classifications face redundant audit cycles under CFIA and Health Canada parallel tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Water Enhancer Market |
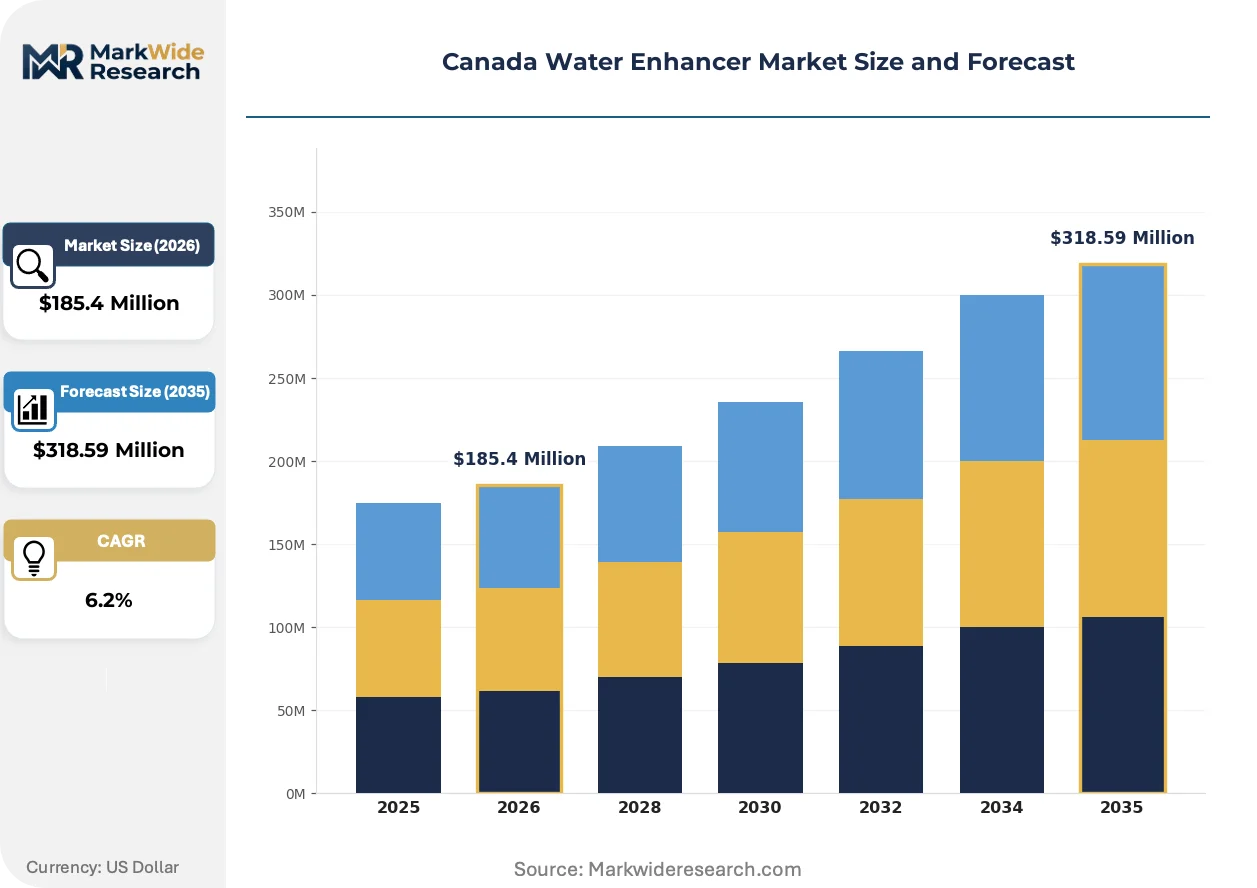
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $318.59 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavored Drops, Powdered Mix, Infused Water, Tablets End User: Fitness Enthusiasts, Health-Conscious Consumers, Athletes, Families Distribution Channel: Supermarkets, Health Stores, Online Retail, Specialty Shops Packaging Type: Bottles, Sachets, Jars, Tetra Packs |
| Companies Covered | Nestlé S.A., Jel Sert Company, The Coca-Cola Company, Cott Corporation, Loblaw Inc., PepsiCo Inc., Wisdom Natural Brands, Nuun & Company Inc., The Kraft Heinz Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Water Enhancer Market Strategic Shifts
Concentration precision and portability are reshaping format preferences across Canadian hydration occasions, while regulatory pressure on packaging materials accelerates sustainable substrate innovation.
Tablet-based water enhancers are miniaturizing active ingredient payloads into effervescent and direct-dissolve formats. Fitness channel buyers in Vancouver and Toronto are adopting these for gym-bag portability. This format compression is miniaturizing shipping-weight economics, enabling direct-to-consumer subscription models to undercut conventional retail distribution costs.
Health Canada's Food and Drug Regulations are tightening permissible nutrient content claim thresholds for vitamin-fortified products. Manufacturers must now substantiate functional positioning through clinical evidence packages. Electrolyte-focused SKUs face the steepest compliance burden, driving consolidation toward established players with regulatory affairs capabilities.
Direct-to-consumer subscription models are displacing conventional grocery replenishment cycles among urban millennials. Specialty online retailers in Ontario and British Columbia are capturing recurring revenue through personalized flavor rotation algorithms. This channel pivot concentrates highest lifetime-value customers away from mass retail shelf-space competition.
Canada Water Enhancer Market Segmentation
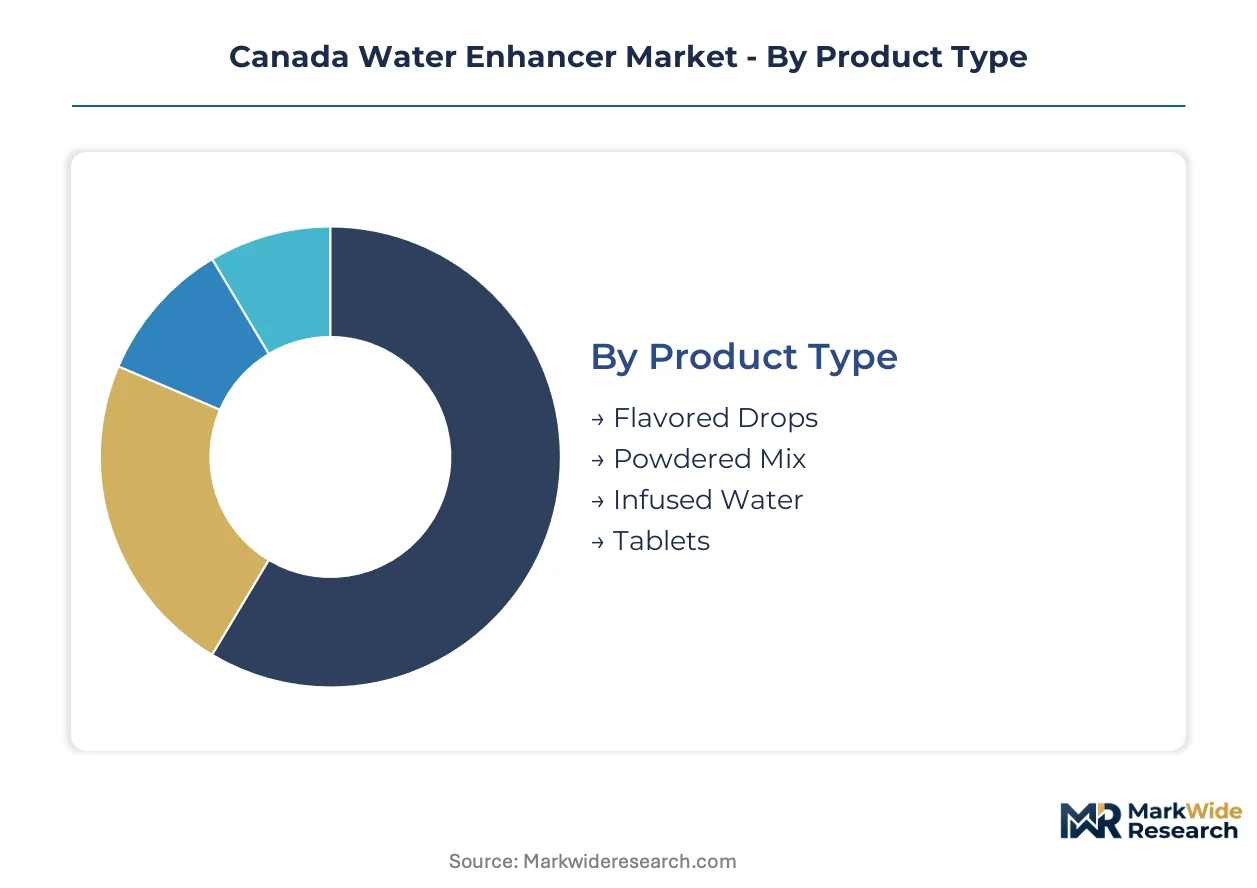
Health Canada's Food and Drug Regulations create divergent compliance pathways across product formats, forcing manufacturers to align formulation complexity with certification economics. Segmentation strategy must account for how bilingual labeling, natural health product thresholds, and single-use plastics restrictions differentially burden each category.
Product Type:
Health Canada's natural health product classification thresholds impose steeper evidentiary burdens on vitamin-fortified formats than on basic flavoring systems.
- Flavored Drops:Concentrated liquid formulations deliver precise dosing at 1-5 mL per 500 mL serving, enabling portion control for Ontario and British Columbia households tracking sugar reduction. Portability advantages concentrate demand among urban commuters seeking gym-bag convenience without refrigeration dependency.
- Tablets:Effervescent and direct-dissolve formats miniaturize shipping-weight economics, allowing Vancouver and Toronto fitness enthusiasts to access subscription-based replenishment at lower per-unit freight costs than liquid alternatives. Reduced dimensional weight unlocks direct-to-consumer channel viability.
- Powdered Mix:Bulk family purchasing dominates this mature segment, though single-serve sachets are gaining traction through Ontario-based subscription retailers.
- Infused Water:Ready-to-drink positioning faces steeper Environment and Climate Change Canada plastics compliance costs than concentrate formats.
Flavored drops handle the majority of throughput; tablets are expanding most quickly on share.
End User:
Customer lifetime value concentrates sharply around repeat-purchase frequency, with subscription economics favoring high-engagement segments over episodic buyers.
- Fitness Enthusiasts:Electrolyte customization demand drives precision-dosing adoption for hydration personalization during endurance training protocols in British Columbia's mountain sports corridors and Ontario's urban marathon circuits.
- Health-Conscious Consumers:Sugar-reduction positioning aligns with Health Canada sodium reduction targets, opening school-lunch adjacent occasions for pediatric functional hydration in Montreal and Quebec City households.
- Athletes:Team-sport bulk procurement concentrates through specialty retail channels in Calgary and Edmonton.
- Families:Value-oriented multi-serve purchasing dominates conventional grocery replenishment cycles in suburban Ontario markets.
Fitness enthusiasts command the highest per-capita spend; health-conscious consumers are climbing the fastest on segment share.
Distribution Channel:
Channel economics bifurcate between high-margin direct relationships and scale-dependent mass retail slotting fees.
- Supermarkets:Dominant shelf-space control in conventional grocery anchors volume throughput for family-oriented powdered mix formats, though slotting fee structures disadvantage emerging brands without established trade marketing budgets.
- Online Retail:Subscription-based direct-to-consumer models capture recurring revenue through personalized flavor rotation algorithms, concentrating highest lifetime-value customers away from mass retail competition in Toronto and Vancouver metropolitan areas.
- Health Stores:Specialty retail density in Ontario and British Columbia supports premium positioning for clean-label formulations.
- Specialty Shops:Curated assortments in Montreal and Quebec City present whitespace for Quebec underpenetration recovery.
Supermarkets handle the majority of throughput; online retail is gaining share fastest.
Packaging Type:
Environment and Climate Change Canada's single-use plastics restrictions are accelerating format transitions toward compliant substrates with divergent cost structures.
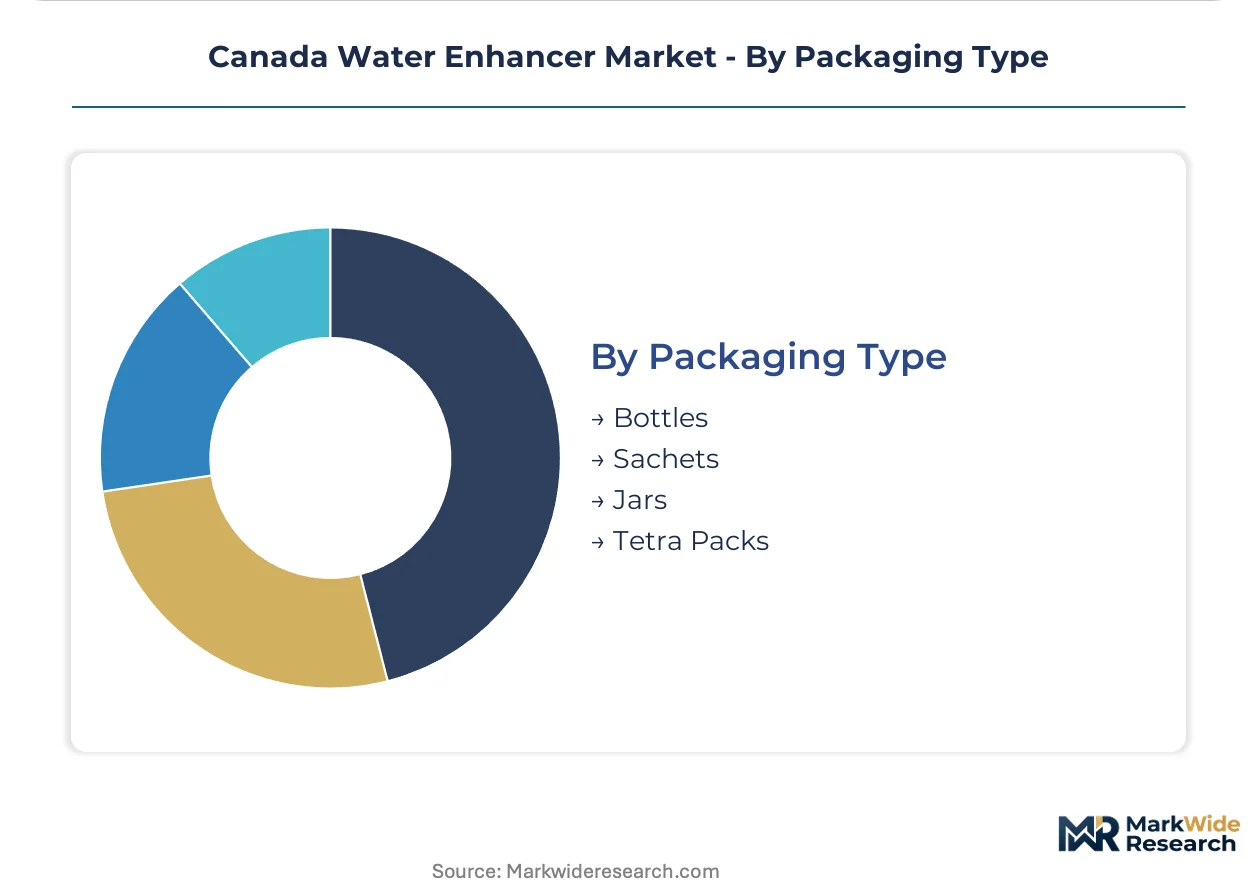
- Sachets:Single-serve powder sachets minimize material intensity while enabling portion-controlled convenience for urban health-conscious households. Compostable substrate innovation is advancing fastest here ahead of enforcement deadlines.
- Bottles:Recyclable bottle formats dominate flavored drops distribution, though resin cost volatility pressures margin stability.
- Jars:Bulk powdered mix containers serve family purchasing patterns with lower per-gram packaging cost.
- Tetra Packs:Aseptic liquid concentrates face limited adoption due to recycling infrastructure gaps in Canadian municipalities.
Bottles handle the majority of throughput; sachets are on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Ontario and British Columbia, where urban density and health-conscious demographics sustain premium positioning, while Quebec and Prairie markets trade at lower price points due to distribution inefficiency and lower specialty retail penetration.
Ontario
Toronto's marathon circuits and Greater Toronto Area fitness density drive electrolyte customization demand through precision-dosing formats. Health Canada's bilingual labeling mandate creates compliance infrastructure advantages for domestic manufacturers headquartered here. Specialty online retailers in Toronto capture recurring subscription revenue through personalized flavor algorithms.
British Columbia
Vancouver's mountain sports corridors and endurance training protocols fuel tablet format adoption for gym-bag portability. Environment and Climate Change Canada's single-use plastics restrictions accelerate compostable sachet innovation among Vancouver-based packaging suppliers. Direct-to-consumer subscription models leverage reduced shipping-weight economics to undercut conventional retail.
Quebec
Montreal and Quebec City present whitespace for specialty retail channel expansion given underpenetration relative to Ontario levels. Health Canada's sodium reduction targets align with sugar-reduction positioning for pediatric functional hydration in school-lunch adjacent occasions. Local distributors face steeper CFIA allergen declaration protocol compliance timelines.
Alberta
Calgary and Edmonton concentrate team-sport bulk procurement through specialty retail channels serving amateur athletics. The province's logistics hub position enables cross-border ingredient sourcing decisions for manufacturers serving western markets. Energy sector commuter culture supports portable format demand for workplace hydration.
Atlantic Canada
Halifax and St. John's exhibit lower per-capita consumption due to limited specialty retail density and delayed e-commerce penetration. Health Canada's Food and Drug Regulations impose identical compliance costs without offsetting scale advantages. Regional distributors rely on Ontario-based fulfillment for subscription service coverage.
Canada Water Enhancer Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Canada water enhancer market. R&D-intensive innovators with proprietary emulsion stability capabilities occupy premium positioning, while private-label followers compete on slotting fee efficiency in conventional grocery. Three archetypes dominate: multinational beverage conglomerates with regulatory affairs infrastructure, mid-cap natural health specialists, and retailer-owned brands leveraging shelf-space control. Consolidation pressure favors M&A activity among vitamin-fortified format players facing Health Canada evidentiary burdens, alongside capacity expansion in compostable packaging substrates.
Within the multinational tier, Nestlé S.A., The Coca-Cola Company, and PepsiCo Inc. anchor competitive positioning through divergent strategic vectors. Nestlé leverages global beverage science infrastructure. Coca-Cola exercises dominant shelf-space control in conventional grocery channels. PepsiCo differentiates via sports-nutrition cross-branding with broader hydration portfolio integration. These three exemplify how scale-driven regulatory compliance capabilities create barrier-to-entry protection against emerging challengers.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Jel Sert Company |
| The Coca-Cola Company |
| Cott Corporation |
| Loblaw Inc. |
| PepsiCo Inc. |
| Wisdom Natural Brands |
| Nuun & Company Inc. |
| The Kraft Heinz Company |
| Others |
Value Chain & Pricing Dynamics
Health Canada's Food and Drug Regulations gate both supply qualification and price differentiation simultaneously, bifurcating manufacturers into compliance-capable premium players and cost-pressured followers while creating tiered market access based on certification infrastructure investment.
Pricing Analysis
The customization-premium spread separates precision-dosing electrolyte formulations from basic flavoring systems, with subscription-based direct-to-consumer channels capturing recurring revenue at 15-20% premiums over conventional grocery. Three-tier pricing structure across premium, standard, and economy levels stratifies around Health Canada natural health product classification thresholds, where vitamin-fortified SKUs carry evidentiary cost burdens that standard drops avoid. Pricing pressure stems from stevia and monk fruit supply volatility originating in Southeast Asian extraction facilities. Fitness enthusiasts in British Columbia and Ontario show lowest price sensitivity due to performance-driven purchasing, while suburban Ontario families trade down to private-label powdered mix during economic softness.
Supply Chain Analysis
China and India anchor high-intensity natural sweetener extraction, while Southeast Asian facilities concentrate stevia and monk fruit processing for Canadian formulation houses. Domestic manufacturing draws from imported acidulants, flavor carriers, and vitamin premixes, with oil-based emulsion stability components facing shelf-life constraints in temperature-variable retail environments. Single-source vulnerability concentrates in natural sweetener supply channels exposed to climate-driven harvest fluctuations. Distribution runs through Ontario-based fulfillment centers serving direct-to-consumer subscription models, supplemented by conventional grocery slotting-fee structures that disadvantage emerging brands without established trade marketing infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward subscription-based direct-to-consumer channels as urban millennials consolidate purchasing through personalized flavor rotation algorithms, fragmenting traditional grocery replenishment cycles.
For Market Incumbents: Compound regulatory affairs capabilities into barrier-to-entry protection against emerging challengers facing Health Canada evidentiary burdens. Expand compostable sachet production capacity ahead of Environment and Climate Change Canada enforcement deadlines. Deepen backward integration into natural sweetener sourcing to mitigate Southeast Asian supply volatility. For New Entrants and Emerging Players: Lead with Quebec specialty retail whitespace in Montreal and Quebec City, where underpenetration relative to Ontario levels presents channel expansion opportunity. Target pediatric functional hydration positioning aligned with Health Canada sodium reduction targets. Deploy direct-to-consumer subscription models with reduced shipping-weight tablet formats to bypass supermarket slotting fee structures. For Investors and Strategic Acquirers: Health Canada's evolving natural health product classification thresholds reshape the acquisition landscape toward vitamin-fortified format players with established clinical evidence packages. Long-term viability favors mid-cap specialists with proprietary emulsion stability technology and regulatory affairs infrastructure. Watch for consolidation signals among private-label followers unable to absorb dual CFIA and Health Canada certification audit cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Compostable Packaging Transition | Environment and Climate Change Canada's single-use plastics restrictions accelerate biodegradable sachet adoption ahead of enforcement. |
| Direct-to-Consumer Channel Expansion | Toronto and Vancouver subscription models capture highest lifetime-value customers through personalized flavor rotation algorithms. |
| Regulatory Affairs Infrastructure Investment | Health Canada natural health product thresholds favor acquirers with established clinical evidence and bilingual labeling capabilities. |
| Backward Integration into Natural Sweeteners | Stevia and monk fruit supply volatility drives captive sourcing strategies to stabilize margin exposure. |
| Pediatric Functional Hydration Positioning | Health Canada sodium reduction targets open school-lunch adjacent occasions for sugar-reduction formulations in Quebec households. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with beverage brand managers, Health Canada regulatory affairs specialists, Ontario and British Columbia specialty retail buyers, and direct-to-consumer subscription platform operators. Secondary validation drew from Health Canada Food and Drug Regulations filings, CFIA allergen declaration protocols, Environment and Climate Change Canada plastics restriction notices, and Nielsen retail audit data. Bottom-up volume triangulation across product formats, end-user segments, and distribution channels was cross-checked against top-down market sizing.
Across the analysis window, the forecasting framework modeled product type segmentation, end-user behavioral clustering, distribution channel economics, and packaging format compliance costs. CAGRs were derived from regression analysis of historical volume trends adjusted for regulatory inflection points and channel shift dynamics. Key inputs included Health Canada natural health product reclassification risk scenarios and direct-to-consumer subscription penetration curves in Toronto and Vancouver metropolitan areas.
The analysis sits within stated boundaries; outcomes outside maintained Health Canada regulatory timelines or sustained direct-to-consumer growth trajectories would require recalibration. Forecasts reflect documented assumptions regarding stevia supply stability and compostable packaging cost parity achievement. Recalibration cycles align with material shifts in Health Canada classification thresholds, CFIA enforcement patterns, or Environment and Climate Change Canada plastics restriction implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Cassia Gum Market
Additives
Middle East Lubricant Additives Market
Additives
Sorbitan Esters Market
Additives
Tamarind Gum Derivatives Market
Additives
Viscosity Reducing Agents Market
Additives
Anti-Pollution Ingredients Market
Additives
Tire Additives Market
Additives
Nucleating and Clarifying Agents Market
Additives
Lactic Acid Ester Market
Additives
Potassium Nitrate Market
Additives
Antimicrobial Ingredients Market
Additives
Potting Mix Additives Market
Additives
Global Pearlizing Agent Market
Additives
Global UV Stabilizers Market
Additives
Tackifier Market
Additives
Isopropyl Acetate Market