
 North America Potassium Nitrate Market | 2026-2036
North America Potassium Nitrate Market Size, Share, and Industry Trends Forecast 2026-2036
North America Potassium Nitrate Market Intelligence
Mexico is tilting toward expanded potassium nitrate blending capacity to serve export-oriented horticulture in Baja California and Sinaloa. Nutrien Ltd. leverages its integrated potash mining and distribution network to dominate Prairie-to-Midwest supply corridors. Haifa Chemicals Ltd. specializes in water-soluble and fertigation-grade formulations, sustaining premium positioning among greenhouse operators. SQM S.A. competes through its caliche ore extraction base, extending cost advantages in technical-grade material.
Potassium nitrate is an inorganic salt with the chemical formula KNO3, typically manufactured through the reaction of potassium chloride with nitric acid or via direct mining of nitrate-bearing deposits; its high solubility and low chloride content make it essential for chloride-sensitive crops and precision agriculture systems. The granular product type anchors volume throughput in bulk fertilizer distribution, while powder formulations capture margin pools in food additive and pyrotechnic applications where particle size uniformity governs performance. Fertilizers dominate end-use consumption, though food additives represent a concentrated premium segment driven by cured meat processing standards.
The EPA enforces Clean Water Act provisions that restrict nitrogen and phosphorus discharge from agricultural runoff, pushing growers toward enhanced-efficiency fertilizers including potassium nitrate blends. OSHA and DOT frameworks govern the handling, storage, and transport of oxidizer-classified materials, shaping packaging specifications and distribution infrastructure investments. State regulators in California and Florida impose additional nutrient management plans that filter product registration and field application rates. Stakeholders must monitor evolving state-level groundwater protection rules and the potential for federal carbon intensity benchmarking to reshape sourcing decisions across the value chain.
Market Dynamics
EPA enforcement of Clean Water Act nitrogen discharge limits is compressing grower tolerance for chloride-heavy fertilizers, redirecting procurement toward low-chloride potassium sources across the Corn Belt and Central Valley specialty zones.
Growth Catalysts
- Controlled-Release Fertilizer Mandates:State-level nutrient management plans in California and Florida require enhanced-efficiency formulations, accelerating potassium nitrate substitution for conventional potassium chloride in vegetable and fruit production systems.
- Hydroponic Infrastructure Expansion:Greenhouse operators across Arizona and Texas are scaling soilless cultivation for year-round tomato and pepper output, creating concentrated demand for water-soluble, chloride-free nutrient solutions.
- Export-Oriented Horticulture:Mexico's Sinaloa and Baja California growing belts are expanding protected agriculture for US-bound fresh produce, driving localized potassium nitrate blending capacity to meet phytosanitary and quality specifications.
Market Restraints
- Potash Feedstock Volatility:Saskatchewan potash mining output fluctuations transmit directly into potassium nitrate production economics, compressing margin stability for North American processors.
- Caliche Ore Competition:Chilean nitrate deposit extraction delivers technical-grade material at structural cost advantages, limiting price elasticity for domestic manufacturers serving industrial applications.
- Oxidizer Classification Friction:OSHA and DOT handling requirements for potassium nitrate impose specialized storage infrastructure and transport routing constraints, elevating distribution costs relative to non-oxidizer fertilizer alternatives.
Strategic Opportunities
- Midwest Fertigation Retrofit:Corn Belt operations with existing center-pivot infrastructure represent underpenetrated conversion potential as growers replace foliar nitrogen with potassium-enriched drip applications.
- Carbon Intensity Benchmarking:Pending federal clean fuel standards may advantage domestic potassium nitrate producers with lower transport emissions versus imported alternatives, reshaping procurement criteria for sustainability-program retailers.
- Direct-to-Grower Digital Channels:Precision agriculture platforms enabling customized nutrient prescription and subscription fulfillment are bypassing traditional cooperative distribution, capturing margin from advisory-intensive specialty crop segments.
Industry Challenges
- Blending Equipment Capex Burden:Conversion to potassium nitrate-compatible bulk handling systems requires significant capital outlay for regional fertilizer terminals, slowing inventory buildout in secondary agricultural markets.
- Groundwater Monitoring Compliance:State-level wellhead protection programs mandate intensive nitrate leaching documentation, extending product registration timelines and field trial requirements for new formulation introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Potassium Nitrate Market |
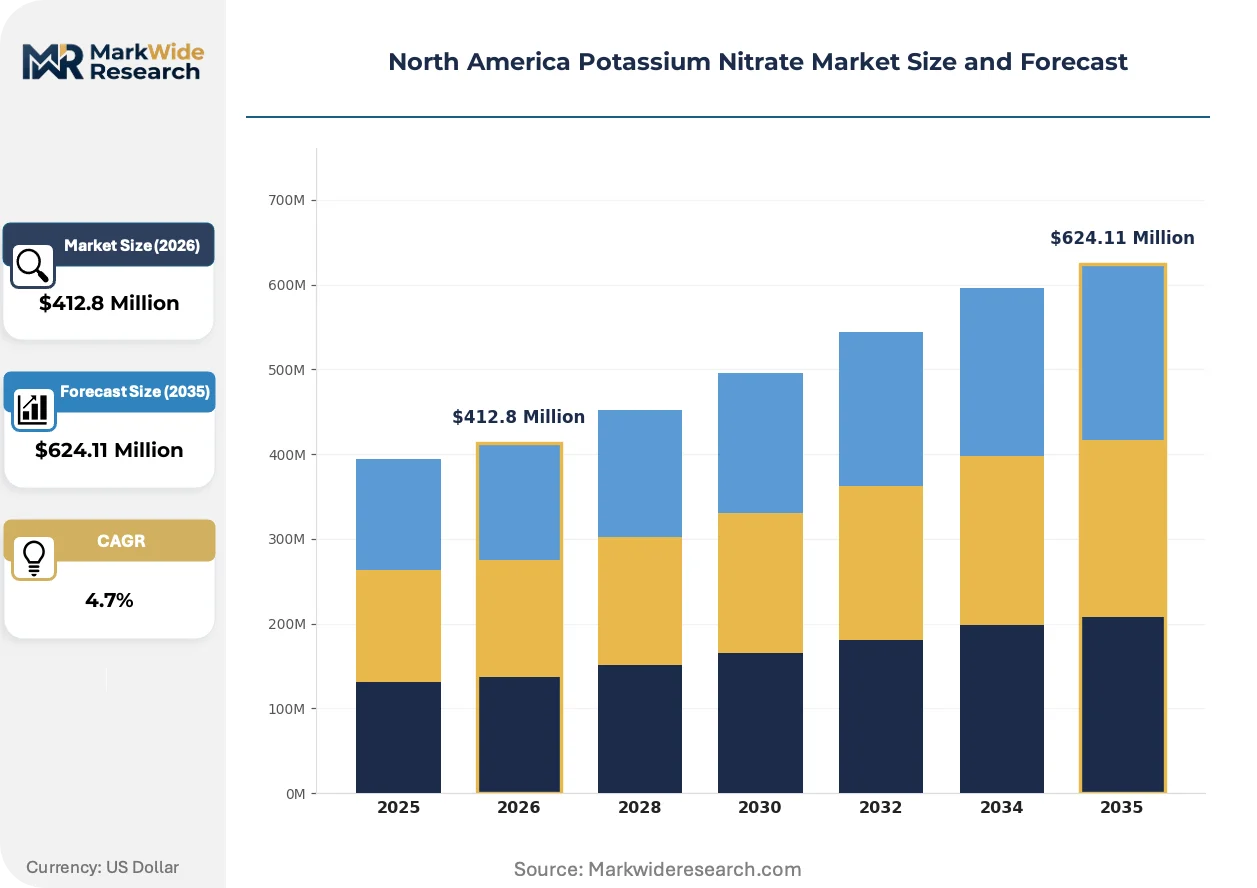
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $624.11 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Liquid, Prilled End Use Industry: Agriculture, Food Preservation, Chemical Manufacturing, Pharmaceuticals Application: Fertilizers, Explosives, Food Additives, Water Treatment Packaging Type: Bags, Bulk Containers, Drums, Pails |
| Companies Covered | Nutrien Ltd., Haifa Chemicals Ltd., SQM S.A., SNDB, AG CHEMI GROUP s.r.o., Yara International ASA, The Mosaic Company, KEMAPCO Arab Fertilizers & Chemicals Industries Ltd., Haifa Negev Technologies Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Potassium Nitrate Market Strategic Shifts & Innovations
Precision agriculture hardware and chloride-sensitive crop breeding are converging to reshape potassium nitrate specification requirements across North American specialty production systems.
Controlled-release coating technology is migrating from polymer-sulfur hybrid formulations to biodegradable starch-based encapsulation for potassium nitrate granules. Large-scale vegetable operations in California's Imperial Valley are piloting these coatings to synchronize nutrient release with peak fruit development stages. The technology is migrating from premium greenhouse applications to open-field row crops, compressing the price premium between enhanced-efficiency and conventional fertilizer grades.
The EPA's strengthened enforcement of Total Maximum Daily Load allocations under the Clean Water Act is mandating nitrogen and phosphorus runoff reductions from agricultural watersheds. This regulatory pressure is compelling Corn Belt growers to document nutrient use efficiency metrics, favoring potassium nitrate blends that demonstrate lower leaching potential in certified environmental management programs. Fertilizer retailers in Iowa and Illinois are responding by expanding technical agronomy staffing to support grower compliance documentation.
Consolidated produce buyers are imposing residue and quality certification requirements that cascade through their contracted growing operations. Large tomato and pepper processors in the Sacramento Valley now specify chloride-free nutrient protocols to prevent flavor profile contamination and meet export market standards. This buyer-driven specification shift is compressing traditional cooperative procurement patterns, with direct manufacturer relationships replacing multi-product distributor arrangements for premium horticulture inputs.
North America Potassium Nitrate Market Segmentation
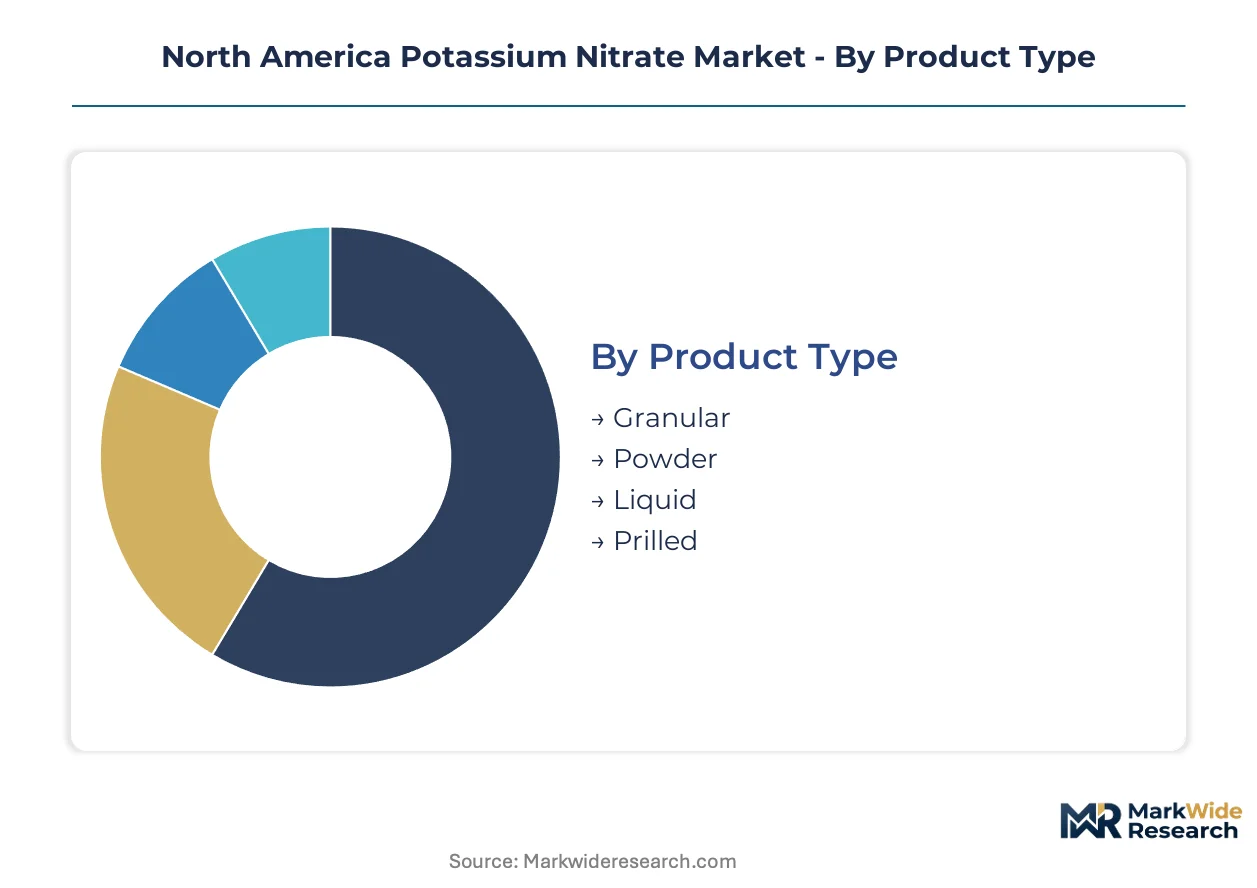
Potassium nitrate specification requirements diverge sharply across agricultural, industrial, and food-grade channels, with product form and purity thresholds determining accessible margin pools. Understanding these dimensional splits reveals where procurement concentration and pricing power concentrate across North American supply chains.
Product Type:
Physical form governs handling economics, dissolution rates, and end-use compatibility across fertilizer distribution and specialty chemical channels.
- Granular:Dense, free-flowing particles engineered for mechanical spreading equipment and bulk blending operations. Corn Belt cooperatives and California Central Valley distributors specify this grade for field-scale potassium supplementation in chloride-sensitive row crops, with particle size uniformity reducing segregation during pneumatic transport.
- Powder:Fine crystalline structure with rapid solubility kinetics. Food additive manufacturers and pyrotechnic compounders in the US Southeast and Midwest specify this grade where particle surface area governs reaction rates and dissolution speed, though dust containment infrastructure elevates handling costs relative to granular alternatives.
- Liquid:Pre-dissolved concentrate solutions for direct injection and fertigation systems. Greenhouse operators in Arizona and Texas hydroponic clusters favor this form for automated nutrient delivery, eliminating dissolution stage variability.
- Prilled:Spherical agglomerates produced through melt-prilling for controlled-release coatings. Specialty crop producers in Florida and Mexico's Sinaloa belt pilot these formulations for synchronized nutrient availability during peak fruit development windows.
Granular commands the established base. The steepest expansion runs through liquid formulations.
End Use Industry:
Industry verticals impose divergent purity, certification, and documentation requirements that filter supplier eligibility and contract structures.
- Agriculture:Dominant consumption channel spanning field crops, specialty vegetables, and protected cultivation systems. EPA Clean Water Act runoff restrictions and state nutrient management plans in California and Florida are redirecting procurement from potassium chloride toward nitrate-based alternatives in vegetable production zones.
- Food Preservation:Cured meat processors specify food-grade potassium nitrate for color retention and antimicrobial control in bacon, ham, and sausage production. USDA-FSIS labeling requirements and residual nitrite limits govern specification compliance, with domestic sourcing preferred for traceability documentation.
- Chemical Manufacturing:Industrial oxidizer applications including metal heat treatment salts and glass refining fluxes. OSHA Process Safety Management and DOT oxidizer classification impose handling infrastructure requirements that elevate delivered costs versus agricultural grades.
- Pharmaceuticals:USP-grade material for diuretic formulations and dental sensitivity products. FDA current Good Manufacturing Practice audits and elemental impurity testing per ICH Q3D limit eligible supplier pools to domestic and select European manufacturers.
Agriculture anchors volume throughput. Food preservation delivers the most concentrated premium realization.
Application:
Functional use case determines solubility, purity, and regulatory compliance thresholds across the value chain.
- Fertilizers:Primary demand driver encompassing base fertilization, side-dressing, and fertigation in chloride-sensitive cropping systems. California's Central Valley vegetable growers and Florida's sandy soil production zones specify potassium nitrate to prevent chloride accumulation that degrades fruit quality and soil microbiology.
- Explosives:Oxidizer component in blasting agents and propellants for mining and defense applications. ATF licensing and OSHA explosive materials handling requirements restrict distribution to qualified handlers, with domestic security concerns favoring North American sourcing over import alternatives.
- Food Additives:Preservative and color-fixative functions in processed meat categories. FDA 21 CFR 172.160 specifications and state-level cured meat processing standards govern permissible applications, with clean-label trends pressuring substitution toward celery powder alternatives in premium product lines.
- Water Treatment:Corrosion inhibition and oxygen scavenging in industrial boiler and cooling systems. Power generation facilities in the US Southwest specify this application for compatibility with high-purity water requirements in combined-cycle plants.
Fertilizers dominate tonnage flows. Food additives capture the highest unit value realization.
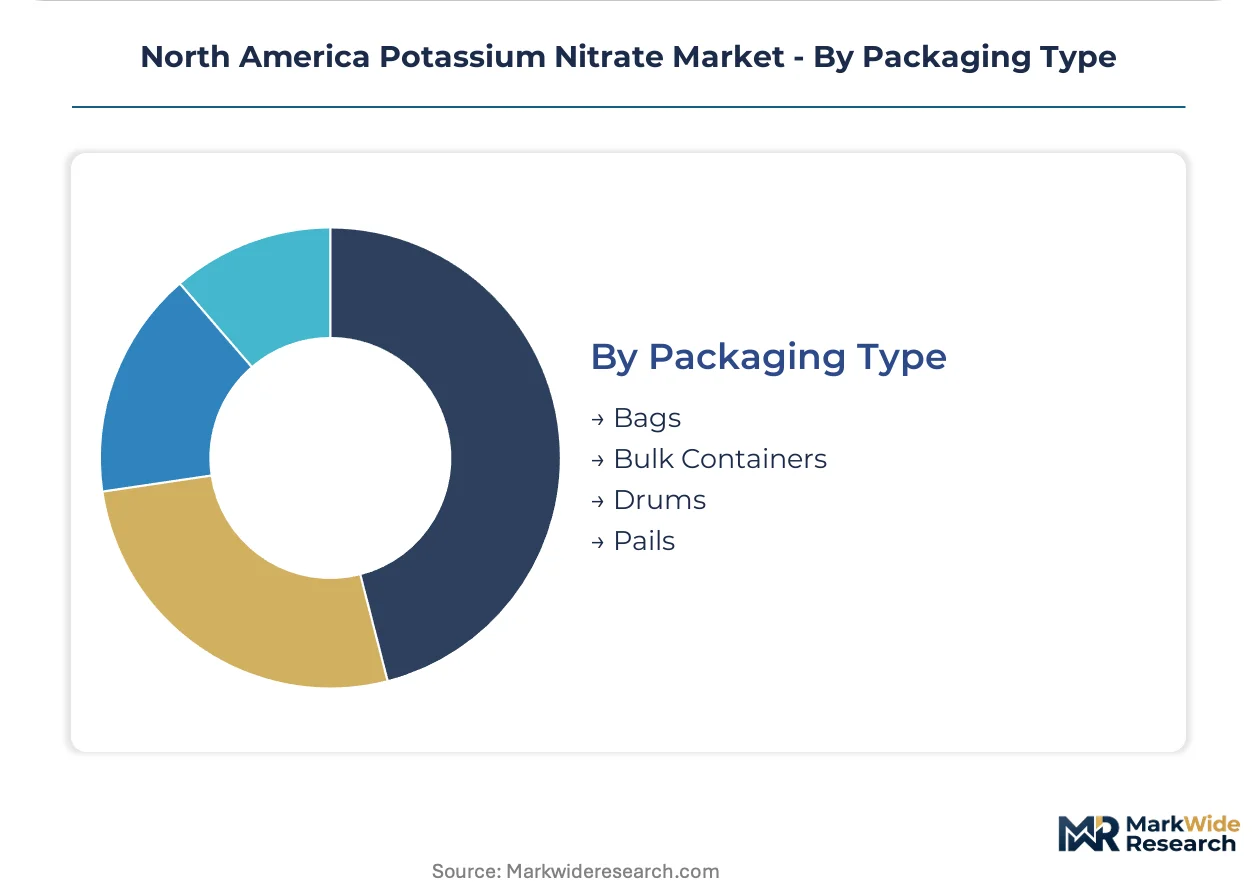
Packaging Type:
Container configuration aligns with customer scale, handling infrastructure, and oxidizer classification compliance requirements.
- Bags:Multi-wall paper or woven polypropylene sacks for 25-50 kg agricultural and food-grade distribution. Retail cooperatives and small-scale greenhouse operators in Texas and Mexico's Baja California prefer this format for inventory flexibility and manual handling compatibility.
- Bulk Containers:Flexible intermediate bulk containers and bulk bags for 500-1000 kg agricultural shipments. Large vegetable processors in California's Imperial Valley and grain elevators in the Corn Belt specify this format for mechanical unloading and reduced packaging waste.
- Drums:Steel or fiber drums for 100-200 kg industrial and pharmaceutical grades. Chemical manufacturers and explosives blenders require UN-certified containers for oxidizer classification compliance during ground transport.
- Pails:5-20 kg plastic containers for laboratory, pharmaceutical, and specialty food applications. Compounding pharmacies and artisanal meat processors specify this format for moisture protection and precise inventory control.
Bulk containers lead agricultural volume. Bags retain the broadest customer reach across segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the North American trade bloc. The United States prioritizes specialty fertilizer formulations for chloride-sensitive row crops. Mexico concentrates on export-oriented horticulture blending capacity. Canada channels production through integrated potash-to-nitrate processing corridors.
United States
The U.S. Corn Belt and California Central Valley drive divergent demand profiles. EPA Clean Water Act Total Maximum Daily Load enforcement compels Iowa and Illinois growers toward enhanced-efficiency potassium nitrate blends. Nutrien Ltd. dominates Prairie-to-Midwest supply corridors through its Saskatchewan potash mining integration.
Mexico
Baja California and Sinaloa protected agriculture belts supply year-round tomatoes and peppers to U.S. retail chains. Mexican regulators under SADER enforce phytosanitary protocols that favor chloride-free nutrient specifications. Local blending capacity expansion targets just-in-time delivery for export-oriented greenhouse clusters.
Canada
Saskatchewan potash deposits anchor upstream feedstock security for North American nitrate production. Environment and Climate Change Canada nutrient management frameworks restrict prairie agricultural runoff, indirectly validating potassium nitrate substitution economics. Alberta and Manitoba distribution terminals handle bulk granular flows for cross-border agricultural supply.
North America Potassium Nitrate Market Key Industry Players
Capability concentration sits with specialty formulation specialists; scale advantage sits with integrated mining-to-distribution conglomerates. The market structures around three tiers: upstream potash extractors with captive nitric acid access, midstream blenders serving regional agricultural cooperatives, and downstream precision agriculture formulators targeting greenhouse operators. Dominant competitive moves include backward integration into potash mining and forward integration into direct-to-grower digital advisory platforms.
Within the integrated mining tier, Nutrien Ltd. and The Mosaic Company exemplify scale-driven upstream control over Saskatchewan potash deposits. Specialty formulation archetypes include Haifa Chemicals Ltd. and SQM S.A., which occupy positions emphasizing water-soluble grades and caliche ore extraction economics respectively. Yara International ASA represents the diversified nitrogen-major portfolio approach spanning commodity and premium fertilizer segments.
| Leading Market Players |
|---|
| Nutrien Ltd. |
| Haifa Chemicals Ltd. |
| SQM S.A. |
| SNDB |
| AG CHEMI GROUP s.r.o. |
| Yara International ASA |
| The Mosaic Company |
| KEMAPCO Arab Fertilizers & Chemicals Industries Ltd. |
| Haifa Negev Technologies Ltd. |
| Others |
Cost & Logistics Intelligence
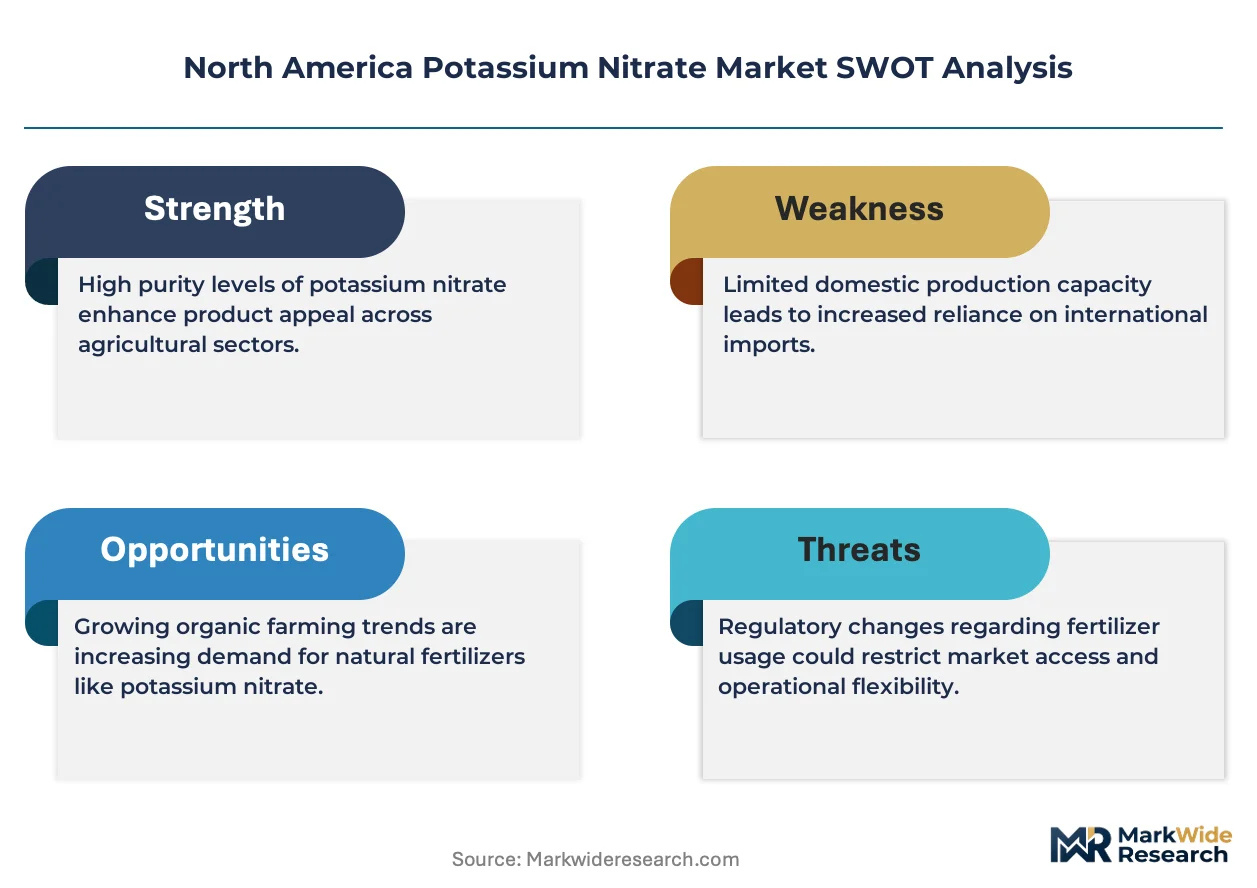
Saskatchewan potash mining concentration anchors upstream feedstock economics, directing margin capture toward integrated producers with captive nitric acid capacity while forcing independent blenders into price-taker positions across Corn Belt distribution corridors.
Pricing Analysis
Long-term offtake contracts dominate procurement between Saskatchewan extractors and Midwest agricultural cooperatives, insulating volume commitments from spot potassium chloride volatility. Price differentiation rests on chloride-free certification tiers and fertigation-grade solubility specifications, with greenhouse operators in Arizona and Texas showing least sensitivity due to crop value density. Cost compression in standard agricultural grades is intensifying because Chilean caliche ore imports exert structural pressure on technical-grade quotations.
Supply Chain Analysis
Tariff exposure between Chile and the United States elevates landed cost uncertainty for SQM S.A. technical-grade material competing against domestic nitric-acid-processed alternatives. Supply concentration in Canada, Chile, and Israel shapes raw material security, with production drawing from potash deposits, caliche ore, and Dead Sea brine extraction respectively. Single-source vulnerability in Saskatchewan rail corridors poses concentrated logistics risk. Distribution runs through cooperative elevator networks and direct-to-grower digital platforms serving specialty crop segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American potassium nitrate demand sits in early-cycle expansion as EPA Clean Water Act enforcement accelerates chloride-free fertilizer substitution across Corn Belt watershed compliance programs.
For Market Incumbents: Harden backward integration into Saskatchewan potash mining to secure feedstock margin capture against Saskatchewan output volatility. Expand blending capacity in Baja California and Sinaloa to preempt Mexican horticulture localization. Defensive positioning against Chilean caliche ore cost advantages requires premium formulation differentiation in water-soluble and controlled-release grades. For New Entrants and Emerging Players: Build out direct-to-grower digital advisory platforms targeting Arizona and Texas greenhouse operators with customized nutrient prescription capabilities. The most penetrable white space sits in Midwest fertigation retrofit for existing center-pivot infrastructure, where technical agronomy support gaps create subscription service opportunities. Go-to-market execution should anchor on precision agriculture hardware integration partnerships. For Investors and Strategic Acquirers: Capital is best deployed toward specialty formulation specialists with USP-grade certification and established FDA audit trails serving pharmaceutical and premium food additive segments. Long-term viability across the analysis window favors assets with dual agricultural-industrial grade flexibility. The signal to watch is federal carbon intensity benchmarking implementation, which would structurally advantage domestic producers with lower transport emission profiles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Potash Mining | Captures upstream margin pools and insulates against Saskatchewan supply volatility. |
| Controlled-Release Coating Technology Investment | Addresses California and Florida regulatory mandates for enhanced-efficiency formulations. |
| Direct-to-Grower Digital Platform Launch | Bypasses cooperative distribution to capture advisory-intensive specialty crop margins. |
| Mexico Blending Capacity Expansion | Secures just-in-time positioning for Baja California and Sinaloa export horticulture clusters. |
| Carbon Intensity Certification Program | Preempts federal clean fuel standard procurement criteria favoring lower-emission domestic sourcing. |
Research Approach
A standing panel of fertilizer procurement managers, greenhouse operations directors, EPA regulatory compliance officers, and agricultural cooperative agronomists provided ongoing calibration against operating reality. Primary fieldwork combined structured interviews with secondary validation through USDA NASS crop production surveys, EPA Clean Water Act enforcement records, SEC 10-K filings from integrated producers, and Canadian potash export statistics. Bottom-up volume modeling triangulated against top-down macroeconomic demand projections.
Scenario-bracketing across regulatory enforcement intensity, potash feedstock cost bands, and adoption curve assumptions framed the projection horizon. Segmentation dimensions modeled include product form, end-use industry, application function, and regional production cluster. CAGRs derived from historical volume trajectories adjusted for structural shift elasticities, with industry-specific inputs incorporating chloride-sensitive crop acreage expansion and hydroponic infrastructure deployment rates.
Stress conditions across Saskatchewan mining output disruptions, Chilean peso exchange rate volatility, and EPA enforcement acceleration timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory trajectory and technology adoption. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Wax Additives Market
Additives
Antiknock Agents Market
Additives
Antimicrobial Ingredients Market
Additives
Ultraviolet Light Stabilizer Market
Additives
Glycol Acetate Market
Additives
Sodium Metabisulfite Market
Additives
Amino Acids Premixes Market
Additives
Biofuel Additives Market
Additives
Global Calcium Formate Market
Additives
Driveline Additives Market
Additives
Performance Minerals Additives Market
Additives
Tire Additives Market
Additives
Foundry Additives Market
Additives
Global Ester Gum Market
Additives
Thermal Conductive Additives Market
Additives
Volatile Corrosion Inhibitors Market