
 Europe Biometrics Market | 2026-2036
Europe Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Biometrics Market Intelligence
Project finance for large-scale national ID infrastructure is tilting competitive dynamics toward vendors capable of underwriting multi-year government contracts. NEC Corporation leverages its deep integration with Japanese parent-company R&D pipelines to sustain technology leadership in multimodal systems. IDEMIA anchors its position through manufacturing scale across French and Czech production facilities. Thales Group competes by controlling defense-adjacent channels that extend into civilian biometric applications.
Biometrics encompasses the automated measurement and statistical analysis of unique physiological or behavioral characteristics—fingerprint minutiae, facial geometry, iris patterns, or vein structures—used to establish or verify human identity with measurable false acceptance and false rejection rates. The primary commercial purpose centers on replacing or supplementing token-based and knowledge-based authentication with inherence factors that resist transfer, sharing, or theft. Fingerprint recognition occupies the most mature margin pool, with established sensor cost curves and standardized interoperability frameworks driving commoditization at the hardware layer. Facial recognition represents the fastest-expanding technology segment, propelled by contactless user experience demands and algorithmic advances in liveness detection. Cloud-based delivery modes are displacing on-premises architectures in banking and retail end-user segments, though government and healthcare buyers retain hybrid deployments for data sovereignty reasons.
The EU AI Act imposes risk-classification obligations on biometric identification systems, with EMA coordination on healthcare data governance and national data protection authorities enforcing GDPR Article 9 restrictions on special-category processing. CE marking under the MDR framework shapes product standards for biometric components integrated into medical devices. Stakeholders must monitor evolving conformity assessment pathways as the AI Act's implementing acts crystallize enforcement timelines and technical documentation requirements.
Market Dynamics
The EU AI Act's risk-classification regime for biometric identification systems is forcing vendors to rearchitect product roadmaps around privacy-preserving computation and on-device processing capabilities. Compliance timelines compress as national data protection authorities begin coordinated enforcement under GDPR Article 9.
Growth Catalysts
- Schengen border modernization:Fingerprint and facial recognition deployments at entry points drive hardware refresh cycles across 27 member states. Procurement budgets consolidate under Frontex-coordinated frameworks.
- MDR CE marking pathways:Biometric components integrated into medical devices gain clearer conformity assessment routes. Device manufacturers accelerate biometric authentication integration for patient identification.
- Contactless user experience mandates:Post-pandemic hygiene protocols persist in banking and retail. Facial and iris recognition displace card-based and PIN-based authentication at physical access points.
Market Restraints
- Silicon sensor supply concentration:Fingerprint sensor fabrication depends on Taiwanese and South Korean foundry capacity. Geopolitical friction exposes European integrators to input volatility.
- GDPR Article 9 processing restrictions:Special-category data classification triggers enhanced consent requirements and data protection impact assessments. Implementation variance across France's CNIL, Germany's BfDI, and Netherlands' AP creates compliance fragmentation.
- Algorithmic audit costs:EU AI Act high-risk system obligations mandate third-party conformity assessment. Documentation and testing burdens scale disproportionately for mid-tier vendors.
Strategic Opportunities
- Polish and Romanian national ID modernization:These member states lag German and French digital identity maturity. Tender pipelines for next-generation eID systems open through 2028.
- Privacy-enhancing technology convergence:Federated learning combined with homomorphic encryption enables biometric matching without central data storage. Healthcare and financial services pilot cross-border implementations.
- Cloud sovereignty frameworks:Gaia-X and national cloud initiatives create procurement preferences for EU-hosted biometric processing. Vendors with French, German, or Dutch data center presence capture public-sector preference.
Industry Challenges
- Multimodal systems integration complexity:Combining fingerprint, facial, and iris recognition with liveness detection requires rare cross-functional expertise spanning computer vision, hardware engineering, and cryptography.
- Legacy identity infrastructure interoperability:National ID systems built on 1990s-era smart card architectures resist seamless biometric overlay. Migration projects face extended certification timelines under eIDAS frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Biometrics Market |
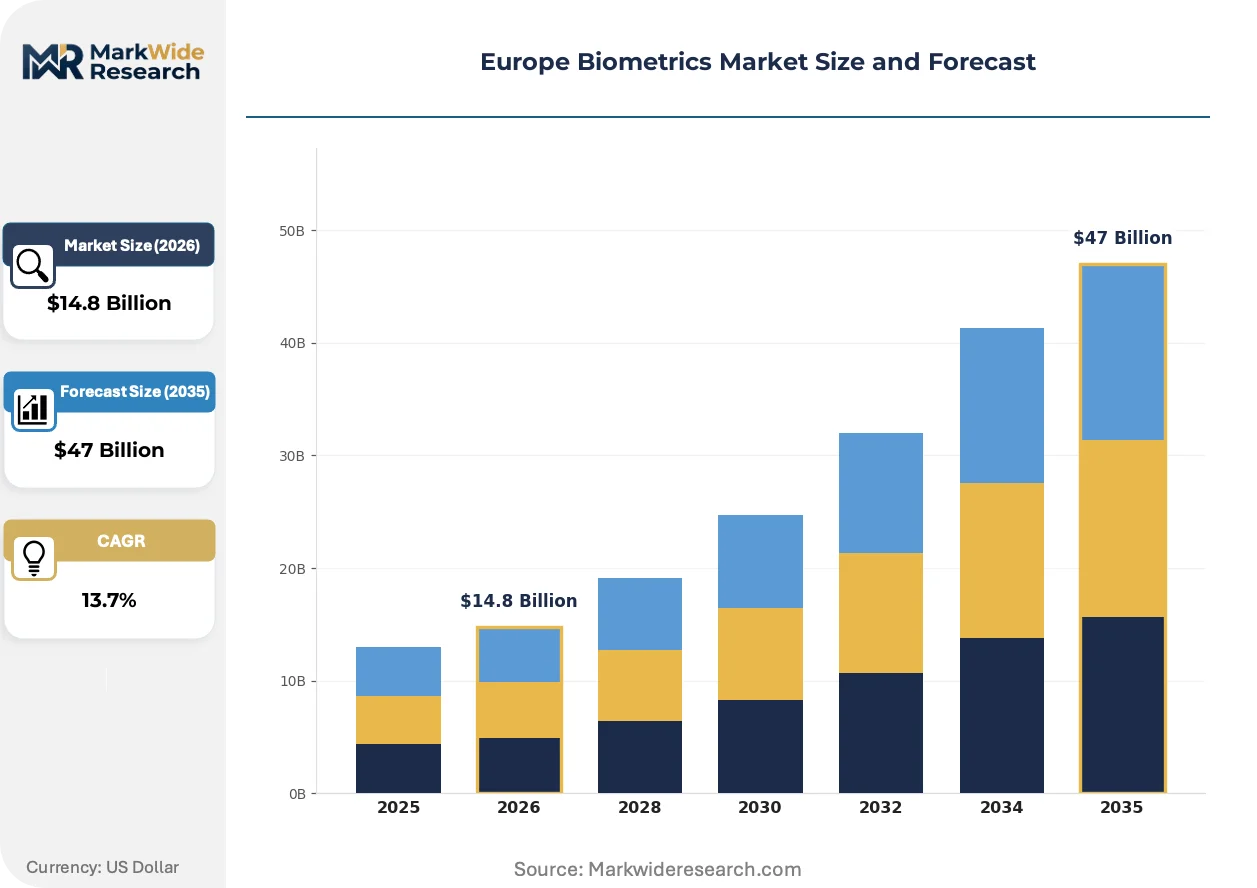
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $47 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Access Control, Time & Attendance, Identity Verification, Border Security Technology: Fingerprint Recognition, Facial Recognition, Iris Recognition, Vein Recognition End User: Government, Healthcare, Banking, Retail Delivery Mode: Cloud-based, On-premises, Hybrid, Mobile |
| Companies Covered | NEC Corporation, Innovatrics, Veridos GmbH, HID Global Corporation, DERMALOG Identification Systems GmbH, IDEMIA, Fujitsu, Fingerprint Cards AB, Thales Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Biometrics Market Strategic Shifts & Innovations
Edge-based biometric processing architectures are displacing cloud-dependent workflows as data minimization principles harden into enforceable design requirements. Algorithmic efficiency gains enable on-device template matching without accuracy degradation.
Presentation attack detection using multispectral imaging is collapsing the hardware cost premium between consumer-grade and enterprise-grade facial recognition systems. Banking and retail deployers now specify liveness detection as standard rather than premium tier. The compression erodes vendor pricing power at the mid-market segment.
The EU AI Act's implementing acts are crystallizing technical documentation requirements for biometric identification systems. High-risk classification triggers mandatory third-party conformity assessment through notified bodies designated under MDR frameworks. German and French healthcare biometric deployments face the steepest compliance ramps as national regulators coordinate with EMA on data governance.
Public-sector buyers are consolidating vendor relationships around multi-year framework agreements with embedded service-level commitments. Small and mid-sized biometric integrators lose access to national ID tenders as procurement thresholds rise. The concentration favors vendors capable of underwriting decade-long maintenance and algorithm update obligations across Germany, France, and Netherlands deployments.
Europe Biometrics Market Segmentation
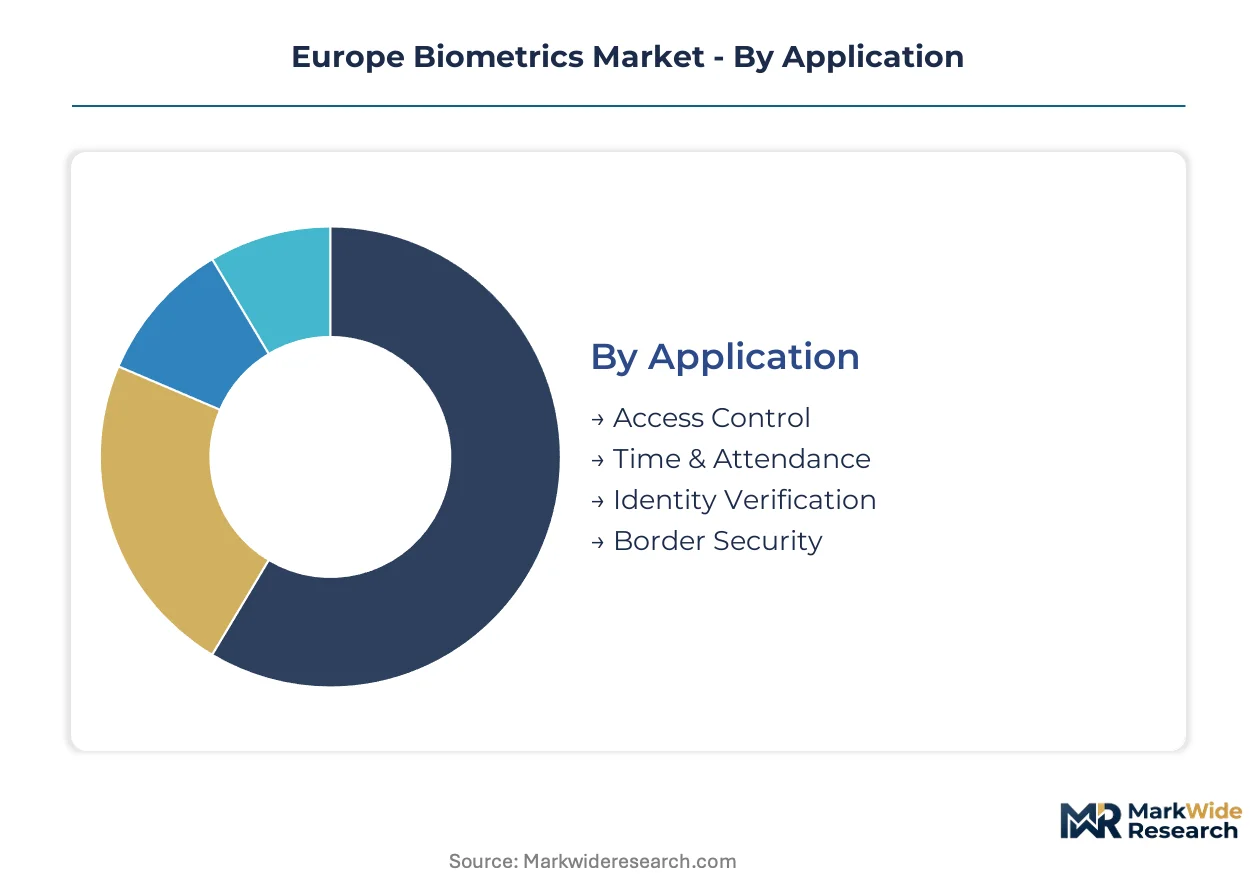
Biometric deployment patterns across Europe diverge sharply by operational context, with after-sales service intensity varying from decade-long government maintenance contracts to rapid-turnover retail installations. Understanding these segment-specific service obligations illuminates vendor profitability structures and competitive positioning.
Application:
After-sales service intensity peaks in installations requiring continuous algorithm updates and hardware lifecycle management, particularly where regulatory compliance mandates periodic recertification.
- Access Control:Physical entry systems for corporate campuses and critical infrastructure facilities require biometric readers with anti-spoofing capabilities. German industrial facilities and French transportation hubs drive replacement demand as legacy card systems reach end-of-life.
- Time & Attendance:Workforce management systems integrate fingerprint or facial terminals with payroll infrastructure. Polish manufacturing clusters and Romanian logistics centers are deploying contactless alternatives to reduce hygiene concerns and buddy-punching fraud.
- Identity Verification:High-assurance authentication for digital service onboarding and in-person document validation. Netherlands banking consortia and Nordic digital identity schemes are standardizing multimodal verification protocols under eIDAS frameworks.
- Border Security:Automated gates and manual inspection points at Schengen external borders combine fingerprint, facial, and document biometric checks. Frontex-coordinated procurement consolidates vendor relationships across 27 member state entry points.
By volume, Access Control leads. By growth pace, Border Security is ahead.
Technology:
Cost tier stratification separates mature sensor technologies with depreciated R&D burdens from emerging modalities requiring sustained algorithm investment.
- Fingerprint Recognition:Capacitive and ultrasonic sensors capture ridge patterns and minutiae points for template generation. Commoditized hardware margins pressure vendors to differentiate through liveness detection software and integration services.
- Facial Recognition:Deep learning-based analysis of facial geometry enables contactless authentication at distance. Dutch airport deployments and German retail banking branches are expanding 3D camera infrastructure to support presentation attack resistance.
- Iris Recognition:Pattern analysis of the colored ring surrounding the pupil offers high accuracy in controlled lighting conditions. Healthcare patient identification in France and secure facility access in Belgium sustain niche demand.
- Vein Recognition:Near-infrared imaging of subcutaneous vascular patterns provides internal biometric characteristics resistant to surface spoofing. Japanese vendor technology licenses are penetrating European financial services for high-security vault and data center access.
By installed base, Fingerprint Recognition dominates. By expansion trajectory, Facial Recognition is climbing the fastest.
End User:
Customer type determines procurement sophistication, with government buyers imposing extended liability terms and healthcare entities demanding clinical workflow integration.
- Government:National ID systems, voter registration, and law enforcement databases require biometric infrastructure with decade-long operational horizons. Germany, France, and Netherlands concentrate procurement for next-generation eID card personalization and border management platforms.
- Healthcare:Patient identification at admission and medication administration points reduces medical errors and insurance fraud. EMA-coordinated data governance and GDPR Article 9 compliance shape system architecture for hospital networks in Germany and France.
- Banking:Branch authentication and mobile onboarding workflows deploy facial and voice biometrics for customer verification. PSD2 strong customer authentication requirements drive replacement of legacy token-based systems.
- Retail:Loss prevention and frictionless payment applications experiment with facial recognition for loyalty program linking and automated checkout. GDPR consent management complexities constrain deployment scale compared to other sectors.
By contract value, Government leads. By pilot velocity, Healthcare is gaining share fastest.
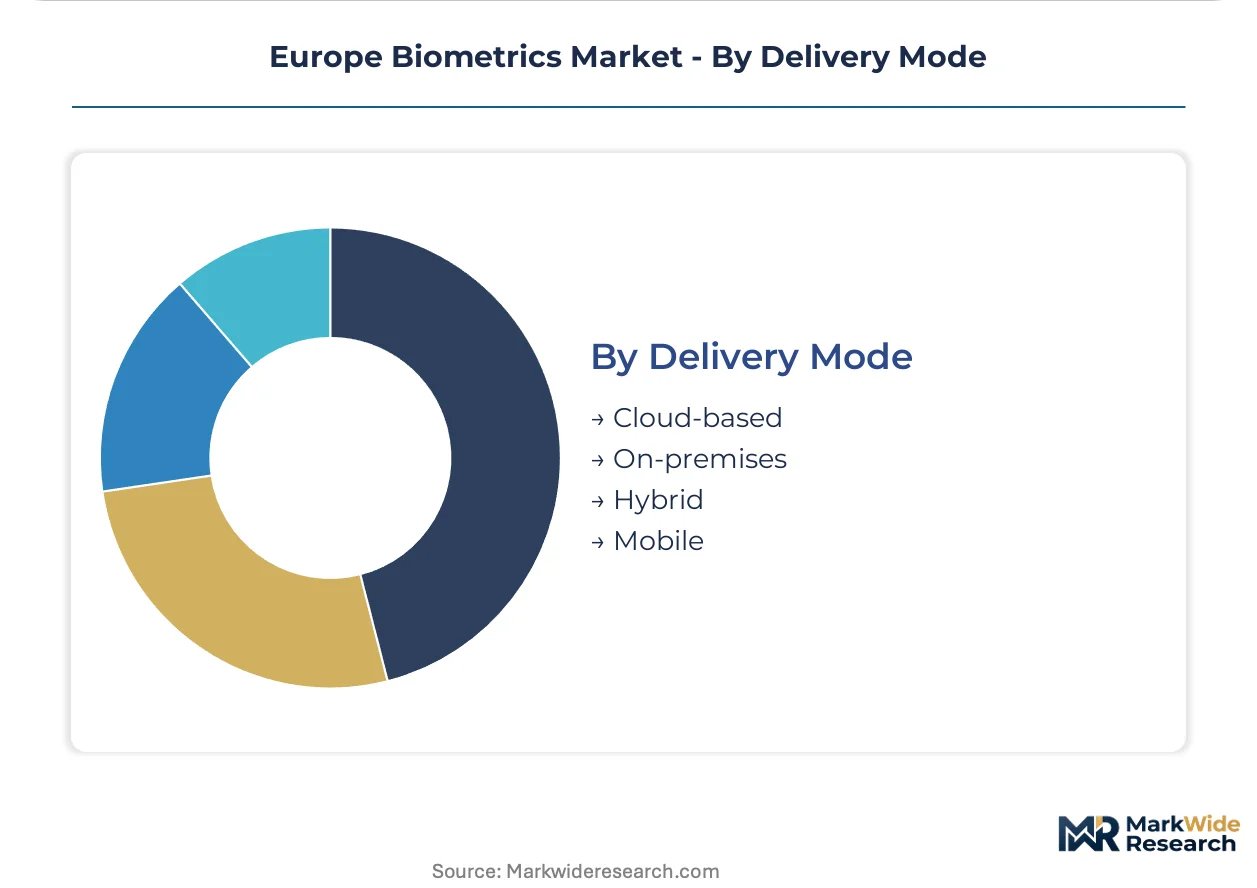
Delivery Mode:
Supply concentration in cloud infrastructure creates procurement preferences for vendors with EU-sovereign data center presence.
- Cloud-based:Biometric processing occurs in vendor-managed or customer-tenant cloud environments with API-based integration. Banking and retail segments in Netherlands and Ireland favor this model for operational flexibility.
- On-premises:Dedicated hardware and software installations within customer-controlled facilities satisfy data sovereignty requirements. Government and healthcare buyers in Germany and France retain this architecture for GDPR Article 9 compliance.
- Hybrid:Template storage on-device with matching logic distributed between edge and cloud tiers. Large enterprise deployments balance latency performance with centralized management needs.
- Mobile:Smartphone-embedded sensors and secure enclaves enable biometric authentication without dedicated peripherals. Digital identity wallets and financial services apps leverage native device capabilities.
By deployment count, On-premises leads. By shift momentum, Cloud-based is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe runs a modest biometric technology trade surplus, with German and French vendors exporting national ID systems to Middle Eastern and African governments while importing specialized sensor components from East Asian foundries. Import dependency concentrates in capacitive fingerprint modules and 3D camera arrays, whereas software and systems integration capabilities anchor domestic value capture.
Germany
BfDI enforcement of GDPR Article 9 shapes procurement specifications for federal police and healthcare biometric databases. The national eID card personalization program drives multi-year framework agreements with vendors capable of underwriting decade-long maintenance obligations. Bavaria's Munich-anchored industrial security cluster deploys vein recognition systems for high-assurance data center access.
France
CNIL's restrictive consent interpretation constrains retail facial recognition pilots while accelerating privacy-preserving architectures in banking. The ANSM coordinates with EMA on biometric patient identification standards for hospital networks. Paris-based defense contractors extend civilian biometric applications through dual-use technology transfer.
Netherlands
Schiphol Airport's automated border gates drive hardware refresh demand under Frontex-coordinated procurement. The AP's data protection impact assessment templates shape vendor documentation requirements across Benelux digital identity schemes. Eindhoven's semiconductor ecosystem supplies near-infrared imaging components for iris recognition systems.
Poland
National ID modernization lags German and French maturity, opening tender pipelines for next-generation eID card systems through 2028. Polish manufacturing clusters in Łódź and Silesia deploy contactless time-and-attendance terminals to reduce buddy-punching fraud. The national cyber security agency publishes biometric system certification guidelines aligned with EU AI Act risk classifications.
Belgium
Brussels hosts Frontex operational coordination, concentrating vendor relationship management for Schengen border infrastructure. Federal police biometric database consolidation drives middleware procurement for legacy system interoperability. Flanders' healthcare networks pilot federated learning architectures for patient identification without central data storage.
Europe Biometrics Market Key Industry Players
On the supply side, the industry is consolidating around vendors capable of underwriting multi-year government contracts with embedded algorithm update obligations. Three strategic archetypes dominate: Japanese conglomerates with deep R&D pipelines, European defense-industrial groups with dual-use civilian applications, and specialized biometric pure-plays with modular software architectures. Competitive moves center on framework agreement capture and privacy-preserving technology licensing.
Within the defense-industrial tier, Thales Group exemplifies channel control extending from military into civilian biometric applications. NEC Corporation anchors the multinational conglomerate archetype through parent-company R&D integration. IDEMIA occupies the European pure-play position with manufacturing scale across French and Czech production facilities.
| Leading Market Players |
|---|
| NEC Corporation |
| Innovatrics |
| Veridos GmbH |
| HID Global Corporation |
| DERMALOG Identification Systems GmbH |
| IDEMIA |
| Fujitsu |
| Fingerprint Cards AB |
| Thales Group |
| Others |
Cost & Logistics Intelligence
Eindhoven's semiconductor ecosystem anchors European near-infrared imaging component supply, with capacity allocation decisions at Dutch fabs directly shaping pricing power for iris recognition system integrators serving Belgian healthcare networks and German industrial security buyers.
Pricing Analysis
Government buyers anchor biometric system pricing through decade-long framework agreements bundling hardware, software licenses, and algorithm update subscriptions. Price differentiation separates CE-marked medical-grade installations from standard commercial access control tiers, with MDR certification commanding substantial premiums. Cost compression in fingerprint sensor hardware is intensifying because Taiwanese foundry capacity expansion outpaces European demand growth. Retail banking segments exhibit highest price sensitivity, while defense-adjacent civilian applications retain pricing resilience.
Supply Chain Analysis
TSMC and Samsung Foundry hold dominant capacity for capacitive fingerprint sensor ASICs, while Chinese module assemblers and South Korean camera module specialists concentrate 3D imaging component supply. Raw material dependencies span silicon wafers, near-infrared LEDs, and specialized optical glass. Single-source vulnerability in advanced node semiconductor fabrication exposes European integrators to geopolitical disruption. Distribution runs through authorized systems integrators with national security clearance rather than open channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's biometrics sector sits in early-cycle expansion, with EU AI Act compliance mandates forcing infrastructure replacement across member state border and healthcare systems that lag digital identity maturity.
For Market Incumbents: Harden market position by acquiring privacy-preserving computation specialists with homomorphic encryption capabilities, as EU AI Act high-risk system obligations threaten vendors lacking on-device processing architectures. Deepen backward integration into secure element manufacturing to reduce exposure to Taiwanese foundry concentration and capture margin from Gaia-X sovereign cloud procurement preferences. For New Entrants and Emerging Players: Establish a beachhead in Polish and Romanian national ID modernization tenders, where procurement thresholds have not yet consolidated around decade-long maintenance commitments from established vendors. Target federated learning pilot programs in Flanders healthcare networks as a go-to-market angle, positioning privacy-enhancing architectures as differentiated alternatives to centralized biometric databases. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with embedded algorithm update obligations in government framework agreements. Long-term viability across the projection horizon favors acquisition targets with notified body relationships under MDR frameworks and existing CE marking pathways. Monitor Frontex procurement consolidation announcements as the critical inflection signal for vendor market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-Preserving Architecture Development | EU AI Act high-risk classification mandates on-device processing for biometric identification systems. |
| Notified Body Partnership | MDR CE marking pathways accelerate hospital network procurement for patient identification solutions. |
| Gaia-X Cloud Certification | German and French sovereign data center presence captures public-sector procurement preference. |
| Multimodal System Integration | Combining fingerprint, facial, and iris recognition addresses Schengen border modernization requirements. |
| Framework Agreement Capture | Frontex-coordinated procurement consolidates vendor relationships across 27 member state entry points. |
Research Approach
Desk research of EU regulatory filings, EMA data governance guidelines, and Frontex procurement databases preceded structured interviews with biometric systems integrators, national data protection authority officials, hospital biomedical engineers, and defense procurement officers. Primary fieldwork with Dutch airport authorities, German federal police technology divisions, and French CNIL compliance teams was cross-validated against secondary sources including eIDAS framework documentation and MDR implementing acts. Bottom-up deployment estimates across application segments were triangulated with top-down market sizing from vendor revenue disclosures.
Assumptions held fixed include EU AI Act enforcement timelines and GDPR Article 9 interpretation stability across German BfDI, French CNIL, and Netherlands AP jurisdictions. The analytical framework modeled technology adoption curves across fingerprint, facial, iris, and vein recognition modalities, with deployment mode segmentation by cloud-based, on-premises, hybrid, and mobile architectures. CAGRs were derived from algorithm update subscription pricing trajectories and hardware refresh cycle compression in banking and retail segments. Inputs included Frontex infrastructure investment pipelines and national eID card personalization program schedules.
Stress conditions across Taiwanese semiconductor supply disruption, GDPR enforcement variance, and EU AI Act implementing act delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions with acknowledged sensitivity to geopolitical friction in East Asian foundry access. Quarterly review of Frontex procurement awards, CNIL consent interpretation bulletins, and BfDI enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Mobile Biometric Security and Services Market
Biometrics & Identity Management
Identity Theft Protection Services Market
Biometrics & Identity Management
Biometric Passport Market
Biometrics & Identity Management
Authentication Solution Market
Biometrics & Identity Management
Face Voice Biometric Market
Biometrics & Identity Management
Signature Verification Market
Biometrics & Identity Management
Airport Biometrics Market
Biometrics & Identity Management
Global Biometric-As-A-Service Market
Biometrics & Identity Management
Biometric Lockers Market
Biometrics & Identity Management
Fingerprint Biometrics Market
Biometrics & Identity Management
Asia Pacific Biometrics in Government Market
Biometrics & Identity Management
Biometric Bike Locks Market
Biometrics & Identity Management
GCC Biometrics Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Software Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Market
Biometrics & Identity Management
AI-Enabled Biometrics Market