
 Face Voice Biometric Market | 2026-2036
Face Voice Biometric Market Size, Share, and Industry Trends Forecast 2026-2036
Face Voice Biometric Market Insights
Multi-modal liveness detection is rotating toward the center of procurement specifications as enterprises reject single-factor vulnerabilities. NEC Corporation leverages its long-standing government relationships to sustain dominance in large-scale national ID deployments. IDEMIA anchors European banking infrastructure with certified presentation-attack-resistant terminals. Daon Inc. differentiates through cloud-native orchestration platforms that unify face and voice templates across mobile channels.
Face voice biometrics denotes integrated identity verification systems that capture, process, and match facial geometry with vocal characteristics using convolutional neural networks and mel-frequency cepstral coefficients, primarily to authenticate individuals in high-assurance access control and remote onboarding workflows. The multi-modal type category leads current revenue contribution by combining anti-spoofing resilience with user convenience, while cloud-based deployment architectures represent the fastest-growing structural segment as regulated industries abandon capital-intensive on-premises infrastructure. Edge computing deployments occupy a narrower but expanding niche where latency constraints and data sovereignty requirements intersect.
The US National Institute of Standards and Technology sets benchmark thresholds for face recognition accuracy through ongoing Face Recognition Vendor Test evaluations, directly shaping vendor qualification for federal contracts. The European Union AI Act imposes risk-tiered conformity obligations on biometric identification systems, forcing product redesigns for vendors seeking CE-marked market access. Stakeholders must monitor evolving cross-border data-localization mandates that threaten to fragment cloud-based biometric service architectures.
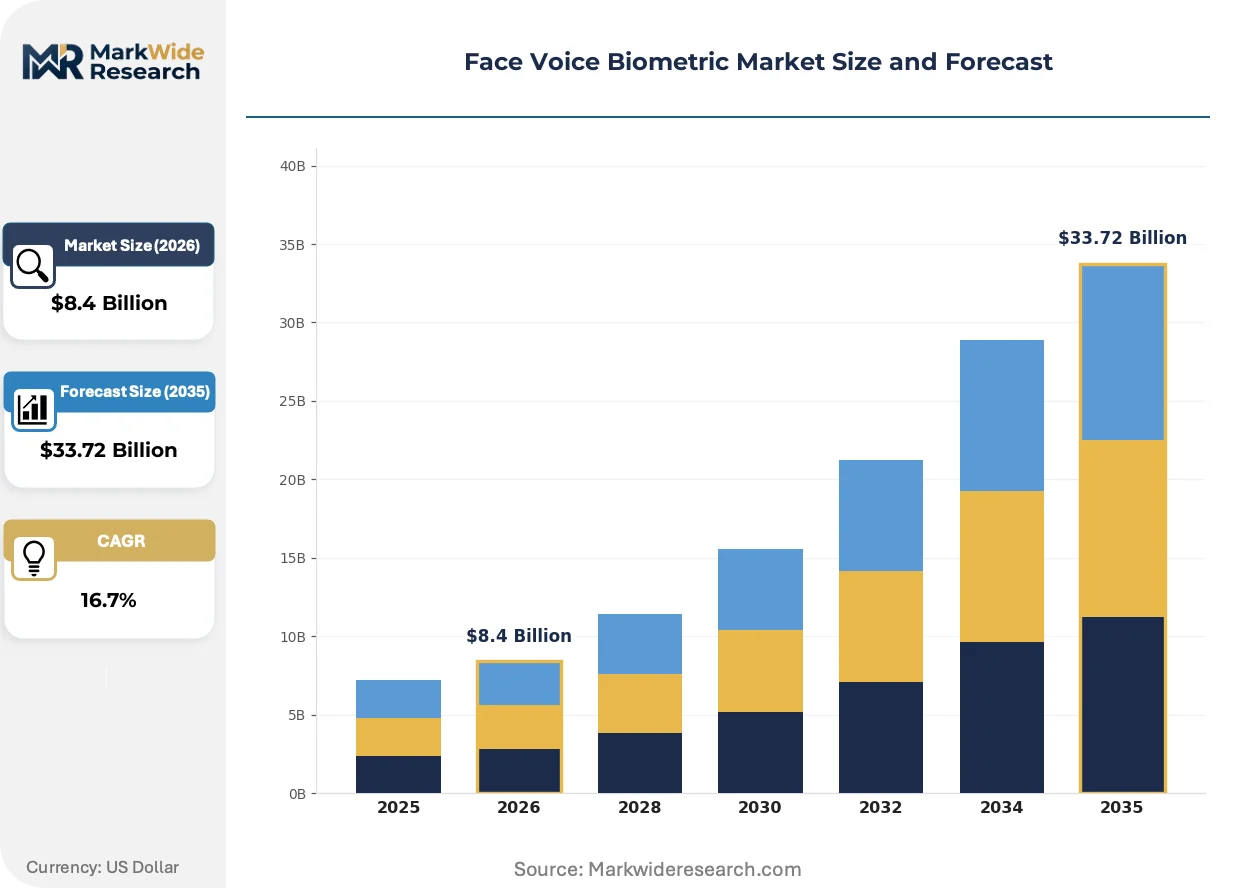
Market Dynamics
Multi-modal biometric fusion is compressing procurement cycles as financial institutions abandon single-factor authentication architectures in favor of liveness-certified face-voice orchestration platforms.
Growth Catalysts
- EU AI Act conformity mandates:Risk-tiered obligations on biometric identification systems are accelerating vendor redesigns for CE-marked market access across European banking infrastructure.
- Remote onboarding workflows:Digital-first customer acquisition in financial services is embedding face-voice verification as a default KYC checkpoint.
- Presentation attack resistance standards:NIST Face Recognition Vendor Test benchmarks are filtering vendor qualification for US federal identity modernization programs.
Market Restraints
- GPU compute cost volatility:Convolutional neural network training and inference workloads expose deployment economics to semiconductor supply fluctuations.
- Cloud concentration risk:Biometric template storage and matching services aggregate within a narrow set of hyperscale providers, creating systemic dependency.
- Cross-border data localization mandates:Fragmenting regulatory requirements threaten to partition unified cloud architectures into incompatible national silos.
Strategic Opportunities
- Edge computing convergence:Latency-sensitive access control deployments in critical infrastructure are driving on-device face-voice processing without cloud round-trips.
- Privacy-preserving architectures:Template-on-device and federated matching models align with GDPR and emerging data minimization frameworks.
- Healthcare access control:HIPAA-covered entities are piloting voice-biometric patient verification for telemedicine and prescription authentication workflows.
Industry Challenges
- Biometric systems integration expertise:Scarce engineering capacity for mel-frequency cepstral coefficient optimization and anti-spoofing algorithm tuning constrains deployment velocity.
- ISO/IEC 30107 certification timelines:Presentation attack detection evaluation protocols impose extended validation periods that delay product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Face Voice Biometric Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $33.72 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Contactless, Multi-Modal, Voice Recognition, Facial Recognition End User: Banking, Government, Healthcare, Retail Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Technology: Machine Learning, Deep Learning, AI Algorithms, Signal Processing |
| Companies Covered | NEC Corporation, Nuance Communications, Inc., Cognitec Systems GmbH, IDEMIA, Thales Group, Aware, Inc., IrisGuard Inc., Daon Inc., Sensory Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Face Voice Biometric Market Trends and Innovations
Architectural decisions around template storage, matching location, and liveness detection modality are compressing vendor differentiation into orchestration-layer capabilities rather than raw algorithmic performance.
On-device neural processing units are miniaturizing face-voice biometric pipelines that previously required server-grade infrastructure. Mobile banking applications in South Korea and Singapore are deploying these capabilities for real-time authentication without network dependency. This compression is displacing cloud-reliant architectures in latency-sensitive use cases while preserving template sovereignty.
The EU AI Act's prohibited-practices tier for real-time biometric identification in public spaces is forcing product architecture pivots toward consent-based, user-initiated verification workflows. Vendors are stripping always-on surveillance features from platforms destined for European deployment. Banking and enterprise access control segments are absorbing the bulk of compliance-driven redesign costs.
Buyer preference is rotating toward consumption-based licensing for biometric verification services rather than perpetual software licenses with maintenance fees. Financial services procurement teams in Germany and France are negotiating transaction-volume pricing with vendors. This shift compresses upfront capital requirements while aligning vendor incentives to authentication success rates.
Face Voice Biometric Market Segmentation
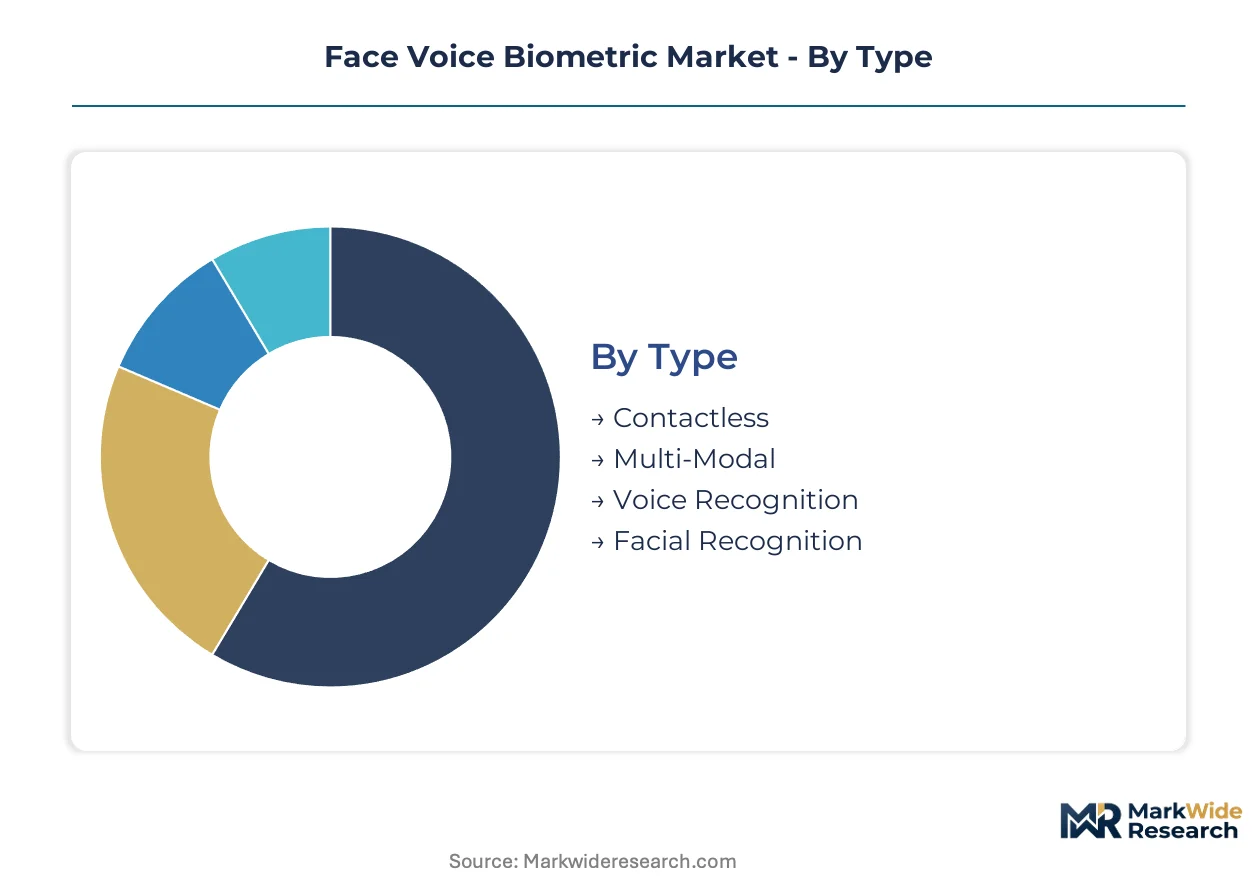
Segmentation in face voice biometrics reveals how procurement specifications diverge across risk tolerance, infrastructure maturity, and regulatory exposure. Buyers sort into distinct technology stacks based on whether their priority centers on presentation attack resistance, deployment agility, or template sovereignty.
Type:
Contactless systems face acute substitution pressure from multi-modal alternatives as single-factor architectures lose procurement eligibility in financial services.
- Multi-Modal:Fuses facial geometry with vocal characteristics through convolutional neural networks and mel-frequency cepstral coefficients. Banking institutions in the United States and Germany are mandating liveness-certified multi-modal stacks for remote onboarding workflows under NIST and EU AI Act compliance frameworks.
- Facial Recognition:Captures and matches facial geometry using deep convolutional architectures. Government identity modernization programs in the United States sustain demand despite EU restrictions on real-time biometric identification in public spaces.
- Voice Recognition:Isolates vocal characteristics for authentication without visual channels. Healthcare entities pilot this modality for telemedicine patient verification under HIPAA requirements.
- Contactless:Enables authentication without physical sensor contact. Retail access control deployments favor this format for throughput optimization in high-volume environments.
Multi-modal configurations anchor the volume base while edge-computing contactless variants gain share at the steepest rate.
End User:
Cost tier stratification separates banking and government deployments, which absorb premium-certified systems, from retail implementations prioritizing transaction economics.
- Banking:Demands presentation-attack-resistant terminals with ISO/IEC 30107 certification for KYC compliance. Financial institutions in France and Germany are negotiating consumption-based licensing tied to authentication success rates.
- Government:Requires large-scale national ID infrastructure with federal security accreditation. The United States sustains dominant procurement volumes through NIST Face Recognition Vendor Test-qualified vendor relationships.
- Healthcare:HIPAA-covered entities pilot voice-biometric verification for prescription authentication and telemedicine access control.
- Retail:Prioritizes frictionless customer experience over assurance tiering. South Korean and Singaporean mobile banking applications deploy on-device processing for real-time authentication.
Government contracts anchor the volume base while healthcare applications expand most quickly as telemedicine infrastructure matures.
Deployment:
Volume concentration in cloud architectures is fragmenting under data localization mandates that force geographic partitioning of biometric template storage.
- Cloud-Based:Centralizes template storage and matching within hyperscale infrastructure. Regulated industries are abandoning this model as cross-border data localization requirements threaten unified service architectures.
- Edge Computing:Executes face-voice processing on-device without network round-trips. Critical infrastructure access control in latency-sensitive environments drives adoption.
- Hybrid:Distributes processing between edge devices and cloud backends based on workload sensitivity. Financial services procurement teams favor this architecture for operational flexibility.
- On-Premises:Retains full infrastructure control within organizational boundaries. Government and defense sectors maintain this deployment mode for template sovereignty assurance.
Cloud-based deployments anchor the volume base while edge computing climbs the fastest as neural processing units miniaturize biometric pipelines.
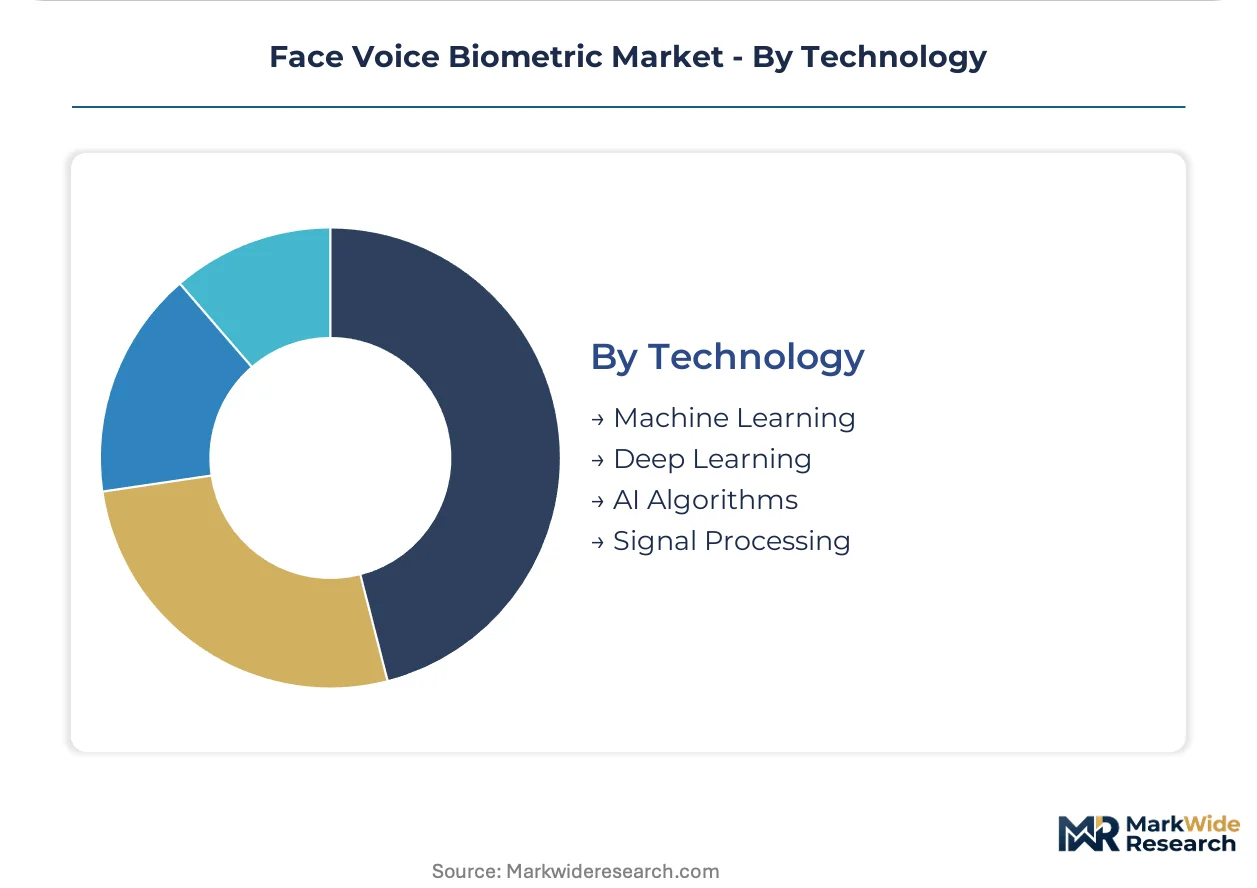
Technology:
Customer type differentiation separates enterprise buyers demanding interpretable signal processing from digital-native adopters prioritizing deep learning accuracy.
- Deep Learning:Deploys convolutional neural networks for feature extraction from facial and vocal inputs. GPU compute cost volatility exposes deployment economics to semiconductor supply fluctuations.
- Machine Learning:Employs classical statistical methods with lower computational requirements. Resource-constrained edge deployments retain this approach for on-device efficiency.
- AI Algorithms:Encompasses proprietary matching and liveness detection methodologies. Vendors differentiate at the orchestration layer rather than raw algorithmic performance.
- Signal Processing:Underlies mel-frequency cepstral coefficient extraction for voice biometric analysis. Scarce engineering expertise in this domain constrains deployment velocity.
Deep learning architectures anchor the volume base while federated AI algorithms gain share at the steepest rate under privacy-preserving design mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israeli biometric component suppliers export liveness-detection modules to German banking infrastructure integrators, while South Korean neural processing unit fabricators supply edge-computing chipsets for Singaporean mobile authentication platforms.
United States
NIST Face Recognition Vendor Test benchmarks filter vendor qualification for federal identity modernization contracts. The Department of Homeland Security's biometric exit program sustains procurement volumes for large-scale airport deployments. NEC Corporation and Daon Inc. anchor federal contractor relationships through Washington DC-area security infrastructure clusters.
Germany
EU AI Act risk-tiered conformity obligations force product redesigns for CE-marked market access. The Federal Financial Supervisory Authority (BaFin) mandates presentation-attack-resistant terminals for remote onboarding workflows. Frankfurt's banking technology corridor concentrates procurement negotiations for consumption-based licensing models.
Singapore
Monetary Authority of Singapore digital banking licenses embed face-voice verification as default KYC infrastructure. The Personal Data Protection Commission enforces data minimization frameworks that accelerate privacy-preserving architecture adoption. Marina Bay fintech clusters pilot on-device neural processing for real-time authentication without cloud dependency.
South Korea
Financial Services Commission open banking mandates drive multi-modal biometric procurement for digital-first customer acquisition. Korea Internet and Security Agency certification requirements shape liveness detection specifications for mobile channels. Seoul's semiconductor design ecosystem miniaturizes face-voice pipelines for smartphone-integrated neural processing units.
France
CNIL biometric data processing guidelines enforce strict purpose limitation and storage duration constraints. The French Banking Federation coordinates industry-wide standards for voice biometric enrollment in telephone banking workflows. Parisian cybersecurity clusters develop federated matching architectures that align with GDPR template sovereignty requirements.
Face Voice Biometric Market Competitive Landscape
Listed leaders compete with private specialists across government certification depth, with tier-one vendors sustaining dominance through NIST-qualified algorithm portfolios while mid-scale players capture share in cloud-native orchestration niches. The vendor base stratifies into three archetypes: legacy government contractors with federal security accreditation, banking infrastructure specialists with ISO/IEC 30107-certified terminals, and mobile-first platforms with edge-computing capabilities. Competitive moves concentrate on M&A for liveness detection IP and strategic partnerships with hyperscale cloud providers for template storage infrastructure.
Within the government contractor archetype, NEC Corporation occupies a position sustained through long-standing federal relationships, while IDEMIA anchors European banking infrastructure with presentation-attack-resistant terminal portfolios. Daon Inc. exemplifies the cloud-native orchestration tier, unifying face and voice templates across mobile channels without mandating on-premises infrastructure deployment.
| Leading Market Players |
|---|
| NEC Corporation |
| Nuance Communications, Inc. |
| Cognitec Systems GmbH |
| IDEMIA |
| Thales Group |
| Aware, Inc. |
| IrisGuard Inc. |
| Daon Inc. |
| Sensory Inc. |
| Others |
Pricing and Supply Chain Analysis
Neural processing unit substitution for server-grade GPU infrastructure simultaneously redraws semiconductor sourcing maps and compresses authentication-as-a-service pricing tiers across biometric verification platforms.
Pricing Analysis
Current-generation edge-NPU pricing sits at a 40-60% premium over prior-generation cloud-reliant licensing, while next-generation federated matching architectures command standard-tier rates. Three-tier pricing structure across premium, standard, and economy levels separates ISO/IEC 30107-certified multi-modal stacks from single-factor alternatives and unvalidated open-source toolkits. Pricing pressure stems from hyperscale cloud providers bundling biometric APIs into broader identity suites at marginal cost. Banking procurement teams in Germany exhibit highest price sensitivity due to consumption-based licensing negotiations, while US federal contractors absorb premium tiers for NIST-qualified algorithm portfolios.
Supply Chain Analysis
Taiwan Semiconductor Manufacturing Company fabrication capacity for neural processing units constitutes a chokepoint that gates global edge-computing biometric deployment velocity. South Korean memory fabricators and Israeli liveness-detection module suppliers anchor upstream concentration alongside Taiwanese foundries. GPU compute cost volatility and single-source vulnerability in advanced-node semiconductor fabrication expose deployment economics to geopolitical disruption. Distribution runs through systems integrators serving Frankfurt banking technology corridors and Washington DC-area federal security infrastructure clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Face voice biometrics sits in early-cycle expansion as EU AI Act compliance mandates force architectural redesigns across European banking infrastructure, accelerating replacement demand for legacy single-factor systems.
For Market Incumbents: Fortify NIST Face Recognition Vendor Test qualification depth against emerging cloud-native orchestration challengers by deepening ISO/IEC 30107 certification pipelines and securing exclusive federal contractor relationships. Vertical integration into on-device neural processing unit firmware development locks in latency-sensitive healthcare and critical infrastructure segments before hyperscale entrants capture template storage economics. For New Entrants and Emerging Players: Differentiate on privacy-preserving federated matching architectures that align with GDPR template sovereignty requirements and Singapore Personal Data Protection Commission data minimization frameworks. Healthcare voice-biometric verification for telemedicine workflows represents the most penetrable white-space segment, with HIPAA-covered entities piloting prescription authentication use cases lacking incumbent saturation. Target consumption-based licensing negotiations with French and German banking procurement teams seeking transaction-volume pricing alignment. For Investors and Strategic Acquirers: Capital is best deployed toward edge-computing specialists with on-device biometric pipeline IP and established Korea Internet and Security Agency certification pathways. Long-term viability across the next decade hinges on architectural positioning for data localization mandate fragmentation rather than unified cloud-scale aggregation. Monitor EU AI Act enforcement intensity and cross-border template storage rulings as the primary inflection signal for cloud versus edge investment allocation.| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 30107 Certification Investment | BaFin and NIST compliance frameworks filter vendor eligibility for banking and federal procurement. |
| Edge-NPU Firmware Development | Samsung and TSMC fabrication partnerships miniaturize biometric pipelines for smartphone-integrated authentication. |
| Consumption-Based Licensing Negotiation | Frankfurt banking technology corridors pilot transaction-volume pricing tied to authentication success rates. |
| Federated Matching Architecture Deployment | CNIL and GDPR template sovereignty requirements accelerate privacy-preserving design adoption across European deployments. |
| Healthcare Voice-Biometric Pilot Expansion | HIPAA-covered entities test prescription authentication workflows in telemedicine infrastructure buildouts. |
Research Methodology
Cross-validation between primary interviews with biometric systems integrators, federal procurement officers, and banking technology executives and secondary validation through NIST Face Recognition Vendor Test publications, EU AI Act regulatory filings, and SEC disclosures from listed biometric vendors anchors the qualitative findings. Bottom-up deployment volume estimates triangulate against top-down market sizing derived from hyperscale cloud provider identity service revenue disclosures and national ID program budget allocations.
Sensitivity analysis across GPU compute cost volatility scenarios, EU AI Act enforcement intensity assumptions, and cross-border data localization mandate adoption curves shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include authentication modality, deployment architecture, end-use vertical, and regional regulatory cluster. CAGR derivation rests on historical procurement cycle analysis and vendor pipeline visibility, with neural processing unit cost curves and presentation attack detection certification timelines as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU AI Act compliance investment and stable semiconductor supply conditions would require recalibration. Forecasts reflect documented assumptions regarding federal identity modernization program continuity and banking digital onboarding workflow penetration. Practitioners should keep alternative scenarios live as hyperscale cloud provider bundling strategies and edge-computing miniaturization trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Biometrics Banking Market
Biometrics & Identity Management
Signature Verification Market
Biometrics & Identity Management
Next Generation Biometric Market
Biometrics & Identity Management
Password Management Market
Biometrics & Identity Management
Asia-Pacific Government and Security Biometrics Market
Biometrics & Identity Management
Palm Vein Biometrics Market
Biometrics & Identity Management
Consumer Biometrics Market
Biometrics & Identity Management
Flash Calling Authentication Market
Biometrics & Identity Management
Europe Government and Security Biometrics Market
Biometrics & Identity Management
North America Biometrics in Government Market
Biometrics & Identity Management
Biometric Point-Of-Sale Terminals Market
Biometrics & Identity Management
Global Mobile User Authentication Market
Biometrics & Identity Management
Vein Recognition Biometrics Market
Biometrics & Identity Management
Global Voice Biometrics Market
Biometrics & Identity Management
Global Personal Identity Management Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Market