
 Global Wearable Security Device Market | 2026-2036
Global Wearable Security Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wearable Security Device Market Foresight
The gap between premium biometric-enabled wearables and basic alert devices is expanding as enterprise buyers split budgets between high-assurance identity verification and simple location tracking. Apple leverages its silicon integration to sustain encryption-grade security on wrist-worn form factors. Axon Enterprise anchors law enforcement demand through body camera ecosystems that dominate North American municipal procurement. Samsung Electronics competes across both consumer and B2B channels with Knox-hardened smartwatches.
Wearable security devices integrate sensors, wireless modules, and tamper-resistant enclosures into garments or accessories for real-time threat detection, identity authentication, and emergency signaling. Typical units incorporate accelerometers, GPS receivers, and Bluetooth Low Energy transceivers operating at 2.4 GHz with sub-10 meter positioning accuracy for personnel tracking and distress alerting. Smartwatches and body cameras capture the largest revenue pools today as corporate security and law enforcement end users consolidate spending on multi-function platforms. Fitness bands and panic buttons occupy faster-growing niches where educational institutions and lone-worker programs prioritize low-cost deployment at scale.
FCC certification governs radio frequency emissions for devices sold in the United States, while the EU AI Act and GDPR impose algorithmic transparency and data minimization rules on biometric wearables deployed across European member states. CE marking under the Radio Equipment Directive remains mandatory for market access, forcing non-European manufacturers to redesign cloud architectures to keep processing within regional boundaries. Stakeholders must monitor evolving encryption export controls and sector-specific procurement standards as national security agencies tighten supply chain vetting for connected personnel devices.
Market Dynamics
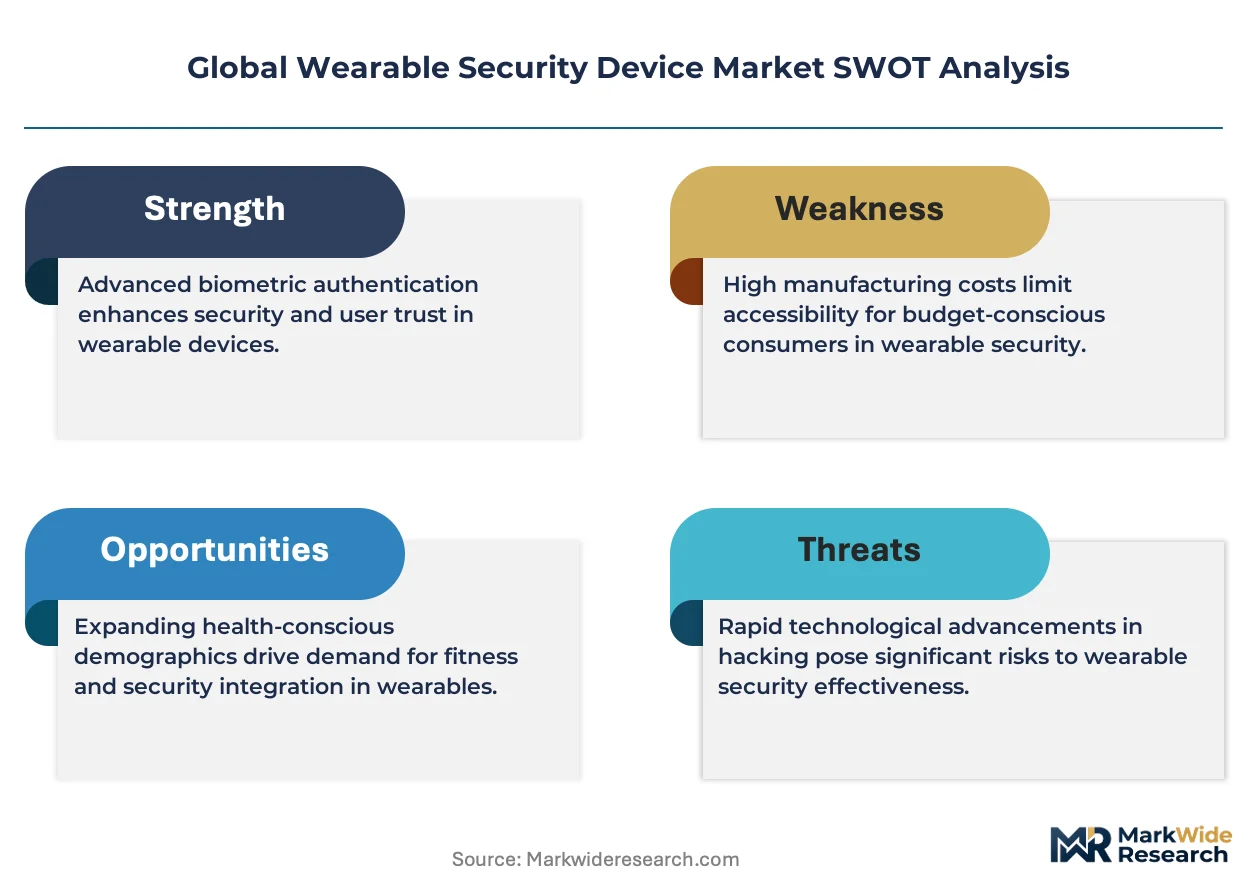
The EU AI Act and GDPR compliance requirements are compressing product development cycles as manufacturers re-architect biometric data processing pipelines to keep inference workloads within European territorial boundaries.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:The regulation forces biometric wearable vendors to document training data provenance and decision logic, creating competitive moats for firms with pre-compliant architectures.
- Lone-worker safety programs:Oil and gas, utilities, and logistics operators are mandating panic-button wearables for field personnel operating beyond visual range of supervisors.
- Silicon integration advances:System-in-package designs combining secure elements, neural accelerators, and RF frontends are shrinking board area requirements for wrist-worn form factors.
Market Restraints
- Lithium-polymer cell supply concentration:Over 70% of wearable-appropriate battery cells originate from Chinese manufacturing clusters, exposing procurement to export control volatility and shipping disruption.
- Biometric template storage costs:GDPR Article 9 special-category data requirements mandate encrypted-at-rest, segmented infrastructure that multiplies cloud hosting expenditure versus standard IoT workloads.
- Smartphone tethering dependency:Many alert devices lack standalone cellular modems, limiting utility in areas with poor Bluetooth coverage and constraining addressable use cases.
Strategic Opportunities
- India industrial safety expansion:The country's factory inspectorates are tightening enforcement of the Occupational Safety, Health and Working Conditions Code, creating first-time demand for connected worker devices in manufacturing plants.
- Edge AI inference on-wrist:Running biometric matching algorithms locally eliminates cloud round-trip latency for access control scenarios and reduces GDPR territorial compliance scope.
- Insurance-linked deployment models:Liability carriers are subsidizing panic button rollouts for home healthcare workers as risk mitigation instruments, opening enterprise-scale channels without direct municipal budget dependence.
Industry Challenges
- FCC Part 15 certification timelines:Radio equipment authorization queues for 2.4 GHz wearable transmitters are extending lead times, compressing launch windows for seasonal procurement cycles.
- Multi-jurisdiction data residency engineering:Architecting cloud backends that shard biometric templates across EU, US, and Asian sovereign zones requires specialized platform engineering talent in short supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wearable Security Device Market |
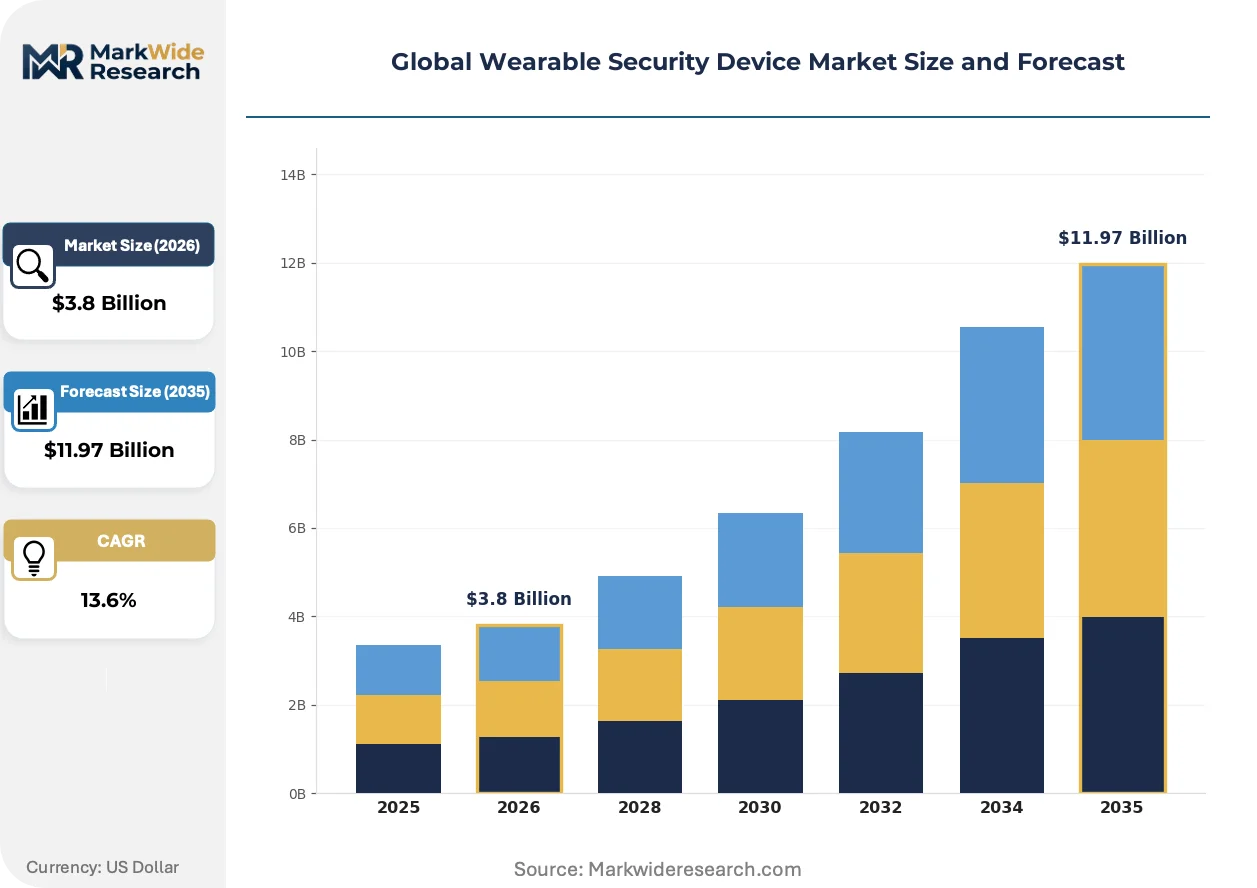
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.97 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Bands, Body Cameras, Smart Rings, Panic Buttons Technology: Bluetooth Low Energy, GPS, NFC, Wi-Fi, Cellular Connectivity End User: Corporate Security, Educational Institutions, Personal Protection, Law Enforcement Deployment Model: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | Axon Enterprise, Meta Platforms, Apple, Fitbit, Garmin, Samsung Electronics, GoPro, Safewave Technology, Google, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wearable Security Device Market Shifts & Advancements
Biometric authentication hardware is migrating from dedicated access control terminals onto personal wearables, collapsing the distinction between workforce identity credentials and consumer fitness accessories.
Ultrawideband (UWB) positioning chips are converging with secure-element microcontrollers to enable centimeter-accurate indoor location for lone-worker distress signaling without beacon infrastructure deployment. Mining operators in Australia and Canada are piloting these integrated modules for underground personnel tracking where GPS fails. The technology is converging with existing Bluetooth Low Energy ecosystems to create redundant location layers that satisfy both safety regulators and insurance underwriters.
The EU AI Act risk-classification framework is forcing biometric wearable vendors to maintain technical documentation repositories for high-risk system deployments. Law enforcement body camera vendors serving European municipal buyers must now submit conformity assessments to notified bodies before procurement eligibility. German and French interior ministries are conditioning multi-year framework agreements on demonstrated compliance with these documentation requirements.
Enterprise security departments are consolidating vendor relationships around multi-function platforms rather than procuring standalone panic buttons. Corporate buyers in the United States and South Korea are bundling biometric smartwatch contracts with existing mobile device management licenses, displacing single-purpose alert hardware from preferred vendor lists. This concentration favors suppliers with cross-certified enterprise mobility suites over specialized safety device manufacturers.
Global Wearable Security Device Market Segmentation
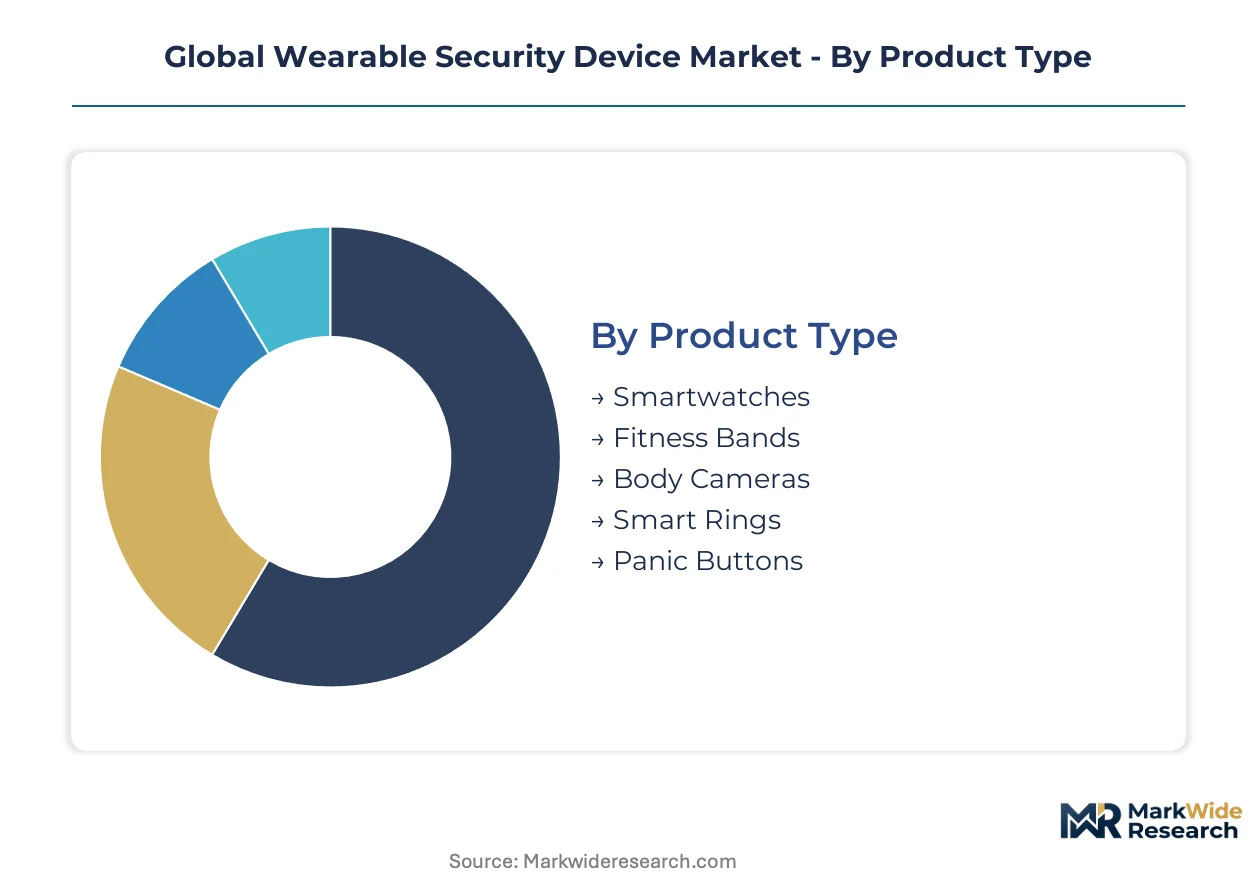
Wearable security devices fragment across four intersecting dimensions that determine procurement priorities and margin structures. Product form factors dictate sensor payload and battery economics, while deployment architectures separate enterprise buyers with compliance obligations from consumer purchasers prioritizing convenience.
Product Type:
Volume concentrates in wrist-worn devices with multi-function capability, while premium pricing attaches to specialized law enforcement hardware with evidentiary-grade encryption.
- Smartwatches:Knox-hardened and Apple silicon platforms dominate enterprise biometric authentication with on-wrist neural accelerators for local inference. Corporate security departments in the United States and South Korea bundle these with existing mobile device management licenses, displacing single-purpose hardware from procurement shortlists.
- Body Cameras:Evidentiary-grade encryption and tamper-resistant enclosures define municipal procurement specifications for officer-worn devices. North American law enforcement agencies anchor demand through multi-year framework agreements conditioned on FCC certification and chain-of-custody documentation.
- Fitness Bands:Low-cost accelerometer and heart-rate sensor packages serve educational institution budgets for student safety monitoring.
- Smart Rings:Compact NFC secure elements enable access control without wrist-worn form factor constraints for healthcare and cleanroom environments.
- Panic Buttons:Dedicated distress signaling hardware with GPS and Bluetooth Low Energy transceivers targets lone-worker programs in oil, gas, and logistics sectors where smartphone tethering fails.
Today's leader: Body Cameras. Tomorrow's challenger: Smartwatches.
Technology:
Connectivity choices trade positioning accuracy against power consumption and infrastructure dependency, with cellular modems commanding 3-4x the bill-of-materials cost of short-range alternatives.
- Bluetooth Low Energy:Sub-10 meter positioning accuracy at minimal power draw dominates indoor personnel tracking for corporate campuses and healthcare facilities. German industrial safety inspectors mandate redundant BLE layers for lone-worker compliance verification.
- GPS:Satellite-based outdoor positioning remains essential for field personnel in mining, utilities, and transportation sectors operating beyond visual range of supervisors.
- NFC:Contactless secure element communication enables physical access control integration without continuous power drain.
- Wi-Fi:Higher throughput supports body camera video offload in enterprise environments with dense access point coverage.
- Cellular Connectivity:Standalone LTE-M and NB-IoT modems eliminate smartphone tethering dependency for remote worker safety in Australian and Canadian mining operations.
Battery economics favor BLE and GPS combinations for volume deployment; cellular modules are climbing fastest as standalone reliability becomes non-negotiable for regulatory compliance.
End User:
Budget authority and compliance exposure separate enterprise purchasers with dedicated safety officers from individual consumers making discretionary trade-offs.
- Corporate Security:Multi-function platform consolidation around biometric smartwatches with mobile device management integration drives procurement in the United States and South Korea. GDPR Article 9 special-category data requirements multiply cloud hosting expenditure versus standard IoT workloads.
- Law Enforcement:Municipal framework agreements in Germany and France condition eligibility on EU AI Act conformity assessments for high-risk biometric systems.
- Educational Institutions:Cost-constrained deployments prioritize low-cost fitness bands and panic buttons for student and staff safety at scale.
- Personal Protection:Consumer discretionary purchases favor smartwatch form factors with cosmetic customization and fitness tracking cross-sell.
Enterprise buyers with compliance mandates control premium pricing; institutional volume is expanding most quickly as factory inspectorates in India tighten occupational safety enforcement.
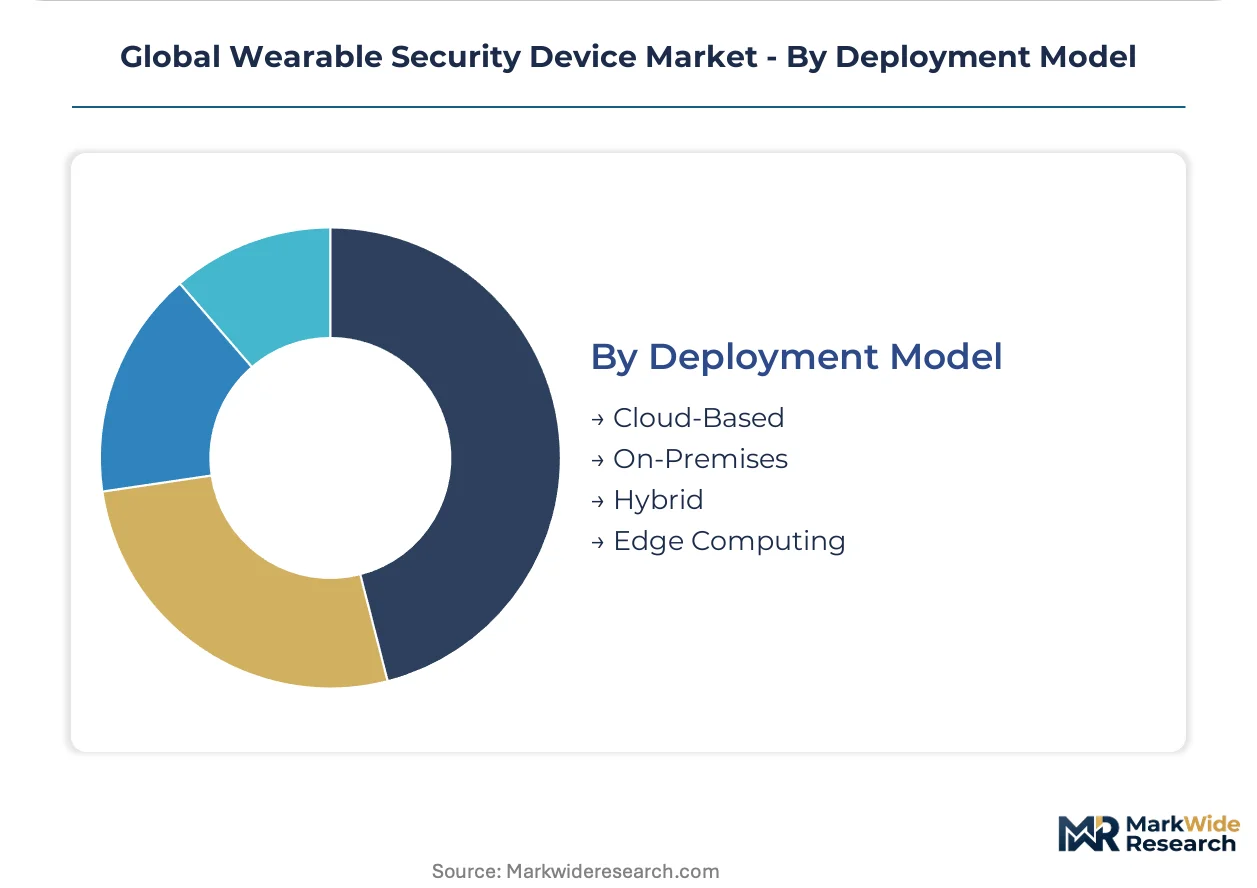
Deployment Model:
Data residency obligations and latency requirements push architectures toward distributed processing, with cloud concentration eroding among European buyers facing territorial compliance constraints.
- Cloud-Based:Centralized biometric template storage and inference reduces capital expenditure for mid-market corporate security buyers without dedicated IT infrastructure.
- On-Premises:Air-gapped systems serve national security agencies and critical infrastructure operators with supply chain vetting requirements for connected personnel devices.
- Hybrid:Tiered processing with local feature extraction and cloud verification balances GDPR territorial compliance against scalability for multi-national enterprises.
- Edge Computing:On-wrist neural accelerators eliminate cloud round-trip latency for access control and reduce compliance scope by keeping biometric matching local to the device.
Cloud architectures retain volume leadership; edge inference is gaining share fastest as EU AI Act and GDPR requirements compress development cycles for biometric data pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Workforce safety engineers in Houston and Munich anchor the largest procurement budgets for officer-worn and industrial field devices. Shenzhen electronics clusters supply the densest concentration of BLE module and secure element manufacturing for wrist-worn form factors.
United States
Municipal police departments in Chicago and Los Angeles drive body camera procurement through multi-year framework agreements. FCC Part 15 certification queues for 2.4 GHz transmitters are extending lead times for seasonal procurement cycles. Silicon Valley security engineering talent concentrates at Apple and Google campuses, accelerating on-wrist neural accelerator development.
Germany
Industrial safety inspectors in North Rhine-Westphalia mandate redundant BLE layers for lone-worker compliance verification. The EU AI Act forces biometric wearable vendors serving German interior ministries to submit conformity assessments to notified bodies. Munich-based automotive security teams are piloting UWB positioning chips for centimeter-accurate indoor personnel tracking.
South Korea
Corporate security departments in Seoul bundle biometric smartwatch contracts with existing mobile device management licenses. The MFDS regulates medical-grade biometric data processing for healthcare worker wearables. Samsung Electronics anchors Knox-hardened platform development in Suwon, displacing single-purpose alert hardware from enterprise shortlists.
Australia
Mining operators in Western Australia pilot integrated UWB and secure-element modules for underground personnel tracking where GPS fails. The country's national safety regulator enforces connected worker device mandates for remote field operations. Perth engineering consultancies specialize in edge AI inference architectures that eliminate cloud round-trip latency for access control.
India
Factory inspectorates in Maharashtra and Gujarat are tightening enforcement of the Occupational Safety, Health and Working Conditions Code, creating first-time demand for connected worker devices. BIS certification requirements for radio equipment are extending market entry timelines for foreign manufacturers. Bangalore IoT startups are developing low-cost panic button hardware for educational institution budgets.
Global Wearable Security Device Market Competitive Landscape
Top-tier vendors anchor municipal and enterprise procurement with end-to-end platform ecosystems, while mid-tier specialists compete on lone-worker safety niches and price-sensitive institutional segments. The vendor base splits between silicon-integrated consumer electronics giants and purpose-built security hardware fabricators. Three archetypes dominate: body camera ecosystem providers, Knox-hardened smartwatch platforms, and BLE-enabled panic button specialists. Competitive moves concentrate on mobile device management bundling and FCC certification acceleration.
Within the silicon-integrated tier, Apple and Samsung Electronics exemplify the shift toward on-wrist neural accelerators and encryption-grade security. Axon Enterprise occupies a distinct position anchoring law enforcement demand through evidentiary-grade hardware and chain-of-custody documentation. These three companies represent the divergent strategic paths—consumer platform extension versus purpose-built security specialization—that are compressing margins for standalone alert device manufacturers.
| Leading Market Players |
|---|
| Axon Enterprise |
| Meta Platforms |
| Apple |
| Fitbit |
| Garmin |
| Samsung Electronics |
| GoPro |
| Safewave Technology |
| Others |
Supply & Pricing Matrix
Secure-element firmware engineers in Shenzhen command wage premiums that widen the spread between economy-tier panic buttons and premium biometric smartwatches. Labor-cost differentials between Guangdong manufacturing clusters and European assembly facilities feed directly into three-tier pricing structures across the wearable security device industry.
Pricing Analysis
Bundled mobile device management licenses versus unbundled hardware-only procurement splits the market into divergent pricing models. Corporate security departments in the United States and South Korea favor subscription-integrated platforms with Knox-hardened or Apple silicon ecosystems, while Indian educational institutions prioritize per-unit transactional purchases of low-cost fitness bands. Price differentiation hinges on FCC certification grade and GDPR Article 9 compliance infrastructure, with cloud-hosting segmentation multiplying hosting costs for biometric template storage. Cost compression in the economy tier is intensifying because Bangalore IoT startups are flooding institutional channels with sub-certified hardware.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from municipal police departments and corporate security teams, while distributor networks serve fragmented educational and lone-worker segments. Manufacturing concentrates in China, South Korea, and Vietnam, with Shenzhen electronics clusters supplying BLE modules and secure elements while Suwon anchors Knox-hardened platform assembly. Lithium-polymer cells, neural accelerators, and UWB positioning chips constitute critical component dependencies. Single-source vulnerability in Chinese battery cell manufacturing exposes procurement to export control volatility. Distribution runs through enterprise mobility vendors and specialized safety equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk system classification for biometric wearables functions as a regulatory compounder, accelerating procurement cycles among European interior ministries and forcing conformity assessment investments that create competitive moats for pre-compliant vendors.
For Market Incumbents: Acquire edge AI inference IP to fortify on-wrist neural accelerator capabilities against cloud-dependent challengers. Samsung Electronics and Apple should expand FCC certification pre-clearance programs to compress seasonal procurement timelines for municipal police departments. Backward integration into secure-element manufacturing reduces exposure to Chinese component volatility while satisfying supply chain vetting requirements from national security agencies.
For New Entrants and Emerging Players: Insurance carriers represent the most underexploited channel partner type for subsidized panic button rollouts. Home healthcare worker programs in North America and lone-worker safety mandates in Indian manufacturing plants offer penetrable white-space targets. A reimbursement-linked deployment model bypasses direct municipal budget dependence and opens enterprise-scale channels without competing against incumbent MDM bundles.
For Investors and Strategic Acquirers: Enterprise mobility platform vendors are the most active acquirer in this space, consolidating biometric smartwatch capabilities into cross-certified suites. The five-to-ten-year viability window favors targets with demonstrated EU AI Act conformity assessment completion and FCC Part 15 certification acceleration capabilities. Watch for BIS certification timeline extensions in India as an inflection indicator for market entry cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Assessment Completion | Notified body approval unlocks German and French interior ministry framework agreements. |
| On-Wrist Neural Accelerator Integration | Local inference eliminates GDPR cloud residency scope and reduces round-trip latency. |
| FCC Certification Pre-Clearance Investment | Accelerated Part 15 authorization compresses lead times for seasonal procurement cycles. |
| Insurance-Linked Deployment Partnership | Liability carrier subsidies open home healthcare channels without municipal budget dependence. |
| UWB Positioning Module Development | Centimeter-accurate indoor tracking satisfies Australian mining safety regulator mandates. |
Research Methodology
Multiple input streams — procurement officer interviews at municipal police departments, regulatory affairs consultations with EU notified bodies, and supply chain mapping with Shenzhen electronics manufacturers — were reconciled against secondary validation from FCC equipment authorization databases, ETSI technical standards filings, and customs trade records. Conversations with corporate security directors, lone-worker safety program managers, biomedical engineers at MFDS-regulated healthcare facilities, and BLE module procurement leads informed demand-side assumptions. Bottom-up unit economics for wrist-worn form factors were cross-checked against top-down market sizing from enterprise mobility platform disclosures.
Historical shipment trajectories for body cameras and biometric smartwatches were cross-referenced against panel input from law enforcement procurement committees and industrial safety inspectors. The analytical framework models product type, connectivity technology, end-user vertical, and deployment architecture segmentation across the projection horizon. CAGRs were derived from elasticity-adjusted adoption curves for lone-worker safety mandates and EU AI Act compliance deadlines. Forecast inputs include BIS certification timeline assumptions for Indian market entry and lithium-polymer cell supply concentration risk weighting.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to export control volatility in Chinese battery manufacturing and evolving encryption export restrictions from national security agencies. Periodic stress-testing of base assumptions around GDPR territorial compliance scope and FCC authorization queue lengths is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
Asia-Pacific Data Center Physical Security Market
Physical Security
Bespoke Safe Rooms and Panic Rooms Market
Physical Security
Policing Technologies Market
Physical Security
Canada Data Center Physical Security Market
Physical Security
Poland Data Center Physical Security Market
Physical Security
France Data Center Physical Security Market
Physical Security
Physical Security Services Market
Physical Security
Malaysia Data Center Physical Security Market
Physical Security
Physical Security Equipment Market
Physical Security
Airport Full Body Scanner Market
Physical Security
Border Security Technologies Market
Physical Security
Security Market
Physical Security
Hong Kong Data Center Physical Security Market
Physical Security
Physical Security Market
Physical Security
Active Geofencing Market
Physical Security
Global Data Center Physical Security Market