
 Identity Theft Protection Services Market | 2026-2036
Identity Theft Protection Services Market Size, Share, and Industry Trends Forecast 2026-2036
Identity Theft Protection Services Market Intelligence
The gap between premium concierge restoration and automated commodity monitoring is repositioning how providers structure their offerings. NortonLifeLock Inc. leverages its bundled security ecosystem to anchor higher-margin subscription tiers. Experian Information Solutions, Inc. competes through deep credit data integration that sustains retention in the consumer segment. Aura differentiates via family-oriented coverage models that occupy a distinct niche between individual and enterprise plans.
Identity theft protection services encompass continuous monitoring of personal identifiers, financial accounts, and digital footprints to detect unauthorized use or data exposure. These systems employ automated surveillance of credit files, dark web forums, and public records, paired with alert protocols and restoration support when compromise occurs. Credit Monitoring and Dark Web Surveillance dominate current revenue pools, while AI Analytics represents the fastest-expanding technology dimension as machine learning improves anomaly detection velocity. Subscription-Based pricing captures the majority of recurring value, though Freemium models are gaining traction as customer acquisition tools in saturated consumer markets.
The US Federal Trade Commission enforces identity theft reporting standards, while state-level breach notification laws in California and New York mandate disclosure timelines that directly stimulate corporate purchasing of monitoring services. The EU GDPR and emerging AI Act frameworks impose data handling accountability that elevates demand for compliant protection infrastructure among multinationals. Stakeholders must weigh whether to build captive AI detection capabilities or partner with specialized vendors as regulatory complexity outpaces in-house expertise.
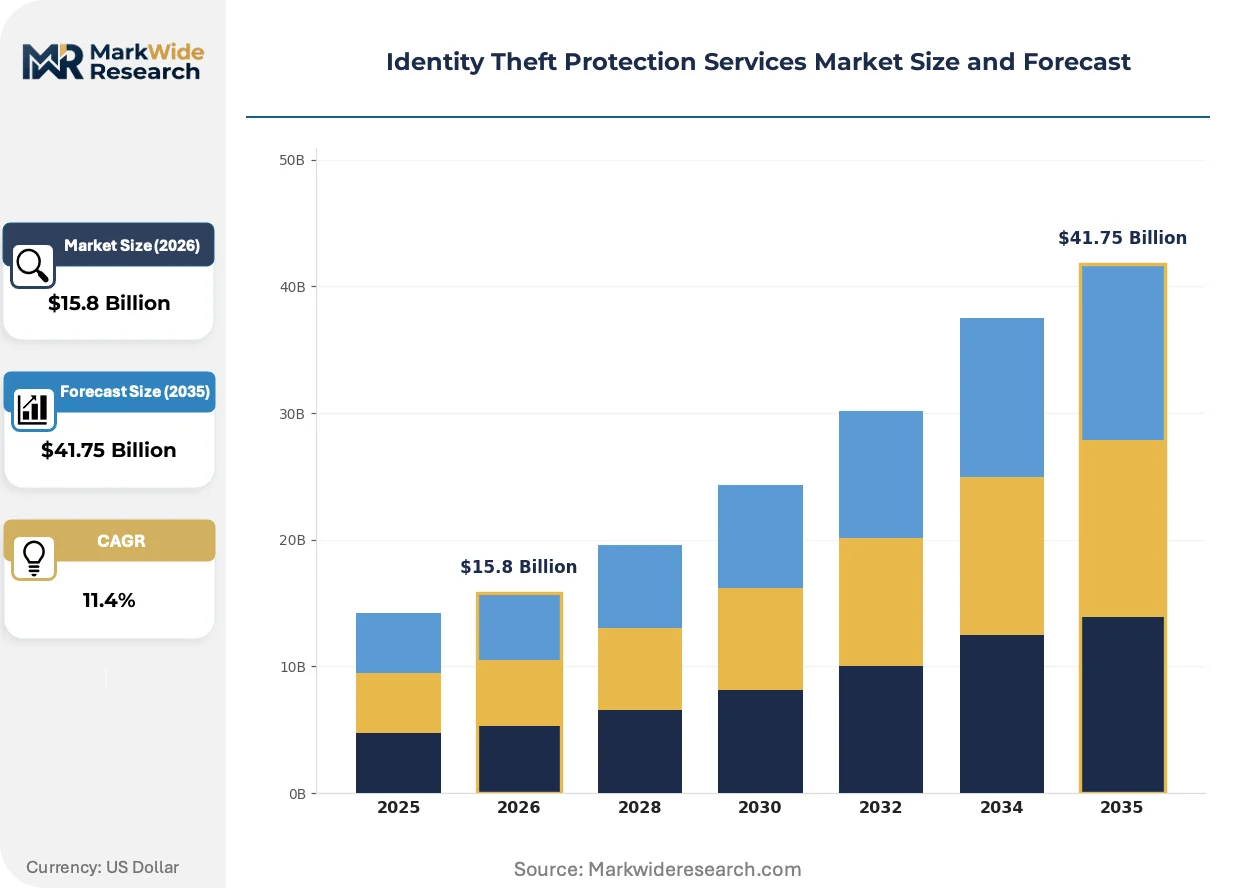
Market Dynamics
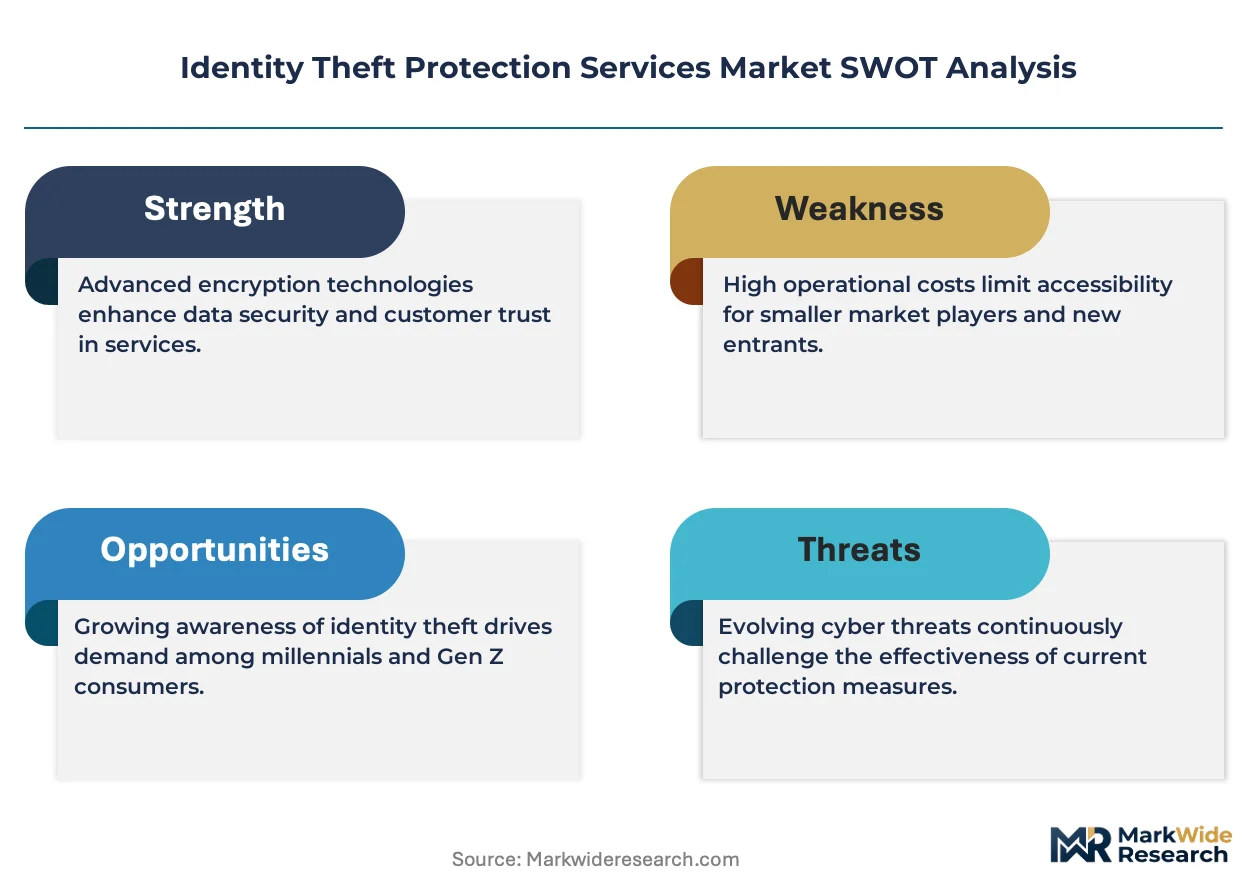
The Identity Theft Protection Services Market is undergoing structural compression as AI-driven detection capabilities force incumbents to rebuild their technology stacks around machine learning inference rather than rules-based monitoring. This technological pivot is redistributing competitive advantage toward providers with proprietary data assets and algorithmic training depth.
Growth Catalysts
- EU AI Act compliance mandates:Multinational enterprises operating across European markets must deploy auditable identity monitoring systems that satisfy algorithmic transparency requirements, creating procurement urgency for compliant infrastructure.
- Financial institutions:Banks and payment processors face escalating fraud losses from synthetic identity schemes, driving institutional subscription volumes for continuous credit file surveillance and behavioral anomaly detection.
- Dark web intelligence feeds:Real-time credential exposure monitoring has become table stakes for consumer-facing protection services, with automated breach notification protocols now expected by mainstream subscribers.
Market Restraints
- Data broker consolidation:The concentration of consumer credit data among three national repositories in the United States creates single-point-of-failure risk and limits competitive differentiation in credit monitoring features.
- GDPR data localization:European data residency requirements fragment operational scale, forcing providers to maintain redundant infrastructure across member states rather than centralizing analytics platforms.
- Free credit monitoring substitutes:Post-breach compensation packages and state-mandated disclosure offerings commoditize basic monitoring tiers, compressing entry-level pricing power.
Strategic Opportunities
- India digital identity expansion:The Aadhaar-linked financial inclusion wave creates addressable demand for first-time credit monitoring among newly banked populations previously outside formal identity protection markets.
- Biometric authentication convergence:Integration of facial recognition and behavioral biometrics with traditional credit surveillance enables premium tier differentiation through multi-factor compromise detection.
- Embedded insurance partnerships:Cyber insurance underwriters in the United Kingdom are bundling proactive monitoring services with policy issuance, opening B2B2C distribution channels outside direct consumer marketing.
Industry Challenges
- Machine learning engineering scarcity:Anomaly detection model development requires specialized talent pools concentrated in technology hubs, constraining in-house capability building for mid-tier providers.
- Legacy system interoperability:Enterprise clients demand API-native deployment, but established providers maintain monolithic architectures that complicate integration with modern security operations centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Identity Theft Protection Services Market |
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $41.75 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Credit Monitoring, Identity Restoration, Fraud Alerts, Dark Web Surveillance End User: Individuals, Small Businesses, Corporations, Financial Institutions Technology: AI Analytics, Blockchain, Cloud-Based Solutions, Multi-Factor Authentication Pricing Model: Subscription-Based, One-Time Fee, Freemium, Tiered Pricing |
| Companies Covered | NortonLifeLock Inc., LifeLock, Aura, Experian Information Solutions, Inc., TransUnion LLC, Equifax, Inc., IdentityForce, McAfee, LLC, Identity Guard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Identity Theft Protection Services Market Strategic Shifts & Innovations
Artificial intelligence is reconstructing how identity protection services detect, verify, and respond to compromise events. The shift from periodic credit pulls to continuous behavioral surveillance is compressing detection latency from weeks to minutes.
Behavioral biometrics is modularizing across financial services deployments. Fingerprinting of typing cadence, swipe patterns, and device interaction signatures enables passive authentication without friction. Major card issuers are embedding these capabilities into mobile banking applications. This modularization is collapsing the distinction between fraud prevention and identity protection, forcing service providers to reposition as integrated risk management platforms rather than standalone monitoring vendors.
The EU AI Act's risk classification framework is restructuring product development roadmaps for providers serving European multinationals. High-risk automated decision systems must maintain human oversight protocols and algorithmic audit trails. Identity verification services used for employment screening and credit decisions fall under these requirements. Providers are responding by building explainable AI layers that document decision rationale for regulatory examination.
Employer-sponsored benefits distribution is displacing direct-to-consumer acquisition as the primary growth channel in the United States. Human resources departments are adding identity protection to voluntary benefits menus alongside supplemental health and legal insurance. This channel shift alters unit economics, reducing customer acquisition costs while compressing margins through group pricing negotiations. The phenomenon is most pronounced among Fortune 500 employers with dispersed workforces requiring consistent protection across state jurisdictions.
Identity Theft Protection Services Market Segmentation
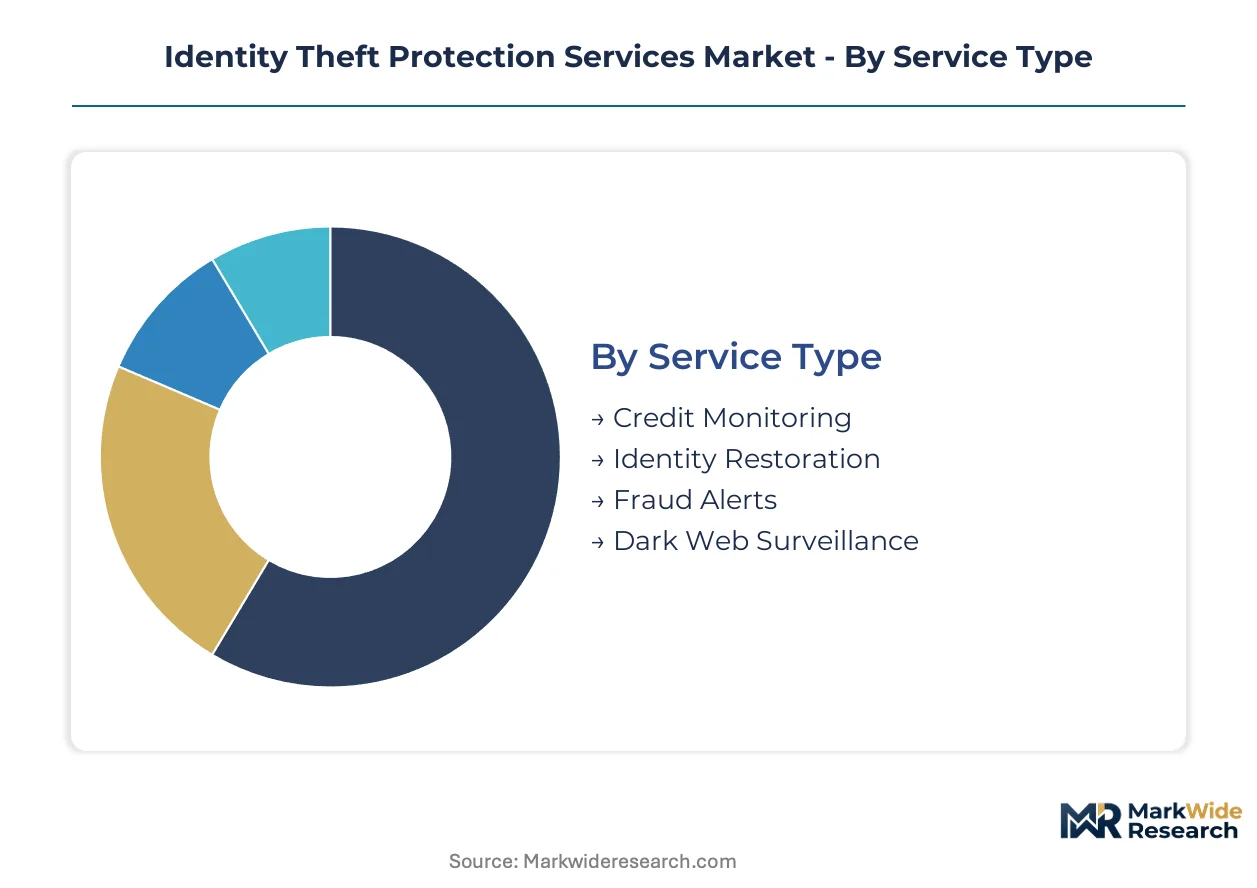
Service differentiation in identity protection hinges on automation depth versus human intervention. Providers calibrate their portfolios across detection velocity, restoration complexity, and price accessibility to capture distinct risk tolerance profiles.
Service Type:
Volume concentrates in automated surveillance tiers while premium restoration commands higher margins through dedicated case management.
- Credit Monitoring:Continuous scanning of credit bureau files for unauthorized inquiries, new account openings, and limit changes. Demand concentrates among US consumers responding to state breach notification mandates from California and New York regulators. FTC enforcement of reporting standards sustains baseline subscription volumes.
- Dark Web Surveillance:Automated crawling of underground forums, paste sites, and encrypted marketplaces for credential exposure. Financial institutions in the United States deploy this as standard fraud prevention infrastructure, driven by synthetic identity scheme losses.
- Identity Restoration:Hands-on recovery support including affidavit preparation, creditor negotiation, and credit file correction. Compact service layer with concentrated demand among high-net-worth individuals seeking concierge resolution.
- Fraud Alerts:Rapid notification protocols triggered by anomalous transaction patterns. Embedded within mobile banking applications by major card issuers as a retention mechanism.
Mature deployment sits with Credit Monitoring. Newer deployment is concentrated in Dark Web Surveillance.
End User:
Procurement authority separates consumer self-purchase from institutional mandate, reshaping sales cycle length and contract structure.
- Financial Institutions:Banks and payment processors require continuous behavioral surveillance and anomaly detection at enterprise scale. GDPR and EU AI Act compliance obligations across European operations elevate procurement urgency for auditable systems.
- Corporations:Employer-sponsored benefits distribution displaces direct acquisition, with human resources departments adding protection to voluntary benefits menus. Group pricing negotiations compress margins while reducing customer acquisition costs.
- Individuals:Direct-to-consumer subscriptions face pressure from free credit monitoring substitutes in post-breach compensation packages. Retention depends on tiered feature differentiation beyond basic alerts.
- Small Businesses:Limited dedicated IT security resources drive demand for outsourced monitoring of business credit files and employee identity exposure. Supply concentrates among providers offering simplified dashboard interfaces.
Revenue concentration favors Financial Institutions. Steepest expansion trajectory belongs to employer-sponsored Corporate deployment.
Technology:
Algorithmic capability now determines competitive position, with inference speed replacing rules-based detection as the core value proposition.
- AI Analytics:Machine learning models trained on proprietary compromise datasets to compress detection latency from weeks to minutes. Talent scarcity in anomaly detection engineering constrains in-house capability building for mid-tier providers.
- Cloud-Based Solutions:API-native deployment architectures enabling integration with modern security operations centers. Enterprise clients demand this interoperability while legacy providers maintain monolithic systems.
- Multi-Factor Authentication:Modular biometric and behavioral verification layers. Fingerprinting of typing cadence and swipe patterns enables passive authentication without friction in mobile banking applications.
- Blockchain:Decentralized identity verification pilots remain experimental, with limited production deployment outside credential wallet prototypes.
Established infrastructure sits with Cloud-Based Solutions. Fastest capability investment flows into AI Analytics.
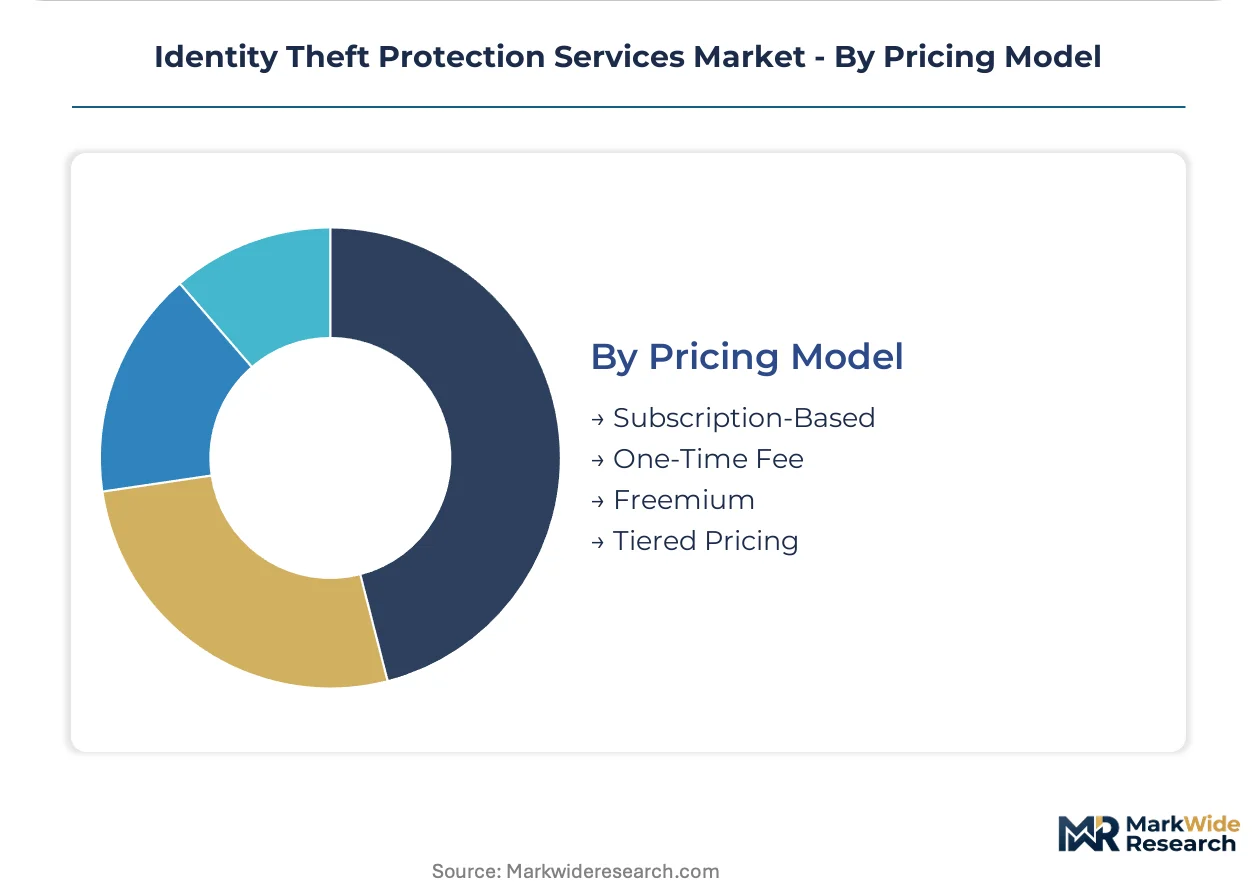
Pricing Model:
Revenue predictability trades off against acquisition friction, with hybrid structures emerging to address saturated consumer markets.
- Subscription-Based:Recurring monthly or annual fees capturing majority of recurring value. Retention depends on continuous feature expansion to justify ongoing expenditure against free alternatives.
- Freemium:Basic monitoring offered without charge to establish data relationships and upsell conversion pathways. Gaining traction as customer acquisition tools where direct marketing costs escalate.
- Tiered Pricing:Feature stratification across premium, standard, and economy levels aligning restoration depth with willingness to pay. Family-oriented coverage models occupy niche positioning between individual and enterprise plans.
- One-Time Fee:Single-payment restoration services triggered post-compromise. Limited recurring value limits provider investment in this structure.
Revenue stability sits with Subscription-Based. Fastest structural shift is occurring in Freemium adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley anchors the global identity theft protection services market, housing the densest concentration of cybersecurity vendors and venture capital deployment for AI-driven detection platforms. This technology corridor shapes product roadmaps that diffuse to financial centers and regulatory jurisdictions worldwide.
United States
Financial institutions in New York and San Francisco drive enterprise subscription volumes for continuous behavioral surveillance and anomaly detection. The FTC enforces identity theft reporting standards while state-level breach notification laws in California and New York mandate disclosure timelines that stimulate corporate purchasing. The Northeast Corridor concentrates employer-sponsored benefits distribution as Fortune 500 human resources departments add protection to voluntary benefits menus.
Germany
Industrial conglomerates and automotive suppliers in Baden-Württemberg and Bavaria procure auditable identity monitoring systems for workforce protection. The EU AI Act imposes algorithmic transparency requirements that reshape product standards for automated decision systems used in employment screening. Frankfurt's financial services cluster elevates demand for compliant protection infrastructure among multinational banking operations.
United Kingdom
London's insurance market pioneers embedded distribution partnerships as cyber insurance underwriters bundle proactive monitoring services with policy issuance. GDPR compliance obligations sustain procurement urgency for data handling accountability among multinationals. The Southeast technology corridor attracts specialized vendors serving European enterprise clients with API-native deployment architectures.
India
The Aadhaar-linked financial inclusion wave creates addressable demand for first-time credit monitoring among newly banked populations in Maharashtra and Karnataka. The Reserve Bank of India mandates security standards for digital payment infrastructure that elevate baseline protection expectations. Bangalore's technology cluster hosts development centers for machine learning inference platforms deployed across Asian markets.
Japan
Tokyo's financial services sector deploys biometric authentication convergence for premium tier differentiation through multi-factor compromise detection. METI guidelines on digital identity infrastructure shape enterprise procurement specifications. The Kansai manufacturing belt generates demand for workforce identity protection as supply chain digitization accelerates.
Identity Theft Protection Services Market Key Industry Players
Capital-heavy data aggregators compete with asset-light platform developers for positioning in identity protection value chains. The market structure concentrates around credit bureau incumbents with proprietary data assets and venture-backed specialists with algorithmic training depth. Three strategic archetypes dominate: integrated security suites bundling monitoring with antivirus and VPN services; credit-data-native providers leveraging bureau relationships for retention; and family-oriented specialists occupying niche positioning between individual and enterprise plans. Competitive moves center on employer-sponsored benefits channel expansion and AI detection capability acquisition through strategic partnerships rather than organic development.
Within the credit-data-native tier, Experian Information Solutions, Inc. and TransUnion LLC exemplify providers sustaining retention through deep integration with consumer financial profiles. NortonLifeLock Inc. anchors the integrated security suite archetype, bundling identity monitoring within broader cybersecurity ecosystems to justify higher-margin subscription tiers. Aura occupies a distinct position between individual and enterprise coverage models with family-oriented benefit structures.
| Leading Market Players |
|---|
| NortonLifeLock Inc. |
| LifeLock |
| Aura |
| Experian Information Solutions, Inc. |
| TransUnion LLC |
| Equifax, Inc. |
| IdentityForce |
| McAfee, LLC |
| Identity Guard |
| Others |
Cost & Logistics Intelligence
Dark web intelligence feed licensing costs cascade through provider cost structures, compressing entry-level subscription margins while enabling premium tier differentiation through proprietary data sourcing. This input cost dynamic stratifies the market into commodity monitoring layers and concierge restoration services with divergent margin profiles.
Pricing Analysis
Outcome-based pricing anchors enterprise contracts, with financial institutions paying premiums tied to fraud loss reduction metrics rather than seat counts. Three-tier pricing structure across premium, standard, and economy levels separates dedicated case management from automated alerts from basic credit pulls. Pricing pressure stems from post-breach free monitoring substitutes distributed under state mandates in California and New York. Small businesses exhibit highest price sensitivity, while financial institutions prioritize detection velocity over unit cost.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand from financial institutions and Fortune 500 employers, while API-native platforms feed embedded distribution through cyber insurance partnerships. Data aggregation concentrates in the United States, Ireland, and India, with credit bureau relationships and dark web crawler networks forming core infrastructure. Provider operations draw from proprietary compromise datasets, machine learning engineering talent pools, and cloud compute resources. Single-source vulnerability in credit data repositories creates systemic exposure. Distribution runs through employer benefits administrators, insurance brokers, and direct digital acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around AI detection capability, with machine learning engineering scarcity forcing mid-tier providers toward acquisition or partnership exits.
For Market Incumbents: Cement proprietary data asset advantages through exclusive dark web intelligence partnerships that widen detection latency gaps against rules-based competitors. Invest in explainable AI layers for EU AI Act compliance to capture multinational procurement mandates. Threat substitution from venture-backed algorithmic specialists intensifies margin pressure at the enterprise tier. For New Entrants and Emerging Players: Employer-sponsored benefits distribution offers the most penetrable channel, with human resources departments seeking differentiated voluntary benefits for dispersed workforces. Target small business segments with simplified dashboard interfaces that address limited IT security resources. Go-to-market angles should emphasize API-native deployment for rapid security operations center integration. For Investors and Strategic Acquirers: Distressed-cycle entries favor algorithmic training depth in Bangalore and Dublin development clusters where machine learning engineering concentrates. Long-term viability favors providers with captive data relationships and regulatory compliance infrastructure over pure technology plays. Watch employer benefits channel penetration rates as the inflection signal for sustained recurring revenue quality.| Strategic Initiative | Industry Significance |
|---|---|
| AI Detection Capability Acquisition | Machine learning model access compresses detection latency from weeks to minutes for enterprise clients. |
| Employer Benefits Channel Expansion | Human resources department relationships reduce customer acquisition costs below direct consumer marketing. |
| EU AI Act Compliance Infrastructure | Algorithmic audit trail capabilities unlock multinational procurement mandates across European operations. |
| Dark Web Intelligence Partnership | Exclusive credential exposure feeds differentiate premium tiers from commodity monitoring substitutes. |
| Embedded Insurance Distribution | Cyber insurance underwriter bundling opens B2B2C channels outside saturated direct markets. |
Research Approach
Document review covered FTC enforcement actions, state breach notification filings, EU regulatory guidance, and venture financing disclosures, complemented by interviews with identity protection product executives, financial institution fraud prevention officers, human resources benefits administrators, cyber insurance underwriters, and machine learning engineering leads. Secondary validation drew from SEC 10-K filings, patent databases, and employer benefits platform documentation. Bottom-up service revenue modeling and top-down addressable market sizing were cross-referenced for triangulation.
Historical growth patterns were cross-referenced against panel input from procurement stakeholders to anchor projection assumptions across the analysis window. Segmentation modeling incorporated service type automation depth, end-user procurement authority, technology deployment architecture, and pricing model structure. CAGRs were derived from fitted trend extrapolation adjusted for regulatory inflection points. Forecast inputs included synthetic identity fraud loss trajectories and employer benefits adoption curves.
The model holds under sustained regulatory enforcement of breach notification timelines and stable employer benefits channel expansion; deviation in dark web data feed cost structures or AI talent availability would shift provider margin trajectories. Forecasts reflect documented assumptions about compliance cost pass-through and substitution elasticity between free and paid monitoring tiers. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Biometric Authentication Solution Market
Biometrics & Identity Management
Next Generation Biometric Market
Biometrics & Identity Management
Europe Government and Security Biometrics Market
Biometrics & Identity Management
Consumer Biometrics Market
Biometrics & Identity Management
Passive Authentication Market
Biometrics & Identity Management
Biometric ATM Market
Biometrics & Identity Management
Global Biometric-As-A-Service Market
Biometrics & Identity Management
Spain Mobile Biometrics Market
Biometrics & Identity Management
Global Phone Based Authentication Solution Market
Biometrics & Identity Management
Biometric Bike Locks Market
Biometrics & Identity Management
Vein Recognition Biometrics Market
Biometrics & Identity Management
FIDO Authentication Market
Biometrics & Identity Management
IRIS Biometrics Market
Biometrics & Identity Management
Biometric Smart Cards Market
Biometrics & Identity Management
Italy Mobile Biometrics Market
Biometrics & Identity Management
Global Human Identification Market