
 Biometric Bike Locks Market | 2026-2036
Biometric Bike Locks Market Size, Share, and Industry Trends Forecast 2026-2036
Biometric Bike Locks Market Analytics
China is rewriting manufacturing economics for biometric bike locks through concentrated Shenzhen-based electronics assembly and sensor module production. ABUS leverages its German engineering heritage to dominate European premium cycling security with hardened steel housings paired with capacitive fingerprint modules. ZiiLock anchors Asian supply chains with in-house production of foldable biometric locks, while LINKA competes through smartphone-integrated geofencing alerts that extend beyond pure mechanical security.
Biometric bike locks are electromechanical security devices that authenticate users through unique biological identifiers—typically capacitive fingerprint sensors with sub-500ms recognition latency—before releasing a hardened shackle or cable mechanism. Their primary commercial purpose is eliminating key loss vulnerability while creating audit trails for fleet operators managing shared bicycle assets. Fingerprint locks occupy the dominant volume position due to mature sensor cost curves, though facial recognition locks are gaining fastest in premium consumer segments where hands-free unlocking matters. Bluetooth-enabled units capture the widest margin pools by bundling GPS tracking and tamper alerts into subscription software tiers, while NFC configurations remain niche among enterprise fleet deployments seeking minimal power draw.
CE marking requirements under EU machinery directives and FCC Part 15 emissions rules in the United States shape product development timelines and testing budgets for biometric lock manufacturers. REACH compliance for nickel-free sensor coatings and RoHS restrictions on solder materials further constrain component sourcing across European and North American markets. Stakeholders must monitor evolving insurance industry premium incentives tied to certified anti-theft device installation, as underwriters in cycling-dense cities increasingly mandate biometric authentication for comprehensive coverage.
Market Dynamics
Bluetooth Low Energy integration with capacitive fingerprint sensors is compressing false rejection rates below two percent, forcing incumbents to redesign authentication stacks or surrender fleet contracts to sensor-integrated competitors.
Growth Catalysts
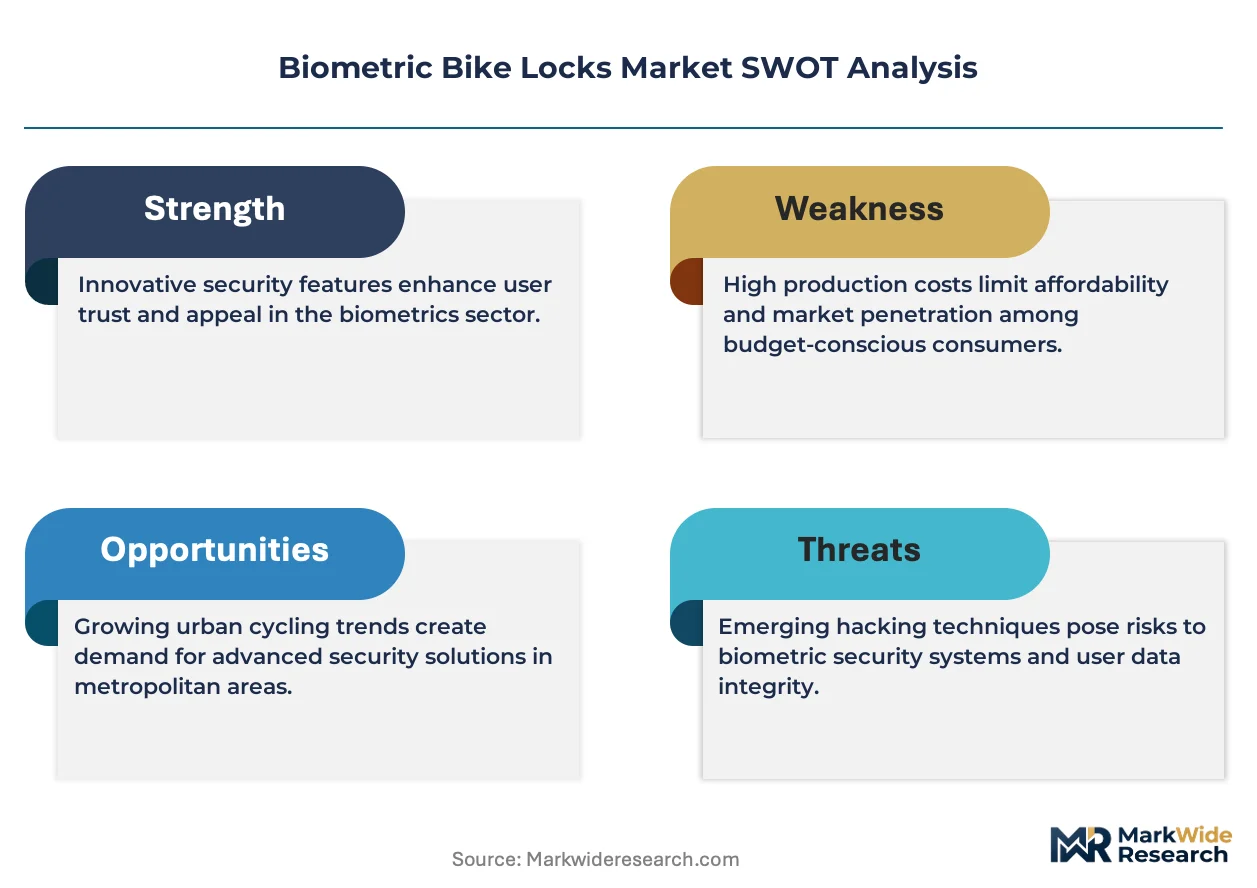
- REACH nickel-free mandates:European coatings compliance is accelerating capacitive sensor module upgrades, locking out legacy electroplated competitors from Dutch and Danish municipal tenders.
- Munich cycling infrastructure bonds:German municipal debt issuance for protected lane networks is bundling biometric lock procurement into fleet operator concession packages.
- Fingerprint-to-cloud audit trails:Shared mobility platforms in Barcelona and Milan are mandating biometric authentication to satisfy insurer fraud-verification requirements.
Market Restraints
- Shenzhen sensor module concentration:Capacitive fingerprint ASIC fabrication clusters in Guangdong province expose European assemblers to single-source geopolitical disruption.
- RoHS solder material restrictions:Lead-free alloy specifications are inflating PCB reflow defect rates and extending manufacturing yield ramp cycles.
- Mechanical key override:Consumer distrust of battery-dependent electronics preserves demand for hybrid mechanical-biometric designs, fragmenting R&D budgets across dual architectures.
Strategic Opportunities
- India PLI scheme for electronics:Component assembly incentives are luring biometric lock assemblers to Noida and Chennai to escape China tariff exposure.
- Facial recognition convergence:3D structured light modules are enabling hands-free unlocking for cargo bike delivery fleets in Copenhagen and Utrecht.
- Subscription telemetry bundling:GPS-tamper alert software tiers are capturing recurring revenue from Amsterdam bike-share operators seeking fleet visibility.
Industry Challenges
- Firmware security certification delays:Common Criteria evaluation timelines for biometric template encryption are stretching product launch windows by eight to fourteen months.
- IP fragmentation across sensor patents:Cross-licensing negotiations between capacitive sensing IP holders are inflating unit royalty stacks and squeezing margin pools for mid-tier assemblers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biometric Bike Locks Market |
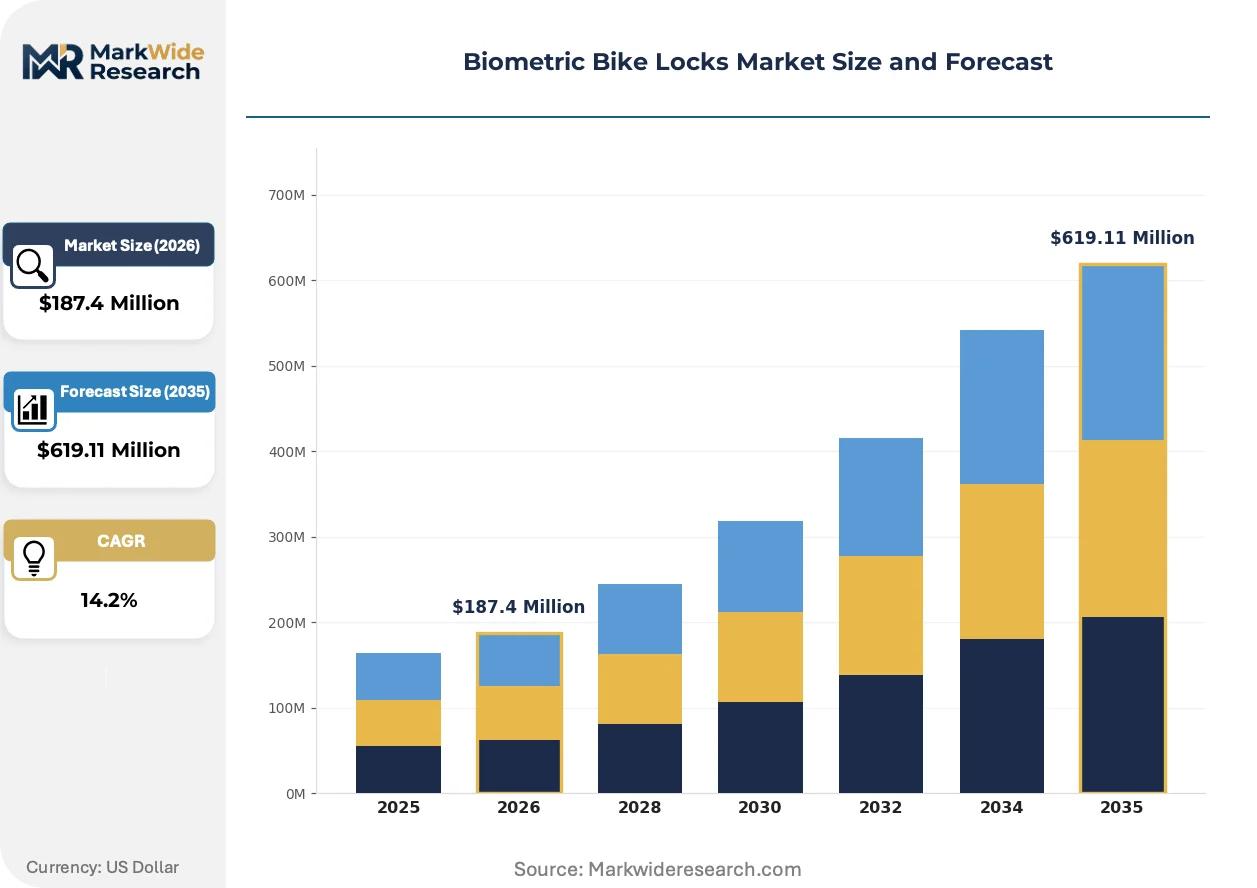
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fingerprint Locks, Facial Recognition Locks, Retina Scanner Locks, Keypad Locks Technology: Bluetooth, Wi-Fi, NFC, Biometric Sensors End User: Cyclists, Bike Rental Services, Security Firms, Fitness Centers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | ABUS, ZiiLock, LINKA, Bitlock, Fipilock, I LOCK IT, Kryptonite, Master Lock, KENRONE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biometric Bike Locks Market Evolving Landscape
Authentication latency and power draw are becoming decisive procurement criteria as fleet operators scale beyond ten-thousand-unit deployments and demand sub-second unlock reliability.
Capacitive fingerprint sensors with sub-500ms recognition latency are the dominant biometric modality in commercial bike security. European fleet operators in Amsterdam and Copenhagen are specifying these modules as baseline procurement requirements. Authentication is migrating from standalone onboard processing to edge-cloud hybrid architectures that enable real-time revocation and firmware updates.
CE marking under EU machinery directives is forcing hardened steel housing redesigns to accommodate sensor cable routing without compromising IP67 ingress ratings. German testing houses in Munich and Stuttgart are extending certification timelines for biometric-electromechanical hybrid devices. Manufacturers are responding by front-loading EMC pre-compliance testing before final mold tooling commits.
Fleet procurement teams are unbundling hardware acquisition from telemetry software subscriptions, treating GPS tracking and tamper alerts as separately negotiated service tiers. This bifurcation is compressing upfront hardware margins while extending customer lifetime value capture through recurring platform fees. The shift is most pronounced in Dutch and Danish municipal bike-share concessions where operators face political pressure to demonstrate theft recovery rates.
Biometric Bike Locks Market Segmentation
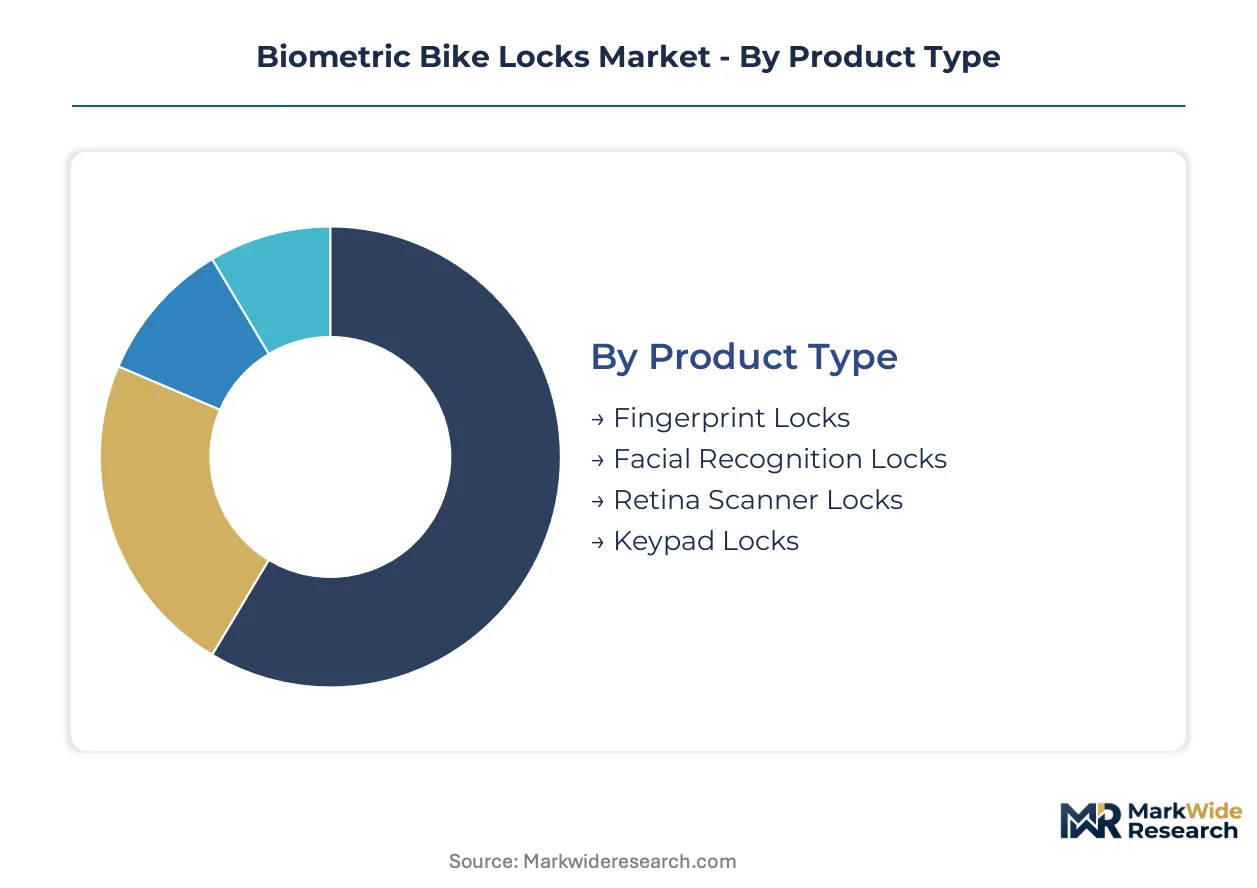
Segmentation in biometric bike locks reveals how authentication modality, connectivity stack, and procurement channel each impose distinct engineering constraints and margin structures. Manufacturers must align sensor specifications with end-use duty cycles while navigating divergent certification requirements across fleet and consumer channels.
Product Type:
Cost tier determines sensor complexity, power architecture, and housing durability across biometric lock variants.
- Fingerprint Locks:Capacitive sensors with sub-500ms recognition latency dominate commercial procurement. Amsterdam and Copenhagen municipal fleets specify these modules as baseline requirements due to mature cost curves and REACH-compliant nickel-free coating availability.
- Facial Recognition Locks:3D structured light modules enable hands-free authentication for cargo bike delivery operators in Utrecht. Premium positioning reflects higher ASIC costs and elevated IP67 sealing requirements for outdoor exposure.
- Retina Scanner Locks:Near-infrared iris acquisition systems remain confined to high-security corporate campuses and defense-adjacent cycling infrastructure.
- Keypad Locks:Electromechanical hybrids with biometric override satisfy consumer distrust of battery-dependent systems in German retail channels.
Fingerprint locks hold installed capacity. Facial recognition locks are rotating up the share rankings.
Technology:
Connectivity protocol selection shapes power draw, telemetry capability, and subscription revenue potential.
- Bluetooth:Low Energy integration with fingerprint sensors compresses false rejection rates below two percent. Barcelona and Milan shared mobility platforms mandate BLE-enabled units to satisfy insurer fraud-verification requirements.
- Biometric Sensors:Standalone capacitive modules without wireless backhaul serve cost-sensitive consumer segments and jurisdictions with restricted RF emissions.
- NFC:Minimal power draw configurations appeal to enterprise fleet deployments seeking extended battery life without GPS telemetry.
- Wi-Fi:Continuous connectivity supports real-time tamper alerts and firmware updates for high-value cargo bike fleets in Copenhagen.
Bluetooth dominates margin capture through subscription bundling. Biometric sensors maintain volume leadership in direct-to-consumer channels.
End User:
Customer type dictates authentication throughput requirements, audit trail specifications, and procurement contract structures.
- Bike Rental Services:Fleet operators in Dutch and Danish municipal concessions demand sub-second unlock reliability and cloud-connected audit trails for theft recovery documentation.
- Cyclists:Individual purchasers prioritize form factor and smartphone integration over enterprise-grade telemetry, accepting trade-offs in tamper alert latency.
- Security Firms:Contract guarding operations specify hardened steel housings with Common Criteria-certified firmware encryption for insured asset protection.
- Fitness Centers:Indoor cycling facilities require minimal IP ratings but demand high-cycle durability for repeated daily use.
Bike rental services drive premium sensor specifications. Cyclists represent the broadest addressable base.
Distribution Channel:
Channel configuration determines margin stacking, certification documentation requirements, and customer education burdens.
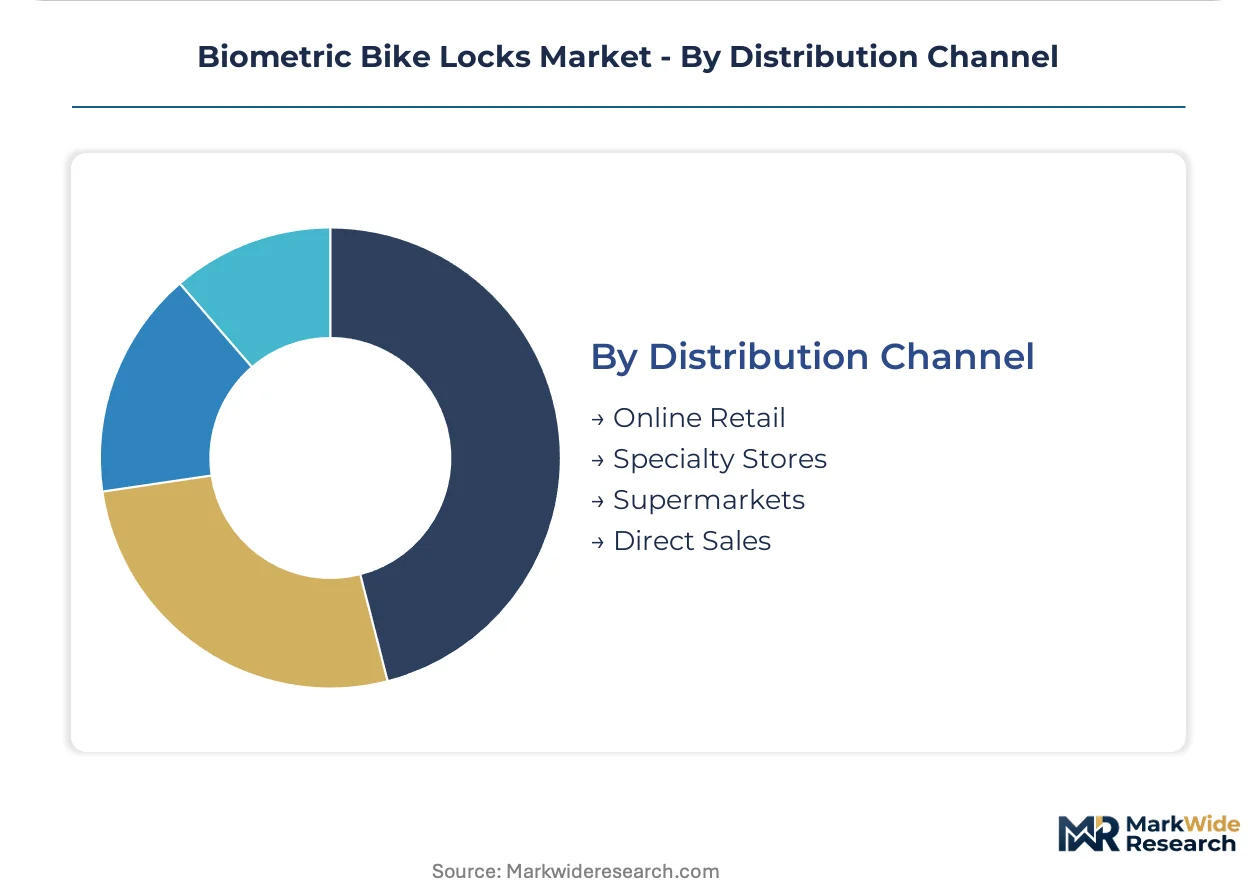
- Online Retail:Direct-to-consumer platforms in Germany bundle installation tutorials with CE-marked units, compressing specialty store margins through price transparency.
- Direct Sales:Municipal fleet procurement teams negotiate hardware-software unbundling, treating GPS telemetry as separately contracted service tiers.
- Specialty Stores:Cycling retailers provide hands-on biometric enrollment support, justifying premium positioning through technical service differentiation.
- Supermarkets:Mass-market distribution focuses on keypad-biometric hybrids with mechanical override for risk-averse casual cyclists.
Online retail is expanding most quickly in consumer segments. Direct sales capture the highest contract values in fleet deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany treats biometric bike locks as cycling infrastructure rather than consumer accessories, while China concentrates manufacturing without matching domestic fleet deployment scale.
Germany
Municipal cycling infrastructure bonds in Munich and Hamburg bundle biometric lock procurement into fleet operator concession packages. KBA insurance mandates now require certified anti-theft devices for comprehensive bicycle coverage, pushing premium adoption. Bavarian testing houses in Munich extend CE marking timelines for biometric-electromechanical hybrid devices.
Netherlands
Amsterdam bike-share operators demand sub-second unlock reliability and cloud-connected audit trails for theft recovery documentation. REACH nickel-free sensor coating mandates lock out legacy electroplated competitors from Dutch municipal tenders. Randstad region procurement teams unbundle hardware acquisition from telemetry software subscriptions.
China
Shenzhen-based electronics assembly clusters dominate capacitive fingerprint ASIC fabrication for export markets. MIIT standards for wireless device emissions shape BLE module integration timelines. Guangdong province sensor module concentration exposes European assemblers to single-source geopolitical disruption.
Denmark
Copenhagen municipal fleets specify capacitive fingerprint modules with sub-500ms recognition latency as baseline procurement requirements. Danish cycling infrastructure investments prioritize protected lane networks with integrated smart locking stations. Odense delivery operators pilot 3D structured light facial recognition for hands-free cargo bike authentication.
United States
FCC Part 15 emissions rules extend certification timelines and testing budgets for biometric lock manufacturers seeking market entry. California bike-share platforms mandate biometric authentication to satisfy insurer fraud-verification requirements. Pacific Northwest municipalities experiment with Wi-Fi-enabled locks for real-time tamper alerts on high-value cargo fleets.
Biometric Bike Locks Market Competitive Landscape
Capability concentration sits with German engineering heritage players; scale advantage sits with Shenzhen-based electronics assemblers. The vendor base separates into hardened steel specialists, foldable mechanism fabricators, and smartphone-integrated platform operators. Two dominant competitive moves are reshaping positioning: backward integration into sensor module production and subscription telemetry bundling for recurring revenue capture.
Within the European premium tier, ABUS anchors hardened steel engineering expertise paired with capacitive biometric modules. ZiiLock occupies the Asian manufacturing vector with Shenzhen-based production of foldable lock architectures. LINKA exemplifies smartphone-integrated positioning through geofencing alert platforms that extend beyond pure mechanical security functions.
| Leading Market Players |
|---|
| ABUS |
| ZiiLock |
| LINKA |
| Bitlock |
| Fipilock |
| I LOCK IT |
| Kryptonite |
| Master Lock |
| KENRONE |
| Others |
Value Network & Pricing Analysis
Rotterdam-Antwerp container corridor freight volatility compresses margin pools for European biometric lock assemblers sourcing capacitive sensor modules from Guangdong, while REACH compliance costs and BLE certification tiers stratify downstream price positioning across fleet and consumer channels.
Pricing Analysis
Long-term offtake contracts dominate fleet procurement in Amsterdam and Copenhagen, locking in volume commitments for capacitive fingerprint modules with sub-500ms latency specifications. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by CE marking grade and telemetry software bundling. Cost compression in economy-tier consumer units intensifies because Shenzhen-based module oversupply erodes hardware margins. Municipal bike-share operators exhibit lowest price sensitivity due to insurer-mandated authentication requirements, while German retail cyclists drive hardest bargain on keypad-biometric hybrids.
Supply Chain Analysis
Export control regimes on semiconductor manufacturing equipment constrain capacitive ASIC fabrication capacity expansion outside China, concentrating sensor module supply in Guangdong province with secondary clusters in South Korea and Taiwan. Supply chains draw from nickel-free sensor coatings, hardened steel billets, and BLE radio chipsets. Single-source vulnerability in Shenzhen electroplating exposes European assemblers to geopolitical disruption. Distribution runs through direct municipal procurement teams in Dutch and Danish concessions, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Dutch and Danish municipal fleet operators bundling hardware-software procurement at scale, fragmenting vendor pricing leverage across ten-thousand-unit concession tenders.
For Market Incumbents: Build firmware encryption certification moats by accelerating Common Criteria evaluation timelines for biometric template protection against emerging smartphone-integrated platform entrants. Secure backward integration into capacitive sensor module production through Noida assembly partnerships under India's PLI scheme, insulating against China tariff exposure. Anchor hardened steel housing expertise with Munich testing house relationships to extend CE marking barriers. For New Entrants and Emerging Players: Establish a beachhead in facial recognition cargo bike authentication for Copenhagen and Utrecht delivery fleets where hands-free unlocking commands premium positioning. Target NFC-minimal-power configurations for enterprise fleet deployments seeking extended battery life without GPS telemetry subscriptions. Leverage direct sales channel bypass of incumbent retail markups through municipal procurement team relationships. For Investors and Strategic Acquirers: Smartphone-integrated platform operators with captive geofencing alert software represent the highest-multiple acquisition archetype as subscription revenue pools expand. Long-term viability hinges on telemetry bundling penetration across European municipal concessions. Watch for India PLI scheme utilization rates as inflection signal for supply chain diversification momentum away from Shenzhen concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Module Backward Integration | In-house capacitive ASIC production in Noida escapes China tariff exposure under PLI incentives. |
| Common Criteria Certification Acceleration | Firmware encryption pre-evaluation compresses Munich testing house timelines by eight to fourteen months. |
| Facial Recognition Platform Launch | 3D structured light modules capture Copenhagen cargo bike delivery premium with hands-free authentication. |
| Telemetry Subscription Tiering | GPS-tamper alert software unbundling extends Amsterdam fleet operator lifetime value through recurring fees. |
| REACH-Compliant Coating Partnership | Nickel-free sensor surface supply agreements lock out legacy electroplated competitors from Dutch municipal tenders. |
Research Methodology
Operator-level perspectives from fleet procurement managers, municipal cycling infrastructure planners, biometric sensor module suppliers, and insurance underwriting specialists anchored the qualitative base for this study. Primary interviews combined with secondary validation from ECHA REACH registration databases, KBA insurance mandate filings, and EU machinery directive CE marking records. Bottom-up unit shipment estimates triangulated against top-down municipal concession contract values across the analysis window.
Scenario-bracketing framed volume and value outputs across authentication modality, connectivity protocol, and procurement channel segmentation dimensions. CAGRs derived from logistic diffusion curves fitted to fleet deployment trajectories in Amsterdam, Copenhagen, and Munich, with cross-referencing against Shenzhen module export customs data and German cycling infrastructure bond issuance pipelines.
Macroeconomic conditions sit as an overlay; deviation in euro-zone municipal debt issuance costs or China semiconductor equipment export control enforcement would shift the trajectory. Forecasts reflect assumptions on BLE module cost curves and insurer authentication mandate diffusion. Material shifts in REACH nickel-free coating supply availability or Common Criteria certification backlog duration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
ID Verification Market
Biometrics & Identity Management
Automated Fingerprint Identification Systems (AFIS) Market
Biometrics & Identity Management
Middle East and Africa Biometrics in Government Market
Biometrics & Identity Management
Hand Geometry Biometrics Market
Biometrics & Identity Management
E-Government Identity Management Market
Biometrics & Identity Management
North America Government and Security Biometrics Market
Biometrics & Identity Management
North America Enterprise Biometrics Market
Biometrics & Identity Management
Mobile Biometric Security and Services Market
Biometrics & Identity Management
Signature Verification Market
Biometrics & Identity Management
Biometric Point-Of-Sale Terminals Market
Biometrics & Identity Management
North America Biometrics in Government Market
Biometrics & Identity Management
Gait Biometrics Market
Biometrics & Identity Management
Europe Biometrics Market
Biometrics & Identity Management
Mobile Biometrics Market
Biometrics & Identity Management
Europe Decentralized Identity Market
Biometrics & Identity Management
Biometrics As a Service in Healthcare Market