
 Fingerprint Biometrics Market | 2026-2036
Fingerprint Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
Fingerprint Biometrics Market Analysis
Enterprise workforce management is unwinding from legacy card-based systems toward biometric authentication, redirecting procurement budgets toward fingerprint-enabled platforms. Suprema Inc. dominates physical access control deployments across Asia-Pacific commercial real estate. NEC Corporation anchors large-scale government identification projects with multimodal biometric fusion. Shenzhen Goodix Technology Co., Ltd. leverages its captive semiconductor fabrication to undercut Western sensor suppliers on unit cost.
Fingerprint biometrics encompasses hardware sensors and matching algorithms that capture, process, and compare ridge patterns from human fingertips for identity verification, typically operating with false acceptance rates below 0.001% in enterprise-grade configurations. The technology serves critical commercial purposes in fraud prevention, physical perimeter security, and streamlined consumer authentication. Capacitive sensors lead volume shipments due to their integration into smartphones and laptops, while ultrasonic modules represent the fastest-growing technology segment as they enable through-glass and through-display enrollment. Software solutions and middleware capture disproportionate margin pools relative to their revenue share because integration complexity and template encryption requirements create sticky vendor relationships.
The US FBI's Integrated Automated Fingerprint Identification System and India's UIDAI mandate shape product standards for template interoperability and data encryption in government deployments. EMA cybersecurity guidelines and ISO/IEC 19794-2 standards govern healthcare and cross-border financial authentication workflows. Stakeholders must monitor regulatory divergence between EU GDPR-derived biometric consent frameworks and emerging Middle Eastern digital identity mandates when allocating R&D and compliance resources.
Market Dynamics
Capacitive sensor commoditization is compressing hardware margins while ultrasonic and optical-under-display technologies command premium positioning in smartphone authentication stacks. This technology bifurcation is redirecting R&D investment toward algorithmic differentiation and multimodal fusion architectures.
Growth Catalysts
- India's Aadhaar-linked service delivery infrastructure:Government mandates for biometric verification in welfare distribution, banking correspondent networks, and mobile SIM activation sustain bulk procurement of fingerprint scanners across rural and urban administrative zones.
- GDPR-derived biometric consent frameworks:European data protection requirements for explicit user authorization are accelerating deployment of on-device template storage and encrypted matching pipelines in enterprise access control systems.
- Ultrasonic through-display enrollment:Mobile OEMs in China's Pearl River Delta manufacturing corridor are integrating piezoelectric sensor arrays that capture ridge detail through cover glass, eliminating physical button requirements.
Market Restraints
- Silicon wafer cost volatility:Capacitive sensor fabrication depends on 8-inch CMOS foundry capacity concentrated in Taiwan and South Korea, where automotive chip demand competes for allocation and inflates unit economics.
- Spoofing vulnerability in legacy optical sensors:Presentation attack detection gaps in first-generation slap scanners limit their eligibility for FBI-certified civil applications, forcing premature replacement cycles in US state law enforcement agencies.
- Facial recognition substitution in consumer devices:Structured light and time-of-flight 3D face authentication in flagship smartphones is displacing fingerprint modules in premium tier handsets, constraining sensor volume growth in high-ASP segments.
Strategic Opportunities
- Middle Eastern digital identity mandates:Saudi Arabia's National Information Center and UAE's Federal Authority for Identity and Citizenship are tendering multimodal biometric enrollment systems for visa, residency, and healthcare integration.
- Automotive in-cabin personalization:Steering wheel-integrated capacitive sensors enable driver profile authentication for seat position, mirror adjustment, and infotainment preferences in electric vehicle platforms from European and Chinese OEMs.
- Healthcare point-of-care authentication:India's HMIS (Health Management Information System) digitization requires biometric patient identification at rural clinics, creating demand for ruggedized, battery-operated fingerprint tablets.
Industry Challenges
- Algorithm certification timelines:FBI's MINEX and NIST's FRVT evaluations require 12-18 month validation cycles for template generators, delaying product launches for vendors seeking law enforcement eligibility.
- Interoperability fragmentation:Divergent template formats between ISO/IEC 19794-2, ANSI/NIST-ITL 1-2011, and proprietary vendor implementations complicate multi-supplier deployments in government ID programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fingerprint Biometrics Market |
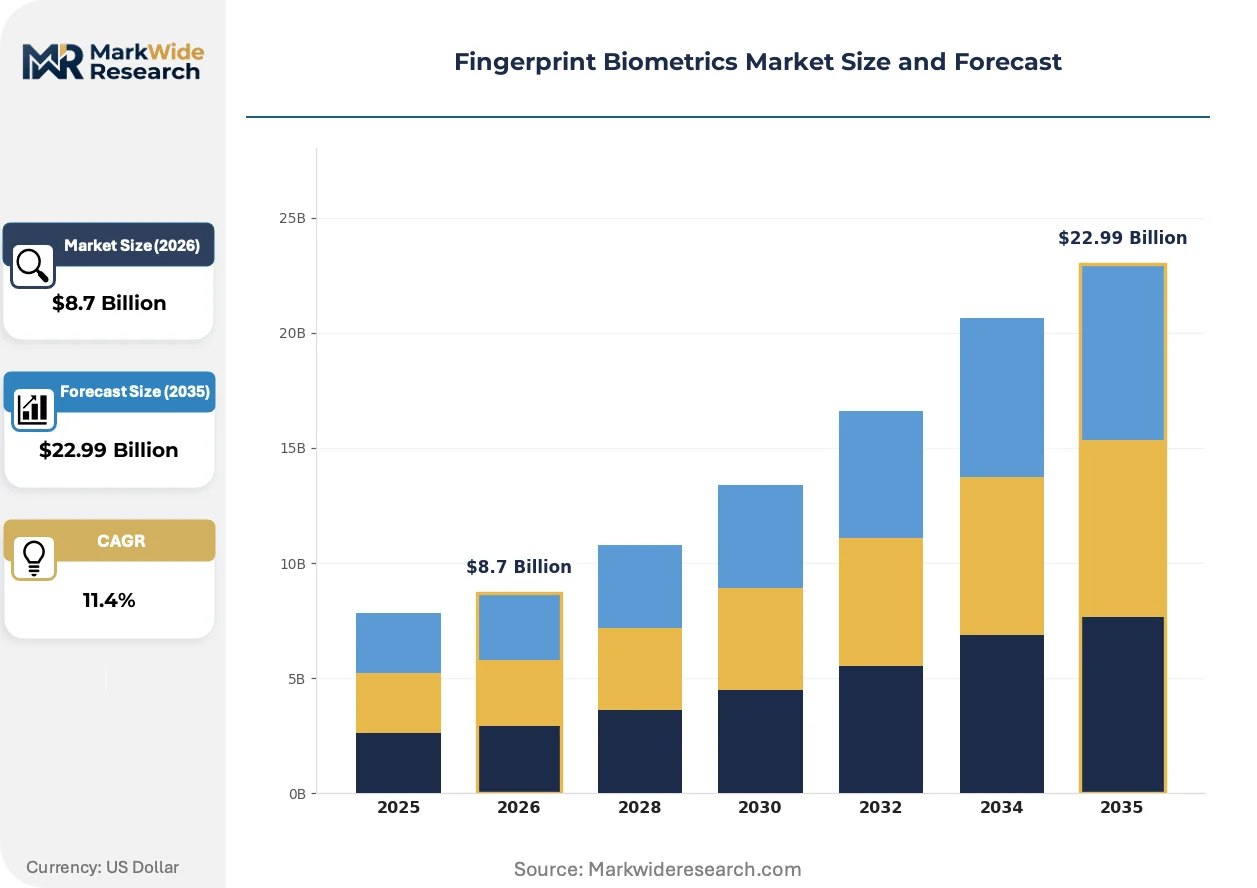
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fingerprint Sensors, Software Solutions, Middleware, Security Systems End User: Government, Financial Institutions, Healthcare, Consumer Electronics Technology: Optical, Capacitive, Ultrasonic, Thermal Application: Access Control, Time & Attendance, Payment Processing, Identification |
| Companies Covered | Shenzhen Goodix Technology Co., Ltd., Fingerprints, Synaptics Incorporated, Fingerprint Cards AB, IDEX Biometrics, Egis Technology Inc., Suprema Inc., NEC Corporation, CrucialTec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fingerprint Biometrics Market Emerging Trajectories
Sensor miniaturization and on-device AI inference are collapsing the boundary between hardware capture and software matching, enabling biometric functionality in form factors previously constrained by power and footprint limitations.
Ultrasonic fingerprint sensing is displacing capacitive modules in flagship smartphone designs. Qualcomm's 3D Sonic Sensor and similar piezoelectric arrays from Goodix capture sub-surface ridge detail through Gorilla Glass Victus and ceramic shields. Samsung's Galaxy S series and Chinese OEM flagships in the 600+ USD tier have standardized this technology, compressing capacitive sensor ASPs in premium segments and forcing suppliers to pivot toward mid-tier volume or automotive diversification.
EU AI Act risk classification for biometric identification systems is tightening compliance obligations for remote authentication deployments. High-risk system designations mandate human oversight, accuracy benchmarking, and fundamental rights impact assessments for public-space applications. Financial services and border control procurements in Germany, France, and the Netherlands are now requiring explicit conformity documentation, extending sales cycles but creating vendor stickiness for certified solution providers.
Enterprise buyers are consolidating authentication vendors around platform ecosystems rather than point solutions. Microsoft Azure AD and Okta integrations now dominate RFP requirements for workforce access control, favoring biometric hardware vendors with pre-built SCIM and SAML connectors. This specification tightening is most visible in US and UK financial services, where CISOs prioritize reduced integration overhead over standalone feature depth, compressing margins for proprietary middleware layers.
Fingerprint Biometrics Market Segmentation
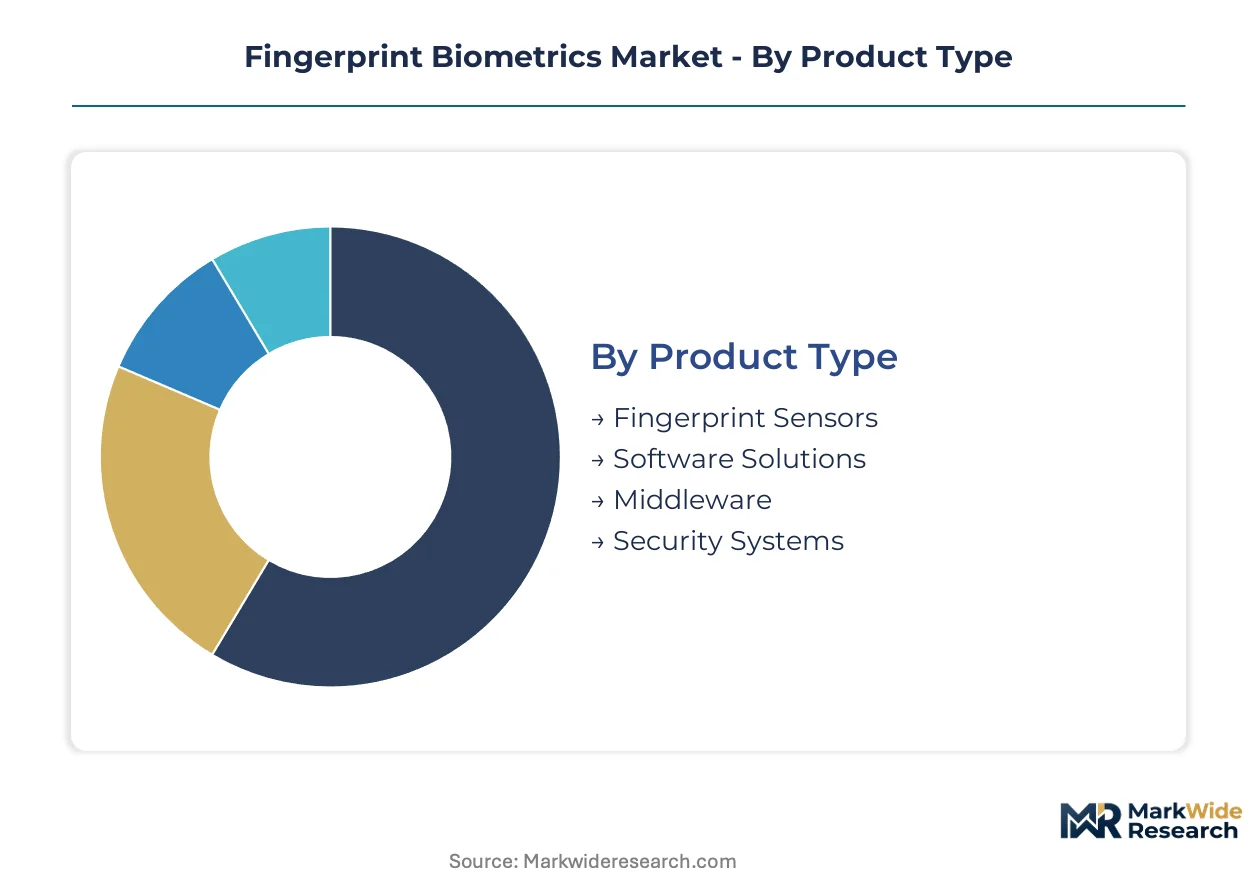
Technology heterogeneity and divergent compliance requirements across government, consumer, and enterprise verticals fragment procurement specifications. Vendors must architect modular product portfolios spanning hardware sensors, algorithmic middleware, and integrated security systems to capture cross-segment opportunities.
Product Type:
Domestic demand concentrates in government-mandated hardware for national ID programs, while export volumes flow toward smartphone OEM supply chains in China's Pearl River Delta manufacturing corridor.
- Fingerprint Sensors:Capacitive CMOS arrays dominate unit shipments through integration into laptops and mid-tier smartphones. India's UIDAI procurement for Aadhaar enrollment sustains bulk orders for optical slap scanners across rural administrative networks.
- Software Solutions:Template generation and matching algorithms capture disproportionate margin pools through encryption requirements and FBI certification barriers. GDPR-mandated on-device processing accelerates demand for edge-deployable SDKs in European enterprise access control.
- Middleware:Integration layers bridge sensor hardware and enterprise identity directories, with pre-built connectors for Azure AD and Okta dominating RFP requirements in US financial services.
- Security Systems:End-to-end biometric authentication platforms bundle hardware, software, and management consoles for high-assurance environments including data centers and critical infrastructure.
Fingerprint Sensors command the established base. The steepest expansion runs through Software Solutions.
End User:
Cost tier stratification separates premium multimodal deployments in financial services from price-sensitive single-factor systems in rural healthcare authentication.
- Government:National ID programs, border control, and law enforcement drive the highest-volume procurement through standardized tender processes. India's Aadhaar-linked welfare distribution and Saudi Arabia's digital identity mandates sustain multi-year contract pipelines.
- Financial Institutions:Payment authentication and branch access control demand FBI-certified template generators with presentation attack detection. RBI guidelines for banking correspondent networks mandate biometric verification in India's rural financial inclusion infrastructure.
- Healthcare:Patient identification at point-of-care requires ruggedized, battery-operated tablets for India's HMIS digitization in rural clinics.
- Consumer Electronics:Smartphone OEMs in China's manufacturing corridors specify ultrasonic through-display modules for premium tier flagships, compressing capacitive sensor ASPs.
Government captures volume concentration. Healthcare is climbing the fastest as digitization mandates penetrate underserved regions.
Technology:
Maturity curves diverge sharply, with optical and capacitive systems commoditizing while ultrasonic modules command technology premiums through sub-surface imaging capabilities.
- Optical:Legacy slap scanners face displacement from capacitive and ultrasonic alternatives due to spoofing vulnerabilities and size constraints. FBI certification requirements limit remaining deployments to civil identification programs with established infrastructure.
- Capacitive:CMOS-based ridge sensing dominates laptop and mid-tier smartphone integration through mature supply chains and sub-dollar unit economics at volume.
- Ultrasonic:Piezoelectric arrays capture ridge detail through cover glass and ceramic shields, eliminating physical button requirements. Samsung's Galaxy S series and Chinese OEM flagships have standardized this technology in 600+ USD tiers.
- Thermal:Temperature differential sensing serves niche applications in high-humidity environments where capacitive performance degrades.
Capacitive technology holds volume leadership. Ultrasonic is gaining share fastest through premium smartphone specification.
Application:
Customer type differentiation separates enterprise workforce management from consumer-facing payment authentication, with divergent requirements for enrollment speed, template storage, and audit trails.
- Access Control:Physical perimeter security systems integrate fingerprint readers with door controllers and visitor management platforms. Suprema Inc. dominates Asia-Pacific commercial real estate deployments.
- Time & Attendance:Workforce management platforms replace legacy card-based systems with biometric verification to eliminate buddy punching. Enterprise buyers prioritize SCIM and SAML connector availability.
- Payment Processing:Point-of-sale biometric authentication requires PCI-DSS compliant template encryption and rapid matching latency for transaction flow integration.
- Identification:Civil and criminal background check systems demand ISO/IEC 19794-2 template interoperability and NIST FRVT accuracy benchmarking.
Access Control anchors current deployment value. Payment Processing is expanding most quickly as contactless biometric checkout penetrates retail infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen-based sensor manufacturers export ultrasonic modules to South Korean smartphone OEMs, while Indian system integrators source optical slap scanners from domestic assembly corridors for Aadhaar enrollment networks.
United States
FBI-certified template generators and enterprise access control systems anchor procurement demand across federal law enforcement and financial services sectors. NIST FRVT accuracy benchmarking governs algorithm eligibility for civil identification deployments. Dallas-Fort Worth and Northern Virginia data center clusters absorb biometric security systems for critical infrastructure perimeter protection.
China
Premium smartphone OEMs in the Pearl River Delta specification pipeline drive ultrasonic sensor volume through through-display enrollment mandates. MIIT cybersecurity standards for biometric data encryption shape product compliance requirements for domestic sales. Shenzhen semiconductor fabrication corridors concentrate capacitive CMOS array production for laptop and mid-tier handset integration.
India
Aadhaar-linked welfare distribution and banking correspondent networks sustain bulk procurement of ruggedized fingerprint tablets across rural administrative zones. RBI guidelines mandate biometric verification for mobile SIM activation and financial inclusion infrastructure. Bengaluru and Hyderabad technology corridors host system integrators assembling enrollment devices for UIDAI tender pipelines.
Germany
EU AI Act high-risk system designations tighten compliance documentation for enterprise access control and border authentication deployments. GDPR-derived explicit consent frameworks accelerate on-device template storage specifications in financial services procurement. Munich and Stuttgart automotive engineering clusters pilot steering wheel-integrated capacitive sensors for electric vehicle personalization.
Saudi Arabia
National Information Center tenders for multimodal biometric enrollment systems drive demand across visa, residency, and healthcare integration mandates. SFDA and digital identity authority procurement guidelines shape vendor qualification requirements for government contracts. Riyadh technology district concentrations attract system integrators positioning for Gulf Cooperation Council identity infrastructure expansion.
Fingerprint Biometrics Market Vendor Landscape
Player mix skews toward vertically integrated semiconductor specialists and algorithm-centric platform vendors. Tiered competitive structure separates premium-tier multimodal fusion providers from volume-driven sensor commoditizers. Strategic archetypes include captive foundry operators, FBI-certified template generators, and enterprise middleware consolidators. Capacity expansion in 8-inch CMOS fabrication and algorithmic M&A targeting presentation attack detection capabilities dominate competitive maneuvering.
Among Asia-Pacific semiconductor specialists, Shenzhen Goodix Technology Co., Ltd. and Egis Technology Inc. occupy positions reflecting captive fabrication advantages and ultrasonic module specification capture. Suprema Inc. anchors physical access control archetypes across commercial real estate deployments. NEC Corporation exemplifies government-facing multimodal fusion positioning through large-scale identification project anchoring.
| Leading Market Players |
|---|
| Shenzhen Goodix Technology Co., Ltd. |
| Fingerprints |
| Synaptics Incorporated |
| Fingerprint Cards AB |
| IDEX Biometrics |
| Egis Technology Inc. |
| Suprema Inc. |
| NEC Corporation |
| CrucialTec |
| Others |
Supply Flow & Price Mechanics
Eight-inch CMOS foundry utilization rates in Taiwan and South Korea shape unit economics across sensor tiers, compressing margins for capacitive commodity suppliers while concentrating pricing power with ultrasonic module vendors holding captive piezoelectric fabrication. This capacity bottleneck feeds into procurement strategies for smartphone OEMs and government enrollment contractors, forcing volume commitments that lock in price floors for multi-year tender cycles.
Pricing Analysis
Prior-generation optical slap scanners trade at commodity unit economics below capacitive CMOS arrays, while next-generation ultrasonic through-display modules command technology premiums in smartphone authentication stacks. Three-tier pricing structure across FBI-certified template generators, enterprise middleware subscriptions, and volume sensor contracts separates premium algorithmic licensing from standard hardware procurement. Cost compression in capacitive sensors intensifies because automotive chip demand competes for foundry allocation, squeezing margins for laptop and mid-tier handset suppliers. Government buyers in India's Aadhaar network exhibit lowest price sensitivity due to compliance mandates, while consumer electronics OEMs in China's Pearl River Delta drive hardest unit-cost negotiations.
Supply Chain Analysis
Strategic stockpiling of silicon wafers dominates inventory strategy among sensor vendors exposed to Taiwan and South Korea foundry volatility, contrasting with just-in-time component flows for optical scanner assembly in India and the Middle East. CMOS wafer supply concentrates in Taiwan and South Korea, with downstream module integration splitting between China's Shenzhen semiconductor corridors and domestic Indian assembly for Aadhaar devices. Raw material dependencies span 8-inch silicon wafers, piezoelectric ceramic substrates, and encryption-capable microcontrollers. Single-source vulnerability in Taiwan's foundry ecosystem poses structural risk given automotive chip competition for capacity allocation. Distribution runs through direct OEM supply agreements for smartphone manufacturers and tender-based procurement for government identity programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software solutions and middleware capture disproportionate margin pools through template encryption requirements and FBI certification barriers, with recurring licensing revenue expanding faster than hardware shipment growth. This service-attach dynamic favors vendors architecting platform ecosystems over point-product suppliers.
For Market Incumbents: Shield algorithmic differentiation against facial recognition substitution by accelerating multimodal fusion R&D investments and deepening certification moats through MINEX and FRVT validation pipelines. Consolidate channel control through pre-built Azure AD and Okta connectors that embed biometric hardware into enterprise identity workflows, raising switching costs for financial services buyers in the US and UK.
For New Entrants and Emerging Players: Differentiate on presentation attack detection capabilities for healthcare point-of-care deployments in India's rural HMIS digitization, where ruggedized battery-operated tablets face limited incumbent saturation. Target automotive in-cabin personalization in European electric vehicle platforms, where steering wheel-integrated capacitive sensors lack established supplier relationships. Pursue white-label middleware partnerships with system integrators serving Saudi Arabia's National Information Center tender pipelines.
For Investors and Strategic Acquirers: Algorithm-centric platform vendors with FBI-certified template generators and encrypted edge-processing SDKs represent the highest-conviction acquisition archetype given GDPR-mandated on-device storage requirements. Long-term viability hinges on regulatory divergence between EU AI Act high-risk system designations and emerging Middle Eastern digital identity mandates creating persistent compliance complexity. Watch for inflection when automotive OEMs standardize biometric personalization across electric vehicle platforms, signaling volume scaling beyond smartphone saturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic Sensor Module Specification Capture | Qualcomm's 3D Sonic Sensor standardization in Samsung Galaxy flagships establishes technology roadmap for through-display enrollment. |
| FBI MINEX Certification Investment | Template generator validation creates 12-18 month competitive moats for law enforcement and civil identification eligibility. |
| Enterprise Middleware Platform Integration | Pre-built SCIM and SAML connectors for Azure AD dominate RFP requirements in US and UK financial services procurement. |
| Automotive In-Cabin Sensor Diversification | Steering wheel-integrated capacitive modules enable driver profile authentication for seat and infotainment personalization. |
| Healthcare Ruggedized Tablet Deployment | India's HMIS digitization mandates biometric patient identification at rural clinics with battery-operated enrollment devices. |
Methodological Framework
The analysis maps capacitive sensor commoditization, ultrasonic module premiumization, algorithmic middleware licensing, and multimodal fusion architectures, each validated through primary interviews with fingerprint sensor procurement managers at smartphone OEMs, enterprise CISOs specifying access control systems, UIDAI tender officials, and automotive platform engineers. Secondary validation draws from MIIT cybersecurity standards, RBI biometric verification guidelines, EU AI Act compliance documentation, NIST FRVT accuracy benchmarks, and FBI MINEX certification records. Bottom-up shipment modeling triangulates against top-down market sizing across technology generations and end-use verticals.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling spanning sensor technology type, application workflow, end-user vertical, and geographic regulatory cluster. CAGRs derive from fitted growth curves incorporating foundry capacity constraints, government tender pipeline visibility, and smartphone specification cycle timing. Industry-specific forecast inputs include Aadhaar enrollment device procurement schedules and ultrasonic module adoption rates in premium handset tiers.
Material uncertainties — silicon wafer cost volatility, algorithm certification timeline delays, and regulatory divergence between GDPR-derived consent frameworks and Middle Eastern digital identity mandates — sit outside the modeled envelope. Forecasts reflect assumptions about foundry allocation prioritization and government budget continuity. Revision becomes warranted when automotive chip demand crosses thresholds that displace biometric sensor fabrication capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Biometric Services Platform (Biosp) Market
Biometrics & Identity Management
Palm Vein Biometrics Market
Biometrics & Identity Management
GCC Biometrics Market
Biometrics & Identity Management
Signature Verification Market
Biometrics & Identity Management
Next Generation Biometric Market
Biometrics & Identity Management
Face Voice Biometric Market
Biometrics & Identity Management
United States Facial Recognition Market
Biometrics & Identity Management
Europe Biometrics in Government Market
Biometrics & Identity Management
Global Phone Based Authentication Solution Market
Biometrics & Identity Management
Italy Mobile Biometrics Market
Biometrics & Identity Management
Biometric Scan Software Market
Biometrics & Identity Management
Biometric Smart Cards Market
Biometrics & Identity Management
Identity Theft Protection Services Market
Biometrics & Identity Management
Global Behavioral Biometrics Market
Biometrics & Identity Management
Automated Fingerprint Identification Systems (AFIS) Market
Biometrics & Identity Management
Middle East and Africa Biometrics in Government Market