
 Physical Identity and Access Management (PIAM) Software Market | 2026-2036
Physical Identity and Access Management (PIAM) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Physical Identity and Access Management (PIAM) Software Market Analytics
The gap between premium enterprise-grade PIAM suites and commodity access-control modules is repositioning vendor economics across the sector. HID Global leverages its hardware-software integration to anchor high-margin deployments in critical infrastructure. SailPoint competes through identity governance specialization that extends into physical-cyber convergence. Okta dominates cloud-native access orchestration for distributed corporate footprints.
Physical Identity and Access Management (PIAM) software governs the lifecycle of human identities across physical security infrastructure, integrating credential provisioning, access authorization, and audit logging through centralized policy engines with real-time synchronization to directory services. The system serves commercial and institutional operators requiring unified visibility across doors, gates, elevators, and secure zones. Cloud-based solutions lead technology adoption as organizations abandon brittle on-premise architectures, while biometric systems capture the fastest expansion as liveness detection and contactless modalities displace card-based credentials. Facility management anchors application demand through building automation integration, though visitor management represents the emerging margin pool as regulatory audit requirements tighten.
FAA cybersecurity directives for airport infrastructure, FDA requirements for pharmaceutical manufacturing access control, and NIST SP 800-207 zero-trust architecture standards collectively reshape product specifications and procurement compliance burdens across US installations. EMA good manufacturing practice annexes and EU AI Act biometric governance provisions extend parallel compliance obligations across European healthcare and life sciences deployments. Stakeholders must monitor how converging physical-cyber regulatory frameworks will force architectural decisions between unified platforms versus best-of-breed integrations.
Market Dynamics
Zero-trust security mandates are compressing procurement cycles as NIST SP 800-207 compliance deadlines force immediate architectural overhauls across critical infrastructure operators.
Growth Catalysts
- FAA Cybersecurity Directives:Airport infrastructure operators must deploy converged physical-cyber identity systems to satisfy binding operational mandates, accelerating PIAM procurement timelines.
- Biometric Liveness Detection:Contactless facial and iris recognition systems eliminate card-based credential vulnerabilities while reducing operational friction at high-throughput access points.
- Healthcare Regulatory Pressure:HIPAA audit enforcement and FDA manufacturing access requirements compel hospital networks and pharmaceutical facilities to replace fragmented legacy systems.
Market Restraints
- Semiconductor Supply Concentration:Biometric sensor and edge processing chip fabrication concentrates in Taiwan and South Korea, exposing deployment timelines to geopolitical disruption.
- EU AI Act Biometric Governance:Strict algorithmic transparency and data retention rules impose compliance costs that deter mid-market facility operators from upgrading systems.
- On-Premise Architecture Stranding:Organizations with sunk capital in legacy server infrastructure face prohibitive migration costs to cloud-native PIAM architectures.
Strategic Opportunities
- Visitor Management Monetization:Regulatory audit trail requirements create recurring revenue streams through automated credential provisioning and background verification services.
- Germany Critical Infrastructure Protection:KRITIS designation expansion mandates identity governance upgrades across energy, water, and transport operators previously exempt from federal oversight.
- Building Automation Convergence:Integration between PIAM policy engines and HVAC/lighting control systems enables energy-efficient zone-based access that reduces operational expenditure.
Industry Challenges
- Identity-Cybersecurity Skill Scarcity:Shortage of professionals credentialed in both physical security engineering and cloud identity administration delays enterprise deployment timelines.
- Multi-Vendor Integration Complexity:Facilities managing disparate access control hardware from multiple OEMs struggle to achieve unified policy enforcement without costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Physical Identity and Access Management (PIAM) Software Market |
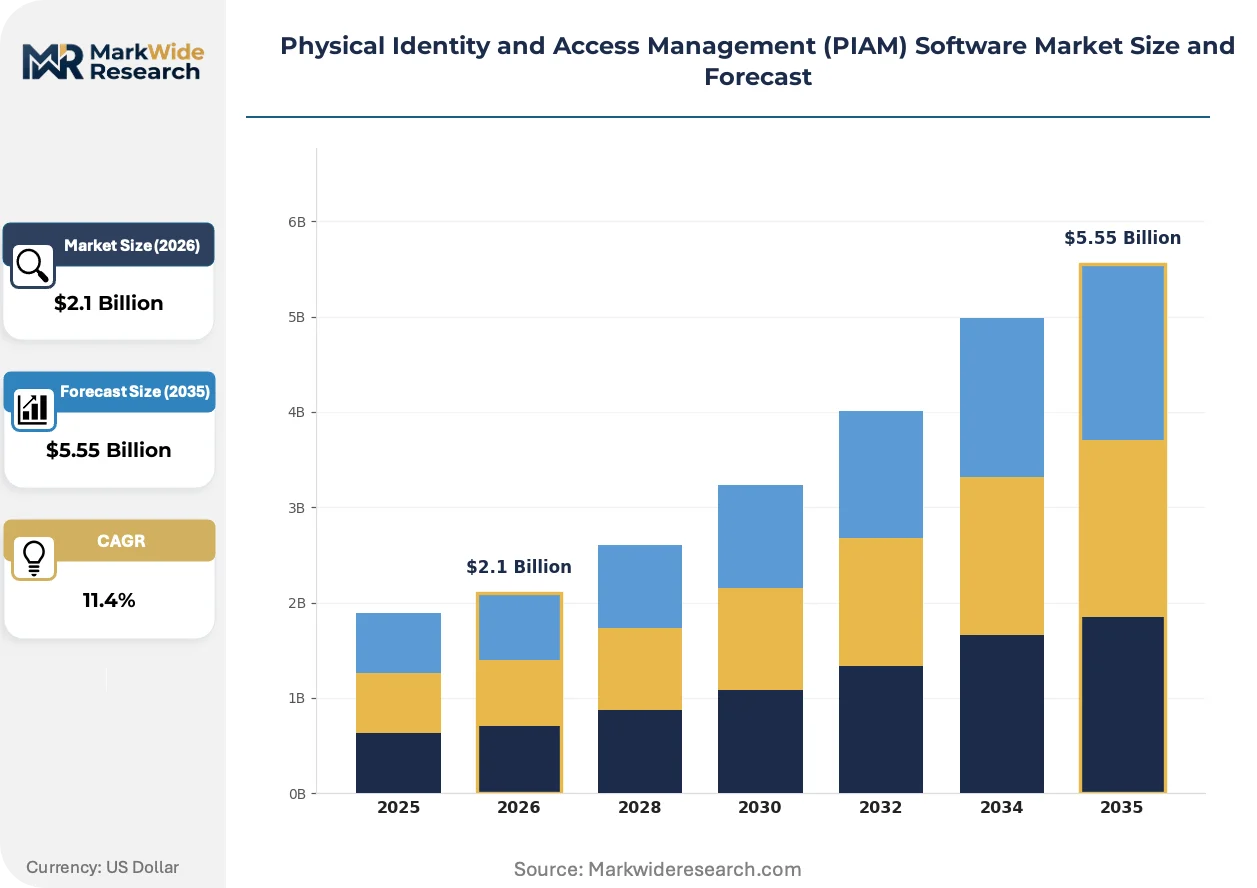
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Facility Management, Attendance Tracking, Visitor Management, Security Monitoring Technology: Biometric Systems, RFID, Cloud-Based Solutions, Mobile Access End User: Healthcare Institutions, Government Offices, Educational Organizations, Corporate Offices Deployment: On-Premise, Cloud, Hybrid, Managed Services |
| Companies Covered | Delinea, SailPoint, HID Global, One Identity, Broadcom, Ping Identity, Okta, Avatier, CyberArk Identity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Physical Identity and Access Management (PIAM) Software Market Evolving Landscape
Convergence between physical access control and cloud identity platforms is dissolving traditional procurement boundaries, forcing vendors to compete on unified policy orchestration rather than hardware dominance.
Contactless biometric modalities incorporating liveness detection and anti-spoofing algorithms are absorbing card-based credential volumes across high-security deployments. Financial services and pharmaceutical manufacturing facilities lead adoption, replacing proximity cards within eighteen-month procurement cycles. The technology is absorbing middleware revenue as direct API integration with directory services eliminates legacy head-end controllers.
NIST SP 800-207 zero-trust architecture standards now govern federal contractor PIAM specifications, mandating continuous authentication and dynamic risk scoring for physical access decisions. Defense industrial base facilities and federally funded research institutions must re-architect perimeter-based systems by compliance deadlines. European operators anticipate parallel ETSI standards that will extend cryptographic binding requirements to biometric credential issuance.
Subscription-based identity-as-a-service models are displacing perpetual license arrangements among mid-market commercial real estate operators. Property management platforms now bundle PIAM functionality with tenant experience applications, compressing standalone vendor margins. Japan and Germany exhibit fastest behavioral transition as facility management outsourcing contracts consolidate technology procurement under single-service integrators.
Physical Identity and Access Management (PIAM) Software Market Segmentation
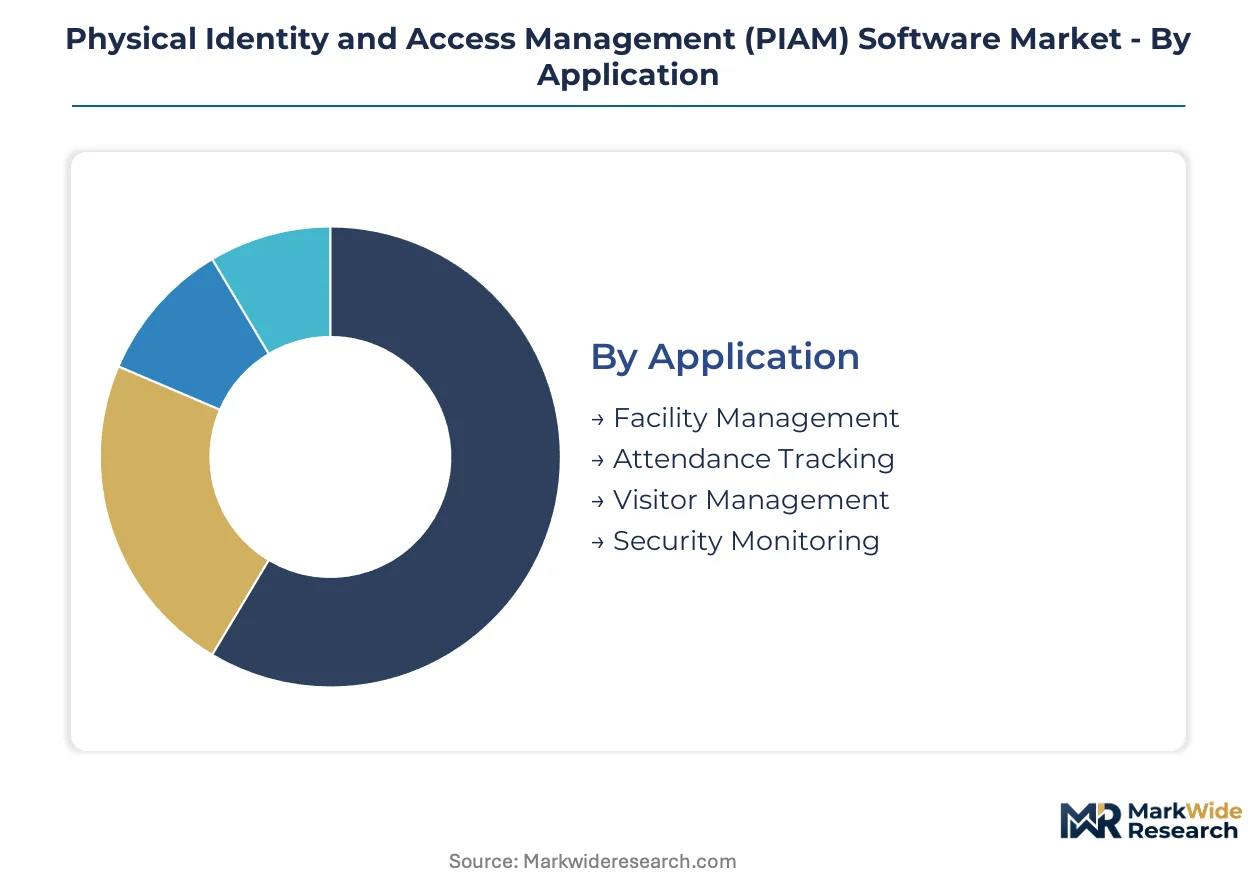
PIAM procurement decisions diverge sharply across application contexts, technology architectures, and compliance environments. Understanding these segmentation boundaries reveals where vendor margins concentrate and where standardization pressures erode pricing power.
Application:
Facility management buyers prioritize building automation integration, while security-focused purchasers emphasize audit trail completeness over operational convenience.
- Facility Management:PIAM platforms synchronize access permissions with HVAC, lighting, and elevator control systems for zone-based energy optimization. Demand concentrates in German commercial real estate and Japanese integrated facility services contracts where operational expenditure reduction drives procurement.
- Visitor Management:Automated credential provisioning, background verification, and regulatory audit trail generation create recurring revenue streams. HIPAA audit enforcement and FDA manufacturing access requirements in US healthcare and pharmaceutical facilities accelerate replacement of paper-based visitor logs.
- Attendance Tracking:Workforce time-and-attendance integration with payroll systems dominates manufacturing and logistics deployments across Taiwan and South Korea electronics assembly facilities.
- Security Monitoring:Real-time anomaly detection and forensic video correlation serve critical infrastructure operators under FAA cybersecurity directives and KRITIS designation requirements.
Facility Management leads on scale; Visitor Management leads on momentum.
Technology:
Technology selection hinges on threat model sophistication versus user experience friction, with biometric systems commanding premium pricing in high-security environments.
- Biometric Systems:Facial recognition with liveness detection and iris scanning eliminate credential sharing vulnerabilities while enabling contactless throughput. Financial services in Singapore and pharmaceutical manufacturing in Switzerland lead adoption, displacing proximity cards within compressed procurement cycles.
- Cloud-Based Solutions:API-native architectures with directory service synchronization replace brittle on-premise head-end controllers. Mid-market commercial real estate in Japan and Germany transitions fastest as property management platforms bundle PIAM with tenant experience applications.
- RFID:Legacy proximity and smart card credentials persist in cost-sensitive education and government segments where infrastructure replacement cycles extend beyond seven years.
- Mobile Access:Smartphone-based credentials leveraging BLE and NFC reduce hardware issuance costs for corporate campuses with high employee turnover.
Cloud-Based Solutions capture volume expansion; Biometric Systems capture value expansion.
End User:
End-user verticals impose distinct compliance architectures that reshape product specifications and sales cycle duration.
- Healthcare Institutions:HIPAA audit enforcement and FDA manufacturing access requirements compel hospital networks to replace fragmented legacy systems with unified identity governance platforms.
- Government Offices:NIST SP 800-207 zero-trust mandates and classified facility requirements drive federal contractor procurement toward continuous authentication architectures.
- Educational Organizations:Campus-wide physical security integration with student information systems dominates K-12 and university deployments where budget constraints favor phased implementation.
- Corporate Offices:Multi-tenant commercial real estate and enterprise headquarters prioritize visitor experience and space utilization analytics over perimeter hardening.
Healthcare Institutions anchor compliance-driven replacement demand; Government Offices anchor specification-setting influence.
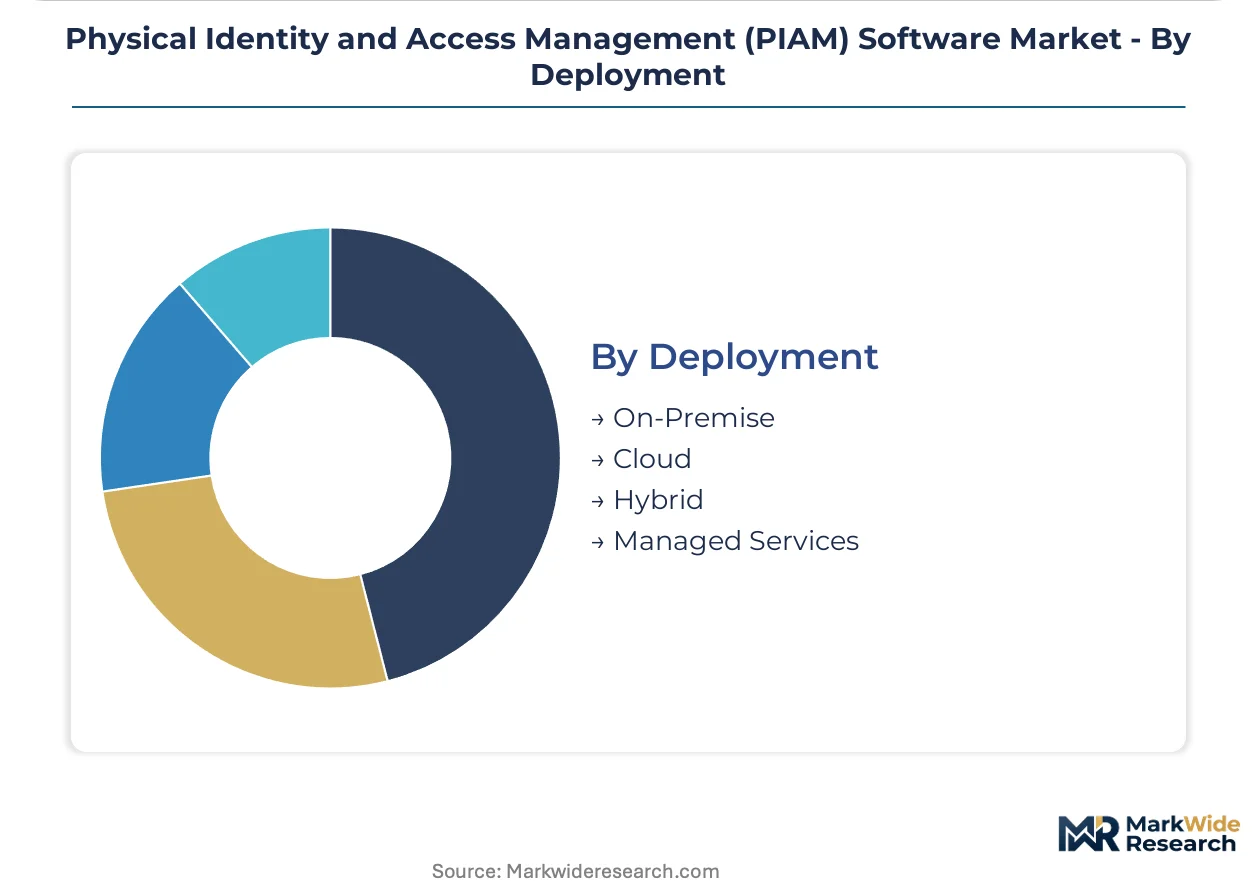
Deployment:
Deployment architecture decisions reflect capital availability, data residency requirements, and internal identity administration capabilities.
- Cloud:Subscription-based identity-as-a-service models displace perpetual licenses among mid-market operators lacking dedicated security engineering staff.
- Hybrid:Edge credential validation with cloud policy management serves critical infrastructure operators requiring local autonomy during network disruption.
- On-Premise:Sunk capital in legacy server infrastructure and strict data localization mandates preserve this architecture in defense and intelligence installations.
- Managed Services:Outsourced identity administration and 24/7 security operations center integration appeals to distributed retail and hospitality chains.
Cloud deployment leads adoption velocity; Hybrid architectures lead resilience requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German critical infrastructure operators outpace Japanese facility managers in zero-trust compliance urgency, while United States federal contractors face the most compressed procurement timelines worldwide.
United States
FAA cybersecurity directives and NIST SP 800-207 mandates force airport operators and defense contractors into immediate PIAM overhauls. Federal procurement specifications now require continuous authentication architectures for physical access. Dallas-Fort Worth and Atlanta airport authorities lead deployment velocity among hub facilities.
Germany
KRITIS designation expansion mandates identity governance upgrades across energy and water utilities previously exempt from federal oversight. EMA good manufacturing practice annexes impose parallel compliance burdens on pharmaceutical manufacturers. The Rhine-Ruhr industrial corridor concentrates demand from chemical and automotive facilities integrating building automation.
Japan
Integrated facility services contracts consolidate PIAM procurement under single-service integrators, accelerating cloud-native transitions. METI cybersecurity guidelines for critical infrastructure reshape vendor selection criteria. Tokyo and Osaka commercial real estate markets exhibit fastest behavioral shift toward subscription-based identity-as-a-service models.
Switzerland
Swissmedic pharmaceutical manufacturing standards and banking secrecy requirements sustain demand for on-premise and hybrid deployment architectures. Geneva and Basel life sciences clusters prioritize biometric liveness detection for high-security cleanroom access. Financial services in Zurich displace proximity cards with iris recognition systems.
Singapore
Smart nation infrastructure investments and maritime port security mandates drive biometric system adoption across logistics and financial services. The Monetary Authority of Singapore's operational resilience requirements compel banks to unify physical-cyber identity governance. The Jurong Island petrochemical complex anchors industrial demand for zone-based access control.
Physical Identity and Access Management (PIAM) Software Market Competitive Landscape
Top-tier vendors anchor enterprise-grade suites with hardware-software integration, while mid-market specialists compete through cloud-native orchestration and vertical-specific compliance modules. The vendor base stratifies across three archetypes: legacy access control hardware extenders, pure-play identity governance platforms, and converged physical-cyber security suites. Dominant competitive moves include strategic partnerships with building automation OEMs and technology licensing for biometric algorithm integration.
Within the converged security suite tier, HID Global and SailPoint exemplify divergent strategic positioning—HID Global represents hardware-anchored integration plays while SailPoint occupies the identity governance specialization vector. Okta anchors cloud-native access orchestration for distributed corporate footprints. These three vendors collectively illustrate how procurement boundaries between physical access and cloud identity platforms are dissolving.
| Leading Market Players |
|---|
| Delinea |
| SailPoint |
| HID Global |
| One Identity |
| Broadcom |
| Ping Identity |
| Okta |
| Avatier |
| CyberArk Identity |
| Others |
Value Network & Pricing Analysis
Semiconductor wafer pricing indices cascade through PIAM hardware tiers, compressing margins on biometric sensors while cloud-native software subscriptions absorb cost volatility through recurring revenue structures. Taiwan foundry capacity allocations directly determine price floors for edge processing modules deployed in critical infrastructure access points.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for biometric sensor modules, forcing tiered pricing stratification across premium liveness-detection systems, standard facial recognition units, and economy-grade proximity card readers. Price differentiation hinges on NIST SP 800-207 certification tiers and algorithmic transparency compliance under EU AI Act biometric governance provisions. Pricing pressure intensifies in the RFID credential segment as cloud-native mobile access alternatives displace hardware-dependent revenue streams. Mid-market commercial real estate operators exhibit highest price sensitivity, while defense contractors and pharmaceutical manufacturers under FDA manufacturing access mandates absorb premium pricing for certified systems.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific semiconductor hubs to European and North American assembly facilities amplifies working capital requirements for PIAM hardware vendors managing just-in-time delivery contracts. Component sourcing concentrates in Taiwan for biometric sensors, South Korea for edge AI processors, and China for RFID credential manufacturing. Raw material dependencies include silicon wafers, specialized optical lenses, and secure element chips for cryptographic credential issuance. Single-source vulnerability in Taiwan-based liveness-detection algorithm licensing creates concentration risk for premium biometric system vendors. Distribution runs through systems integrators and facility management outsourcing contracts, with direct enterprise sales capturing high-margin government and healthcare verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PIAM procurement has shifted toward late-cycle quality specifications as zero-trust mandates and biometric governance rules elevate compliance requirements above cost minimization. Premium-tier vendors with integrated hardware-software certification stacks capture disproportionate margin expansion.
For Market Incumbents: Anticipate margin compression in commoditized RFID credential segments as cloud-native competitors displace legacy controller architectures. Defensive consolidation moves should prioritize backward integration into biometric algorithm development and certification investment for EU AI Act compliance. Channel control through exclusive systems integrator partnerships in Germany and Japan protects installed-base revenue against pure-play SaaS entrants. For New Entrants and Emerging Players: Enter via visitor management automation in US healthcare networks, where HIPAA audit enforcement creates immediate replacement demand for paper-based credential logs. The most penetrable white-space target lies in mid-market German commercial real estate under KRITIS designation expansion, where facility management outsourcing contracts consolidate procurement decisions. A vertical-specific go-to-market angle emphasizing automated background verification and regulatory audit trail generation differentiates against generic access control platforms. For Investors and Strategic Acquirers: Consolidation pressure builds where identity-cybersecurity skill scarcity delays enterprise deployment timelines and fragments vendor execution capability. Long-term viability favors converged physical-cyber security suites with demonstrated federal contractor certification and building automation OEM partnerships. Acquisition target archetypes include biometric algorithm specialists with liveness-detection IP and cloud-native orchestration platforms with healthcare vertical penetration. The signal to watch is NIST SP 800-207 compliance deadline acceleration among defense industrial base facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Algorithm Acquisition | Captures liveness-detection IP essential for EU AI Act compliance and high-security cleanroom deployments. |
| Building Automation OEM Partnership | Enables zone-based energy optimization integration demanded by German commercial real estate operators. |
| Zero-Trust Architecture Certification | Unlocks federal contractor procurement under NIST SP 800-207 mandates with compressed timeline requirements. |
| Visitor Management Platform Launch | Addresses HIPAA audit trail automation replacing paper-based logs in hospital networks. |
| Identity-as-a-Service Geographic Expansion | Captures Japanese facility management outsourcing contract consolidation under METI cybersecurity guidelines. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with physical security directors, IT procurement officers, facility management executives, and biometric systems integrators alongside secondary validation. Primary fieldwork drew from hospital network security committees, airport authority technology divisions, pharmaceutical manufacturing compliance leads, and commercial real estate asset managers. Secondary sources encompassed FAA cybersecurity directive filings, EMA good manufacturing practice annexes, NIST SP 800-207 implementation guidance, and METI critical infrastructure guidelines. Bottom-up deployment modeling and top-down market sizing triangulated volume estimates across technology and application segments.
Rate-of-change decomposition anchored the analytical framework, disaggregating growth across the projection horizon into replacement-cycle acceleration, compliance-mandated upgrade intensity, and net-new facility penetration. Segmentation dimensions modeled encompass deployment architecture, organization size tier, vertical industry, integration complexity level, and regional regulatory cluster. CAGRs derived from fitted adoption curves calibrated against historical procurement velocity in comparable security technology markets. Industry-specific forecast inputs included KRITIS designation expansion timelines, FDA manufacturing access enforcement patterns, and biometric sensor cost curves from semiconductor supply chain disclosures.
Inputs from regulatory filing databases and systems integrator contract announcements were available through the study window; gaps in real-time procurement pipeline visibility from classified defense installations introduce uncertainty bands around government vertical estimates. Forecasts reflect assumptions regarding zero-trust mandate compliance deadlines and EU AI Act biometric governance implementation pacing. A model refresh is warranted upon material change in FAA cybersecurity directive enforcement intensity or Taiwan semiconductor supply disruption severity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Biometrics Banking Market
Biometrics & Identity Management
Global Phone Based Authentication Solution Market
Biometrics & Identity Management
Biometric Data Encryption Device Market
Biometrics & Identity Management
Face Voice Biometric Market
Biometrics & Identity Management
Airport Biometrics Market
Biometrics & Identity Management
Biometric Services Platform (Biosp) Market
Biometrics & Identity Management
Signature Verification Market
Biometrics & Identity Management
Global Biometric Technology Market
Biometrics & Identity Management
GCC Biometrics Market
Biometrics & Identity Management
North America Enterprise Biometrics Market
Biometrics & Identity Management
Latin America Biometrics Market
Biometrics & Identity Management
Authentication Solution Market
Biometrics & Identity Management
Global Mobile User Authentication Market
Biometrics & Identity Management
E-Government Identity Management Market
Biometrics & Identity Management
Germany Identity Verification and Authentication Market
Biometrics & Identity Management
Hand Geometry Biometrics Market