
 Europe Border Security Market | 2026-2036
Europe Border Security Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Border Security Market Foresight
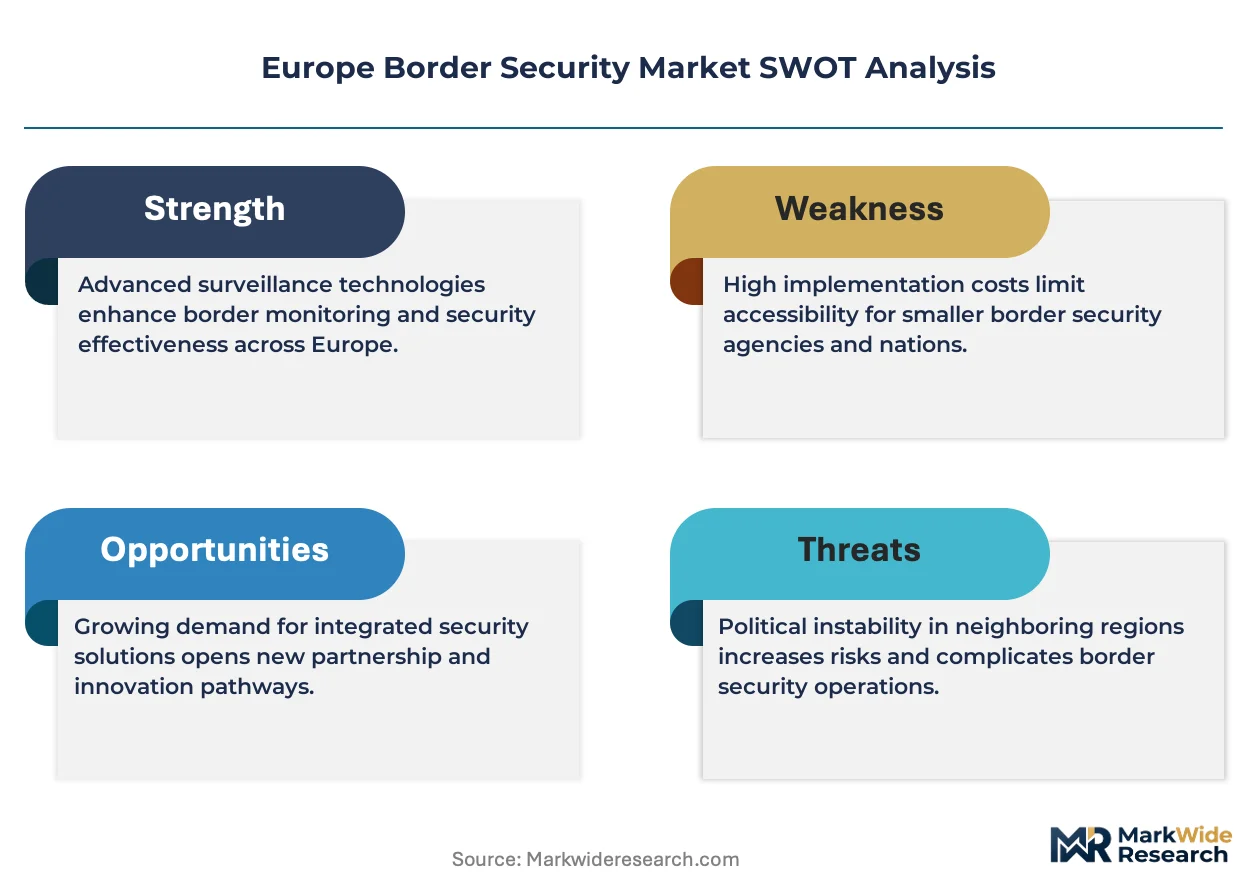
Modular system bundling is recalibrating how European border agencies evaluate procurement options, shifting from standalone hardware purchases toward integrated platform contracts. Thales Group leverages its command-and-control software heritage to anchor multi-domain border architectures spanning land and maritime domains. Leonardo competes through specialized radar and electro-optic payloads designed for harsh Mediterranean and Baltic operating conditions. BAE Systems extends its footprint via intelligence-fusion systems that consolidate sensor feeds into unified situational awareness displays for frontline operators.
Europe border security encompasses the integrated hardware, software, and service infrastructure deployed to monitor, detect, and interdict unauthorized cross-border movement across land, maritime, and aerial frontiers, incorporating sensor densities measured in detection probability per kilometer and response latency thresholds under sixty seconds. Surveillance systems command the largest value share as coastal and green-border states replace aging camera networks with multi-spectral platforms; biometrics represents the fastest-expanding solution category as facial recognition and fingerprint matching migrate from airport checkpoints to land border crossings. Video analytics technology is displacing human-only monitoring at scale, while thermal imaging maintains premium positioning for night and adverse-weather operations where electro-optical performance degrades.
The European Border and Coast Guard Agency (Frontex) operational mandates under EU Regulation 2019/1896 shape equipment interoperability standards and joint procurement frameworks across member states. EASA certification requirements for unmanned aerial systems deployed in border patrol corridors constrain platform selection and integration timelines for national agencies. Schengen Borders Code enforcement protocols mandate standardized data exchange formats that drive software architecture decisions. Stakeholders must monitor the interplay between EU defense-industrial sovereignty initiatives and existing transatlantic technology supply relationships as localization pressures intensify.
Market Dynamics
Modular procurement frameworks under EU Regulation 2019/1896 are compressing equipment refresh cycles as Frontex operational mandates force interoperability upgrades across member state border agencies.
Growth Catalysts
- Schengen Borders Code enforcement protocols:Mandated data exchange formats accelerate software architecture investments at land crossings in Poland and Romania.
- Biometric screening migration:Facial recognition and fingerprint matching systems deploy from airports to green borders, expanding addressable infrastructure scope.
- Maritime domain awareness gaps:Mediterranean and Baltic coastal states replace aging radar networks with multi-spectral surveillance platforms.
Market Restraints
- Dual-use export control complexity:EU defense-industrial sovereignty initiatives create friction in transatlantic sensor supply relationships.
- EASA certification timelines:Unmanned aerial system airworthiness requirements extend platform integration schedules by 18-24 months.
- Electro-optical performance degradation:Adverse weather conditions in North Sea corridors limit camera-only surveillance effectiveness.
Strategic Opportunities
- Green border underpenetration:Forest and mountain crossings in Slovakia and Hungary lack integrated sensor density present at coastal frontiers.
- Video analytics convergence:Machine learning overlays on thermal imaging compress false-alarm rates for night operations.
- Joint procurement frameworks:Frontex pooled purchasing mechanisms reduce per-unit costs for smaller member state agencies.
Industry Challenges
- Cyber-physical integration complexity:Legacy analog camera networks in Portugal and Greece resist seamless feed consolidation into unified command platforms.
- Specialized technician scarcity:Multi-spectral sensor calibration and AI model retraining require skills concentrated in defense contractor workforces.
- Interoperability certification backlog:National agencies queue for EU-standardized interface validation before deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Border Security Market |
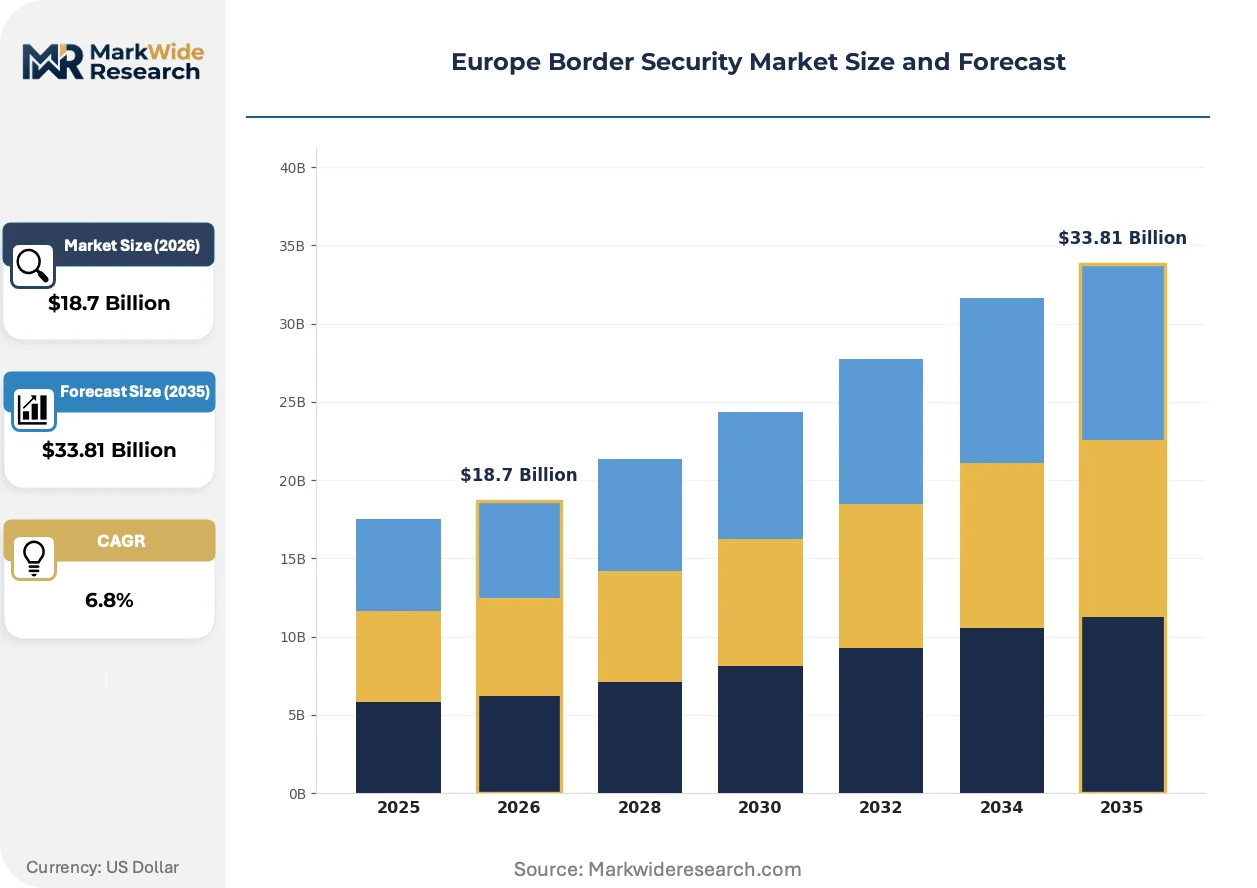
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Surveillance Systems, Access Control, Perimeter Security, Biometrics Technology: Facial Recognition, Radar, Video Analytics, Thermal Imaging End User: Government, Military, Airport Security, Maritime Authorities Installation: Fixed Systems, Mobile Units, Software Integration, On-Site Services |
| Companies Covered | Thales Group, BAE Systems, RTX Corporation, Indra Sistemas, Leidos, Leonardo, Airbus, Safran, General Dynamics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Border Security Market Shifts & Advancements
Artificial intelligence is compressing response latency thresholds while regulatory mandates harden data sovereignty requirements across member state procurement.
Multi-spectral sensor fusion is expanding into standardized border architectures. Thales Group and Leonardo anchor integrated platform contracts spanning radar, electro-optic, and biometric subsystems. National agencies in Germany and France now specify unified situational awareness displays rather than standalone hardware purchases, collapsing vendor negotiation cycles.
EU AI Act risk classification rules now govern automated decision systems at external borders. High-risk biometric identification deployments require conformity assessments and human oversight protocols. Mediterranean member states delay facial recognition procurement until national regulators publish implementation guidance.
Consolidated maintenance contracts displace discrete equipment warranties. Polish and Romanian border agencies now procure ten-year service bundles covering sensor refresh, software updates, and operator training. Channel partners with embedded technical teams capture recurring revenue streams previously fragmented across multiple suppliers.
Europe Border Security Market Segmentation
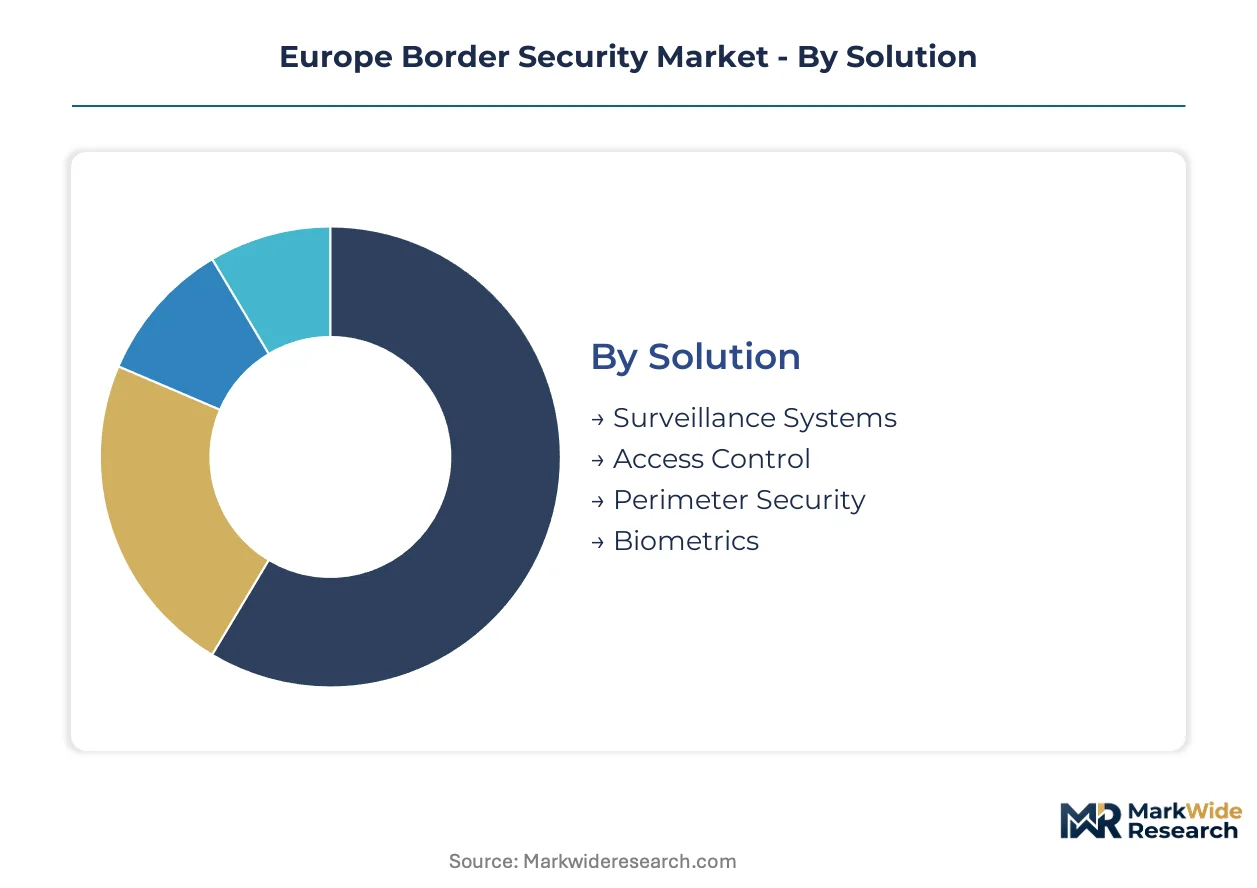
Border security procurement in Europe fragments across solution architectures, sensing technologies, operational end users, and deployment modalities. Understanding these segment boundaries clarifies where interoperability mandates from Frontex concentrate investment versus where national agencies retain procurement autonomy.
Solution:
Standardization pressures from EU Regulation 2019/1896 dominate surveillance and biometrics, while perimeter and access systems retain more national customization latitude.
- Surveillance Systems:Multi-spectral camera networks, radar arrays, and electro-optic towers form the backbone of coastal and green-border monitoring. Polish and Romanian land crossings drive replacement demand as Schengen Borders Code enforcement mandates unified data formats for cross-border coordination.
- Biometrics:Facial recognition and fingerprint matching systems migrate from airport terminals to vehicle checkpoints and pedestrian gates. Mediterranean member states delay procurement until national regulators publish EU AI Act implementation guidance for high-risk automated identification.
- Access Control:Credential verification gates and document authentication stations process authorized cross-border movement at Schengen external frontiers.
- Perimeter Security:Physical barriers, intrusion detection cables, and ground sensors protect remote border sections where infrastructure electrification remains incomplete.
Leading the category by volume: Surveillance Systems. Growing fastest: Biometrics.
Technology:
Cost tiers separate mature electro-optic hardware from AI-enabled software layers that command premium pricing and recurring service contracts.
- Video Analytics:Machine learning algorithms reduce false-alarm rates on thermal and visual feeds, compressing operator workload for night operations. German and French border agencies now specify unified situational awareness displays rather than standalone hardware, collapsing vendor negotiation cycles toward software-centric awards.
- Thermal Imaging:Uncooled infrared sensors maintain detection capability through North Sea fog and Baltic winter conditions where standard cameras degrade. Coastal states in the Mediterranean basin prioritize these systems for small-vessel interdiction.
- Facial Recognition:Deep learning matching engines compare live captures against watchlist databases at processing speeds under two seconds per query.
- Radar:Ground and coastal surveillance radars track movement across terrain and surface vessels beyond electro-optical range.
Commanding the highest unit margins: Video Analytics. Expanding most quickly: Thermal Imaging.
End User:
Customer type determines procurement channel — pooled Frontex frameworks for government agencies versus bilateral national contracts for military and specialized maritime authorities.
- Government:National border guard services and interior ministries operate land crossing infrastructure across the Schengen external frontier. Polish and Romanian agencies leverage joint procurement mechanisms to reduce per-unit costs for integrated sensor platforms.
- Maritime Authorities:Coast guard services and port police manage blue-border surveillance across Mediterranean and Baltic corridors. These agencies replace aging radar networks with multi-spectral platforms capable of small-vessel detection at ranges exceeding legacy systems.
- Military:Defense ministries deploy hardened border security assets in contested or high-threat zones requiring encrypted command links.
- Airport Security:Civil aviation authorities maintain biometric checkpoints for passenger processing, increasingly sourcing from the same vendor pools as land border agencies under interoperability mandates.
Driving the largest contract values: Government. Gaining share fastest: Maritime Authorities.
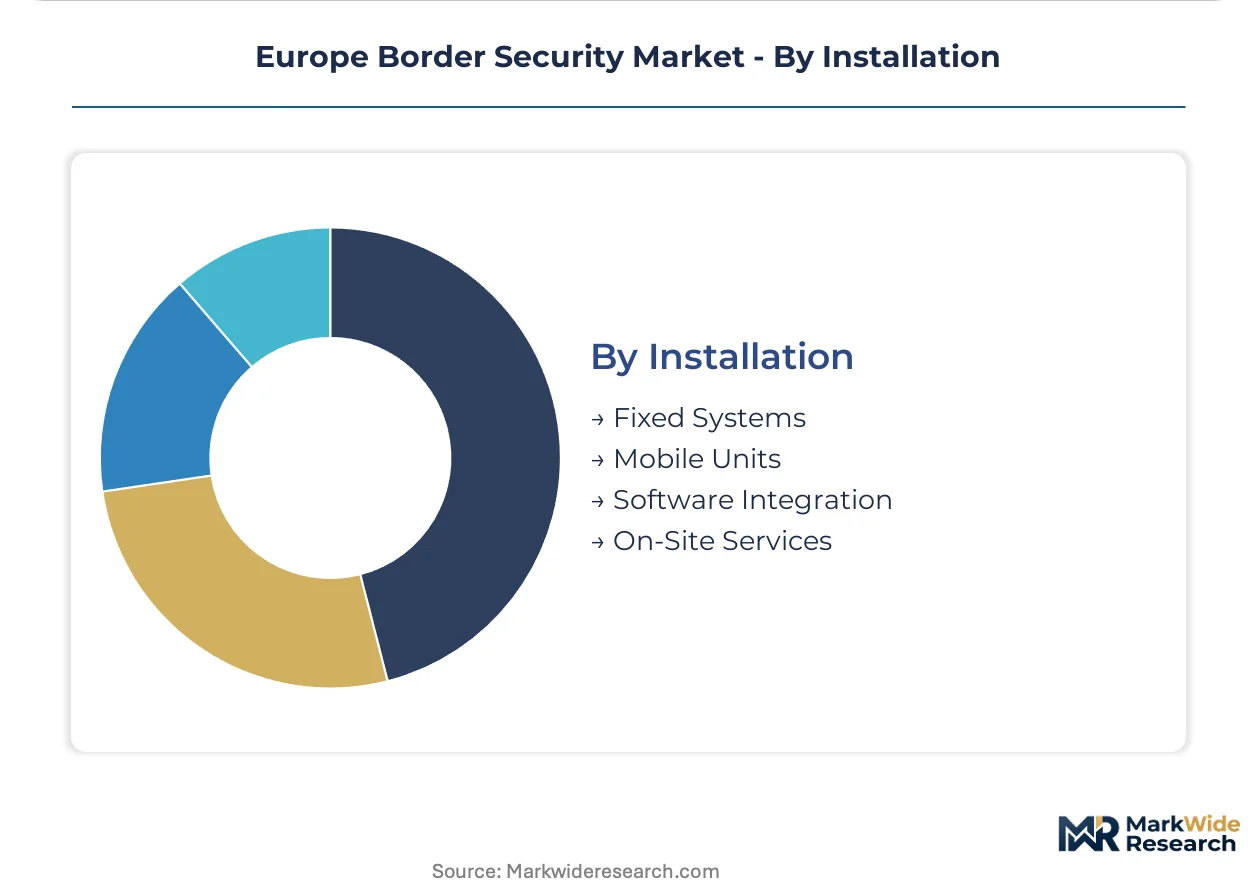
Installation:
Deployment modality shapes margin structure — fixed hardware carries lower lifetime service attachment, while software integration and mobile units generate recurring revenue streams.
- Fixed Systems:Permanent camera towers, radar masts, and biometric gates anchor border infrastructure at high-throughput crossings. Portuguese and Greek agencies struggle with legacy analog networks that resist seamless feed consolidation into unified command platforms.
- Software Integration:Middleware layers consolidate sensor feeds, enable cross-system interoperability, and host AI analytics engines. Polish and Romanian border agencies now procure ten-year service bundles covering sensor refresh, software updates, and operator training.
- Mobile Units:Vehicle-mounted surveillance platforms and deployable drone systems patrol remote border sections without permanent infrastructure.
- On-Site Services:Technical teams embedded with border agencies perform calibration, maintenance, and operator training under long-term service contracts.
Generating the highest renewal rates: Software Integration. Climbing the fastest: Mobile Units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Border security production concentrates among defense-industrial clusters in France, Germany, and Italy, while consumption spreads across external frontier states from Poland to Greece. Schengen external border exposure drives procurement intensity in member states facing migration pressure and maritime infiltration corridors.
Germany
Federal Police and customs authorities drive integrated platform procurement for land crossings into Poland and Czechia. Germany's implementation of EU Regulation 2019/1896 mandates interoperability upgrades across federal and state-level border agencies. The Munich-Stuttgart corridor hosts Thales and Airbus defense operations supplying command-and-control architectures.
France
Maritime surveillance demand dominates as coast guard services patrol Mediterranean and Atlantic approaches under Frontex operational mandates. France's EU AI Act conformity assessment procedures delay facial recognition deployment at land borders pending national regulator guidance. The Paris-Saclay cluster anchors Thales Group's border security engineering and systems integration capabilities.
Poland
External Schengen frontier exposure with Belarus and Ukraine sustains perimeter detection and biometric screening investment. Poland's adoption of Frontex joint procurement frameworks reduces per-unit costs for multi-spectral surveillance platforms. The Warsaw-Łódź corridor concentrates system integrators serving eastern border modernization programs.
Italy
Central Mediterranean migration routes drive coastal radar and electro-optic tower deployment under naval and coast guard coordination. Italy's Schengen Borders Code enforcement protocols require standardized data exchange formats with Maltese and Greek counterparts. The Rome-Genoa axis hosts Leonardo's maritime surveillance payload development and naval systems engineering.
Spain
Ceuta and Melilla enclave borders with Morocco sustain hardened perimeter infrastructure and rapid response mobile units. Spain's EASA certification requirements for unmanned aerial systems constrain platform integration timelines for southern coastal patrols. The Madrid-Toulouse aerospace corridor supports Airbus border surveillance drone development and cross-border industrial coordination.
Europe Border Security Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across layered procurement channels. The vendor base splits between full-spectrum platform integrators and component-level sensor suppliers. Three archetypes dominate: aerospace-defense conglomerates with software heritage, radar-electro-optic specialists, and intelligence-fusion system providers. Competitive moves center on multi-year service bundling and interoperability certification capture.
Among the aerospace-defense tier, Thales Group and Leonardo exemplify integrated platform strategies spanning command software and multi-spectral payloads. BAE Systems occupies a position in intelligence-fusion architectures that consolidate heterogeneous sensor feeds. These three anchors represent contrasting approaches to the shift from standalone hardware toward ten-year service contracts covering refresh cycles and operator training.
| Leading Market Players |
|---|
| Thales Group |
| BAE Systems |
| RTX Corporation |
| Indra Sistemas |
| Leidos |
| Leonardo |
| Airbus |
| Safran |
| General Dynamics |
| Others |
Supply & Pricing Matrix
Sovereign-backed defense conglomerates in France, Germany, and Italy anchor supply-side concentration, translating into pricing discipline that resists commoditization even as modular procurement frameworks compress equipment refresh cycles. Frontex joint purchasing mechanisms introduce countervailing buyer power, yet ten-year service bundling contracts preserve vendor margins through recurring software and training revenues.
Pricing Analysis
Margin tightening in biometric subsystems reflects EU AI Act conformity assessment delays that extend sales cycles and inflate pre-certification engineering costs. Three-tier pricing structure across premium, standard, and economy levels separates Thales Group's command-and-control architectures from Leonardo's specialized radar payloads and generic electro-optic component suppliers. Price differentiation hinges on interoperability certification depth and embedded AI analytics capability. Polish and Romanian border agencies exhibit highest price sensitivity as joint procurement participants, while German Federal Police prioritize performance over unit cost.
Supply Chain Analysis
Thermal sensor supply rests on French and German uncooled infrared foundries, with critical semiconductor components drawing from Dutch ASML lithography-dependent fabs and Taiwanese specialty chip packaging. Multi-spectral camera assemblies hinge on German precision optics, Israeli image-processing chipsets, and Japanese sensor substrates. Single-source vulnerability concentrates in EUV-dependent processor supply for AI-enabled video analytics. Distribution runs through national defense procurement offices and Frontex pooled purchasing frameworks rather than commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained specialized technician scarcity props pricing for calibration and AI model retraining services, creating durable margin pools for embedded technical teams.
For Market Incumbents: Deploy ten-year service bundling as the anchor lever to lock out modular component competitors. Capture interoperability certification backlog queues through advance engagement with Frontex standard-setting processes. Consolidate position by acquiring channel partners with embedded Polish and Romanian technical teams before smaller agencies complete joint procurement migrations. For New Entrants and Emerging Players: Forest and mountain crossing agencies in Slovakia and Hungary represent an underserved buyer archetype lacking integrated sensor density present at coastal frontiers. Penetrate through portable mobile surveillance units with rapid-deployment drone packages bypassing fixed infrastructure electrification gaps. Partner with national system integrators in the Warsaw-Łódź corridor to access Frontex framework eligibility. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap software integration specialists in Portugal and Greece struggling with legacy analog camera network consolidation. Long-term viability hinges on AI Act compliance capability and Frontex certification track record. Watch EASA unmanned aerial system airworthiness ruling timelines as inflection indicator for platform integration demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Interoperability Certification Capture | Frontex standard alignment secures multi-year platform contracts across member state agencies. |
| AI Model Retraining Service Bundling | Embedded technical teams generate recurring revenue streams previously fragmented across suppliers. |
| Mobile Surveillance Platform Development | EASA certification timelines constrain competitors while rewarding early airworthiness investment. |
| Green Border Sensor Density Expansion | Slovak and Hungarian forest crossings lack coastal-equivalent infrastructure investment. |
| Biometric System Conformity Assessment | EU AI Act high-risk classification mandates human oversight protocols before deployment. |
Research Methodology
Document review covered Frontex operational mandates, EU Regulation 2019/1896 implementation guidance, and EASA unmanned system certification databases, complemented by interviews with border guard procurement officers, defense systems integrators, and multi-spectral sensor engineering leads. Secondary validation drew from Schengen Borders Code enforcement protocols, national defense ministry budget disclosures, and customs procurement registries. Bottom-up equipment deployment tracking triangulated against top-down member state security expenditure aggregates.
Segment-level outputs across the analysis window reflect modeled projections for surveillance systems, biometrics, access control, and perimeter security by technology layer and end-user archetype. CAGRs derived from equipment refresh cycle compression rates, biometric migration penetration curves, and maritime domain awareness investment trajectories. Forecast inputs incorporated Frontex joint procurement volume commitments, EASA certification pipeline backlogs, and EU AI Act implementation guidance publication schedules.
Revisions become necessary when EASA unmanned aerial system rulemaking accelerates, EU defense-industrial sovereignty initiatives disrupt transatlantic sensor supply relationships, or Frontex operational mandates expand beyond current Schengen external frontier scope. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Explosive Trace Detection Market
Security and Surveillance
Lawful Interception Market
Security and Surveillance
Security Operations Center Market
Security and Surveillance
Sirens Market
Security and Surveillance
Global Law Enforcement Software Market
Security and Surveillance
Alarm Monitoring Software Market
Security and Surveillance
Prescriptive Security Market
Security and Surveillance
Private Military Security Services Market
Security and Surveillance
Europe Security Services Market
Security and Surveillance
Europe Rockfall Radar Market
Security and Surveillance
Global Intrusion Detection System Market
Security and Surveillance
Proactive Security Market
Security and Surveillance
TSCM Equipment Market
Security and Surveillance
Perimeter Security Market
Security and Surveillance
Global Bot Security Market
Security and Surveillance
X-Ray Security Screening System Market