
 Airport Biometrics Market | 2026-2036
Airport Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Biometrics Market Analysis
Airport security screening is pivoting toward fully automated identity verification corridors, reducing manual document checks at congested checkpoints. NEC Corporation leverages its algorithm leadership in one-to-many facial matching to dominate large-hub deployments across Asia-Pacific. Thales Group anchors European market presence through ICAO-compliant e-gate integrations that sustain multi-year service contracts with major carriers.
Airport biometrics encompasses hardware and software systems that capture, process, and match unique physiological identifiers—typically facial geometry, fingerprint minutiae, or iris patterns against templates stored in secure databases—with matching accuracy thresholds often exceeding one false match per million attempts, primarily to verify passenger identity across touchpoints from curb to gate. Facial recognition systems command the largest installed base among product types due to their contactless operation and compatibility with existing camera infrastructure, while cloud-based technology architectures are displacing legacy on-premises deployments as airports seek elastic capacity during peak travel seasons. Integrated systems that unify enrollment, authentication, and data management functions capture disproportionate margin pools compared with point solutions.
The United States Transportation Security Administration and Customs and Border Protection enforce biometric entry-exit mandates that shape procurement specifications for federal compliance, while the European Union AI Act and GDPR impose algorithmic transparency and data retention limits that restrict vendor design choices. The International Civil Aviation Organization's Doc 9303 standards for machine-readable travel documents further constrain interoperability requirements. Stakeholders must monitor evolving national biometric data governance frameworks as divergent privacy regimes fragment supplier certification burdens across operating regions.
Market Dynamics
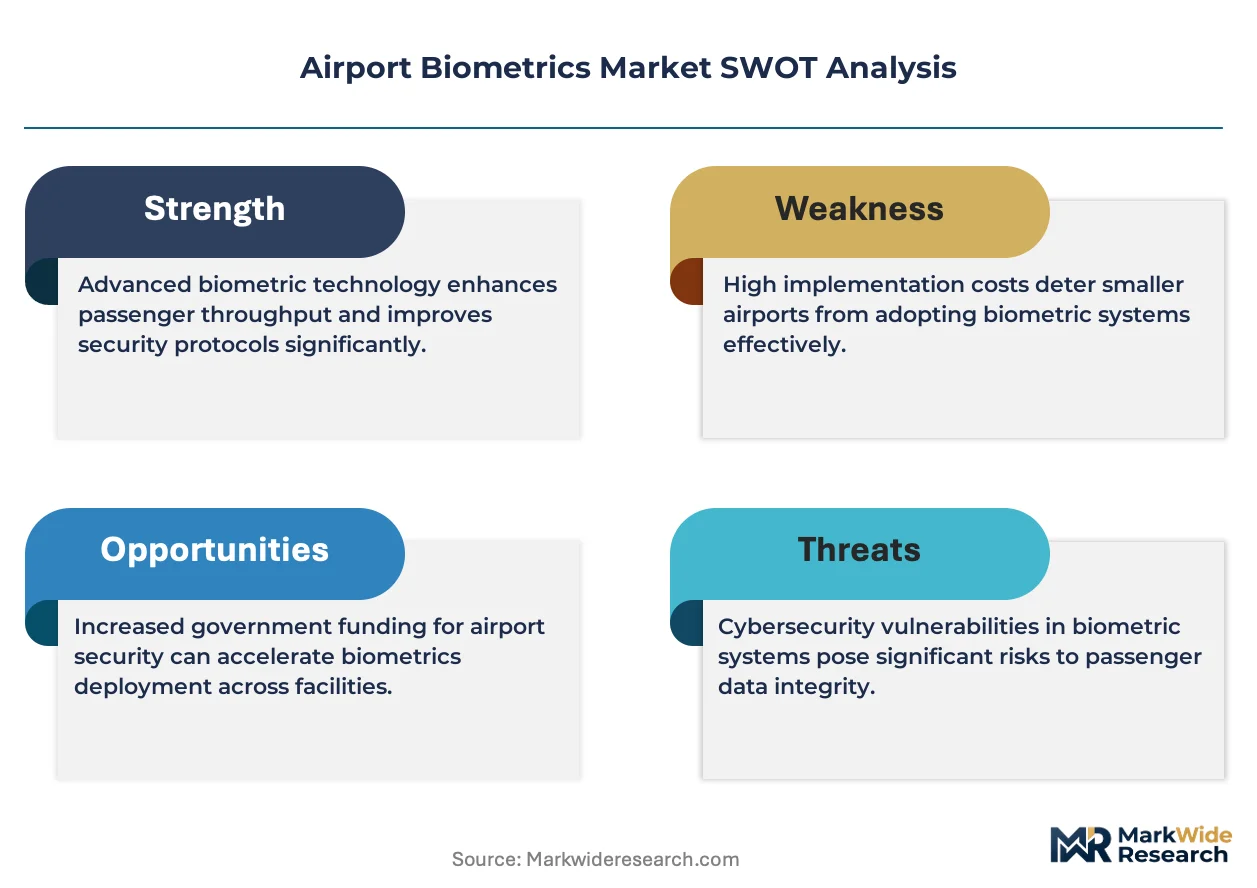
The airport biometrics sector is reconfiguring around regulatory fragmentation as the EU AI Act and GDPR impose algorithmic transparency mandates that diverge sharply from US federal biometric entry-exit requirements, forcing vendors to maintain parallel certification tracks.
Growth Catalysts
- TSA PreCheck Expansion:The Transportation Security Administration's enrollment growth mandates contactless identity verification infrastructure at security checkpoints across major US hubs.
- ICAO Doc 9303 Standards:Machine-readable travel document specifications drive interoperability investments that enable cross-border biometric data exchange between immigration authorities.
- Contactless Processing:Post-pandemic passenger preference for touchless airport experiences accelerates facial recognition deployment over fingerprint-based alternatives.
Market Restraints
- Algorithmic Audit Costs:EU AI Act conformity assessments require third-party bias testing that adds recurring compliance expenditure for biometric vendors.
- Data Localization Mandates:China's Personal Information Protection Law and similar frameworks in Russia and India force infrastructure duplication that fragments vendor economics.
- Template Storage Limitations:GDPR's purpose limitation and storage minimization principles restrict retention periods for biometric templates, degrading matching accuracy over repeat passenger journeys.
Strategic Opportunities
- India Airport Modernization:The Airports Authority of India's Digi Yatra program creates greenfield demand for end-to-end biometric passenger processing at tier-2 and tier-3 airports.
- Health-Biometrics Convergence:Integration of temperature screening and health credential verification with identity systems opens new revenue streams at boarding gates.
- Saudi Vision 2030:Giga-project airport developments at NEOM and Red Sea Global mandate next-generation biometric infrastructure with performance specifications exceeding current ICAO standards.
Industry Challenges
- Legacy System Integration:Decades-old passenger service systems at established hubs resist API-based connectivity with modern biometric enrollment platforms.
- Specialized Engineering Talent:Scarcity of computer vision engineers with aviation security clearances constrains deployment velocity for complex one-to-many facial matching installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Biometrics Market |
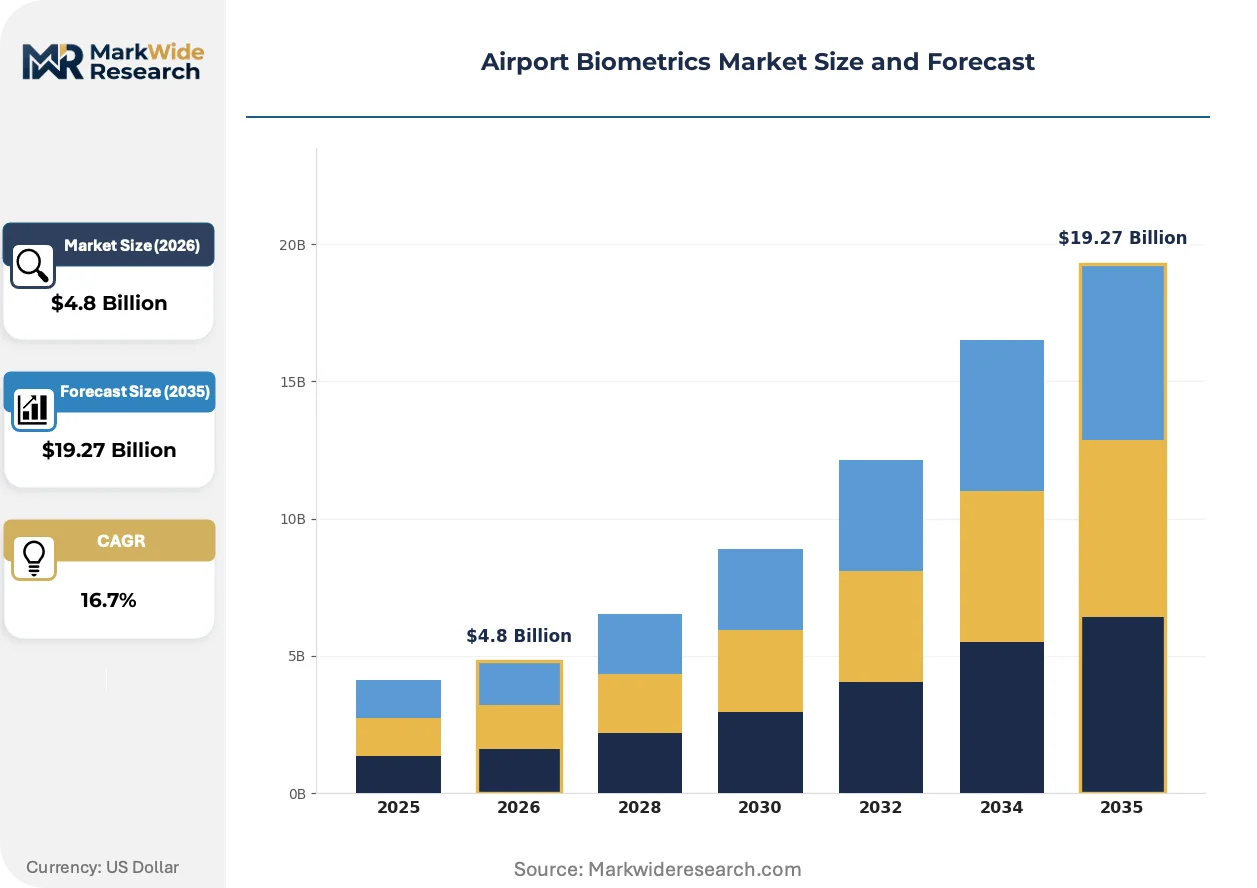
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Facial Recognition, Fingerprint Scanners, Iris Recognition, Voice Recognition Technology: Cloud-Based, On-Premises, Mobile Biometrics, Integrated Systems Application: Passport Control, Check-In Processes, Boarding, Security Screening End User: Airlines, Airports, Government Agencies, Security Firms |
| Companies Covered | NEC Corporation, IDEMIA, Safran, Thales Group, SITA, Fujitsu, Aware Inc., Cognitec Systems GmbH, Vision-Box, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Biometrics Market Emerging Trajectories
Biometric corridors are displacing discrete checkpoint installations as airports seek continuous identity assurance from curb to gate, compressing vendor business models toward integrated platform provision rather than point-solution sales.
Multimodal biometric fusion combining facial geometry with iris pattern recognition is automating passenger re-verification at transfer points without document presentation. Middle Eastern carriers at Dubai International and Hamad International are deploying these systems at scale. The technology is automating the elimination of boarding pass scanning at gate entry, collapsing processing time to under three seconds per passenger.
The EU AI Act's risk-based classification of biometric identification as high-risk AI imposes documented training data governance and human oversight requirements that reshape vendor development workflows. European airports must now maintain algorithmic impact assessments that US counterparts do not require. This bifurcation is fragmenting product roadmaps as vendors maintain separate European and North American code branches.
Airline procurement departments are consolidating biometric vendor relationships from fragmented point-solution contracts toward multi-airport framework agreements that bundle hardware, software, and biometric matching services under unified SLAs. Lufthansa Group and IAG have pioneered this approach across their hub networks. The shift is most visible in Europe where airline-operated common-use infrastructure exceeds airport-controlled deployments.
Airport Biometrics Market Segmentation
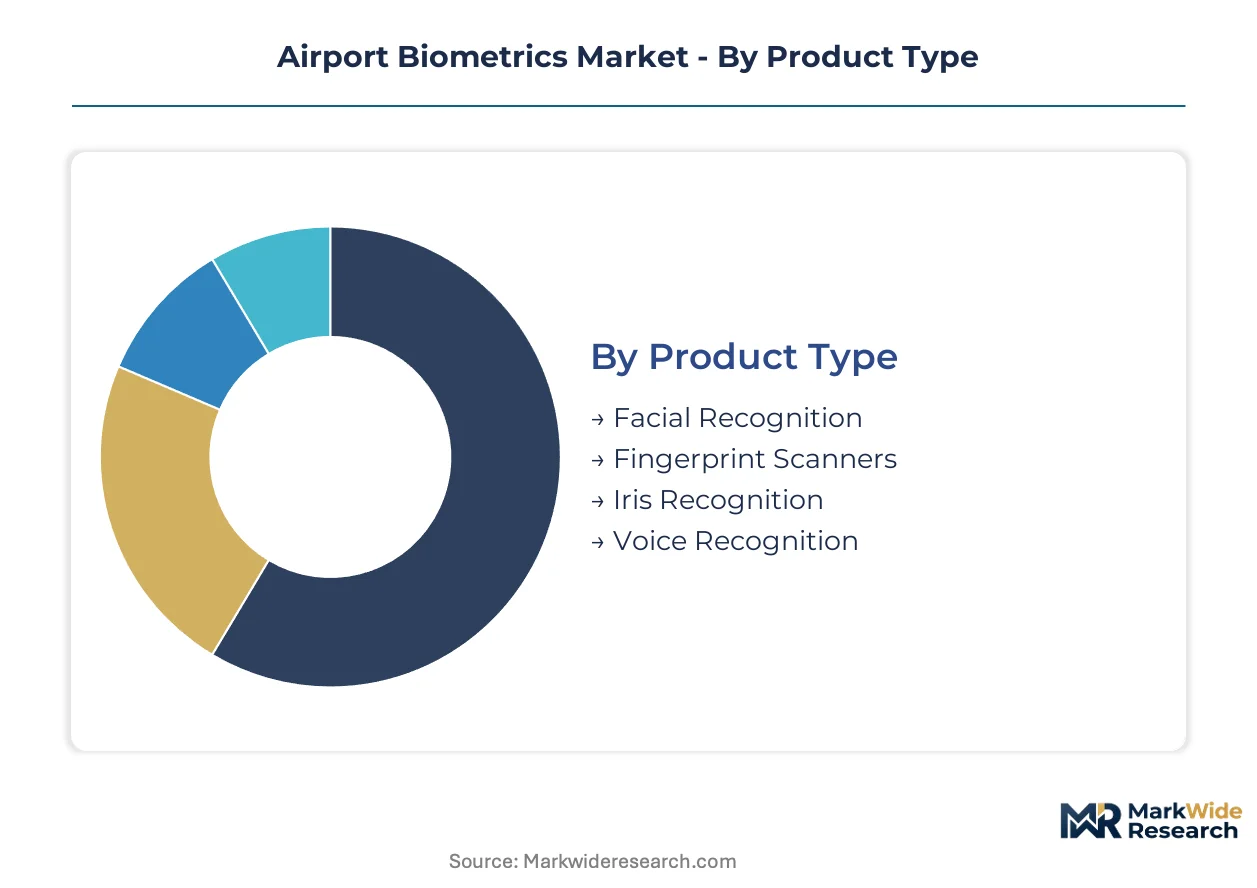
Segmentation in airport biometrics reveals how procurement decisions split between hardware durability requirements and software integration complexity. Buyers prioritize interoperability across legacy infrastructure while balancing compliance with divergent regulatory regimes.
Product Type:
Procurement teams select biometric modalities based on throughput demands and passenger contact preferences at specific airport touchpoints.
- Facial Recognition:Contactless capture of facial geometry using 2D or 3D imaging arrays enables high-throughput passenger processing without physical interaction. Demand concentrates at US hubs including Atlanta and Dallas-Fort Worth where TSA PreCheck expansion mandates touchless identity verification at congested security checkpoints.
- Fingerprint Scanners:Capacitive or optical sensors capture minutiae patterns from finger pads with established forensic reliability. Deployment concentrates at immigration counters in Asia-Pacific terminals where CBP-equivalent agencies require ten-print collection for visa-waiver program enrollment.
- Iris Recognition:Near-infrared imaging of unique stromal patterns delivers one-to-many matching accuracy exceeding facial alternatives in controlled lighting conditions.
- Voice Recognition:Spectral analysis of vocal characteristics supports telephone-based identity verification for airline customer service operations.
Facial recognition leads on scale; iris recognition leads on momentum in premium terminal deployments.
Technology:
Architecture choices hinge on data sovereignty requirements and elasticity needs during seasonal passenger volume spikes.
- Cloud-Based:Distributed processing infrastructure enables elastic capacity scaling during peak travel seasons without permanent hardware overprovisioning. European airports favor this architecture despite GDPR data localization constraints because EU AI Act algorithmic transparency mandates are easier to audit in centralized environments.
- Integrated Systems:Unified platforms combine enrollment, authentication, and template management functions under single vendor accountability. Saudi Arabia's NEOM and Red Sea Global giga-projects specify these systems to avoid multi-vendor integration failures during compressed construction schedules.
- On-Premises:Local server deployments retain biometric data within airport physical perimeters to satisfy national security classifications.
- Mobile Biometrics:Smartphone-based capture and matching shifts enrollment burden to passenger-owned devices.
Integrated systems dominate current procurement; cloud-based architectures are climbing the fastest as airports modernize legacy data centers.
Application:
Touchpoint-specific requirements drive divergent accuracy thresholds and processing speed specifications.
- Security Screening:One-to-many facial matching against watchlist databases demands sub-second response times at TSA and equivalent checkpoints. India's Digi Yatra program is deploying these capabilities at tier-2 and tier-3 airports to eliminate manual document inspection bottlenecks.
- Boarding:Gate-level biometric verification eliminates boarding pass scanning through automated facial comparison against departure control system manifests. Dubai International and Hamad International have achieved sub-three-second processing per passenger using multimodal fusion at these touchpoints.
- Passport Control:Immigration counter verification matches live captures against ICAO Doc 9303-compliant e-passport chips.
- Check-In Processes:Curb-to-terminal identity binding reduces repetitive document presentation.
Security screening commands the largest installed base; boarding applications show the steepest expansion trajectory as airlines consolidate biometric vendor relationships.
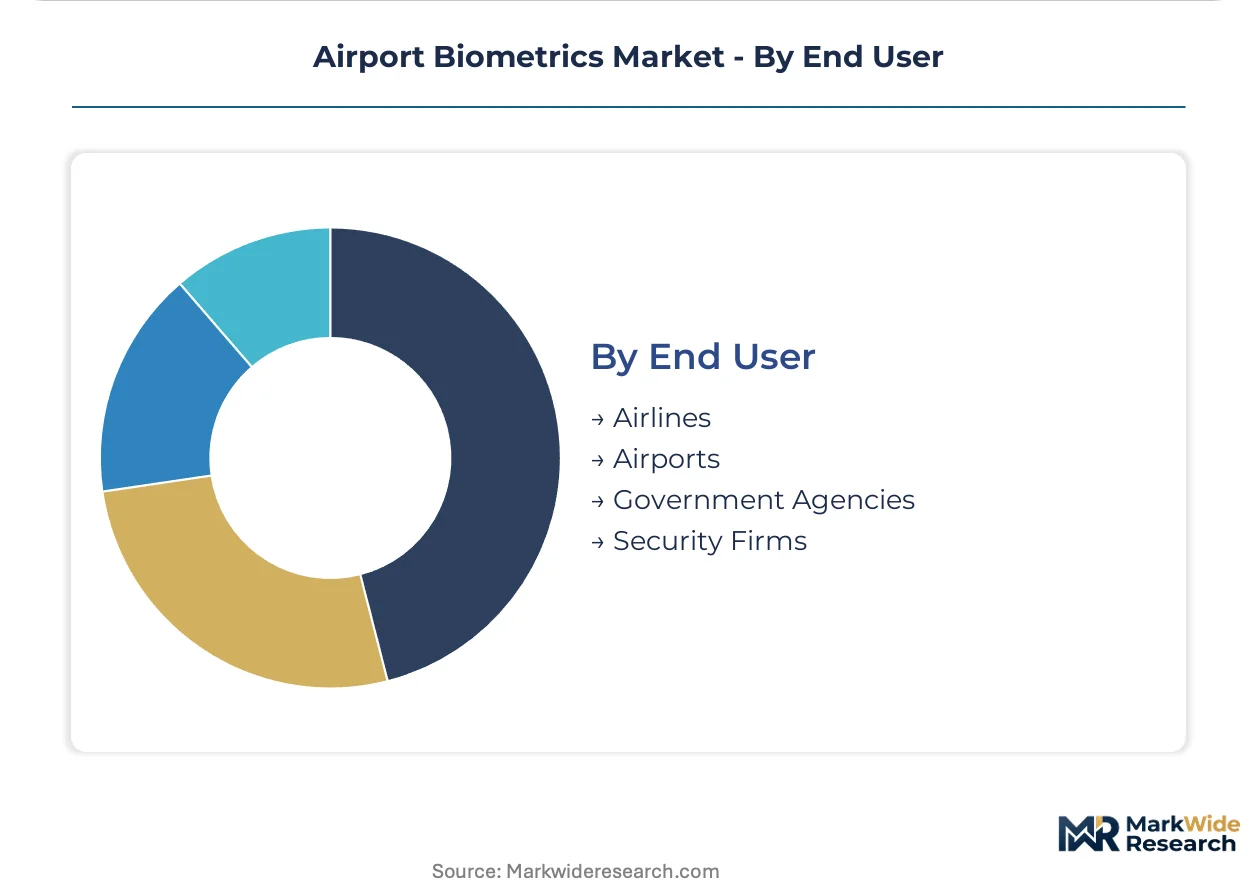
End User:
Contracting authority determines whether specifications prioritize federal compliance or operational efficiency metrics.
- Airports:Terminal operators procure common-use infrastructure serving multiple carriers under concession agreements. Lufthansa Group and IAG have pioneered framework agreements that shift procurement authority toward airline consortiums rather than airport authorities in European hubs.
- Government Agencies:Customs and immigration authorities mandate biometric entry-exit systems with specific accuracy thresholds and audit trails. US CBP specifications shape vendor product roadmaps more than any other single buyer segment due to procurement scale and technical stringency.
- Airlines:Individual carriers deploy proprietary biometric services to differentiate passenger experience at owned lounges and priority lanes.
- Security Firms:Private contractors operate outsourced checkpoint operations with biometric equipment supplied under service agreements.
Government agencies anchor procurement volume; airports are gaining share fastest as common-use infrastructure models expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting vendor investment toward jurisdictions where compliance costs diverge most sharply, with the United States offering streamlined federal certification pathways while European markets impose algorithmic audit burdens that inflate operational overhead.
United States
TSA PreCheck enrollment growth and CBP facial recognition mandates at Atlanta, Dallas-Fort Worth, and Los Angeles hubs drive procurement volume. The Transportation Security Administration and Customs and Border Protection enforce biometric entry-exit specifications that shape vendor product roadmaps more than any other single buyer segment. NEC Corporation leverages its algorithm leadership to dominate large-hub deployments across these major aviation clusters.
Germany
Lufthansa Group's framework agreements bundle hardware, software, and biometric matching services under unified SLAs across hub networks. The EU AI Act and GDPR impose algorithmic transparency and data retention limits that restrict vendor design choices and force parallel certification tracks. Frankfurt and Munich anchor European common-use infrastructure models that shift procurement authority toward airline consortiums.
China
The Personal Information Protection Law forces infrastructure duplication that fragments vendor economics for multinational suppliers. The country's national aviation regulator mandates biometric processing standards at tier-1 airports that exceed ICAO baseline specifications. Beijing Capital and Shanghai Pudong concentrate deployment of domestic facial recognition systems with performance thresholds calibrated to high-volume Spring Festival travel peaks.
Saudi Arabia
Giga-project airport developments at NEOM and Red Sea Global mandate next-generation biometric infrastructure with specifications exceeding current ICAO standards. The Saudi national data protection authority imposes localization requirements that favor integrated system providers capable of end-to-end deployment. King Abdulaziz International and the new Red Sea airport cluster anchor Middle Eastern demand for multimodal biometric fusion at transfer points.
India
The Airports Authority of India's Digi Yatra program creates greenfield demand for end-to-end biometric passenger processing at tier-2 and tier-3 airports. The country's national data protection framework restricts cross-border template transfer, mandating domestic server infrastructure. Bangalore, Hyderabad, and Delhi-NCR concentrate deployment of security screening systems that eliminate manual document inspection bottlenecks through one-to-many facial matching.
Airport Biometrics Market Vendor Landscape
Strategic partnerships dominate the current landscape as vendors seek to bundle enrollment, authentication, and template management functions under single accountability structures. The vendor base concentrates around three tiers: integrated platform providers capturing multi-year service contracts, specialized algorithm developers licensing matching engines, and hardware fabricators supplying durable capture devices. Two competitive moves define current positioning: technology licensing agreements that embed biometric engines within broader aviation IT stacks, and geographic expansion through local partnership structures that satisfy data sovereignty requirements.
Within the integrated platform tier, NEC Corporation, Thales Group, and IDEMIA exemplify divergent regional anchoring strategies. NEC Corporation represents algorithm-centric positioning with strength in one-to-many facial matching deployments. Thales Group occupies a position anchored to European regulatory compliance through ICAO-standard e-gate integrations. IDEMIA sits within the government-contracting archetype with procurement relationships shaped by federal biometric entry-exit mandates.
| Leading Market Players |
|---|
| NEC Corporation |
| IDEMIA |
| Safran |
| Thales Group |
| SITA |
| Fujitsu |
| Aware Inc. |
| Cognitec Systems GmbH |
| Vision-Box |
| Others |
Supply Flow & Price Mechanics
Captive algorithm development within integrated platform providers anchors both supply security and pricing power, as NEC Corporation and Thales Group maintain in-house facial-matching engines that insulate their service contracts from third-party licensing volatility. This backward integration into core biometric software allows these vendors to sustain multi-year framework agreements with airport operators and government agencies while compressing competitor margins on standalone hardware sales.
Pricing Analysis
Distributor margins on hardware-only sales have compressed to single-digit percentages as direct-to-government contracting displaces channel intermediaries. Three-tier pricing structure across premium algorithm licenses, standard integrated systems, and economy hardware bundles captures divergent buyer budgets, with EU AI Act compliance costs pushing premium tier pricing upward. Cost compression in the hardware tier is intensifying because Chinese domestic suppliers are flooding tier-2 airport procurement tenders with subsidized capture devices. Government agencies exhibit the lowest price sensitivity due to federal biometric mandates, while tier-3 airport operators in India and Southeast Asia drive aggressive discounting.
Supply Chain Analysis
China's Personal Information Protection Law and India's data localization mandates are reshaping sourcing patterns, forcing multinational vendors to duplicate server infrastructure across domestic facilities. Component supply draws from Taiwan for advanced imaging sensors, Germany for precision optics, and South Korea for semiconductor memory modules. Near-infrared camera arrays, edge-computing processors, and secure enclave chips constitute critical input dependencies. Single-source vulnerability concentrates in specialized facial-recognition ASICs where NVIDIA and Intel anchor global capacity. Distribution runs through aviation IT systems integrators who bundle biometric modules within broader passenger processing platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in airport biometrics rests on algorithm licensing revenue displacing hardware-centric business models, as cloud-based matching services command recurring SaaS multiples against depreciating capture device sales.
For Market Incumbents: Extend platform consolidation by acquiring specialized iris-recognition developers to close multimodal capability gaps against NEC Corporation's facial-matching dominance. Deepen vertical integration into edge-computing hardware to capture margin pools currently flowing to NVIDIA and Intel. EU AI Act compliance investments represent a defensive moat that smaller algorithm vendors cannot replicate. For New Entrants and Emerging Players: Digi Yatra program implementation in India opens a window for greenfield biometric deployments at tier-2 airports where incumbent relationships remain unformed. Target airline-operated common-use infrastructure in Europe, where Lufthansa Group and IAG framework agreements have shifted procurement authority away from established airport authorities. A channel partnership with aviation IT integrators accelerates access to gate-level boarding verification tenders without direct incumbent confrontation. For Investors and Strategic Acquirers: Roll-up economics work for regional biometric service providers because airline framework agreements favor vendors with multi-airport coverage that fragmented local players cannot achieve organically. Focus acquisition screening on computer vision engineering teams holding aviation security clearances, the scarcest input constraining deployment velocity. Watch CBP procurement specification releases as the inflection signal for federal contract flow acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Licensing Expansion | Recurring revenue from facial-matching APIs embedded within airline departure control systems displaces hardware dependency. |
| Multimodal Biometric Fusion | Combined iris and facial verification at Dubai International achieves sub-three-second processing that single-modality rivals cannot match. |
| Cloud Architecture Migration | Elastic capacity scaling during peak travel seasons reduces permanent infrastructure overprovisioning at European hubs. |
| EU AI Act Compliance Certification | Third-party bias testing documentation satisfies algorithmic transparency mandates that gate government contract eligibility. |
| Domestic Data Center Deployment | In-country server infrastructure satisfies China's Personal Information Protection Law and India's template localization requirements. |
Methodological Framework
Bottom-up airport procurement tracking reconciled against top-down vendor revenue segmentation forms the analytical core of this study. Primary interviews with airport IT directors, government biometric program managers, airline innovation executives, and aviation security consultants supplied deployment timelines and accuracy specification requirements. Secondary validation drew from TSA budget appropriations documents, CBP entry-exit program reports, EU AI Act implementation guidance, ICAO Doc 9303 technical specifications, and airport concession agreement filings. Cross-referencing procurement contract values against disclosed vendor bookings enabled triangulation of market sizing estimates.
Historical deployment trajectory analysis across major hub airports established baseline penetration rates for facial recognition, fingerprint, and iris modalities. Segmentation modeling incorporated product type, technology architecture, application touchpoint, and end-user contracting authority dimensions across the projection horizon. CAGRs derived from fitting logistic adoption curves to observed deployment phases, with inputs from passenger volume forecasts and regulatory mandate implementation schedules. Biometric matching accuracy thresholds, template storage cost curves, and cloud infrastructure pricing informed unit economics assumptions.
Revisions become necessary when regulatory implementation delays, data sovereignty rule changes, or algorithmic bias litigation outcomes materially alter vendor certification burdens or airport procurement priorities. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Global Mobile User Authentication Market
Biometrics & Identity Management
Identity Verification Market
Biometrics & Identity Management
ID Verification Market
Biometrics & Identity Management
Healthcare Biometrics Market
Biometrics & Identity Management
Global Voice Biometrics Market
Biometrics & Identity Management
Europe Government and Security Biometrics Market
Biometrics & Identity Management
China Mobile Biometrics Market
Biometrics & Identity Management
Global Biometric-As-A-Service Market
Biometrics & Identity Management
Passive Authentication Market
Biometrics & Identity Management
AI-Enabled Biometrics Market
Biometrics & Identity Management
Middle East and Africa Biometrics in Government Market
Biometrics & Identity Management
Iris Recognition Market
Biometrics & Identity Management
Multi-Factor Authentication (MFA) Market
Biometrics & Identity Management
Fingerprint Biometrics Market
Biometrics & Identity Management
Europe Biometrics Market
Biometrics & Identity Management
Palm Vein Biometrics Market