
 Biometric Passport Market | 2026-2036
Biometric Passport Market Size, Share, and Industry Trends Forecast 2026-2036
Biometric Passport Market Outlook
Multi-source procurement for secure document components is rebalancing toward qualified domestic vendors in several issuing nations. Thales Group leverages its semiconductor foundry partnerships to sustain chip supply continuity for embedded passport modules. IDEMIA anchors large-scale personalization center deployments across multiple continents. Infineon Technologies AG specializes in contactless security controller architectures that dominate ICAO-compliant e-document specifications.
A biometric passport is an electronic travel document incorporating a contactless integrated circuit chip that stores biometric identifiers—typically facial recognition templates, fingerprint minutiae, or iris patterns—alongside machine-readable zone data conforming to ICAO Doc 9303 standards. The document's primary purpose is to authenticate traveler identity through automated border control gates and manual inspection systems while resisting forgery through cryptographic key infrastructure. E-passport volumes lead product type demand as nations phase out traditional booklets to meet international interoperability mandates. Biometric recognition technology captures the fastest growth trajectory within the technology dimension, driven by multimodal template enrollment requirements at issuance offices. Government agencies represent the dominant end-user category, though airlines are expanding ground-handling investments to integrate departure control systems with chip-based identity verification.
ICAO's Doc 9303 standards, the EU's GDPR biometric data handling provisions, and the US Department of State's FIPS 140-3 cryptographic module requirements collectively shape product certification pathways and procurement eligibility for document suppliers. Regulatory fragmentation across data localization rules in China, India's BIS marking mandates, and Brazil's ANVISA-equivalent identity governance frameworks complicates multinational deployment strategies for integrated passport ecosystems. Stakeholders must monitor evolving national data sovereignty legislation that increasingly restricts cross-border biometric template storage and algorithm training.
Market Dynamics
ICAO's Doc 9303 compliance mandates are compressing supplier qualification timelines while fragmenting procurement across qualified domestic vendors in major issuing nations.
Growth Catalysts
- ETIAS Authorization Framework:The European Union's pre-travel clearance system mandates biometric enrollment, forcing Schengen-border nations to upgrade document infrastructure.
- Contactless Security Controllers:ICAO-compliant chip architectures enable automated border gate interoperability, accelerating replacement cycles for legacy machine-readable zones.
- India:The Ministry of External Affairs has scaled domestic manufacturing partnerships, creating template demand for multimodal biometric enrollment systems.
Market Restraints
- Semiconductor Supply Concentration:Embedded passport module production depends on foundry capacity concentrated in East Asian manufacturing clusters.
- Data Localization Requirements:China's cross-border biometric template storage restrictions and India's BIS marking mandates fragment multinational deployment strategies.
- Cryptographic Certification Delays:US FIPS 140-3 module validation timelines extend product qualification cycles by 18-24 months.
Strategic Opportunities
- Airline Ground-Handling Integration:Departure control system vendors seek chip-based identity verification partnerships for passenger processing automation.
- Southeast Asia Procurement Wave:Government agencies across Vietnam, Indonesia, and Thailand are accelerating e-passport system tenders.
- Biometric-Blockchain Convergence:Self-sovereign identity pilots in the UAE and Singapore test decentralized credential verification for travel document ecosystems.
Industry Challenges
- Multimodal Template Engineering Talent:Shortage of specialists in facial recognition, fingerprint minutiae, and iris pattern integration slows personalization center deployments.
- Legacy System Interoperability:Migration from optical character recognition to contactless chip reading requires coordinated border infrastructure upgrades.
- Algorithm Training Data Sovereignty:National restrictions on cross-border biometric dataset sharing complicate machine learning model refinement for document verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biometric Passport Market |
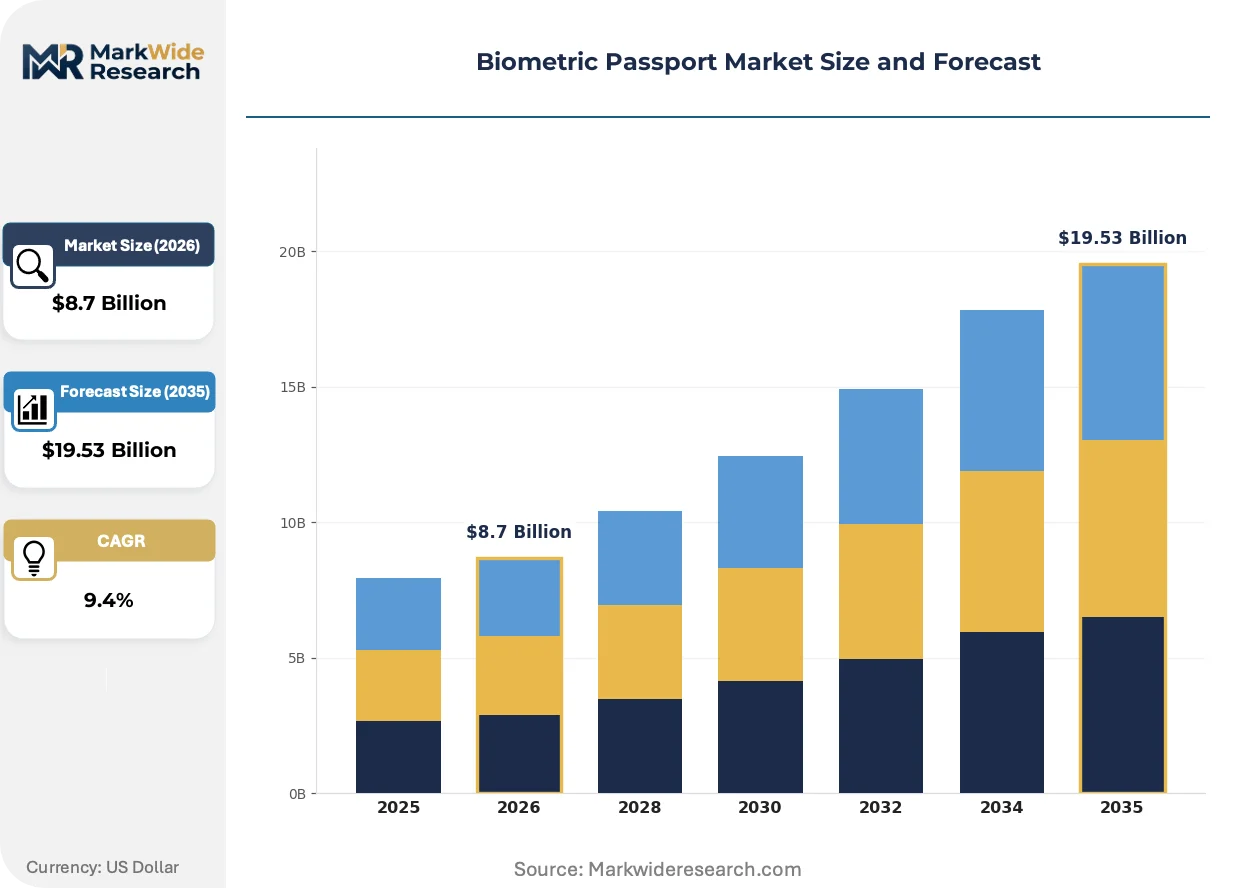
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Passports, E-passports, Smart Passports, Visa Passports End User: Government Agencies, Airlines, Border Control, Immigration Authorities Technology: RFID, Optical Character Recognition, Biometric Recognition, Encryption Distribution Channel: Online, Offline, Direct, Third-Party Vendors |
| Companies Covered | Thales Group, IDEMIA, HID Global Corporation, Muhlbauer Group, Entrust Corporation, Eastcompeace Technology Co., Ltd., Infineon Technologies AG, 4G Identity Solutions, Safran, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biometric Passport Market Strategic Shifts
Document security architectures are converging around tamper-evident substrates and quantum-resistant cryptography, reshaping supplier R&D priorities and procurement specifications.
Polycarbonate data pages with laser-engraved personalization are overtaking laminated paper composites in next-generation passport booklets. Government printing authorities in Germany, Japan, and Australia have adopted these substrates for 10-year validity documents. The shift is overtaking traditional security printing margins as polycarbonate requires specialized laser engraving equipment and captive substrate supply chains.
The EU AI Act's biometric identification system classification rules are redefining algorithm vendor liability for automated border gates. Systems deployed at Schengen external borders must now demonstrate conformity with fundamental rights impact assessments. High-risk classification is forcing document personalization centers to segregate template enrollment workflows from verification algorithm training environments.
Airlines are unbundling identity verification from traditional ground-handling contracts, creating direct procurement relationships with biometric middleware providers. Lufthansa, Singapore Airlines, and Emirates have established separate RFP processes for departure control system integration. This pattern is most visible at hub airports where passenger processing throughput directly determines gate allocation economics.
Biometric Passport Market Segmentation
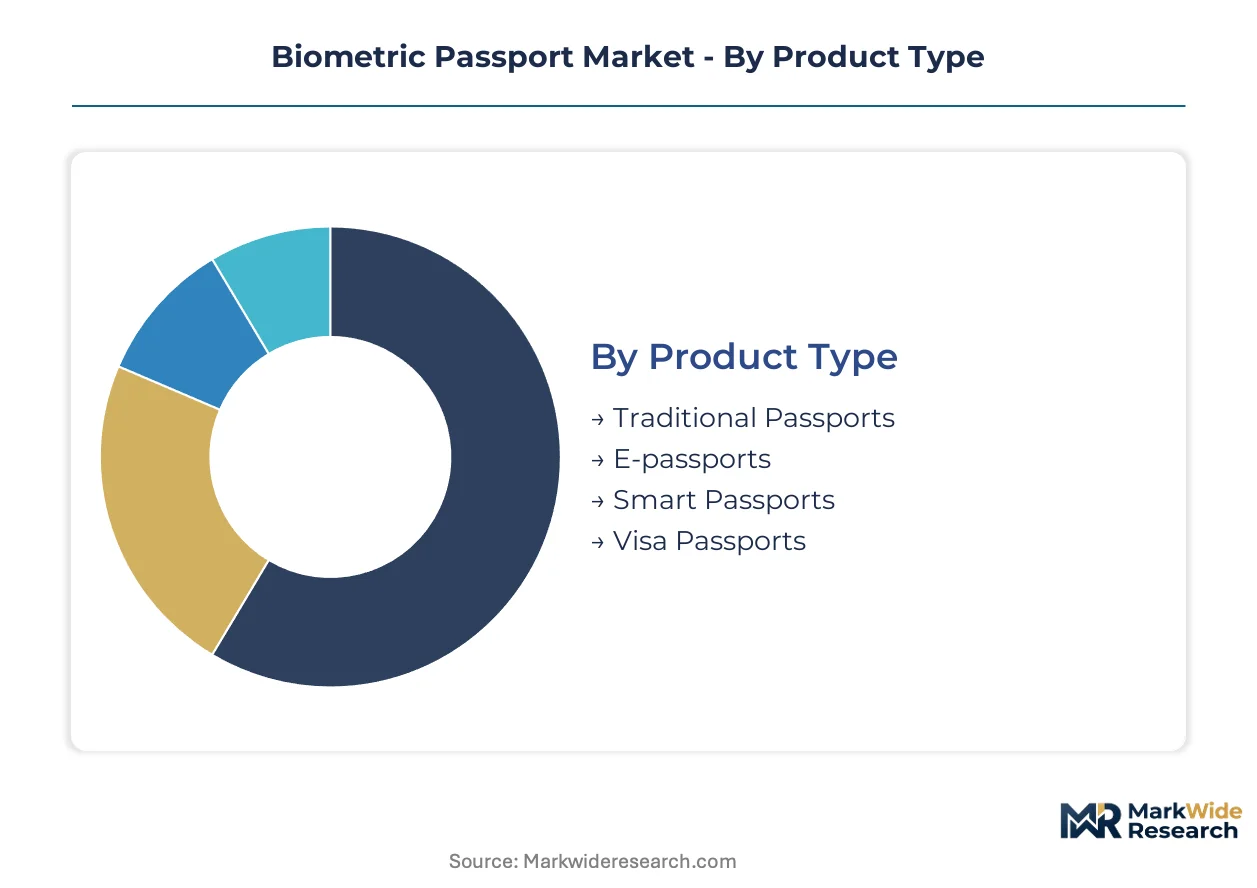
Biometric passport procurement patterns diverge sharply between high-volume national rollouts and premium-tier diplomatic document programs. Issuing authorities segment supplier selection by chip architecture maturity, personalization throughput requirements, and data sovereignty compliance thresholds.
Product Type:
E-passport volumes dominate procurement tenders, while smart passport specifications command premium unit economics in limited diplomatic deployments.
- E-passports:Contactless integrated circuit chips store facial recognition templates and fingerprint minutiae per ICAO Doc 9303 standards. India's Ministry of External Affairs has scaled domestic manufacturing partnerships for next-generation e-passport booklets, compressing supplier qualification timelines for embedded module vendors.
- Smart Passports:Advanced security controllers enable offline biometric verification through tamper-resistant cryptographic coprocessors. Germany's Federal Printing Office and Japan's National Printing Bureau specify these substrates for 10-year validity diplomatic credentials.
- Traditional Passports:Machine-readable zone documents without embedded electronics persist in nations with limited border infrastructure investment.
- Visa Passports:Specialized booklets integrate visa issuance workflows with biometric enrollment at consular facilities.
Mature deployment sits with e-passports. Newer deployment is concentrated in smart passport diplomatic programs.
End User:
Government agencies anchor procurement volume, though airlines are unbundling identity verification from traditional ground-handling contracts.
- Government Agencies:National printing authorities and interior ministries manage personalization center infrastructure, chip procurement, and document lifecycle systems. Vietnam, Indonesia, and Thailand have accelerated e-passport system tenders.
- Airlines:Lufthansa, Singapore Airlines, and Emirates have established separate RFP processes for departure control system integration with chip-based identity verification.
- Border Control:Automated gate deployments at Schengen external borders must demonstrate conformity with EU AI Act fundamental rights impact assessments.
- Immigration Authorities:Consular biometric enrollment workflows require segregation from verification algorithm training environments under GDPR provisions.
Established procurement relationships sit with government agencies. Expanding deployment is concentrated in airline ground-handling integration.
Technology:
Biometric recognition specifications are displacing legacy optical systems, while encryption mandates tighten under FIPS 140-3 certification timelines.
- Biometric Recognition:Multimodal template enrollment combines facial recognition, fingerprint minutiae, and iris pattern capture at issuance offices. The EU AI Act's high-risk classification forces segregation of enrollment workflows from algorithm training environments.
- RFID:Contactless security controller architectures from Infineon Technologies AG dominate ICAO-compliant e-document specifications.
- Encryption:Quantum-resistant cryptography R&D priorities are reshaping supplier certification pathways.
- Optical Character Recognition:Legacy machine-readable zone reading persists at ports lacking chip-enabled infrastructure.
Legacy infrastructure sits with optical character recognition. Steepest expansion trajectory is concentrated in biometric recognition multimodal systems.
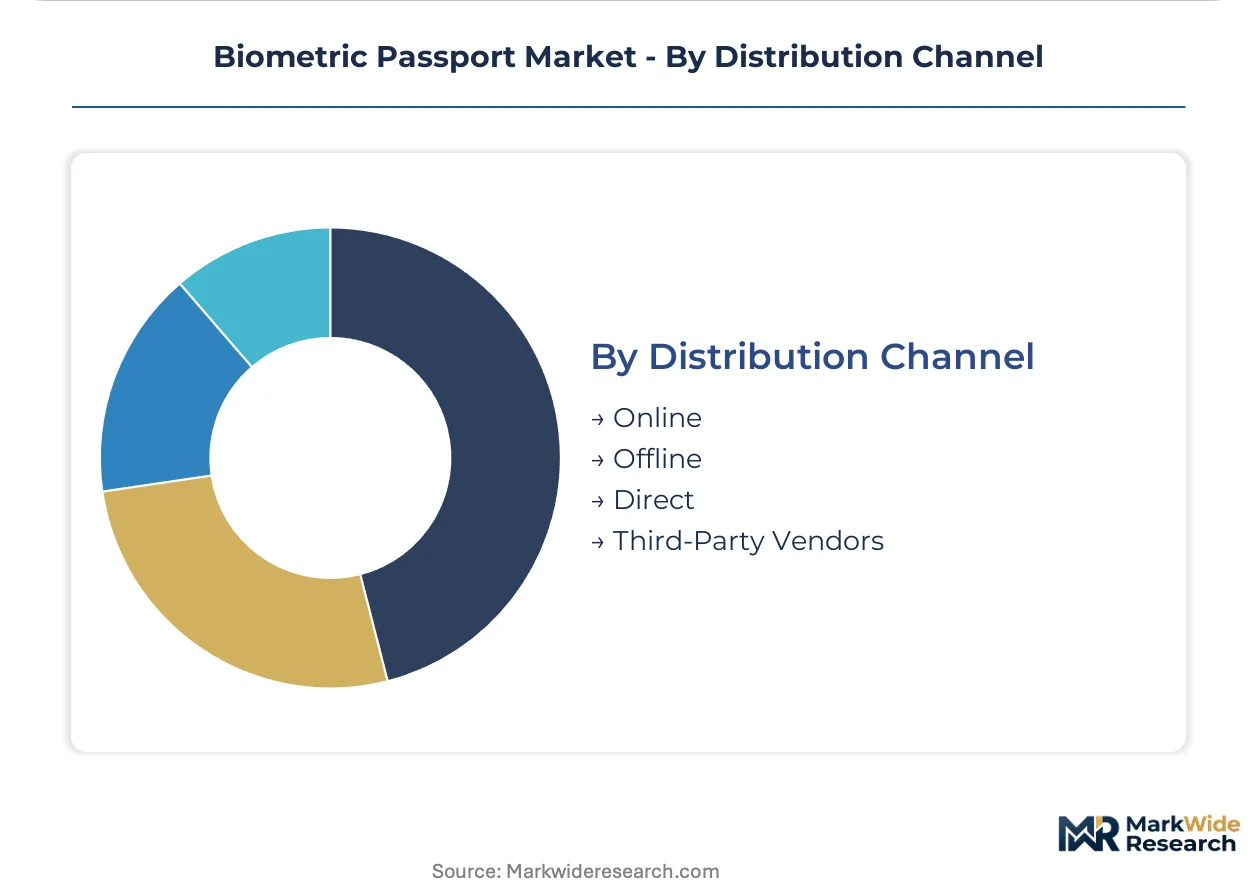
Distribution Channel:
Direct procurement relationships are consolidating around qualified domestic vendors, while third-party vendor networks fragment across data localization jurisdictions.
- Direct:National printing authorities contract directly with semiconductor foundries and personalization equipment manufacturers. Thales Group leverages foundry partnerships to sustain chip supply continuity.
- Third-Party Vendors:Regional system integrators navigate China's cross-border biometric template storage restrictions and India's BIS marking mandates.
- Offline:Physical tender processes dominate government procurement for secure document components.
- Online:Digital procurement platforms facilitate component sourcing for non-security-critical passport booklet materials.
Traditional tender processes sit with offline channels. Emerging deployment is concentrated in direct national authority relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polycarbonate substrate supply chains anchor biometric passport manufacturing in Germany, France, and Japan, with semiconductor foundry partnerships concentrated in East Asian manufacturing clusters.
India
The Ministry of External Affairs has scaled domestic manufacturing partnerships for next-generation e-passport booklets, compressing supplier qualification timelines for embedded module vendors. India's BIS marking mandates restrict multinational deployment strategies for integrated passport ecosystems. Personalization center deployments concentrate in Delhi-NCR and Hyderabad, where multimodal biometric enrollment systems process high-volume citizen applications.
Germany
The Federal Printing Office specifies polycarbonate substrates with laser-engraved personalization for 10-year validity diplomatic credentials. GDPR biometric data handling provisions force segregation of template enrollment workflows from verification algorithm training environments. Security printing clusters in Berlin and Munich host specialized laser engraving equipment and captive substrate supply chains for premium-tier document programs.
United States
The Department of State's FIPS 140-3 cryptographic module requirements extend product qualification cycles by 18-24 months for embedded passport suppliers. US border infrastructure investments drive automated gate deployments at major international airports. Semiconductor packaging capabilities in Arizona and Texas sustain chip supply continuity for contactless security controller architectures.
China
Cross-border biometric template storage restrictions fragment multinational deployment strategies for integrated passport ecosystems. Eastcompeace Technology Co., Ltd. anchors domestic manufacturing of secure document components. Personalization equipment manufacturing clusters in Shenzhen and Shanghai serve regional government procurement tenders across Southeast Asia.
United Arab Emirates
Self-sovereign identity pilots in Dubai and Abu Dhabi test decentralized credential verification for travel document ecosystems. MOHAP governance frameworks shape biometric data handling requirements for federal identity programs. Smart city infrastructure investments integrate chip-based identity verification with automated border control gates at Dubai International Airport.
Biometric Passport Market Competitive Environment
Global majors compete with regional champions across semiconductor supply chains and personalization center deployments. The vendor base clusters around three tiers: integrated security technology conglomerates, specialized document personalization equipment fabricators, and semiconductor foundry partners. Strategic differentiation hinges on foundry partnerships for chip supply continuity and domestic manufacturing alliances for data sovereignty compliance. Competitive moves concentrate on capacity expansion in qualified domestic vendor networks and technology licensing for quantum-resistant cryptographic architectures.
Within the integrated security technology tier, Thales Group and IDEMIA exemplify archetypes that leverage semiconductor foundry partnerships and large-scale personalization center deployments across multiple continents. Infineon Technologies AG occupies a specialized position in contactless security controller architectures that dominate ICAO-compliant e-document specifications. These three entities anchor the competitive structure through distinct capability configurations rather than overlapping market positions.
| Leading Market Players |
|---|
| Thales Group |
| IDEMIA |
| HID Global Corporation |
| Muhlbauer Group |
| Entrust Corporation |
| Eastcompeace Technology Co., Ltd. |
| Infineon Technologies AG |
| 4G Identity Solutions |
| Safran |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between FIPS 140-3 validated modules and standard ICAO-compliant chips manifests in both unit pricing spreads and foundry allocation priorities, with cryptographic certification timelines compressing margins for suppliers serving US Department of State tenders while accelerating procurement cycles for nations accepting baseline security controller specifications.
Pricing Analysis
Service bundling separates turnkey personalization center deployments from component-only supply contracts, with Thales Group and IDEMIA commanding premium positioning through integrated enrollment-to-issuance workflows. Price differentiation rests on cryptographic certification tier and domestic manufacturing qualification status, with India's BIS marking mandates adding compliance premiums for foreign suppliers. Cost compression in standard e-passport modules is intensifying because semiconductor foundry capacity concentrates among East Asian manufacturing clusters. Government printing authorities exhibit lowest price sensitivity for diplomatic credential programs, while Southeast Asian procurement tenders drive aggressive volume-based negotiations.
Supply Chain Analysis
Domestic-content mandates from India's Ministry of External Affairs and China's cross-border data localization rules are reshaping sourcing patterns toward qualified local vendors and captive semiconductor packaging facilities. Supply concentration centers on Taiwan, South Korea, and Germany for contactless security controller fabrication, with polycarbonate substrate production anchored in France and Japan. Raw material dependencies include silicon wafers, laser-engraving equipment, and tamper-evident substrate formulations. Single-source vulnerability in advanced node foundry capacity presents structural risk. Distribution runs through direct national authority contracts rather than third-party vendor networks for security-critical components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race, with foundry partnerships and domestic manufacturing alliances serving as the decisive upstream levers for securing procurement eligibility in data-sovereignty-conscious jurisdictions.
For Market Incumbents: Anticipate margin compression from India's scaled domestic manufacturing partnerships by securing captive polycarbonate substrate supply chains and laser-engraving equipment fabrication capabilities. Prioritize FIPS 140-3 pre-certification investments to compress qualification timelines for US Department of State tenders before cryptographic module validation backlogs extend further. For New Entrants and Emerging Players: Launch via regional system integrator partnerships in Vietnam, Indonesia, and Thailand to bypass direct qualification barriers with national printing authorities. Target airline ground-handling integration as the most penetrable segment, where departure control system vendors seek chip-based identity verification partnerships outside traditional government procurement channels. For Investors and Strategic Acquirers: Exit pathways concentrate in semiconductor foundry partnerships and personalization equipment fabricators with established domestic manufacturing alliances. Long-term viability hinges on quantum-resistant cryptography R&D positioning and qualified vendor status in India's BIS marking framework. Watch for EU AI Act fundamental rights impact assessment enforcement as an inflection indicator for algorithm vendor liability restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Alliance | India's BIS marking mandates require local production partnerships for procurement eligibility. |
| Quantum-Resistant Cryptography R&D | FIPS 140-3 evolution and EU security standards are reshaping certification pathways. |
| Personalization Center Expansion | Multimodal biometric enrollment throughput determines contract win rates in high-volume tenders. |
| Airline Ground-Handling Partnership | Lufthansa and Emirates are unbundling identity verification from traditional handling contracts. |
| Foundry Partnership Securement | East Asian semiconductor capacity constraints elevate supply continuity to strategic priority. |
Study Parameters
Document review covered ICAO Doc 9303 technical specifications, EU ETIAS implementation frameworks, and national procurement tender databases, complemented by interviews with semiconductor supply chain directors, government printing authority procurement leads, personalization center operations managers, and airline IT integration specialists. Secondary validation drew from FIPS 140-3 certification records, BIS marking registries, and customs trade data for secure document component flows. Bottom-up unit economics modeling and top-down market sizing triangulated volume and value estimates.
Cross-referencing historical issuance volumes against expert panel input on replacement cycle acceleration shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end-user procurement authority, biometric recognition technology maturity, and data sovereignty compliance threshold. CAGRs were derived from trend extrapolation moderated by regulatory implementation timelines and foundry capacity expansion announcements. Forecast inputs incorporated ICAO compliance mandate adoption curves and domestic manufacturing partnership formation rates.
Semiconductor supply disruptions, cryptographic certification backlog extensions, and data localization rule expansions are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented procurement timelines and regulatory implementation schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Global Behavioral Biometrics Market
Biometrics & Identity Management
North America Government and Security Biometrics Market
Biometrics & Identity Management
United States Biometrics Market
Biometrics & Identity Management
ID Verification Market
Biometrics & Identity Management
Global Phone Based Authentication Solution Market
Biometrics & Identity Management
Global Biometric Identification Market
Biometrics & Identity Management
Global Biometrics Middleware Market
Biometrics & Identity Management
Spain Mobile Biometrics Market
Biometrics & Identity Management
Out-Of-Band Authentication Market
Biometrics & Identity Management
Face Voice Biometric Market
Biometrics & Identity Management
Europe Government and Security Biometrics Market
Biometrics & Identity Management
Biometric ATM Market
Biometrics & Identity Management
Global Mobile User Authentication Market
Biometrics & Identity Management
Mobile Biometric Security and Services Market
Biometrics & Identity Management
United States Facial Recognition Market
Biometrics & Identity Management
Signature Verification Market