
 GCC Biometrics Market | 2026-2036
GCC Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Biometrics Market Intelligence
Silicon-based fingerprint sensors is restructuring cost curves across access control hardware, enabling OEMs to deliver multi-modal units at price points previously reserved for single-factor devices. Suprema Inc. dominates the GCC channel with vertically integrated manufacturing of fingerprint modules and access terminals. NEC Corporation anchors large-scale government identity programs through iris and facial recognition system integration. IDEMIA France SAS leverages its civil biometric database expertise to compete for national ID contracts across Gulf states.
Biometrics encompasses automated methods of recognizing individuals based on measurable physiological or behavioral characteristics, including fingerprint minutiae patterns, iris stromal texture, facial geometry vectors, and voice spectrograms processed through machine learning classifiers with false acceptance rates below 0.001%. These systems authenticate identity for physical access, digital transactions, and border crossing verification without reliance on tokens or memorized credentials. Fingerprint recognition retains the largest installed base across GCC banking and retail deployments due to mature sensor economics and consumer familiarity. Facial recognition exhibits the fastest expansion in government and aviation applications, driven by contactless hygiene preferences and integration with existing camera infrastructure. Cloud-based deployment models are capturing margin pools in mid-market healthcare and retail segments by shifting capital expenditure to subscription frameworks.
Saudi Arabia's National Cybersecurity Authority and the UAE's Telecommunications and Digital Government Regulatory Authority enforce data localization and encryption standards that shape product certification requirements for biometric vendors. SAMR-aligned GB standards and GCC-wide interoperability frameworks for national ID systems further condition market access and technical specifications. Stakeholders must monitor evolving liveness detection mandates and cross-border data governance protocols as Gulf states deepen biometric integration across smart city and financial infrastructure layers.
Market Dynamics
Gulf cybersecurity mandates from Saudi Arabia's National Cybersecurity Authority and the UAE's Telecommunications and Digital Government Regulatory Authority are compressing vendor certification timelines while embedding liveness detection and hardware-level encryption as baseline requirements for market access.
Growth Catalysts
- Smart city infrastructure mandates:Saudi Arabia's giga-project developments are mandating biometric access control as standard civic infrastructure, creating embedded demand for multi-modal authentication systems across residential, commercial, and transport nodes.
- Aviation hub expansion:The UAE's airport capacity investments are requiring contactless passenger processing, accelerating deployment of facial recognition corridors and iris scanning gates at Dubai and Abu Dhabi international terminals.
- GB standards alignment:SAMR-aligned technical specifications for national ID interoperability are creating procurement frameworks that favor vendors with integrated civil biometric database capabilities.
Market Restraints
- Silicon sensor supply concentration:Fingerprint module production relies on concentrated East Asian semiconductor foundry capacity, exposing GCC hardware OEMs to input volatility and extended lead times during supply shocks.
- Data localization compliance costs:Mandatory on-shore storage of biometric templates under NCA and TDRA rules forces cloud-native vendors to establish regional data centers, elevating operational overhead.
- Template interoperability limitations:Proprietary matching algorithms from incumbent vendors create technical lock-in that complicates multi-supplier deployments for large-scale government identity programs.
Strategic Opportunities
- Qatar's healthcare digitization:The country's hospital network modernization is creating first-mover demand for patient identification systems using palm-vein and facial recognition to eliminate duplicate medical records.
- Multi-modal convergence:Integration of behavioral biometrics—keystroke dynamics and gait analysis—with physiological sensors is opening new authentication tiers for high-security financial transactions.
- Kuwait's financial inclusion drive:Central bank directives for unbanked population onboarding are creating regulatory tailwinds for mobile biometric enrollment systems using national ID card readers.
Industry Challenges
- Specialized systems integration talent:Shortage of engineers certified in liveness detection algorithm tuning and anti-spoofing protocol implementation is extending deployment timelines for government identity projects.
- Legacy access control retrofit complexity:Existing magnetic stripe and proximity card infrastructure in Gulf commercial real estate requires parallel authentication architectures during transition periods, doubling capex for facility managers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Biometrics Market |
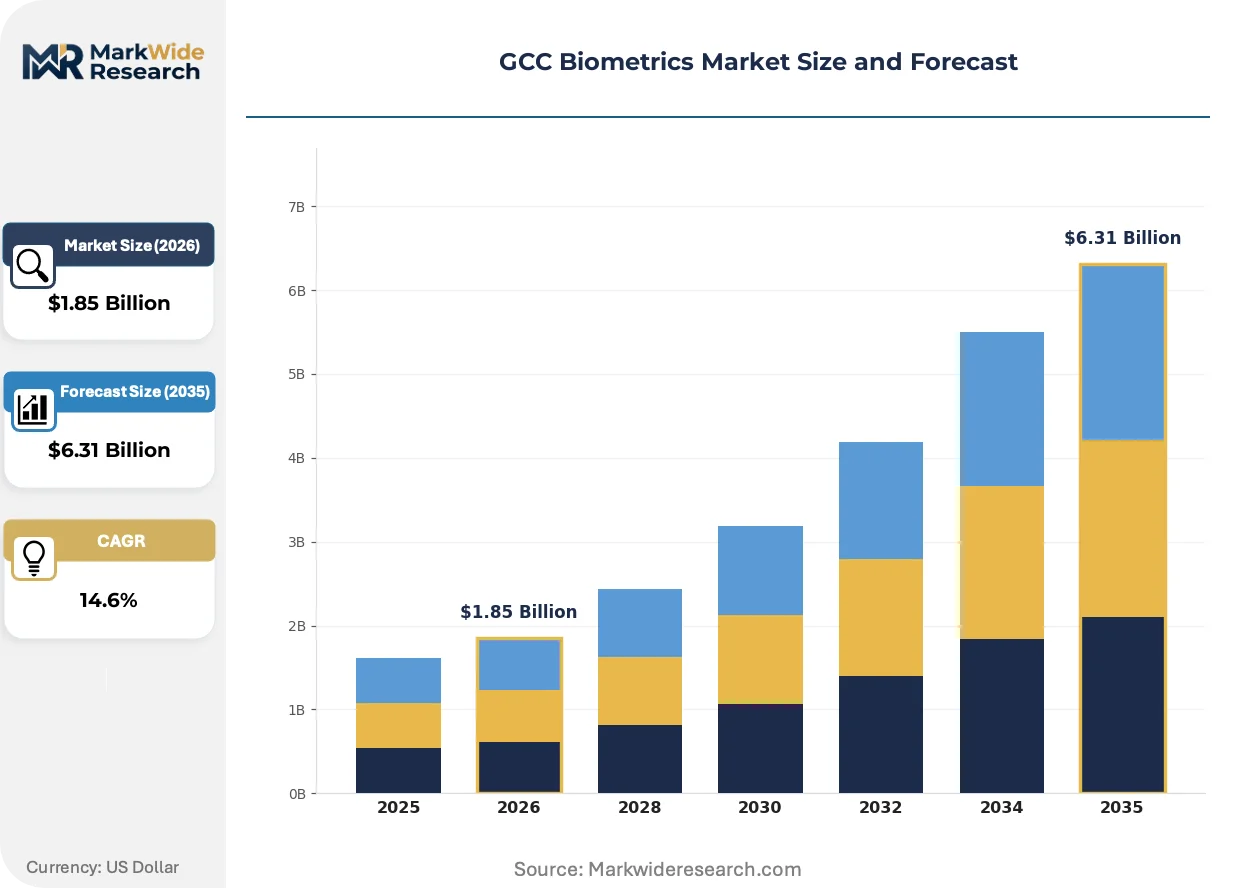
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.31 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fingerprint Recognition, Facial Recognition, Iris Recognition, Voice Recognition Deployment Model: On-Premises, Cloud-Based, Hybrid, Embedded Systems End User: Government, Healthcare, Banking, Retail Application: Access Control, Time & Attendance, Border Security, Identity Verification |
| Companies Covered | Suprema Inc., IBM Corporation, NEC Corporation, BioCatch Ltd., Fujitsu Limited, IDEMIA France SAS, Samsung Electronics Co., Ltd., Nuance Communications, Inc., Thales S.A., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Biometrics Market Strategic Shifts & Innovations
Edge-based biometric processing is displacing cloud-dependent architectures across GCC deployments, driven by data sovereignty requirements and latency constraints in high-throughput aviation and border control environments.
Contactless fingerprint sensors using ultrasonic and optical waveguide technologies are integrating liveness detection directly into hardware modules. Saudi banking networks are adopting these units at branch counters to eliminate hygiene concerns while maintaining authentication accuracy. This integration is compressing the market for standalone presentation attack detection peripherals.
The UAE's TDRA biometric data protection regulations are mandating template encryption standards that exceed legacy ISO/IEC 19794 compliance baselines. Vendors must now submit hardware for penetration testing and algorithmic bias auditing before procurement eligibility. Healthcare providers in Dubai are responding by prioritizing certified devices in radiology and pharmacy access control tenders.
Subscription-based authentication services are displacing perpetual license models among mid-market retailers and clinic chains. Managed biometric access with per-door monthly fees is replacing upfront hardware purchases in Oman and Bahrain commercial deployments. This shift is most visible in franchise retail networks seeking predictable opex structures across multiple locations.
GCC Biometrics Market Segmentation
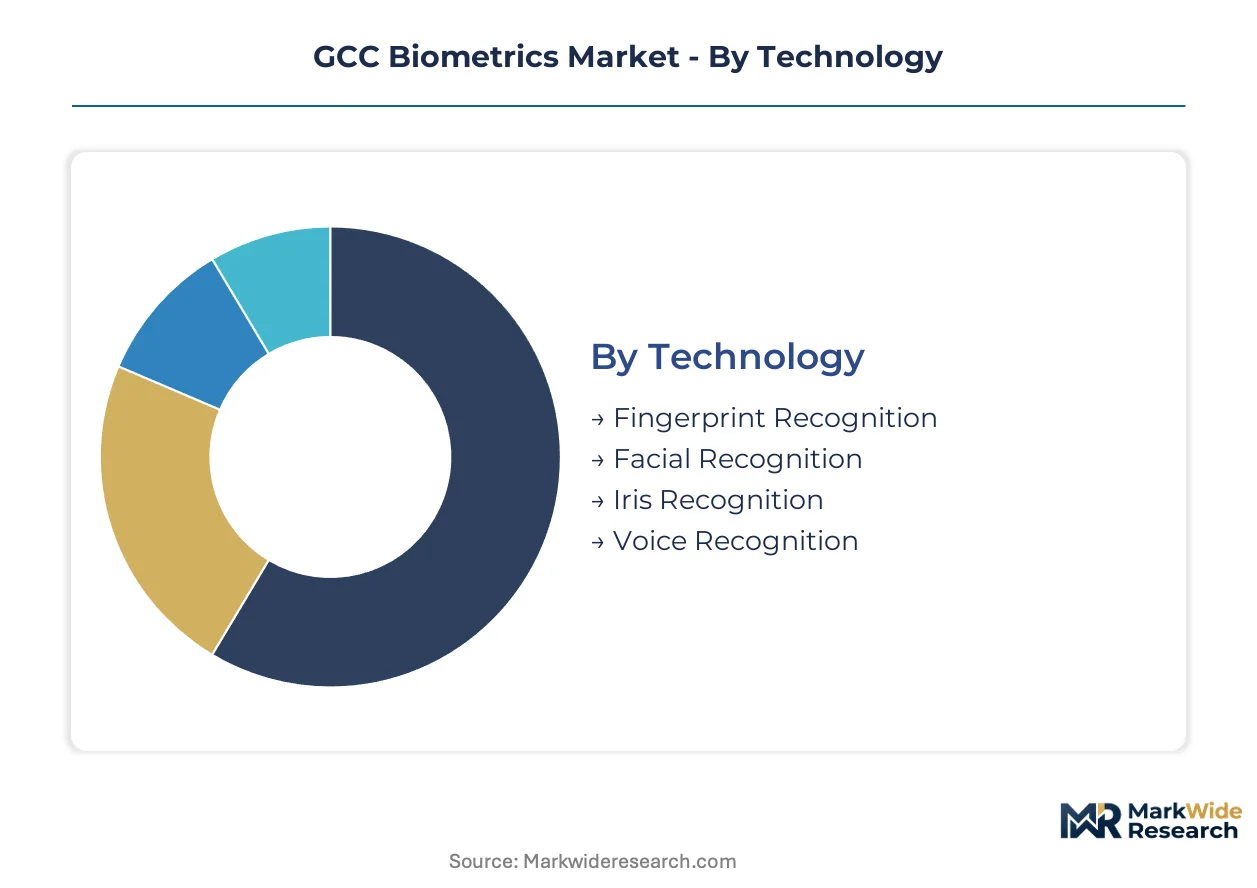
Segmentation reveals how capital deployment, regulatory compliance, and infrastructure maturity diverge across authentication modalities in Gulf markets. Procurement patterns in Saudi Arabia and the UAE favor integrated multi-modal systems over single-factor alternatives, reshaping vendor positioning.
Technology:
Capital intensity varies sharply by sensor type, with iris and facial recognition systems requiring specialized optical arrays and edge-processing chipsets that fingerprint modules avoid.
- Facial Recognition:Contactless authentication using 3D depth mapping and neural network classifiers processes identity verification in under one second. Demand concentrates in UAE aviation corridors and Saudi smart city checkpoints, driven by hygiene protocols and integration with existing surveillance infrastructure.
- Fingerprint Recognition:Silicon capacitive and ultrasonic sensors capture ridge patterns with liveness detection embedded at the hardware layer. Saudi banking networks and retail point-of-sale terminals represent the largest installed base due to mature unit economics and consumer familiarity.
- Iris Recognition:Near-infrared imaging of stromal texture delivers false acceptance rates below one in one million. Deployments cluster in Qatar border control and high-security government facilities where authentication certainty outweighs hardware cost.
- Voice Recognition:Spectrogram analysis of vocal tract resonance provides hands-free authentication for call center and remote banking applications.
Most installed capacity flows through fingerprint recognition. Expansion is steepest in facial recognition.
Deployment Model:
Operational expenditure profiles separate segments, with cloud-based models shifting capital burden to recurring subscriptions while embedded systems demand full upfront hardware commitment.
- On-Premises:Dedicated server infrastructure hosts biometric databases within facility boundaries, satisfying Saudi NCA and UAE TDRA data localization mandates for sensitive government and financial deployments. Large-scale national ID programs in Riyadh and Abu Dhabi require this architecture.
- Cloud-Based:Subscription frameworks deliver authentication-as-a-service with regional data center residency. Mid-market healthcare clinics in Dubai and retail chains in Oman adopt this model to convert capital expenditure into predictable monthly operating costs.
- Hybrid:Template storage remains on-premise while algorithm updates and analytics processing occur via cloud connectivity.
- Embedded Systems:Edge-based processing executes matching algorithms directly on biometric hardware without network dependency.
Hybrid architectures dominate new large-scale tenders. Cloud-based deployment is gaining share fastest among commercial mid-market buyers.
End User:
Procurement sophistication and compliance stringency create distinct customer tiers, with government buyers mandating certification regimes that commercial segments rarely require.
- Government:National cybersecurity authorities enforce hardware-level encryption and liveness detection certification for civil registry, border control, and law enforcement applications. Saudi Arabia's National ID program and UAE resident visa systems anchor regional demand.
- Banking:Central bank directives for customer onboarding and transaction authentication drive branch counter and ATM integration. Kuwait's financial inclusion initiatives and Saudi digital banking expansion sustain procurement volume.
- Healthcare:Patient identification systems eliminate duplicate records and secure pharmaceutical access.
- Retail:Franchise networks deploy biometric time-and-attendance and customer loyalty authentication.
Government contracts absorb the highest per-unit investment. Banking represents the fastest-climbing commercial vertical.
Application:
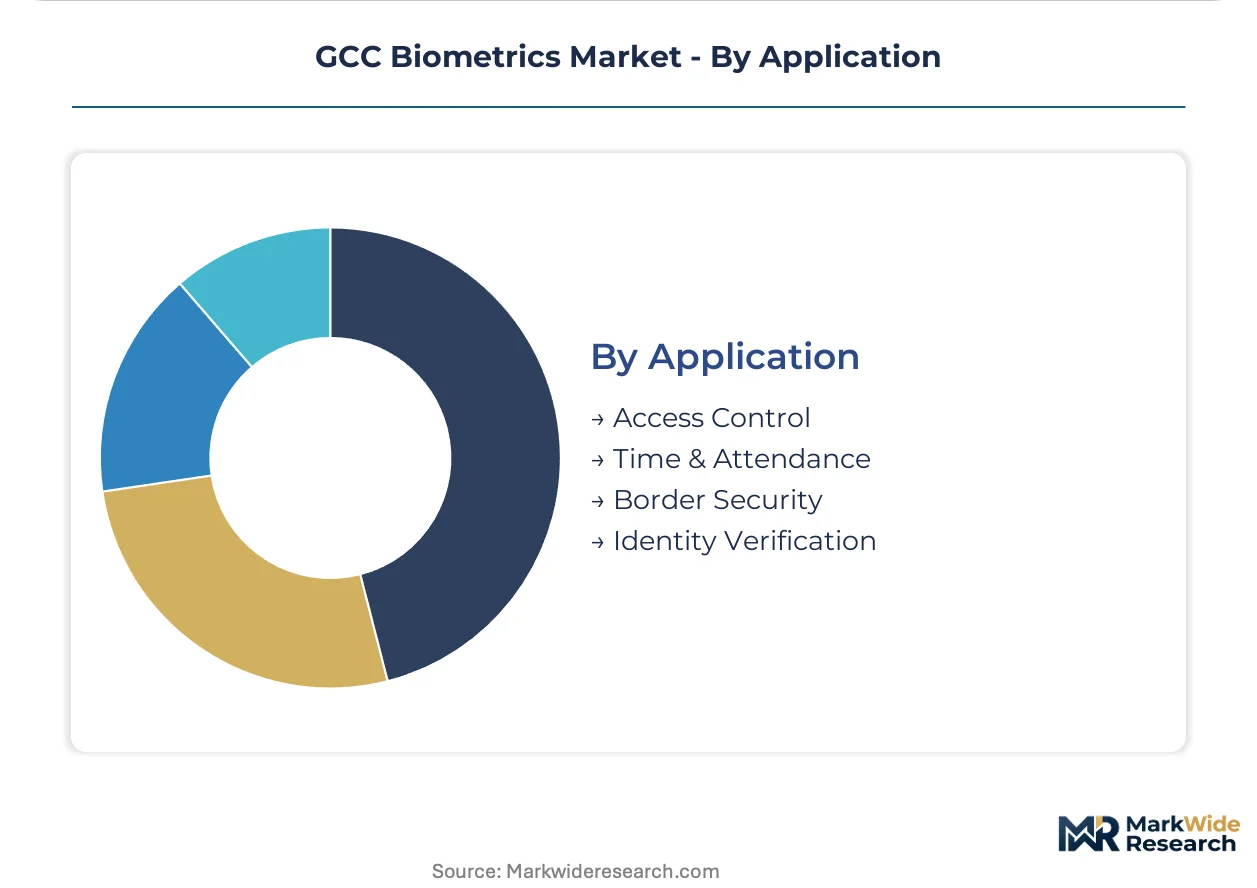
Throughput requirements and false acceptance tolerance define technical specifications, with border security demanding near-zero error rates that time-and-attendance applications relax.
- Border Security:Multi-modal corridors combining facial and iris recognition process thousands of passengers hourly at Dubai and Abu Dhabi international terminals. UAE aviation hub expansion mandates contactless passenger processing with sub-second authentication cycles.
- Access Control:Physical entry systems for commercial real estate, government facilities, and residential compounds constitute the broadest deployment category. Saudi giga-project developments embed biometric access as standard civic infrastructure across transport and commercial nodes.
- Identity Verification:Remote and in-person proofing for financial onboarding and government service delivery.
- Time & Attendance:Workforce management systems replace card-based clocking with physiological authentication.
Access control commands the largest installed base. Border security exhibits the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's NEOM giga-project anchors regional demand for biometric infrastructure, with Riyadh and Dubai serving as procurement command centers for national identity and aviation security programs.
Saudi Arabia
The National ID program and NEOM smart city construction drive multi-modal authentication procurement. SAMR-aligned GB standards mandate hardware-level encryption for all civil biometric deployments. Riyadh concentrates government contracting activity, while the Eastern Province hosts oil facility access control upgrades.
United Arab Emirates
Dubai International Airport's passenger processing expansion requires contactless facial recognition corridors with sub-second throughput. TDRA biometric data protection regulations exceed ISO/IEC 19794 baselines, forcing algorithmic bias auditing. Abu Dhabi anchors national resident visa system deployments and federal security infrastructure.
Qatar
Hamad International Airport border modernization and healthcare digitization create dual demand vectors for iris and palm-vein systems. The national cybersecurity authority enforces template localization for patient identification networks. Doha concentrates hospital network modernization and sovereign wealth fund-backed smart infrastructure.
Kuwait
Central bank financial inclusion directives mandate biometric onboarding for unbanked populations. National ID card reader integration for mobile enrollment shapes vendor selection criteria. Kuwait City anchors banking sector procurement, with retail network expansion driving branch counter authentication upgrades.
Oman
Commercial real estate access control retrofit programs and franchise retail network expansion sustain mid-market demand. Subscription-based authentication services displace perpetual licenses in clinic chains and hospitality. Muscat concentrates property management procurement, with Salalah port logistics driving workforce time-and-attendance deployment.
GCC Biometrics Market Key Industry Players
Vertical integration dominates the current landscape as hardware OEMs capture sensor-to-terminal margins and cloud-native vendors establish regional data centers. The vendor base separates into three tiers: integrated manufacturers with captive semiconductor supply, system integrators anchoring government identity programs, and subscription-platform specialists serving commercial mid-markets. M&A activity concentrates on liveness detection algorithm acquisitions and regional certification capability buys. Strategic partnerships between Gulf distributors and East Asian sensor foundries secure supply allocation during semiconductor allocation cycles.
Within the integrated manufacturing tier, Suprema Inc. and NEC Corporation exemplify divergent approaches to Gulf market penetration. Suprema anchors access control hardware through vertically integrated fingerprint module production. NEC occupies a position in large-scale government identity program integration, particularly iris and facial recognition system deployment. IDEMIA France SAS represents the civil biometric database specialist archetype, competing for national ID contracts across multiple Gulf states. These three players illustrate how technical certification depth, manufacturing control, and sovereign database experience create distinct competitive positions in a procurement environment shaped by NCA and TDRA mandates.
| Leading Market Players |
|---|
| Suprema Inc. |
| IBM Corporation |
| NEC Corporation |
| BioCatch Ltd. |
| Fujitsu Limited |
| IDEMIA France SAS |
| Samsung Electronics Co., Ltd. |
| Nuance Communications, Inc. |
| Thales S.A. |
| Others |
Cost & Logistics Intelligence
Government procurement programs across Saudi Arabia and the UAE anchor pricing power for biometric hardware vendors, concentrating volume in multi-year national ID and aviation security contracts that favor subscription-based SaaS frameworks over perpetual licensing.
Pricing Analysis
Silicon sensor cost pass-through from East Asian foundries shapes hardware pricing tiers across the GCC. Three-tier pricing structure across premium, standard, and economy levels separates government-grade encrypted modules from commercial access control units. Cost compression in mid-market fingerprint terminals is intensifying because Korean and Taiwanese semiconductor allocation cycles create input volatility. Banking sector buyers exhibit highest price sensitivity due to branch network scale, while Qatar's healthcare digitization programs prioritize liveness detection accuracy over unit cost.
Supply Chain Analysis
NCA and TDRA certification requirements gate market access for biometric hardware vendors before manufacturing scale becomes relevant. Sensor module production concentrates in Taiwan, South Korea, and China, with near-infrared optical arrays for iris systems drawing from specialized Japanese component suppliers. Single-source vulnerability runs through concentrated East Asian foundry capacity for capacitive fingerprint chips. Distribution runs through Dubai-based channel partners serving Saudi and UAE government integrators directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in GCC biometrics rests on silicon sensor cost curves flattening and premium-tier facial recognition systems capturing share in aviation and smart city deployments.
For Market Incumbents: Deepen liveness detection algorithm development to defend against cloud-native entrants offering subscription-based authentication services. Anchor manufacturing control through captive supply of fingerprint sensor modules from Korean foundry partnerships. Invest in SAMR-aligned GB standards certification ahead of Saudi national ID program expansion to maintain procurement eligibility. For New Entrants and Emerging Players: Begin with palm-vein authentication systems for Qatar's hospital network modernization, where first-mover status remains available and technical specifications are less prescriptive than government identity programs. Target Oman's franchise retail segment with per-door monthly subscription models that displace legacy card-based access control. Partner with Dubai-based system integrators already holding TDRA certification to bypass direct regulatory approval timelines. For Investors and Strategic Acquirers: Hardware OEMs with integrated sensor manufacturing are the most active acquirer in this space, seeking liveness detection software specialists to complete multi-modal authentication stacks. Long-term viability favors vendors with civil biometric database deployment experience across multiple Gulf states. Watch for NCA mandates extending hardware-level encryption requirements to commercial banking deployments as the inflection indicator for premium-tier hardware demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Liveness Detection Algorithm Acquisition | Suprema and NEC are consolidating software specialists to embed anti-spoofing directly into fingerprint and iris modules. |
| Regional Data Center Establishment | Cloud-native vendors must build UAE and Saudi facilities to satisfy TDRA and NCA template localization mandates. |
| GB Standards Certification Investment | SAMR-aligned technical specifications gate access to Saudi Arabia's National ID program and NEOM infrastructure tenders. |
| Multi-Modal System Integration | Facial-iris convergence in Dubai International Airport corridors sets specification benchmarks for aviation security procurement. |
| Subscription Model Transition | Mid-market healthcare and retail buyers in Oman and Bahrain prefer per-door monthly fees over upfront hardware purchases. |
Research Approach
Multiple input streams — procurement officer interviews at Saudi and UAE government agencies, channel partner discussions with Dubai-based distributors, and technical validation with liveness detection algorithm developers — were reconciled against secondary sources including NCA cybersecurity directives, TDRA biometric data protection regulations, SAMR-aligned GB standards documentation, and customs records of fingerprint sensor module imports. Bottom-up unit deployment estimates across aviation, banking, and healthcare verticals were triangulated with top-down market sizing from national ID program budgets and smart city infrastructure allocations.
Historical deployment trajectories in Saudi Arabia's National ID program and Dubai International Airport passenger processing expansion were cross-referenced against panel input from system integrators regarding pipeline visibility. The analytical framework segmented by authentication modality, deployment architecture, end-user vertical, and application throughput requirement across the projection horizon. CAGRs were derived from installed base growth curves adjusted for replacement cycles in banking terminals and greenfield penetration in Qatar healthcare networks.
Several conditions sit outside the modeled scope, including potential NCA mandate expansion to commercial sectors, geopolitical disruption of East Asian semiconductor supply, and GCC currency peg adjustments affecting import costs. Forecasts reflect assumptions about continued government infrastructure investment and stable regulatory certification timelines. A model refresh is warranted upon material change in Saudi giga-project construction schedules or TDRA encryption standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Italy Mobile Biometrics Market
Biometrics & Identity Management
E-Government Identity Management Market
Biometrics & Identity Management
Global Mobile User Authentication Market
Biometrics & Identity Management
Hand Geometry Biometrics Market
Biometrics & Identity Management
Vein Recognition Biometrics Market
Biometrics & Identity Management
ID Verification Market
Biometrics & Identity Management
Global Multifactor Authentication Market
Biometrics & Identity Management
Germany Identity Verification and Authentication Market
Biometrics & Identity Management
Europe Biometrics Market
Biometrics & Identity Management
Global Biometric Card Market
Biometrics & Identity Management
Global Authentication Services Market
Biometrics & Identity Management
Multi-Factor Authentication (MFA) Market
Biometrics & Identity Management
United States Facial Recognition Market
Biometrics & Identity Management
Global Biometric Systems Market
Biometrics & Identity Management
China Mobile Biometrics Market
Biometrics & Identity Management
Passive Authentication Market