
 Biometric Lockers Market | 2026-2036
Biometric Lockers Market Size, Share, and Industry Trends Forecast 2026-2036
Biometric Lockers Market Outlook
Corporate logistics buyers are unwinding legacy key-based locker contracts in favor of facial recognition and RFID-integrated systems. ASSA ABLOY leverages its access control heritage to dominate premium commercial installations across Europe. ZKTeco competes aggressively on cost-engineered fingerprint modules for Asia-Pacific deployment. Godrej & Boyce Mfg Co. Private Limited anchors its position through deep manufacturing scale and channel control within India's institutional sector.
Biometric lockers are electromechanical storage units incorporating fingerprint sensors, facial recognition cameras, or iris scanners with embedded encryption processors to authenticate users before releasing contents. These systems typically operate on 12-24V DC power with IP54-IP65 enclosure ratings and communicate via Ethernet, Wi-Fi, or cellular protocols to central management platforms. Smart lockers lead product type adoption in last-mile delivery networks where real-time chain-of-custody tracking is mandatory. Fingerprint recognition technology sustains the largest installed base due to mature sensor economics and sub-second authentication speeds. Package lockers represent the fastest-growing end-user segment as e-commerce fulfillment operators demand unattended pickup infrastructure.
FDA cybersecurity guidance for connected devices, the EU AI Act's risk classification framework for biometric systems, and BIS certification requirements for electronic locking mechanisms in India collectively shape product development roadmaps and market access conditions. The EU AI Act specifically mandates conformity assessments for facial recognition deployments in public and semi-public spaces, forcing manufacturers to re-engineer algorithms for explainability and audit trails. Stakeholders must monitor evolving data localization requirements and decide whether to architect region-specific firmware stacks or pursue modular compliance architectures that adapt to jurisdiction-specific biometric governance.
Market Dynamics
The EU AI Act's risk classification framework for biometric systems is forcing manufacturers to re-engineer facial recognition algorithms with embedded explainability modules and immutable audit trails before market access.
Growth Catalysts
- E-commerce fulfillment infrastructure:Last-mile delivery operators in Germany and the United States are deploying unattended pickup terminals with real-time chain-of-custody tracking.
- GDPR-mandated encryption:European data protection authorities require biometric template storage with AES-256 encryption and local processing, accelerating hardware refresh cycles.
- Smart city investments:Municipalities across Japan are integrating biometric lockers into transit hubs and public service centers as part of METI-backed digital infrastructure programs.
Market Restraints
- Semiconductor supply concentration:Fingerprint sensor ASIC fabrication relies heavily on Taiwan-based foundry capacity, creating vulnerability to geopolitical disruption.
- Algorithm training data scarcity:Iris recognition systems require diverse biometric datasets that remain concentrated in North American and Western European populations, limiting accuracy in emerging markets.
- Mechanical lock substitution:Low-cost electronic keypad systems continue to satisfy price-sensitive segments in institutional procurement, compressing biometric adoption timelines.
Strategic Opportunities
- Healthcare medication dispensing:Hospital pharmacies in the United States are piloting fingerprint-automated narcotic cabinets to satisfy DEA chain-of-custody requirements.
- Edge AI convergence:On-device neural processing units combined with 3D facial mapping enable authentication without cloud connectivity, opening air-gapped defense and critical infrastructure applications.
- India PLI scheme:Domestic manufacturing incentives for electronic hardware are attracting component localization investments for BIS-certified locking mechanisms.
Industry Challenges
- Firmware certification timelines:EU AI Act conformity assessment procedures for high-risk biometric systems extend product launch cycles by eight to fourteen months.
- Legacy access control integration:Enterprise buyers require API compatibility with existing ASSA ABLOY, LenelS2, and Software House credential management platforms, complicating vendor switching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biometric Lockers Market |
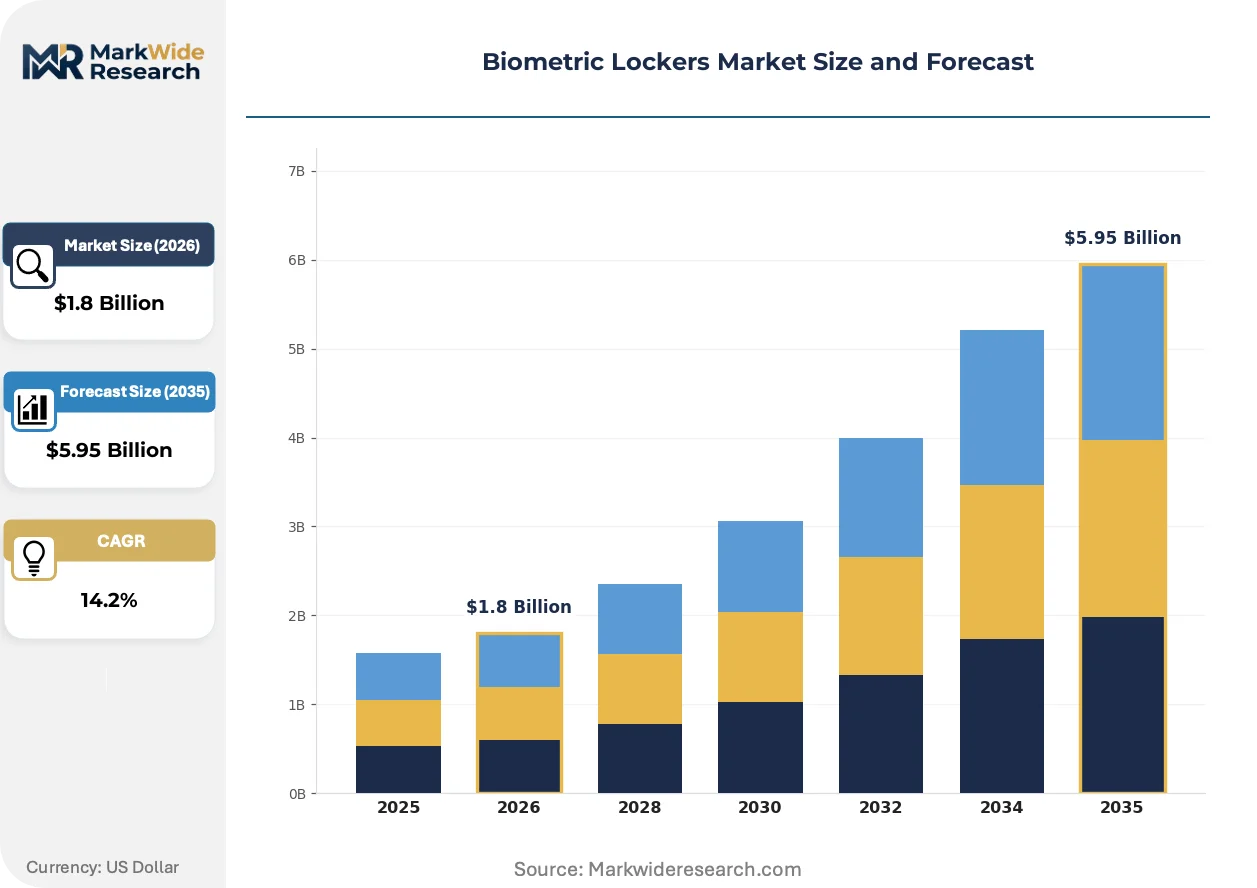
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lockers, Automated Retrieval, Modular Lockers, Package Lockers End User: Residential, Commercial, Educational Institutions, Logistics Technology: Fingerprint Recognition, Facial Recognition, Iris Scanning, RFID Installation: Indoor, Outdoor, Self-Service Kiosks, Mobile Units |
| Companies Covered | WYSE, SentriLock, GANTNER, Godrej & Boyce Mfg Co. Private Limited, IDEMIA, ZKTeco, Gunnebo, ASSA ABLOY, Digillock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biometric Lockers Market Strategic Shifts
Authentication architectures are migrating from centralized cloud verification to edge-local processing, compressing latency while satisfying data sovereignty mandates across fragmented regulatory jurisdictions.
Multispectral fingerprint sensors capturing subcutaneous vein patterns are supplanting capacitive surface-only modules in high-security deployments. Financial services vault operators and diamond trading facilities in Antwerp and Mumbai are adopting these systems to defeat spoof attacks. The technology is compressing market share for legacy optical sensors that remain vulnerable to gelatin and latex reproductions.
The EU AI Act's mandatory conformity assessments for facial recognition in semi-public spaces are redirecting R&D investment toward algorithmic explainability tools. Manufacturers must now document decision pathways for each authentication event. Smart locker deployments in French and German railway stations are most affected, with operators demanding vendor-provided audit trail middleware.
Facility managers are unbundling hardware procurement from software subscription fees, reversing the bundled SaaS model that dominated early smart locker adoption. Universities and corporate campuses in the United States are now requesting perpetual license options with on-premise management servers. This shift is visible most acutely in California and Texas where IT governance policies restrict third-party cloud data residency.
Biometric Lockers Market Segmentation
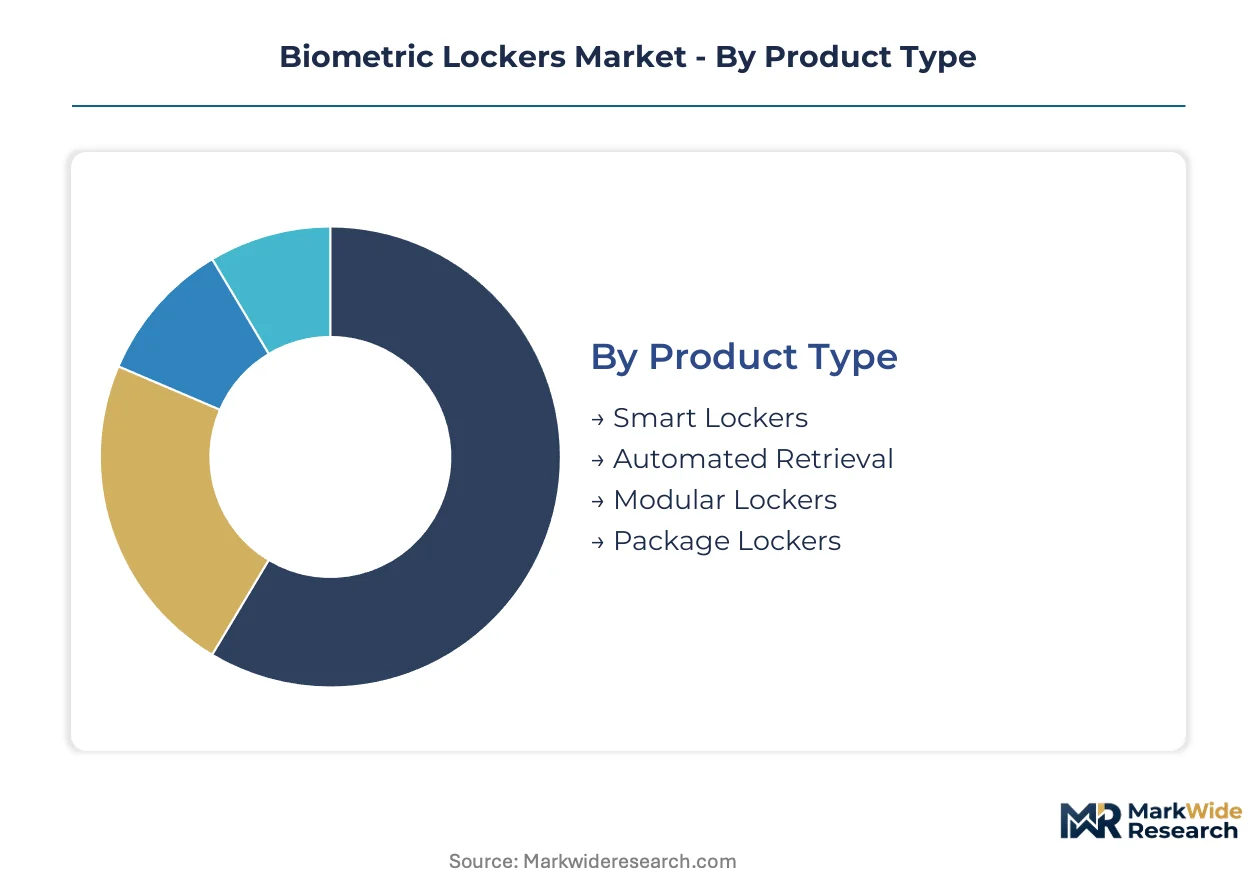
Biometric locker procurement decisions hinge on authentication precision, environmental exposure, and integration complexity. Each segmentation dimension carries distinct regulatory footprints and total cost-of-ownership profiles that reshape vendor selection criteria across deployment contexts.
Product Type:
EU AI Act risk classifications and FDA cybersecurity guidance create divergent compliance burdens across form factors, with high-risk biometric deployments requiring conformity assessments that extend hardware refresh cycles.
- Smart Lockers:These units integrate fingerprint or facial recognition sensors with cloud-connected management platforms and real-time inventory tracking. German railway operators and Japanese transit authorities deploy these systems for unattended parcel exchange, driven by METI-backed smart city mandates and GDPR chain-of-custody requirements.
- Package Lockers:Purpose-built terminals for last-mile delivery networks feature sub-second authentication speeds and AES-256 encrypted template storage. E-commerce fulfillment operators in the United States and Germany are unwinding legacy key-based contracts in favor of these systems, compelled by unattended pickup volume surges.
- Automated Retrieval:Robotic internal mechanisms position stored items at access points upon biometric verification.
- Modular Lockers:Configurable cell banks allow capacity scaling without full system replacement.
Established volume favors Smart Lockers; emerging adoption favors Package Lockers.
End User:
Procurement authority and authentication stringency vary sharply across customer types, with institutional buyers demanding API compatibility and residential users prioritizing installation simplicity.
- Logistics:Third-party fulfillment operators and postal services require unattended pickup infrastructure with immutable audit trails. Last-mile operators in Germany and the United States are deploying these terminals to satisfy real-time chain-of-custody tracking mandates under GDPR and FDA cybersecurity guidance.
- Commercial:Corporate campuses and co-working facilities integrate fingerprint or facial recognition units with existing access control platforms. Facility managers in California and Texas are requesting perpetual software licenses with on-premise management servers to satisfy IT governance policies restricting third-party cloud data residency.
- Educational Institutions:Universities deploy shared storage for equipment, documents, and personal belongings.
- Residential:Apartment complexes and private homes adopt simplified fingerprint modules for package and key storage.
Logistics commands the steepest expansion trajectory; Commercial offers the densest pricing realization.
Technology:
Sensor economics and spoof resistance determine technology selection, with multispectral modules commanding premiums over capacitive alternatives in high-security deployments.
- Fingerprint Recognition:Capacitive and multispectral sensors capture surface or subcutaneous vein patterns for authentication. Mature sensor economics and sub-second verification speeds sustain the largest installed base across Germany, Japan, and the United States, though gelatin and latex spoof vulnerabilities persist in legacy optical modules.
- Facial Recognition:2D and 3D camera systems with embedded neural processing units enable authentication without cloud connectivity. The EU AI Act's mandatory conformity assessments for semi-public deployments are forcing algorithm re-engineering with explainability modules, extending product launch cycles.
- Iris Scanning:Near-infrared cameras map unique patterns in the colored portion of the eye.
- RFID:Contactless credential verification complements or substitutes biometric methods in hybrid architectures.
Fingerprint Recognition dominates current deployment; Facial Recognition is gaining share fastest in regulated environments.
Installation:
Environmental exposure ratings and power infrastructure availability segment deployment feasibility across indoor, outdoor, and mobile contexts.
- Indoor:Climate-controlled environments with standard 12-24V DC power and IP54 enclosure ratings suffice. Corporate campuses and hospital pharmacies in the United States deploy these units for medication dispensing, satisfying DEA chain-of-custody requirements with fingerprint-automated narcotic cabinets.
- Outdoor:Weatherized systems with IP65 ratings and cellular connectivity serve transit hubs and public spaces. Municipalities across Japan integrate these units into railway stations and service centers under METI digital infrastructure programs.
- Self-Service Kiosks:Freestanding terminals combine storage with touchscreen interfaces for user guidance.
- Mobile Units:Battery-powered or solar-equipped systems serve temporary events and construction sites.
Indoor installations anchor current revenue; Outdoor deployments are climbing the fastest on smart city investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports biometric locker systems to fulfillment operators across the Netherlands and Scandinavia, establishing a trade corridor anchored by GDPR-compliant encryption standards and METI-aligned smart city specifications.
United States
Last-mile delivery operators deploy unattended pickup terminals with real-time chain-of-custody tracking. FDA cybersecurity guidance for connected devices mandates encrypted biometric template storage. Dallas-Fort Worth logistics clusters anchor deployment density for e-commerce fulfillment infrastructure.
Germany
Railway operators and postal services replace mechanical systems with facial recognition units for parcel exchange. The EU AI Act's risk classification framework forces algorithm re-engineering with explainability modules. Frankfurt and Hamburg transit hubs concentrate smart locker integration under federal digital infrastructure programs.
Japan
Municipalities integrate biometric terminals into railway stations and public service centers. METI-backed digital infrastructure programs fund IP65-rated outdoor installations with cellular connectivity. Tokyo and Osaka metropolitan areas lead Kanto and Kansai regional deployment cycles.
India
Institutional buyers adopt fingerprint modules for equipment and document storage in educational and government facilities. BIS certification requirements for electronic locking mechanisms shape product roadmaps. Maharashtra and Karnataka manufacturing clusters attract PLI scheme investments for component localization.
United Kingdom
Corporate campuses and co-working facilities integrate biometric units with existing access control platforms. GDPR-mandated AES-256 encryption accelerates hardware refresh cycles. London and Southeast England concentrate commercial deployment density for facility management upgrades.
Biometric Lockers Market Competitive Environment
Listed leaders compete with private specialists across access control heritage and manufacturing scale dimensions. The vendor base stratifies into three tiers: premium commercial installers, cost-engineered module fabricators, and domestic institutional anchors. Strategic archetypes include access control incumbents leveraging credential management integration, sensor module specialists competing on authentication speed, and diversified industrials exploiting captive distribution channels. Competitive moves center on API compatibility investments and firmware certification acceleration.
Among access control heritage players, ASSA ABLOY exemplifies the premium-tier archetype through its credential management platform integration. ZKTeco occupies a position within the cost-engineered module segment, representing sensor economics specialization for high-volume deployment contexts. Godrej & Boyce Mfg Co. Private Limited anchors the domestic institutional tier, exemplifying manufacturing scale advantages within geographically concentrated procurement environments.
| Leading Market Players |
|---|
| WYSE |
| SentriLock |
| GANTNER |
| Godrej & Boyce Mfg Co. Private Limited |
| IDEMIA |
| ZKTeco |
| Gunnebo |
| ASSA ABLOY |
| Digillock |
| Others |
Value Chain & Pricing Dynamics
Foundry-scale economies in Taiwan-based fingerprint sensor ASIC fabrication compress unit economics for capacitive modules while erecting price floors for next-generation multispectral alternatives. This concentration dynamic creates divergent margin structures across authentication tiers, with high-security deployments absorbing premiums for subcutaneous vein-pattern technology while cost-engineered segments face relentless pressure from keypad substitution.
Pricing Analysis
Multispectral fingerprint modules command substantial premiums over legacy capacitive sensors, while facial recognition units with embedded neural processing units occupy a mid-tier position pending EU AI Act compliance cost absorption. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with BIS-certified and FDA-aligned hardware realizing substantial markups over uncertified alternatives. Cost compression in economy-tier capacitive sensors is intensifying because of ZKTeco's aggressive sensor economics specialization. Logistics operators demonstrate the least price sensitivity due to chain-of-custody compliance mandates, while Indian institutional procurement remains acutely cost-conscious.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for sensor module shipments originating from Taiwan and South Korea. Fingerprint sensor ASIC fabrication draws from Taiwan-based foundry capacity, multispectral imaging components rest on Japanese and German optical supply chains, and enclosure manufacturing feeds from Chinese and Indian metalworking clusters. Single-source vulnerability in Taiwan-based semiconductor fabrication exposes lead times to geopolitical disruption. Distribution runs through ASSA ABLOY's credential management platform integration, ZKTeco's direct high-volume deployment channels, and Godrej & Boyce's captive institutional networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory jurisdictions creates niche opportunities for compliance-specialized vendors, as the EU AI Act's risk classification framework splinters homogeneous product architectures into region-specific firmware stacks.
For Market Incumbents: Shield premium positioning by accelerating EU AI Act conformity assessment pre-certification before competitors complete algorithm re-engineering cycles. Deepen backward integration into Taiwan-based foundry relationships to secure fingerprint sensor ASIC allocation during capacity constraints. Cement API compatibility with LenelS2 and Software House credential management platforms to complicate enterprise switching. For New Entrants and Emerging Players: Differentiate on edge-AI authentication architectures that eliminate cloud connectivity requirements for air-gapped defense and critical infrastructure deployments. Target Indian institutional procurement under PLI scheme incentives for BIS-certified component localization. Pursue hospital pharmacy narcotic cabinet pilots in the United States to exploit DEA chain-of-custody compliance gaps. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sensor module specialists with explainability-ready facial recognition algorithms and established EU conformity assessment pathways. Long-term viability hinges on firmware certification velocity rather than hardware scale alone. Watch for EU AI Act enforcement intensity in French and German railway station deployments as inflection indicator for compliance-premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Pre-Certification | Accelerates market access for facial recognition deployments in German and French transit hubs. |
| Edge AI Neural Processing Integration | Enables air-gapped authentication without cloud connectivity for defense infrastructure. |
| India PLI Scheme Component Localization | Reduces landed cost for BIS-certified locking mechanisms in Maharashtra procurement clusters. |
| API Compatibility Investment | Preserves enterprise switching costs through ASSA ABLOY and LenelS2 platform integration. |
| Multispectral Sensor Module Development | Defeats gelatin spoof attacks for Antwerp diamond trading and Mumbai financial vault operators. |
Study Parameters
A standing panel of biometric hardware procurement managers, access control system integrators, logistics fulfillment operators, and regulatory compliance officers provided ongoing calibration throughout the research process. Primary fieldwork combined structured interviews with facility managers at German railway operators, Japanese transit authorities, and Dallas-Fort Worth logistics clusters with secondary validation against EU AI Act implementation guidance, FDA cybersecurity documentation, METI smart city program disclosures, and BIS certification registries. Bottom-up unit deployment estimates triangulated against top-down market sizing derived from foundry capacity disclosures and sensor module shipment data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including authentication technology type, installation environment rating, end-user procurement authority, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles, e-commerce fulfillment infrastructure buildout trajectories, and smart city investment program commitments. Industry-specific forecast inputs incorporated DEA chain-of-custody mandate expansion timelines and EU AI Act conformity assessment completion rates.
Material uncertainties — geopolitical disruption of Taiwan-based foundry capacity, algorithm training data scarcity for non-Western biometric populations, and mechanical lock substitution in price-sensitive procurement — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory enforcement intensity and infrastructure investment continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Global Phone Based Authentication Solution Market
Biometrics & Identity Management
Automated Fingerprint Identification Systems (AFIS) Market
Biometrics & Identity Management
Biometric Bike Locks Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Software Market
Biometrics & Identity Management
Biometric ATM Market
Biometrics & Identity Management
Europe Biometrics Market
Biometrics & Identity Management
Global Biometric Authentication Identification Market
Biometrics & Identity Management
Airport Biometrics Market
Biometrics & Identity Management
Global Mobile User Authentication Market
Biometrics & Identity Management
Global Authentication Services Market
Biometrics & Identity Management
North America Biometrics in Government Market
Biometrics & Identity Management
Germany Identity Verification and Authentication Market
Biometrics & Identity Management
Italy Mobile Biometrics Market
Biometrics & Identity Management
Spain Mobile Biometrics Market
Biometrics & Identity Management
Global Authentication and Brand Protection Market
Biometrics & Identity Management
Europe Government and Security Biometrics Market