
 Global Human Identification Market | 2026-2036
Global Human Identification Market Size, Share, and Industry Trends Forecast 2026-2036
Global Human Identification Market Foresight
Subscription-based software licensing for forensic DNA analysis platforms is realigning how laboratories procure human identification capabilities. Thermo Fisher Scientific leverages its integrated instrument-software ecosystem to anchor long-term contracts with government forensic labs. QIAGEN sustains competitive positioning through specialized sample-to-insight workflows that reduce turnaround times for criminal casework.
Human identification encompasses the biometric and molecular methods used to establish or verify individual identity through unique biological markers, primarily relying on DNA polymorphism analysis, fingerprint minutiae mapping, or iris pattern encoding with resolution thresholds exceeding 200 pixels per inch for forensic admissibility. Its commercial purpose centers on delivering legally defensible identity confirmation for criminal justice, border management, and disaster response operations. DNA profiling kits command the deepest margin pools due to consumable replenishment cycles, while next-generation sequencing represents the fastest-expanding technology segment as laboratories transition from capillary electrophoresis. Multimodal biometrics occupies a maturing niche in high-throughput border security installations where false acceptance rates must fall below one in one million.
The U.S. FBI's CODIS standards, the EU AI Act's biometric surveillance restrictions, and China's GB standards for fingerprint data compression collectively shape product certification requirements and market access conditions across major jurisdictions. FDA oversight of forensic-grade reagents and EMA-aligned quality standards for DNA profiling consumables create layered compliance burdens that favor established suppliers with dedicated regulatory affairs functions. Stakeholders must monitor evolving national DNA database legislation and cross-border data transfer protocols to anticipate procurement shifts in law enforcement and immigration sectors.
Market Dynamics
Forensic laboratories face simultaneous pressure to reduce DNA analysis turnaround times while the EU AI Act and GDPR impose stricter biometric data governance protocols. This tension between operational acceleration and compliance rigor is forcing procurement departments to renegotiate vendor contracts around data sovereignty and audit trail capabilities.
Growth Catalysts
- CODIS database expansion:The FBI's Combined DNA Index System mandates drive consumable demand across state forensic laboratories in the United States. State-level backlog reduction programs accelerate kit procurement cycles.
- Disaster victim identification protocols:International standards for mass casualty response require rapid DNA matching capabilities. Governments in Japan, Australia, and Germany stockpile portable identification systems for emergency deployment.
- Next-generation sequencing migration:Capillary electrophoresis replacement cycles create equipment refresh demand. Forensic service providers in China and South Korea prioritize platforms with integrated bioinformatics pipelines.
Market Restraints
- Reagent supply concentration:Certified forensic-grade DNA polymerases and fluorescent dyes rely on a limited supplier base in Switzerland and Germany. Single-source dependencies create vulnerability to export licensing delays.
- EU AI Act biometric surveillance restrictions:Real-time facial recognition deployments in public spaces face operational prohibitions. Law enforcement agencies must segment databases to comply with purpose-limitation requirements.
- Capillary electrophoresis asset stranding:Laboratories with recent CE instrument investments face accelerated obsolescence risk. Capital depreciation schedules conflict with NGS transition timelines.
Strategic Opportunities
- Rapid DNA at point-of-arrest:Booking station workflows in the United States and United Kingdom create demand for 90-minute analysis systems. Police forces seek cartridge-based platforms requiring minimal technical training.
- Missing persons database integration:Family reference sample collection programs in India and Brazil remain underpenetrated. Mobile collection units paired with cloud-based matching algorithms address infrastructure gaps.
- Forensic genetic genealogy convergence:Consumer database cross-referencing with law enforcement samples solves cold cases. Regulatory frameworks in Australia and Canada are clarifying permissible use boundaries.
Industry Challenges
- Bioinformatics specialist scarcity:Interpretation of complex NGS mixtures requires computational biology expertise. Forensic laboratories compete with pharmaceutical and agricultural genomics sectors for qualified personnel.
- Validation timeline compression:ISO 17025 accreditation for new chemistries demands 12-18 months of reproducibility studies. Prosecutors resist admitting methods without established court precedent.
- Interoperability with legacy STR databases:NGS platforms generate SNP and STR data simultaneously. Data format standardization across CODIS, Interpol, and national systems remains incomplete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Human Identification Market |
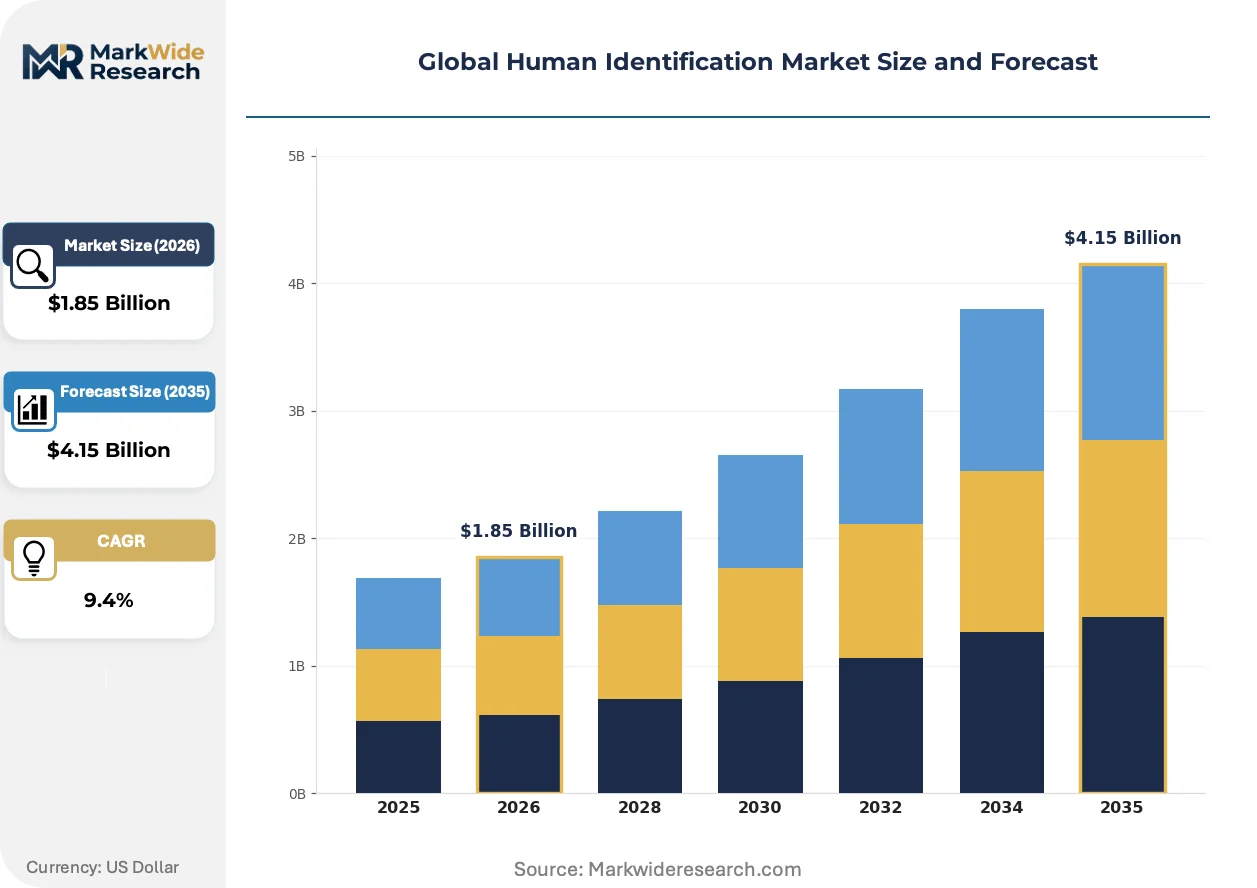
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Profiling Kits, Biometric Scanners, Fingerprint Analyzers, Iris Recognition Devices, Facial Recognition Systems Technology: Polymerase Chain Reaction, Short Tandem Repeat Analysis, Next-Generation Sequencing, Automated Fingerprint Identification, Multimodal Biometrics Application: Forensic Analysis, Border Security, Criminal Investigations, Disaster Victim Identification, Personal Identity Verification End User: Law Enforcement Agencies, Immigration Authorities, Forensic Laboratories, Security Providers, Government Bodies |
| Companies Covered | Thermo Fisher Scientific Inc., QIAGEN, Promega Corporation, Bio-Rad Laboratories Inc., Hamilton Company, Agilent Technologies Inc., Abbott Laboratories, PerkinElmer Inc., Illumina Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Human Identification Market Shifts & Advancements
Workflow automation and artificial intelligence-assisted mixture deconvolution are compressing analysis timelines while raising admissibility questions. Vendors must balance speed claims with reproducibility documentation sufficient for Daubert challenges.
Next-generation sequencing is expanding into forensic casework laboratories previously restricted to capillary electrophoresis methods. State crime laboratories in Texas, California, and Virginia have completed validation studies for NGS-based STR analysis. The technology is expanding into missing persons identification and disaster victim response by enabling simultaneous analysis of nuclear and mitochondrial DNA from degraded samples.
The EU AI Act's biometric surveillance restrictions took effect in 2024 with extraterritorial implications for equipment vendors. Manufacturers must embed purpose-limitation controls and audit logging into software architectures. Forensic database management systems sold into European markets now require explicit human-in-the-loop protocols for automated matching alerts.
Subscription licensing for forensic software is displacing perpetual license models among underfunded municipal laboratories. Cloud-based genotyping and statistical interpretation tools reduce upfront capital requirements. This shift concentrates most visibly in the United Kingdom and Australia where police forces operate under centralized procurement frameworks with strict annual budget cycles.
Global Human Identification Market Segmentation
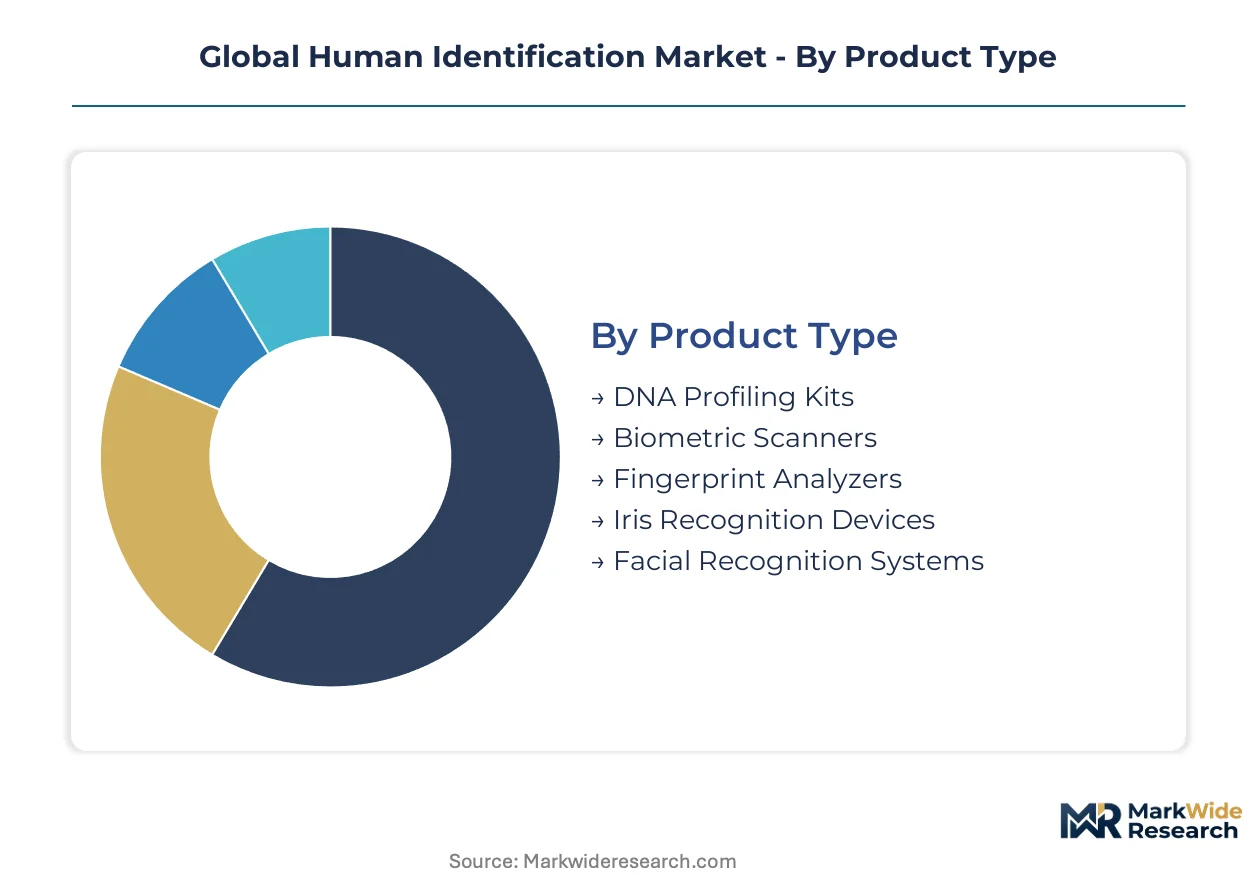
Human identification markets fragment across molecular and biometric modalities, each carrying distinct procurement cycles, regulatory burdens, and margin profiles. Laboratories and security agencies prioritize segments offering admissible evidence standards or border throughput compliance.
Product Type:
Supply concentration clusters around consumable chemistries with ISO 17025 certification, while hardware vendors compete on interoperability with legacy database architectures.
- DNA Profiling Kits:STR multiplex reagents and extraction chemistries dominate consumable spend. State forensic laboratories in the United States and Germany drive procurement through CODIS and national DNA database expansion programs.
- Biometric Scanners:Multimodal enrollment stations for border checkpoints require FBI-certified fingerprint sensors and ISO-compliant iris cameras. Airports in the United Arab Emirates and Singapore deploy these for high-throughput passenger processing.
- Fingerprint Analyzers:Latent print examination systems with AFIS connectivity serve criminal identification workflows.
- Iris Recognition Devices:Contactless biometric capture systems address hygiene and speed requirements in immigration corridors.
- Facial Recognition Systems:EU AI Act restrictions limit real-time deployment in public spaces; purpose-limited forensic applications persist.
DNA Profiling Kits absorb the bulk of installed capacity; Biometric Scanners are expanding most quickly.
Technology:
Cost tier differentiation separates validated casework methods from emerging platforms still navigating accreditation timelines.
- Polymerase Chain Reaction:Thermocycling amplification remains the forensic standard for STR locus expansion. Laboratories in China and Brazil rely on PCR for high-volume criminal database sample processing.
- Short Tandem Repeat Analysis:Capillary electrophoresis-based STR profiling generates court-admissible genotypes. The FBI's CODIS standards mandate specific locus panels, locking in reagent specifications.
- Next-Generation Sequencing:Massively parallel sequencing enables mitochondrial and SNP analysis from degraded remains. Forensic service providers in Australia and South Korea prioritize platforms with integrated bioinformatics.
- Automated Fingerprint Identification:Minutiae extraction algorithms with NIST-compliant accuracy thresholds support tenprint and latent searches.
- Multimodal Biometrics:Fused fingerprint-iris-face matching reduces false acceptance rates below one in one million for critical infrastructure access.
Short Tandem Repeat Analysis commands the deepest validation investment; Next-Generation Sequencing shows the steepest expansion trajectory.
Application:
Volume concentrates in government-funded programs with statutory mandates, while commercial identity verification remains fragmented across compliance-driven sectors.
- Forensic Analysis:DNA profiling for criminal casework and database enrollment operates under strict chain-of-custody protocols. State backlog reduction initiatives in Texas and California accelerate kit consumption.
- Border Security:Biometric entry-exit systems for visa overstayer detection require real-time matching against watchlists. Schengen Area ports of entry deploy multimodal gates under GDPR data retention limits.
- Criminal Investigations:Rapid DNA at booking stations creates demand for 90-minute turnaround systems in the United States and United Kingdom.
- Disaster Victim Identification:International protocols for mass casualty response mandate portable DNA analysis capabilities. Japan and Germany maintain stockpiled rapid deployment systems.
- Personal Identity Verification:Civil registry biometric enrollment supports national ID programs in India and Brazil.
Forensic Analysis anchors government procurement budgets; Border Security is gaining share fastest.
End User:
Customer type determines contract structure, with centralized procurement frameworks favoring subscription licensing over capital expenditure.
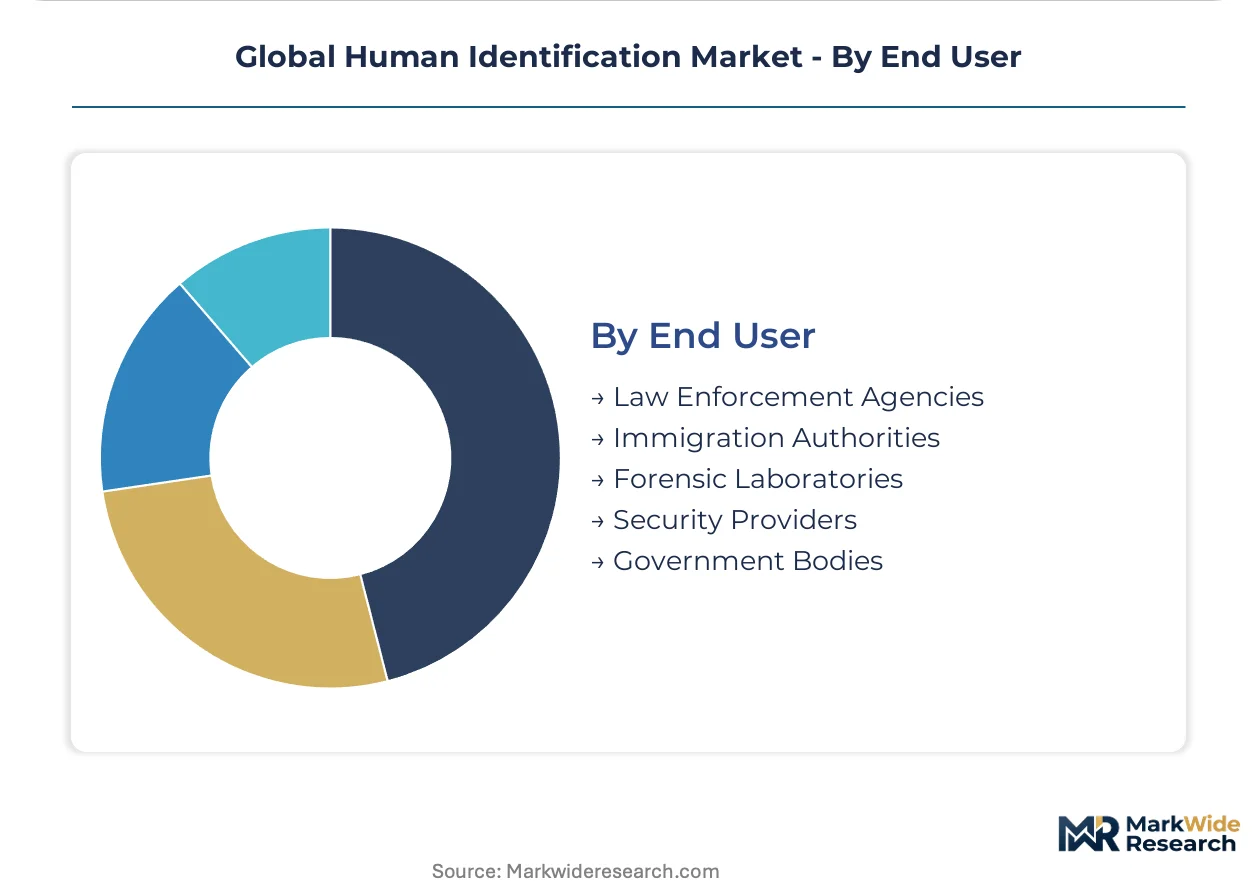
- Law Enforcement Agencies:Police forces require admissible DNA analysis and rapid fingerprint identification for arrest and booking workflows. FBI grant programs shape purchasing timelines across United States municipal departments.
- Immigration Authorities:Border control agencies need high-throughput biometric enrollment with Interpol database connectivity. Australia's Department of Home Affairs operates centralized procurement for multi-site deployment.
- Forensic Laboratories:ISO 17025-accredited facilities validate new chemistries through 12-18 month reproducibility studies before casework adoption.
- Security Providers:Private sector access control and background screening services operate under less stringent evidentiary standards.
- Government Bodies:National DNA database administrators in China and the United Kingdom drive standardization and interoperability requirements.
Law Enforcement Agencies represent the largest addressable budget pool; Immigration Authorities are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotechnology corridor anchors forensic genomics innovation, with Massachusetts General Hospital and Harvard-affiliated laboratories validating next-generation sequencing protocols for criminal casework. This concentration of academic medical centers and instrument manufacturers shapes procurement standards that cascade to state crime laboratories nationwide.
United States
The FBI's CODIS database expansion and state-level backlog reduction programs drive consumable procurement across Texas, California, and Virginia crime laboratories. FDA oversight of forensic-grade reagents creates compliance barriers favoring established suppliers. The Virginia Department of Forensic Science in Richmond completed NGS validation studies in 2023, establishing precedent for admissibility standards.
Germany
Federal police modernization programs and BSI certification requirements for biometric systems sustain demand for ISO 17025-accredited DNA profiling kits. The EU AI Act's biometric surveillance restrictions reshape border control procurement specifications. The Frankfurt Rhine-Main metropolitan region concentrates forensic service providers serving both domestic law enforcement and Interpol coordination centers.
China
National DNA database scaling and GB standards for fingerprint data compression mandate technology localization for foreign vendors. The Ministry of Public Security operates centralized procurement for provincial public security bureaus. Shenzhen's technology corridor hosts domestic manufacturers developing integrated biometric enrollment stations for immigration checkpoints.
United Kingdom
Home Office centralized procurement frameworks and strict annual budget cycles accelerate subscription licensing adoption for forensic software. GDPR data retention limits constrain biometric database architecture decisions. The London metropolitan area concentrates private forensic service providers contracting with regional police forces under competitive tender arrangements.
Australia
Disaster victim identification protocol mandates and family reference sample collection programs for missing persons databases expand portable DNA analysis demand. The Department of Home Affairs operates centralized procurement for multi-site border biometric deployment. Melbourne's forensic medicine institutes collaborate with Southeast Asian counterparts on mass casualty response standardization.
Global Human Identification Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the forensic technology stack, with integrated instrument-software ecosystems commanding premium pricing against modular component suppliers. The vendor base stratifies into three tiers: multinational life science conglomerates with dedicated forensic divisions, specialized molecular diagnostics firms, and emerging rapid DNA platform developers. Strategic consolidation concentrates around bioinformatics pipeline acquisitions and cloud-based genotyping service partnerships. Geographic expansion into underpenetrated national DNA database programs represents the dominant competitive move alongside ISO 17025 certification racing for new chemistries.
Within the integrated-systems tier, Thermo Fisher Scientific Inc. exemplifies the instrument-reagent-software bundling archetype that anchors long-term government contracts. QIAGEN occupies a specialist position emphasizing sample-to-insight workflow compression. Illumina Inc. represents the sequencing technology layer that enables NGS migration across forensic laboratories transitioning from capillary electrophoresis methods.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| QIAGEN |
| Promega Corporation |
| Bio-Rad Laboratories Inc. |
| Hamilton Company |
| Agilent Technologies Inc. |
| Abbott Laboratories |
| PerkinElmer Inc. |
| Illumina Inc. |
| Others |
Supply & Pricing Matrix
State forensic laboratories operating under FBI CODIS procurement mandates anchor demand for certified DNA profiling consumables, locking in subscription-based pricing models that bundle reagents with validation support and regulatory compliance services. This buyer concentration grants incumbent suppliers pricing power through long-term service contracts while compressing margins for modular component vendors competing on spot-market terms.
Pricing Analysis
Outcome-based pricing anchors forensic DNA analysis platforms, with laboratories paying premium rates for ISO 17025-certified chemistries that guarantee court admissibility and chain-of-custody integrity. Three-tier pricing structure across premium, standard, and economy levels separates FBI-validated STR multiplex kits from research-grade reagents and unvalidated imports. Pricing pressure stems from municipal budget constraints in United Kingdom and Australian police forces, which are driving subscription licensing adoption to convert capital expenditure into operational spend. State crime laboratories in Texas and California exhibit lowest price sensitivity due to federal backlog reduction grants, while underfunded municipal departments in Brazil and India face acute cost compression.
Supply Chain Analysis
Single-source vulnerability sits with certified forensic-grade DNA polymerases and fluorescent dye chemistries manufactured in Switzerland and Germany. Manufacturing concentration in these jurisdictions draws from specialized fermentation capabilities and precision chemical synthesis expertise that cannot be replicated rapidly. Raw material dependencies include high-purity nucleotides, fluorophore conjugates, and synthetic oligonucleotide primers. Tariff exposure on reagent exports to China creates supply risk as the Ministry of Public Security scales national DNA database enrollment. Distribution runs through authorized distributors with cold-chain logistics capabilities serving ISO 17025-accredited facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints on certified forensic-grade reagents prop pricing power for validated suppliers, with bioinformatics specialist scarcity creating additional bottlenecks that sustain premium positioning across the analysis window.
For Market Incumbents: Anticipate NGS platform commoditization by deepening bioinformatics service bundling and securing exclusive reference database partnerships for forensic genetic genealogy applications. Rapid DNA cartridge standardization at booking stations in the United States and United Kingdom represents the priority capacity addition. Cloud-based genotyping subscriptions offer channel control against modular software entrants. For New Entrants and Emerging Players: Cloud-native LIMS platforms with integrated audit logging for EU AI Act compliance offer the most penetrable entry vector. Mobile collection units paired with AI-assisted mixture deconvolution address infrastructure gaps in India's missing persons database programs and Brazil's family reference sample collection initiatives. Direct procurement relationships with centralized police force IT departments bypass entrenched reagent distributors. For Investors and Strategic Acquirers: The window for entry favors bioinformatics pipeline specialists with ISO 17025 accreditation pathways already initiated. Long-term viability rests on convergence between consumer genetic databases and law enforcement matching protocols, with regulatory clarity in Australia and Canada as the signal to watch for inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| NGS Platform Validation | FBI and state crime laboratory accreditation establishes court precedent for admissibility standards. |
| Forensic Genetic Genealogy Partnership | Consumer database cross-referencing agreements with GEDmatch and FamilyTreeDNA solve cold case backlogs. |
| Rapid DNA Cartridge Development | 90-minute analysis systems meet United Kingdom and United States booking station workflow requirements. |
| Cloud-Based Genotyping Subscription | Home Office procurement frameworks in the United Kingdom favor operational expenditure over capital outlay. |
| EU AI Act Compliance Certification | Purpose-limitation controls and human-in-the-loop protocols unlock Schengen Area border security contracts. |
Research Methodology
Multi-period observation of CODIS database expansion rates, state backlog reduction grant allocations, and NGS validation study completions anchored the trend analysis, supplemented by interviews with forensic laboratory directors, DNA technical leaders, government procurement officers, and bioinformatics specialists. Secondary validation drew from FBI budget justifications, EU AI Act implementation guidance, FDA forensic reagent oversight documents, and ISO 17025 accreditation records. Bottom-up consumption modeling triangulated against top-down government spending forecasts.
Input-output matrices mapped reagent consumption per caseload type against equipment replacement cycles and database enrollment targets across the projection horizon. Segmentation dimensions included molecular versus biometric modality, STR analysis versus NGS technology tier, forensic casework versus border security application, and centralized versus municipal procurement authority. CAGRs derived from instrument installed base turnover rates and consumable replenishment cycles, with forensic genetic genealogy adoption curves and EU AI Act compliance timelines as industry-specific forecast inputs.
The model holds under stable government forensic science funding and continued CODIS database expansion; deviation in federal grant allocations or biometric surveillance regulatory restrictions would shift equipment procurement timing and reagent consumption trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Asia-Pacific Government and Security Biometrics Market
Biometrics & Identity Management
Signature Verification Market
Biometrics & Identity Management
Fingerprint Biometrics Market
Biometrics & Identity Management
United States Biometrics Market
Biometrics & Identity Management
FIDO Authentication Market
Biometrics & Identity Management
IRIS Biometrics Market
Biometrics & Identity Management
Iris Recognition Market
Biometrics & Identity Management
Global Personal Identity Management Market
Biometrics & Identity Management
Authentication Solution Market
Biometrics & Identity Management
Global Mobile User Authentication Market
Biometrics & Identity Management
Biometric Point-Of-Sale Terminals Market
Biometrics & Identity Management
Europe Biometrics Market
Biometrics & Identity Management
Global Biometric-As-A-Service Market
Biometrics & Identity Management
Biometric Passport Market
Biometrics & Identity Management
Airport Biometrics Market
Biometrics & Identity Management
Military Biometrics Market