
 Passenger Emergency Oxygen Deployment Systems Market | 2026-2036
Passenger Emergency Oxygen Deployment Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Passenger Emergency Oxygen Deployment Systems Market Analytics
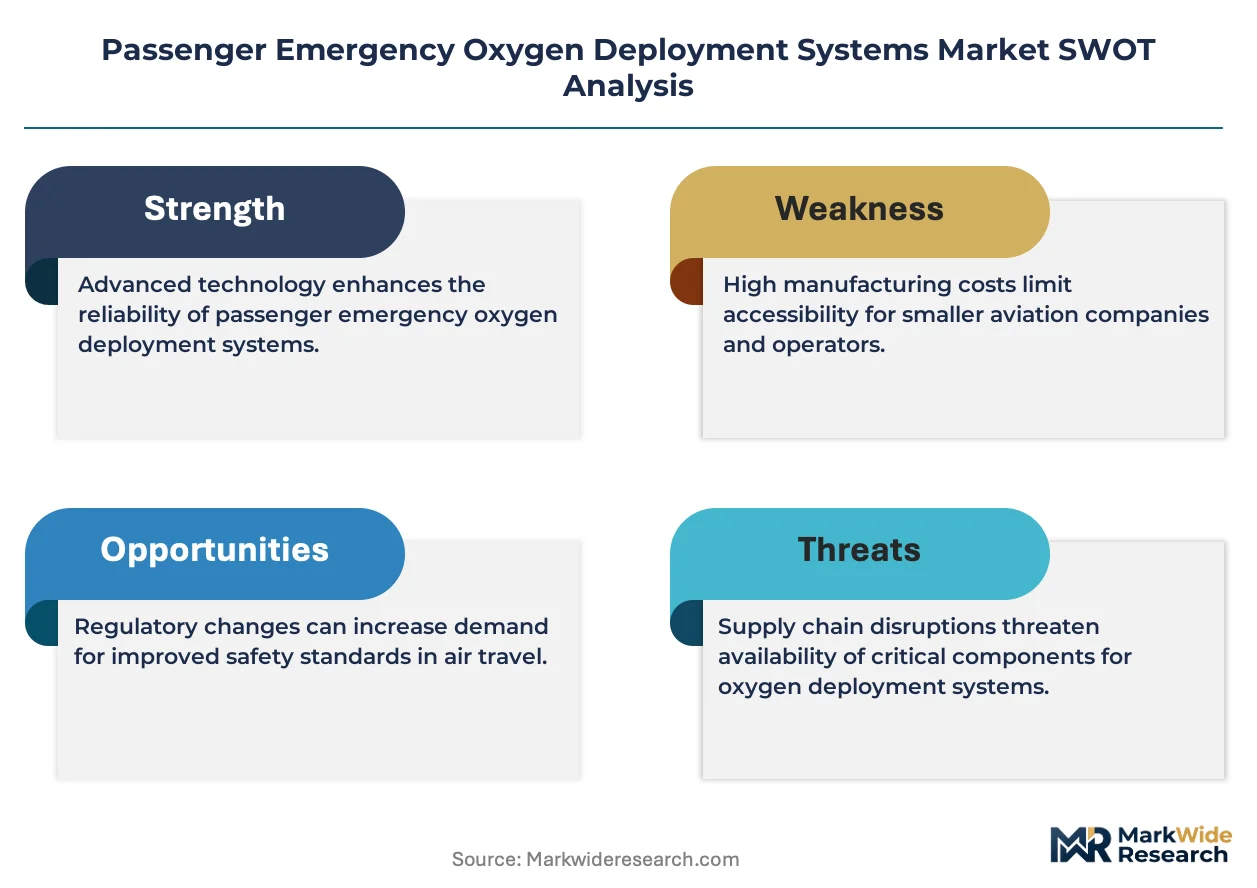
The EU Green Deal's aviation decarbonization targets are consolidating sustainability requirements across cabin safety equipment procurement. Safran leverages its integrated aerospace portfolio to dominate European airline retrofit programs. RTX Corporation anchors North American defense and commercial aviation contracts through advanced oxygen system engineering. Diehl Stiftung & Co. KG competes on precision manufacturing scale for fixed installation systems serving major European carriers.
Passenger emergency oxygen deployment systems are pressurized chemical or gaseous oxygen delivery apparatuses designed to activate automatically during cabin decompression events, typically supplying oxygen at flow rates between two and four liters per minute through masks deployed from overhead compartments. These systems serve the critical function of preventing hypoxia among occupants when aircraft altitude exceeds safe breathable atmospheric pressure. Fixed systems retain the largest installed base across commercial aviation fleets due to regulatory grandfathering and airframe integration complexity, while portable systems represent the fastest-expanding segment driven by supplemental crew requirements and flexible cabin configurations. Hybrid delivery modes command premium positioning as airlines seek redundancy between automatic activation and manual override protocols.
FAA airworthiness directives and EASA certification specifications govern oxygen system performance thresholds, testing protocols, and replacement intervals, directly determining product lifecycle revenue patterns for manufacturers. The EPA and REACH frameworks additionally constrain chemical oxygen generator compositions, pushing suppliers toward compressed gaseous alternatives with lower hazardous material profiles. Stakeholders must monitor evolving MDR and CSRD disclosure requirements as sustainability reporting extends into aerospace supply chain documentation.
Market Dynamics
Fleet modernization mandates from FAA and EASA are compressing replacement cycles for legacy chemical oxygen generators, forcing suppliers to reengineer systems around compressed gaseous architectures with lower hazardous material footprints.
Growth Catalysts
- REACH chemical restrictions:ECHA frameworks banning sodium chlorate compositions in oxygen generators are accelerating airline adoption of compressed gaseous alternatives across European-registered fleets.
- Commercial aviation retrofit waves:Narrow-body aircraft reaching mid-life maintenance intervals are triggering wholesale oxygen system replacements rather than component-level repairs.
- Hybrid activation protocols:Dual-mode delivery systems combining automatic decompression triggers with manual crew override are capturing premium positioning in new-generation airframe contracts.
Market Restraints
- Specialty alloy supply concentration:High-pressure vessel manufacturing depends on titanium and Inconel sources concentrated in a limited supplier base, creating input cost volatility.
- Airframe integration complexity:Fixed oxygen systems require structural modifications to overhead compartments and ducting that extend aircraft downtime during installation.
- Regulatory grandfathering:FAA airworthiness directives permit extended service intervals for legacy chemical generators, delaying fleet-wide upgrade decisions.
Strategic Opportunities
- CSRD supply chain disclosure:EU sustainability reporting mandates are creating first-mover advantage for manufacturers with documented carbon footprints across compressed gas distribution networks.
- Supplemental crew portable systems:Flexible cabin configurations on long-haul routes are expanding demand for mobile oxygen units beyond fixed overhead installations.
- MEA sensor convergence:Integration of oxygen flow sensors with cabin pressure monitoring systems enables predictive maintenance contracts and recurring revenue streams.
Industry Challenges
- FAA-EASA certification divergence:Differing test protocols for oxygen mask deployment timing and flow rate verification extend type certification timelines for dual-approval products.
- Legacy airframe compatibility:Retrofitting compressed gas systems into aircraft originally designed for chemical generators requires structural reinforcement and weight redistribution engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passenger Emergency Oxygen Deployment Systems Market |
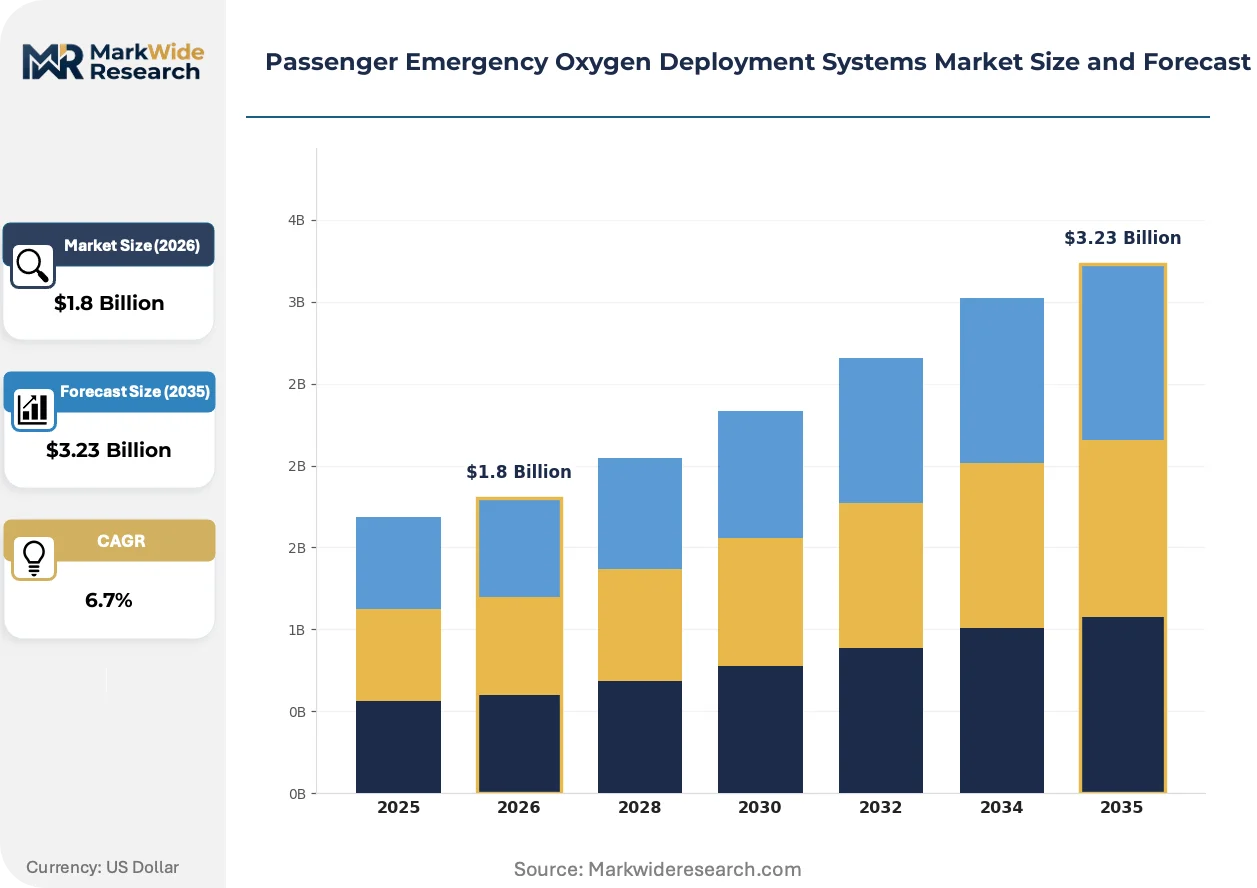
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Systems, Fixed Systems, On-Demand Systems, Manual Release Systems Application: Aerospace, Aviation Safety, Maritime, Transport Vehicles Delivery Mode: Automatic, Semi-Automatic, Manual, Hybrid End User: Airlines, Ship Operators, Transit Authorities, Emergency Services |
| Companies Covered | Safran, RTX Corporation, Diehl Stiftung & Co. KG, Meggitt Ltd, Worthington Industries, Collins Aerospace, Cobham Limited, Aerox Aviation Oxygen Systems, L’AIR LIQUIDE SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passenger Emergency Oxygen Deployment Systems Market Evolving Landscape
Digital sensor integration and sustainability mandates are reshaping how oxygen systems communicate with aircraft health monitoring networks while regulatory chemistry restrictions force material substitutions across the installed base.
Solid-state oxygen sensors are converging with centralized avionics health management platforms, enabling real-time monitoring of cylinder pressure and mask deployment status. Airlines operating long-haul fleets are adopting these integrated systems fastest, prioritizing predictive maintenance capabilities that reduce unscheduled removals. This convergence is compressing service intervals for traditional pneumatic-only monitoring architectures.
REACH Annex XVII restrictions on hazardous substance compositions are forcing reformulation of chemical oxygen generator cores across European-registered aircraft. Manufacturers must now certify alternative pyrotechnic compositions or pivot entirely to compressed gas storage systems. Narrow-body operators with dense European route networks face the most acute compliance pressure and are accelerating fleet-wide conversion programs.
Airline technical procurement teams are consolidating oxygen system contracts under airframe-level lifecycle agreements rather than component spot purchases. Full-service leasing companies and flag carriers with large owned fleets are driving this consolidation, seeking single-source accountability for installation, maintenance, and regulatory compliance. This pattern is most pronounced in North American and Middle Eastern markets where lessor influence over specifications remains strongest.
Passenger Emergency Oxygen Deployment Systems Market Segmentation
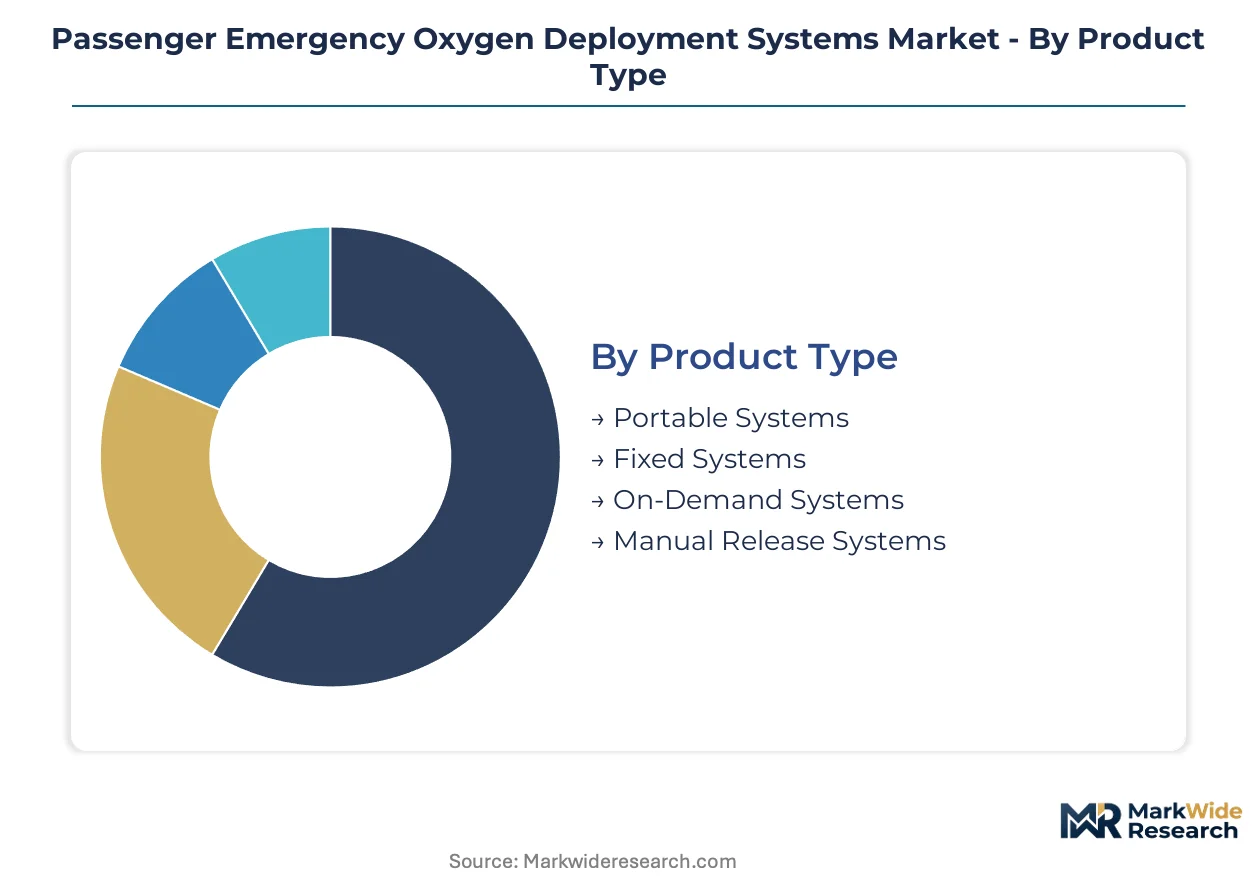
Oxygen deployment configurations diverge sharply between integrated airframe architectures and modular supplemental units. Procurement patterns track directly to regulatory mandate intensity and fleet replacement cycles across operator categories.
Product Type:
Standalone portable units serve supplemental crew requirements and flexible cabin layouts, while embedded fixed installations dominate new airframe production due to structural integration mandates.
- Fixed Systems:Permanently installed overhead compartment units with automatic activation triggers and integrated ducting. Airlines in the United States with dense narrow-body fleets drive replacement demand as FAA airworthiness directives compress service intervals for legacy chemical generators.
- Portable Systems:Mobile oxygen delivery units with independent pressure vessels and manual deployment protocols. Long-haul carriers expanding premium cabin configurations source these for flight crew mobility and supplemental passenger coverage on extended routes.
- On-Demand Systems:Flow-activated units delivering oxygen only upon mask inhalation, conserving supply during decompression events.
- Manual Release Systems:Crew-activated deployment mechanisms providing override capability when automatic sensors fail.
Fixed systems lead volumes today; portable configurations are gaining share fastest.
Application:
Certification complexity and incident frequency determine deployment density across transport modes, with pressurized cabin environments commanding the strictest equipment mandates.
- Aerospace:Commercial and military aircraft operating above 25,000 feet requiring full cabin oxygen coverage. Narrow-body retrofit programs across European-registered fleets accelerate as REACH chemical restrictions force generator replacements.
- Aviation Safety:Regulatory compliance equipment for general aviation and training aircraft with supplemental oxygen protocols.
- Maritime:Passenger vessel emergency breathing apparatus for enclosed space evacuation scenarios.
- Transport Vehicles:High-altitude rail and specialized ground transport with pressurized cabin environments.
Aerospace commands installed base dominance; aviation safety applications show steepest expansion trajectory.
Delivery Mode:
Automation level directly correlates with crew training requirements and liability exposure in emergency scenarios.
- Automatic:Pressure-sensor-triggered deployment activating within seconds of cabin decompression detection. Flag carriers with large owned fleets specify these for reduced crew workload during rapid descent procedures.
- Hybrid:Dual-protocol systems combining automatic triggers with manual crew override. Full-service leasing companies in the Middle East drive specification for these units to satisfy diverse operator requirements across their portfolios.
- Semi-Automatic:Systems requiring crew confirmation before full oxygen flow activation.
- Manual:Entirely crew-dependent deployment for specialized aircraft with limited automation infrastructure.
Automatic systems anchor current fleet specifications; hybrid modes are climbing the fastest.
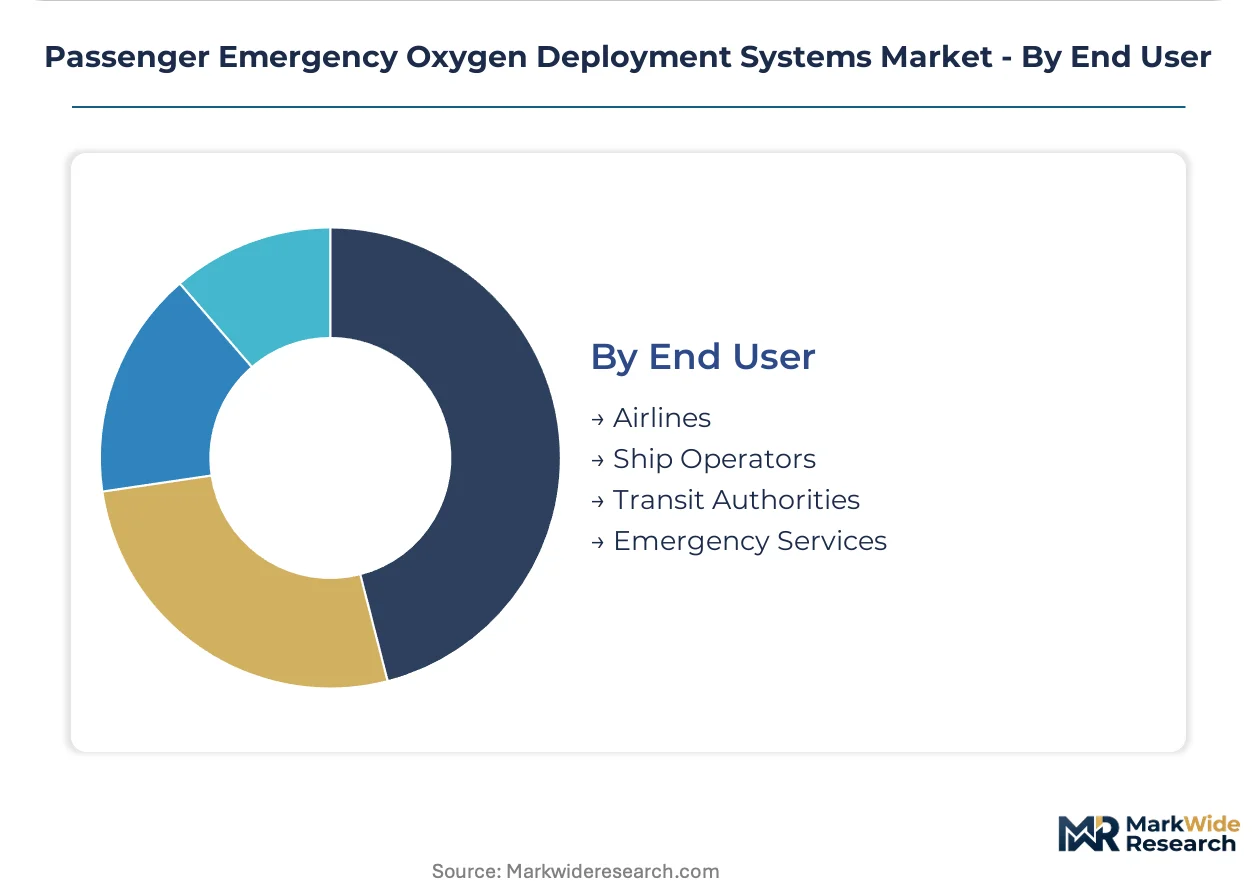
End User:
Procurement authority and lifecycle cost accountability shape contract structures across operator categories.
- Airlines:Commercial carriers with fleet-wide standardization mandates and airframe-level lifecycle agreements. Major United States network carriers consolidate oxygen system contracts under single-source accountability frameworks covering installation through regulatory compliance.
- Ship Operators:Cruise and ferry companies with SOLAS-mandated emergency breathing equipment for passenger evacuation.
- Transit Authorities:High-altitude rail operators with specialized cabin pressure management requirements.
- Emergency Services:Medical evacuation aircraft and search-and-rescue platforms with mission-critical oxygen redundancy.
Airlines dominate procurement volumes; emergency services represent the highest-margin segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The passenger emergency oxygen deployment systems industry traces its commercial scale to post-war aviation manufacturing corridors in the United States and Western Europe, where airframe integration expertise first concentrated around defense contractors transitioning to commercial platforms.
United States
FAA airworthiness directives mandating compressed gas system retrofits are driving replacement demand across narrow-body fleets operated by network carriers. The EPA's hazardous material restrictions on chemical oxygen generators are accelerating supplier pivots toward gaseous architectures. Seattle-Tacoma and Wichita manufacturing clusters anchor OEM and tier-one supplier production networks serving both commercial and defense contracts.
Germany
REACH Annex XVII chemical restrictions are forcing fleet-wide conversion programs among European-registered operators with dense route networks. EASA certification specifications for enhanced cabin safety equipment are tightening performance thresholds for oxygen mask deployment timing. Hamburg and Munich aerospace engineering centers concentrate precision manufacturing capabilities for fixed installation systems serving major flag carriers.
France
EU Green Deal aviation decarbonization targets are consolidating sustainability requirements across cabin safety equipment procurement for national carrier fleets. The country's national aerospace regulator enforces stringent documentation standards for chemical oxygen generator disposal and replacement intervals. Toulouse and Paris-Saclay industrial corridors host integrated aerospace portfolios dominating European airline retrofit programs.
United Kingdom
Post-Brexit divergence from EASA certification protocols is creating dual-approval complexity for suppliers serving both UK-registered and EU-registered aircraft. The Civil Aviation Authority maintains parallel airworthiness directive frameworks governing oxygen system service intervals. Southwest England aerospace clusters around Bristol and Gloucestershire retain specialized engineering capabilities for military and legacy commercial platforms.
Japan
METI industrial policy supporting domestic aerospace supply chain resilience is expanding local production capacity for compressed gas oxygen systems. The country's national aviation regulator mandates enhanced documentation for foreign-manufactured safety equipment imports. Nagoya and Kobe manufacturing centers concentrate airframe integration expertise serving regional jet programs and defense platforms.
Passenger Emergency Oxygen Deployment Systems Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and airframe integration depth. The vendor base organizes into three tiers: integrated aerospace conglomerates with full airframe lifecycle contracts, specialized cabin safety equipment manufacturers with regulatory expertise, and regional fabricators serving aftermarket replacement demand. Consolidation pressures favor players with dual FAA-EASA approval capabilities and documented sustainability credentials under CSRD frameworks. Dominant competitive moves include strategic partnerships with full-service leasing companies and backward integration into high-pressure vessel manufacturing.
Among integrated aerospace conglomerates, Safran and RTX Corporation exemplify the premium-tier archetype through their positioning across European and North American regulatory jurisdictions respectively. Diehl Stiftung & Co. KG occupies a position within the specialized manufacturing tier, representing precision engineering capabilities for fixed installation systems. These three entities anchor the competitive structure by demonstrating how regulatory compliance depth and manufacturing scale combine to secure airframe-level lifecycle agreements.
| Leading Market Players |
|---|
| Safran |
| RTX Corporation |
| Diehl Stiftung & Co. KG |
| Meggitt Ltd |
| Worthington Industries |
| Collins Aerospace |
| Cobham Limited |
| Aerox Aviation Oxygen Systems |
| L'AIR LIQUIDE SA |
| Others |
Value Network & Pricing Analysis
Titanium and Inconel alloy costs cascade through high-pressure vessel fabrication into three-tier pricing stratification across premium FAA-EASA dual-certified systems, standard single-jurisdiction units, and economy-grade aftermarket replacements. Chemical oxygen generator feedstock volatility under REACH Annex XVII restrictions compresses margins on legacy product lines while compressed gas architectures command premium positioning.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between major airlines and tier-one suppliers, with price differentiation anchored in certification grade and volume scale. Dual FAA-EASA approval commands substantial premiums over single-jurisdiction products, while aftermarket spot purchases for narrow-body retrofits face acute price sensitivity from regional carriers. Pricing pressure stems from REACH-mandated material substitutions forcing reformulation investments, with flag carriers least sensitive due to lifecycle cost accountability and budget operators most exposed.
Supply Chain Analysis
Freight costs for high-pressure oxygen cylinders constrain sourcing radii, with manufacturing gravity drawing from United States, Germany, and Japan where precision machining capabilities concentrate. Titanium sponge and Inconel bar stock feed from limited specialty alloy producers, creating single-source vulnerability for vessel fabrication. Distribution runs through airframe OEM tier-one supplier networks with direct airline contracts for retrofit programs, while regulatory documentation requirements extend lead times for cross-border equipment transfers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory obligation into durable demand, with FAA airworthiness directives and EASA certification specifications forcing systematic replacement cycles regardless of economic conditions.
For Market Incumbents: Extend airframe-level lifecycle agreements to capture full retrofit program value, locking out competitors through single-source accountability frameworks. Deepen backward integration into high-pressure vessel manufacturing to offset titanium and Inconel cost volatility. Invest in dual-jurisdiction certification capabilities before FAA-EASA test protocol divergence widens compliance gaps. For New Entrants and Emerging Players: Regional carriers with narrow-body European route networks face acute REACH compliance pressure without incumbent relationship entrenchment, presenting accessible entry points. Target portable supplemental crew systems where flexible cabin configurations create specification fluidity outside fixed installation incumbency. Pursue partnerships with full-service leasing companies seeking documented CSRD sustainability credentials for portfolio standardization. For Investors and Strategic Acquirers: Consolidation pressure builds where dual-approval capabilities and CSRD-compliant carbon footprint documentation concentrate among mid-scale precision manufacturers. Five-to-ten year viability favors targets with established EASA certification pipelines and compressed gas system engineering depth. Watch for inflection when FAA mandates compressed gas retrofits for legacy narrow-body fleets currently grandfathered under extended chemical generator service intervals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Pressure Vessel Manufacturing | Captive supply of titanium and Inconel components insulates margin from specialty alloy price volatility. |
| Dual FAA-EASA Certification Investment | Dual-approval capabilities unlock premium positioning across North American and European airline procurement. |
| CSRD Supply Chain Documentation Program | Documented carbon footprints create first-mover advantage with EU flag carriers under sustainability mandates. |
| MEA Sensor Convergence Development | Integrated oxygen flow monitoring enables predictive maintenance contracts and recurring revenue streams. |
| Long-term Lifecycle Agreement with Full-Service Lessors | Single-source accountability frameworks capture fleet-wide standardization decisions across leased aircraft portfolios. |
Research Methodology
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with aircraft OEM procurement directors, airline technical fleet managers, tier-one supplier engineering leads, and EASA certification specialists anchored demand-side intelligence. Secondary sources included FAA airworthiness directive filings, EASA certification specifications, EPA hazardous material restrictions, REACH Annex XVII chemical registers, and SEC filings from publicly traded aerospace conglomerates. Bottom-up unit economics triangulated against top-down fleet replacement projections.
Granularity-level modeling distinguished fixed versus portable system configurations, automatic versus hybrid versus manual delivery modes, and commercial airline versus military versus general aviation end-use segments across the projection horizon. CAGRs derived from fleet age distribution analysis, regulatory mandate timelines, and retrofit program announcements. Industry-specific inputs incorporated narrow-body aircraft mid-life maintenance intervals, chemical oxygen generator replacement cycles, and compressed gas system airframe integration complexity.
Underlying measurement precision varies by segment; aerospace applications with documented fleet registries carry tighter precision than emerging aviation safety segments with fragmented operator bases. Forecasts reflect assumptions around regulatory enforcement consistency, fleet modernization budget availability, and specialty alloy supply stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Head Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Seat Belt System Market
Safety Equipment and Personal Protective Equipment (PPE)
Ship Life-Saving Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
South America Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Cylinders Market
Safety Equipment and Personal Protective Equipment (PPE)
Driving Protection Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Power Air Purifying Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Flammable Storage Cabinets Market
Safety Equipment and Personal Protective Equipment (PPE)
Functional Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Smart PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Motion Control Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Safety Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Locker Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Detection Equipment Market