
 Authentication Solution Market | 2026-2036
Authentication Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Authentication Solution Market Outlook
Subscription-based financing and managed-security service leasing is rewriting capital allocation for mid-market buyers, lowering barriers to enterprise-grade identity platforms. Okta leverages cloud-native architecture to sustain recurring revenue from distributed workforces. Yubico anchors hardware token supply chains for regulated industries requiring offline cryptographic verification. HID Global dominates physical-digital convergence through controlled access to smart card and mobile credential ecosystems.
Authentication solutions encompass technologies, protocols, and infrastructure that verify user or device identity through credential validation, cryptographic challenge-response, or biometric pattern matching against enrolled templates, typically operating with false acceptance rates below 0.001% in high-assurance configurations. These systems enforce access boundaries across enterprise networks, consumer applications, and critical infrastructure by binding digital identity claims to possession, knowledge, or inherence factors. Multi-factor authentication retains the largest installed base among technology segments, though passwordless architectures are capturing disproportionate investment as organizations eliminate credential-based attack surfaces. Cloud-based deployment models are expanding fastest among delivery modes, while hybrid configurations retain margin concentration due to integration complexity and ongoing on-premises legacy system dependencies.
The National Institute of Standards and Technology zero-trust framework, alongside state-level biometric privacy statutes such as Illinois BIPA and California CPRA, compels vendors to engineer granular consent mechanisms and continuous verification architectures. The Federal Trade Commission actively pursues enforcement against authentication failures in consumer-facing platforms, elevating liability exposure for inadequate identity safeguards. Stakeholders must weigh interoperability commitments against emerging quantum-resistant cryptographic standards when architecting multi-year platform roadmaps.
Market Dynamics
Zero-trust security mandates from the US federal government are compressing procurement cycles and forcing architectural overhauls across enterprise identity stacks, privileging continuous verification over perimeter-based models.
Growth Catalysts
- EU AI Act compliance deadlines:European enterprises face binding requirements for high-risk AI system transparency, driving demand for auditable biometric verification platforms with built-in consent management.
- Financial services digital transaction volumes:Banking and payment processors deploy passwordless FIDO2 architectures to eliminate credential phishing exposure across mobile and web channels.
- Hardware security module integration:Critical infrastructure operators in energy and healthcare sectors mandate offline cryptographic key storage for air-gapped authentication workflows.
Market Restraints
- Semiconductor supply concentration:Secure element fabrication for hardware tokens concentrates among Taiwan-based foundries, exposing lead time volatility to geopolitical disruption.
- Biometric template storage costs:Enterprise-grade liveness detection and encrypted vault infrastructure impose per-user operational expenditures that strain mid-market IT budgets.
- Fragmented state privacy statutes:Illinois BIPA and California CPRA impose conflicting consent and retention requirements, complicating multi-jurisdictional deployment architectures.
Strategic Opportunities
- India digital public infrastructure:The country's Aadhaar-linked authentication stack creates openings for vendors integrating with the UIDAI ecosystem for financial inclusion services.
- Post-quantum cryptographic migration:NIST's standardization of lattice-based algorithms enables first-mover positioning for vendors offering crypto-agile certificate management.
- Managed security service bundling:Channel partners in Germany and France are packaging identity verification with SOC operations, lowering customer acquisition costs for platform vendors.
Industry Challenges
- Legacy directory service entanglement:Active Directory and LDAP dependencies in established enterprises extend migration timelines for cloud-native authentication architectures.
- Biometric algorithm bias remediation:Demographic performance disparities in facial recognition systems require ongoing model retraining and third-party audit investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Authentication Solution Market |
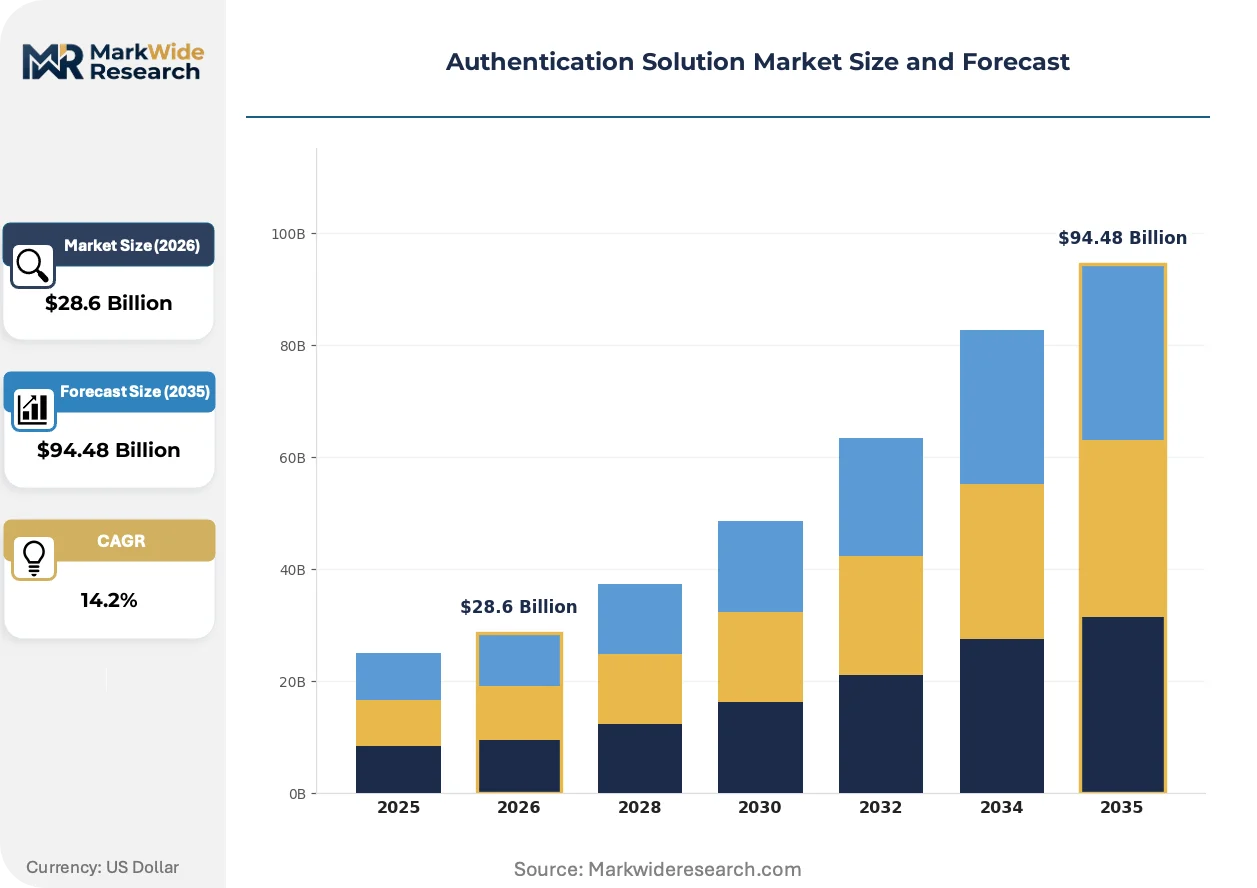
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Biometrics, Multi-Factor Authentication, Passwordless, Public Key Infrastructure Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Financial Services, Government, Healthcare, Retail Application: Identity Verification, Access Control, Fraud Prevention, Secure Transactions |
| Companies Covered | OneSpan, Yubico, Okta, Ping Identity, Duo Security, Auth0, HID Global, ManageEngine ADSelfService Plus, Microsoft Entra ID, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Authentication Solution Market Strategic Shifts
Authentication architectures are pivoting from credential vaulting to continuous risk-based evaluation, embedding identity verification into every transaction rather than gating it at session initiation.
Passkey implementations built on FIDO2 standards are rendering obsolete SMS-based one-time passwords and knowledge-based authentication in consumer-facing applications. Financial institutions and e-commerce platforms are deploying platform authenticators at scale, eliminating password reset support costs while compressing login abandonment rates. The structural consequence is collapsing revenue for legacy multi-factor authentication SMS gateway providers.
The EU AI Act's risk classification framework for biometric identification systems imposes conformity assessment obligations on vendors deploying remote authentication in public and semi-public spaces. Industrial consequence includes mandatory human oversight provisions and algorithmic impact documentation, elevating compliance engineering headcount. Healthcare and border control deployments in France, Germany, and the Netherlands are restructuring procurement specifications to incorporate these audit trail requirements.
Enterprise buyers are consolidating vendor relationships through platform consolidation, displacing point solutions for identity proofing, device trust, and privileged access management. Managed security service providers in the United States are capturing this consolidation by offering unified identity fabrics with guaranteed uptime SLAs. This pattern is most pronounced among Fortune 500 manufacturers with distributed operational technology environments requiring converged IT/OT identity governance.
Authentication Solution Market Segmentation
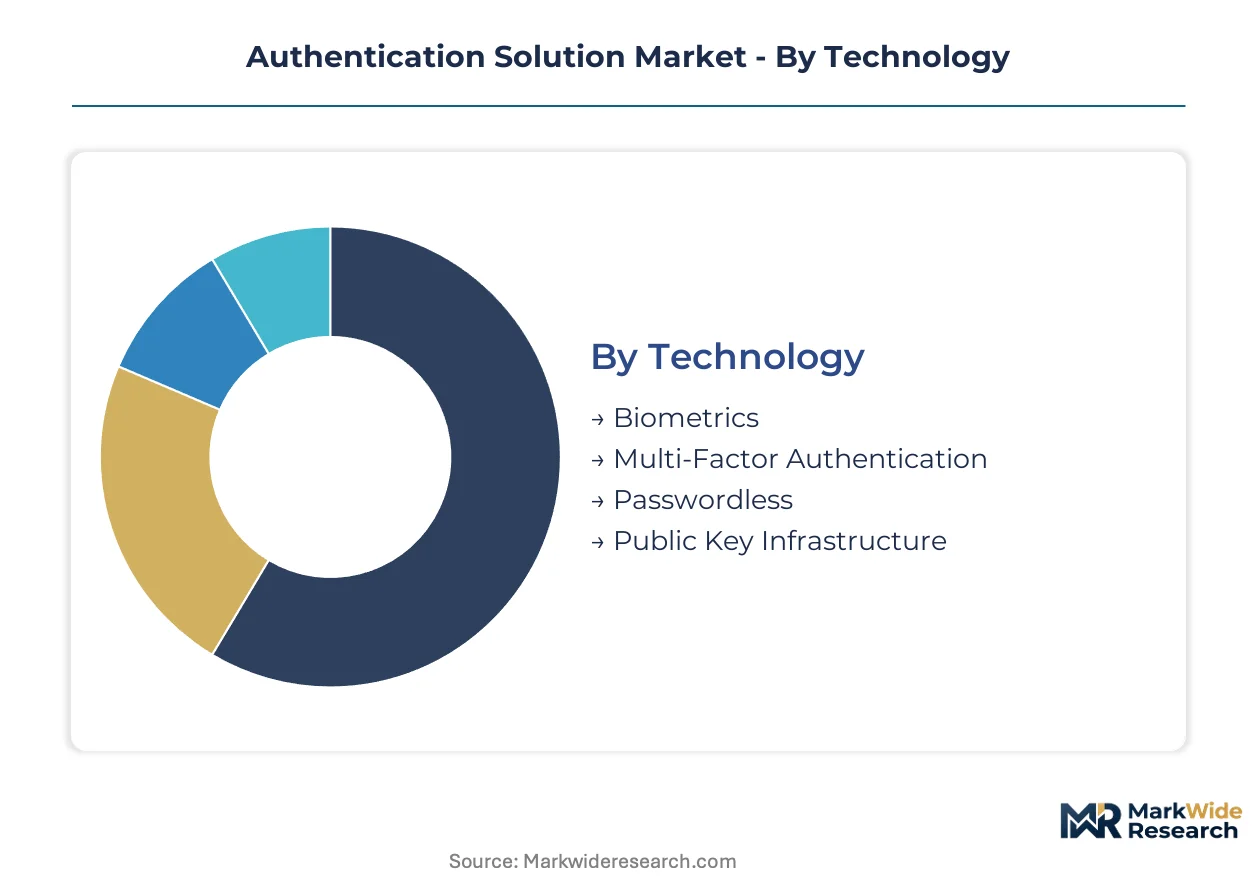
Authentication solution procurement varies sharply by deployment complexity and ongoing operational intensity. Service dependencies, integration labor, and compliance audit requirements create divergent margin profiles across technology and delivery models.
Technology:
Post-deployment service intensity escalates with biometric template management and cryptographic lifecycle complexity, favoring vendors with embedded managed service capabilities.
- Biometrics:Fingerprint, facial, iris, and behavioral pattern recognition systems require continuous liveness detection updates and demographic bias remediation. Financial institutions in the United States and EU member states drive procurement under BIPA and GDPR consent mandates, though template storage vaults impose recurring per-user infrastructure costs.
- Multi-Factor Authentication:Combines possession, knowledge, and inherence factors through SMS, hardware tokens, or push notifications. Retains the largest installed base among enterprise identity stacks, with government agencies prioritizing FIPS 140-2 validated hardware token integration for high-assurance environments.
- Passwordless:FIDO2 and WebAuthn standards eliminate credential phishing surfaces through cryptographic key pairs bound to devices. Demand concentrates among e-commerce platforms seeking login abandonment reduction.
- Public Key Infrastructure:Certificate authorities and key management infrastructure for digital identity binding. Critical infrastructure operators mandate HSM-backed issuance for air-gapped authentication workflows.
By volume, Multi-Factor Authentication leads. By growth pace, Passwordless architectures are expanding most quickly.
Deployment:
Capital allocation patterns split between subscription elasticity and legacy system entanglement, with hybrid configurations commanding integration premiums.
- Cloud-Based:SaaS identity platforms with API-native provisioning and elastic scale. Distributed workforces in technology and professional services sectors favor this model for rapid deployment without data center overhead.
- Hybrid:Split architectures maintaining sensitive credential vaults on-premises while leveraging cloud policy engines. Margin concentration persists due to Active Directory synchronization complexity and ongoing legacy dependency management.
- On-Premises:Fully captive infrastructure for classified or air-gapped environments. Defense and intelligence agencies mandate this model under federal zero-trust directives with physical control requirements.
- Managed Services:Third-party operation of authentication infrastructure with guaranteed SLA uptime. Mid-market buyers in Germany and France adopt this model to access enterprise-grade identity governance without internal security engineering headcount.
Cloud-Based deployments capture the steepest expansion trajectory, while Hybrid configurations retain the highest margin concentration.
End User:
Regulatory enforcement intensity and transaction value density shape sector-specific authentication requirements and vendor selection criteria.
- Financial Services:Banking, payment processing, and insurance institutions deploy passwordless FIDO2 at scale to eliminate credential phishing across mobile and web channels. The FTC pursues active enforcement against authentication failures, elevating liability exposure.
- Government:Federal, state, and local agencies implement continuous verification architectures under NIST zero-trust framework mandates. Procurement cycles compress as legacy perimeter models face mandatory retirement.
- Healthcare:HIPAA-covered entities integrate biometric patient identification with EHR access governance. Liveness detection requirements intensify under state-level biometric privacy statutes.
- Retail:E-commerce platforms and brick-and-mortar chains deploy friction-reducing authentication to compress checkout abandonment. Passkey implementations displace SMS-based one-time passwords.
Financial Services commands the largest revenue share, while Government verticals are gaining share fastest under compliance-driven procurement acceleration.
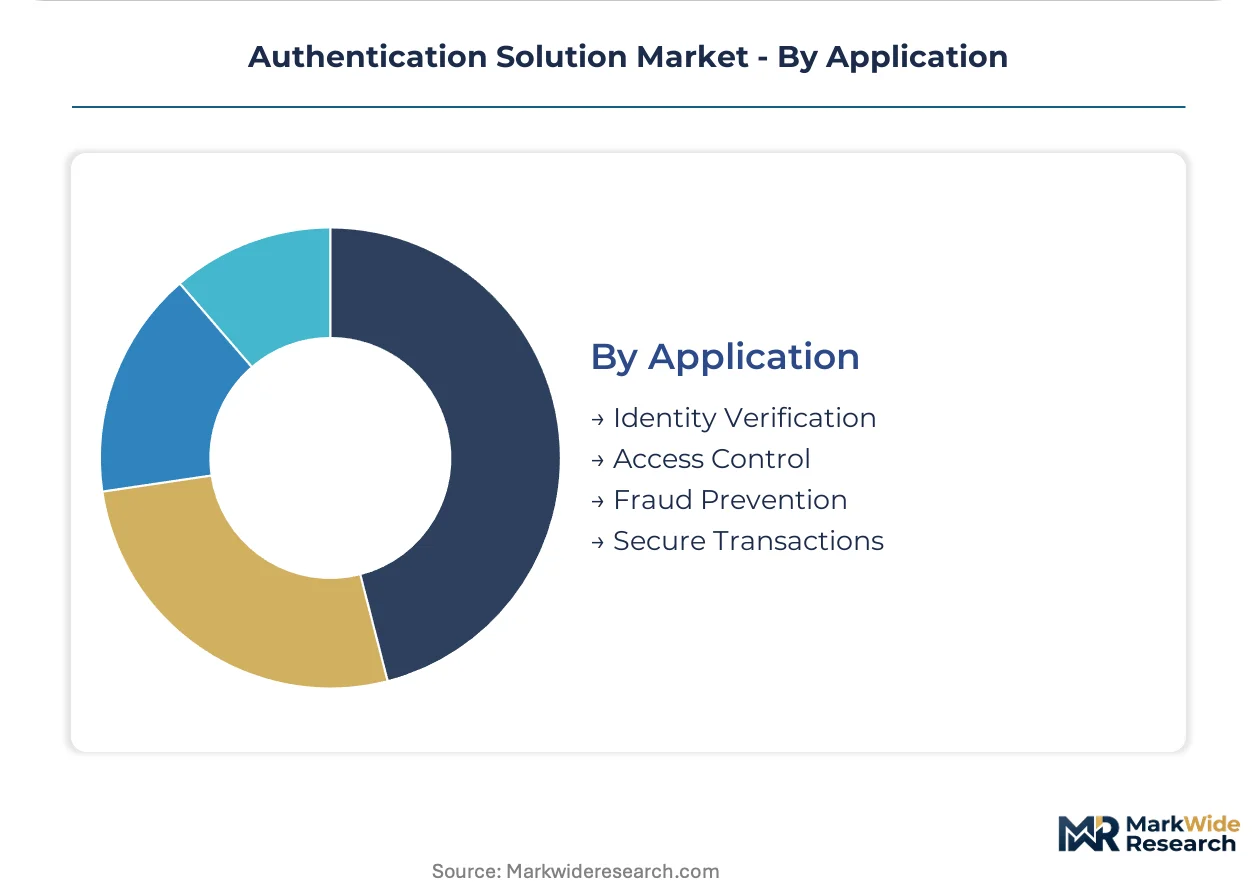
Application:
Use case differentiation centers on real-time decision velocity, with fraud prevention demanding sub-100 millisecond response latencies.
- Identity Verification:Document validation, biometric matching, and proofing against authoritative databases. EU AI Act conformity assessments impose mandatory human oversight for high-risk biometric deployments in France, Germany, and the Netherlands.
- Fraud Prevention:Behavioral analytics and risk scoring to intercept synthetic identity and account takeover attacks. Payment processors prioritize this capability for real-time transaction authorization.
- Access Control:Session gating and privilege elevation for enterprise resources. Converges with physical security through smart card and mobile credential ecosystems.
- Secure Transactions:Cryptographic signing and non-repudiation for high-value transfers. Critical infrastructure operators mandate hardware security module integration for energy and healthcare sector workflows.
Access Control retains the broadest installed base, while Identity Verification climbs the fastest under regulatory audit trail mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement of authentication solutions concentrates among financial institutions in the United States, regulated entities across the European Union, and government-led digital identity programs in India.
United States
Federal zero-trust architecture directives and FTC enforcement actions are compressing procurement cycles across government agencies and consumer-facing platforms. NIST framework mandates require continuous verification architectures with physical control provisions for classified environments. Defense contractors in the Washington DC corridor and financial services clusters in New York and San Francisco are deploying FIDO2 passwordless systems at scale.
Germany
Industrial manufacturers and automotive suppliers are bundling identity verification with managed SOC operations through channel partners. GDPR and the EU AI Act impose conformity assessment obligations for biometric deployments in manufacturing and logistics settings. Munich and Stuttgart-based industrial conglomerates are restructuring procurement specifications to incorporate audit trail requirements for high-risk AI systems.
India
Financial inclusion initiatives and Aadhaar-linked authentication infrastructure are creating vendor opportunities across banking and telecommunications sectors. The UIDAI ecosystem and RBI guidelines mandate interoperable identity verification for digital payment systems. Bangalore and Hyderabad technology corridors are hosting integration specialists connecting global authentication platforms to domestic digital public infrastructure.
United Kingdom
Financial services regulators and critical infrastructure operators are mandating crypto-agile certificate management ahead of post-quantum transitions. The UK National Cyber Security Centre guidance aligns with EU AI Act risk classifications for biometric systems. London-based payment processors and Manchester healthcare networks are consolidating vendor relationships through unified identity fabric procurement.
Japan
Manufacturing supply chains and healthcare providers are deploying hardware security modules for air-gapped authentication workflows. METI industrial security guidelines and JIS standards govern cryptographic key storage for operational technology environments. Tokyo and Osaka industrial clusters are integrating physical-digital convergence systems for smart factory access control.
Authentication Solution Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure that fragments between cloud-native platforms, hardware token manufacturers, and managed service integrators. The vendor base separates into three strategic archetypes: cloud-identity platforms with recurring revenue models, hardware security specialists with regulated-industry anchoring, and converged physical-digital access providers. Dominant competitive moves include platform consolidation through unified identity fabric offerings and geographic expansion via managed security service bundling in European markets.
Within the cloud-native platform tier, Okta and Auth0 represent recurring-revenue archetypes serving distributed workforces, while Yubico occupies a position among hardware token specialists supplying offline cryptographic verification to regulated industries. Ping Identity sits within the hybrid-deployment segment addressing Active Directory synchronization complexity in established enterprises.
| Leading Market Players |
|---|
| OneSpan |
| Yubico |
| Okta |
| Ping Identity |
| Duo Security |
| Auth0 |
| HID Global |
| ManageEngine ADSelfService Plus |
| Microsoft Entra ID |
| Others |
Value Chain & Pricing Dynamics
Taipei-based secure element foundries govern upstream capacity allocation for hardware tokens, translating semiconductor wafer availability directly into tiered subscription pricing elasticity for authentication platform vendors serving regulated industries.
Pricing Analysis
Cost-plus contracts with Taiwanese foundries index hardware token production to silicon wafer spot markets, forcing authentication vendors to absorb commodity volatility or pass through via annual subscription escalators. Pricing stratifies across FIPS 140-2 validated hardware tiers, cloud-native SaaS bundles, and managed service wraps, with certification grade and after-sales biometric template management as primary differentiation drivers. Cost compression in mid-market SaaS tiers intensifies because hyperscaler infrastructure discounts compress hosting margins. Government buyers exhibit lowest price sensitivity due to zero-trust mandate compliance deadlines, while retail e-commerce platforms prioritize friction-reduction over security premium.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Taiwan Semiconductor Manufacturing anchor working capital structures for Yubico and hardware token specialists dependent on secure microcontroller fabrication. Geographic concentration centers on Taiwan, South Korea, and Japan for cryptographic chip production, with China and Vietnam hosting final assembly and packaging operations. Raw material dependencies include silicon wafers, rare-earth elements for sensor components, and specialized epoxy resins for tamper-evident housings. Single-source vulnerability around Taiwan Strait logistics chokepoints elevates contingency planning for air-gapped authentication deployments. Distribution runs through direct enterprise sales teams for government contracts and managed security service providers for mid-market European penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Authentication solutions represent a service-attach opportunity where biometric template lifecycle management and continuous liveness detection updates expand recurring revenue faster than hardware token shipments.
For Market Incumbents: Insulate platform margins by deepening backward integration into secure element supply chains through exclusive foundry partnerships in Taiwan, while accelerating FIDO2 passkey certification investments to preempt SMS-based MFA displacement. Cloud-native competitors with superior API elasticity threaten established hybrid-deployment vendors locked in Active Directory synchronization complexity. For New Entrants and Emerging Players: Mid-market healthcare networks in the United Kingdom and Germany represent the most penetrable entry point, given GDPR and EU AI Act compliance gaps in existing biometric consent architectures. India's Aadhaar-linked financial inclusion stack offers a second white-space target for vendors integrating with UIDAI authentication APIs. A channel-first go-to-market through German managed security service providers reduces customer acquisition costs and accelerates SOC-2 bundled deployment. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core physical access control divisions amid IT/OT convergence pressure. Long-term viability favors vendors with crypto-agile certificate management capabilities positioned for post-quantum migration. The signal to watch is NIST lattice-based algorithm standardization velocity, which would trigger accelerated procurement for quantum-resistant authentication stacks.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies identity proofing, device trust, and privileged access management under single SLA guarantees for Fortune 500 manufacturers. |
| Geographic Expansion | Targets India's Aadhaar ecosystem through Bangalore and Hyderabad integration specialists connecting global platforms to UIDAI infrastructure. |
| Strategic Partnership | Bundles biometric verification with German and French managed SOC operations to lower mid-market customer acquisition costs. |
| Acquisition of Specialist Firm | Captures post-quantum cryptographic expertise ahead of NIST lattice-based algorithm standardization and federal migration mandates. |
| Product Launch | Deploys FIDO2 passkey implementations displacing SMS-based one-time passwords across e-commerce checkout flows. |
Study Parameters
A standing panel of CISOs, identity platform engineers, federal procurement officers, and biometric algorithm researchers provided ongoing calibration across primary interview cycles, with secondary validation drawing from NIST framework publications, SEC 10-K filings of publicly traded identity vendors, EU AI Act conformity assessment databases, and UIDAI technical specifications. Bottom-up segmentation modeling triangulated against top-down macroeconomic sizing across technology, deployment, and end-user dimensions.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning biometric modality type, cloud-hybrid-on-premises deployment architecture, and regulatory compliance intensity by vertical. CAGRs derived from installed base migration curves, replacement cycle compression under zero-trust mandates, and pricing elasticity functions for subscription versus perpetual license models. Forecast inputs incorporated federal procurement pipeline disclosures, EU AI Act implementation timelines, and Aadhaar authentication transaction growth trajectories.
Macroeconomic conditions sit as an overlay; deviation in enterprise IT spending cycles, semiconductor supply availability, or cross-border data localization enforcement would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory compliance deadlines and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
IRIS Biometrics Market
Biometrics & Identity Management
Global Personal Identity Management Market
Biometrics & Identity Management
Middle East and Africa Biometrics in Government Market
Biometrics & Identity Management
Vein Recognition Biometrics Market
Biometrics & Identity Management
Hand Geometry Biometrics Market
Biometrics & Identity Management
Consumer Biometrics Market
Biometrics & Identity Management
Biometric Scan Software Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Market
Biometrics & Identity Management
Italy Mobile Biometrics Market
Biometrics & Identity Management
Flash Calling Authentication Market
Biometrics & Identity Management
Biometric Services Platform (Biosp) Market
Biometrics & Identity Management
Europe Decentralized Identity Market
Biometrics & Identity Management
Global Authentication Services Market
Biometrics & Identity Management
Europe Biometrics in Government Market
Biometrics & Identity Management
Global Multifactor Authentication Market
Biometrics & Identity Management
Password Management Market