
 AI-Enabled Biometrics Market | 2026-2036
AI-Enabled Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
AI-Enabled Biometrics Market Analysis
A capital-intensity divergence between cloud-native startups and established hardware vendors is reorganizing competitive dynamics in AI-enabled biometrics. IrisGuard leverages its specialized iris-capture hardware to anchor defense and humanitarian deployments across challenging environments. Facia differentiates through software-only facial recognition that eliminates proprietary sensor dependencies, while Crayonic competes on cryptographic binding of biometric templates to secure elements.
AI-enabled biometrics encompasses identity verification systems that apply neural network architectures to physiological or behavioral characteristics, typically processing templates through convolutional or transformer-based models with liveness detection thresholds below one percent false acceptance rates. The primary commercial purpose centers on replacing credential-based access with continuous, non-replicable identity assurance across physical and digital boundaries. Facial recognition dominates transaction authentication deployments due to minimal user friction, while iris recognition occupies the highest-assurance tier in government identity programs where template stability across decades matters. Cloud-based deployment is accelerating fastest among retail and BFSI end users seeking elastic capacity during peak verification volumes.
The EU AI Act classifies remote biometric identification as high-risk, mandating conformity assessments and human oversight that reshape product development cycles for vendors seeking European market access. In the United States, NIST testing protocols and state-level biometric privacy laws in Illinois, Texas, and Washington create a fragmented compliance landscape that favors vendors with dedicated regulatory engineering functions. Stakeholders must monitor the divergence between permissive federal procurement standards and restrictive state legislation when prioritizing geographic expansion and product roadmap investments.
Market Dynamics
Neural network architectures for liveness detection are compressing hardware dependencies, forcing vendors to choose between sensor-anchored hardware strategies and software-only deployment models that scale across commodity cameras.
Growth Catalysts
- EU AI Act Conformity Mandates:High-risk classification for remote biometric identification creates procurement preference for vendors with pre-certified assessment pipelines, accelerating consolidation around compliant product architectures.
- Voice Recognition in BFSI:Financial institutions deploy speaker verification for remote account recovery and transaction authorization, replacing knowledge-based authentication with behavioral biometrics.
- Federal Identity Modernization:United States agencies replace legacy fingerprint systems with multi-modal platforms, creating sustained demand for iris and facial fusion templates in civilian and defense applications.
Market Restraints
- Silicon Supply Concentration:Specialized image signal processors for biometric edge devices source from Taiwan and South Korea foundries, exposing hardware vendors to geopolitical disruption and allocation constraints.
- Template Storage Costs:Cryptographic binding of biometric data to secure elements requires dedicated hardware security modules, elevating per-unit costs for government-grade deployments.
- Illinois BIPA Liability:Private right of action for biometric privacy violations in Illinois generates litigation exposure that discourages retail deployment of facial recognition in consumer-facing applications.
Strategic Opportunities
- Humanitarian Identity Programs:UNHCR and World Food Programme deployments in refugee camps create demand for iris-capture systems that function without network connectivity or centralized databases.
- Continuous Authentication Convergence:Integration of behavioral biometrics with zero-trust security architectures enables passwordless enterprise access that adapts risk scoring in real-time.
- India Digital Public Infrastructure:Aadhaar-linked face authentication APIs open API-based revenue models for software vendors serving ration distribution, pension verification, and financial inclusion programs.
Industry Challenges
- Adversarial ML Expertise Scarcity:Deepfake detection and presentation attack resistance require rare skill sets spanning computer vision and security research, constraining product development velocity.
- NIST Evaluation Timelines:Face Recognition Vendor Test certification cycles extend 12-18 months, delaying market entry for algorithm updates and compressing competitive response windows.
- Legacy System Integration:Government identity databases built on proprietary template formats resist migration to interoperable ISO/IEC 19795 standards, fragmenting procurement across incompatible technology generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI-Enabled Biometrics Market |
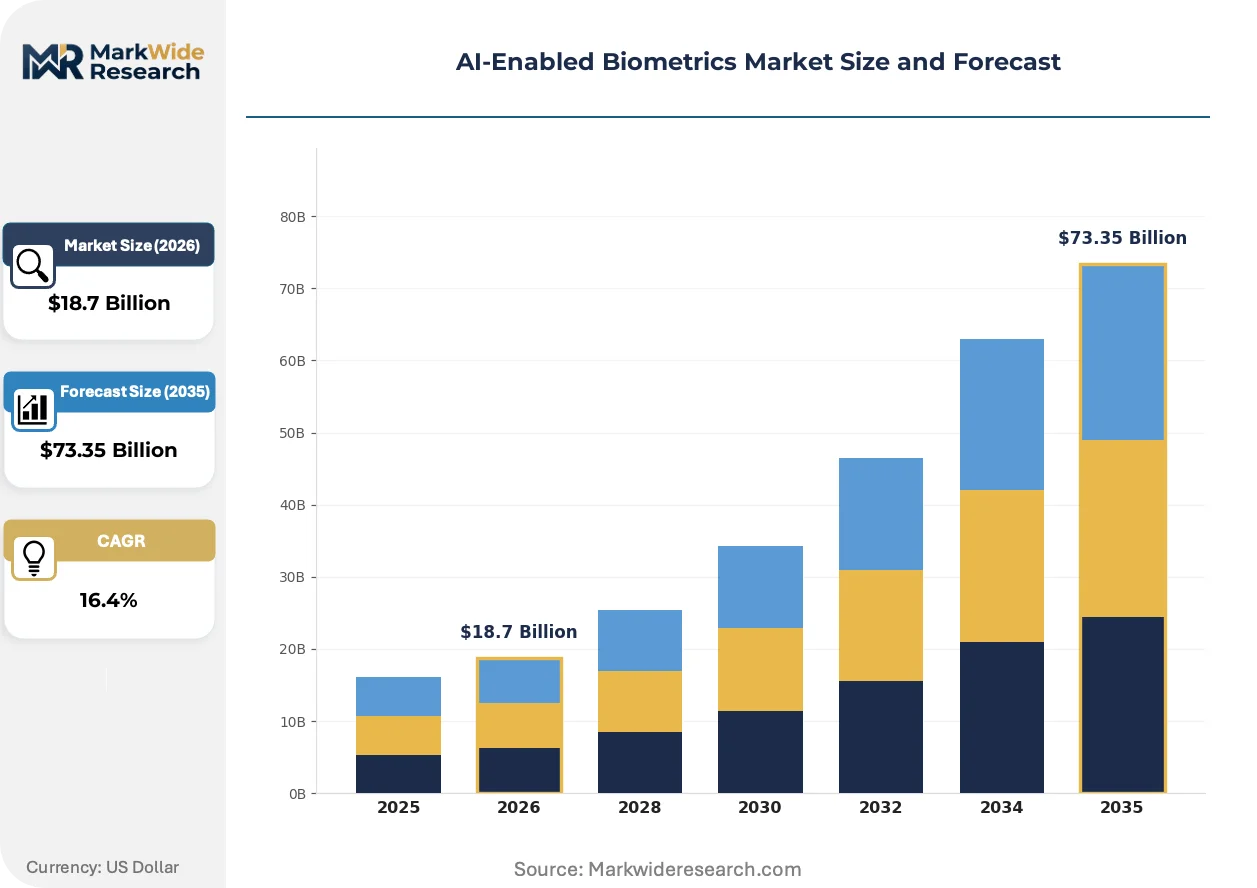
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Access Control, Identity Verification, Time Attendance, Transaction Authentication Technology: Facial Recognition, Fingerprint Recognition, Voice Recognition, Iris Recognition End User: Government, BFSI, Healthcare, Retail Deployment: Cloud-Based, On-Premises, Hybrid, Others |
| Companies Covered | IrisGuard, Badge Inc, Facia, Aerendir Mobile Inc, Lymbic AI, Camvi, Crayonic, IRISYS Co., Ltd., MultiKol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI-Enabled Biometrics Market Emerging Trajectories
Transformer-based architectures are displacing convolutional neural networks as the dominant approach for biometric feature extraction, compressing accuracy gaps between established vendors and algorithm specialists.
Edge-based liveness detection is fragmenting the market for dedicated biometric hardware. Convolutional neural networks optimized for mobile NPUs now execute depth estimation and texture analysis on commodity smartphones, eliminating reliance on structured-light or time-of-flight sensors. Retail banking applications in Brazil and Indonesia adopt these software-only pipelines to avoid hardware procurement cycles. The shift compresses margins for sensor-integrated device manufacturers while expanding addressable market for algorithm licensing.
EU AI Act Article 14 mandates human oversight for real-time remote biometric identification in publicly accessible spaces. Law enforcement procurement specifications across France, Germany, and the Netherlands now require audit trails and operator intervention protocols that reshape product roadmaps. Vendors redirect engineering resources from accuracy optimization toward explainability interfaces and decision logging systems.
Subscription-based biometric verification is displacing perpetual licensing in enterprise workforce management. Human resources platforms in the United States and United Kingdom bundle identity verification into SaaS workforce suites rather than procuring standalone biometric systems. The model shifts customer relationships from security vendors to HR software consolidators, compressing direct vendor margins while expanding volume through platform distribution.
AI-Enabled Biometrics Market Segmentation
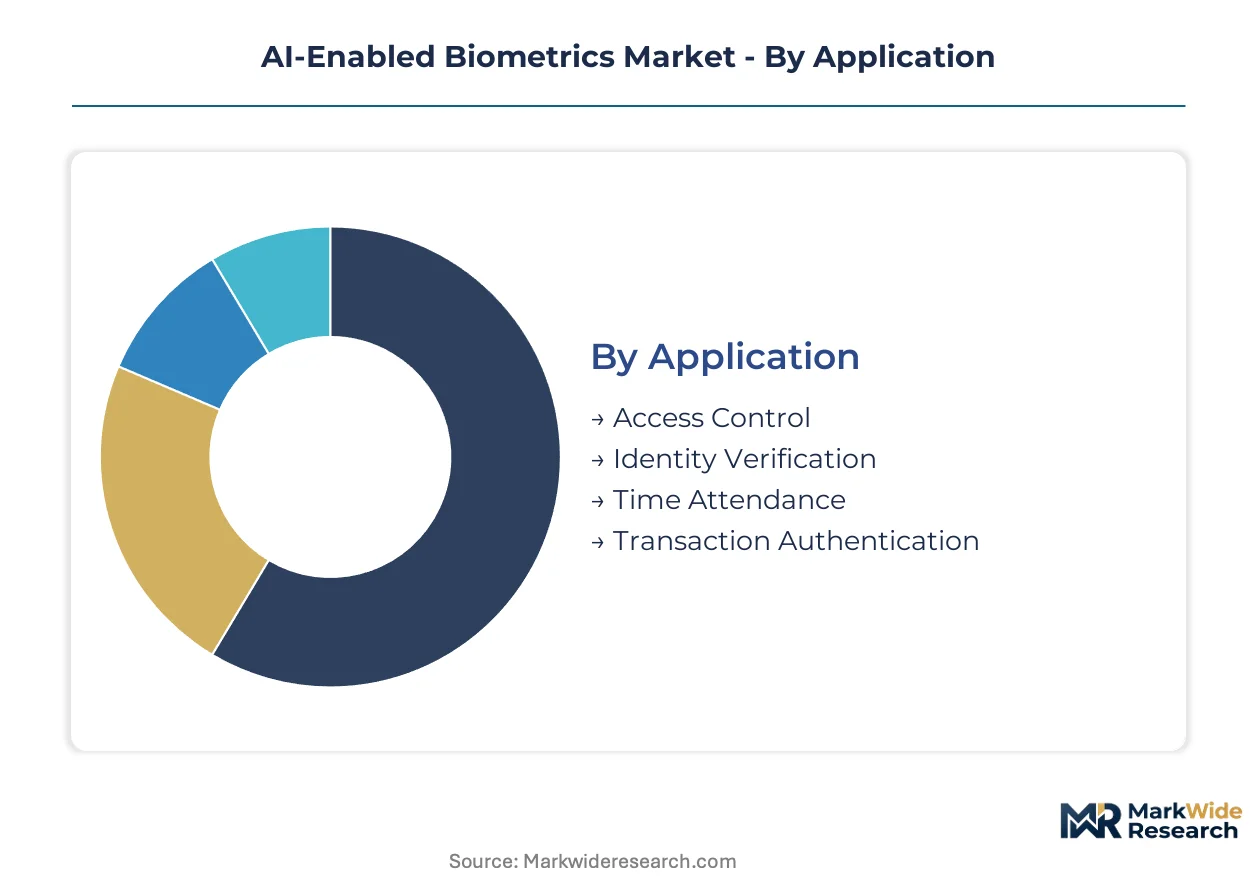
Segmentation in AI-enabled biometrics reveals divergent substitution pressures across authentication modalities. Hardware-dependent technologies face compression from software-only alternatives, while deployment models reshape vendor margin structures and customer switching costs.
Application:
Substitution pressure from passwordless authentication frameworks and behavioral analytics is reshaping demand across functional use cases, with legacy credential systems losing ground fastest in consumer-facing verification workflows.
- Identity Verification:Multi-modal template fusion combines facial, voice, and liveness signals into single assurance scores for remote onboarding. Demand concentrates in United States neobanks and European digital wallet providers facing EU AI Act conformity deadlines for high-risk biometric classification.
- Transaction Authentication:Real-time biometric confirmation replaces SMS one-time passwords for high-value transfers. Brazilian and Indonesian retail banks deploy edge-based facial liveness on commodity smartphones to bypass hardware procurement cycles.
- Access Control:Physical perimeter systems integrate iris and facial templates for multi-factor entry at critical infrastructure sites.
- Time Attendance:Workforce management platforms embed biometric verification into SaaS suites, shifting procurement from standalone systems to HR software consolidators.
Identity Verification retains volume leadership; Transaction Authentication holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium sensor-anchored modalities from software-scalable alternatives, with neural network compression eliminating hardware dependencies for mid-market deployments.
- Facial Recognition:Transformer-based architectures now extract features from standard camera feeds without structured-light or time-of-flight sensors. Cloud-based deployment accelerates among retail and BFSI end users seeking elastic capacity during peak verification volumes.
- Iris Recognition:Specialized capture hardware maintains template stability across decades for highest-assurance government identity programs. UNHCR and World Food Programme deployments in refugee camps create demand for offline-capable systems.
- Voice Recognition:Speaker verification replaces knowledge-based authentication for remote account recovery in financial institutions.
- Fingerprint Recognition:Legacy civilian and defense systems face replacement pressure from multi-modal fusion platforms in United States federal modernization programs.
Facial Recognition dominates commercial volume; Iris Recognition commands premium positioning in government-grade assurance tiers.
End User:
Customer type determines compliance burden intensity, with government and regulated financial services facing mandatory conformity assessments under risk-classification frameworks.
- Government:Civilian and defense agencies replace legacy fingerprint systems with multi-modal platforms incorporating iris and facial fusion templates. NIST Face Recognition Vendor Test certification cycles extend 12-18 months, delaying algorithm updates.
- BFSI:Financial institutions deploy speaker verification and facial liveness for remote customer authentication, navigating Illinois BIPA private right of action exposure that discourages consumer-facing retail deployment.
- Healthcare:Patient identity matching and provider access control drive demand for HIPAA-compliant biometric verification.
- Retail:Workforce management and loss prevention applications face litigation risk fragmentation across Illinois, Texas, and Washington state biometric privacy laws.
Government anchors procurement value; BFSI is expanding most quickly through voice and facial verification integration.
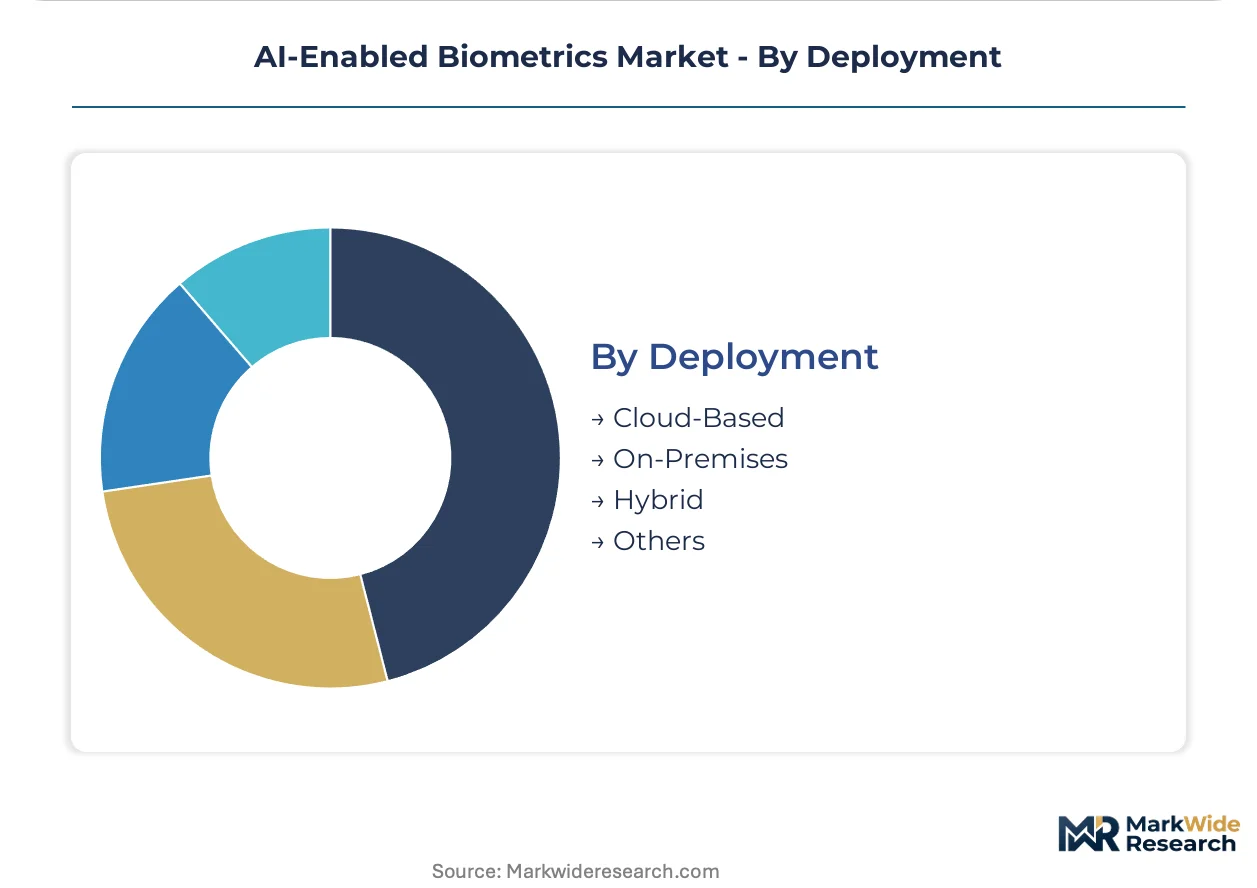
Deployment:
Supply concentration in specialized image signal processors creates vulnerability for edge device manufacturers, while cloud-native architectures bypass silicon allocation constraints.
- Cloud-Based:Elastic verification capacity serves peak transaction volumes without capital-intensive infrastructure. India Aadhaar-linked face authentication APIs enable software vendors to serve ration distribution and pension verification through API-based revenue models.
- On-Premises:Cryptographic binding of biometric templates to secure elements requires dedicated hardware security modules, elevating per-unit costs for government-grade deployments with air-gapped security requirements.
- Hybrid:Edge inference with cloud template storage balances latency and scalability for enterprise zero-trust architectures.
- Others:Embedded and air-gapped configurations serve humanitarian identity programs lacking network connectivity or centralized databases.
Cloud-Based deployment leads volume adoption; On-Premises maintains position in highest-assurance government infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive retail deployments in emerging economies contrast sharply with premium government-grade procurement in established markets, creating divergent vendor strategies across geographies.
United States
Federal agencies drive multi-modal platform adoption for civilian and defense identity modernization. NIST Face Recognition Vendor Test certification requirements extend procurement cycles to 12-18 months. Illinois BIPA litigation exposure constrains consumer-facing facial recognition deployment in Chicago and other major metros.
India
Aadhaar-linked face authentication APIs enable software vendors to serve ration distribution and pension verification at massive scale. RBI guidelines shape financial inclusion biometric standards. Karnataka's Bangalore cluster hosts cloud-native verification platforms targeting API-based revenue models.
Germany
EU AI Act Article 14 mandates reshape law enforcement procurement specifications for real-time biometric identification. BSI conformity assessment frameworks filter vendor market access. Berlin-Brandenburg cybersecurity clusters develop explainability interfaces for high-risk classification compliance.
Brazil
Retail banks deploy edge-based facial liveness on commodity smartphones to bypass hardware procurement cycles. Central bank regulations accelerate behavioral biometric adoption for transaction authentication. São Paulo's fintech corridor concentrates software-only verification platform development.
United Arab Emirates
Smart city and border control investments sustain premium iris and facial fusion template demand. UAE national identity authority specifications influence Gulf Cooperation Council procurement standards. Dubai's AI and blockchain clusters integrate biometric verification into digital government service architectures.
AI-Enabled Biometrics Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, fragmenting competitive dynamics across hardware-anchored and software-scalable deployment models. Sensor-integrated specialists compete on template stability and liveness assurance, while algorithm vendors compress margins through neural network optimization for commodity cameras. Three archetypes dominate: specialized hardware manufacturers, software-only platform providers, and cryptographic security integrators. Consolidation pressure intensifies through strategic partnerships bridging hardware and cloud-native capabilities, alongside geographic licensing arrangements navigating regulatory fragmentation.
Within the specialized hardware tier, IrisGuard and IRISYS Co., Ltd. exemplify sensor-anchored strategies targeting highest-assurance government and humanitarian deployments. Facia occupies a position among software-only facial recognition providers eliminating proprietary dependencies, while Crayonic represents cryptographic binding specialists addressing secure element integration requirements. These three anchors illustrate the market's tripartite segmentation: hardware-captured biometric stability, algorithm-scalable verification pipelines, and template protection architectures.
| Leading Market Players |
|---|
| IrisGuard |
| Badge Inc |
| Facia |
| Aerendir Mobile Inc |
| Lymbic AI |
| Camvi |
| Crayonic |
| IRISYS Co., Ltd. |
| MultiKol |
| Others |
Supply Flow & Price Mechanics
Twelve-to-eighteen-month NIST certification cycles compress vendor pricing power by delaying algorithm updates and extending competitive response windows. Hardware security module dependencies for cryptographic template binding elevate per-unit costs in government-grade deployments, while software-only pipelines on commodity smartphones erode sensor-integrated margins.
Pricing Analysis
After-sales revenue from subscription-based verification APIs and extended SaaS contracts drives lifetime value beyond perpetual licensing. Three-tier pricing structure across premium certification-grade, standard enterprise, and economy API-volume levels separates vendors by NIST FRVT compliance status and deployment complexity. Cost compression in standard-tier facial recognition intensifies as transformer architectures eliminate proprietary sensor dependencies. Retail banking segments in emerging markets exhibit highest price sensitivity, while defense and humanitarian procurement maintains lowest sensitivity due to template stability requirements.
Supply Chain Analysis
Taiwan and South Korea anchor specialized image signal processor fabrication for biometric edge devices, exposing hardware vendors to geopolitical allocation constraints. Foundry capacity for neural network accelerators draws from these concentrations, while secure element manufacturing centers on Germany and Japan. Single-source vulnerability in Taiwan semiconductor supply creates disruption exposure for iris-capture hardware specialists. Distribution runs through direct government procurement channels and cloud API marketplaces serving enterprise SaaS integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in AI-enabled biometrics rests on EU AI Act conformity deadlines accelerating procurement preference for pre-certified assessment pipelines. Federal identity modernization programs sustain multi-modal platform demand across civilian and defense applications.
For Market Incumbents: Secure NIST FRVT pre-certification pipelines to compress competitive response windows against algorithm specialists. Anchor sensor-integrated hardware positions in defense and humanitarian deployments where template stability commands premium positioning. Vertical integration into secure element manufacturing mitigates hardware security module cost escalation in government-grade procurement.
For New Entrants and Emerging Players: EU AI Act conformity fast-tracks create procurement preference windows for vendors with pre-certified assessment pipelines. White-space concentrates in India Aadhaar-linked API distribution and Brazilian retail banking edge-deployment on commodity smartphones. Channel partnerships with HR software consolidators bypass direct enterprise sales friction in workforce management verification.
For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate biometric divisions lacking dedicated regulatory engineering functions. Five-to-ten-year viability favors software-only platform providers with transformer-based architectures and cloud-native deployment elasticity. Monitor NIST FRVT certification cycle compression as inflection indicator for algorithm update velocity and competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| NIST FRVT Pre-Certification Investment | Accelerates market entry timelines and procurement preference under federal identity modernization programs. |
| EU AI Act Conformity Pipeline | Unlocks high-risk biometric classification market access across France, Germany, and Netherlands law enforcement procurement. |
| Cloud API Platform Integration | Captures elastic verification demand from retail and BFSI end users during peak transaction volumes. |
| Secure Element Manufacturing Partnership | Reduces per-unit costs for cryptographic template binding in government-grade deployments. |
| Humanitarian Identity Program Expansion | Builds offline-capable iris-capture deployment expertise for UNHCR and World Food Programme refugee camp applications. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with biometric vendor product managers, government procurement officers, and enterprise IT security directors; and secondary validation through NIST FRVT test results, EU AI Act conformity assessment documentation, SEC filings of publicly traded identity technology providers, and Aadhaar API usage disclosures. Bottom-up triangulation across deployment model segmentation and top-down cross-check against federal budget authorization data anchored volume estimates.
Across the projection horizon, the analytical framework modeled technology modality, deployment architecture, end-user compliance intensity, and regional regulatory cluster. CAGRs derived from algorithm adoption curves and procurement cycle normalization. Industry-specific forecast inputs included NIST certification timeline compression and EU AI Act implementation pace across member state conformity assessment bodies.
Underlying assumptions cover sustained federal identity modernization appropriations and EU AI Act enforcement consistency, with deviation risk concentrated in Illinois BIPA litigation expansion and Taiwan semiconductor supply disruption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Latin America Government & Security Biometrics Market
Biometrics & Identity Management
Global Authentication Services Market
Biometrics & Identity Management
Global Biometric-As-A-Service Market
Biometrics & Identity Management
Biometric ATM Market
Biometrics & Identity Management
Global Human Identification Market
Biometrics & Identity Management
Consumer Biometrics Market
Biometrics & Identity Management
Healthcare Biometrics Market
Biometrics & Identity Management
Out-Of-Band Authentication Market
Biometrics & Identity Management
Biometrics As a Service in Healthcare Market
Biometrics & Identity Management
Global Biometrics Middleware Market
Biometrics & Identity Management
Europe Government and Security Biometrics Market
Biometrics & Identity Management
Italy Mobile Biometrics Market
Biometrics & Identity Management
Global Personal Identity Management Market
Biometrics & Identity Management
Biometrics Banking Market
Biometrics & Identity Management
FIDO Authentication Market
Biometrics & Identity Management
Mobile Devices User Authentication Services Market