
 Mobile Biometric Security and Services Market | 2026-2036
Mobile Biometric Security and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Biometric Security and Services Market Outlook
Asset-light licensing models for fingerprint and facial recognition algorithms are tilting competitive dynamics toward fabless semiconductor specialists. Qualcomm Technologies Inc. leverages its Snapdragon Secure processing enclave to anchor premium smartphone biometric pipelines. Samsung Electronics Co. Ltd. sustains vertical control through in-house Exynos security modules and Knox platform integration. Fingerprint Cards AB specializes in capacitive sensor miniaturization for mid-tier handset manufacturers seeking certified authentication hardware.
Mobile biometric security and services encompass identity verification systems deployed on smartphones and tablets, combining hardware sensors with cryptographic processors and machine-matching algorithms to authenticate individuals through physiological or behavioral traits. These systems typically operate with false acceptance rates below 0.002% and integrate dedicated secure elements isolated from host operating systems to protect template data. Fingerprint recognition dominates volume shipments due to mature sensor costs and established user habits, while facial recognition captures expanding share as 3D structured-light modules penetrate mid-range devices. Cloud-based deployment architectures attract financial institutions seeking centralized template management, though hybrid configurations gain traction among healthcare providers balancing accessibility with HIPAA-mandated data locality.
The US FDA regulates biometric data collection in clinical settings, while the EU AI Act imposes conformity assessments on remote biometric identification systems deployed in public spaces. India's BIS mandates certification for fingerprint scanners used in Aadhaar authentication, creating compliance gateways for hardware vendors. Stakeholders must weigh on-device template storage against cloud analytics flexibility as data sovereignty frameworks proliferate across jurisdictions.
Market Dynamics
The EU AI Act's risk-based classification of remote biometric identification systems is forcing a wholesale migration from cloud-based template storage toward on-device processing architectures, compressing vendor margins while elevating semiconductor security enclaves to strategic chokepoints.
Growth Catalysts
- Financial services digitization:Mobile banking penetration across emerging markets drives demand for certified fingerprint and facial recognition modules that meet PSD2 strong customer authentication mandates in the European Union.
- Aadhaar-linked infrastructure:India's digital identity ecosystem mandates biometric authentication for welfare disbursements and payment platforms, creating sustained procurement volume for certified sensor hardware.
- GDPR-compliant processing:Data minimization requirements under European privacy law accelerate adoption of edge-based matching algorithms that eliminate centralized template repositories.
Market Restraints
- Secure element supply concentration:Advanced cryptographic processors for biometric template protection depend on a limited pool of foundry capacity concentrated in Taiwan and South Korea.
- 3D structured-light module costs:Time-of-flight sensor arrays and dot-projector components remain prohibitively expensive for sub-premium smartphone tiers, constraining facial recognition penetration.
- Cross-border data friction:India's data localization directives under its Personal Data Protection framework complicate cloud-based biometric service architectures for multinational financial institutions.
Strategic Opportunities
- Healthcare access authentication:HIPAA-covered entities in the United States seek touchless biometric modalities for patient identity verification that reduce surface contact and integrate with electronic health record systems.
- Behavioral biometrics convergence:Keystroke dynamics and gait analysis algorithms layered atop physiological traits create continuous authentication frameworks for high-value transaction monitoring.
- Indonesia's digital identity buildout:The national e-KTP program expansion creates procurement windows for fingerprint sensor vendors capable of meeting tropical climate durability specifications.
Industry Challenges
- Spoof-resistant algorithm development:Presentation attack detection capabilities require ongoing investment in liveness detection training datasets and synthetic fraud simulation environments.
- Interoperability certification timelines:FIDO Alliance and ISO/IEC 30107-3 compliance testing creates 12-18 month product qualification cycles that delay revenue recognition for new sensor platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Biometric Security and Services Market |
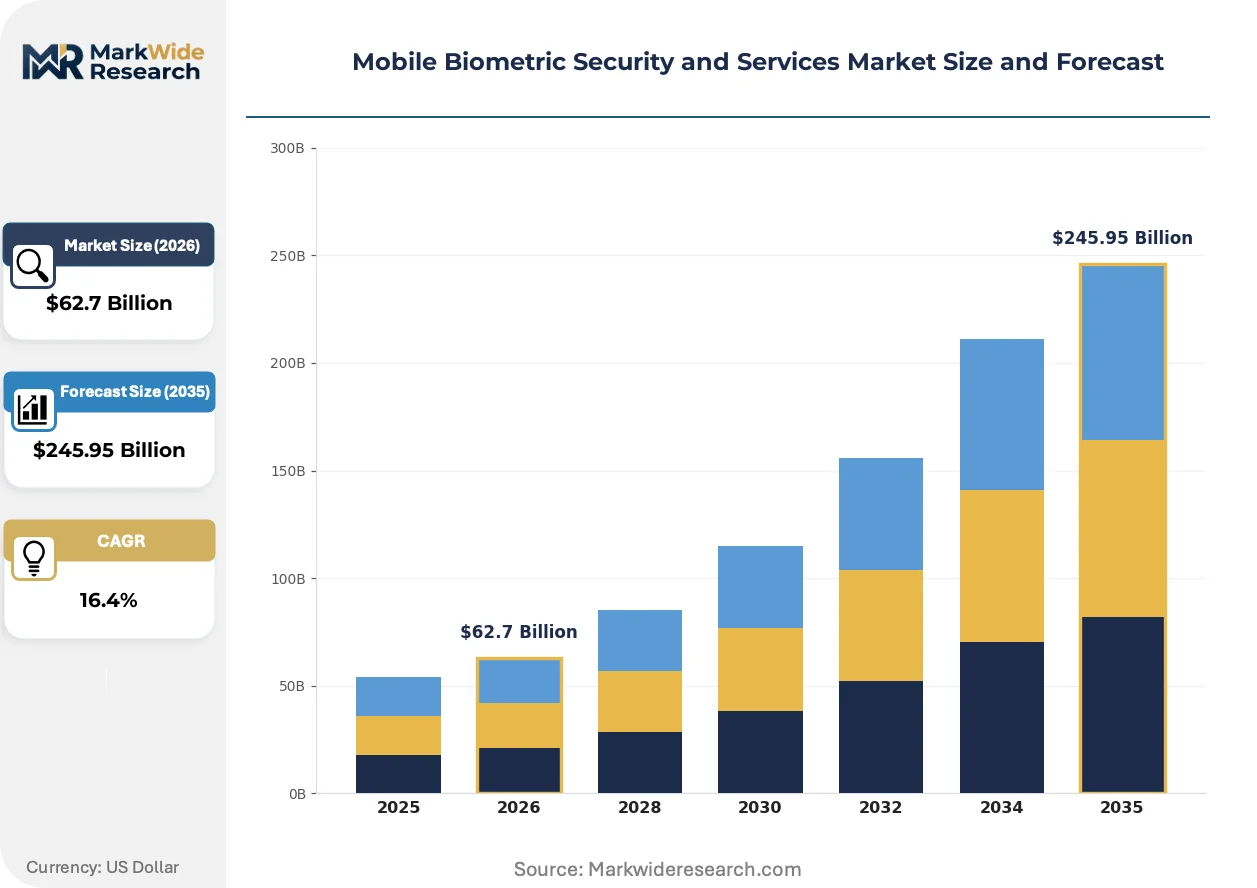
| Market Size in 2026 | $62.7 Billion |
| Market Size in 2035 | $245.95 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fingerprint Recognition, Facial Recognition, Iris Recognition, Voice Recognition Service Type: Biometric Authentication, Identity Verification, Fraud Detection, Access Control End User: Government Agencies, Financial Institutions, Retail Sector, Healthcare Providers Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Devices |
| Companies Covered | Thales Group, Samsung Electronics Co. Ltd., Qualcomm Technologies Inc., Goodix Technology Co. Ltd., Apple Inc., IDEMIA, Fingerprint Cards AB, Synaptics Incorporated, NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Biometric Security and Services Market Strategic Shifts
Algorithm virtualization is compressing the traditional hardware-software boundary in biometric systems, enabling sensor-agnostic matching engines that run across heterogeneous device fleets without dedicated secure element dependencies.
Presentation attack detection is virtualizing through software-based liveness verification that leverages existing RGB cameras rather than dedicated infrared or depth sensors. Mid-tier smartphone original equipment manufacturers in Southeast Asia adopt these solutions to avoid premium hardware costs. This compression is virtualizing the competitive moat that specialized sensor vendors previously maintained through hardware miniaturization expertise.
The EU AI Act's conformity assessment requirements for high-risk biometric systems impose third-party auditing obligations on vendors deploying remote identification in public spaces. Industrial consequence includes mandatory documentation of training data provenance and algorithmic bias testing. Healthcare and transportation sectors in Germany and France face the steepest compliance ramps, driving procurement preference toward vendors with pre-certified quality management systems.
Enterprise buyers in financial services now unbundle biometric authentication from core banking platform contracts, creating direct procurement relationships with specialized identity vendors. This disintermediation displaces traditional system integrator channels in the United Kingdom and Netherlands. Asset managers and insurance underwriters represent the fastest-adopting segments, seeking API-first biometric services that integrate with existing customer identity and access management stacks.
Mobile Biometric Security and Services Market Segmentation
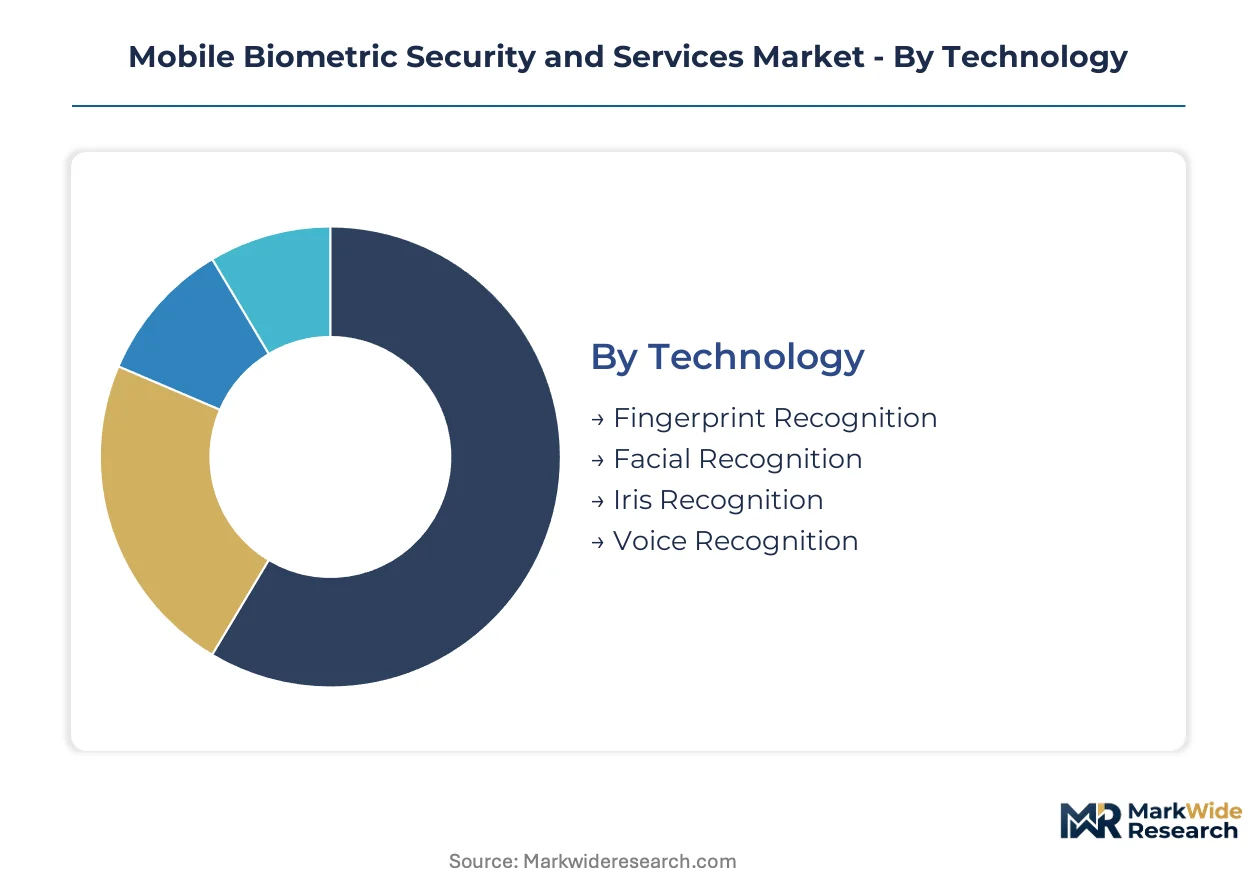
Technology-service combinations in mobile biometrics require distinct hardware-software integration depth, with fingerprint and facial modalities demanding continuous firmware updates and liveness detection algorithm refreshes. Deployment architecture choices between on-device and cloud processing reshape vendor revenue models and customer lock-in duration.
Technology:
After-sales-service intensity varies sharply across biometric modalities, with fingerprint sensors requiring periodic recalibration support and facial recognition systems demanding ongoing presentation attack detection library updates.
- Fingerprint Recognition:Capacitive and ultrasonic sensor arrays capture ridge patterns through physical contact, with Qualcomm's 3D Sonic technology enabling under-display integration. Indian Aadhaar authentication networks and European PSD2-compliant banking apps drive procurement of certified hardware meeting BIS and FIDO Alliance standards. Service intensity concentrates on sensor durability replacement cycles and template migration support.
- Facial Recognition:Structured-light and time-of-flight systems construct 3D facial maps through infrared dot projection and depth sensing. Healthcare providers in the United States adopt touchless patient verification to reduce surface contact under FDA-regulated clinical protocols. Continuous algorithm updates for spoof resistance create recurring revenue streams distinct from hardware margins.
- Iris Recognition:Near-infrared imaging of unique stromal patterns delivers higher accuracy thresholds than facial modalities.
- Voice Recognition:Spectral analysis of vocal tract characteristics enables hands-free authentication for automotive and smart home integrations.
By volume, Fingerprint Recognition leads. By growth pace, Facial Recognition is ahead.
Service Type:
Cost tier stratification separates commodity authentication APIs from premium fraud detection suites with behavioral analytics layering.
- Biometric Authentication:One-to-one template matching for device unlock and application access represents the baseline service tier. Financial institutions in India deploy liveness-certified fingerprint verification for Aadhaar-linked payment authentication, with RBI mandates driving standardization. Margins compress as open-source matching libraries proliferate.
- Identity Verification:Document-to-biometric binding with government database cross-checks commands premium pricing. EU AI Act conformity assessments for remote identification systems elevate vendor qualification costs and extend sales cycles. German and French healthcare procurement favors pre-certified quality management systems.
- Fraud Detection:Behavioral biometrics integration for transaction monitoring serves asset managers and insurance underwriters.
- Access Control:Enterprise physical and logical security convergence for zero-trust architectures.
Authentication dominates transaction volume. Identity verification claims the steepest expansion trajectory.
End User:
Application-specific compliance requirements fragment procurement specifications across regulated sectors.
- Government Agencies:National digital identity programs mandate certified hardware with documented supply chain provenance. India's BIS certification for Aadhaar scanners creates hardware gateways, while Indonesia's e-KTP expansion specifies tropical climate durability. Long procurement cycles and bid-rigging scrutiny compress vendor margins.
- Financial Institutions:Mobile banking penetration across emerging markets drives demand for PSD2-compliant strong customer authentication. UK and Netherlands enterprise buyers increasingly unbundle biometric services from core banking contracts, creating direct vendor relationships. API-first integration with existing identity stacks accelerates deployment.
- Retail Sector:Payment authentication and loyalty program identity binding for frictionless checkout.
- Healthcare Providers:HIPAA-covered entities seek touchless modalities reducing infection risk.
Financial institutions lead procurement value. Government agencies anchor volume stability.
Deployment:
Customer type preferences split between centralized control and edge autonomy.
- On-Premises:Dedicated infrastructure within organizational firewalls satisfies data localization mandates. Indian Personal Data Protection framework directives complicate multinational financial institution architectures, favoring captive server deployments. Capital intensity and maintenance overhead limit adoption to large enterprises.
- Cloud-Based:Centralized template management attracts financial institutions seeking analytics flexibility and rapid scaling. GDPR data minimization requirements and EU AI Act risk classifications are forcing migration toward edge alternatives, compressing addressable market growth. Latency and sovereignty concerns persist.
- Hybrid:Template storage on-device with analytics aggregation in cloud balances accessibility and compliance.
- Mobile Devices:Native secure enclave processing eliminates network dependency for authentication.
Mobile Devices command the fastest uptake. Hybrid architectures are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import-dependent economies in South Asia and Southeast Asia drive hardware procurement for biometric sensor modules, while regulatory divergence between data localization mandates and cross-border service frameworks shapes deployment architectures across major markets.
United States
Financial institutions and healthcare providers dominate sensor procurement, with HIPAA-covered entities seeking touchless patient verification systems. The FDA regulates biometric data collection in clinical settings, creating compliance gateways for vendors. Silicon Valley clusters anchor algorithm development, while Texas hosts secure element testing facilities for federal procurement.
India
Aadhaar-linked payment authentication and welfare disbursement platforms sustain the world's largest certified fingerprint scanner deployment. BIS mandates certification for hardware used in national identity networks, compressing vendor qualification timelines. Bengaluru and Hyderabad concentrate software development centers for liveness detection algorithms serving domestic fintech applications.
Germany
Automotive and industrial automation sectors drive demand for secure biometric access control systems. The EU AI Act imposes conformity assessments on remote identification deployments, elevating vendor documentation requirements. Munich and Stuttgart host quality management system auditors pre-certifying biometric platforms for healthcare and transportation procurement.
China
Domestic smartphone manufacturers anchor capacitive and ultrasonic sensor demand for mid-tier device integration. MIIT standards govern secure element certification for financial applications, creating technical barriers for foreign component vendors. Shenzhen and Shanghai concentrate module assembly capacity serving both domestic consumption and Southeast Asian export markets.
Indonesia
National e-KTP program expansion generates procurement windows for fingerprint hardware meeting tropical climate durability specifications. The central bank mandates biometric verification for mobile banking onboarding, accelerating sensor deployment across archipelago banking networks. Jakarta and Surabaya concentrate system integrator capacity for government identity infrastructure rollouts.
Mobile Biometric Security and Services Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in licensing and sensor fabrication. The vendor base stratifies between semiconductor enclave providers, algorithm licensors, and certified hardware fabricators. Three archetypes dominate: fabless semiconductor designers with secure processing IP, sensor miniaturization specialists serving mid-tier OEMs, and vertical platform owners integrating hardware-software stacks. Competitive moves concentrate on strategic IP licensing to capture royalty streams and foundry partnerships to secure advanced node capacity.
Within the platform integrator tier, Qualcomm Technologies Inc. and Samsung Electronics Co. Ltd. exemplify divergent approaches to secure enclave architecture—one licensing across heterogeneous device fleets, the other maintaining captive integration. Fingerprint Cards AB occupies a position among component specialists focused on certified sensor hardware for price-sensitive tiers. These three anchors illustrate how competitive positioning splits between IP monetization breadth and vertical control depth.
| Leading Market Players |
|---|
| Thales Group |
| Samsung Electronics Co. Ltd. |
| Qualcomm Technologies Inc. |
| Goodix Technology Co. Ltd. |
| Apple Inc. |
| IDEMIA |
| Fingerprint Cards AB |
| Synaptics Incorporated |
| NEC Corporation |
| Others |
Value Chain & Pricing Dynamics
Secure element foundry concentration in Taiwan and South Korea determines both margin compression in premium tiers and the geographic shape of component sourcing. Vendors face simultaneous pressure from EU AI Act compliance costs and tariff exposure on sensor module imports, forcing tiered pricing spreads that separate certified enclave hardware from commodity alternatives.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on FIDO Alliance certification grade and after-sales algorithm update bundling, with premium tiers commanding substantial markups for liveness detection libraries. Pricing pressure stems from open-source matching library proliferation in the authentication tier, compressing margins for sensor-agnostic software vendors. Mid-tier smartphone manufacturers exhibit the highest price sensitivity, while financial institutions under PSD2 mandates accept premium positioning for certified hardware.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for biometric hardware vendors. Advanced cryptographic processors draw from Taiwan and South Korea foundry capacity, while capacitive sensor assembly concentrates in China and Vietnam. Time-of-flight dot projectors and infrared imaging arrays feed from Japanese and South Korean component specialists. Single-source vulnerability in 3nm secure enclave production creates procurement bottlenecks for premium smartphone integrations. Distribution runs through direct OEM partnerships and licensed module integrators serving government identity programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-based liveness detection threatens to displace specialized sensor hardware, forcing incumbents to defend through certification moats and algorithm-agnostic platform control.
For Market Incumbents: Pre-empt substitution by embedding presentation attack detection libraries into secure enclave firmware, locking in recurring revenue streams. Deepen backward integration into foundry partnerships for advanced node capacity, insulating against Taiwan supply concentration. Defend against open-source matching libraries by accelerating FIDO Alliance and ISO/IEC 30107-3 certification timelines to extend product stickiness. For New Entrants and Emerging Players: Pursue white-space in Indonesia's e-KTP expansion and India's Aadhaar-linked welfare platforms, where tropical durability specifications and BIS certification create hardware procurement windows. Target healthcare providers in the United States seeking touchless patient verification under FDA clinical protocols, a segment with limited incumbent saturation. Lead with API-first integration pitches to UK and Netherlands financial institutions that have unbundled biometric services from core banking contracts. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors fabless semiconductor specialists with secure processing IP and established foundry relationships. Long-term viability hinges on regulatory compliance automation rather than hardware miniaturization alone. Watch for EU AI Act third-party auditing mandates as the inflection signal that separates pre-certified quality management vendors from laggards facing extended sales cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Secure Enclave IP Licensing | Qualcomm's Snapdragon pipeline demonstrates royalty capture across heterogeneous OEM fleets without captive fabrication. |
| Presentation Attack Detection Virtualization | Software-based liveness verification using RGB cameras compresses hardware costs for Southeast Asian mid-tier manufacturers. |
| Foundry Partnership Securement | Advanced node allocation from TSMC or Samsung insulates against supply concentration in Taiwan and South Korea. |
| Pre-Certified Quality Management Investment | German and French healthcare procurement favors vendors with documented training data provenance under EU AI Act mandates. |
| Behavioral Biometrics Layering | Keystroke dynamics and gait analysis integration serves asset managers seeking continuous authentication for high-value transactions. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC filings, FIDO Alliance certification databases, BIS hardware approval registries, and EU AI Act conformity assessment documentation. Semiconductor vendor executives, biometric algorithm R&D directors, financial institution procurement officers, and government identity program administrators provided operational perspective. Customs trade data and smartphone production estimates supplied volume anchors. Bottom-up sensor shipment tallies triangulate against top-down service revenue aggregation.
Forecast inputs span technology modality, service tier, deployment architecture, and end-use sector concentration across the projection horizon. Segmentation modeling captures fingerprint, facial, iris, and voice recognition penetration curves alongside authentication, identity verification, fraud detection, and access control service splits. CAGRs derive from fitted adoption curves incorporating regulatory mandate timelines and smartphone replacement cycles. EU AI Act implementation phases and India's Aadhaar authentication volume trajectories inform regional weightings.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or cross-border data localization enforcement would shift the trajectory. Forecasts reflect documented assumptions on certification timeline compression and foundry capacity allocation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Biometric Smart Cards Market
Biometrics & Identity Management
Biometric Data Encryption Device Market
Biometrics & Identity Management
Global Biometrics Middleware Market
Biometrics & Identity Management
Password Management Market
Biometrics & Identity Management
Airport Biometrics Market
Biometrics & Identity Management
Automated Fingerprint Identification Systems (AFIS) Market
Biometrics & Identity Management
Latin America Government & Security Biometrics Market
Biometrics & Identity Management
Biometric Authentication Solution Market
Biometrics & Identity Management
Global Biometric Authentication Identification Market
Biometrics & Identity Management
Global Multifactor Authentication Market
Biometrics & Identity Management
Out-Of-Band Authentication Market
Biometrics & Identity Management
Germany Identity Verification and Authentication Market
Biometrics & Identity Management
Vein Recognition Biometrics Market
Biometrics & Identity Management
Mobile Biometrics Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Software Market
Biometrics & Identity Management
Biometric Passport Market