
 Physical Identity and Access Management (PIAM) Market | 2026-2036
Physical Identity and Access Management (PIAM) Market Size, Share, and Industry Trends Forecast 2026-2036
Physical Identity and Access Management (PIAM) Market Analytics
ISO 27001 certification cycles are redrawing competitive boundaries in the PIAM sector. Honeywell leverages its building automation heritage to anchor integrated security offerings across commercial real estate portfolios. Genetec Inc. specializes in unified video and access platforms that sustain recurring revenue through software subscriptions. AlertEnterprise Inc. differentiates by competing on cyber-physical convergence for critical infrastructure operators.
Physical Identity and Access Management encompasses the centralized provisioning, authentication, and lifecycle governance of credentials that bridge physical entry points with digital identity stores, typically operating through LDAP or SAML federation protocols with real-time door controller synchronization. The technology's primary commercial purpose is eliminating credential sprawl while enforcing consistent policy across disparate security systems. Biometrics and cloud-based solutions represent the fastest-expanding technology pairing, as organizations abandon card-centric models in favor of facial recognition and mobile authentication. On-premises deployment retains dominance in government agencies and financial institutions where data sovereignty mandates predominate, though hybrid architectures are capturing margin pools by offering managed security services atop customer-controlled hardware.
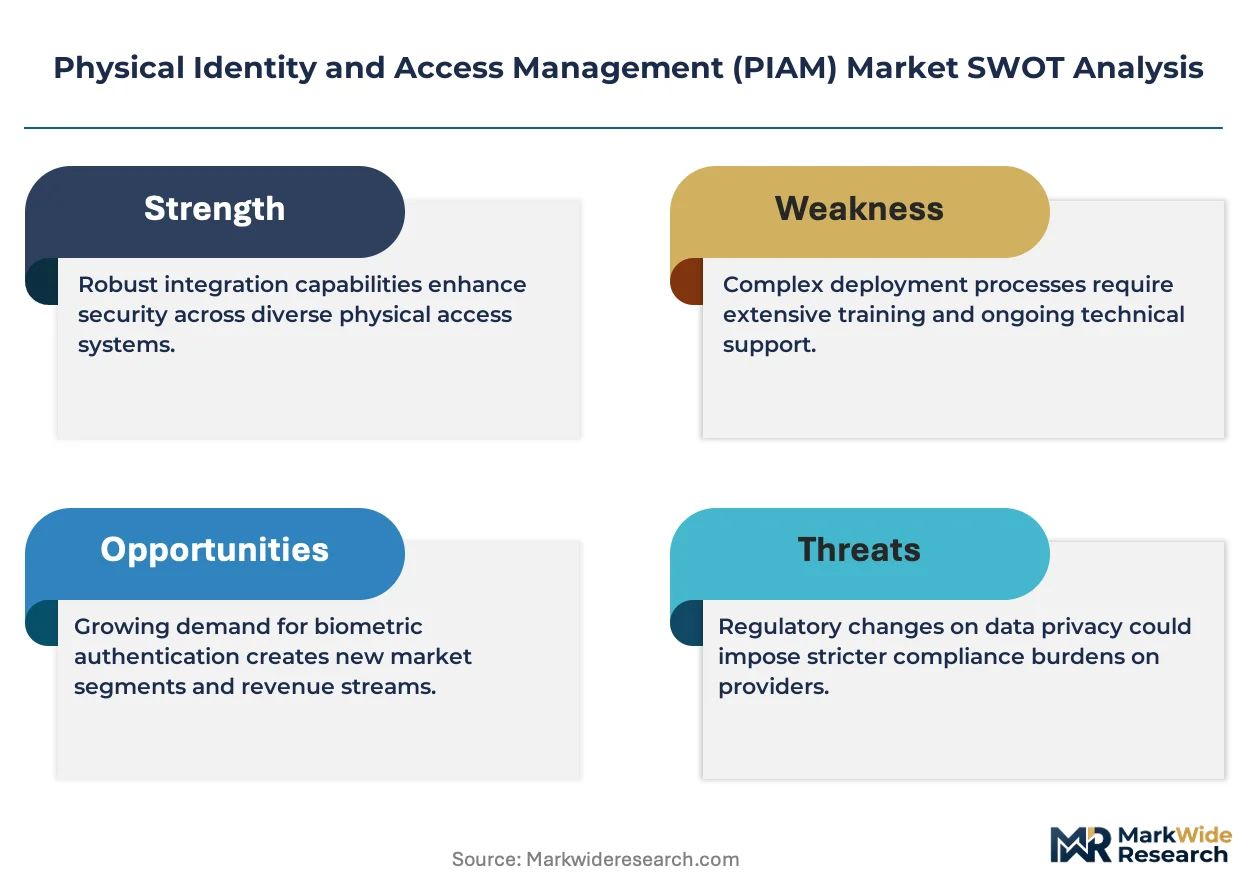
FCC guidelines on communications infrastructure security, EU GDPR data processing requirements for biometric templates, and NIST SP 800-53 controls for federal facilities collectively shape product roadmaps and procurement eligibility. Compliance with these frameworks determines market access for vendors serving regulated end users. Stakeholders must monitor how converging cybersecurity and physical security audit regimes reshape RFP requirements and vendor qualification criteria.
Market Dynamics
The Physical Identity and Access Management market is undergoing structural compression as biometric authentication and mobile credentials dismantle card-centric infrastructure, forcing incumbents to rebuild software stacks around cloud-native architectures while navigating fragmented compliance mandates across jurisdictions.
Growth Catalysts
- EU AI Act compliance deadlines:Healthcare systems and critical infrastructure operators face mandatory algorithmic transparency requirements for biometric systems, driving replacement of legacy black-box facial recognition with auditable, explainable alternatives.
- Cloud-to-edge synchronization protocols:Real-time credential propagation across distributed door controllers eliminates latency gaps that previously forced on-premise retention, expanding addressable market for hybrid deployment models.
- Germany:Industrial campus consolidation around converged physical-cyber platforms is creating reference architectures that neighboring European states are adopting through bilateral security cooperation frameworks.
Market Restraints
- Silicon supply concentration:Specialized biometric sensor chip fabrication concentrates in Taiwan and South Korea, exposing PIAM hardware vendors to geopolitical disruption and allocation rationing during demand spikes.
- GDPR Article 9 friction:Biometric template classification as special category data triggers enhanced consent requirements and data protection impact assessments that extend enterprise sales cycles.
- Card-based credential persistence:Low-cost proximity card systems retain installed base in price-sensitive commercial real estate, slowing biometric substitution despite superior security profiles.
Strategic Opportunities
- India:Smart city infrastructure investments and Aadhaar-linked identity frameworks are creating demand for municipal-scale PIAM systems that bridge national digital identity with physical access control.
- Zero-trust architecture mandates:NIST SP 800-207 adoption across US federal contractors is forcing integration between physical access events and continuous identity verification, opening subscription revenue for converged platform vendors.
- Mobile wallet credentialing:Apple Wallet and Google Wallet native access key standards are enabling phone-as-badge deployments that bypass proprietary card distribution logistics entirely.
Industry Challenges
- Multi-domain certification stacking:Vendors must simultaneously maintain ISO 27001, SOC 2 Type II, and sector-specific attestations for healthcare and federal markets, multiplying audit costs and timeline risk.
- OT-IT integration complexity:Industrial PIAM deployments require bridging operational technology door controllers with enterprise identity stores, demanding scarce expertise in both legacy industrial protocols and modern SAML/OAuth federation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Physical Identity and Access Management (PIAM) Market |
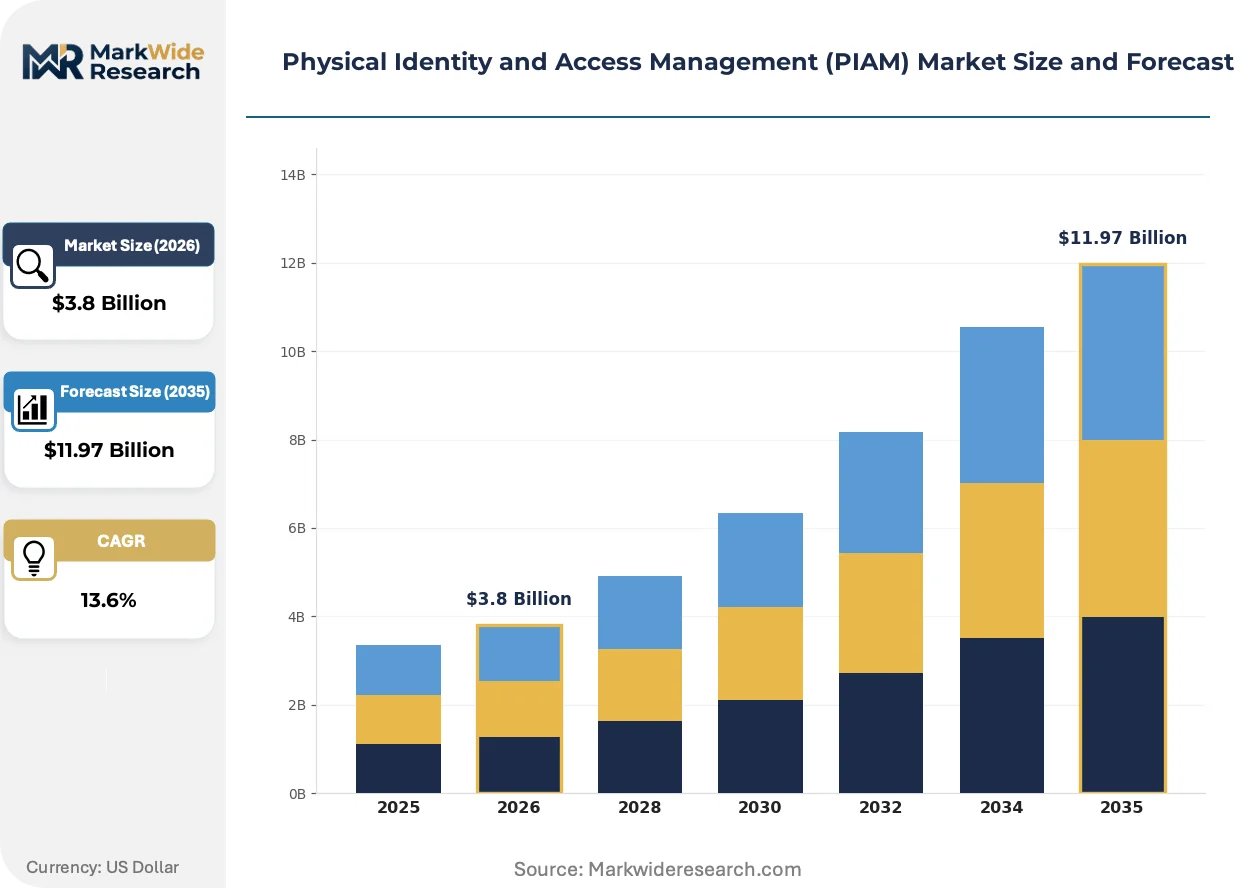
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.97 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biometrics, Smart Cards, Access Control Systems, Identity Verification Solutions Technology: Facial Recognition, RFID, Cloud-Based Solutions, Mobile Authentication End User: Healthcare Facilities, Government Agencies, Financial Institutions, Corporate Offices Deployment: On-Premises, Cloud, Hybrid, Managed Services |
| Companies Covered | Brivo, Honeywell, HID Global Corporation, Siemens, IBM Corporation, Genetec Inc., AlertEnterprise Inc., Oracle Corporation, Johnson Controls, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Physical Identity and Access Management (PIAM) Market Evolving Landscape
Biometric modalities and mobile authentication are actively compressing hardware refresh cycles while regulatory fragmentation around algorithmic accountability is forcing product architecture redesigns across vendor portfolios.
Facial recognition with liveness detection is displacing fingerprint readers as the dominant biometric modality in high-throughput environments. Airport operators and corporate campuses are deploying touchless systems at scale to reduce contact points and throughput friction. This displacement is compressing sensor hardware margins while expanding software licensing revenue for anti-spoofing algorithms and template management platforms.
The EU AI Act's risk-based classification system for biometric identification is mandating conformity assessments and CE marking for PIAM systems deployed in public spaces. Vendors must now maintain technical documentation, human oversight protocols, and accuracy benchmarking that previously applied only to law enforcement applications. German critical infrastructure operators are responding earliest, using the Act's implementation timeline to justify accelerated procurement of compliant systems ahead of competitor markets.
Subscription-based identity-as-a-service models are unbundling perpetual license economics and concentrating buyer relationships with cloud-native vendors. System integrators that previously captured margin through on-premise deployment and maintenance are losing position to direct vendor-customer relationships. This shift is most visible in US commercial real estate, where portfolio managers favor operational expenditure treatment and centralized policy administration across distributed properties.
Physical Identity and Access Management (PIAM) Market Segmentation
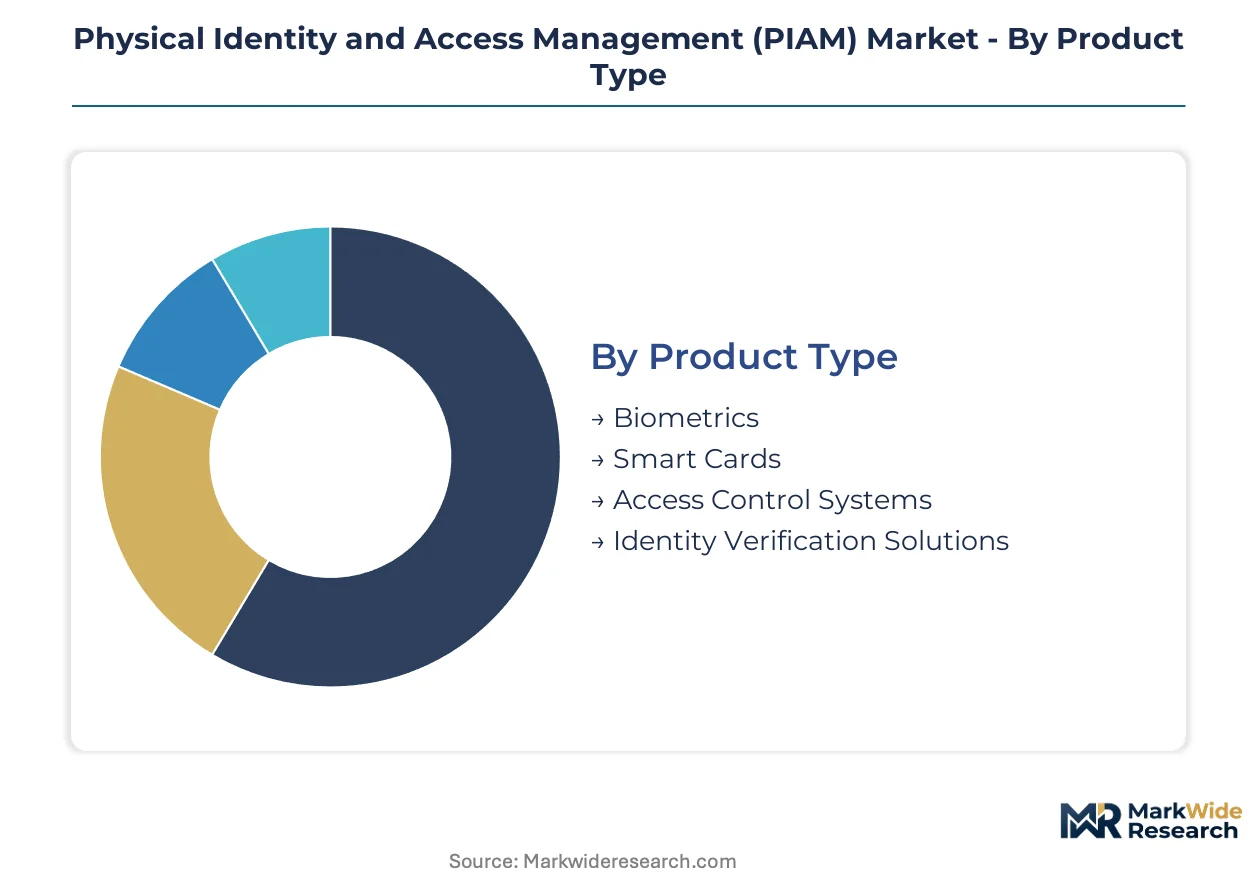
PIAM purchasing decisions fragment across credential formats, infrastructure architectures, and compliance regimes. Technology substitution pressures and deployment model trade-offs reshape vendor positioning in each slice. Procurement committees weigh biometric accuracy against card-system replacement costs.
Product Type:
Biometric modalities face acute substitution pressure from mobile wallet credentials that bypass dedicated hardware entirely.
- Biometrics:Facial recognition and fingerprint systems authenticate through physiological pattern matching against encrypted templates. German industrial campuses deploy these for high-security zones under EU AI Act conformity requirements. Template storage architectures determine GDPR Article 9 compliance feasibility.
- Smart Cards:Contactless credentials using RFID or NFC chips persist in price-sensitive installations. Commercial real estate portfolios in the United States retain proximity card infrastructure to defer capital refresh cycles despite inferior security profiles.
- Access Control Systems:Door controllers and credential readers form the physical enforcement layer.
- Identity Verification Solutions:Software platforms centralize provisioning, de-provisioning, and audit logging.
Smart Cards retain volume leadership; Biometrics holds the steepest expansion curve.
Technology:
Cost tier stratification separates enterprise-grade facial recognition from commodity RFID deployments.
- Facial Recognition:3D depth-sensing cameras with liveness detection prevent presentation attacks. Airport operators in France and the Netherlands deploy touchless corridors to reduce throughput friction. Anti-spoofing algorithm licensing generates recurring software revenue.
- RFID:Passive tag systems operating at 125 kHz or 13.56 MHz dominate legacy installed bases. Low per-credential cost sustains adoption in budget-constrained municipal facilities.
- Cloud-Based Solutions:Identity-as-a-service models shift capital expenditure to operational treatment.
- Mobile Authentication:Apple Wallet and Google Wallet native access keys eliminate card distribution logistics.
RFID retains volume leadership; Mobile Authentication gains share fastest.
End User:
Application-specific compliance mandates reshape feature requirements across verticals.
- Healthcare Facilities:Patient data protection under HIPAA drives biometric adoption for pharmacy and records room access. JCAHO audit readiness requires immutable access logs.
- Government Agencies:NIST SP 800-53 controls mandate FICAM-compliant architectures. Federal facilities in the United States prioritize on-premises deployment for data sovereignty.
- Financial Institutions:PCI-DSS and SOX requirements enforce separation of duties in data center access.
- Corporate Offices:Portfolio managers favor centralized policy administration across distributed properties.
Corporate Offices retain volume leadership; Healthcare Facilities climb the fastest.
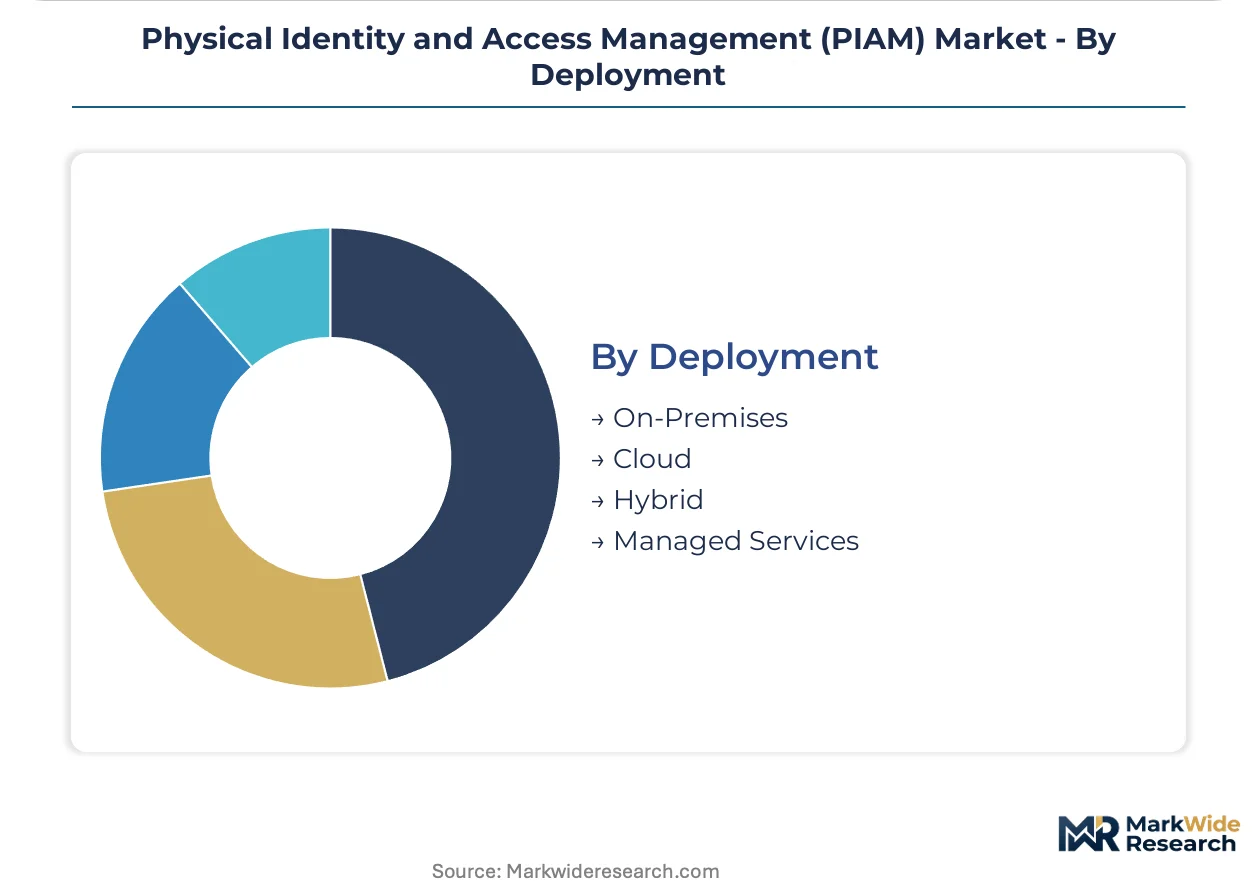
Deployment:
Customer type segmentation separates regulated entities with sovereignty mandates from commercial buyers seeking operational flexibility.
- On-Premises:Hardware and software reside within customer-controlled data centers. Financial institutions in Frankfurt and Singapore mandate this model for biometric template custody.
- Cloud:Multi-tenant platforms deliver identity services via subscription. US commercial real estate favors this model for OPEX treatment and rapid provisioning.
- Hybrid:Edge controllers synchronize with cloud policy engines.
- Managed Services:Third-party operators assume infrastructure maintenance and compliance monitoring.
On-Premises retains volume leadership; Hybrid shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU AI Act compliance deadlines and GDPR biometric processing rules are redrawing procurement timelines across national jurisdictions. Industrial campus consolidation and critical infrastructure security mandates concentrate demand in specific metropolitan clusters.
United States
Federal zero-trust architecture mandates under NIST SP 800-207 are accelerating converged physical-cyber platform adoption. The Department of Homeland Security's binding operational directives shape vendor qualification criteria for federal facilities. Washington DC and Northern Virginia host the densest concentration of FICAM-compliant deployment projects.
Germany
Industrial operators in chemical and automotive sectors are replacing legacy card systems with EU AI Act-conformant biometric platforms. The Federal Office for Information Security issues technical guidelines for critical infrastructure access control. The Rhine-Ruhr industrial corridor and Munich metropolitan area anchor continental Europe's largest PIAM refresh cycle.
India
Smart city mission investments and Aadhaar-linked identity frameworks are creating municipal-scale integration opportunities. The Ministry of Housing and Urban Affairs mandates interoperable access systems for urban infrastructure projects. Bangalore and Hyderabad lead software-centric deployments, while Delhi-Mumbai industrial corridors drive hardware-heavy installations.
United Arab Emirates
NEOM and other giga-project developments specify AI-enabled facial recognition for resident and visitor credentialing. The National Cybersecurity Council issues sector-specific controls for critical facility access. Dubai's aviation and hospitality clusters deploy touchless biometric corridors at scale.
Japan
Tokyo's preparations for major international events are accelerating touchless authentication deployment in transportation hubs. METI's guidelines for operational technology security influence industrial facility access specifications. The Osaka-Kobe manufacturing belt and Fukuza's semiconductor clusters prioritize OT-IT converged platforms.
Physical Identity and Access Management (PIAM) Market Competitive Landscape
Listed leaders compete with private specialists across compliance certification depth and vertical integration breadth. The vendor base stratifies between building automation conglomerates, pure-play software platforms, and cyber-physical convergence specialists. Three archetypes dominate: integrated security portfolios, subscription-native SaaS vendors, and critical infrastructure specialists. Competitive moves concentrate on M&A for biometric algorithm capabilities and strategic partnerships for cloud-to-edge synchronization protocols.
Within the integrated portfolio tier, Honeywell leverages building automation heritage to anchor commercial real estate offerings, while Siemens occupies a position bridging industrial control systems with enterprise identity stores. Genetec Inc. exemplifies the subscription-native archetype through unified video-access platforms. AlertEnterprise Inc. represents the cyber-physical specialist model for critical infrastructure operators.
| Leading Market Players |
|---|
| Brivo |
| Honeywell |
| HID Global Corporation |
| Siemens |
| IBM Corporation |
| Genetec Inc. |
| AlertEnterprise Inc. |
| Oracle Corporation |
| Johnson Controls |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with Taiwan-based biometric sensor fabricators lock in supply access while anchoring price visibility for PIAM hardware vendors navigating EU AI Act compliance timelines. These arrangements insulate German industrial operators from allocation rationing during demand spikes while compressing margins for buyers without forward commitments.
Pricing Analysis
Certification level creates the primary spread between EU AI Act-conformant biometric platforms and legacy card-centric systems. Three-tier pricing structure across premium, standard, and economy levels segments by ISO 27001 attestation depth and GDPR Article 9 template handling architecture. Cost compression in the standard tier is intensifying because cloud-native vendors are unbundling perpetual licenses into subscription models. Commercial real estate portfolio managers exhibit highest price sensitivity; federal contractors under FICAM mandates show lowest.
Supply Chain Analysis
Taiwan Strait transit vulnerability concentrates specialized biometric sensor chip fabrication, exposing PIAM hardware vendors to geopolitical disruption. Supply draws from Taiwan, South Korea, and Japan for 3D depth-sensing cameras, liveness detection algorithms, and edge controller processors. Single-source vulnerability in EUV lithography equipment amplifies allocation risk during demand spikes. Distribution runs through systems integrators and direct vendor relationships to end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PIAM is approaching a platform-economics inflection as Apple Wallet and Google Wallet native access key standards commoditize credential distribution while concentrating power with cloud-native identity orchestrators.
For Market Incumbents: Shield installed base relationships by embedding EU AI Act conformity documentation into renewal negotiations before compliance deadlines harden procurement criteria. Invest in backward integration into biometric algorithm development to capture software licensing revenue streams that cloud-native entrants are unbundling from hardware.
For New Entrants and Emerging Players: Anchor in India's smart city infrastructure pipeline where Aadhaar-linked identity frameworks create municipal-scale integration white space underserved by legacy vendors. Target healthcare facilities in the United States facing JCAHO audit readiness requirements with identity-as-a-service offerings that bypass capital-intensive controller hardware.
For Investors and Strategic Acquirers: Capital is best deployed toward cyber-physical convergence specialists with OT-IT integration capabilities and existing ISO 27001 certification cycles. Watch for inflection when NIST SP 800-207 zero-trust mandates expand beyond federal contractors to critical infrastructure operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Algorithm Acquisition | Captures recurring software revenue from anti-spoofing licensing as hardware margins compress. |
| EU AI Act Conformity Certification | Unlocks procurement eligibility for German industrial campuses and public space deployments. |
| Cloud-to-Edge Synchronization Partnership | Eliminates latency gaps that previously forced on-premises retention, expanding hybrid addressable market. |
| Mobile Wallet Credential Integration | Bypasses proprietary card distribution logistics entirely through Apple Wallet and Google Wallet standards. |
| Critical Infrastructure Vertical Expansion | Positions vendors for binding operational directives from the Department of Homeland Security. |
Research Methodology
A spread of perspectives from physical security directors, identity and access management procurement officers, biometric algorithm engineers, and critical infrastructure compliance leads converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through SEC filings, EU technical documentation databases, and NIST SP 800-53 implementation guides. Bottom-up credential deployment estimates and top-down security spending allocations were triangulated to anchor volume assumptions.
Segmentation dimensions modeled span biometric modality, credential format, deployment architecture, end-user vertical, and regional regulatory cluster across the projection horizon. CAGRs were derived from fitted growth curves against historical adoption patterns and policy-driven procurement timelines. Forecast inputs incorporated EU AI Act implementation schedules, NIST zero-trust architecture adoption curves, and cloud-to-edge synchronization protocol maturation.
Decision-makers should treat outputs as directional under assumptions of stable geopolitical conditions in Taiwan and South Korea; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as GDPR Article 9 enforcement intensity and silicon supply allocation regimes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Next Generation Biometric Market
Biometrics & Identity Management
Healthcare Biometrics Market
Biometrics & Identity Management
Automated Fingerprint Identification Systems (AFIS) Market
Biometrics & Identity Management
Europe Biometrics in Government Market
Biometrics & Identity Management
Global Phone Based Authentication Solution Market
Biometrics & Identity Management
Global Human Identification Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Software Market
Biometrics & Identity Management
Biometric Services Platform (Biosp) Market
Biometrics & Identity Management
Asia Pacific Biometrics in Government Market
Biometrics & Identity Management
Biometric Smart Cards Market
Biometrics & Identity Management
Hand Geometry Biometrics Market
Biometrics & Identity Management
Biometrics Banking Market
Biometrics & Identity Management
United States Biometrics Market
Biometrics & Identity Management
Biometric Authentication Solution Market
Biometrics & Identity Management
Out-Of-Band Authentication Market
Biometrics & Identity Management
Global Personal Identity Management Market