
 Global Biometric-As-A-Service Market | 2026-2036
Global Biometric-As-A-Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biometric-As-A-Service Market Foresight
The gap between premium multimodal platforms and commodity single-factor offerings is repositioning vendor strategies across the Biometric-As-A-Service landscape. NEC Corporation leverages its long-standing government relationships to sustain dominance in large-scale national ID deployments. Thales Group anchors its competitive stance through deep integration with civil aviation security infrastructure. Idemia differentiates by controlling end-to-end identity credentialing workflows across multiple continents.
Biometric-As-A-Service denotes a cloud-delivered model where fingerprint, facial, iris, voice, or palm vein recognition capabilities are provisioned via subscription APIs rather than on-site hardware. These platforms typically process authentication requests through encrypted channels with latency thresholds under 500 milliseconds for real-time verification. Facial recognition and fingerprint recognition currently lead transaction volumes, while iris scanning commands premium pricing in high-assurance environments such as cross-border travel. Cloud-based deployment models capture the fastest expansion as enterprises abandon capital-intensive on-premises biometric infrastructure.
The EU AI Act, GDPR, and India's BIS certification requirements collectively shape product roadmaps by mandating algorithmic transparency, consent audit trails, and liveness detection standards. The US NIST testing protocols and India's UIDAI framework further segment market access between jurisdictions with divergent biometric data governance models. Stakeholders must monitor regulatory divergence between privacy-first jurisdictions and security-prioritized markets to calibrate geographic expansion and R&D allocation without overcommitting to incompatible compliance architectures.
Market Dynamics
Cloud migration in financial services is compressing deployment timelines from months to days, forcing biometric vendors to rearchitect latency-sensitive authentication pipelines for distributed edge infrastructure.
Growth Catalysts
- GDPR Article 9 Compliance:EU enterprises are mandating biometric data processors with certified EU data residency, accelerating contract wins for regional cloud providers with Frankfurt and Dublin availability zones.
- Contactless Payment Rails:Palm vein and facial recognition terminals are displacing PIN pads at retail checkout across South Korea and Singapore transit networks.
- India's UIDAI Integration:Aadhaar-authenticated service delivery is expanding into rural banking and telemedicine, creating sustained API volume demand.
Market Restraints
- Algorithm Training Data Concentration:High-quality facial datasets cluster with US and Chinese AI labs, creating licensing bottlenecks for second-tier biometric vendors.
- NIST Certification Timelines:Minutiae extraction algorithm validation cycles now exceed 18 months, freezing product roadmaps for fingerprint module suppliers.
- Silicon Supply Tightness:Specialized image signal processors for iris cameras face allocation constraints from Taiwan foundry capacity.
Strategic Opportunities
- Brazil's Digital ID Mandate:The national civil identification program is tendering cloud-based biometric matching for 150 million citizens without incumbent vendor lock-in.
- Voice Biometric Convergence:Integration with conversational AI agents is opening authentication-as-a-feature pricing in customer service automation.
- Saudi Vision 2030 Smart Cities:NEOM and Red Sea Project developments are specifying multimodal biometric access for hospitality and logistics zones.
Industry Challenges
- Spoof Detection Engineering:Presentation attack detection specialists command compensation premiums exceeding 40% above standard computer vision roles.
- Cross-Border Data Architecture:Enterprises operating across GDPR, China's PIPL, and Saudi PDPL must maintain three incompatible encryption and audit trail implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biometric-As-A-Service Market |
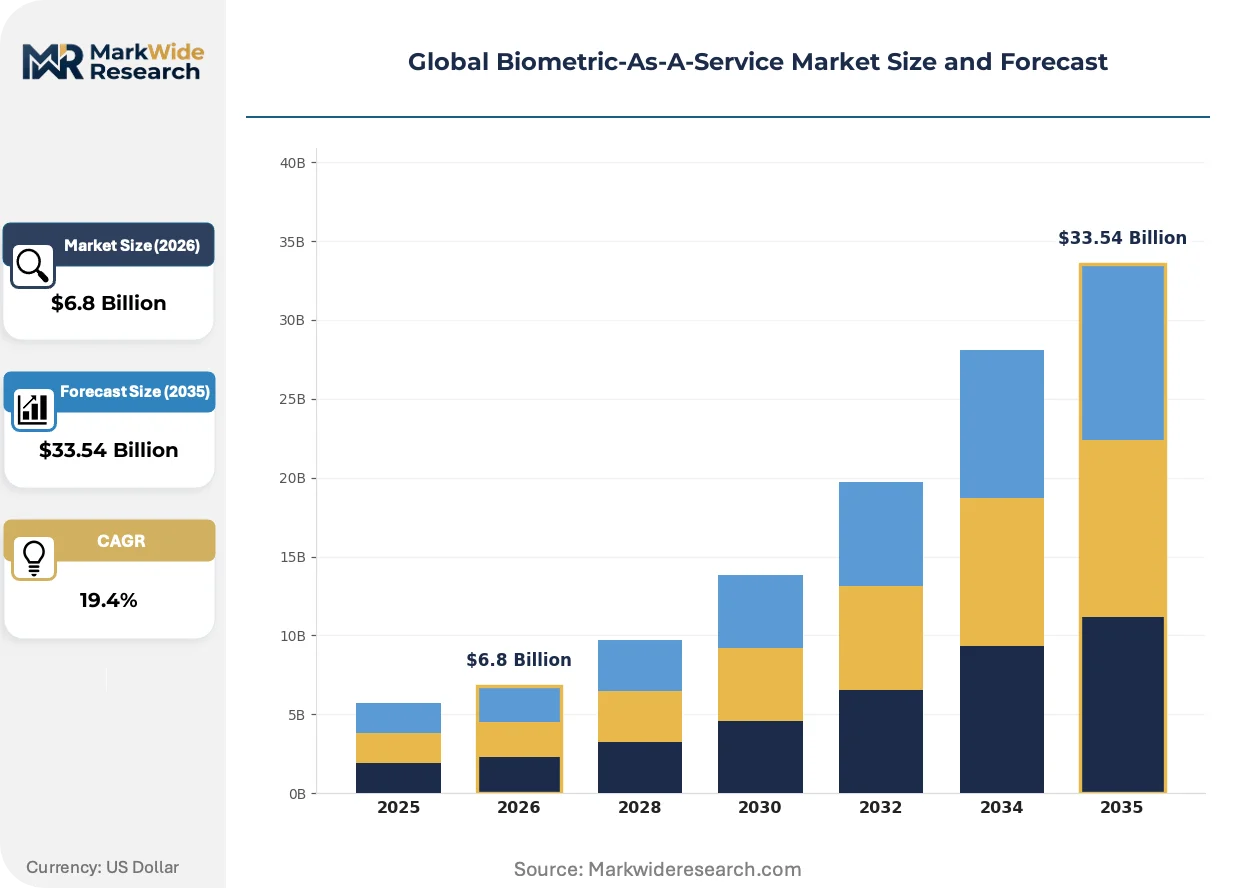
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $33.54 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Authentication Type: Fingerprint Recognition, Facial Recognition, Iris Scanning, Voice Recognition, Palm Vein Recognition Deployment Model: Cloud-Based, On-Premises, Hybrid, Edge Computing End User Industry: BFSI, Government Agencies, Telecommunications, Travel & Hospitality, Education Service Model: Identity Verification, Access Control, Fraud Detection, Employee Attendance, Customer Authentication |
| Companies Covered | NEC Corporation, Thales Group, Leidos Holdings, Fujitsu Limited, Idemia, M2SYS Technology, Aware Inc., BioID, Accenture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biometric-As-A-Service Market Shifts & Advancements
Multimodal fusion architectures are collapsing the distinction between authentication and continuous identity verification, embedding biometric checkpoints throughout user journeys rather than isolating them at session start.
Edge-native biometric SDKs are unifying on-device template matching with cloud-based enrollment, eliminating round-trip latency for facial recognition in autonomous vehicle cabin access. Automotive OEMs in Germany and Japan are specifying sub-200-millisecond verification thresholds. This architecture is compressing infrastructure requirements for high-throughput scenarios like stadium entry and airport boarding.
The EU AI Act's risk classification system is mandating conformity assessments for remote biometric identification systems deployed in publicly accessible spaces. High-risk system providers must maintain quality management systems and human oversight protocols. Civil aviation security vendors serving Schiphol and Charles de Gaulle are restructuring product documentation to satisfy notified body review timelines.
Consumption of biometric APIs is fragmenting from enterprise annual contracts toward metered, event-based pricing aligned with transaction volumes. Fintech challengers in Nigeria and Indonesia are rejecting per-seat licensing in favor of pay-per-authentication models. This shift is most visible in embedded finance and buy-now-pay-later onboarding flows where authentication volumes spike unpredictably.
Global Biometric-As-A-Service Market Segmentation
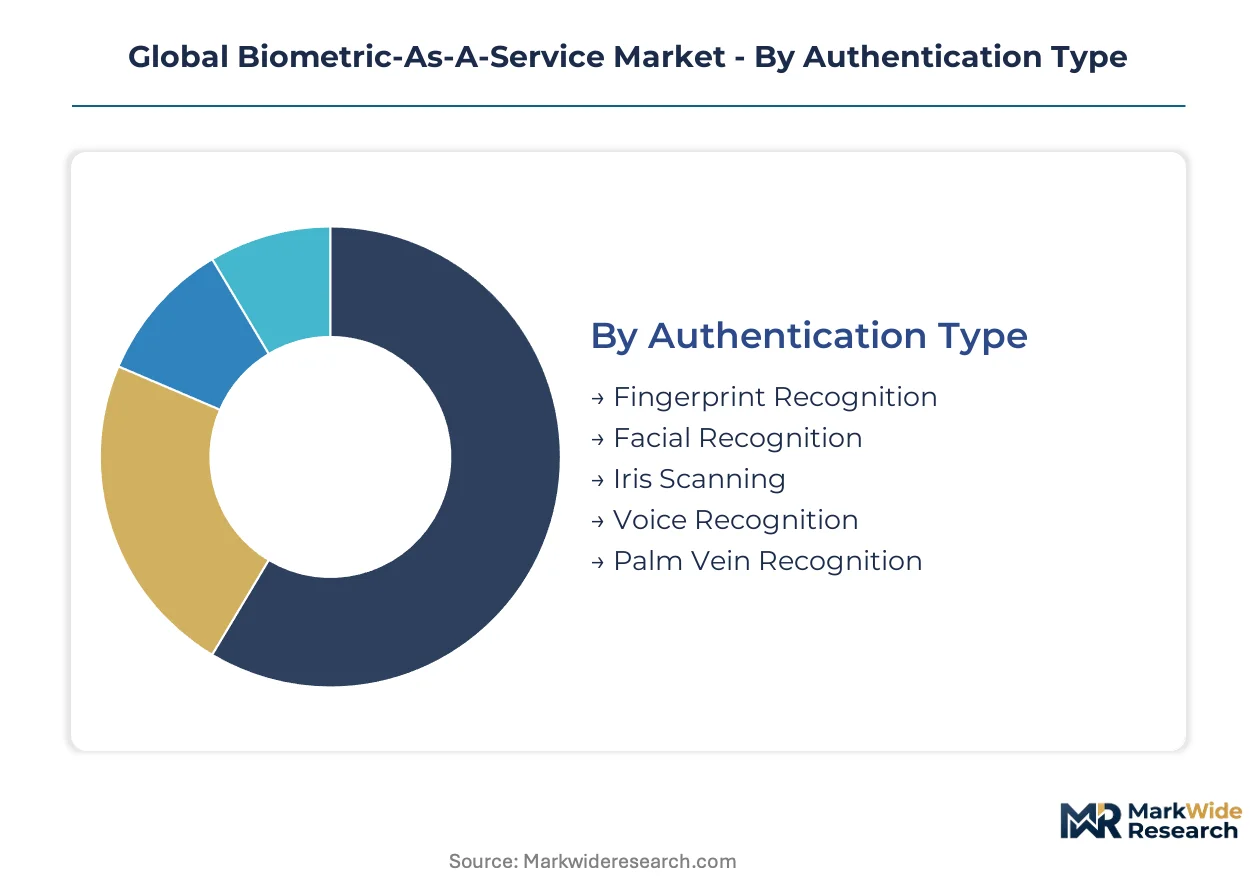
Biometric-As-A-Service segmentation reveals divergent margin profiles across authentication modalities and deployment architectures. Vendors must align R&D investment with the volume-premium trade-offs inherent in each category.
Authentication Type:
Volume concentrates in commoditized single-factor methods while premium pricing attaches to multimodal and high-assurance modalities.
- Fingerprint Recognition:Capacitive and ultrasonic sensors capture the highest transaction volumes across mobile banking and point-of-sale terminals. Demand clusters in India's rural banking expansion and Nigeria's agent networks where cost-per-authentication drives vendor selection.
- Facial Recognition:Deep learning-based liveness detection enables contactless verification at sub-500-millisecond latency thresholds. South Korea's transit authorities and Singapore's retail networks are displacing card-present authentication with 3D facial matching.
- Iris Scanning:Near-infrared acquisition systems command premium pricing in cross-border travel corridors. Schiphol and Charles de Gaulle deployments prioritize presentation attack resistance over cost optimization.
- Voice Recognition:Text-independent speaker verification integrates with conversational AI agents for telebanking authentication. MFDS certification requirements in South Korea shape algorithm training protocols.
- Palm Vein Recognition:Near-infrared palm geometry offers contactless hygiene advantages over fingerprint systems. Japan's METI standards and Saudi Arabia's NEOM smart city specifications drive specification-grade demand.
Today's leader: Facial Recognition. Tomorrow's challenger: Palm Vein Recognition.
Deployment Model:
Latency requirements and data sovereignty constraints fragment deployment preferences across regulated industries.
- Cloud-Based:API-delivered authentication scales elastically with transaction spikes in buy-now-pay-later onboarding. Frankfurt and Dublin availability zones satisfy GDPR Article 9 residency mandates for EU financial institutions.
- On-Premises:Dedicated hardware deployments persist in defense and intelligence applications with air-gapped security requirements. Germany's BSI certification and India's UIDAI framework mandate localized template storage for national ID systems.
- Hybrid:Split architectures enroll templates centrally while matching at edge nodes. Brazil's national civil identification tender specifies hybrid models to balance latency against centralized audit requirements.
- Edge Computing:On-device template matching eliminates round-trip latency for automotive cabin access and stadium entry. German and Japanese OEMs specify sub-200-millisecond verification thresholds for autonomous vehicle applications.
Cloud-Based deployments gain share fastest in financial services, while Edge Computing climbs fastest in transportation and smart city infrastructure.
End User Industry:
Regulatory intensity and transaction volume shape industry-specific authentication requirements and vendor procurement criteria.
- BFSI:Real-time payment authentication and account recovery workflows drive API consumption. RBI guidelines in India and PSD2 in Europe mandate strong customer authentication with biometric fallback options.
- Government Agencies:National ID systems and voter registration demand multimodal enrollment at population scale. UIDAI in India and Brazil's civil identification program create sustained infrastructure demand.
- Telecommunications:SIM registration and mobile wallet onboarding require low-friction identity verification. TRAI regulations in India and Nigeria's NCC directives mandate biometric subscriber verification.
- Travel & Hospitality:Self-service bag drop and hospitality access control prioritize throughput over forensic accuracy. IATA One ID specifications and EU EES border systems drive interoperability requirements.
- Education:Examination proctoring and campus access control represent emerging demand with price-sensitive procurement. India's NTA and Brazil's ENEM specify remote biometric verification for high-stakes testing.
BFSI commands current revenue concentration. Government Agencies present the steepest expansion trajectory through national digital ID mandates.
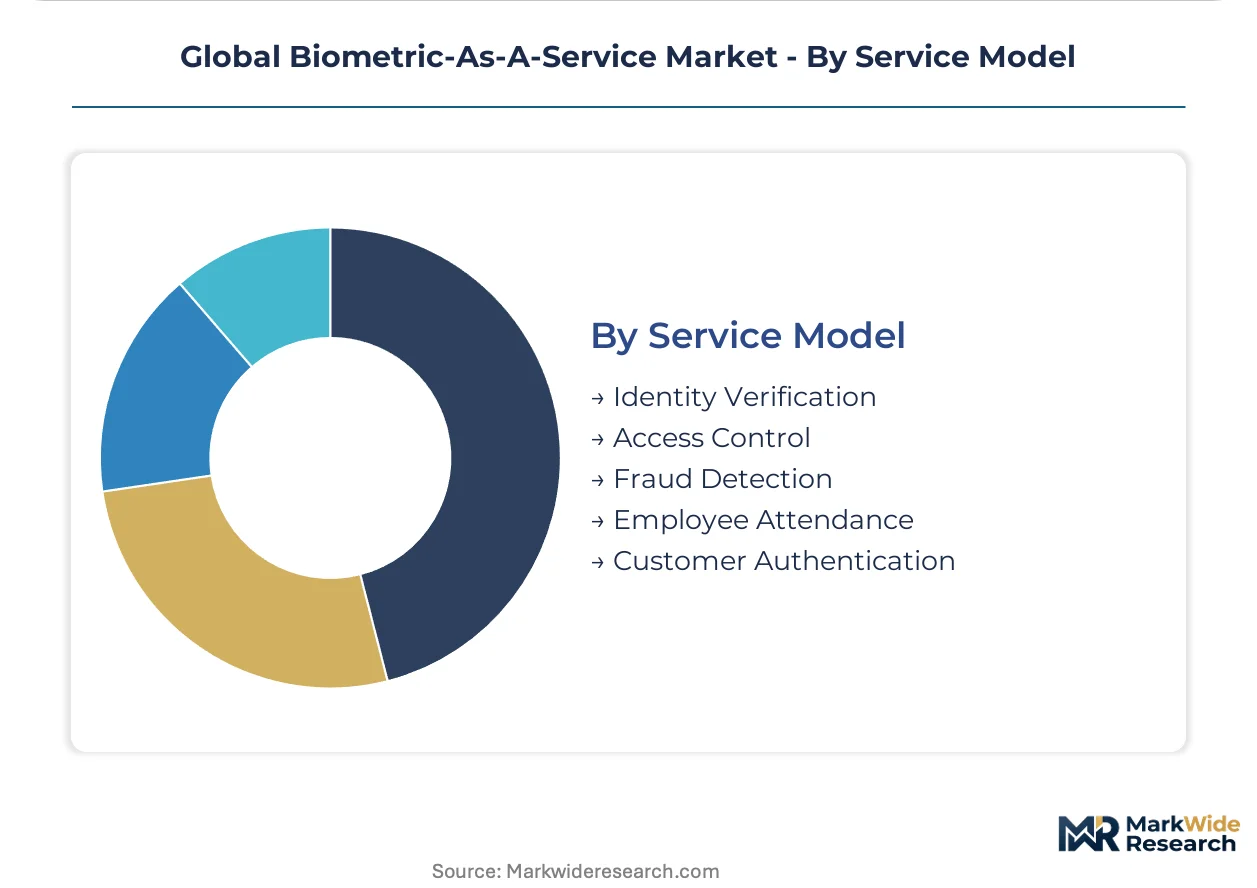
Service Model:
Pricing architecture shifts from per-seat licensing toward metered consumption aligned with transaction volatility.
- Identity Verification:Document-to-biometric matching anchors customer onboarding for fintech challengers. Indonesia's OJK regulations and Nigeria's CBN guidelines mandate tiered verification by transaction risk.
- Access Control:Physical and logical access convergence drives multimodal template management. Saudi Arabia's PDPL and UAE's NESA standards govern critical infrastructure biometric deployments.
- Fraud Detection:Behavioral biometrics and liveness detection reduce synthetic identity losses. EU AI Act high-risk system classifications mandate human oversight protocols for remote biometric identification.
- Employee Attendance:Workforce management applications prioritize cost efficiency over presentation attack resistance. India's EPF Organization and Brazil's public sector timekeeping reforms drive volume demand.
- Customer Authentication:Passwordless login and step-up authentication integrate with CIAM platforms. FIDO Alliance certification and NIST SP 800-63B guidelines shape technical specifications.
Identity Verification leads current contract value. Fraud Detection represents the fastest-climbing segment as synthetic identity attacks escalate across digital channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biometric engineering talent clusters in Bangalore, Frankfurt, and Seoul anchor cloud-native identity infrastructure development across three continents.
United States
NIST biometric testing protocols and DHS border modernization programs drive federal procurement. The Transportation Security Administration mandates facial recognition at 16 major airports. Seattle and Austin house cloud-native identity startups serving fintech and healthcare verticals.
Germany
BSI certification requirements and EU AI Act conformity assessments reshape vendor selection for banking and automotive applications. Bavaria's automotive OEMs specify sub-200-millisecond edge verification for cabin access systems. Frankfurt availability zones satisfy GDPR Article 9 data residency mandates.
India
UIDAI framework integration and rural banking expansion create sustained API volume demand. The Reserve Bank of India mandates biometric authentication for payment systems above specified thresholds. Hyderabad and Bengaluru host the largest concentration of Aadhaar-integrated service developers.
Saudi Arabia
Vision 2030 smart city specifications and PDPL compliance requirements drive multimodal access control procurement. NEOM and Red Sea Project developments specify biometric hospitality and logistics zone management. Riyadh anchors government digital transformation contracting.
South Korea
MFDS certification for voice biometrics and transit authority facial recognition deployments lead adoption. Seoul's metropolitan rail network operates contactless palm vein terminals at 280 stations. Pangyo Techno Valley houses liveness detection algorithm specialists serving financial services.
Global Biometric-As-A-Service Market Competitive Landscape
Top-tier vendors anchor government and civil aviation contracts, while mid-tier specialists compete on API flexibility and regional compliance expertise. The vendor base segments across three strategic archetypes: legacy defense integrators with biometric divisions, cloud-native platform builders, and component specialists focused on presentation attack detection. Competitive moves concentrate on strategic partnerships with hyperscale cloud providers and geographic expansion through regulatory certification stacking.
Within the government-contracting tier, NEC Corporation, Thales Group, and Idemia exemplify divergent anchoring strategies. NEC leverages long-standing relationships with national ID authorities across multiple continents. Thales integrates biometric modules with civil aviation security infrastructure at major European hubs. Idemia controls end-to-end credentialing workflows spanning enrollment, template management, and document personalization. These three occupy positions that smaller cloud-native entrants cannot replicate without decade-long certification accumulation.
| Leading Market Players |
|---|
| NEC Corporation |
| Thales Group |
| Leidos Holdings |
| Fujitsu Limited |
| Idemia |
| M2SYS Technology |
| Aware Inc. |
| BioID |
| Accenture |
| Others |
Supply & Pricing Matrix
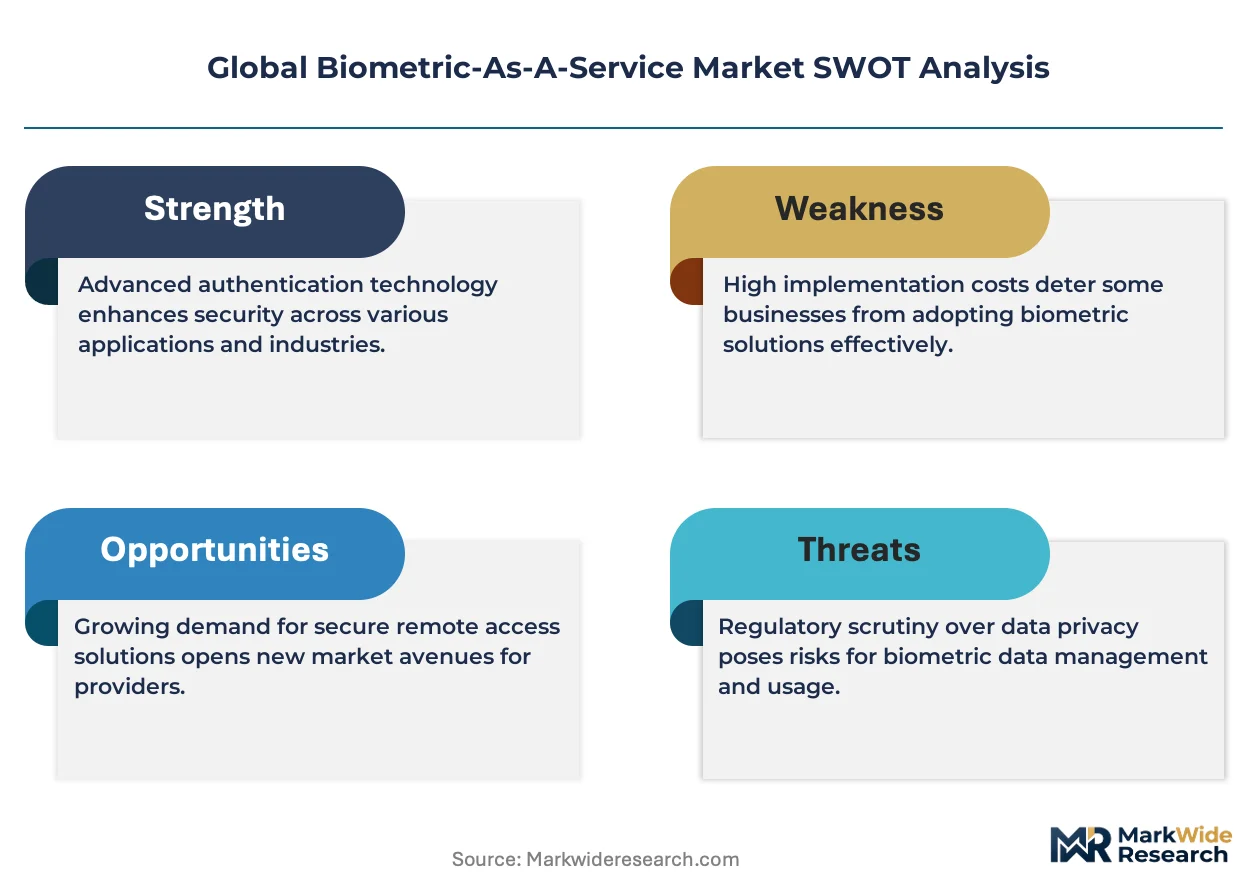
Government procurement programs for national digital ID systems anchor demand for bundled multimodal biometric platforms, compressing pricing power for unbundled single-factor API providers. This buyer concentration forces vendors to absorb certification and compliance costs within fixed-fee contract structures.
Pricing Analysis
Subscription tiers separating enrollment, matching, and liveness detection modules define the dominant pricing architecture. Premium-mid-economy pricing differentiation hinges on NIST certification tier and EU AI Act conformity assessment completion. Cost compression in facial recognition APIs is intensifying because hyperscale cloud providers bundle biometric capabilities within broader identity suites. Fintech challengers in Nigeria and Indonesia exhibit highest price sensitivity, while civil aviation security vendors at Schiphol and Charles de Gaulle prioritize presentation attack resistance over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for edge-native biometric SDKs, while API marketplaces serve metered consumption for fintech onboarding workflows. Hardware component manufacturing draws from Taiwan, South Korea, and Germany, with specialized image signal processors for iris cameras resting on Taiwan foundry allocation. Algorithm training data sourcing is anchored in US and Chinese AI lab licensing agreements. Single-source vulnerability in near-infrared sensor supply creates exposure for palm vein and iris system vendors serving Saudi Vision 2030 and Japan METI specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk system classification for remote biometric identification operates as a regulatory compounder, mandating quality management systems and human oversight protocols that inflate vendor compliance costs and consolidate procurement around certified incumbents.
For Market Incumbents: Extend certification stacking across GDPR, India's BIS, and Saudi PDPL to lock out cloud-native entrants lacking decade-long compliance accumulation. Prioritize backward integration into presentation attack detection engineering, where talent scarcity commands compensation premiums exceeding 40% above standard computer vision roles. Defensive patent positioning around liveness detection algorithms counters emerging specialists in Pangyo Techno Valley and Bangalore.
For New Entrants and Emerging Players: Capture voice biometric convergence opportunities in conversational AI agent integration, where authentication-as-a-feature pricing avoids direct competition with NEC and Thales in government contracts. Target education sector examination proctoring in India and Brazil, where price-sensitive procurement favors API-flexible mid-tier vendors over end-to-end credentialing workflows. Go-to-market through embedded finance platforms in Indonesia and Nigeria enables pay-per-authentication models that bypass incumbent per-seat licensing dominance.
For Investors and Strategic Acquirers: Hyperscale cloud providers with Frankfurt and Dublin availability zones are the most active acquirers in this space, seeking biometric capabilities to anchor identity-as-a-service bundles. Long-term viability hinges on regulatory certification moats rather than algorithmic performance alone. Acquisition target archetype: regional compliance specialists with UIDAI or BSI certification and established API volume contracts. Monitor NIST certification queue backlogs as inflection indicator for vendor product roadmap freezes and distressed asset availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Stacking | EU AI Act conformity assessments combined with BSI and UIDAI compliance lock out unqualified competitors. |
| Edge-Native SDK Development | Sub-200-millisecond verification thresholds for German and Japanese automotive OEMs eliminate round-trip latency. |
| Presentation Attack Detection Acquisition | Specialist engineering talent scarcity in liveness detection creates defensive moat against commodity facial recognition. |
| Hybrid Deployment Architecture | Brazil's national civil identification tender specifies split models balancing edge latency against centralized audit. |
| Voice Biometric Platform Integration | MFDS-certified speaker verification integrates with conversational AI agents for South Korean telebanking authentication. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Middle East, with primary inputs from each combining structured interviews with biometric platform CTOs, government digital ID procurement officers, airline security system integrators, fintech compliance leads, and cloud infrastructure architects. Secondary validation draws from NIST biometric testing protocol publications, EU AI Act implementation guidance, UIDAI technical specifications, SEC filings of publicly traded identity vendors, and hyperscaler capex disclosures for cloud availability zone expansion. Bottom-up API volume modeling and top-down national ID program budget aggregation enable cross-checking.
Granularity-level modeling captures authentication modality, deployment architecture, end-user industry, and service model dimensions at the country-regulator level. CAGRs were derived through logarithmic trend fitting across the projection horizon, with biometric transaction volume elasticity to digital payment adoption serving as primary demand-side input. Supply-side constraints from Taiwan foundry capacity and NIST certification timelines anchor capacity boundary assumptions.
Underlying measurement precision varies by segment; cloud-based financial services authentication carries tighter precision than emerging education sector proctoring applications. Forecasts reflect documented assumptions around regulatory implementation timelines and silicon supply normalization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Vein Recognition Biometrics Market
Biometrics & Identity Management
Biometric Passport Market
Biometrics & Identity Management
Global Personal Identity Management Market
Biometrics & Identity Management
Palm Vein Biometrics Market
Biometrics & Identity Management
Biometrics Banking Market
Biometrics & Identity Management
Military Biometrics Market
Biometrics & Identity Management
Iris Recognition Market
Biometrics & Identity Management
Signature Verification Market
Biometrics & Identity Management
Middle East and Africa Biometrics in Government Market
Biometrics & Identity Management
Biometrics As a Service in Healthcare Market
Biometrics & Identity Management
Latin America Government & Security Biometrics Market
Biometrics & Identity Management
Biometric Smart Cards Market
Biometrics & Identity Management
Biometrics Software Market
Biometrics & Identity Management
North America Enterprise Biometrics Market
Biometrics & Identity Management
Next Generation Biometric Market
Biometrics & Identity Management
Face Voice Biometric Market