
 Asia Pacific Biometrics in Government Market | 2026-2036
Asia Pacific Biometrics in Government Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Biometrics in Government Market Outlook
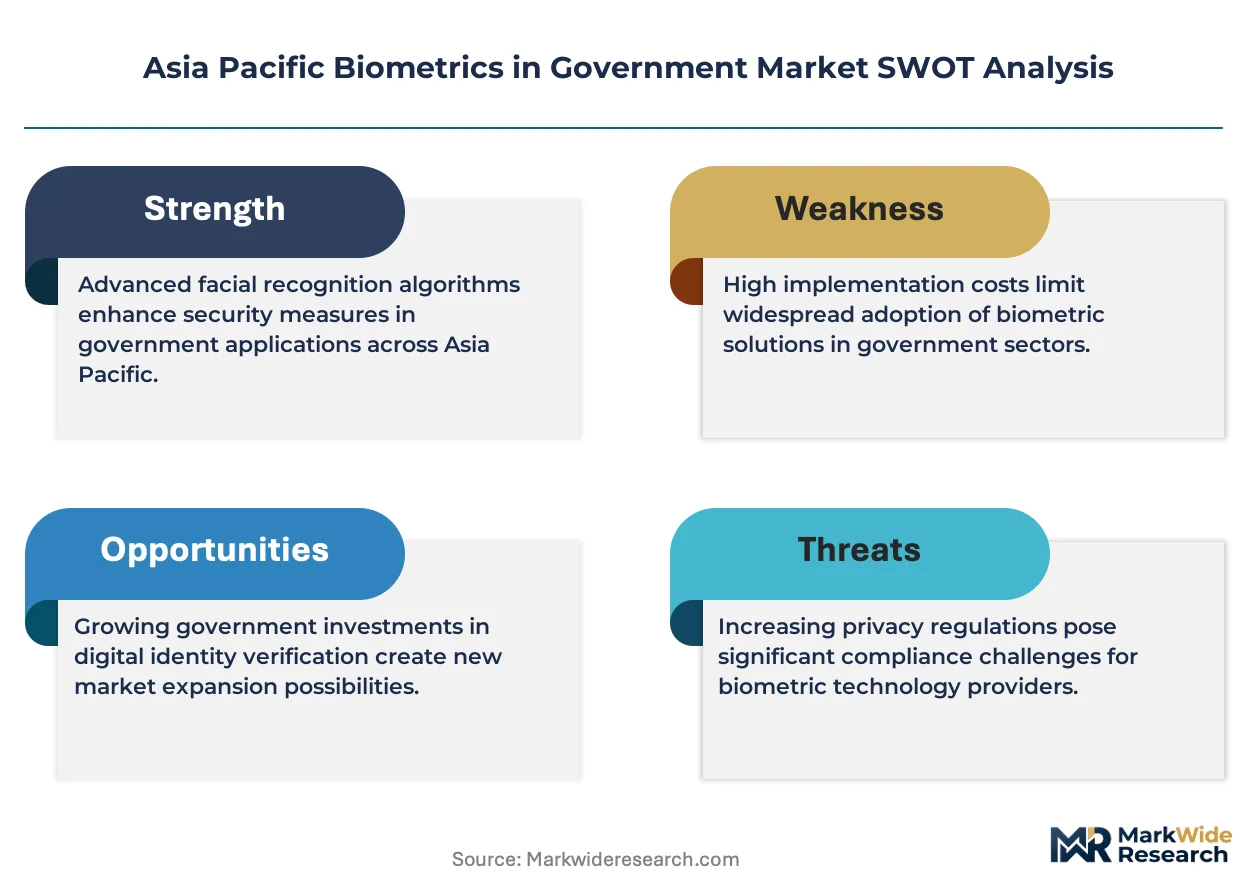
Software-defined biometric platforms with subscription-based algorithm updates is restructuring procurement patterns across government agencies. NEC Corporation leverages its long-standing fingerprint and facial recognition R&D to sustain technology leadership in large-scale national ID deployments. IDEMIA Group SAS anchors its position through integrated credentialing systems that span civil and defense applications. Fujitsu Limited competes with palm vein authentication systems that differentiate on contactless security for high-throughput environments.
Asia Pacific biometrics in government encompasses the acquisition, deployment, and operation of automated physiological and behavioral identification systems for public-sector authentication, with core specifications including ISO/IEC 19795-compliant matching accuracy thresholds and liveness detection protocols to prevent spoofing attacks. These systems serve primarily to establish trusted identity verification for citizen services, border control, and secure facility access. Fingerprint recognition retains the largest installed base among technology segments, though facial recognition is gaining fastest as contactless protocols expand across immigration checkpoints. Among end users, immigration authorities command the dominant share of procurement budgets, while defense agencies represent the highest-margin segment due to classified-environment requirements. Cloud-based deployment models are accelerating fastest where data sovereignty frameworks permit federated identity architectures.
India's UIDAI operates under Ministry of Electronics and Information Technology guidelines that mandate biometric deduplication standards shaping vendor qualification requirements. Australia's Digital Identity legislation and New Zealand's Privacy Act framework govern cross-border biometric data flows, constraining cloud deployment architectures. Japan's Personal Information Protection Commission and South Korea's Personal Information Protection Commission enforce consent and retention limits that affect system design. Stakeholders must monitor evolving data localization mandates and interoperability standards that will determine which deployment models and technology combinations gain regulatory clearance across the region.
Market Dynamics
Cloud-native biometric architectures are forcing procurement departments across Asia Pacific government agencies to abandon perpetual licensing models in favor of subscription-based algorithm consumption, restructuring vendor relationships and capital allocation patterns.
Growth Catalysts
- India's Aadhaar-linked deduplication mandate:The UIDAI's biometric deduplication standards under Ministry of Electronics and Information Technology guidelines create mandatory procurement volumes for fingerprint and iris matching infrastructure.
- Contactless border protocols:Immigration authorities across Southeast Asia are expanding facial recognition enrollment to replace physical document inspection at high-throughput checkpoints.
- Australia's Digital Identity Act:Federal legislation establishing accredited identity service providers triggers biometric infrastructure procurement across federal and state government tiers.
Market Restraints
- Data localization requirements:India's data protection framework and China's cybersecurity law mandate sovereign cloud storage, fragmenting deployment architectures and raising infrastructure costs.
- Algorithm training data scarcity:Demographic bias in facial recognition training sets limits matching accuracy for underrepresented ethnic populations across Southeast Asian populations.
- Silicon supply concentration:Edge biometric device manufacturing depends on semiconductor fabrication concentrated in Taiwan and South Korea, exposing procurement timelines to foundry capacity constraints.
Strategic Opportunities
- Vietnam's national ID modernization:The country's transition from paper-based to chip-enabled citizen identity cards creates greenfield biometric enrollment infrastructure demand.
- Behavioral biometrics convergence:Keystroke dynamics and gait analysis integration with physiological systems opens high-assurance authentication for defense and intelligence applications.
- Japan's My Number expansion:Government mandates linking social security and taxation systems to biometric verification drive civil service procurement modernization.
Industry Challenges
- Legacy system interoperability:Government agencies operate decades-old identity databases with incompatible data formats, forcing expensive middleware development for biometric system integration.
- Forensic examiner talent scarcity:Latent fingerprint and facial examination expertise required for adjudication of biometric matching results concentrates in national police forces, limiting vendor support capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Biometrics in Government Market |
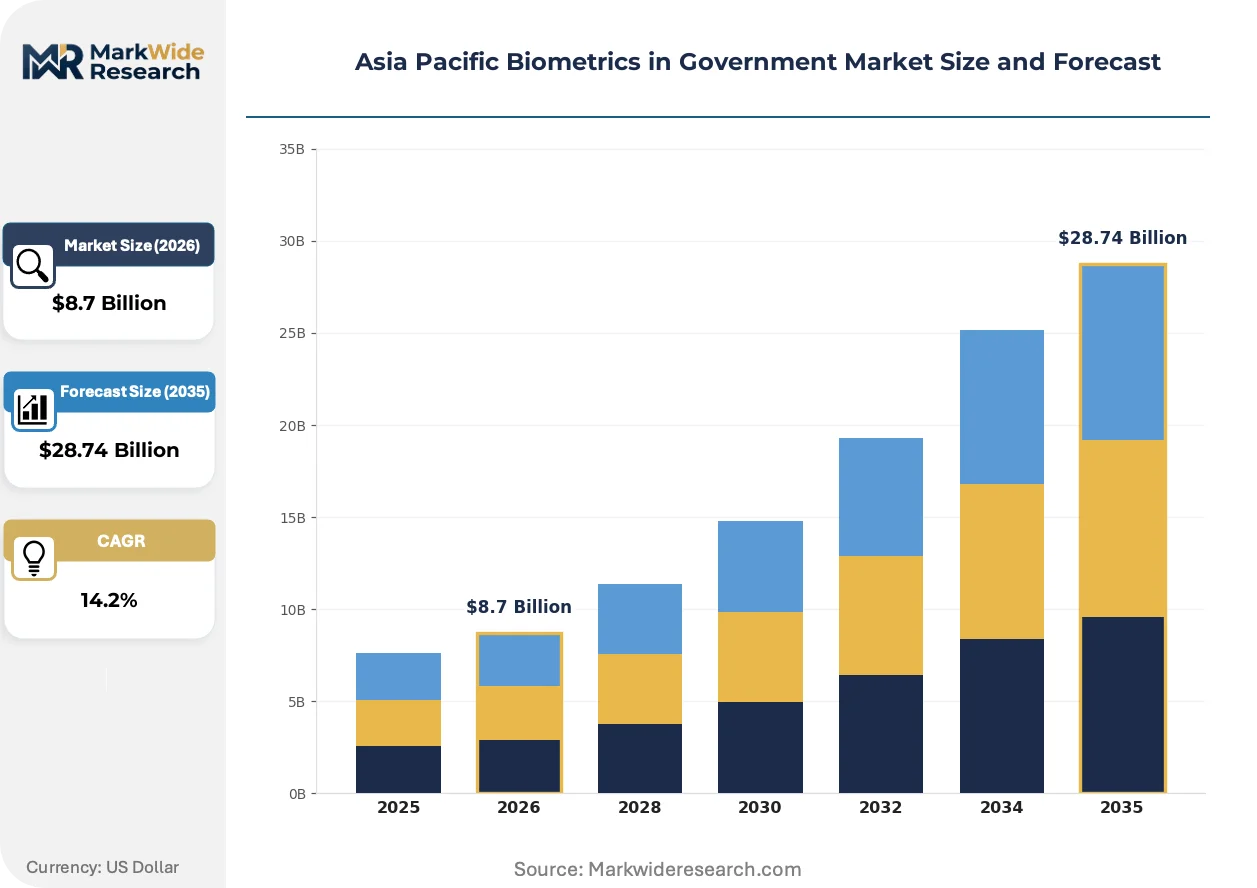
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fingerprint Recognition, Facial Recognition, Iris Recognition, Vein Pattern Recognition End User: Immigration Authorities, Law Enforcement, Defense Agencies, Regulatory Bodies Application: ID Verification, Access Control, Time & Attendance, Public Safety Deployment Model: On-Premises, Cloud-Based, Hybrid Solutions, Mobile-Based Systems |
| Companies Covered | HID Global Corporation, IDEMIA Group SAS, NEC Corporation, Precise Biometrics AB, Qualcomm Technology Inc., Fujitsu Limited, Aware Inc., Crossmatch, Thales Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Biometrics in Government Market Strategic Shifts
Artificial intelligence inference at the network edge is collapsing the latency constraints that previously centralized biometric processing, enabling real-time authentication in bandwidth-constrained environments across remote government facilities.
Multimodal biometric fusion—combining fingerprint, facial, and iris templates into unified matching scores—is rewriting accuracy benchmarks for high-security government applications. Defense agencies in Australia and classified facilities in Singapore are deploying these systems for physical access control, compressing false acceptance rates below single-modality thresholds while maintaining sub-second transaction speeds.
New Zealand's Privacy Act framework and Australia's Digital Identity legislation are tightening consent and retention requirements for biometric data storage. Government system architects must now design federated identity architectures that process templates locally while enabling cross-jurisdictional verification, favoring vendors with modular edge-deployment capabilities over centralized cloud-native platforms.
Subscription-based algorithm licensing is displacing perpetual software purchases across immigration and civil registry departments. Australia's Department of Home Affairs and India's state-level registrars now negotiate consumption-based contracts with automatic accuracy updates, transferring technology obsolescence risk from agency capital budgets to vendor operational commitments.
Asia Pacific Biometrics in Government Market Segmentation
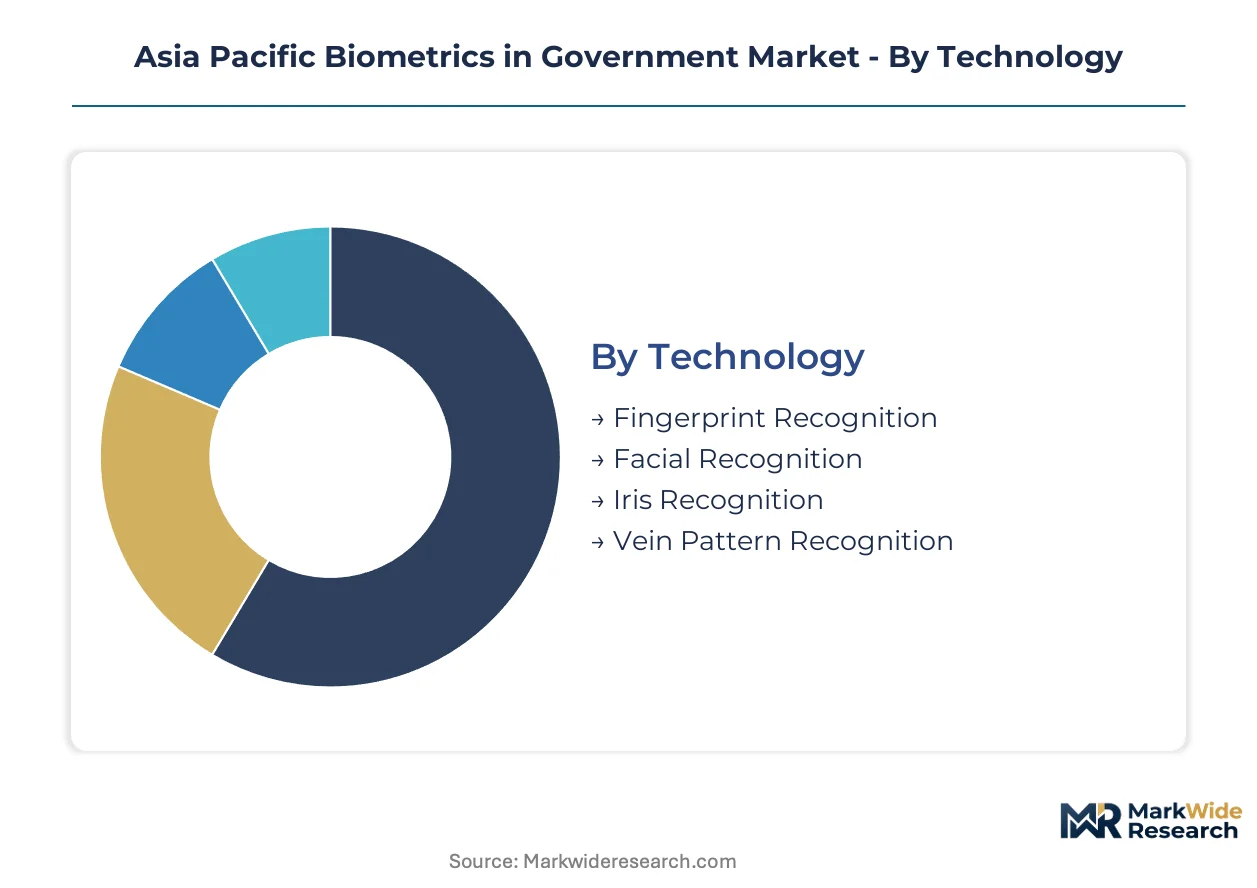
Biometric procurement across Asia Pacific government agencies fragments across four intersecting dimensions. Technology choices determine hardware lifecycle costs, while deployment models constrain data sovereignty compliance. End-user priorities and application criticality further reshape vendor selection criteria.
Technology:
Volume concentrates in legacy fingerprint infrastructure, though premium contracts flow to multimodal and contactless systems.
- Facial Recognition:Contactless capture systems using 2D and 3D imaging arrays enable high-throughput authentication without physical sensor contact. Immigration checkpoints across Southeast Asia and Australia's SmartGates deploy these systems where throughput speed overrides per-unit cost sensitivity.
- Fingerprint Recognition:Optical and capacitive sensors matching ISO/IEC 19795-2 templates retain the largest installed base across civil registries and national ID programs. India's UIDAI deduplication infrastructure and Indonesia's e-KTP system anchor procurement volumes, though sensor wear and hygiene concerns constrain new deployments.
- Iris Recognition:Near-infrared imaging of unique trabecular mesh patterns delivers the lowest false match rates among single modalities. UIDAI's enrollment stations and high-security defense facilities in Singapore deploy these systems where accuracy thresholds justify hardware premiums.
- Vein Pattern Recognition:Near-infrared transillumination of subcutaneous vascular structures enables contactless authentication with liveness detection. Japan's financial and government facilities favor Fujitsu's palm vein systems for physical access control in humidity-sensitive environments.
Today's leader: Fingerprint Recognition. Tomorrow's challenger: Facial Recognition.
End User:
Application maturity separates established civil registries from emerging defense and intelligence procurement.
- Immigration Authorities:Border management agencies command the dominant procurement share across the region. Australia's Department of Home Affairs and Singapore's Immigration and Checkpoints Authority drive facial recognition enrollment at air and seaport terminals, with contracts bundling hardware, software, and algorithm update subscriptions.
- Defense Agencies:Classified facility access and battlefield identity verification generate the highest-margin contracts. Australia's Defence Department and Singapore's Ministry of Defence demand multimodal fusion systems with air-gapped deployment and tamper-evident hardware modules.
- Law Enforcement:Criminal identification and forensic matching applications concentrate in national police forces. India's National Crime Records Bureau and Japan's National Police Agency operate latent fingerprint and facial examination laboratories requiring specialized adjudication workstations.
- Regulatory Bodies:Civil registry and social welfare agencies deploy biometric verification for service delivery authentication. India's state-level registrars and Vietnam's national ID modernization program drive enrollment infrastructure demand with cost-optimized specifications.
Immigration Authorities capture current procurement volume. Defense Agencies command margin expansion.
Application:
Identity assurance requirements stratify across civil, security, and administrative use cases.
- ID Verification:Biometric deduplication and authentication for citizen service enrollment and delivery. India's Aadhaar ecosystem and Indonesia's e-KTP program anchor this segment with billion-scale template databases.
- Access Control:Physical and logical entry authentication for government facilities and classified networks. Australia's Parliament House and Singapore's ministries deploy multimodal systems with liveness detection for high-assurance environments.
- Public Safety:Real-time identification and watchlist matching for law enforcement and emergency response. Thailand's Royal Thai Police and Philippines' law enforcement agencies pilot facial recognition in urban surveillance deployments.
- Time & Attendance:Workforce verification for civil service payroll integrity. State government offices across India and Malaysia implement fingerprint-based systems with anti-spoofing protocols.
ID Verification dominates transaction volume. Access Control climbs fastest on security premiumization.
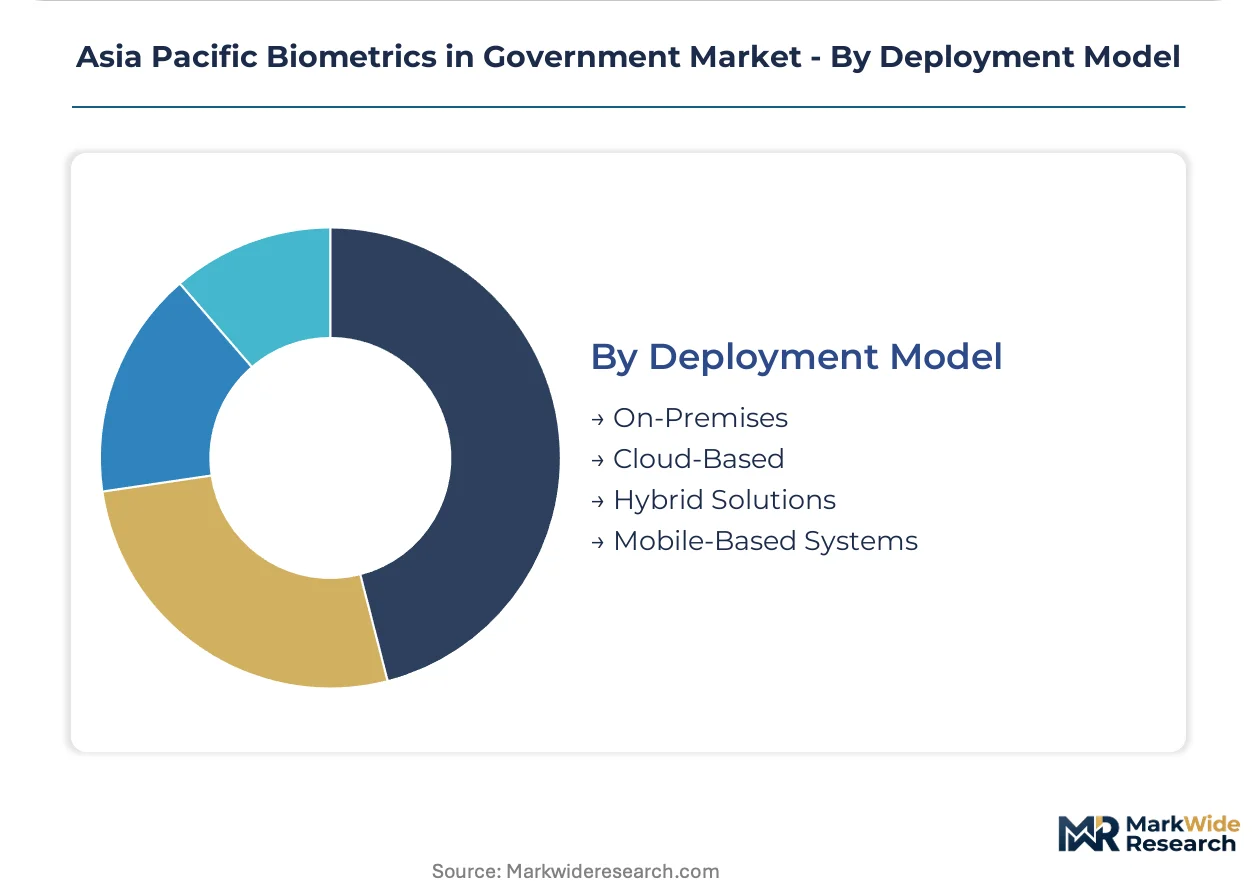
Deployment Model:
Data sovereignty frameworks fragment architecture choices across sovereign, federated, and portable configurations.
- On-Premises:Dedicated infrastructure within government data centers with full operational control. India's data localization mandates and China's cybersecurity law require this model for citizen biometric databases, constraining cloud migration despite higher capital intensity.
- Cloud-Based:Federated identity architectures with template processing at sovereign cloud nodes. Australia's Digital Identity legislation enables accredited private providers to host verification services, accelerating subscription-based procurement in that market.
- Hybrid Solutions:Edge enrollment with centralized matching, or tiered storage separating templates from demographic records. New Zealand's Privacy Act framework and Japan's Personal Information Protection Commission guidelines favor this architecture for cross-jurisdictional verification.
- Mobile-Based Systems:Portable biometric capture for field enrollment, election monitoring, and disaster response. India's election commission and Philippines' civil registry deploy tablet-based fingerprint and facial capture for remote population coverage.
On-Premises retains regulatory default. Cloud-Based gains where federated legislation permits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are concentrating biometric procurement in jurisdictions with federated identity legislation, where vendors face lower compliance costs than in data-sovereignty-restrictive markets. Australia's Digital Identity Act and India's UIDAI framework create divergent deployment architectures across the region.
Australia
The Digital Identity legislation mandates accredited identity service providers, triggering biometric infrastructure procurement across federal and state tiers. The Department of Home Affairs operates under this framework to expand facial recognition enrollment at air and seaports. Sydney and Melbourne anchor deployment concentration for high-throughput immigration checkpoints.
India
UIDAI's deduplication standards under Ministry of Electronics and Information Technology guidelines create mandatory procurement volumes for fingerprint and iris matching systems. The Aadhaar-linked digital identity framework shapes vendor qualification requirements nationwide. State-level registrars in Maharashtra and Karnataka drive cost-optimized enrollment infrastructure demand.
Japan
My Number expansion mandates linking social security and taxation systems to biometric verification, driving civil service procurement modernization. The Personal Information Protection Commission enforces consent and retention limits that affect system design specifications. Tokyo and Osaka metropolitan governments lead physical access control deployments for government facilities.
Singapore
The Immigration and Checkpoints Authority drives facial recognition enrollment at seaport and airport terminals with bundled hardware-software-algorithm contracts. Defense agencies demand multimodal fusion systems with air-gapped deployment for classified facilities. The city-state's smart nation initiative concentrates procurement in integrated credentialing systems.
Vietnam
National ID modernization from paper-based to chip-enabled citizen identity cards creates greenfield biometric enrollment infrastructure demand. The Ministry of Public Security governs procurement specifications for civil registry digitization. Ho Chi Minh City and Hanoi anchor enrollment station deployment for remote population coverage.
Asia Pacific Biometrics in Government Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated credentialing providers commanding premium positions in defense and immigration applications while hardware-focused vendors compete on sensor cost in civil registry deployments. The vendor base concentrates around three strategic archetypes: multinational technology conglomerates with long-standing biometric R&D, specialized identity solution providers with integrated software-hardware portfolios, and semiconductor firms supplying edge-processing components for mobile capture devices. Dominant competitive moves include strategic partnerships between algorithm developers and systems integrators, plus geographic expansion through local accreditation in data-sovereignty-restrictive markets.
Among Japan-based technology conglomerates, NEC Corporation and Fujitsu Limited occupy positions as archetypal integrated solution providers with decades of physiological identification research heritage. IDEMIA Group SAS represents the European specialist tier with credentialing systems spanning civil and defense applications. These three entities exemplify contrasting approaches to procurement restructuring: subscription-based algorithm licensing, multimodal fusion system deployment, and contactless authentication hardware differentiation.
| Leading Market Players |
|---|
| HID Global Corporation |
| IDEMIA Group SAS |
| NEC Corporation |
| Precise Biometrics AB |
| Qualcomm Technology Inc. |
| Fujitsu Limited |
| Aware Inc. |
| Crossmatch |
| Thales Group |
| Others |
Value Chain & Pricing Dynamics
Semiconductor fabrication costs for edge biometric processors flow from Taiwan and South Korea foundries through tiered pricing structures downstream, with sensor module integrators in China and Japan capturing margin layers before systems reach government procurement departments across India and Australia.
Pricing Analysis
Direct-to-agency contracts bypass distributor markups for large-scale national ID deployments, while state-level registrars in India negotiate through systems integrators adding margin layers. Subscription-based algorithm licensing dominates Australia's Digital Identity framework, separating premium multimodal fusion systems from cost-optimized fingerprint enrollment stations. Price differentiation stems from ISO/IEC 19795 certification tiers and after-sales algorithm update bundling. Margins are tightening in civil registry segments as Vietnam's national ID modernization drives volume procurement with compressed hardware specifications.
Supply Chain Analysis
Near-infrared imaging sensors for iris and vein recognition rest on Japanese optical component manufacturers and German precision lens fabricators, with final assembly concentrating in China and Malaysia. Raw material dependencies span silicon wafers, specialty glass substrates, and biometric-grade plastics. Single-source vulnerability concentrates in CMOS sensor fabrication, where foundry capacity constraints in Taiwan extend procurement timelines for immigration checkpoint deployments. Distribution runs through accredited systems integrators holding UIDAI or Australia's Digital Identity provider certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory mandate stacking, with India's Aadhaar deduplication standards and Australia's Digital Identity Act creating successive procurement waves that outpace discretionary technology spending cycles.
For Market Incumbents: Anchor market position through backward integration into edge processor design, reducing foundry dependency exposure. Deepen certification moats by securing UIDAI algorithm accreditation and Australia's Digital Identity provider status ahead of competitor qualification rounds. Defensive patent positioning around multimodal fusion architectures protects margin tiers as behavioral biometrics convergence accelerates.
For New Entrants and Emerging Players: Begin with Vietnam's greenfield national ID modernization, where incumbent relationships remain unformed and procurement specifications favor cost-competitive hardware over legacy algorithm portfolios. Target mobile-based enrollment systems for India's election commission and Philippines civil registry, segments where portable biometric capture demand outstacks specialized vendor capacity. Pursue channel partnerships with accredited systems integrators rather than direct agency sales.
For Investors and Strategic Acquirers: Consolidation pressure builds where algorithm subscription models concentrate recurring revenue with vendors holding dual civil-defense accreditation. Long-term viability favors platforms with federated identity architecture capabilities spanning data-sovereignty-restrictive and permissive jurisdictions. Acquisition targets with modular edge-deployment modules and existing UIDAI or Australia Digital Identity accreditation warrant priority evaluation. Watch India's data localization enforcement intensity as inflection signal for cloud-native versus on-premises deployment model winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Subscription Licensing | Shifts technology obsolescence risk from agency capital budgets to vendor operational commitments across Australia's Department of Home Affairs. |
| Multimodal Fusion System Deployment | Compresses false acceptance rates below single-modality thresholds for Singapore's classified defense facilities. |
| Local Accreditation Expansion | Enables market access in India's data-sovereignty-restrictive procurement environment where foreign cloud hosting faces prohibition. |
| Edge Processor Design Integration | Reduces foundry dependency exposure for Taiwan and South Korea semiconductor supply concentration. |
| Behavioral Biometrics R&D Partnership | Opens high-assurance authentication for defense and intelligence applications through keystroke dynamics and gait analysis convergence. |
Study Parameters
Multiple input streams — procurement documentation from India's UIDAI and Australia's Digital Identity framework, vendor technical specifications, and regulatory filing analysis — were reconciled through structured primary interviews with biometric systems procurement officers, national ID program directors, and defense security architects, validated against secondary sources including UIDAI annual reports, Australian Digital Identity legislation transcripts, and ISO/IEC 19795 compliance documentation. Bottom-up enrollment infrastructure unit economics were triangulated against top-down government IT expenditure forecasts.
Historical deployment trajectories in India's Aadhaar ecosystem and Singapore's Immigration and Checkpoints Authority were cross-referenced against expert panel inputs on Vietnam's national ID modernization and Japan's My Number expansion timelines. The analytical framework modeled technology, end user, application, and deployment model dimensions across the projection horizon. CAGRs were derived from algorithm licensing revenue run-rates and hardware shipment volumes, with sensitivity testing against data localization enforcement scenarios and foundry capacity constraint probabilities.
Several conditions sit outside the modeled scope, including sudden export control restrictions on biometric-grade semiconductors, unanticipated Privacy Act amendments in New Zealand or Australia, and breakthrough non-biometric authentication technologies. Forecasts reflect assumptions about regulatory continuity and sovereign cloud infrastructure buildout pacing. A small set of named triggers — India's data protection enforcement intensity, Vietnam's procurement award timing, and Taiwan foundry capacity allocation shifts — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Identity Theft Protection Services Market
Biometrics & Identity Management
Gait Biometrics Market
Biometrics & Identity Management
Global Biometric Authentication Identification Market
Biometrics & Identity Management
Mobile Devices User Authentication Services Market
Biometrics & Identity Management
Europe Biometrics in Government Market
Biometrics & Identity Management
Next Generation Biometric Market
Biometrics & Identity Management
Palm Vein Biometrics Market
Biometrics & Identity Management
Asia-Pacific Government and Security Biometrics Market
Biometrics & Identity Management
Global Biometric Systems Market
Biometrics & Identity Management
Middle East and Africa Biometrics in Government Market
Biometrics & Identity Management
Biometric Point-Of-Sale Terminals Market
Biometrics & Identity Management
Biometric Smart Cards Market
Biometrics & Identity Management
Germany Identity Verification and Authentication Market
Biometrics & Identity Management
Global Mobile User Authentication Market
Biometrics & Identity Management
Europe Enterprise Biometrics Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Market