
 Europe Biodegradable Food Service Disposables Market | 2026-2036
Europe Biodegradable Food Service Disposables Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Biodegradable Food Service Disposables Market Intelligence
A capital-intensity divergence between integrated pulp molders and specialty converters is reorganizing competitive tiers across the European biodegradable disposables sector. Huhtamaki Group leverages its Nordic fiber-forming infrastructure to supply major quick-service chains across Northern Europe. Vegware anchors its position through Edinburgh-based compostable packaging R&D and direct relationships with independent foodservice operators. Biopac (U.K.) Ltd competes through specialized bagasse plate manufacturing serving British catering distributors.
Biodegradable food service disposables comprise single-use serviceware engineered from plant-derived substrates—typically polylactic acid, sugarcane bagasse, or palm leaf sheaths—that decompose under industrial composting conditions within 90 to 180 days. These products serve the foodservice industry's need for hygienic, low-carbon alternatives to petroleum-based plastics across dine-in, takeaway, and event catering applications. PLA-based cutlery commands premium positioning due to crystallinity improvements that extend heat tolerance above 85 degrees Celsius, while bagasse plates dominate volume throughput in price-sensitive institutional catering channels. Bamboo straws occupy niche artisan positioning within specialty coffee and beverage segments where tactile differentiation supports brand storytelling.
The EU Single-Use Plastics Directive, enforced by member state environmental agencies, mandates elimination of conventional plastic plates and cutlery, directly redirecting procurement budgets toward certified compostable substitutes. ECHA's REACH framework governs chemical migration limits from bio-based coatings, creating compliance thresholds that favor larger manufacturers with dedicated regulatory affairs functions. France's AGEC law extends producer responsibility to tableware, requiring recyclability or compostability labeling that shapes retailer assortment decisions. Stakeholders must monitor evolving industrial composting capacity gaps between regulation-driven demand and actual anaerobic digestion infrastructure deployment across European municipalities.
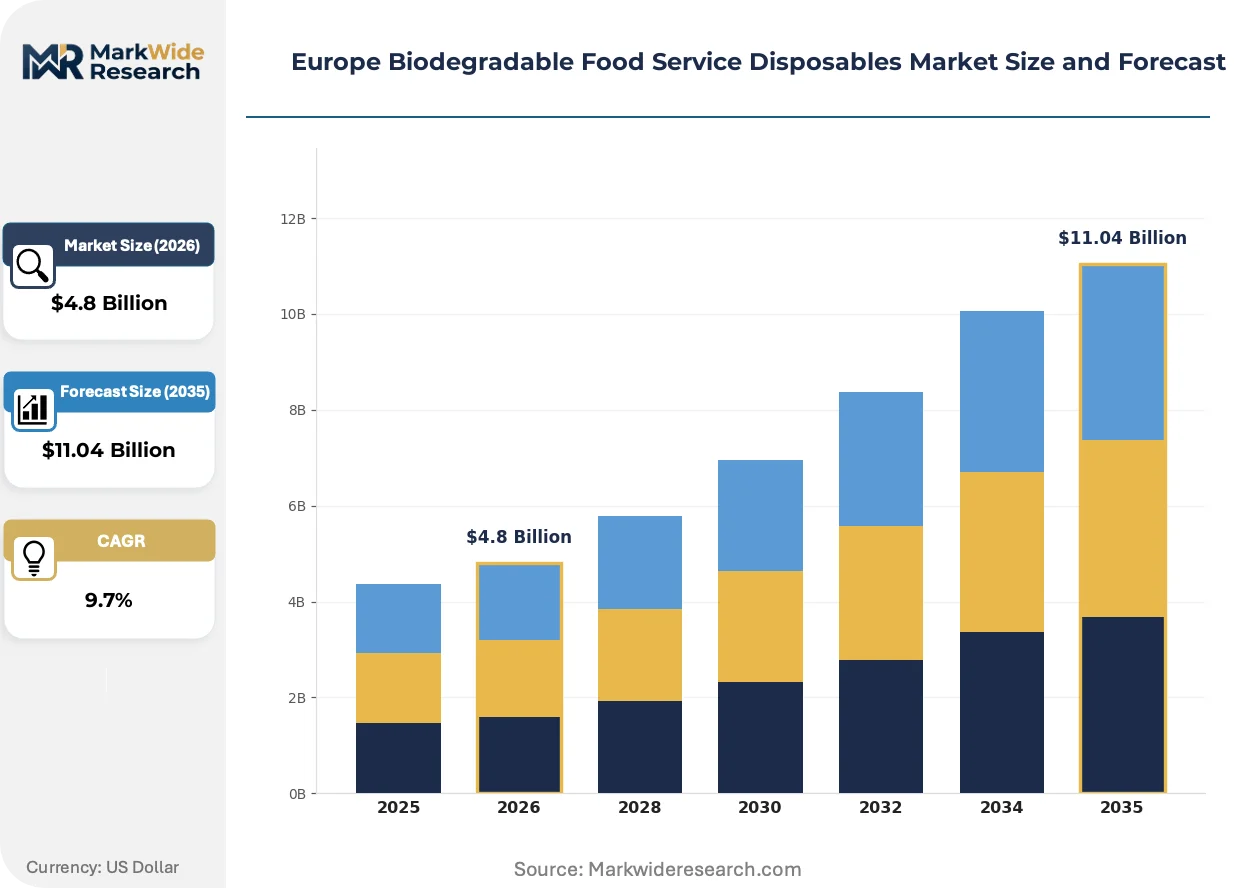
Market Dynamics
The EU Single-Use Plastics Directive is compressing procurement timelines across European foodservice supply chains, forcing distributors to requalify entire product portfolios within compressed windows that favor pre-certified manufacturers with established compostability documentation.
Growth Catalysts
- REACH chemical migration standards:ECHA's tightened thresholds for bio-based coatings are filtering out uncertified imports, redirecting volume toward compliant domestic converters with dedicated testing laboratories.
- Quick-service restaurant procurement mandates:Major chains across Germany and France now require compostable serviceware in all new supplier agreements, eliminating conventional plastic from tender processes.
- Bagasse fiber availability:Expanded sugarcane processing capacity in Southern Europe is stabilizing pulp input costs for molded plate manufacturers serving institutional catering channels.
Market Restraints
- PLA resin price volatility:Polylactic acid feedstock costs fluctuate with corn starch markets, compressing margins for cutlery specialists without long-term supply contracts.
- Industrial composting infrastructure gaps:Anaerobic digestion capacity in Eastern European municipalities lags regulation-driven demand, creating end-of-life uncertainty that dampens buyer confidence.
- Conventional plastic residual stocks:Pre-ban inventory liquidation by distributors is temporarily undercutting certified compostable pricing in price-sensitive contract catering segments.
Strategic Opportunities
- AGEC law labeling requirements:France's extended producer responsibility framework creates first-mover advantage for suppliers with pre-validated recyclability documentation.
- Palm leaf sheath applications:Untapped artisan positioning in specialty coffee segments offers premium pricing for tactile-differentiated serveware with origin storytelling.
- Direct-to-operator digital platforms:Independent restaurant purchasing cooperatives are consolidating procurement volume, enabling bypass of traditional distribution markups.
Industry Challenges
- Compostability certification timelines:TÜV Austria and DIN CERTCO validation cycles extend 14-18 months, delaying product launches and freezing working capital in pre-revenue inventory.
- Coating formulation expertise scarcity:Industrial chemists with bio-based barrier coating experience command premium compensation, constraining R&D throughput at mid-scale converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Biodegradable Food Service Disposables Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Bowls, Cutlery, Straws Material: PLA, Bagasse, Bamboo, Palm Leaf End User: Restaurants, Catering Services, Events, Food Trucks Distribution Channel: Online Retail, Supermarkets, Wholesale, Direct Sales |
| Companies Covered | Huhtamaki Group, Biopac (U.K.) Ltd, Bionatic GmbH & Co. KG, I.L.P.A. S.p.A. Group, Gold Plast S.p.A, The Jim Pattison Group, Vegware, Bunzl plc, Graphic Packaging International, L.L.C., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Biodegradable Food Service Disposables Market Strategic Shifts & Innovations
Material science advances and enforcement tightening are reconfiguring competitive advantage around heat performance, end-of-life verification, and supply chain transparency rather than unit cost alone.
Crystallinity-enhanced PLA formulations are decomposing the historical trade-off between biodegradability and thermal resistance in cutlery applications. Quick-service chains in the Netherlands and Belgium are adopting these grades for hot beverage lids and soup containers previously reserved for petroleum-based plastics. The technology is decomposing legacy material segmentation between dine-in and takeaway applications.
France's AGEC law and Germany's Packaging Act amendments are mandating standardized compostability labeling that transcends voluntary industry schemes. Retailers are delisting products without certified markings, consolidating shelf space toward pre-qualified suppliers. Independent foodservice operators in Paris and Berlin metropolitan corridors are responding by consolidating purchasing through verified distributor networks.
Buyer certification preference is hardening into explicit tender requirements that displace price-only evaluation. Contract caterers serving corporate campuses and event venues are specifying TÜV OK Compost or DIN-Geprüft marks as mandatory pass-fail criteria. This pattern concentrates most visibly in Scandinavian markets where municipal procurement guidelines embed circular economy scoring.
Europe Biodegradable Food Service Disposables Market Segmentation
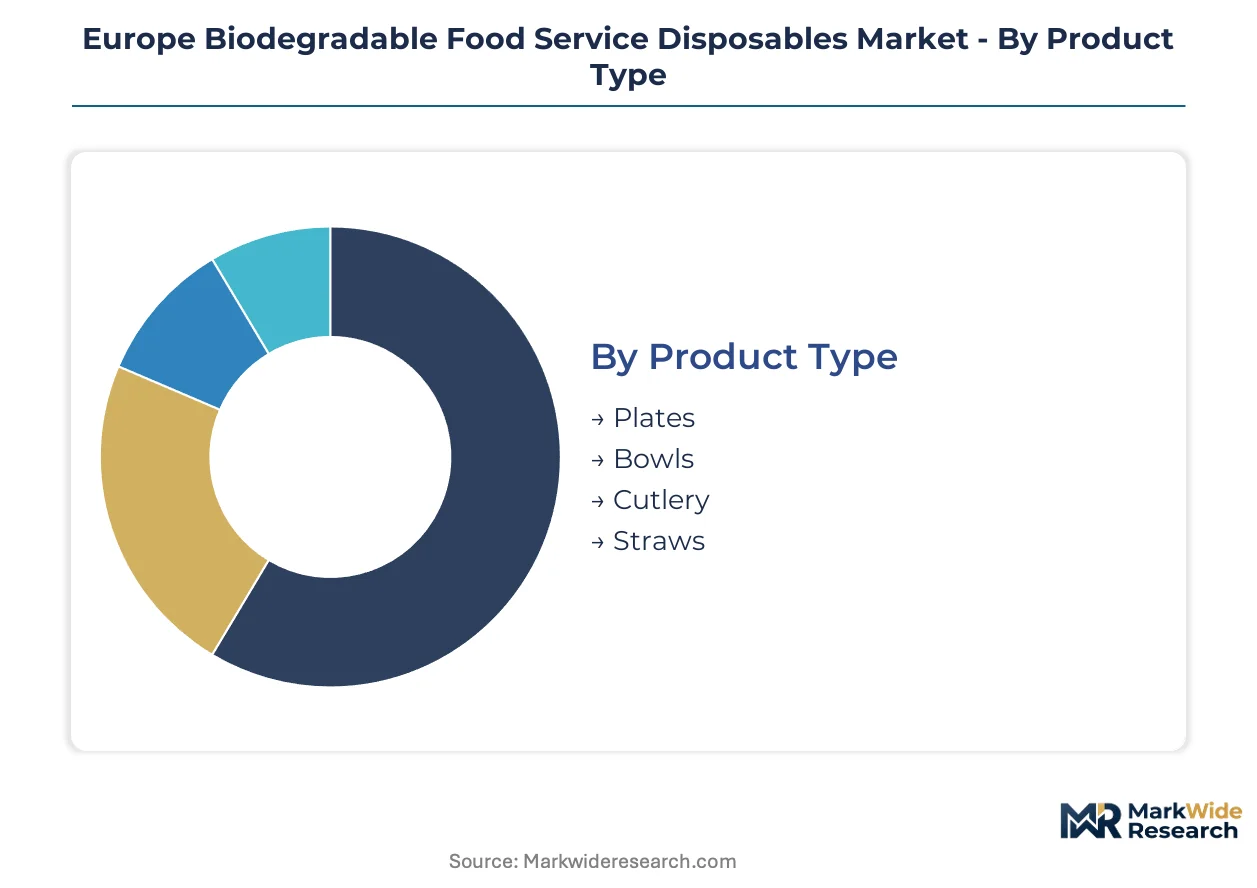
Segmentation in this market reveals how procurement authority, material performance, and end-of-life infrastructure intersect to determine channel economics. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier strategy across Northern, Western, and Southern European corridors.
Product Type:
Channel mix varies sharply by product: institutional distributors dominate plate and bowl volume, while cutlery and straws flow through specialized foodservice intermediaries with certification expertise.
- Plates:Molded bagasse and palm leaf constructions serve high-throughput institutional catering. Demand clusters in German corporate canteens and French school feeding programs where DIN-Geprüft certification is mandatory.
- Bowls:PLA-lined fiber vessels handle hot soups and grain bowls for quick-service chains. Crystallinity-enhanced grades from Dutch compounders are displacing conventional plastic in Amsterdam and Rotterdam metropolitan clusters.
- Cutlery:Heat-tolerant PLA formulations command premium positioning.
- Straws:Bamboo and paper alternatives occupy beverage-focused niches.
Plates dominate installed base across contract catering. Bowls are where expansion concentrates as hot-format takeaway formats proliferate.
Material:
Cost tier stratification separates commodity pulp from engineered biopolymers, with margin structure inversely correlated to raw material substitutability.
- PLA:Corn-derived polylactic acid delivers crystallinity-tunable performance for cutlery and hot-fill applications. Price volatility with starch markets compresses margins for converters lacking long-term supply agreements.
- Bagasse:Sugarcane fiber pulp enables low-cost molded plate production. Expanded processing capacity in Southern Europe is stabilizing input costs for manufacturers serving British and Iberian institutional channels.
- Bamboo:Rapid-renewable grass fibers suit straws and artisan serveware.
- Palm Leaf:Areca sheath pressing creates tactile-differentiated plates for specialty coffee and premium catering segments.
Bagasse dominates installed base in volume terms. PLA is climbing the fastest as heat-performance thresholds improve.
End User:
Customer type determines certification stringency and order fragmentation, with corporate procurement functions imposing stricter documentation than independent operators.
- Restaurants:Independent bistros and quick-service chains in Paris and Berlin corridors consolidate purchasing through verified distributor networks. AGEC law labeling requirements are filtering assortment toward pre-qualified suppliers.
- Catering Services:Contract caterers serving corporate campuses specify TÜV OK Compost marks as mandatory tender criteria. Scandinavian municipal procurement guidelines embed circular economy scoring that hardens certification preference.
- Events:Festival and stadium concessionaires drive seasonal demand spikes.
- Food Trucks:Mobile operators prioritize compact storage and rapid turnover.
Catering services dominate installed base through multi-year corporate contracts. Restaurants are gaining share fastest as independent purchasing cooperatives consolidate volume.
Distribution Channel:
Supply concentration in wholesale and direct sales is producing tiered access to certification documentation and technical support.
- Online Retail:Digital platforms serve fragmented independent operators with small-batch availability. Direct-to-operator models are bypassing traditional distribution markups in British and Dutch urban corridors.
- Supermarkets:Retail shelf space consolidates toward pre-qualified suppliers as France's AGEC law and Germany's Packaging Act mandate standardized compostability labeling.
- Wholesale:Broadline distributors carry inventory risk for high-volume institutional accounts.
- Direct Sales:Manufacturer relationships with major chains eliminate intermediary margins.
Wholesale dominates installed base through established foodservice distribution relationships. Online retail is expanding most quickly as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments across European corridors. German and French buyers absorb certification premiums for heat-tolerant PLA cutlery. Southern European institutional caterers prioritize bagasse plate economics over thermal performance thresholds.
Germany
Corporate canteen procurement drives molded fiber plate volume through broadline distributors. The Packaging Act amendments mandate DIN-Geprüft compostability labeling that filters supermarket assortments. Berlin metropolitan clusters concentrate quick-service chain consolidation, with major operators requalifying supplier portfolios ahead of enforcement deadlines.
France
Independent bistros and café chains in Paris corridors consolidate purchasing through verified distributor networks. AGEC law extended producer responsibility requires recyclability or compostability labeling on all tableware. Lyon and Marseille institutional feeding programs specify TÜV OK Compost marks as mandatory tender pass-fail criteria.
United Kingdom
British catering distributors specialize in bagasse plate manufacturing for contract foodservice channels. Edinburgh-based compostable packaging R&D anchors innovation positioning for independent operator segments. London metropolitan procurement digitization accelerates direct-to-operator platform adoption, bypassing traditional wholesale markups.
Netherlands
Quick-service chains in Amsterdam and Rotterdam metropolitan clusters adopt crystallinity-enhanced PLA grades for hot beverage lids. REACH chemical migration standards for bio-based coatings redirect volume toward compliant domestic converters. Dutch compounders supply heat-tolerant formulations displacing conventional plastic in soup container applications.
Italy
Southern European sugarcane processing expansion stabilizes pulp input costs for molded plate manufacturers. Milan and Rome catering distributors carry inventory risk for high-volume institutional accounts. Italian converters serve price-sensitive Iberian and North African export channels from expanded domestic fiber-forming capacity.
Europe Biodegradable Food Service Disposables Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier across the European biodegradable disposables sector. Nordic fiber-forming infrastructure and Edinburgh-based compostable packaging R&D anchor distinct competitive positions. Three archetypes dominate: integrated pulp molders with captive raw material access, specialty converters with certification expertise, and broadline distributors with inventory risk absorption. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with pre-certified manufacturers capturing requalified procurement volumes.
Among Nordic-based integrated operators, Huhtamaki Group exemplifies the fiber-forming archetype with established quick-service chain relationships across Northern Europe. Within the specialty converter tier, Vegware occupies a position defined by compostable packaging R&D concentration and direct independent operator relationships. British bagasse specialists including Biopac (U.K.) Ltd represent the regional manufacturing archetype, serving institutional catering distributors with dedicated plate production capacity.
| Leading Market Players |
|---|
| Huhtamaki Group |
| Biopac (U.K.) Ltd |
| Bionatic GmbH & Co. KG |
| I.L.P.A. S.p.A. Group |
| Gold Plast S.p.A |
| The Jim Pattison Group |
| Vegware |
| Bunzl plc |
| Graphic Packaging International, L.L.C. |
| Others |
Cost & Logistics Intelligence
Bagasse pulp capacity utilization across Southern European sugarcane processing facilities shapes both supply concentration and minimum viable pricing for molded plate manufacturers serving institutional catering channels. Scale advantages at integrated fiber-forming operations in Italy and Spain compress unit economics for mid-scale converters lacking captive pulp supply, while REACH-compliant coating chemists command premium compensation that elevates price floors for certified compostable serveware.
Pricing Analysis
After-sales certification documentation and extended compostability validation services now generate disproportionate lifetime value relative to base product margins. Three-tier pricing structure across premium crystallinity-enhanced PLA, standard bagasse formulations, and economy uncoated pulp separates heat-performance tiers. Cost compression in standard-grade cutlery intensifies as pre-ban plastic inventory liquidation temporarily undercuts certified alternatives. Contract caterers serving German corporate campuses exhibit lowest price sensitivity due to mandatory DIN-Geprüft tender requirements, while independent British food trucks prioritize compact storage economics over certification premiums.
Supply Chain Analysis
Sugarcane bagasse pulp processing in Italy, Spain, and Portugal anchors raw material availability for molded plate manufacturers serving British and Iberian institutional channels. PLA resin production draws from corn starch feedstocks concentrated in North American and Chinese agricultural processing, exposing European converters to commodity price volatility. Single-source vulnerability in industrial composting infrastructure deployment across Eastern European municipalities creates end-of-life uncertainty that dampens procurement confidence. Distribution runs through broadline foodservice wholesalers carrying inventory risk for high-volume quick-service chain accounts, with direct-to-operator digital platforms emerging in London and Amsterdam metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compostability certification services and industrial composting facility partnerships now expand faster than base product manufacturing, reframing biodegradable disposables as a compliance-attach business where documentation quality determines renewal rates.
For Market Incumbents: Fortify Nordic fiber-forming infrastructure against Southern European pulp cost advantages by deepening captive bagasse supply agreements with Italian and Spanish sugarcane processors. Accelerate TÜV Austria and DIN CERTCO pre-certification pipelines to capture requalified procurement volumes before enforcement deadlines compress supplier qualification windows. Defend against specialty converter encroachment by embedding dedicated regulatory affairs functions that mid-scale competitors cannot replicate. For New Entrants and Emerging Players: Lead with palm leaf sheath artisan positioning in specialty coffee segments across Paris and Berlin metropolitan corridors, where tactile differentiation supports premium pricing independent of commodity pulp economics. Target underpenetrated Eastern European event catering channels where seasonal demand spikes and limited industrial composting infrastructure create white-space for origin-storytelling serveware. Deploy direct-to-operator digital platforms that bypass established wholesale markups and consolidate fragmented independent restaurant purchasing. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty converters with pre-validated certification documentation and established independent operator relationships over capital-intensive pulp molders facing raw material cost volatility. Long-term viability rests on industrial composting infrastructure buildout pace across European municipalities, with certification expertise scarcity creating durable moats. Watch anaerobic digestion capacity deployment in Poland and Romania as the critical inflection indicator for Eastern European demand normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bagasse Pulp Supply | Captive Southern European fiber supply stabilizes input costs against corn starch volatility. |
| Pre-Certification Pipeline Expansion | TÜV Austria and DIN CERTCO validation investments capture requalified procurement volumes ahead of enforcement. |
| Direct-to-Operator Digital Platform Launch | Bypassing broadline distributor markups consolidates fragmented independent restaurant purchasing. |
| Industrial Composting Facility Partnerships | Strategic alliances with anaerobic digestion operators resolve end-of-life uncertainty dampening buyer confidence. |
| Palm Leaf Sheath Product Line Extension | Artisan positioning in specialty coffee segments commands premium pricing through tactile differentiation. |
Research Approach
A spread of perspectives from foodservice procurement directors, compostability certification specialists, industrial composting facility operators, and bio-based coating chemists converged on the working assumptions underlying this analysis. Primary fieldwork with quick-service chain sustainability officers and contract catering supply chain managers combined with secondary validation against EU Single-Use Plastics Directive implementation timelines, ECHA REACH framework amendments, and member state industrial composting capacity databases. Bottom-up volume modeling across product type, material formulation, and end-user segments triangulated against top-down macroeconomic indicators.
Segmentation dimensions modeled include product category hierarchy, material performance tier, end-user procurement authority, and distribution channel structure across the analysis window. CAGRs were derived from segment-level volume trajectories weighted by price realization trends and regulatory enforcement phasing. Crystallinity-enhanced PLA adoption curves and bagasse pulp processing capacity expansion schedules served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU Single-Use Plastics Directive enforcement and France's AGEC law extended producer responsibility frameworks; material policy shifts would require re-modeling. Compostability certification timeline extensions, industrial composting infrastructure deployment delays, or PLA resin supply disruptions represent specific risk factors that could revise projections. Practitioners should keep alternative scenarios live as Eastern European anaerobic digestion capacity and pre-ban plastic inventory liquidation dynamics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
North America Cafes & Bars Market
Food Service
Asia-Pacific Halal Food and Beverage Market
Food Service
Contract Blending Services Market
Food Service
Catering Food Warmers Market
Food Service
Netherlands Food Service Market
Food Service
Europe Online Grocery Market
Food Service
Global Food Platform-To-Consumer Delivery Market
Food Service
Qatar Food Service Market
Food Service
Singapore Food Service Market
Food Service
Food Trucks Market
Food Service
Portion Cups Market
Food Service
Commercial Tableware Services Market
Food Service
Street Vendors Market
Food Service
Gourmet Street Food Market
Food Service
Saudi Arabia Pizza Restaurants Market
Food Service
Instant Noodle Vending Machine Market