
 Decaf Coffee Market | 2026-2036
Decaf Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Decaf Coffee Market Analysis
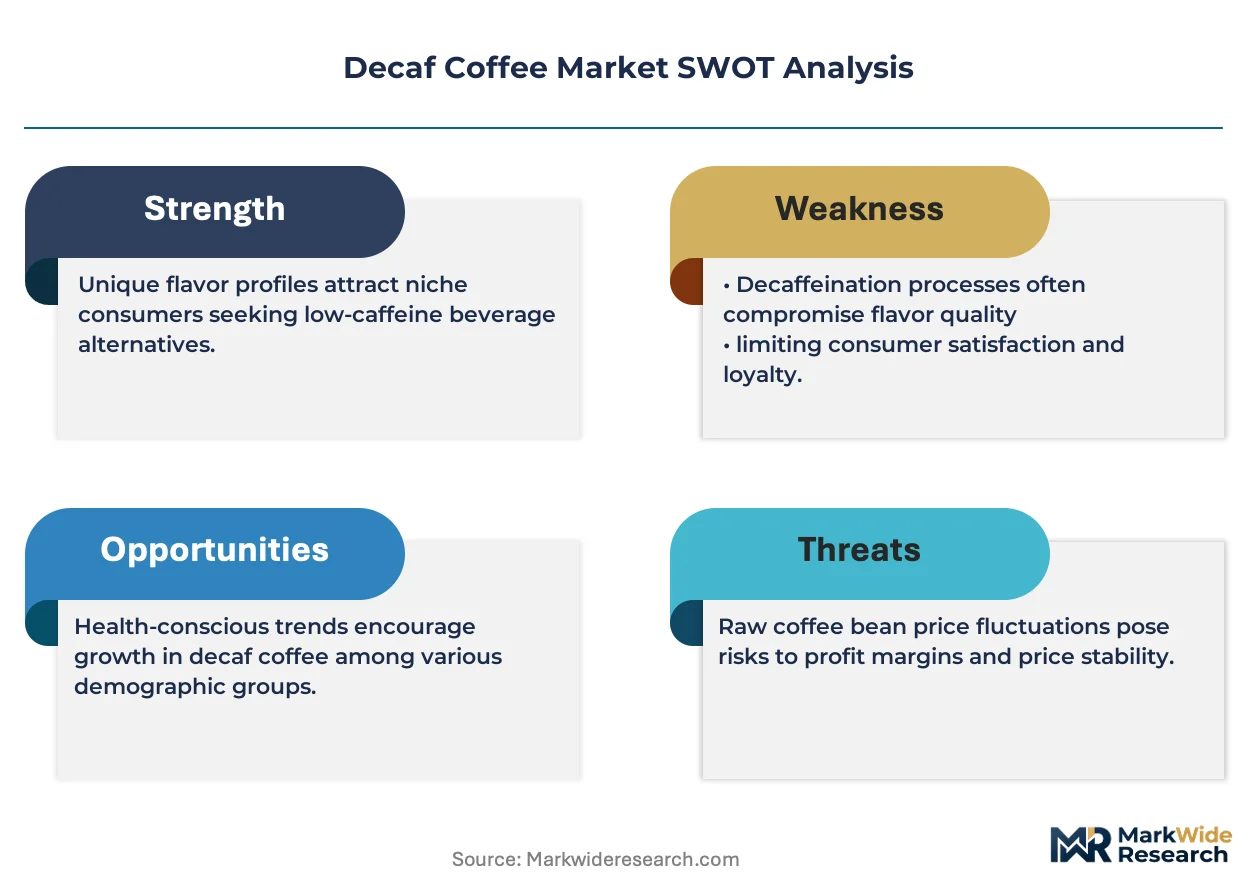
Asset-light contract roasting and third-party decaffeination tolling is fragmenting capital requirements across the value chain, enabling smaller brands to enter without owning extraction infrastructure. Nestlé SA leverages its captive soluble coffee network to secure volume positions in instant decaf. JDE Peet's N.V. anchors European retail shelf space through multi-brand portfolio density. Swiss Water Decaffeinated Coffee Inc. differentiates through proprietary carbon-filter extraction technology that eliminates methylene chloride residue concerns.
Decaf coffee comprises green beans processed to remove at least 97% of naturally occurring caffeine while preserving volatile aromatic compounds, typically achieved through water-based, solvent-based, or supercritical carbon dioxide extraction methods. The product serves consumers seeking to limit caffeine intake without abandoning ritual coffee consumption across home, office, and foodservice environments. Ground decaf occupies the largest volume share in North American retail, while pods capture expanding premium household penetration through single-serve convenience. Instant decaf sustains dominant positions in European and Asian markets where soluble coffee traditions remain entrenched. Whole bean decaf registers the fastest growth in specialty channels as home grinding equipment proliferates among quality-focused buyers.
The FDA sets residual solvent limits for methylene chloride decaffeination under 21 CFR 173.255, directly influencing processor technology choices and import compliance costs for US-bound shipments. The EU's REACH framework and F-Gas Regulation govern chemical inputs and emissions profiles at extraction facilities across member states. Organic certification under USDA and EU organic standards creates parallel supply chains with distinct sourcing and processing protocols. Stakeholders must monitor evolving regulatory thresholds for chemical residues and carbon intensity as these standards increasingly determine market access and premium positioning.
Market Dynamics
The EU's F-Gas Regulation is forcing capital retooling across European extraction facilities, while specialty café chains in Germany and the United States drive preference shifts toward chemical-free Swiss Water process beans. These dual pressures compress margins for solvent-dependent processors while opening premium positioning for carbon-filter operators.
Growth Catalysts
- REACH solvent standards:The EU's tightening chemical residue thresholds under ECHA oversight push roasters toward water-based and supercritical CO2 methods, expanding addressable premium shelf space.
- Specialty café channel expansion:Third-wave coffee shops in Portland, Melbourne, and Copenhagen now feature single-origin decaf offerings, normalizing quality parity with caffeinated counterparts.
- Home grinding equipment proliferation:Burr grinder adoption among quality-focused households lifts whole bean decaf velocity faster than pre-ground formats.
Market Restraints
- Arabica price volatility:Green coffee input costs swing with Brazilian climate events, squeezing tolling margins for independent decaffeination facilities.
- Supercritical CO2 equipment concentration:German and Swiss engineering houses control high-pressure extraction system supply, creating bottleneck risk for capacity expansion.
- Instant decaf substitution:Soluble coffee traditions in Japan and the United Kingdom limit ground bean penetration in established consumption markets.
Strategic Opportunities
- India specialty channel:Underdeveloped café infrastructure in Bangalore and Mumbai offers first-mover positioning for Swiss Water process branding.
- USDA organic certification convergence:Dual organic-decaf labeling commands shelf price premiums in Whole Foods and Sprouts distribution networks.
- Direct-to-subscription models:Roasters bypass wholesale margin stacking through curated decaf clubs targeting sleep-conscious professionals.
Industry Challenges
- Volatile aromatic compound retention:Maintaining flavor fidelity through decaffeination requires specialized cupping talent scarce outside established roasting hubs.
- F-Gas compliance capex:European facilities face seven-figure retrofit costs for emission capture systems under 2024 enforcement timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decaf Coffee Market |
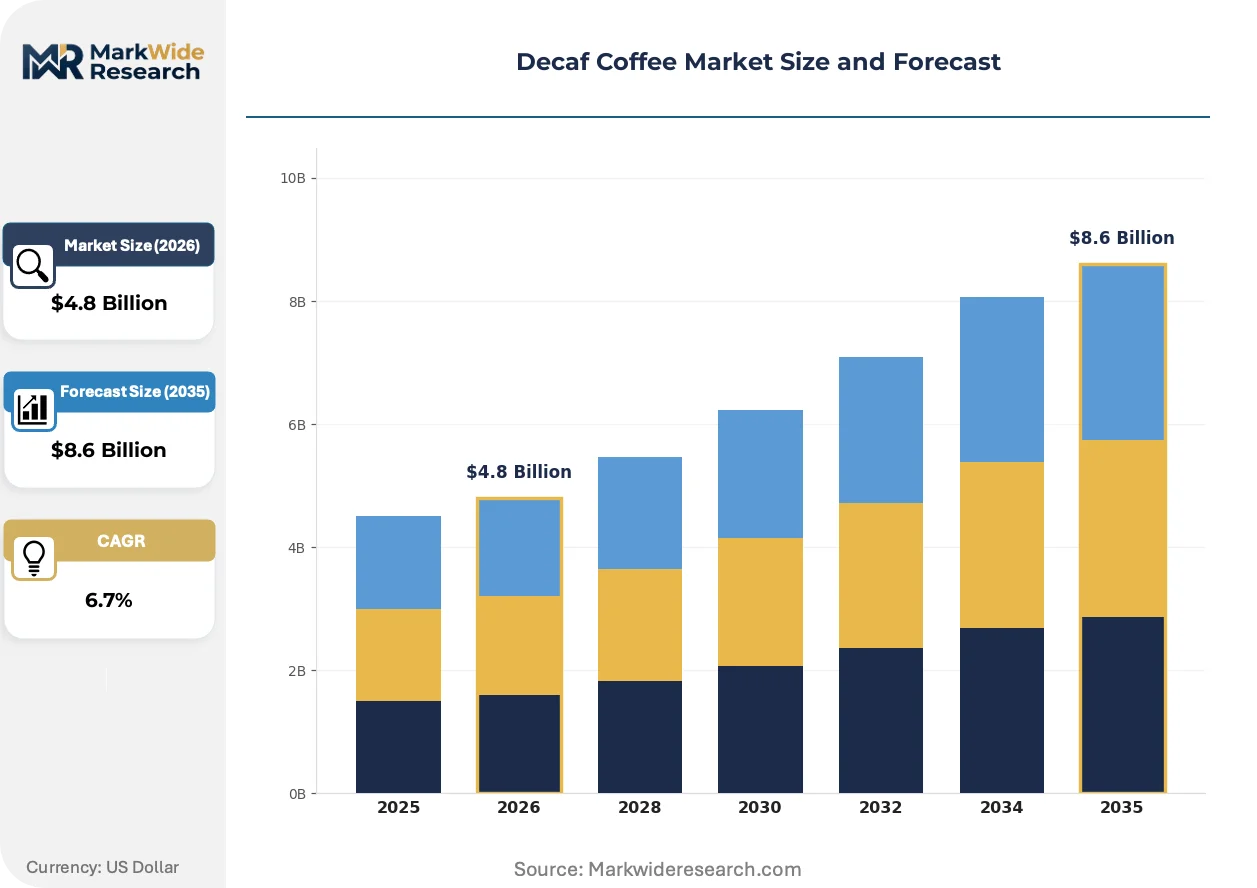
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Bean, Ground, Instant, Pods Roast Level: Light, Medium, Dark, Espresso Packaging Type: Bags, Cans, Boxes, Bottles Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Cafés |
| Companies Covered | Nestlé SA, Starbucks Corporation, JDE Peet's N.V., The J.M. Smucker Company, The Kraft Heinz Company, Tata Consumer Products Limited, Swiss Water Decaffeinated Coffee Inc., Keurig Dr Pepper Inc., Tchibo GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decaf Coffee Market Emerging Trajectories
Extraction technology is fragmenting across multiple validated methods, while regulatory chemistry constraints and consumer transparency demands reshape competitive positioning. Three developments dominate the current transformation.
Supercritical carbon dioxide extraction is migrating from industrial soluble coffee plants into specialty-scale batch processing. Medium-sized roasters in Italy and the Netherlands now adopt modular 50-tonne systems previously exclusive to Nestlé-scale operations. This diffusion compresses the minimum viable scale for residue-free production, eroding the Swiss Water process's technology monopoly in premium segments.
The EU F-Gas Regulation's phasedown schedule for hydrofluorocarbon refrigerants directly impacts extraction facility cooling infrastructure. Processors must substitute alternative cooling chemistries or absorb retrofit costs by 2027. German tolling operators Tchibo and third-party facilities in Hamburg anchor the most advanced compliance transitions, creating regulatory arbitrage against Southern European competitors.
Transparency-seeking buyers now demand batch-level decaffeination method disclosure at point of sale. Specialty retailers in Copenhagen and San Francisco replace generic "naturally decaffeinated" claims with specific process callouts. This labeling evolution favors operators with certified carbon-filter or CO2 capabilities while marginalizing methylene chloride users in quality-focused channels.
Decaf Coffee Market Segmentation
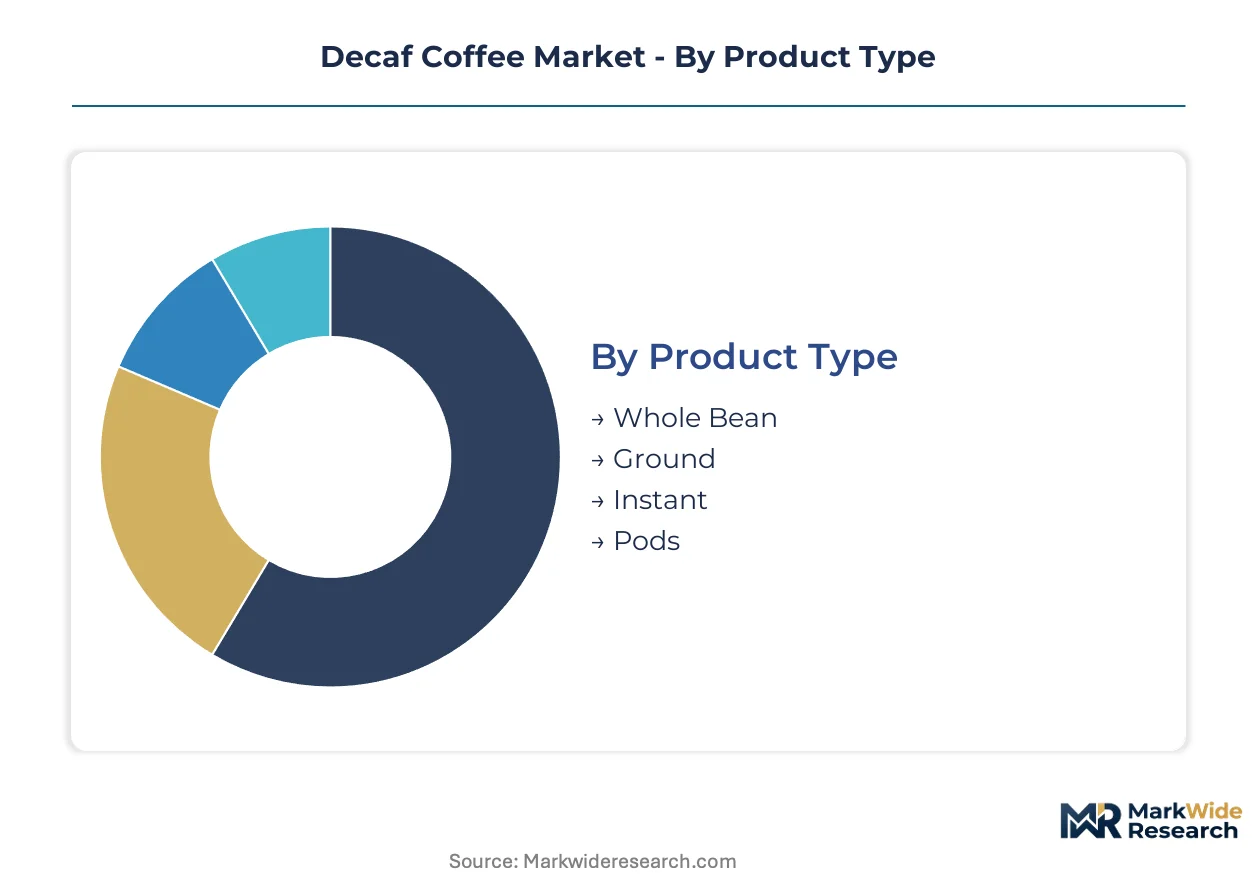
Decaf coffee segmentation reflects divergent consumption rituals across preparation methods, roast preferences, and channel access. Each dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning.
Product Type:
Volume concentration across preparation formats reveals how convenience trade-offs fragment addressable demand.
- Whole Bean:Unprocessed roasted beans requiring home grinding equipment preserve volatile aromatic compounds most effectively. Specialty cafés in Copenhagen and Portland drive preference for single-origin whole bean decaf as grinding equipment proliferates among quality-focused households.
- Ground:Pre-milled coffee dominates North American retail shelf space through immediate brew accessibility without capital investment. Supermarket distribution in Germany and the United States sustains volume leadership despite faster aroma degradation versus whole bean alternatives.
- Instant:Soluble powder and granule formats anchor European and Asian consumption traditions through preparation speed.
- Pods:Single-serve capsules capture premium household penetration through portion control and machine ecosystem lock-in.
Ground decaf commands the established base. The steepest expansion runs through whole bean as home grinding equipment proliferates.
Roast Level:
Application context across preparation methods determines roast specification demand.
- Light:Shorter roasting profiles preserve origin-specific acidity and fruit notes prized by third-wave cafés. Melbourne and San Francisco specialty shops feature light roast decaf to demonstrate quality parity with caffeinated counterparts despite decaffeination flavor loss.
- Medium:Balanced roast development suits drip brewing and French press methods across mainstream household consumption. German retail chains and US supermarket channels concentrate medium roast decaf velocity through broad compatibility with home preparation equipment.
- Dark:Extended roasting masks processing defects and creates bold flavor profiles favored by espresso preparation.
- Espresso:Specific roast and grind calibration optimized for high-pressure extraction equipment.
Medium roast commands the established base. The steepest expansion runs through light roast as specialty cafés normalize quality-focused decaf positioning.
Packaging Type:
Supply chain configuration and shelf-life requirements fragment container specification across channels.
- Bags:Flexible laminated pouches with one-way degassing valves dominate specialty retail and subscription channels. Roasters in Italy and the Netherlands favor bag formats for whole bean distribution to preserve freshness through reduced oxygen exposure versus rigid alternatives.
- Cans:Metal containers with resealable lids sustain instant decaf distribution in European and Asian markets where soluble traditions remain entrenched. Nestlé-scale operators leverage canning infrastructure for ambient-stable product positioning in ambient retail.
- Boxes:Carton formats accommodate pod assortment packaging and gift set configurations.
- Bottles:Rigid plastic and glass containers serve ready-to-drink liquid decaf coffee in convenience retail.
Can formats command the established base through instant coffee distribution. The steepest expansion runs through bags as specialty channels prioritize freshness signaling.
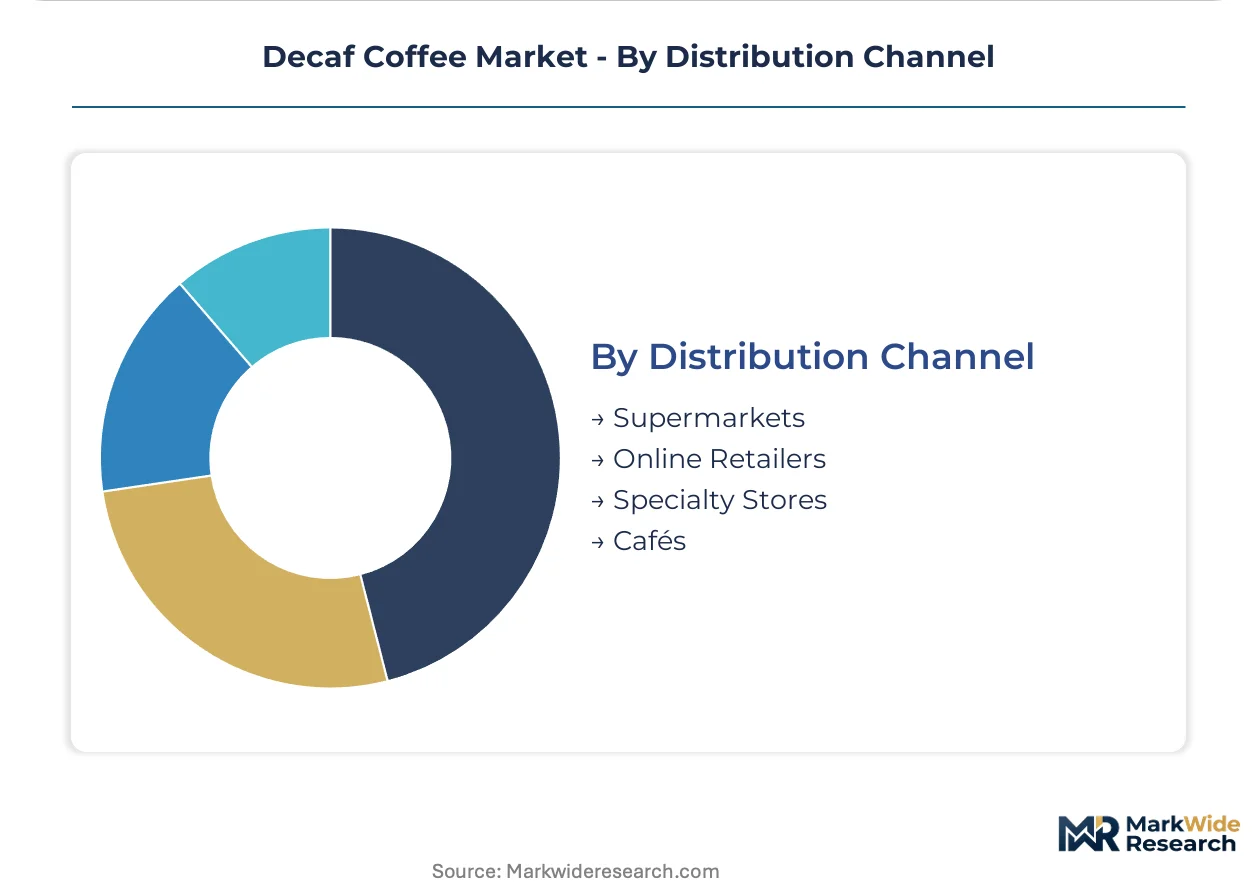
Distribution Channel:
Customer type and purchase occasion fragment channel access with distinct margin and working capital requirements.
- Supermarkets:Mass retail chains anchor volume throughput through promotional pricing and shelf space allocation. JDE Peet's N.V. portfolio density secures European supermarket positioning while US retailers concentrate ground decaf in center-store coffee aisles.
- Online Retailers:Direct-to-consumer and marketplace platforms enable subscription models bypassing wholesale margin stacking. Sleep-conscious professionals in the United States and United Kingdom drive decaf club growth through curated delivery and process transparency claims.
- Specialty Stores:Independent retailers and natural food chains command premium pricing through certified organic and Swiss Water process assortment.
- Cafés:Foodservice operators normalize decaf as quality-equivalent through single-origin offerings and skilled barista preparation.
Supermarkets command the established base. The steepest expansion runs through online retailers as subscription models disintermediate traditional wholesale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU's F-Gas Regulation and tightening solvent residue standards under ECHA oversight are redirecting capital toward carbon-filter and supercritical CO2 extraction infrastructure across major consuming markets.
Germany
Specialty café chains in Berlin and Hamburg drive preference for chemical-free Swiss Water process beans, while the F-Gas Regulation forces retrofit investments at extraction facilities. Tchibo GmbH anchors roasting capacity in Hamburg, where tolling operators lead compliance transitions ahead of 2027 enforcement timelines.
United States
Third-wave coffee shops in Portland and San Francisco normalize single-origin decaf offerings, expanding premium shelf space for residue-free processors. FDA residual solvent limits under 21 CFR 173.255 shape import compliance costs and technology choices at decaffeination facilities. Subscription clubs targeting sleep-conscious professionals in New York and Los Angeles bypass traditional wholesale channels.
United Kingdom
Instant decaf traditions limit ground bean penetration despite expanding specialty café presence in London and Manchester. REACH framework alignment governs chemical inputs at extraction facilities serving EU-bound shipments. Whole Foods and Sprouts distribution networks command dual organic-decaf labeling premiums across Southeast England.
Netherlands
Medium-sized roasters in Amsterdam adopt modular supercritical CO2 systems previously exclusive to industrial-scale operators. ECHA oversight of solvent standards pushes water-based method adoption. Rotterdam and Utrecht specialty retailers feature batch-level process disclosure at point of sale.
Italy
Espresso preparation traditions sustain dark roast demand despite light roast expansion elsewhere. F-Gas Regulation compliance costs concentrate in Northern Italian extraction facilities. Milan and Turin roasters leverage bag-format distribution to preserve freshness signaling in specialty channels.
Decaf Coffee Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic tiers: multinational beverage conglomerates with captive soluble networks, regional roasting specialists with tolling arrangements, and technology-differentiated processors with proprietary extraction methods. Swiss Water Decaffeinated Coffee Inc. exemplifies the technology-specialist archetype, while Nestlé SA and JDE Peet's N.V. represent scale-driven integrated beverage platforms. Competitive dynamics center on portfolio diversification into organic-certified offerings and geographic expansion through asset-light contract roasting partnerships.
Among scale-driven integrated operators, Nestlé SA, JDE Peet's N.V., and Starbucks Corporation occupy positions spanning retail shelf space, foodservice distribution, and direct-to-consumer channels. Nestlé SA leverages captive soluble coffee infrastructure, while JDE Peet's N.V. secures European retail positioning through multi-brand portfolio density. Starbucks Corporation anchors foodservice normalization of quality-equivalent decaf through skilled barista preparation and single-origin offerings. These three exemplify how beverage conglomerates integrate upstream extraction access with downstream brand equity to defend margin positions against specialty challengers.
| Leading Market Players |
|---|
| Nestlé SA |
| Starbucks Corporation |
| JDE Peet's N.V. |
| The J.M. Smucker Company |
| The Kraft Heinz Company |
| Tata Consumer Products Limited |
| Swiss Water Decaffeinated Coffee Inc. |
| Keurig Dr Pepper Inc. |
| Tchibo GmbH |
| Others |
Supply Flow & Price Mechanics
Undercapacity at Swiss Water process facilities in British Columbia and Hamburg is compressing tolling availability and pushing roasters toward longer-term contract structures with embedded price escalators. This utilization squeeze simultaneously elevates spot pricing for chemical-free decaffeination slots while forcing solvent-dependent operators to absorb margin compression from F-Gas retrofit obligations.
Pricing Analysis
Certification level creates the primary spread across decaf coffee tiers, with USDA organic and Swiss Water process dual-labeling commanding shelf price premiums against conventional methylene chloride alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects extraction method transparency, with carbon-filter and supercritical CO2 batches occupying premium positioning. Cost compression in solvent-dependent tolling is intensifying because ECHA residue thresholds are forcing capital retooling without corresponding price recovery mechanisms. Price-sensitive mass retail buyers in German supermarket chains resist pass-through of organic certification costs, while specialty café operators in Portland and Copenhagen absorb premiums for batch-level process disclosure.
Supply Chain Analysis
Contract manufacturing concentration rests with Tchibo GmbH in Hamburg, Swiss Water Decaffeinated Coffee Inc. in British Columbia, and Nestlé-scale soluble operations in Orbe, Switzerland. Geographic supply concentration centers on Germany, Switzerland, and Canada for extraction capacity, with green bean sourcing drawing from Brazilian, Colombian, and Ethiopian origins. Raw material dependencies hinge on Arabica futures volatility, specialized activated carbon filtration media, and high-pressure CO2 equipment from German engineering houses. Single-source vulnerability runs through supercritical system manufacturers in Bavaria and Baden-Württemberg. Distribution runs through tolling arrangements that fragment roasting and extraction across multiple facilities rather than captive vertical integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where ECHA solvent standards and FDA residue limits create asymmetric compliance burdens that favor incumbent processors with capital reserves for F-Gas retrofit and carbon-filter certification.
For Market Incumbents: Harden defensibility through backward integration into certified organic green bean sourcing in Colombia and Ethiopia, securing supply priority as dual-label demand expands. Deepen channel control by embedding Swiss Water process exclusivity clauses into multi-year specialty café supply agreements, locking out solvent-dependent competitors from third-wave positioning. Prioritize capacity addition in Hamburg and British Columbia to capture tolling overflow from Southern European facilities facing 2027 F-Gas enforcement timelines. For New Entrants and Emerging Players: Build out white-space positioning in India's underdeveloped specialty café channel, where Bangalore and Mumbai infrastructure gaps offer first-mover Swiss Water process branding opportunities. Target direct-to-subscription models targeting sleep-conscious professionals in London and New York, bypassing wholesale margin stacking through curated decaf clubs with batch-level transparency claims. Anchor go-to-market execution through online retail platforms that disintermediate established supermarket shelf space controlled by JDE Peet's portfolio density. For Investors and Strategic Acquirers: Capital is best deployed toward technology-differentiated processors with proprietary carbon-filter or modular supercritical CO2 capabilities, as regulatory chemistry constraints increasingly determine market access. Long-term viability across the projection horizon favors operators with certified residue-free production and organic certification convergence. Acquisition target archetype: mid-scale roasters with tolling arrangements and established specialty café relationships. The signal to watch is ECHA enforcement velocity on F-Gas retrofit compliance, which will determine capacity exit rates among solvent-dependent Southern European facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Convergence | Dual organic-decaf labeling commands shelf price premiums in Whole Foods and Sprouts networks. |
| Direct-to-Consumer Subscription Launch | Sleep-conscious professionals in New York and Los Angeles drive decaf club growth through curated delivery. |
| Supercritical CO2 Capacity Expansion | Modular 50-tonne system adoption in Italy and Netherlands compresses minimum viable scale for residue-free production. |
| Specialty Café Channel Partnership | Third-wave shops in Portland and Copenhagen normalize single-origin decaf offerings, expanding premium shelf space. |
| F-Gas Compliance Retrofit | German tolling operators in Hamburg lead emission capture system transitions ahead of 2027 enforcement timelines. |
Methodological Framework
The analysis maps water-based, solvent-based, and supercritical CO2 extraction sub-sectors, each validated through primary interviews with decaffeination facility operators, specialty café procurement managers, and organic certification auditors. Secondary validation draws from FDA 21 CFR filings, ECHA REACH substance registrations, USDA organic handler databases, and EU F-Gas Regulation implementation reports. Bottom-up volume triangulation across extraction method, roast level, and distribution channel converged with top-down value estimates derived from tolling rate benchmarks and retail price audit data.
Assumptions held fixed include ECHA solvent residue thresholds at current enforcement levels, FDA methylene chloride limits under 21 CFR 173.255, and Swiss Water process capacity expansion timelines. Variables stress-tested across the analysis window encompass Arabica price volatility bands, F-Gas retrofit compliance rates among European processors, and specialty café channel growth trajectories in Germany and the United States. CAGR derivation incorporated segment-level volume velocity, price elasticity by certification tier, and channel shift assumptions toward online retail and subscription models.
Stress conditions across Brazilian climate events, ECHA enforcement acceleration, and supercritical equipment delivery delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these assumptions and risk factors including Arabica supply disruption, regulatory threshold tightening, and carbon-filter media cost inflation. Quarterly review of ECHA compliance announcements, specialty café expansion rates in target cities, and tolling capacity utilization indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Office Coffee Service (OCS) Market
Coffee
Coffee Concentrate Market
Coffee
Cafix Market
Coffee
Espresso Powder Market
Coffee
Asia Pacific Coffee Market
Coffee
Instant Coffee Market
Coffee
Asia-Pacific Ready to Drink (RTD) Coffee Market
Coffee
Coffee Premixes Market
Coffee
Middle East Coffee Market
Coffee
Ground Coffee Market
Coffee
Coffee and Tea Capsule Market
Coffee
Coffee Crystal Market
Coffee
Oceania Coffee Market
Coffee
Espresso Tamper Market
Coffee
Ethiopia Coffee Market
Coffee
Global Portable Coffee Makers Market